
 Investment Casting Market | 2026-2036
Investment Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Investment Casting Market Intelligence
The bundling of design-for-manufacturing analysis with casting and post-processing services is realigning buyer preferences toward integrated suppliers. Precision Castparts Corp. leverages its extensive capabilities to serve demanding aerospace and power generation clients. CIREX Group specializes in complex, small-to-medium batch production primarily for the European automotive sector. MetalTek International differentiates through its wide range of alloy expertise and centrifugal casting technologies.
Investment casting is a manufacturing process using a wax pattern to create a disposable ceramic mold for molten metal. This lost-wax technique produces intricate parts with high dimensional accuracy and superior surface finish, reducing the need for subsequent machining. Titanium alloys and other non-ferrous alloys represent the fastest-growing product segments, driven by aerospace and medical implant requirements. The aerospace end-user segment commands significant value, while the automotive sector contributes substantial volume for components like turbocharger wheels.
Component quality is governed by strict standards from bodies like the FAA in the United States for aerospace parts and the FDA for medical devices. Industrial machinery components must comply with regional directives such as CE marking in the European Union and GB standards in China. Successfully navigating material qualification and process certification across these varied regulatory landscapes remains a critical decision point for foundries.
Market Dynamics
The convergence of advanced material science with digital manufacturing processes defines the investment casting market's current trajectory. Strict performance requirements from aerospace and medical end-users for components made from titanium alloys are elevating the importance of process control and technological sophistication among foundries.
Growth Catalysts
- Process Innovation:The integration of 3D printing to produce complex wax patterns shortens tooling lead times and enables more intricate component designs, especially for rapid prototyping and small-batch production.
- Aerospace Sector Requirements:Sustained demand for lightweight, high-performance turbine blades and structural components made from superalloys fuels investment in advanced casting capabilities to meet exacting flight-critical specifications.
- Automotive Volume Growth:The automotive industry's need for durable turbocharger wheels and other engine components provides a high-volume demand base, particularly in manufacturing centers across Germany and China.
Market Restraints
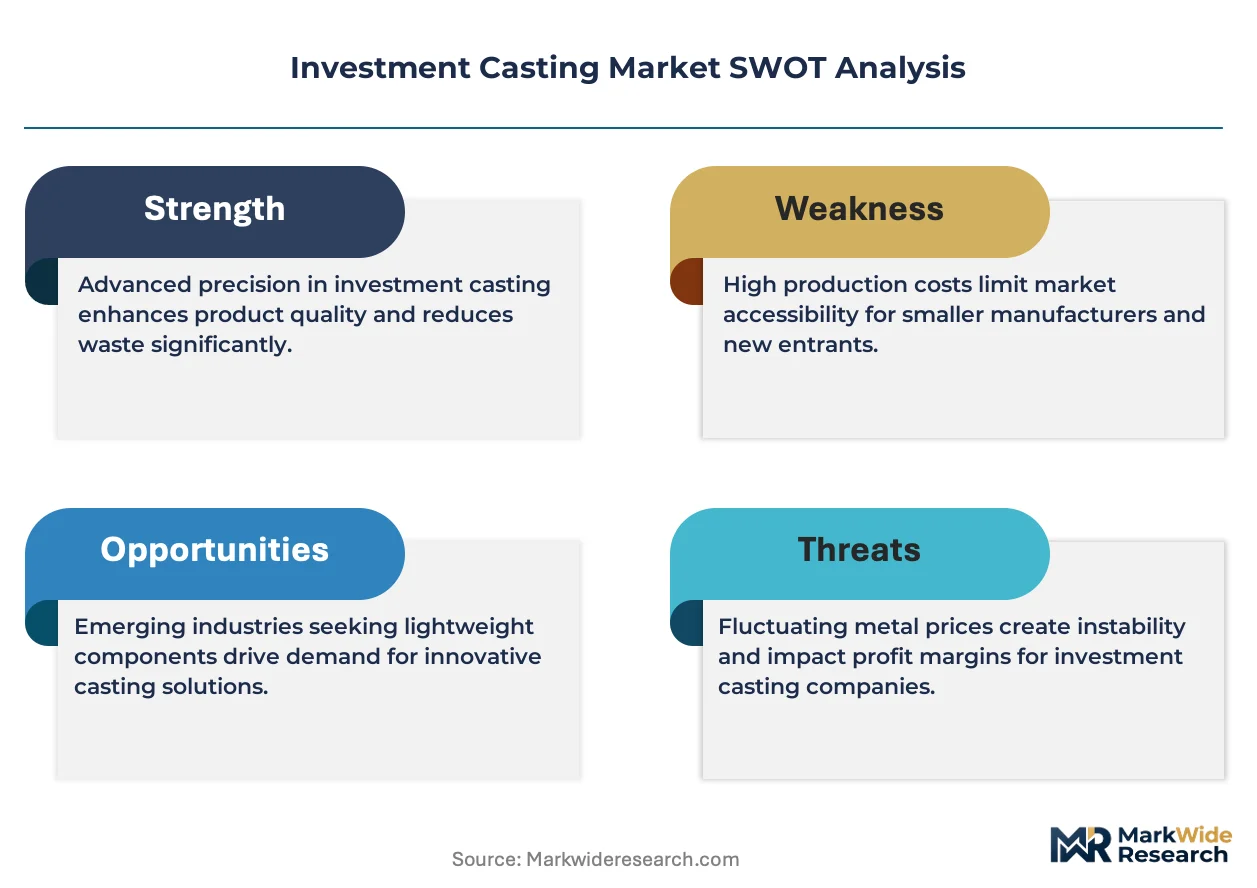
- Input Material Costs:The market is sensitive to price volatility in key raw materials, including titanium and cobalt, which directly impacts component pricing and foundry margins, especially for aerospace-grade alloys.
- High Tooling Investment:Traditional investment casting requires significant upfront capital for creating durable injection molds, posing a barrier for short-run production and making it less competitive for prototypes.
- Additive Manufacturing Threat:Direct metal laser sintering and other additive techniques present a substitution risk, offering a viable alternative for producing small, highly complex parts without the need for molds.
Strategic Opportunities
- Medical Device Expansion:There is significant potential in producing custom orthopedic implants and surgical tools, where the process's ability to cast complex shapes with biocompatible titanium alloys meets FDA and MDR requirements.
- Digital Twin Integration:Creating digital twins of the entire casting process, from mold design to solidification simulation, offers a path to optimize yields, reduce defects, and predict final part properties before pouring metal.
- Industrial Machinery in New Markets:Foundries can target the growing industrial machinery sector in markets like India and Vietnam, supplying high-wear components for pumps, valves, and automation equipment requiring precision.
Industry Challenges
- Skilled Labor Scarcity:The industry faces a critical shortage of experienced foundry engineers, metallurgists, and technicians who possess the specialized knowledge required for process control and quality assurance in high-specification casting.
- Regulatory Compliance Burden:Maintaining material and process certifications from disparate bodies like the FAA, FDA, and those enforcing CE marking requires significant ongoing investment in documentation, testing, and audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Investment Casting Market |
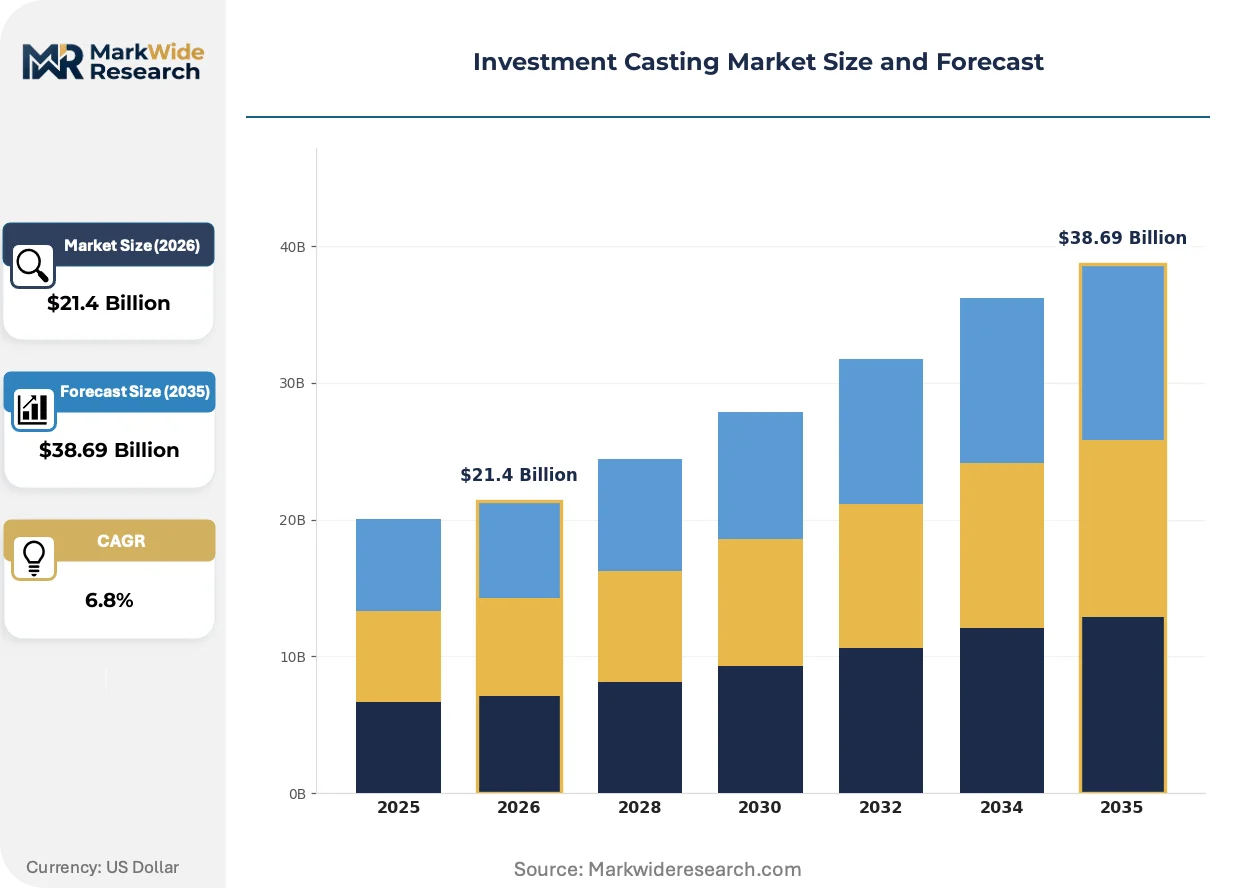
| Market Size in 2026 | $21.4 Billion |
| Market Size in 2035 | $38.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ferrous Alloys, Non-Ferrous Alloys, Stainless Steel, Titanium Alloys End User: Aerospace, Automotive, Medical, Industrial Equipment Technology: 3D Printing, Lost Wax, Ceramic Shell, Investment Molding Application: Machinery Parts, Components, Tools, Military Equipment |
| Companies Covered | CFS Foundry, Hitchiner Manufacturing, Precision Castparts Corp., CIREX Group, Milwaukee Precision Casting, Impro Precision Industries Limited, Alcoa Corporation, Zollern GmbH & Co. KG, MetalTek International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Investment Casting Market Strategic Shifts & Innovations
Digital technologies are fundamentally altering the economics and capabilities of investment casting, a process historically rooted in manual craftsmanship. The shift toward data-driven manufacturing and automated quality control is redefining industry standards for precision and repeatability.
Robotic systems are increasingly utilized for the repetitive and critical shell-building process. Foundries serving the aerospace and automotive sectors are adopting this technology to achieve greater consistency in shell thickness and material application. This advancement is automating the entire dipping and stuccoing sequence, which minimizes human error, enhances shell uniformity, and ultimately reduces scrap rates from shell-related defects.
The European Union's REACH framework imposes stringent controls on chemical substances, directly impacting materials used in casting. This regulation affects the binders, refractory materials, and solvents available to foundries, compelling them to seek and validate compliant alternatives. European industrial equipment manufacturers are particularly exposed, needing to ensure their entire supply chain, including casting suppliers, adheres to REACH to maintain market access.
A significant behavioral shift involves buyers prioritizing suppliers who bundle casting with secondary services like machining, heat treatment, and non-destructive testing. This model of integrated procurement is displacing the fragmented approach of using multiple specialized vendors. Such consolidation is especially prevalent among aerospace and defense contractors in the United States, who seek to simplify supply chain management and assign single-source responsibility for the final component.
Investment Casting Market Segmentation
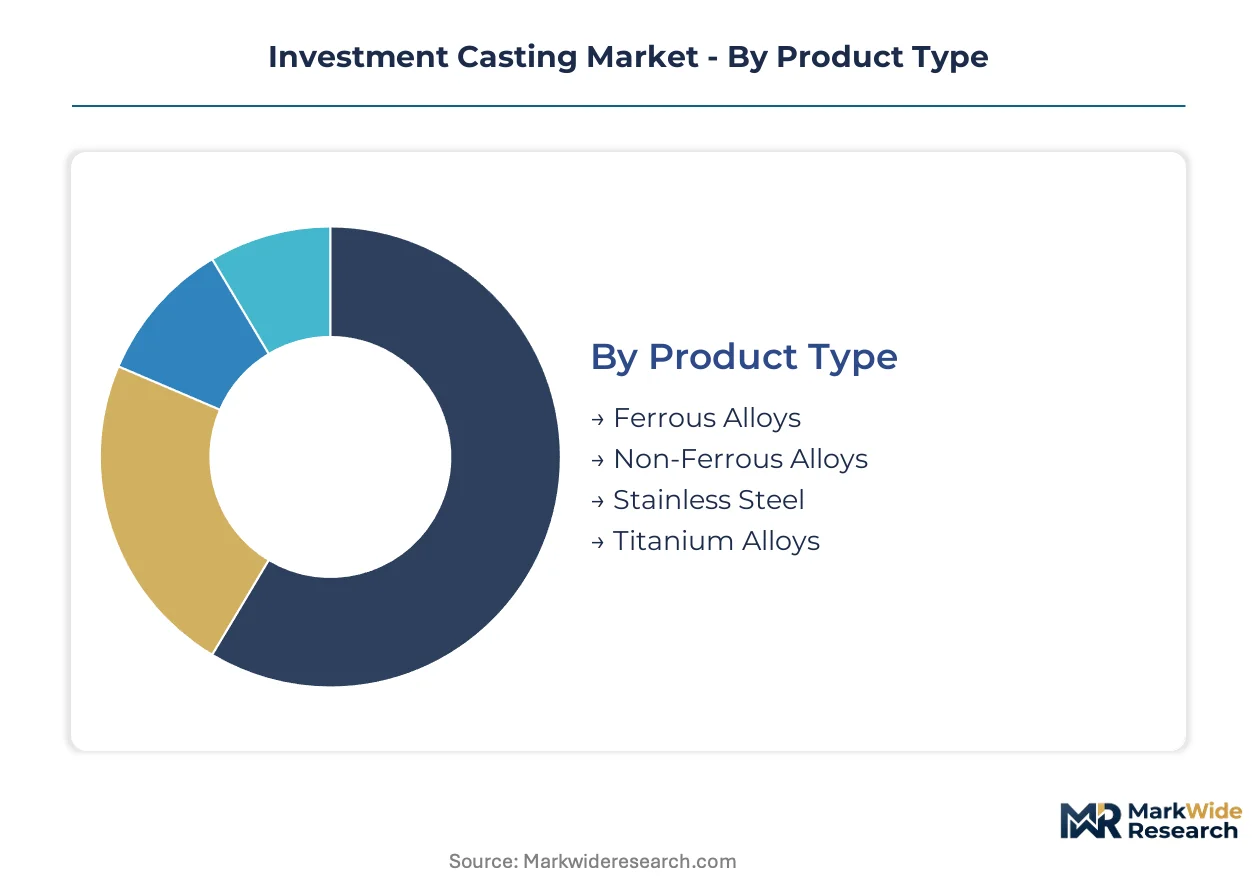
Market segmentation provides a critical framework for understanding the diverse demands and technological influences shaping the investment casting industry. This detailed breakdown reveals where value is created and how various end-user requirements drive material selection and process innovation.
Product Type:
The product type segmentation highlights the market's differentiation between high-volume, cost-sensitive materials and specialized, high-performance alloys commanding premium pricing.
- Titanium Alloys:These lightweight, high-strength, and biocompatible alloys are critical for demanding applications. Demand originates from the aerospace sector for engine components and the medical industry for FDA-regulated orthopedic implants.
- Ferrous Alloys:Iron-based compositions, including carbon and alloy steels, offer cost-effectiveness and robust mechanical properties. Volume demand stems from industrial machinery and automotive sectors, particularly for heavy-duty structural components.
- Stainless Steel:Corrosion-resistant alloys find extensive use in food processing equipment, marine applications, and chemical handling.
- Non-Ferrous Alloys:This category encompasses nickel, cobalt, and aluminum-based alloys, often specified for high-temperature and corrosive environments.
Mature deployment sits with Ferrous Alloys. Newer deployment is concentrated in Titanium Alloys.
End User:
End-user segments dictate the specific performance requirements and regulatory compliance standards for investment cast components.
- Aerospace:This sector requires lightweight, high-temperature resistant components like turbine blades, structural parts, and engine housings. Stringent FAA certifications govern part integrity and material traceability for flight-critical applications.
- Medical:Demands biocompatible and high-precision implants, surgical instruments, and prosthetic components. FDA and EU MDR regulations impose strict material and process validation for patient safety.
- Automotive:This industry provides high-volume demand for components such as turbocharger wheels, engine parts, and transmission components.
- Industrial Equipment:This segment includes durable parts for pumps, valves, compressors, and general machinery across various manufacturing and processing sectors.
The highest regulatory burden falls on Aerospace and Medical components, while Automotive drives significant volume.
Technology:
Technology segmentation reflects the evolution of casting processes, from traditional methods to advanced digital manufacturing techniques.
- 3D Printing:Utilizes additive manufacturing to create complex wax patterns directly from digital designs. This innovation shortens tooling lead times and enables rapid prototyping for intricate geometries.
- Lost Wax:The foundational investment casting method, involving a sacrificial wax pattern coated with refractory material. This technique produces high dimensional accuracy and superior surface finish for complex parts.
- Ceramic Shell:A critical step in lost wax casting, where layers of ceramic slurry and stucco are built around the wax pattern to form a robust mold.
- Investment Molding:Refers to the overall process of creating a ceramic mold around a pattern for subsequent molten metal pouring.
Digital technologies like 3D Printing offer significant efficiency gains, while Lost Wax remains the core process for precision.
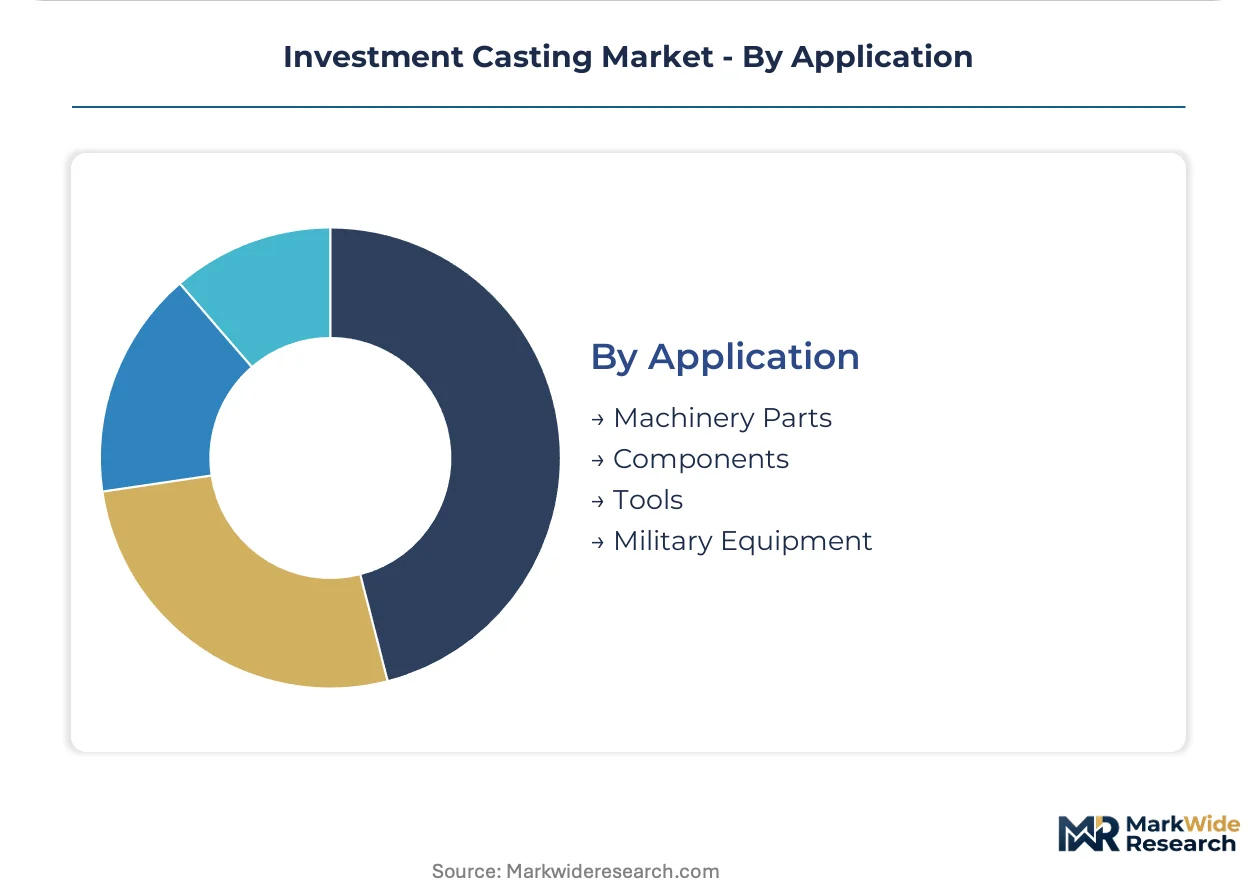
Application:
Application segmentation outlines the diverse functional requirements that investment cast parts fulfill across various industries.
- Military Equipment:Demands high-strength, durable components for aerospace, naval, and ground defense systems. These parts must withstand extreme conditions and meet stringent defense standards.
- Machinery Parts:Covers a wide array of industrial components, including gears, housings, and structural elements for pumps and valves. These applications prioritize wear resistance and operational reliability.
- Components:This broad category encompasses various sub-assemblies and individual pieces used in larger systems or products.
- Tools:Specialized cutting, forming, or holding implements requiring precision and hardness for manufacturing and maintenance.
Performance criticality is paramount for Military Equipment applications, whereas Machinery Parts focus on durability and cost-effectiveness.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized industrial zones in Germany, the United States, and China drive significant market concentration for investment casting. These areas serve as key manufacturing hubs for the automotive and medical device sectors. The strategic placement of foundries within these zones optimizes supply chain logistics and caters to localized industry demands.
Germany
Demand for intricate components for automotive powertrains and advanced industrial machinery fuels the investment casting market in Germany. The CE marking directive ensures product safety and quality across the European Union, influencing manufacturing processes. Industrial clusters in Bavaria and North Rhine-Westphalia specialize in high-precision casting for German engineering firms.
United States
The aerospace sector's need for high-performance turbine blades and the medical industry's demand for biocompatible implants propel investment casting growth in the United States. FAA certifications for flight-critical parts and FDA regulations for medical devices mandate stringent quality control. The Pacific Northwest region, particularly around Seattle, concentrates aerospace casting activities.
China
China's automotive industry and its expanding industrial machinery sector create substantial volume demand for investment cast parts. Compliance with GB standards is essential for market access and product quality within the country. The Yangtze River Delta region, including cities like Shanghai and Nanjing, serves as a major manufacturing base for these components.
Japan
Precision components for the automotive industry and specialized industrial equipment drive demand for investment casting in Japan. METI policies support advanced manufacturing technologies, fostering innovation in casting processes. The Chubu region, centered around Nagoya, remains a critical hub for automotive component manufacturing.
India
The growing industrial machinery and automotive sectors in India require durable and precise investment cast parts. BIS standards ensure product quality and material specifications for locally manufactured goods. Manufacturing centers in Maharashtra, such as Pune and Mumbai, are expanding their capabilities for heavy engineering components.
Investment Casting Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists in the investment casting market, creating a tiered competitive structure. This market features large-scale integrated suppliers alongside niche providers with specialized alloy expertise. Geographic expansion and strategic partnerships remain dominant competitive moves among foundries.
Large-scale integrated players like Precision Castparts Corp. represent the high-performance aerospace and power generation segments, leveraging extensive capabilities. CIREX Group exemplifies a regional specialist, focusing on complex, small-to-medium batch production for the European automotive sector. MetalTek International occupies a position as an alloy expert, differentiating through its wide range of material expertise and centrifugal casting technologies.
| Leading Market Players |
|---|
| CFS Foundry |
| Hitchiner Manufacturing |
| Precision Castparts Corp. |
| CIREX Group |
| Milwaukee Precision Casting |
| Impro Precision Industries Limited |
| Alcoa Corporation |
| Zollern GmbH & Co. KG |
| MetalTek International |
| Others |
Cost & Logistics Intelligence
European Union's REACH framework directly impacts material availability, gating access to qualified casting suppliers and influencing premium-tier pricing for compliant components.
Pricing Analysis
Input material cost volatility creates margin pressure for foundries specializing in aerospace-grade alloys. Contract-based long-term agreements dominate for high-performance sectors like aerospace and medical devices. Price differentiation stems from stringent FAA and FDA certifications, complex geometry requirements, and specialized alloy processing capabilities. Automotive buyers exhibit high price sensitivity, contrasting with the lower sensitivity of aerospace and medical device manufacturers.
Supply Chain Analysis
Skilled labor scarcity in specialized industrial zones across Germany, the United States, and China poses a significant supply chain constraint. The investment casting supply chain relies heavily on raw materials such as titanium, cobalt, and specialized refractory materials. Price volatility in these key raw materials presents a structural risk for foundries globally. Integrated procurement models, bundling casting with post-processing services, are becoming the dominant distribution structure for demanding end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The investment casting market is undergoing a consolidation phase, driven by the increasing regulatory compliance burden that strains smaller, less capitalized foundries.
For Market Incumbents:To counter the additive manufacturing threat, established foundries must invest heavily in digital twin integration and robotic automation for shell building. Securing long-term supply agreements for critical raw materials mitigates price volatility risks. Expanding material qualification and process certifications, especially for FAA and FDA standards, reinforces market position in high-value segments.
For New Entrants and Emerging Players:Small-to-medium batch producers requiring rapid prototyping represent an underserved buyer archetype for new entrants. Focusing on medical device expansion, particularly custom orthopedic implants, offers significant potential due to demand for biocompatible titanium alloys. Leveraging 3D printing for wax patterns provides a key go-to-market angle by shortening tooling lead times and enabling intricate designs.
For Investors and Strategic Acquirers:The integration of AI-driven process control across foundry operations is the leading indicator that signals a new era of efficiency and quality. The investment casting market offers sustained growth over the next decade due to critical aerospace and medical demands. Acquisition targets should include mid-sized specialists with advanced material science expertise or strong digital manufacturing capabilities. Adoption rates of digital twin technologies serve as a critical signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Robotics Deployment | Automating shell building processes enhances consistency and reduces scrap rates for aerospace components. |
| Digital Twin Integration | Optimizing casting parameters pre-production minimizes defects and accelerates time-to-market for complex parts. |
| Material Certification Expansion | Broadening FAA and FDA compliant alloy offerings unlocks new opportunities in critical end-user segments. |
| 3D Printing for Patterns | Shortening tooling lead times supports rapid prototyping and small-batch production for medical devices. |
| Bundled Service Offerings | Providing integrated casting, machining, and NDT services simplifies procurement for defense contractors. |
Research Approach
Trade association data, regulatory filings from FAA and FDA, and customs records anchored secondary inputs for this market analysis. Primary research involved in-depth interviews with foundry engineers, metallurgists, procurement managers from aerospace and medical device firms, and R&D leads. This approach facilitated a robust bottom-up and top-down triangulation of market data and trends.
Quantitative data streams were reconciled through a multi-variate analytical framework to project market trajectories across the analysis window. Segmentation dimensions included product type (titanium, ferrous alloys), end-user (aerospace, medical, automotive), technology (3D printing, lost wax), and geographic region. Compound annual growth rates were derived from regression analysis, incorporating expert consensus and historical performance, with raw material price forecasts and end-user sector production volumes serving as key inputs.
Revisions become necessary when significant shifts in raw material supply, regulatory mandates, or disruptive additive manufacturing technologies materialize. Forecasts reflect assumptions regarding technological adoption and demand patterns; material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
High Speed Steels Market
Industrial Materials
Wire Drawing Dies Market
Industrial Materials
Wear-Resistant Welding Wire Market
Industrial Materials
Tension Spring Market
Industrial Materials
North America Non-Structural Stainless Steel Fasteners Market
Industrial Materials
Compression Gas Spring Market
Industrial Materials
Extruders Market
Industrial Materials
Global Glass Wool Board Sales Market
Industrial Materials
Plastic Recycling Machine Market
Industrial Materials
Pultrusion Products Market
Industrial Materials
Neoprene Foam Market
Industrial Materials
North America Industrial Fasteners Market
Industrial Materials
Global Cast Acrylic Sheet Market
Industrial Materials
Heat-Insulation Boards for Industrial Equipment Market
Industrial Materials
Foam Insulation Market
Industrial Materials
Southeast Asia Industrial Flooring Market