
 Medical Fluoropolymers Market | 2026-2036
Medical Fluoropolymers Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Fluoropolymers Market Intelligence
Medical fluoropolymer distribution is tilting toward direct OEM partnerships and specialized compounder networks as device makers seek tighter lot traceability. Daikin Industries sustains its position through captive resin-to-film verticality in Asian supply chains. W. L. Gore & Associates differentiates via proprietary expanded PTFE architectures for implantable applications. Solvay SA anchors European supply through Antwerp-based polymerization assets serving tier-one catheter brands.
Medical fluoropolymers are high-performance polymers characterized by carbon-fluorine backbone bonds delivering chemical inertness, thermal stability up to 260°C, and ultra-low surface energy for non-stick blood-contacting surfaces. These properties make them indispensable for minimally invasive devices requiring lubricity, sterilization resilience, and long-term implant biocompatibility. PTFE films dominate catheter liner applications due to lowest coefficient of friction among available medical polymers, while PFA extrusions capture growth in multi-lumen tubing for advanced endoscopy where melt-processability enables complex geometries. FEP coatings command premium positioning in stent delivery systems requiring optical clarity combined with flex fatigue resistance.
FDA 21 CFR 177.1550 perfluorocarbon resin regulations govern food-contact overlap with medical device polymers, while EU MDR Annex I general safety and performance requirements mandate biological evaluation per ISO 10993 series for all blood-contacting fluoropolymer components. REACH restrictions on PFAS precursor substances are forcing reformulation roadmaps across European compounders. Stakeholders must monitor emerging EPA toxicity assessments for long-chain perfluoroalkyl substances and their potential to trigger state-level procurement bans affecting hospital purchasing consortia.
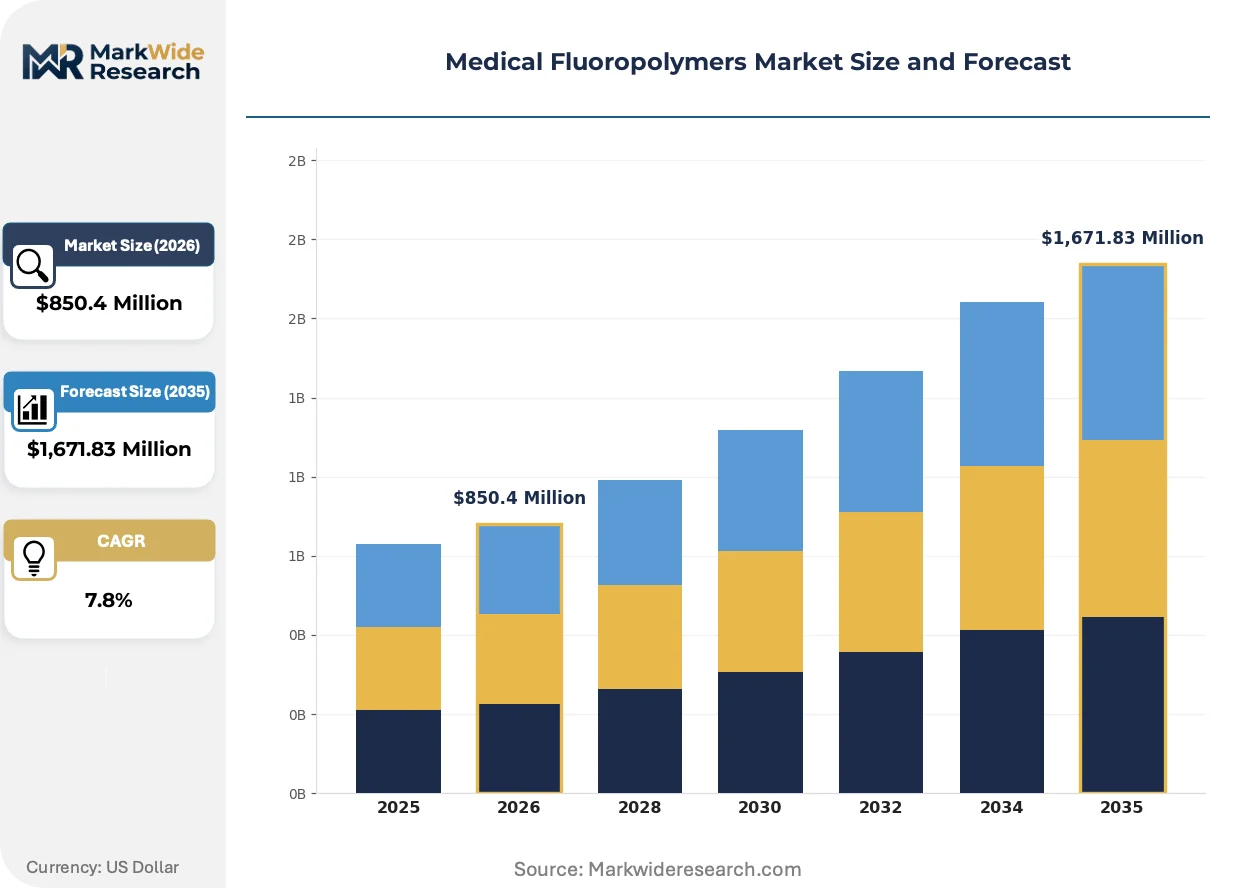
Market Dynamics
Catheter OEMs are consolidating fluoropolymer supply relationships to satisfy EU MDR traceability mandates and FDA 510(k) biocompatibility documentation requirements, compressing vendor lists and favoring resin-to-device integrated suppliers.
Growth Catalysts
- Minimally invasive surgery expansion:Laparoscopic and interventional cardiology procedures require lubricious fluoropolymer liners that reduce vessel trauma, pulling demand from PTFE and PFA extrusion specialists.
- EU MDR substance documentation:The regulation's Annex I general safety requirements mandate ISO 10993 biological evaluation for all blood-contacting components, forcing device makers toward pre-qualified fluoropolymer grades with existing toxicology dossiers.
- German precision device cluster:Stuttgart and Freiburg host concentrated catheter manufacturing operations that source fluoropolymer films and tubing through localized compounder networks.
Market Restraints
- Fluoromonomer feedstock volatility:Tetrafluoroethylene and hexafluoropropylene prices track chlorodifluoromethane refrigerant phase-down schedules under F-Gas Regulation, creating input cost unpredictability for European compounders.
- Asian resin concentration:Captive fluoropolymer polymerization capacity in Japan and China limits Western compounders' negotiating leverage for virgin resin supply.
- Long-chain PFAS toxicity assessments:EPA emerging contaminant evaluations for perfluorooctanoic acid precursors threaten state-level procurement restrictions that would constrain hospital purchasing consortia.
Strategic Opportunities
- Bioresorbable stent coatings:Fluoropolymer-fluoropolymer hybrid formulations that balance lubricity with controlled degradation timelines address unmet needs in pediatric and coronary applications.
- India medical device PLI scheme:Production-linked incentives for domestic catheter manufacturing create localized fluoropolymer compounding demand as global OEMs establish Bangalore and Hyderabad assembly operations.
- Optical coherence tomography catheter compatibility:FEP's refractive index matching and flex fatigue resistance enable next-generation imaging catheter designs requiring sub-millimeter wall thickness consistency.
Industry Challenges
- ISO 10993-18 chemical characterization expertise:Extractables and leachables testing for fluoropolymer additives requires specialized analytical chemistry capabilities that compounders struggle to staff.
- Multi-site polymerization audit coordination:Device OEMs demand simultaneous qualification of primary and secondary resin sources, extending vendor onboarding timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Fluoropolymers Market |
| Market Size in 2026 | $850.4 Million |
| Market Size in 2035 | $1,671.83 Million |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, ETFE Application: Medical Devices, Catheters, Tubing, Sealants End User: Hospitals, Clinics, Healthcare Facilities, Laboratories Form: Films, Rods, Sheets, Coatings |
| Companies Covered | 3M Company, Saint-Gobain, Daikin Industries, Ltd., AGC Inc., W. L. Gore & Associates, Inc., The Chemours Company, Arkema, Dongyue Group Limited, Solvay SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Fluoropolymers Market Strategic Shifts & Innovations
Fluoropolymer processing methods are pivoting toward additive manufacturing compatibility and in-situ surface modification, enabling patient-specific device geometries while preserving the material's intrinsic blood compatibility.
Multi-lumen catheter tubing fabrication is migrating from conventional ram extrusion toward continuous melt-processed PFA architectures. Interventional cardiology device manufacturers in Germany and the United States are adopting these geometries for drug-eluting balloon delivery systems. The shift is compressing lead times for complex cross-section profiles while raising barrier-to-entry for extrusion houses lacking precision thermal control capabilities.
REACH restrictions on per- and polyfluoroalkyl substances are forcing European compounders to reformulate processing aids and nucleating agents. The regulation's restriction roadmap threatens existing medical device masterfile approvals for legacy fluoropolymer grades. German catheter brands are accelerating alternative substance qualification timelines to maintain CE marking continuity ahead of sunset dates.
Hospital purchasing consortia are consolidating fluoropolymer component suppliers to reduce qualification burden and lot-to-lot variability exposure. Cardiovascular device procurement teams now mandate single-source resin genealogy documentation from catheter OEMs. This concentration is most visible in United States integrated delivery networks and German university hospital systems, where procurement committees prioritize vendors with captive polymerization assets over merchant compounders.
Medical Fluoropolymers Market Segmentation
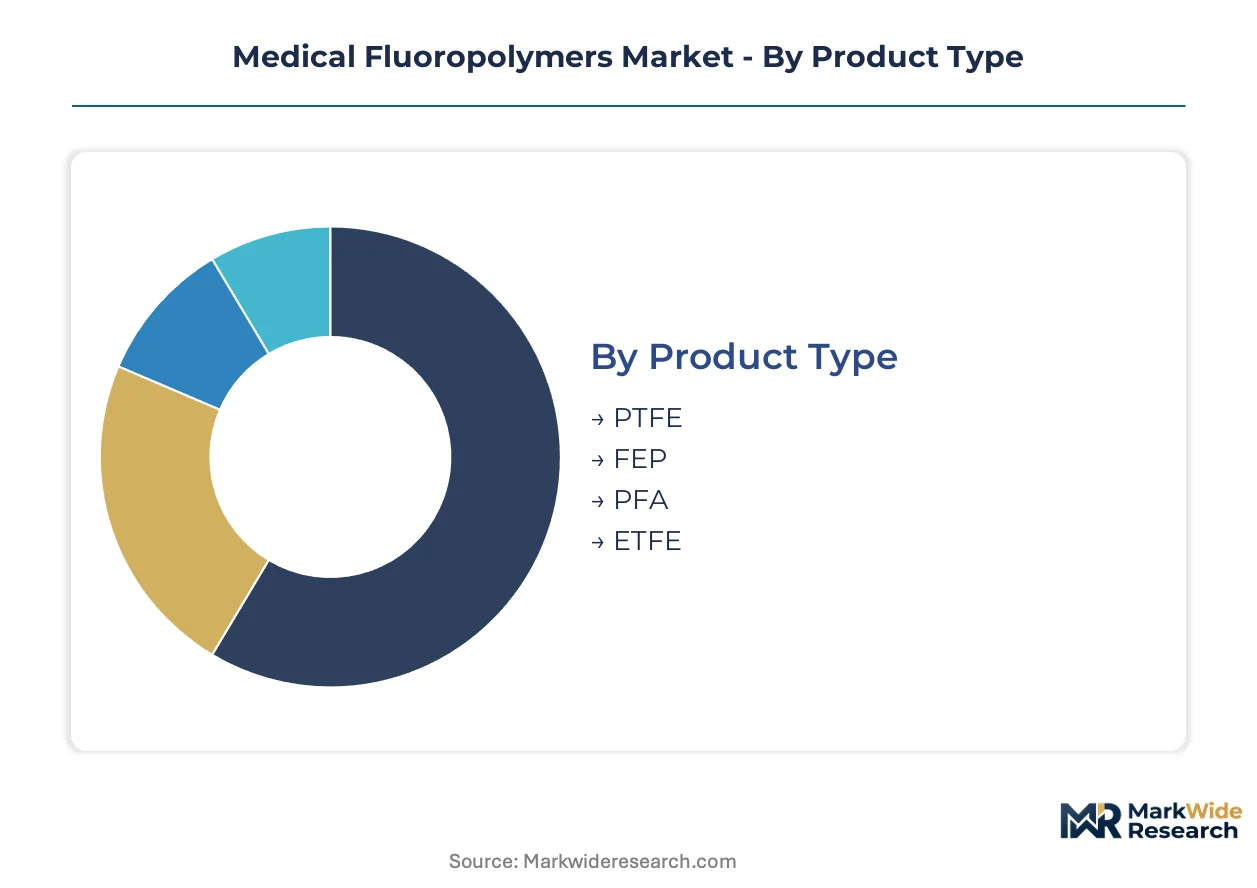
Segmentation in medical fluoropolymers reveals how material specifications align with procedural requirements. Device OEMs select grades based on sterilization resilience, lubricity thresholds, and regulatory pre-qualification status.
Product Type:
PTFE dominates catheter liner applications where coefficient of friction determines clinical performance. FEP and PFA grades compete on melt-processability for complex geometries.
- PTFE:Sintered and expanded architectures deliver the lowest surface energy among medical polymers. Catheter manufacturers in Germany's Stuttgart cluster specify PTFE liners for coronary guidewires requiring sub-0.1 friction coefficients against vessel walls.
- FEP:Melt-processable fluoropolymer with optical clarity matching refractive indices of blood and tissue. Endoscopy device OEMs favor FEP for imaging catheter sheaths where light transmission preserves image fidelity.
- PFA:Combines PTFE-like chemical resistance with thermoplastic processability. Multi-lumen tubing extrusion for drug-eluting balloon catheters exploits PFA's flow characteristics under precision thermal control.
- ETFE:Tougher mechanical profile suits structural components requiring puncture resistance. Limited medical adoption concentrates in pump housings and valve membranes.
Established volume favors PTFE; emerging adoption favors PFA.
Application:
Application segmentation tracks procedural volume and regulatory qualification burden. Blood-contacting devices demand ISO 10993 dossiers that lock in material specifications.
- Medical Devices:Implantable pumps, pacemaker leads, and artificial heart components exploit fluoropolymer dielectric stability and biocompatibility. FDA 510(k) clearances for these devices carry material genealogy requirements that perpetuate incumbent resin grades.
- Catheters:Interventional cardiology and electrophysiology procedures drive specification for lubricious liners and braided shafts. German catheter OEMs source PTFE films through Freiburg-area compounder networks to satisfy EU MDR traceability mandates.
- Tubing:Fluid transfer and sampling lines leverage chemical inertness against aggressive disinfectants. Multi-lumen extrusions for critical care applications command premium positioning due to dimensional tolerance requirements.
- Sealants:Gaskets and O-rings in diagnostic equipment face less stringent biocompatibility thresholds. This segment absorbs reformulation pressure as REACH restrictions phase out legacy processing aids.
Catheter applications command the steepest expansion trajectory; sealant demand faces substitution pressure from silicone alternatives.
End User:
Procurement concentration shapes material qualification economics. Integrated delivery networks consolidate vendor lists to reduce lot-to-lot variability exposure.
- Hospitals:Cardiovascular service lines in university hospital systems mandate single-source resin documentation. German hospital purchasing consortia prioritize suppliers with captive polymerization assets.
- Clinics:Outpatient interventional centers drive disposable catheter consumption. Volume concentration in US ambulatory surgery centers favors standard-grade fluoropolymer specifications.
- Healthcare Facilities:Long-term care and dialysis centers generate steady demand for fluid management tubing. Price sensitivity here favors FEP over PTFE where performance specifications permit.
- Laboratories:Analytical and research applications exploit chemical resistance for aggressive reagent handling. Smaller lot sizes and custom formulations characterize this fragmented demand pool.
Hospital procurement consolidation favors standardized grades; laboratory demand sustains specialty compounder margins.
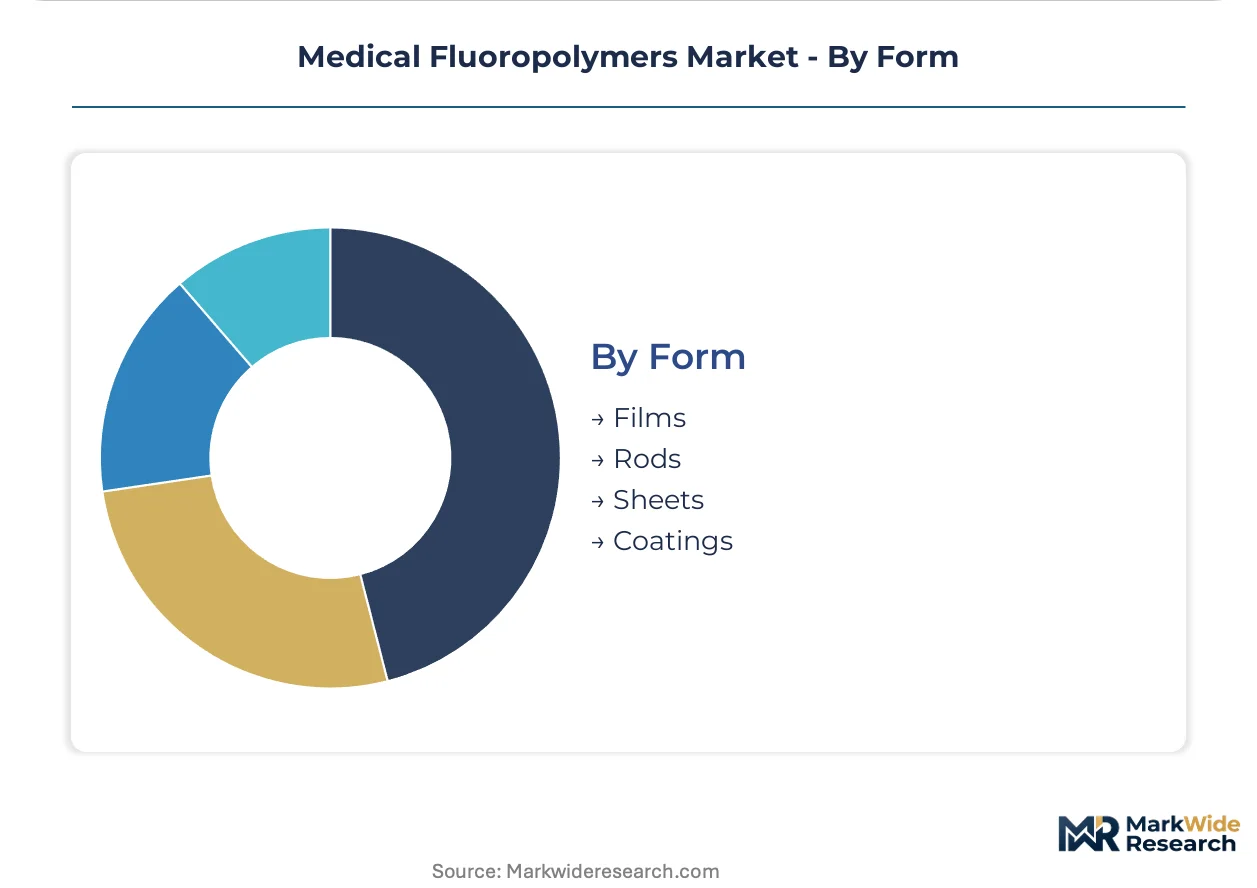
Form:
Form factor determines processing method and supply chain configuration. Film and tubing production concentrate with extrusion specialists; coatings remain captive to device OEMs.
- Films:Skived and cast PTFE films serve catheter liner and wrap applications. Thickness consistency below 25 micrometers separates qualified suppliers from commodity producers.
- Rods:Compression-molded and extruded rod stock machines into precision seals and bearings. Dimensional stability under thermal cycling determines medical-grade qualification.
- Sheets:Gasket and membrane applications in diagnostic equipment. Broader thickness range and lower purity requirements than film products.
- Coatings:Dip and spray-applied fluoropolymer layers on stents, guidewires, and surgical instruments. Application equipment and surface preparation chemistry create high switching costs for device manufacturers.
Film supply concentrates with Asian and European extrusion houses; coating capability remains integrated within major device OEMs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure anchors European fluoropolymer distribution, while Asian resin flows concentrate through Singapore's Jurong Island petrochemical hub. These logistics arteries shape regional procurement patterns for medical device manufacturers seeking qualified material supply.
United States
Cardiovascular device OEMs in Minneapolis and Irvine drive specification for PTFE catheter liners with FDA 510(k) material genealogy documentation. EPA emerging contaminant assessments for long-chain PFAS precursors threaten state-level procurement restrictions affecting hospital purchasing consortia. Boston's medical device corridor sources fluoropolymer films through qualified compounder networks serving implantable lead applications.
Germany
EU MDR Annex I biological evaluation mandates force device makers toward pre-qualified fluoropolymer grades with existing ISO 10993 dossiers. Stuttgart and Freiburg host concentrated catheter manufacturing operations sourcing films and tubing through localized compounder networks. REACH restrictions on PFAS precursor substances are accelerating reformulation roadmaps across Baden-Württemberg compounders.
China
Domestic catheter production expansion in Suzhou and Shenzhen pulls fluoropolymer resin demand through NMPA regulatory pathways. Captive polymerization capacity in Japan and China limits Western compounders' negotiating leverage for virgin resin supply. Shanghai's medical device free trade zone concentrates import substitution efforts for high-purity PTFE grades.
Japan
Daikin Industries' captive resin-to-film verticality sustains supply chain control for Asian medical device OEMs. PMDA quality management system requirements perpetuate incumbent resin specifications for long-implant applications. Osaka-based polymerization assets serve tier-one catheter brands with lot traceability documentation exceeding EU MDR standards.
India
Production-linked incentives for domestic catheter manufacturing create localized fluoropolymer compounding demand as global OEMs establish Bangalore and Hyderabad assembly operations. CDSCO medical device rules mandate biological evaluation for blood-contacting components, favoring suppliers with pre-qualified material dossiers. Maharashtra's emerging device corridor attracts compounder investment to serve export-oriented catheter operations.
Medical Fluoropolymers Market Key Industry Players
On the supply side, the industry is consolidating around resin-to-device integrated suppliers capable of delivering lot traceability documentation demanded by EU MDR and FDA biocompatibility mandates. Three archetypes dominate: captive polymerization specialists with backward integration into monomer supply, precision extrusion houses serving catheter OEMs with qualified film and tubing geometries, and diversified chemical conglomerates leveraging antitrust polymerization assets for medical-grade qualification. Competitive moves center on multi-site polymerization audit coordination to satisfy simultaneous primary and secondary source requirements, and strategic partnerships with hospital purchasing consortia seeking single-source resin genealogy.
Within the captive polymerization tier, Daikin Industries, Ltd. exemplifies vertical control from fluoromonomer through finished film, while Solvay SA anchors European supply through Antwerp-based assets. W. L. Gore & Associates, Inc. occupies a differentiated position via proprietary expanded PTFE architectures. These three represent distinct strategic postures: Asian supply chain integration, European regulatory proximity, and implantable application specialization respectively.
| Leading Market Players |
|---|
| 3M Company |
| Saint-Gobain |
| Daikin Industries, Ltd. |
| AGC Inc. |
| W. L. Gore & Associates, Inc. |
| The Chemours Company |
| Arkema |
| Dongyue Group Limited |
| Solvay SA |
| Others |
Cost & Logistics Intelligence
The Port of Rotterdam's chemical handling infrastructure anchors European fluoropolymer distribution, connecting Asian resin flows through Singapore's Jurong Island hub to catheter manufacturers in Germany and the United States. Freight cost volatility across this corridor amplifies price differentiation between captive polymerization specialists and merchant compounders, while EU MDR traceability mandates compress vendor lists and consolidate purchasing power among hospital consortia.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies medical fluoropolymer procurement. Premium tiers command positioning through ISO 10993 pre-qualification and FDA masterfile documentation, while standard grades serve volume catheter OEMs with established biocompatibility dossiers. Cost compression in economy tiers intensifies as REACH restrictions on PFAS processing aids force reformulation investments. Hospital purchasing committees exhibit lowest price sensitivity for implantable-grade PTFE, whereas outpatient clinic networks driving disposable catheter consumption prioritize standard specifications.
Supply Chain Analysis
Export-control scrutiny on fluoropolymer polymerization technology limits Western equipment flows to Chinese resin producers, reinforcing supply concentration in Japan and China. Virgin tetrafluoroethylene and hexafluoropropylene monomers feed from chlorodifluoromethane refrigerant phase-down schedules under F-Gas Regulation. Single-source vulnerability concentrates in Daikin Industries' captive Asian vertical integration, threatening negotiating leverage for European compounders lacking backward integration into monomer supply. Distribution runs through direct OEM partnerships and specialized compounder networks serving Germany's Stuttgart-Freiburg precision device cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical fluoropolymer demand is accelerating through minimally invasive surgery expansion and EU MDR regulatory inflection, creating asymmetric returns for positioned suppliers.
For Market Incumbents: Entrench market position through multi-site polymerization audit coordination that satisfies simultaneous primary and secondary source requirements from tier-one catheter OEMs. Deepen backward integration into fluoromonomer supply to mitigate feedstock volatility from F-Gas Regulation phase-down schedules. Priority investment targets ISO 10993-18 chemical characterization capabilities as extractables testing expertise scarcity widens competitive moats. For New Entrants and Emerging Players: Pursue India's production-linked incentive corridor for domestic catheter manufacturing, where CDSCO biological evaluation requirements favor suppliers with pre-qualified material dossiers. Target bioresorbable stent coating formulations as the most penetrable white-space application, balancing fluoropolymer lubricity with controlled degradation timelines. Go-to-market leverage centers on optical coherence tomography catheter compatibility, exploiting FEP's refractive index matching for sub-millimeter imaging sheath designs. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with antitrust polymerization assets underutilized for medical-grade qualification. Long-term viability frames around regulatory pre-qualification scarcity and hospital procurement consolidation favoring resin-genealogy documentation. Signal to monitor: EPA toxicity assessments for long-chain perfluoroalkyl substances triggering state-level procurement restrictions that would reshape hospital purchasing consortia vendor selection.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Annex I Compliance Investment | ISO 10993 biological evaluation dossiers lock in catheter OEM specifications and perpetuate incumbent resin grades. |
| Backward Integration into Fluoromonomer Supply | Captive tetrafluoroethylene production insulates European compounders from F-Gas Regulation feedstock volatility. |
| India PLI Scheme Localization | Bangalore and Hyderabad assembly operations create captive fluoropolymer compounding demand for export-oriented catheter production. |
| Multi-Site Polymerization Audit Coordination | Simultaneous primary and secondary source qualification satisfies FDA 510(k) material genealogy requirements. |
| REACH Reformulation Roadmap Execution | Alternative substance qualification ahead of PFAS sunset dates preserves CE marking continuity for German catheter brands. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with catheter OEM procurement directors, fluoropolymer compounder technical leads, hospital purchasing committee members, and regulatory affairs specialists managing FDA 510(k) submissions. Secondary validation drew from FDA 21 CFR device clearances, ECHA REACH restriction roadmaps, EU MDR technical documentation, and customs trade flow records. Bottom-up segmentation modeling triangulated against top-down industry association capacity estimates.
Calibration anchored volume projections to procedural volume trajectories in interventional cardiology and electrophysiology, with price evolution tracked across PTFE, FEP, and PFA grade tiers. Segmentation dimensions spanned product type, application, end user, and form factor, with regional regulatory cluster differentiation. CAGR derivation incorporated fluoromonomer feedstock cost dynamics and hospital procurement consolidation patterns. Industry-specific inputs included catheter OEM vendor consolidation timelines and EPA emerging contaminant assessment trajectories.
Macroeconomic conditions sit as an overlay; deviation in fluoromonomer pricing volatility or freight corridor disruption would shift the trajectory. Forecasts reflect documented assumptions on regulatory pre-qualification timelines and REACH restriction enforcement. Material shifts in EPA long-chain PFAS toxicity classifications or EU MDR substance documentation requirements would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Ion Exchange Resin Market
Polymers & Resins
Metallocene Polyethylene Market
Polymers & Resins
Global Polypropylene Random Copolymer Market
Polymers & Resins
Global Protein a Resin Market
Polymers & Resins
Africa Polyamide Market
Polymers & Resins
Europe Medical Polyethylene Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Renewable Polyethylene Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
North America Geopolymer Market
Polymers & Resins
South America Polycarbonate (PC) Market
Polymers & Resins
Europe Polyamide Market
Polymers & Resins
Polycarbonate Glazing Market