
 Long-Chain Polyamide Market | 2026-2036
Long-Chain Polyamide Market Size, Share, and Industry Trends Forecast 2026-2036
Long-Chain Polyamide Market Outlook
Technical support and material qualification services are repositioning how resin suppliers capture value beyond commodity polymer sales. BASF SE leverages its Ultramid portfolio to anchor long-chain formulations in thermal management applications for electric vehicles. Arkema competes through its Rilsan PA 11 platform, which dominates bio-based polyamide supply with castor-oil derived chemistry.
Long-chain polyamides are semi-crystalline thermoplastics with repeating amide linkages separated by ten or more methylene units, delivering lower moisture absorption and superior chemical resistance than standard PA 6 or PA 66. These properties suit fuel lines, pneumatic tubing, and cable sheathing where dimensional stability under hydrolytic stress matters. PA 12 leads among product types due to its established pipeline in automotive fuel systems and mature processing infrastructure across European compounding houses. Aerospace application demand is accelerating fastest, driven by FAA and EASA flame-retardancy mandates that favor halogen-free cable jacketing. Granule form occupies the largest volume share, though fiber form commands premium positioning in medical catheter braiding where lot-to-lot consistency dictates supplier selection.
EPA fuel permeation standards and ECHA REACH restrictions on phthalate plasticizers are tightening material specifications, forcing reformulation toward inherently flexible long-chain grades without external additives. China's SAMR enforces GB standards for automotive fluid handling that increasingly reference ISO 7628 test protocols for polyamide tubing. Stakeholders must monitor regulatory divergence between California Air Resources Board thresholds and EU F-Gas Regulation amendments, as these will determine which polymer architectures qualify for next-generation thermal management systems.
Market Dynamics
Automotive lightweighting mandates in Germany and China are compressing resin substitution timelines for fuel line systems, forcing compounders to qualify long-chain polyamide grades faster than historical material approval cycles.
Growth Catalysts
- EPA Fuel Permeation Standards:Tier 3 emission limits in the United States mandate sub-15 mg/m²/day permeation rates, accelerating PA 12 adoption in multi-layer tubing architectures.
- Electric Vehicle Thermal Management:Battery pack cooling loops require hydrolysis-resistant polymers that maintain dimensional stability across -40°C to 150°C operating windows.
- China's Dual Carbon Goals:SAMR enforcement of GB standards for automotive fluid handling aligns with ISO 7628 test protocols, creating regulatory pull for qualified long-chain grades.
Market Restraints
- Castor Oil Supply Concentration:Over 80 percent of global sebacic acid feedstock originates from Indian and Brazilian castor bean cultivation, exposing PA 11 and PA 1010 producers to monsoon-dependent harvest volatility.
- Lactam Ring Closure Energy Intensity:PA 12 synthesis requires high-pressure hydrogenation of cyclododecatriene, a C12 intermediate with concentrated European production that elevates energy input costs relative to shorter-chain alternatives.
- REACH Authorization Burden:ECHA scrutiny of C6-C10 diacid precursors extends registration timelines for new long-chain formulations, delaying commercialization by 18-24 months.
Strategic Opportunities
- Medical Catheter Braiding:Fiber-grade PA 12 and PA 11 with lot-to-lot molecular weight consistency command 40-60 percent price premiums over industrial granules in minimally invasive device supply chains.
- FAA-EASA Harmonized Flame Retardancy:Halogen-free cable jacketing mandates for commercial aircraft interiors favor inherently low-smoke long-chain polyamides over PVC and fluoropolymer incumbents.
- Wind Turbine Cable Sheathing:Offshore installations in the North Sea and Baltic require hydrolytically stable jacketing materials that withstand 25-year salt spray exposure without degradation.
Industry Challenges
- Polymer Rheology Expertise Gap:Long-chain polyamides exhibit narrow processing windows between degradation and incomplete crystallization, requiring specialized compounding talent scarce outside Bavaria and Michigan engineering centers.
- Multi-Layer Co-Extrusion Certification:Fuel line systems require ISO 7628 compliance across adhesive tie-layer compatibility, barrier layer continuity, and electrostatic discharge resistance — a three-year qualification cycle that locks suppliers into incumbent relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Long-Chain Polyamide Market |
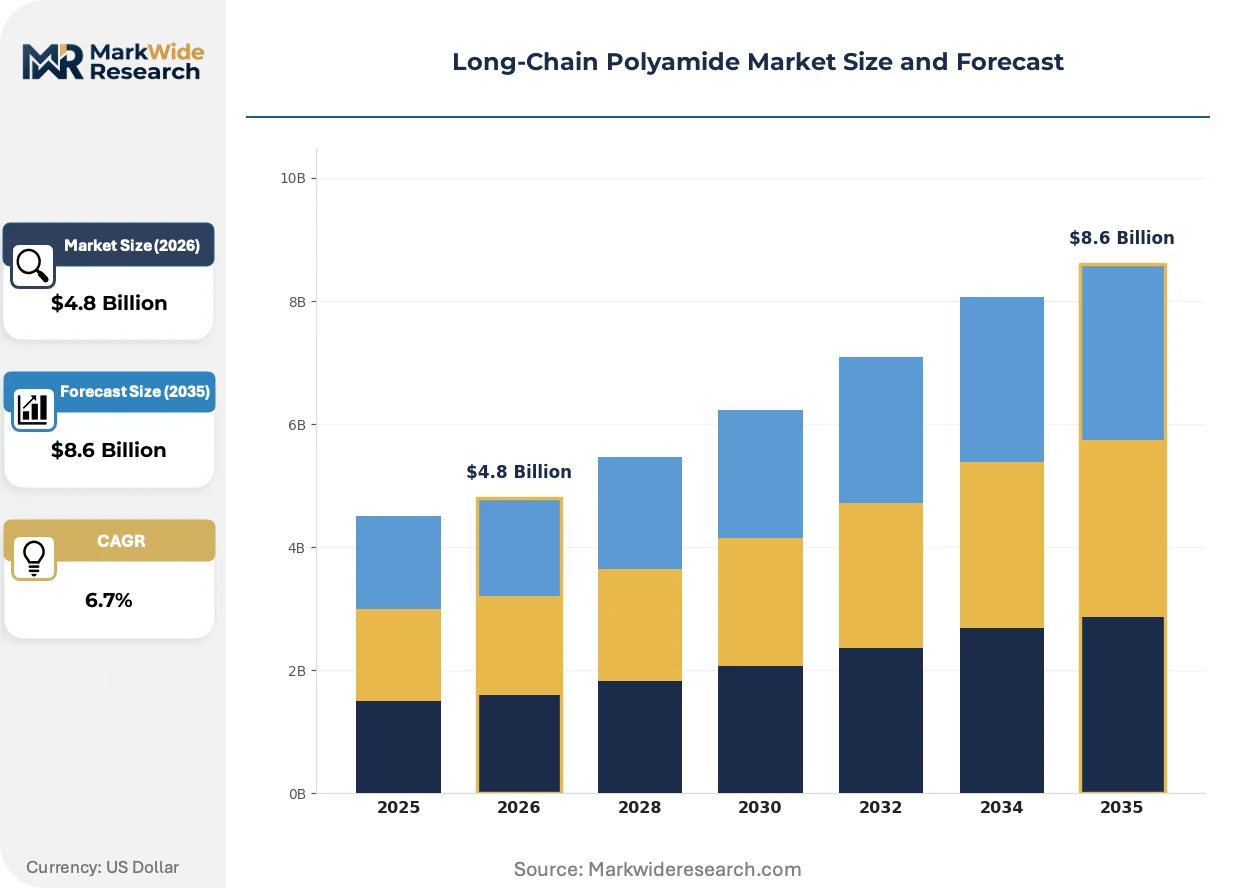
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA 6, PA 66, PA 610, PA 12 Application: Aerospace, Automotive, Electronics, Textiles End User: Consumer Goods, Industrial Equipment, Construction, Healthcare Form: Granules, Powders, Films, Fibers |
| Companies Covered | BASF SE, Arkema, Celanese Corporation, Evonik Industries AG, Asahi Kasei Corporation, Toray Industries, Inc., Ascend Performance Materials, DuPont de Nemours, Inc., EMS-Chemie Holding AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Long-Chain Polyamide Market Strategic Shifts
Material qualification services are displacing commodity resin transactions as the primary value capture mechanism, with compounders bundling thermal modeling, mold flow simulation, and regulatory documentation into supply agreements.
Reactive extrusion compounding is modularizing how fuel line manufacturers integrate functional additives directly into PA 12 base resin, eliminating separate masterbatch handling steps. Tier 1 suppliers in Stuttgart and Shanghai are adopting twin-screw extrusion lines configured for in-situ viscosity modification. This convergence of polymerization and compounding is compressing the traditional three-tier supplier structure into direct resin-to-tube relationships.
ECHA F-Gas Regulation amendments are phasing down hydrofluorocarbon blowing agents used in foamed cable jacketing, redirecting specification engineers toward nitrogen-gas foamed long-chain polyamides with equivalent dielectric properties. Wire harness producers in the Czech Republic and Romania are requalifying halogen-free PA 12 grades ahead of 2027 restriction deadlines. The regulatory friction is accelerating substitution in building wire applications previously dominated by PVC.
Automotive OEMs are consolidating qualified resin suppliers to single-source arrangements per fuel system platform, reversing the historical dual-source redundancy model. Procurement teams at engineering centers in Munich, Detroit, and Shanghai are negotiating five-year volume commitments with locked pricing in exchange for dedicated technical support resources. This concentration is visible most acutely in battery electric vehicle programs where thermal management tubing represents a new specification category without incumbent supplier relationships.
Long-Chain Polyamide Market Segmentation
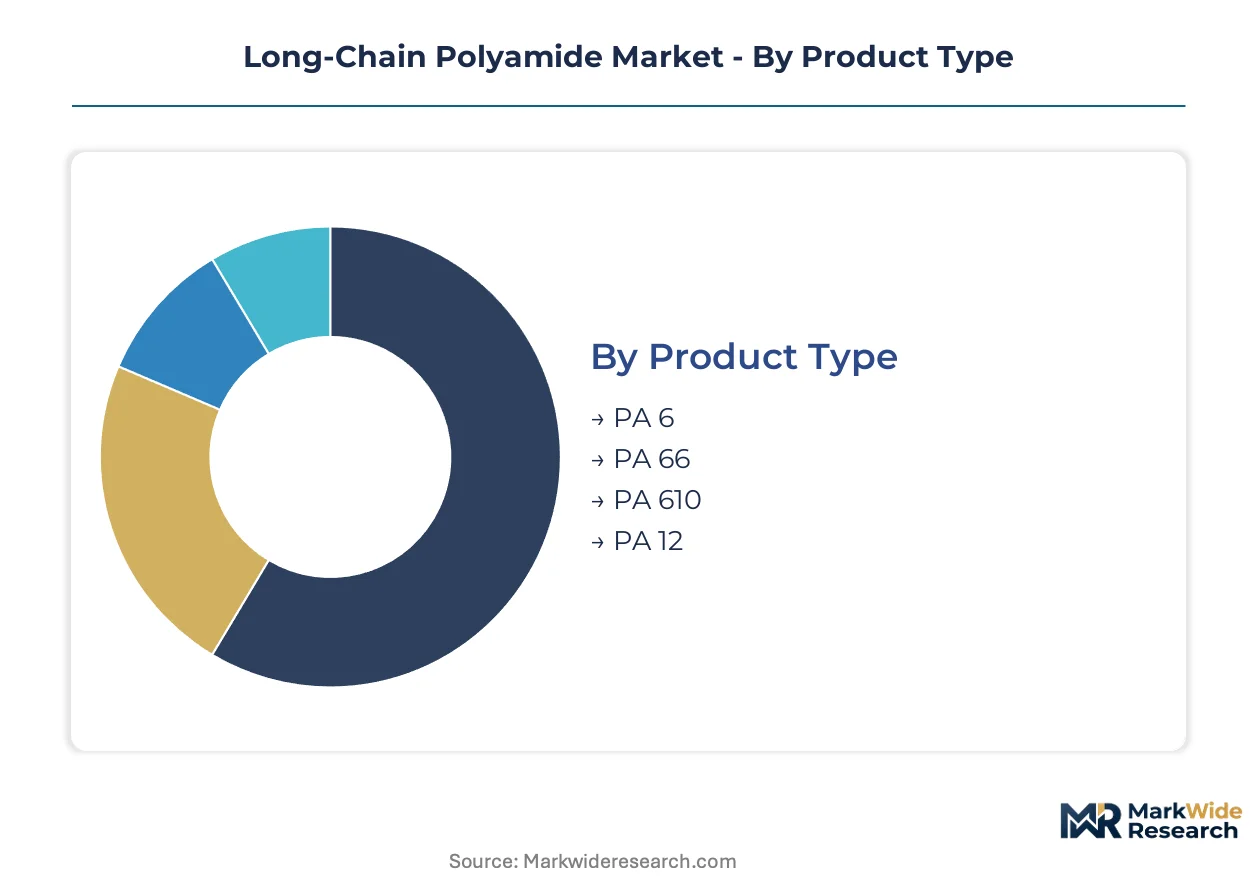
Long-chain polyamide procurement decisions cascade through multiple technical dimensions, from monomer chemistry to final form factor. Specification engineers weight moisture absorption coefficients against processing infrastructure compatibility when locking in multi-year supply agreements.
Product Type:
Specialty resin production concentrates among European and Asian compounders with captive lactam hydrogenation capacity.
- PA 12:Semi-crystalline thermoplastic synthesized via high-pressure hydrogenation of cyclododecatriene delivers the lowest moisture absorption among commercial polyamides. Automotive fuel line manufacturers in Germany and China specify PA 12 for multi-layer tubing architectures meeting EPA Tier 3 permeation thresholds. The established European compounding infrastructure anchors supply security for this grade.
- PA 610:Partially bio-based polymer combining sebacic acid from castor oil with hexamethylenediamine offers intermediate properties between PA 6 and long-chain alternatives. Industrial hose producers favor PA 610 where moderate chemical resistance balances cost-positioning against fully bio-derived PA 11. Indian and Brazilian castor harvest volatility constrains feedstock planning.
- PA 6:Short-chain workhorse polymer with six-carbon backbone dominates commodity applications where moisture sensitivity is manageable.
- PA 66:Higher melting point and stiffness profile suits under-hood automotive components exposed to elevated thermal loads.
PA 12 absorbs the bulk of installed capacity; PA 610 is expanding most quickly amid bio-based feedstock diversification mandates.
Application:
End-use demand concentrates where regulatory pressure intersects with material performance ceilings.
- Automotive:Fuel line systems, pneumatic tubing, and battery thermal management loops constitute the dominant volume sink. OEM engineering centers in Stuttgart, Detroit, and Shanghai are consolidating qualified suppliers into single-source arrangements per platform, compressing traditional dual-source redundancy models. Lightweighting mandates accelerate resin substitution timelines beyond historical qualification cycles.
- Aerospace:FAA and EASA flame-retardancy mandates for commercial aircraft interiors favor halogen-free cable jacketing with low smoke density. Long-chain polyamides displace PVC and fluoropolymer incumbents in wire harness applications where 25-year service life is non-negotiable. Offshore wind turbine installations in the North Sea extend this specification logic to subsea cable sheathing.
- Electronics:Connector housings and cable insulation demand dimensional stability across humidity cycling.
- Textiles:Industrial fiber applications include high-tenacity cordage and filtration media.
Automotive anchors current volume; aerospace is gaining share fastest on regulatory-driven specification shifts.
End User:
Customer procurement sophistication varies sharply across sector maturity curves.
- Industrial Equipment:Pneumatic tubing, hydraulic hose, and process fluid handling systems specify long-chain grades for hydrolytic stability. Machine builders in Bavaria and Michigan maintain dedicated polymer engineering teams capable of in-house rheology optimization. These buyers negotiate technical service bundling into resin supply agreements.
- Healthcare:Medical catheter braiding demands fiber-grade PA 12 and PA 11 with lot-to-lot molecular weight consistency. Minimally invasive device supply chains impose pharmaceutical-grade documentation burdens that command substantial price premiums over industrial specifications. FDA and EMA device regulations extend qualification timelines to 24-36 months.
- Consumer Goods:Sporting equipment and appliance components prioritize cost-positioning over performance margins.
- Construction:Geotextiles and membrane applications remain nascent for long-chain formulations.
Industrial Equipment commands the deepest supplier relationships; Healthcare is climbing the fastest on outcome-based procurement models.
Form:
Processing infrastructure lock-in determines form factor selection across regional manufacturing bases.
- Granules:Standard extrusion and injection molding feedstock dominates volume throughput. European compounding houses in Belgium and Germany maintain granule production lines optimized for PA 12 with established logistics networks into automotive Tier 1 suppliers. The form factor supports reactive extrusion compounding where functional additives integrate directly during processing.
- Fibers:Melt-spun continuous filament commands premium positioning in medical and aerospace applications where lot-to-lot consistency dictates supplier selection. Fiber-grade production requires specialized spinneret configurations and quench air systems concentrated among Japanese and German specialty polymer houses. Medical catheter braiding represents the highest-value application cluster.
- Powders:Rotational molding and coating applications favor fine particle size distributions.
- Films:Extruded sheet and blown film serve packaging and membrane applications with emerging interest in battery separator substrates.
Granules absorb the bulk of installed capacity; Fibers is expanding most quickly on medical and aerospace specification premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European compounders dominate long-chain polyamide production capacity, while Asian automotive manufacturing clusters absorb the majority of finished resin volume. This geographic disconnect shapes logistics networks and technical service deployment strategies across the value chain.
Germany
Bavarian engineering centers in Munich and Ingolstadt drive fuel line system qualification for lightweighting programs. KBA enforcement of EU emission standards accelerates PA 12 adoption in multi-layer tubing architectures. Stuttgart-based Tier 1 suppliers consolidate resin sourcing into single-source arrangements per EV platform.
China
Shanghai and Yangtze River Delta automotive clusters specify hydrolysis-resistant grades for battery thermal management loops. SAMR alignment of GB standards with ISO 7628 protocols creates regulatory pull for qualified long-chain formulations. Domestic compounders in Jiangsu province expand reactive extrusion capacity for direct resin-to-tube supply relationships.
United States
Michigan automotive engineering centers in Detroit and Ann Arbor compress material approval cycles for fuel system platforms. EPA Tier 3 permeation mandates push PA 12 into multi-layer architectures meeting sub-15 mg/m²/day thresholds. Southeast compounding facilities serve transplant OEM operations with localized granule supply.
India
Gujarat and Maharashtra industrial corridors absorb PA 610 for cost-sensitive pneumatic tubing applications. Monsoon-dependent castor harvests in the Deccan Plateau constrain sebacic acid feedstock planning for bio-based grades. Domestic hose manufacturers qualify partially bio-derived formulations for agricultural equipment export markets.
Japan
Nagoya-area automotive suppliers specify fiber-grade PA 12 for precision pneumatic components. METI industrial standards guide material selection in robotics and factory automation systems. Osaka-based specialty polymer houses maintain spinneret configurations for medical-grade filament production.
Long-Chain Polyamide Market Competitive Environment
Capital-heavy producers compete with asset-light designers across distinct value capture models. European and Asian compounders with captive lactam hydrogenation capacity anchor supply security for PA 12, while specialty resin houses concentrate on medical and aerospace qualification services. Three archetypes dominate: integrated petrochemical majors with backward control over C12 intermediates, bio-based specialists leveraging castor-oil chemistry, and regional compounders serving automotive Tier 1 clusters through technical service bundling. Capacity expansion and M&A consolidation represent the dominant competitive moves, as procurement teams negotiate five-year volume commitments with locked pricing.
Among German chemical conglomerates, BASF SE anchors the integrated producer archetype through its Ultramid portfolio and captive hydrogenation infrastructure. French specialty material houses exemplify the bio-based vector, with Arkema occupying a position tied to castor-oil derived chemistry. Japanese diversified chemical groups including Asahi Kasei Corporation and Toray Industries, Inc. represent the Asia-Pacific technical qualification tier, emphasizing fiber-grade consistency for medical and aerospace specification premiums.
| Leading Market Players |
|---|
| BASF SE |
| Arkema |
| Celanese Corporation |
| Evonik Industries AG |
| Asahi Kasei Corporation |
| Toray Industries, Inc. |
| Ascend Performance Materials |
| DuPont de Nemours, Inc. |
| EMS-Chemie Holding AG |
| Others |
Value Chain & Pricing Dynamics
Automotive OEM procurement consolidation into single-source arrangements per EV platform forces compounders to absorb technical service costs upfront, compressing spot-market flexibility and anchoring long-term contract premiums to qualification timelines rather than feedstock indices.
Pricing Analysis
Margin tightening in fiber-grade PA 12 traces to pharmaceutical-grade documentation burdens and lot-to-lot molecular weight consistency requirements that command substantial premiums over industrial granules. Three-tier pricing structure across medical certification, automotive specification, and industrial commodity levels separates buyers by documentation intensity and volume scale. Cost-down pressure on standard granules accelerates because reactive extrusion compounding eliminates masterbatch handling steps and compresses supplier tiers. Healthcare device manufacturers exhibit lowest price sensitivity due to FDA and EMA qualification timelines, while agricultural hose producers in India demonstrate highest sensitivity to sebacic acid feedstock volatility.
Supply Chain Analysis
Sebacic acid feedstock rests on Indian and Brazilian castor bean cultivation, exposing PA 11 and PA 1010 producers to monsoon-dependent harvest cycles that propagate through global bio-based polyamide pricing. European compounders in Belgium and Germany anchor PA 12 supply through captive lactam hydrogenation capacity, while Japanese specialty polymer houses concentrate fiber-grade spinneret configurations. Single-source vulnerability concentrates in C12 intermediate production, where cyclododecatriene hydrogenation capacity clusters in European petrochemical corridors. Distribution runs through automotive Tier 1 engineering centers in Stuttgart, Detroit, and Shanghai that negotiate five-year volume commitments with locked pricing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Captive hydrogenation capacity for cyclododecatriene intermediates props pricing power for integrated producers, while bio-based feedstock concentration in Indian monsoon zones constrains supply elasticity for specialty grades.
For Market Incumbents: Acquire reactive extrusion compounding lines in Jiangsu province to compress three-tier supplier structures into direct resin-to-tube relationships. Secure backward integration into castor oil processing through offtake agreements with Gujarat-based sebacic acid producers to buffer monsoon volatility. Defend against emerging regional compounders by embedding thermal modeling and mold flow simulation into standard supply agreements, locking OEM relationships through technical service bundling. For New Entrants and Emerging Players: Begin with medical catheter braiding fiber production, where lot-to-lot molecular weight consistency commands substantial premiums and incumbent qualification timelines create white-space for specialized entrants. Target aerospace cable jacketing applications ahead of FAA-EASA harmonized flame-retardancy deadlines, leveraging halogen-free positioning against PVC incumbents. Pursue qualification partnerships with Osaka-based specialty polymer houses to access spinneret configurations without captive infrastructure investment. For Investors and Strategic Acquirers: The window for entry favors bio-based specialists with castor-oil chemistry platforms and regional compounders serving automotive Tier 1 clusters through technical service bundling. Long-term viability hinges on regulatory alignment with REACH authorization timelines and SAMR enforcement of GB standards for automotive fluid handling. Watch ECHA F-Gas Regulation amendment implementation as inflection indicator for nitrogen-gas foamed grade substitution rates.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Captive lactam hydrogenation in European corridors secures PA 12 supply amid automotive lightweighting mandates. |
| Backward Integration | Castor oil processing offtakes in Gujarat buffer monsoon volatility for bio-based PA 11 and PA 610 grades. |
| Long-term Supply Agreement | Five-year volume commitments with locked pricing embed incumbents in EV thermal management tubing specifications. |
| Joint Venture | Reactive extrusion partnerships in Jiangsu province compress traditional three-tier supplier structures. |
| Green Manufacturing Transition | Nitrogen-gas foamed grades displace hydrofluorocarbon-blown alternatives ahead of ECHA F-Gas phase-down deadlines. |
Study Parameters
Multi-period observation of automotive fuel line qualification timelines and castor harvest volatility anchored the trend analysis, supplemented by interviews with plant managers at European compounding houses, procurement leads at Stuttgart-based Tier 1 suppliers, technical R&D directors at specialty polymer houses, and distribution channel partners serving Bavarian engineering centers. Secondary validation drew from customs and trade data tracking sebacic acid flows, Cefic polymer production reports, SEC filings of listed chemical conglomerates, and ISO 7628 test protocol documentation. Bottom-up volume modeling across granule, fiber, powder, and film form factors triangulated against top-down demand aggregation by automotive, aerospace, and medical end-use segments.
Input-output matrices mapped PA 12 hydrogenation capacity utilization, PA 11 castor oil feedstock conversion rates, and reactive extrusion adoption curves across the projection horizon. Segmentation dimensions included monomer chemistry, application sector, end-user procurement sophistication, and regional production hub. CAGRs derived from regression analysis of historical qualification cycle compression and regulatory mandate implementation schedules. Industry-specific forecast inputs incorporated EPA Tier 3 permeation threshold enforcement and SAMR alignment of GB standards with ISO protocols.
Underlying measurement precision varies by segment; medical fiber-grade specifications carry tighter precision than industrial granule volumes due to pharmaceutical-grade documentation requirements. Forecasts reflect assumptions regarding regulatory implementation timelines, feedstock harvest stability, and OEM platform standardization decisions. Castor oil supply disruption, REACH authorization delays for new formulations, and automotive platform consolidation beyond single-source thresholds warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
Soy Polysaccharides Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Co-Polymer Resin Market
Polymers & Resins
Global Thermosetting Polymer Market
Polymers & Resins
Medical Polyoxymethylene (POM) Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
Thermoplastics Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
North America and Europe Phenolic Resin Market
Polymers & Resins
Global Sulfone Polymers Market
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Polyamide-Imide (PAI) Market