
 Metallocene Polyethylene Market | 2026-2036
Metallocene Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Metallocene Polyethylene Market Analysis
Aftermarket technical service revenue is tilting toward resin specification consulting as converters face tighter performance targets. ExxonMobil Corporation leverages its catalyst technology platform to anchor premium film-grade supply relationships across North America. Borealis AG sustains European market presence through backward integration into polymerization catalyst development. SABIC competes on manufacturing scale with integrated feedstock access at its Middle Eastern production complexes.
Metallocene polyethylene denotes a thermoplastic polymer synthesized using metallocene catalysts that enable precise control of molecular weight distribution and comonomer incorporation, yielding density ranges from 0.86 to 0.97 g/cm³ with superior puncture resistance and seal initiation temperatures. Films command the dominant product position due to their penetration in food protection and agricultural mulching, while injection molding grades capture expanding automotive under-hood applications. Flexible packaging leads application demand as brand owners substitute multi-layer structures with monomaterial solutions compatible with mechanical recycling streams.
REACH registration requirements in Europe and FDA food-contact notification protocols in the United States shape material migration limits and catalyst residue thresholds for consumer-facing applications. China's GB standards and NMPA medical device material regulations create parallel compliance pathways for healthcare-grade extrusions. Stakeholders must monitor catalyst licensing costs and recycled-content mandates as these forces redefine cost structures and product qualification timelines.
Market Dynamics
Converters in China are accelerating metallocene-capable film production capacity, concentrating demand pull toward Asia-Pacific supply nodes while European REACH compliance costs reshape competitive positioning among Western producers.
Growth Catalysts
- Monomaterial packaging mandates:Brand owners across food and beverage sectors are substituting multi-layer structures with single-polymer solutions compatible with mechanical recycling streams. This specification shift elevates metallocene grades for sealability and puncture resistance.
- REACH registration thresholds:ECHA requirements for catalyst residue documentation and migration testing are filtering out commodity polyethylene suppliers unable to certify material purity, consolidating qualified supply relationships.
- Agricultural film specification tightening:Extended UV stability and tear resistance requirements in greenhouse and mulching applications are displacing conventional LLDPE with metallocene-enhanced alternatives.
Market Restraints
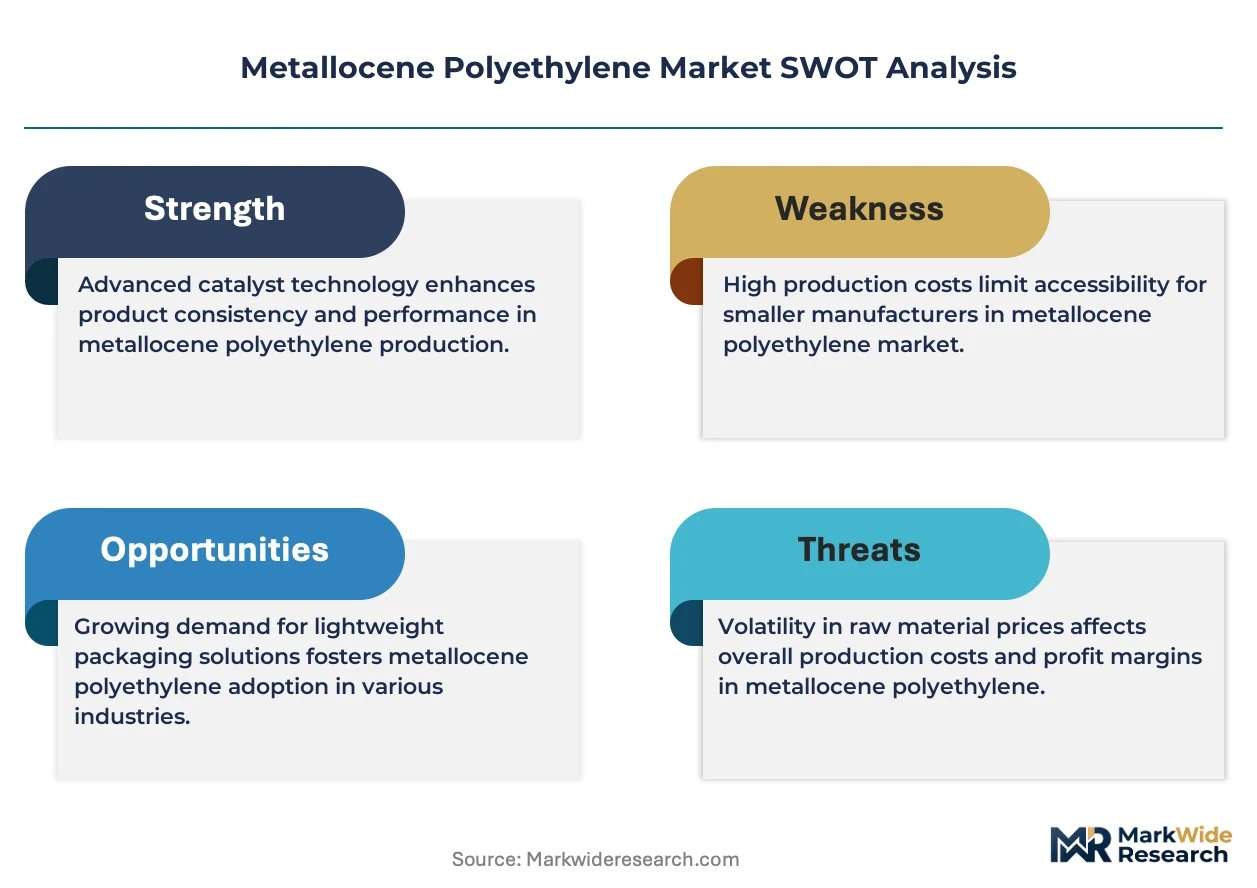
- Catalyst licensing cost structure:Proprietary metallocene catalyst systems carry royalty burdens that compress margins for non-integrated producers lacking captive technology development.
- Feedstock concentration in the Middle East:Ethane-based cost advantages at integrated Gulf Coast complexes limit price competitiveness for naphtha-dependent European and Asian producers.
- Technical limitation in blow molding:Metallocene grades exhibit melt strength deficiencies versus conventional HDPE in large-part hollow container applications, constraining penetration in industrial packaging.
Strategic Opportunities
- India's packaging converter expansion:Domestic film production capacity additions under PLI scheme incentives create qualified demand for imported metallocene resin specifications.
- Healthcare extrusion certification:NMPA medical device material regulations in China establish parallel compliance pathways for sterilizable healthcare-grade tubing and pharmaceutical packaging.
- Digital specification platforms:Resin selection tools integrating rheological data and regulatory documentation are compressing converter qualification timelines and reducing technical service overhead.
Industry Challenges
- Metallocene catalyst synthesis expertise:Limited pool of chemists capable of ligand design and polymerization scale-up creates recruitment bottlenecks for technology licensors and integrated producers.
- Multi-jurisdiction notification timelines:Parallel FDA food-contact, REACH registration, and GB standards compliance processes extend product launch cycles by 18-24 months for new grade introductions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metallocene Polyethylene Market |
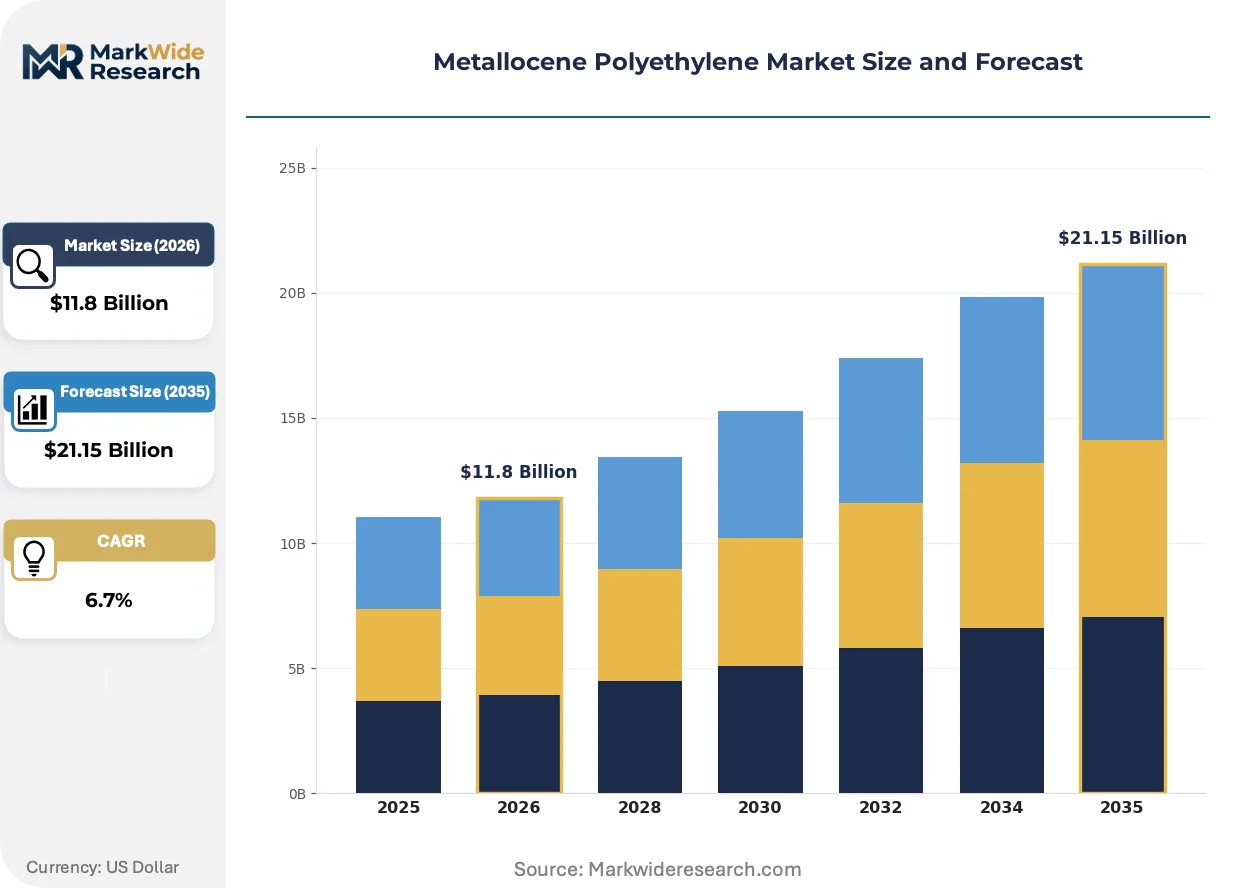
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $21.15 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Sheets, Extrusions, Injection Molding End User: Packaging, Automotive, Healthcare, Construction Application: Flexible Packaging, Rigid Containers, Coatings, Adhesives Distribution Channel: Direct Sales, E-commerce, Distributors, Retail |
| Companies Covered | ExxonMobil Corporation, Borealis AG, SABIC, INEOS Group Holdings S.A., TotalEnergies SE, Chevron Phillips Chemical Company LLC, LyondellBasell Industries N.V., Braskem, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metallocene Polyethylene Market Emerging Trajectories
Polymer architecture control is advancing beyond conventional single-site catalysts toward hybrid systems that enable real-time molecular weight distribution adjustment during continuous production.
Hybrid metallocene-zirconocene catalyst systems are rendering obsolete fixed-reactor configurations that required grade-change shutdowns. Major film converters in Germany and the United States are piloting these systems to compress order-to-delivery cycles for custom seal-initiation specifications. The technology is collapsing minimum efficient scale thresholds for specialty grade production.
REACH authorization requirements for persistent organic pollutants are tightening catalyst residue thresholds in food-contact applications. ECHA's 2024 updates to Annex XVII restrictions are forcing reformulation of certain co-catalyst systems. European flexible packaging producers are accelerating qualification of alternative activator chemistries to maintain compliance.
Specification-driven procurement is consolidating converter relationships around resin suppliers with embedded technical service capabilities. Food brand technical teams in Japan and South Korea now require rheological fingerprinting data and migration study documentation prior to supplier approval. This documentation burden is favoring integrated producers with in-house analytical laboratories over trading intermediaries.
Metallocene Polyethylene Market Segmentation
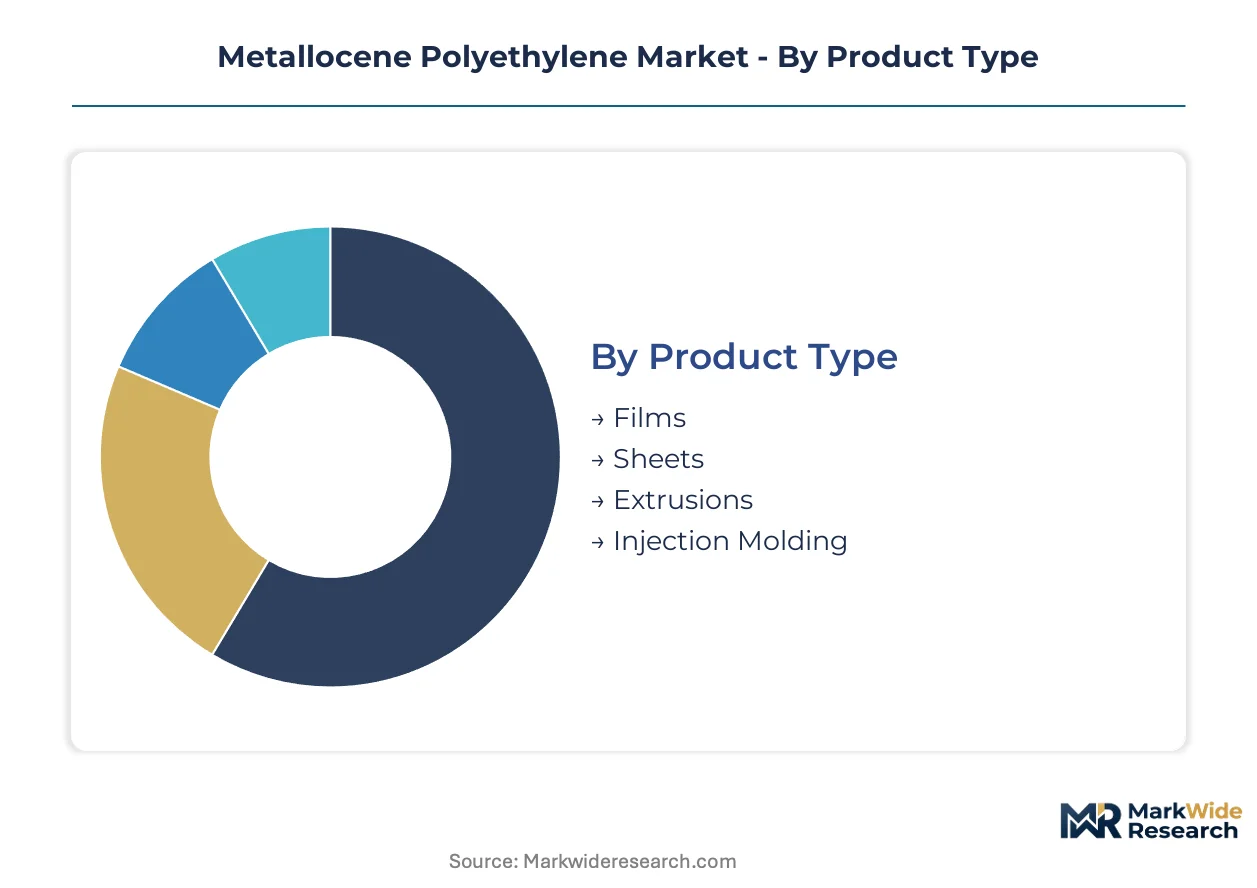
Metallocene polyethylene specifications diverge sharply by processing method and end-use performance requirements. Converter equipment capabilities and regulatory compliance thresholds reshape procurement patterns across each segment boundary.
Product Type:
Mature extrusion and film technologies anchor current volume, while emerging injection molding grades capture specification-driven substitution in precision applications.
- Films:These grades deliver puncture resistance and low seal initiation temperatures through precise molecular weight distribution control. Food brand technical teams in Japan and Germany now require rheological fingerprinting data and migration study documentation prior to supplier approval, filtering supply relationships toward integrated producers with in-house analytical laboratories.
- Injection Molding:Automotive under-hood applications demand thermal stability and dimensional precision that conventional polyethylene cannot match. Tier-1 suppliers in Michigan and Stuttgart are qualifying these grades for charge air coolers and fluid reservoirs as OEMs tighten material traceability requirements.
- Sheets:Thermoforming feedstock for medical tray and industrial packaging applications.
- Extrusions:Profile and tubing specifications for healthcare and agricultural conduit systems.
Films retain volume leadership; injection molding holds the steepest expansion curve.
End User:
Cost tier stratification separates commodity converters from premium specification buyers across medical, automotive, and food protection applications.
- Packaging:Brand owners across food and beverage sectors substitute multi-layer structures with single-polymer solutions compatible with mechanical recycling streams. FDA food-contact notification protocols and REACH registration requirements elevate metallocene grades for sealability and catalyst residue compliance.
- Healthcare:Sterilizable tubing and pharmaceutical packaging demand NMPA medical device material regulations in China and parallel FDA pathways. Domestic converters in Shanghai and Shenzhen are expanding extrusion capacity to capture import substitution opportunities.
- Automotive:Under-hood component specifications from Detroit and Wolfsburg OEMs.
- Construction:Geomembrane and pipe applications with extended UV stability requirements.
Packaging commands the broadest converter base; healthcare posts the most rapid qualification timeline compression.
Application:
Customer type fragmentation separates brand-direct specifications from distributor-mediated procurement across flexible and rigid formats.
- Flexible Packaging:Monomaterial mandates from European retailers and California brand owners displace multi-layer barrier structures. ECHA's REACH authorization updates for persistent organic pollutants tighten catalyst residue thresholds, forcing reformulation of certain co-catalyst systems.
- Rigid Containers:Blow molding limitations constrain large-part hollow container penetration due to melt strength deficiencies versus conventional HDPE. Industrial packaging producers in Ohio and Bavaria pilot hybrid metallocene-zirconocene systems to compress order-to-delivery cycles.
- Coatings:Substrate adhesion layers for multi-material laminations.
- Adhesives:Hot-melt formulations with controlled rheological profiles.
Flexible packaging dominates specification activity; rigid containers face technical barriers in scale-up applications.
Distribution Channel:
Supply concentration patterns favor direct relationships for qualified grades while distributors handle commoditized volume.
- Direct Sales:Resin specification consulting now anchors aftermarket technical service revenue as converters face tighter performance targets. ExxonMobil and Borealis AG leverage embedded technical teams to secure multi-year supply agreements with film converters in Germany and the United States.
- Distributors:Inventory pooling for standard film grades serves mid-tier converters lacking volume scale for mill-direct procurement.
- E-commerce:Digital specification platforms integrating rheological data and regulatory documentation compress converter qualification timelines.
- Retail:Small-lot availability for R&D sampling and grade trials.
Direct sales capture premium grade relationships; e-commerce platforms gain traction in technical documentation delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Metallocene polyethylene consumption patterns diverge sharply by geography. China deploys the material predominantly in food-grade flexible film for domestic brand owners. Germany concentrates demand in automotive under-hood precision components. The United States splits consumption between agricultural mulch films and healthcare sterilizable packaging.
China
Domestic film converters in Shanghai and Shenzhen are expanding metallocene-capable extrusion lines to capture food packaging import substitution. NMPA medical device material regulations establish parallel compliance pathways for healthcare-grade tubing. The Yangtze River Delta cluster hosts the fastest capacity additions for monomaterial flexible packaging specifications.
Germany
Automotive tier-1 suppliers in Stuttgart and Wolfsburg are qualifying injection molding grades for charge air coolers and fluid reservoirs. ECHA REACH authorization requirements for persistent organic pollutants tighten catalyst residue thresholds in food-contact applications. Bavarian film converters pilot hybrid metallocene-zirconocene systems to compress custom seal-initiation order cycles.
United States
Brand owners in California and the Midwest substitute multi-layer barrier structures with single-polymer solutions compatible with mechanical recycling streams. FDA food-contact notification protocols elevate documentation requirements for migration studies and rheological fingerprinting. Ohio industrial packaging producers face technical limitations in blow molding large-part hollow containers due to melt strength deficiencies versus conventional HDPE.
Saudi Arabia
Integrated ethane-based production complexes at Gulf Coast scale deliver feedstock cost advantages that compress margins for naphtha-dependent European and Asian competitors. The country's national petrochemical regulator aligns catalyst residue documentation with emerging EU REACH-equivalent standards. Eastern Province production hubs supply premium film-grade specifications to converters across the Middle East and South Asia.
India
Domestic packaging converter expansion under PLI scheme incentives creates qualified demand for imported metallocene resin specifications. BIS standards for food-contact materials are tightening purity requirements in parallel with FDA and ECHA developments. Maharashtra and Gujarat film production clusters are upgrading equipment to handle higher-performance seal-layer formulations.
Metallocene Polyethylene Market Vendor Landscape
Capability concentration sits with integrated catalyst technology developers; scale advantage sits with feedstock-integrated petrochemical complexes. The market structures around three tiers: technology licensors with proprietary metallocene systems, integrated producers with captive catalyst development, and regional converters dependent on licensed technology. Dominant competitive moves include backward integration into polymerization catalyst development and multi-year supply agreements embedding technical service capabilities.
Within the integrated technology tier, ExxonMobil Corporation anchors premium film-grade supply relationships through embedded technical teams in North America. Borealis AG occupies a position as a European representative of backward-integrated catalyst development capability. SABIC exemplifies the scale-driven archetype with integrated feedstock access at Middle Eastern production complexes. These three patterns illustrate how competitive positioning separates technology differentiation from manufacturing scale.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| Borealis AG |
| SABIC |
| INEOS Group Holdings S.A. |
| TotalEnergies SE |
| Chevron Phillips Chemical Company LLC |
| LyondellBasell Industries N.V. |
| Braskem |
| Dow |
| Others |
Supply Flow & Price Mechanics
The Yangtze River Delta cluster anchors Asia-Pacific capacity additions for metallocene-capable film production, concentrating supply-side leverage among integrated producers with captive catalyst technology. This geographic concentration amplifies pricing power for premium film-grade specifications while naphtha-dependent European converters face margin compression from ethane-based Gulf Coast competition.
Pricing Analysis
Long-term offtake agreements dominate procurement relationships between major film converters and integrated resin suppliers, embedding technical service capabilities into multi-year contracts. Three-tier pricing structure across premium, standard, and economy levels separates catalyst residue-compliant food-contact grades from industrial packaging specifications. Pricing pressure stems from royalty burdens on proprietary metallocene systems that compress margins for non-integrated producers. Mid-tier converters lacking volume scale for mill-direct procurement exhibit highest price sensitivity, while automotive tier-1 suppliers prioritize performance consistency over unit cost.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities are becoming standard practice as resin suppliers compete for qualified converter relationships in China and India. Manufacturing concentration rests on Saudi Arabia, China, and the United States as primary production hubs. Feedstock dependencies center on ethane availability at Gulf Coast complexes and naphtha supply to European crackers. Single-source vulnerability from proprietary catalyst licensing creates structural risk for converters dependent on specific technology platforms. Distribution runs through direct sales relationships for premium grades and regional distributors for commoditized volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward food brand technical teams and automotive OEMs as specification requirements tighten across multiple jurisdictions. Converter consolidation in China and India is concentrating procurement leverage among fewer qualified buyers with embedded technical capabilities.
For Market Incumbents: Build regulatory documentation moats by investing in in-house analytical laboratories capable of rheological fingerprinting and migration study generation. Secure multi-year supply agreements with film converters in Germany and Japan before REACH authorization updates filter out commodity competitors. Capacity additions in the Yangtze River Delta defend position against domestic Chinese producers expanding metallocene-capable extrusion lines. For New Entrants and Emerging Players: Healthcare extrusion certification under China's NMPA medical device material regulations represents the most penetrable entry point for specialized grades with sterilization stability requirements. India's PLI scheme incentives for domestic packaging converter expansion create qualified demand for imported resin specifications with technical service bundling. Partner with digital specification platforms integrating regulatory documentation to compress qualification timelines versus traditional channel development. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated producers with captive catalyst development capabilities and embedded technical service teams. Long-term viability over the next decade hinges on backward integration into polymerization catalyst synthesis rather than commodity resin manufacturing scale. Target acquisition archetypes include mid-sized European producers with REACH-compliant grade portfolios and established automotive supply relationships. Monitor catalyst licensing cost structures as the inflection signal for margin compression among non-integrated competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Development | Captive ligand design capabilities eliminate royalty burdens and accelerate custom grade development for food-contact specifications. |
| Long-term Supply Agreement with Technical Service Embedding | Multi-year contracts with German and Japanese film converters lock in premium pricing through rheological fingerprinting documentation. |
| Capacity Expansion in Yangtze River Delta | Proximity to China's fastest-growing monomaterial flexible packaging demand reduces logistics costs and import substitution risk. |
| Healthcare Grade Certification under NMPA Pathway | Sterilizable tubing qualifications open pharmaceutical packaging segments with higher margin profiles than commodity film applications. |
| Hybrid Metallocene-Zirconocene System Deployment | Real-time molecular weight distribution adjustment compresses order-to-delivery cycles for custom seal-initiation specifications. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with polymerization plant managers, procurement leads at film converters, catalyst technology licensors, and regulatory affairs specialists at resin suppliers. Secondary validation drew from customs and trade data, SEC 10-K filings of integrated petrochemical producers, ECHA REACH registration databases, and NMPA medical device material filings. Bottom-up volume estimates from converter capacity utilization were triangulated against top-down resin production data across the analysis window.
Calibration against historical price realizations and capacity utilization rates anchored the projection framework. Segmentation dimensions modeled include product type, end-use industry, application format, and regional production hub. CAGRs were derived through regression analysis of demand drivers and supply elasticity parameters. Forecast inputs incorporated catalyst licensing cost trajectories and evolving FDA food-contact notification timelines.
Macroeconomic conditions sit as an overlay; deviation in ethane-naphtha feedstock spreads or polyethylene commodity price cycles would shift the trajectory. Forecasts reflect documented assumptions about regulatory compliance timelines and converter equipment upgrade rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Vinyl Acetate Ethylene Copolymer Powder Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Amorphous Polyolefin Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Global Polyphthalamide Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Novolac Resins Market
Polymers & Resins
High-Solids Acrylic Polyol Resins for Low-VOC Industrial Coatings Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Terpene Resins Market
Polymers & Resins
Fluorinated Polyimide Market
Polymers & Resins
Polystyrene and Expandable Polystyrene (EPS) Market