
 South America Fluoropolymer Market | 2026-2036
South America Fluoropolymer Market Size, Share, and Industry Trends Forecast 2026-2036
South America Fluoropolymer Market Insights
Brazilian resin compounders is realigning regional supply chains toward captive PTFE and FEP pellet production. Arkema leverages its specialty fluoropolymer expertise to serve chemical processing clients across the Mercosur trade zone. The Chemours Company anchors its regional position through sustained R&D investment in high-performance grades for automotive underhood applications. Solvay competes via differentiated ETFE architectural film formulations targeting Chilean and Colombian infrastructure projects.
Fluoropolymers constitute a family of synthetic polymers built on carbon-fluorine bonds, with PTFE exhibiting a melting point near 327°C and dielectric constants below 2.1, rendering them indispensable for corrosion-resistant linings, electrical insulation, and extreme-temperature seals. PTFE dominates volume consumption across South American chemical processing and electrical end users due to its established supply base and cost-positioning against exotic alternatives. Specialty and modified grades capture disproportionate margin pools as Brazilian semiconductor fabricators and Argentine lithium-battery developers specify tighter purity thresholds.
Brazil's national chemical regulator ANVISA and environmental agency IBAMA shape import approval pathways and waste-handling protocols for fluoropolymer processors, while Argentina's Secretariat of Industry enforces local content thresholds on public infrastructure materials. The EU F-Gas Regulation exerts extraterritorial pull on South American exporters serving European automotive and appliance OEMs, compelling upstream investment in low-global-warming-potential chemistries. Stakeholders must track regulatory divergence between Mercosur harmonization efforts and Chile's independent chemical registry system when allocating technical service resources.
Market Dynamics
REACH-equivalent chemical safety frameworks in Brazil and tightening automotive emission standards across the Mercosur zone are forcing resin compounders to requalify entire product portfolios, compressing approval timelines and elevating technical service costs for fluoropolymer suppliers serving chemical processing and semiconductor manufacturing clusters.
Growth Catalysts
- ANVISA chemical safety alignment:Brazil's national health regulator is accelerating import approval pathways for fluoropolymer-lined equipment, reducing qualification delays for petrochemical processors in Sao Paulo state's industrial corridor.
- Semiconductor purity thresholds:Brazilian fabricators are specifying tighter contamination limits for PTFE and modified grades, pulling specialty resin volumes into domestic cleanroom construction and wafer handling systems.
- Automotive underhood specifications:Evolving emission standards across Argentina and Brazil are mandating fluoropolymer seals and fuel system components capable of sustained operation above 250°C.
Market Restraints
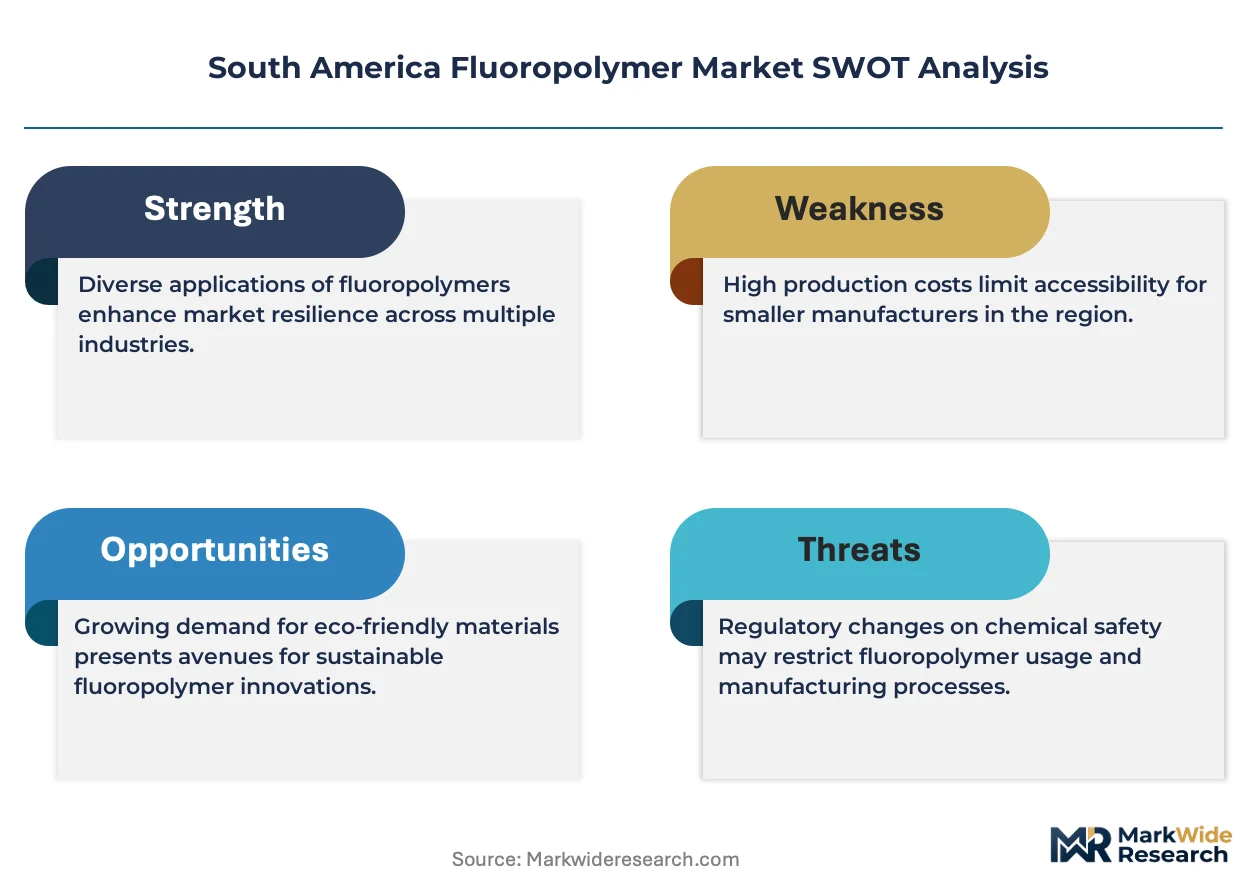
- Fluorospar supply concentration:Acid-grade fluorspar feedstock dependence on Chinese and Mexican mining operations exposes South American compounders to volatile input costs and currency mismatch risks.
- IBAMA waste-handling protocols:Brazil's environmental agency imposes extended producer responsibility frameworks on fluoropolymer processors, elevating end-of-life compliance expenditures relative to regional competitors.
- Perfluoroalkyl substance scrutiny:Emerging restrictions on long-chain chemistries are constraining legacy PTFE formulation options for food-contact and potable water applications across the region.
Strategic Opportunities
- Argentine lithium-battery development:Cathode binder and separator membrane specifications for emerging battery cell production in Catamarca and Jujuy provinces are creating pull for high-purity PVDF grades.
- Chilean infrastructure ETFE demand:Architectural film specifications for Santiago transit hubs and mining camp enclosures are opening differentiated formulation opportunities distinct from commodity PTFE competition.
- Mercosur harmonization tailwinds:Converging chemical registry standards across member states are reducing multi-country registration burdens for suppliers with Brazilian technical service capabilities.
Industry Challenges
- Fluoropolymer compounding technician scarcity:Specialized extrusion and sintering expertise required for high-performance grades remains concentrated in Sao Paulo and Porto Alegre, constraining geographic expansion of technical service teams.
- Legacy equipment requalification timelines:Chemical processors in Argentina's petrochemical belt face extended validation periods when retrofitting fluoropolymer-lined vessels to meet revised ANVISA purity standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Fluoropolymer Market |
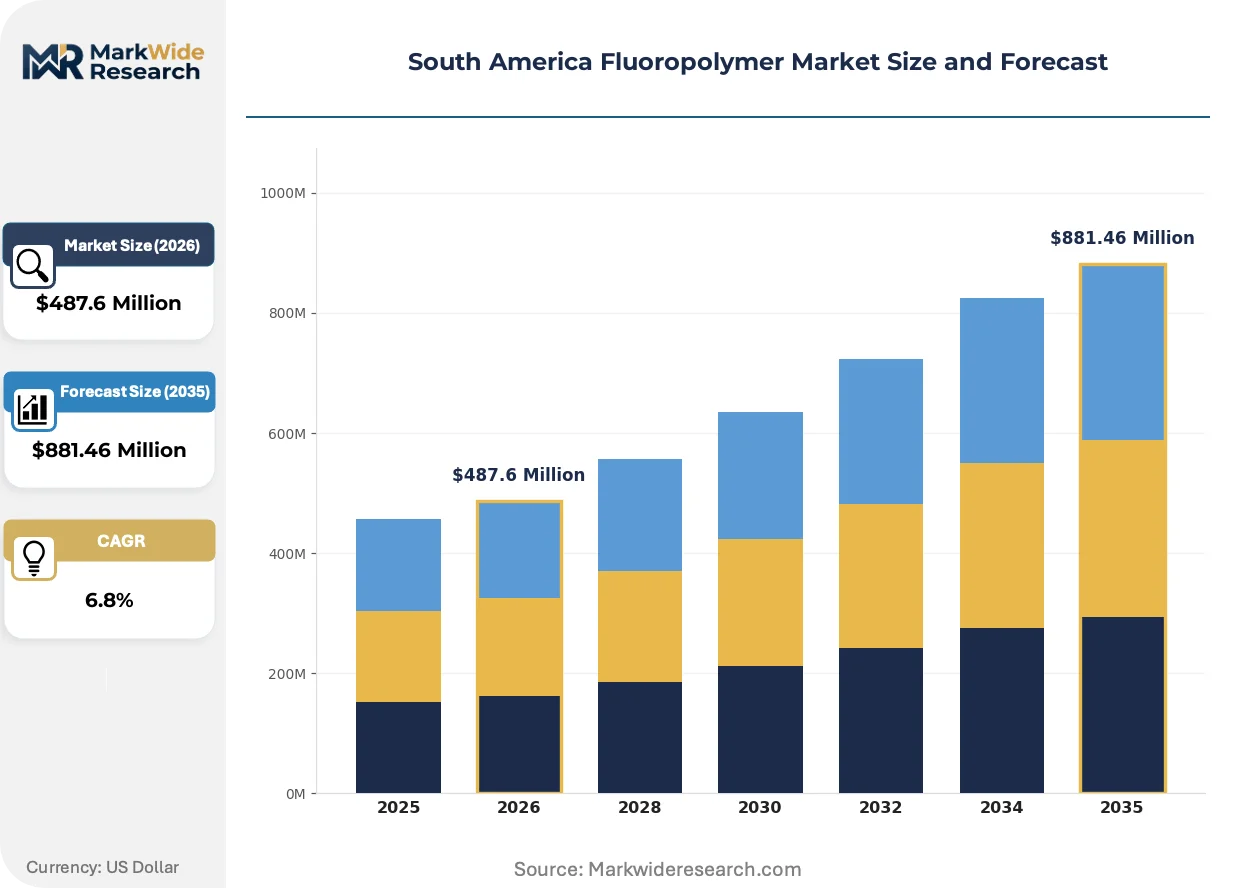
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, ETFE End User: Electrical, Chemical Processing, Automotive, Industrial Grade: High Performance, Standard, Specialty, Modified Application: Coatings, Seals, Insulation, Gaskets |
| Companies Covered | Arkema, 3M, The Chemours Company, Solvay, AGC Inc., Daikin Industries, Dongyue Group, Gujarat Fluorochemicals Limited, INOFLON, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Fluoropolymer Market Trends and Innovations
Modified fluoropolymer grades and advanced compounding techniques are compressing the performance gap between commodity PTFE and exotic high-performance polymers, while regulatory pressure on perfluorinated substances is accelerating chemistry diversification among South American resin suppliers.
Perfluoroalkoxy alkane (PFA) melt-processable variants are rewriting competitive positioning in chemical processing applications. Brazilian petrochemical operators in Camacari and Triunfo complexes are specifying PFA-lined pumps and valves for sulfuric acid handling above 200°C. This material substitution is compressing demand for traditional PTFE machining and enabling thinner-wall lining designs that reduce equipment weight and thermal mass.
Brazil's ANVISA is implementing REACH-aligned substance registration requirements for imported fluoropolymer resins and compounded products. Industrial consequence includes mandatory safety data sheet harmonization and extended toxicological dossier preparation for new chemistry introductions. Argentine and Chilean chemical processors serving export markets are most affected, compelling upstream suppliers to maintain parallel documentation systems for Mercosur and EU-bound product streams.
Specification-driven procurement is consolidating fluoropolymer purchasing authority within Brazilian semiconductor and chemical processing majors. Centralized technical teams in Sao Paulo and Curitiba are displacing distributed plant-level buying for critical linings and seals. This concentration is most visible in the petrochemical vertical, where integrated operators are qualifying single-source resin suppliers across multiple production sites to secure volume pricing and technical service priority.
South America Fluoropolymer Market Segmentation
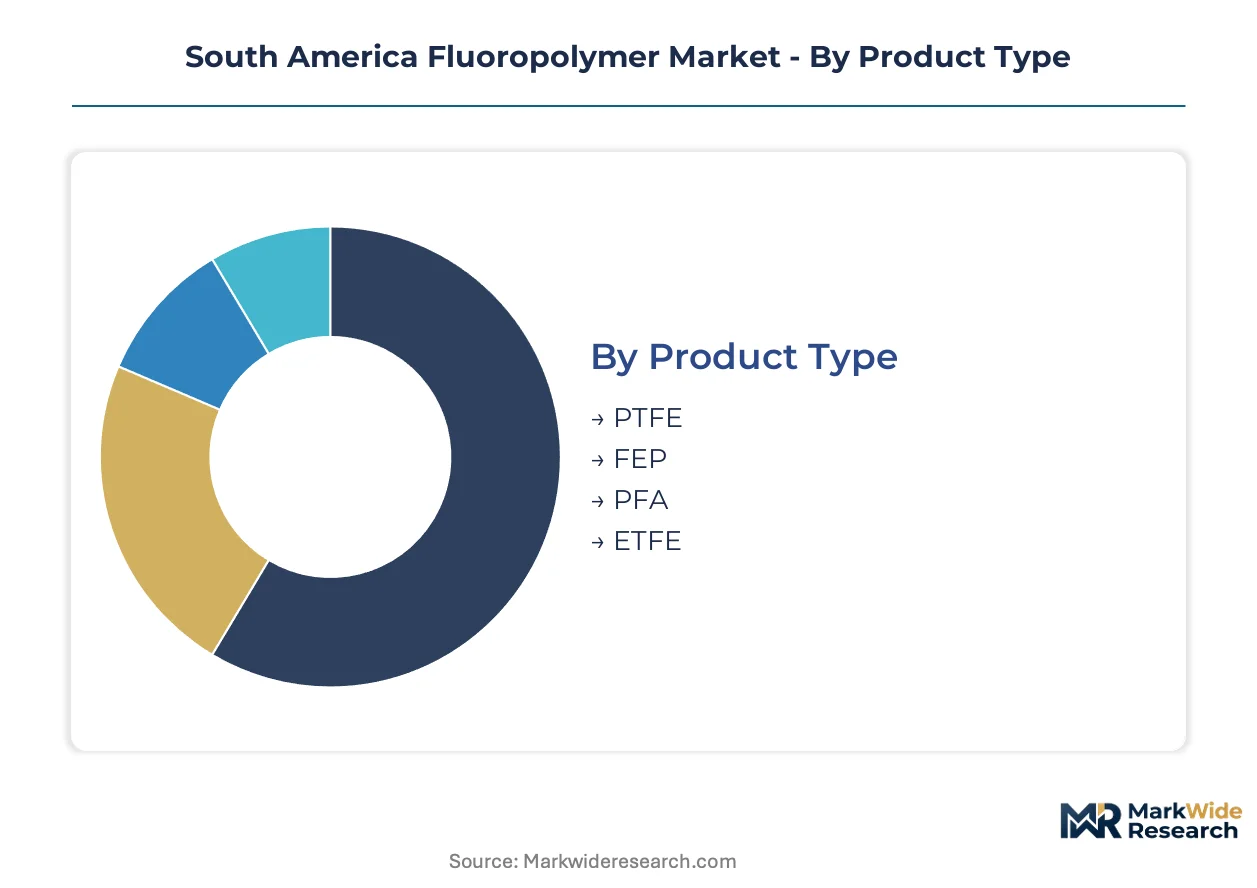
Fluoropolymer procurement in South America fragments across technical specifications, regulatory thresholds, and end-use performance requirements. Segmentation discipline separates commodity volume plays from specialty margin pools, with ANVISA registration pathways and semiconductor purity standards acting as the primary sorting mechanisms for supplier qualification.
Product Type:
Certification burden varies sharply across polymer chemistries, with modified grades requiring extended toxicological dossiers under Brazil's REACH-aligned framework while commodity PTFE maintains grandfathered approval status.
- PTFE:Polytetrafluoroethylene dominates volume consumption through established supply chains serving Sao Paulo state's petrochemical corridors. Brazilian chemical processors specify PTFE-lined vessels for sulfuric acid handling below 200°C, though PFA substitution is compressing growth in high-temperature pump applications.
- FEP:Fluorinated ethylene propylene offers melt-processability that PTFE lacks, enabling extruded wire insulation for automotive harnesses across Mercosur assembly plants. Argentine and Brazilian OEMs specify FEP for emission-control sensor cabling operating above 150°C.
- PFA:Perfluoroalkoxy alkane variants command premium positioning in semiconductor cleanroom construction, with Brazilian fabricators in Campinas mandating PFA for ultra-high-purity fluid handling systems.
- ETFE:Ethylene tetrafluoroethylene architectural films target Chilean infrastructure projects, with Santiago transit hub specifications driving differentiated formulation demand distinct from industrial polymer competition.
PTFE sits at the top of the volume ranking, with PFA climbing the fastest as semiconductor purity thresholds tighten across Brazilian fabrication facilities.
End User:
Customer concentration patterns separate price-sensitive bulk purchasers from specification-driven technical buyers, with procurement authority centralizing within integrated operators.
- Electrical:Wire and cable insulation demand concentrates in Brazilian automotive harness production and power distribution infrastructure. FEP and ETFE capture share in high-frequency data transmission applications requiring dielectric constants below 2.5.
- Chemical Processing:Petrochemical operators in Camacari and Triunfo complexes drive fluoropolymer-lined equipment procurement, with ANVISA import approvals accelerating for corrosion-resistant vessel specifications.
- Automotive:Emission standard tightening across Argentina and Brazil mandates fluoropolymer seals and fuel system components for sustained operation above 250°C, pulling specialty resin volumes into underhood applications.
- Industrial:Diverse manufacturing applications span food-processing equipment, pharmaceutical containment, and textile machinery, with modified PTFE grades gaining traction in food-contact applications facing perfluoroalkyl substance scrutiny.
Chemical Processing anchors regional demand value, with Automotive expanding most quickly as Mercosur emission regulations phase in.
Grade:
Margin stratification follows purity certification intensity, with semiconductor and battery applications commanding qualification premiums over standard industrial specifications.
- High Performance:Ultra-pure formulations for semiconductor wafer handling and lithium-ion battery separators carry extended validation timelines and technical service premiums. Argentine lithium development in Catamarca province specifies high-performance PVDF cathode binders.
- Standard:Commodity PTFE and FEP pellets serve cost-sensitive chemical processing and general industrial applications, with Brazilian compounders realigning toward captive production to defend margin position.
- Specialty:Custom-formulated grades address specific corrosion resistance or electrical performance requirements, typically qualifying through single-source agreements with Sao Paulo-based technical service teams.
- Modified:Filled and reinforced variants incorporate glass fiber, carbon, or graphite to improve wear resistance and dimensional stability, compressing the performance gap against exotic polymers in seal and bearing applications.
Standard grade dominates shipment volumes, with High Performance gaining share fastest as Brazilian semiconductor fabrication scales.
Application:
Functional requirements dictate polymer selection, with thermal cycling resistance and chemical exposure severity determining formulation complexity.
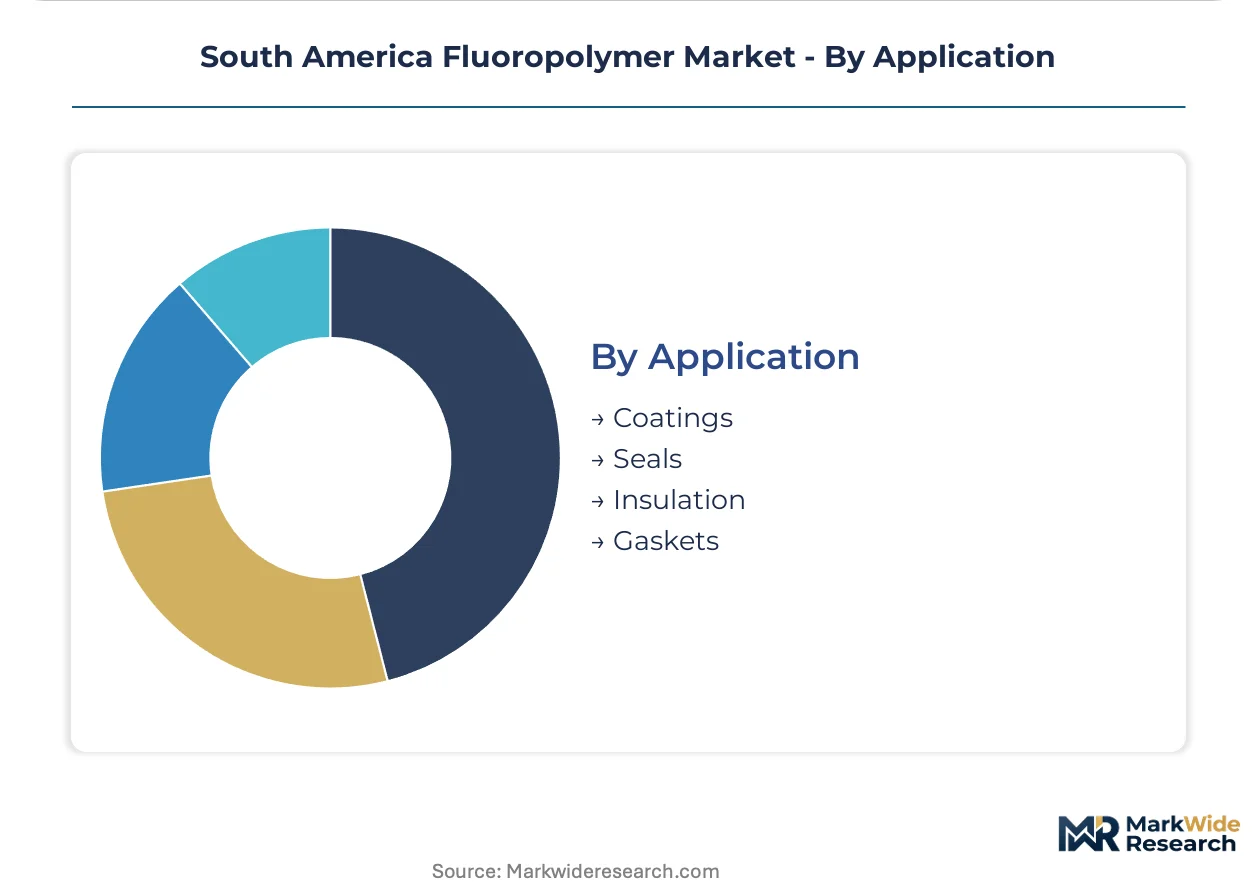
- Coatings:Spray and powder-applied fluoropolymer films protect chemical processing equipment, architectural substrates, and cookware surfaces. Brazilian appliance manufacturers specify coating grades compliant with evolving food-contact regulations.
- Seals:O-rings, shaft seals, and valve seats demand creep resistance and low friction coefficients, with automotive fuel system specifications driving fluorocarbon elastomer substitution in high-temperature zones.
- Insulation:Wire and cable jacketing applications favor FEP and ETFE for processing efficiency, while PTFE tape maintains position in high-voltage motor and transformer winding.
- Gaskets:Sheet and formed gasket products serve flange sealing in chemical processing, with expanded PTFE variants capturing share in irregular surface applications requiring conformability.
Coatings lead application volumes, with Seals showing steepest expansion trajectory as automotive thermal specifications tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands fluoropolymer consumption volumes that dwarf Argentine demand, yet Chilean infrastructure specifications are pulling architectural-grade ETFE volumes northward at faster clip than either neighbor.
Brazil
Petrochemical expansion in São Paulo state's industrial corridor and semiconductor cleanroom construction in Campinas drive specialty resin procurement. ANVISA's REACH-aligned substance registration requirements are compressing import approval timelines for fluoropolymer-lined equipment. Brazilian compounders in the Camacari and Triunfo complexes are consolidating purchasing authority within centralized technical teams.
Argentina
Lithium-battery cathode binder specifications for emerging cell production in Catamarca and Jujuy provinces are creating demand pull for high-purity PVDF grades. The Secretariat of Industry enforces local content thresholds on public infrastructure materials containing fluoropolymer components. Petrochemical processors in the Bahía Blanca industrial belt face extended requalification timelines when retrofitting lined vessels to meet revised purity standards.
Chile
Architectural film specifications for Santiago transit hubs and mining camp enclosures are opening differentiated ETFE formulation opportunities. The country's independent chemical registry system diverges from Mercosur harmonization efforts, requiring parallel documentation for suppliers. Northern mining districts are specifying fluoropolymer-lined processing equipment for acid leaching operations in copper extraction.
Colombia
Automotive wire harness production for export markets is pulling FEP insulation volumes into Bogotá-area manufacturing zones. National chemical safety frameworks are evolving toward EU-equivalent standards, elevating technical service costs for resin suppliers. The Medellín industrial cluster is consolidating procurement for chemical processing equipment linings serving regional pharmaceutical manufacturers.
Peru
Mining sector demand for corrosion-resistant pump and valve linings concentrates in the southern copper belt around Arequipa. Environmental permitting protocols for fluoropolymer waste handling are tightening faster than regional counterparts. Lima-based distributors are building technical service capabilities to support specification-driven procurement from centralized mining operator headquarters.
South America Fluoropolymer Market Competitive Landscape
European and North American producers anchor the premium-grade tier; Asian manufacturers hold cost-positioned supply for standard industrial specifications. Market structure concentrates around integrated resin compounders with captive fluorospar access and specialized formulators serving semiconductor purity thresholds. Two strategic archetypes dominate: vertically integrated chemical conglomerates with global R&D networks, and regional technical specialists with deep Mercosur regulatory expertise. Competitive moves center on backward integration into acid-grade fluorspar sourcing and geographic expansion of technical service teams into Argentine and Chilean industrial corridors.
Within the premium specialty tier, Arkema and Solvay represent European-based formulators with established Mercosur technical service infrastructure. The Chemours Company anchors North American-origin supply for high-performance automotive and semiconductor grades. These three exemplify the integrated-compound archetype, occupying positions that depend on sustained regulatory compliance investment across divergent national chemical registry systems.
| Leading Market Players |
|---|
| Arkema |
| 3M |
| The Chemours Company |
| Solvay |
| AGC Inc. |
| Daikin Industries |
| Dongyue Group |
| Gujarat Fluorochemicals Limited |
| INOFLON |
| Others |
Pricing and Supply Chain Analysis
Captive acid-grade fluorspar sourcing through Mexican and Chinese mining partnerships anchors pricing power for South American resin compounders while insulating against currency mismatch risks that plague import-dependent processors. This upstream control feeds directly into contract-based long-term offtake structures that Brazilian petrochemical operators favor for fluoropolymer-lined equipment procurement.
Pricing Analysis
Capacity additions in Brazilian captive PTFE and FEP pellet production are reshaping price floors for standard industrial grades, compressing margins on commodity formulations while premium-mid-economy pricing differentiation persists in semiconductor and battery applications. Price differentiation stems from ANVISA certification burden and volume scale, with high-purity PFA and PVDF grades commanding technical service premiums. Cost compression in standard PTFE is intensifying because Brazilian compounders are realigning toward in-house production. Chemical processing buyers show highest price sensitivity, while semiconductor fabricators remain least sensitive due to contamination threshold requirements.
Supply Chain Analysis
Ocean freight cost volatility from Chinese and Mexican acid-grade fluorspar terminals to Brazilian ports directly feeds into landed cost structures for resin compounders serving Sao Paulo's industrial corridor. Geographic supply concentration centers on China, Mexico, and domestic Brazilian compounding capacity. Raw material dependencies rest on acid-grade fluorspar, virgin PTFE resin, and specialty modifier additives. Single-source vulnerability from Chinese fluorspar mining concentration presents structural risk. Distribution runs through Sao Paulo-based technical service teams with direct mill relationships to petrochemical and semiconductor end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where ANVISA's REACH-aligned substance registration requirements are accelerating import approval pathways and consolidating procurement authority within centralized technical teams.
For Market Incumbents: Deepen backward integration into acid-grade fluorspar sourcing to defend margin position against currency mismatch risks from Chinese and Mexican feedstock dependence. Expand technical service teams into Argentine lithium-battery corridors and Chilean mining districts to preempt emerging PVDF and ETFE specification demand. Certification investment in high-purity grades for semiconductor cleanroom construction represents the critical defensive lever against specialty resin competition.
For New Entrants and Emerging Players: The price-point gap between premium PFA semiconductor grades and economy PTFE chemical processing formulations creates white-space opportunity for modified-grade positioning. Target Argentine lithium-battery cathode binder specifications in Catamarca and Jujuy provinces as the most penetrable segment given nascent local supply. Pursue technical partnership go-to-market angles with Sao Paulo-based engineering procurement contractors to bypass entrenched mill-direct relationships.
For Investors and Strategic Acquirers: Roll-up economics work for regional technical specialists with deep Mercosur regulatory expertise because ANVISA registration pathways create sticky customer relationships and multi-year qualification timelines. Long-term viability over a 5-10 year window hinges on exposure to semiconductor and battery end-use diversification beyond commodity chemical processing. Acquisition target archetype: Brazilian compounders with captive fluorspar access and ANVISA-approved high-performance grade portfolios. The signal to watch is PFA substitution rates in Brazilian petrochemical pump applications above 200°C as indicator of specialty grade margin expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluorspar Sourcing | Mitigates Chinese mining concentration risk for Brazilian resin compounders. |
| High-Purity Grade Certification Investment | Captures ANVISA-aligned semiconductor specification demand in Campinas cleanrooms. |
| Technical Service Expansion to Argentina | Positions suppliers for Catamarca lithium-battery cathode binder qualification. |
| ETFE Formulation Differentiation | Opens Santiago transit hub architectural film specifications distinct from commodity PTFE. |
| Long-Term Supply Agreement with Petrochemical Majors | Locks in volume pricing across Camacari and Triunfo complex operators. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study, combining primary interviews with plant managers at Brazilian petrochemical complexes, procurement leads at Argentine lithium developers, distribution channel partners, and technical R&D directors with secondary validation from customs and trade data, SEC filings of global resin suppliers, ANVISA registration databases, and ACC regional chemical reports. Triangulation across these sources ensures volume and value estimates reflect actual procurement patterns rather than shipment-level distortions.
Historical trendline analysis of fluoropolymer consumption by grade tier, end-use industry, and regional production hub established baseline growth patterns across the projection horizon. The modeling framework segments by product chemistry, application function, and purity certification intensity, with CAGRs derived from regression against industrial production indices and capital expenditure cycles in target end-use sectors. Forecast inputs include semiconductor fabrication capacity announcements in Campinas and lithium-cell production timelines in Catamarca province.
Caveats apply where ANVISA regulatory implementation delays, fluorspar supply disruptions, or perfluoroalkyl substance restriction expansions could materially shift the outlook. Forecasts reflect assumptions about Mercosur harmonization progress and Chilean chemical registry divergence. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Polyphenylene Sulfide Market
Polymers & Resins
GCC Polyethylene Terephthalate (PET) Market
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
Polyurethane (PU) Foam Market
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
PEG 3500 Market
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Global Graft Polyols Market
Polymers & Resins
Natural Oil Polyols (NOP) Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
EVA Foam Market