
 Renewable Polyethylene Market | 2026-2036
Renewable Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Renewable Polyethylene Market Analytics
Aftermarket technical service revenue for conventional polyethylene processing equipment is narrowing as plant operators retrofit lines for bio-based feedstock compatibility. Braskem S.A. anchors South American supply through its sugarcane-derived ethylene platform, while Borealis AG leverages European cracker integration to sustain premium-grade output. Dow competes on manufacturing scale across North American and European sites, and SABIC positions its renewable product line to extend petrochemical expertise into circular feedstock segments.
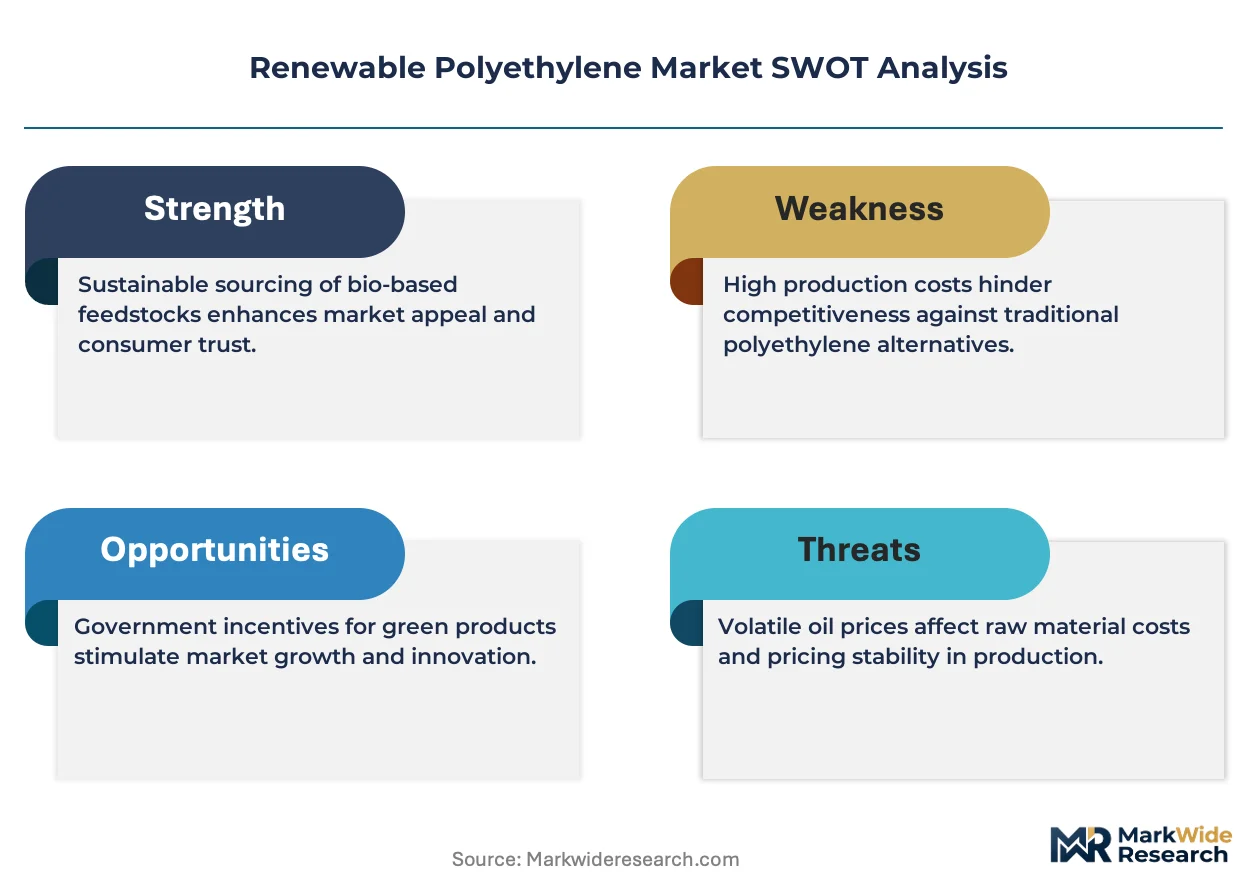
Renewable polyethylene denotes a thermoplastic polymer produced from bio-based ethylene feedstocks such as sugarcane ethanol or naphtha alternatives, manufactured via steam cracking and polymerization to achieve density specifications comparable to fossil-derived grades. Its primary commercial purpose centers on reducing Scope 3 emissions in plastic packaging and durable goods without requiring downstream processing equipment redesign. HDPE currently dominates structural volume in rigid packaging and construction piping, where established performance benchmarks support immediate substitution. LLDPE represents the fastest-expanding product category, driven by stretch film and agricultural film applications requiring flexibility and puncture resistance. The Food & Beverage end user segment concentrates margin pools, as brand owners negotiate long-term offtake agreements to secure certified renewable content for consumer-facing packaging claims.
The EU Green Deal and REACH frameworks mandate progressive renewable and recycled content thresholds for plastic packaging placed on the European market, directly conditioning product standards and market access for non-compliant suppliers. FDA food contact notifications and USDA BioPreferred program specifications govern parallel pathways in the United States, creating divergent compliance architectures that multinational producers must navigate simultaneously. Stakeholders should monitor feedstock certification scheme fragmentation, as ISCC PLUS, RSB, and Bonsucro standards compete for commercial adoption and determine premium capture across regional supply chains.
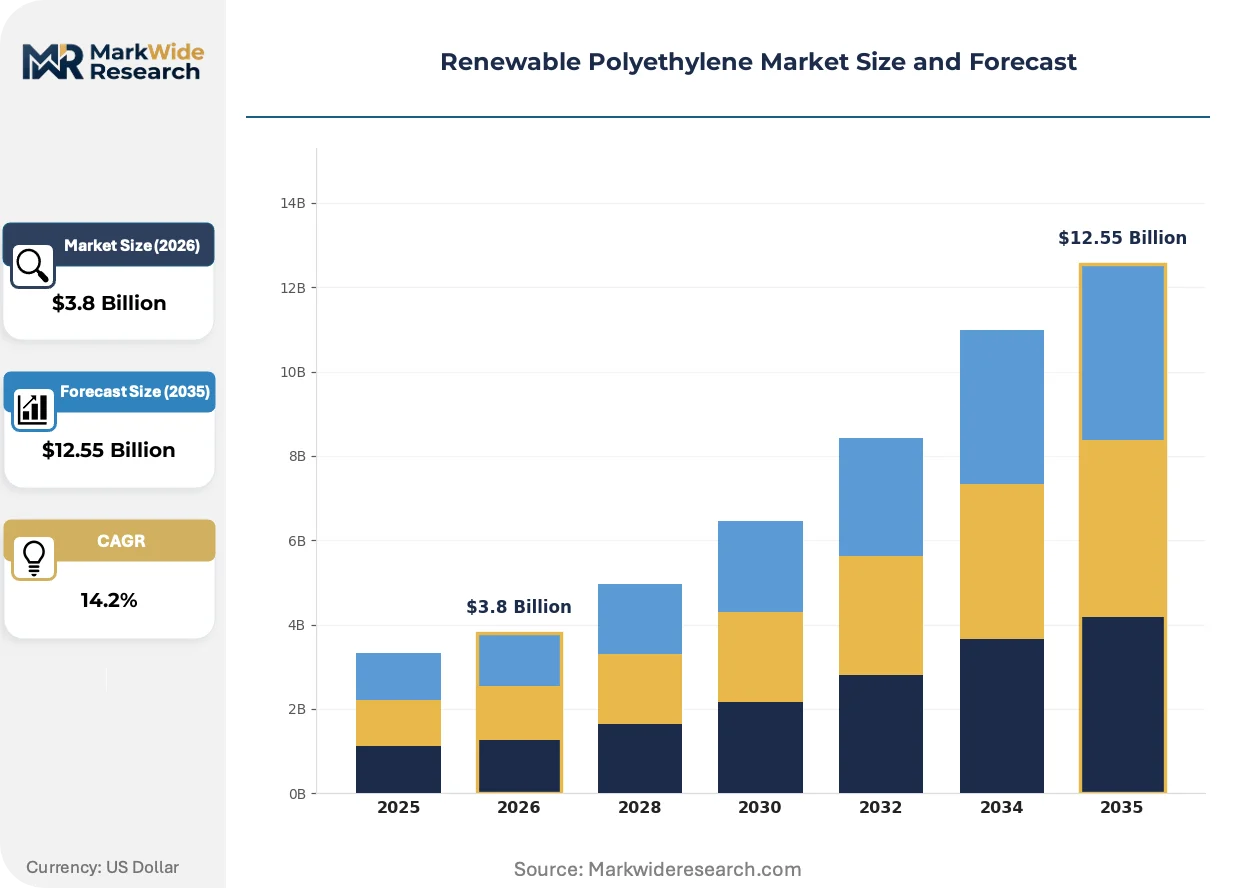
Market Dynamics
EU Green Deal mandates on recycled and renewable content thresholds are forcing packaging converters to reconfigure procurement specifications and retrofit processing lines before compliance deadlines tighten.
Growth Catalysts
- EU Green Deal Packaging Mandates:Progressive renewable content thresholds for plastic packaging placed on the European market are conditioning product standards and market access, compelling converters to secure certified bio-based feedstock grades.
- Sugar-to-Ethanol Platform Maturity:Commercial-scale steam cracking of sugarcane-derived ethanol has achieved density specifications comparable to fossil-derived polyethylene, enabling immediate substitution in rigid packaging without equipment redesign.
- Brand Owner Ofotake Agreements:Food and beverage companies are negotiating long-term supply contracts to secure certified renewable content for consumer-facing packaging claims, concentrating margin pools in this end-use vertical.
Market Restraints
- Feedstock Cost Volatility:Agricultural commodity price swings for sugarcane and corn directly compress margins for bio-based ethylene producers, unlike the more stable naphtha pricing that underpins conventional polyethylene economics.
- Brazilian Supply Concentration:A single geography dominates sugarcane-derived ethylene capacity, exposing buyers to currency risk, logistical bottlenecks, and climate-related harvest disruptions without geographic diversification.
- Certification Scheme Fragmentation:Competing ISCC PLUS, RSB, and Bonsucro standards create compliance friction and premium capture uncertainty across regional supply chains, complicating multinational procurement strategies.
Strategic Opportunities
- USDA BioPreferred Program Expansion:Federal procurement preferences for bio-based products are opening institutional purchasing channels for renewable polyethylene in agricultural films and durable goods applications.
- Agricultural Film Segment Penetration:LLDPE grades for stretch film and silage wrap represent underdeveloped demand pockets where puncture resistance requirements align with bio-based material performance characteristics.
- Chemical Cluster Integration:European crackers in Germany and the Netherlands are retrofitting for bio-naphtha co-processing, creating captive supply advantages for integrated producers serving premium packaging markets.
Industry Challenges
- Processing Equipment Retrofit Complexity:Plant operators face technical service revenue erosion and capital allocation dilemmas when adapting conventional polyethylene lines for bio-based feedstock compatibility without guaranteed offtake volumes.
- Multi-Jurisdiction Compliance Burden:Producers must simultaneously navigate divergent FDA food contact notifications, REACH substance restrictions, and EU Green Deal implementation timelines, straining regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Renewable Polyethylene Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: HDPE, LDPE, LLDPE, bioplastics Application: Packaging, Automotive, Construction, Agricultural Films End User: Consumer Goods, Food & Beverage, Industrial, Healthcare Distribution Channel: Direct Sales, Online Retail, Wholesale, Distributors |
| Companies Covered | Braskem S.A., LyondellBasell Industries Holdings B.V., Borealis AG, Dow, INEOS Group, Iwatani Corporation, SABIC, ExxonMobil Corporation, Avery Dennison Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Renewable Polyethylene Market Evolving Landscape
Digital certification and molecular tracing technologies are compressing verification timelines while regulatory frameworks harden compliance requirements across multiple jurisdictions simultaneously.
Mass balance accounting software is virtualizing supply chain transparency for renewable polyethylene. Brand owners in food packaging are adopting these systems to substantiate sustainability claims without physical segregation of bio-based and fossil streams. This technology is virtualizing the documentation burden that previously required dedicated storage and handling infrastructure.
REACH substance restrictions are tightening impurity thresholds for bio-based feedstocks entering European polymerization facilities. Chemical producers must now document contaminant profiles across agricultural supply chains to maintain market access. Food contact applications face the most stringent documentation requirements, driving investment in purification and testing capabilities.
Converters are unbundling after-sales technical service contracts from equipment procurement as they retrofit lines for bio-based compatibility. Machinery vendors now face compressed service revenue streams while buyers seek specialized expertise in processing parameter optimization. This shift is most pronounced in Germany and the Netherlands, where chemical cluster density supports independent technical service providers.
Renewable Polyethylene Market Segmentation
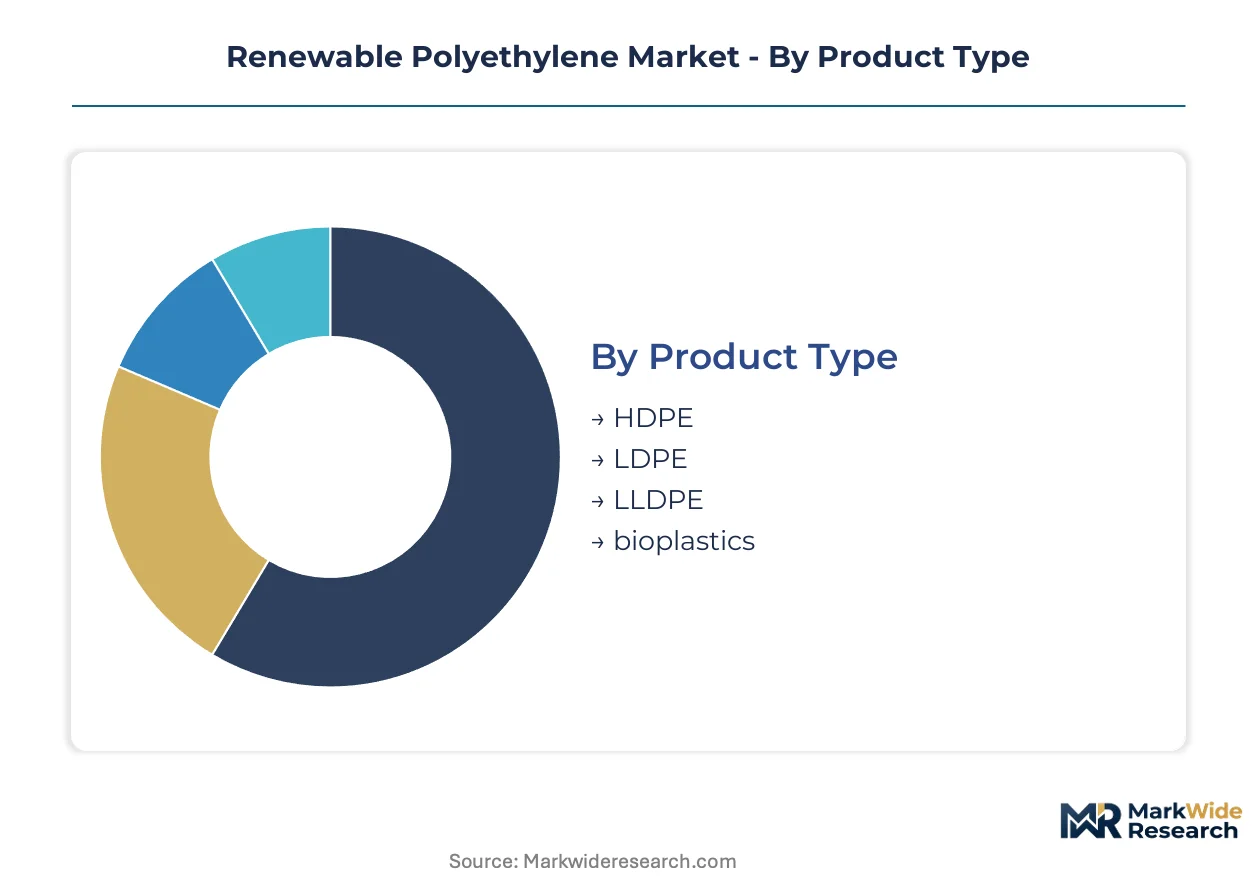
Segmentation reveals how renewable polyethylene demand fragments across performance requirements, regulatory exposure, and procurement sophistication. Each dimension carries distinct margin profiles and compliance burdens that reshape supplier priorities.
Product Type:
Mature commodity grades dominate volume, while specialty bioplastics carve out premium niches through certification complexity.
- HDPE:High-density formulations deliver rigidity specifications matching fossil-derived grades in blow-molded containers and extruded piping. German packaging converters source this grade most heavily for dairy bottles and industrial drums where drop-test performance is non-negotiable.
- LLDPE:Linear low-density structures provide puncture resistance and stretch recovery for agricultural film and flexible packaging. Dutch chemical cluster producers are scaling LLDPE output fastest to serve European silage wrap and pallet stretch film demand.
- LDPE:Low-density grades serve film and coating applications requiring optical clarity and low seal-initiation temperatures.
- Bioplastics:Compostable and biodegradable variants address single-use bans in select municipal jurisdictions with divergent degradation standards.
HDPE handles the majority of throughput; LLDPE is the fastest mover on share.
Application:
Application mix tracks regulatory intensity, with packaging facing the steepest renewable content mandates while construction lags on specification adoption.
- Packaging:Rigid and flexible formats for food, beverage, and consumer goods carry EU Green Deal compliance deadlines. Brand owners in the Netherlands negotiate long-term offtake agreements to secure ISCC PLUS certification for consumer-facing claims.
- Agricultural Films:Mulch films, greenhouse covers, and silage wrap represent underdeveloped demand pockets where bio-based LLDPE puncture resistance aligns with field performance requirements.
- Automotive:Interior trim and under-hood components adopt renewable polyethylene for Scope 3 reporting, though temperature specifications limit penetration.
- Construction:Piping and geomembrane applications progress slowly due to decades-long performance warranties and conservative specification bodies.
Packaging commands the deepest margin pools; agricultural films are expanding most quickly as sustainability premiums align with crop protection economics.
End User:
End-user concentration reflects certification willingness, with consumer-facing brands absorbing premium costs faster than industrial buyers.
- Food & Beverage:Bottled water, dairy, and prepared food brands drive certified renewable content procurement. German retailers mandate bio-based packaging thresholds for private-label suppliers under corporate sustainability commitments.
- Consumer Goods:Personal care and household product manufacturers leverage renewable polyethylene for shelf differentiation and ESG reporting.
- Industrial:Bulk containers, drums, and dunnage applications prioritize cost parity over certification, slowing adoption.
- Healthcare:Sterile packaging and medical device components face FDA notification burdens and biocompatibility testing that constrain near-term uptake.
Food & Beverage concentrates procurement volume; consumer goods are gaining share fastest as brand marketing budgets absorb sustainability premiums.
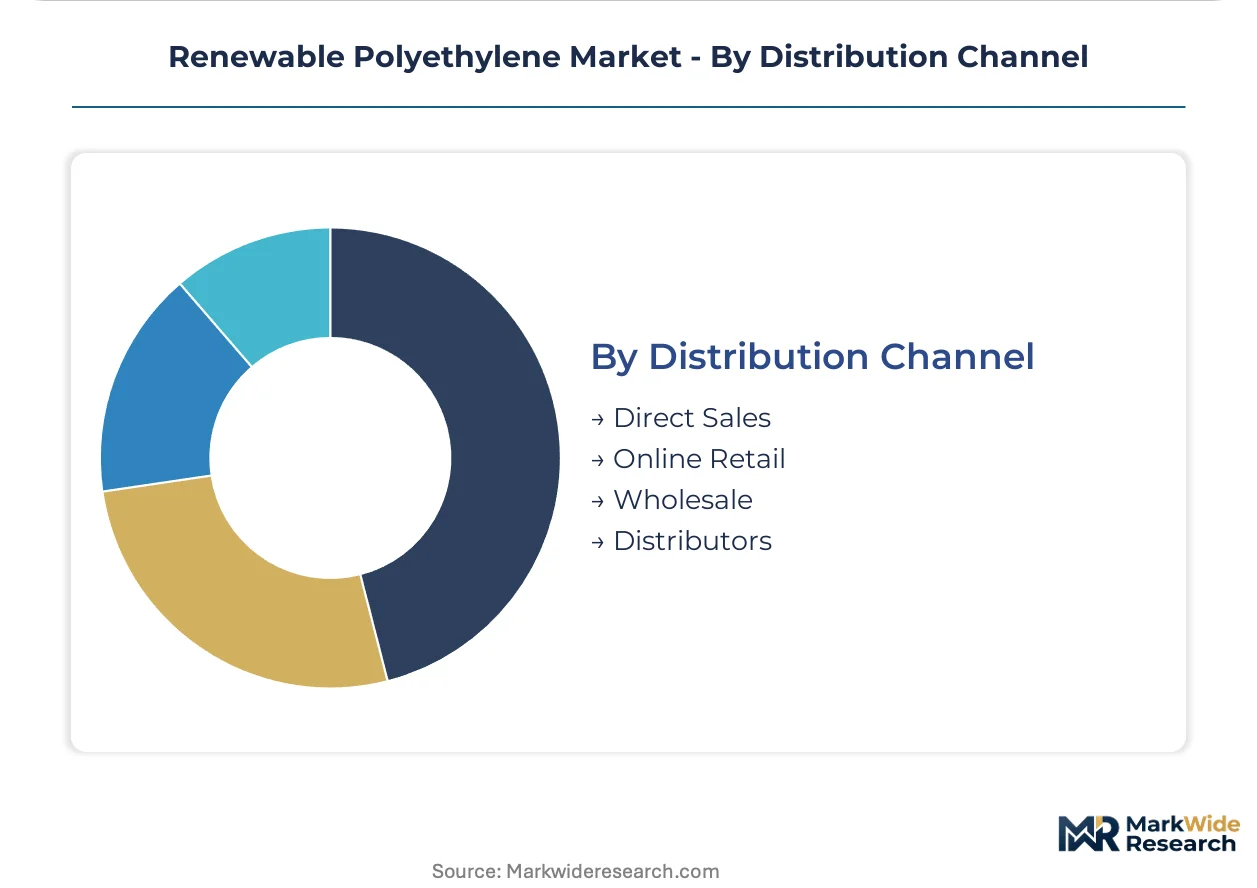
Distribution Channel:
Channel structure tracks customer scale and technical service requirements, with large converters bypassing intermediaries while smaller buyers rely on distributor inventory.
- Direct Sales:Integrated producers serve high-volume converters in the Netherlands and Germany through dedicated account teams managing certification documentation.
- Distributors:Regional stockists hold ISCC PLUS-certified inventory for mid-tier converters lacking procurement scale for mill-direct relationships.
- Wholesale:Volume aggregators serve commodity film extruders with standard grades where certification documentation is less critical.
- Online Retail:E-procurement platforms emerge for specialty bioplastics and small-lot experimental grades, though bulk polyethylene remains offline.
Direct sales capture the largest contract value; distributors are expanding fastest as mid-market converter technical requirements fragment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil absorb agricultural commodity volatility most readily, while European converters face the steepest compliance-driven cost premiums. German and Dutch chemical clusters command pricing power through integrated infrastructure. North American procurement prioritizes federal bio-preferred certification over mandatory thresholds.
Germany
Packaging converters in the Rhine-Ruhr corridor source HDPE for dairy bottles and industrial drums under retailer-mandated bio-based thresholds. EU Green Deal implementation timelines condition procurement specifications for private-label suppliers. The Marl chemical cluster hosts retrofitted crackers co-processing bio-naphtha for captive renewable polyethylene output.
Brazil
Sugarcane-derived ethylene capacity concentrates in São Paulo state, exposing buyers to harvest disruption and currency risk without geographic diversification. ANVISA governs food contact applications parallel to FDA pathways for export-oriented production. The Triângulo Mineiro region anchors feedstock supply through integrated sugar-to-ethanol-to-polymer infrastructure.
United States
Federal procurement through the USDA BioPreferred program opens institutional channels for agricultural films and durable goods applications. FDA food contact notifications govern packaging claims separately from EU REACH frameworks. Gulf Coast petrochemical complexes evaluate bio-naphtha co-processing feasibility for domestic renewable grade production.
Netherlands
Rotterdam-area chemical clusters scale LLDPE output fastest to serve European silage wrap and pallet stretch film demand. ISCC PLUS certification requirements concentrate margin pools among converters with mill-direct relationships. The Moerdijk industrial zone integrates bio-naphtha handling with existing steam cracking assets for premium packaging supply.
China
Dual carbon goals accelerate pilot projects for coal-to-ethanol substitution with bio-based alternatives in packaging applications. NMPA and GB standards govern food contact specifications with increasing alignment to EU migration limits. The Yangtze River Delta hosts emerging biopolymer demonstration plants targeting export-oriented brand owner requirements.
Renewable Polyethylene Market Competitive Landscape
Capability concentration sits with integrated petrochemical majors possessing cracker retrofit expertise; scale advantage sits with diversified polymer producers with multi-site manufacturing footprints. The vendor base stratifies into three tiers: sugar-to-ethanol platform specialists, European cracker-integrated producers, and North American scale players with bio-naphtha sourcing relationships. Dominant competitive moves include chemical cluster integration for captive feedstock supply and long-term offtake contracting with food and beverage brand owners.
Within the integrated petrochemical tier, Braskem S.A. and Borealis AG occupy positions representing divergent geographic and feedstock strategies. Braskem anchors South American supply through its São Paulo-based sugarcane platform. Borealis exemplifies European cracker integration advantages through its Austrian-German manufacturing footprint. Dow sits within the scale-driven North American and European producer category with multi-site operational scope.
| Leading Market Players |
|---|
| Braskem S.A. |
| LyondellBasell Industries Holdings B.V. |
| Borealis AG |
| Dow |
| INEOS Group |
| Iwatani Corporation |
| SABIC |
| ExxonMobil Corporation |
| Avery Dennison Corporation |
| Others |
Value Network & Pricing Analysis
Rotterdam-Antwerp barge freight corridors carry bio-naphtha feedstock premiums that cascade through European chemical clusters, compressing margins for non-integrated converters while rewarding backward-linked producers with captive supply advantages and tiered pricing power across certification grades.
Pricing Analysis
After-sales technical service contracts drive lifetime value capture for machinery vendors retrofitting conventional polyethylene lines. Three-tier pricing structure across ISCC PLUS-certified premium, standard bio-based, and economy fossil-adjacent grades separates converters by documentation burden and brand claim eligibility. Cost compression in mid-tier standard grades is intensifying because agricultural commodity volatility transmits directly into ethanol feedstock costs. Industrial bulk container buyers exhibit highest price sensitivity, while food and beverage brand owners absorb sustainability premiums for consumer-facing packaging claims.
Supply Chain Analysis
Sugarcane ethanol feedstock draws from São Paulo state plantations, Brazilian Triângulo Mineiro processing hubs, and emerging European wheat straw pilot projects. Raw material dependencies center on agricultural harvest cycles, ANVISA-compliant purification chemistries, and cracker co-processing catalysts. Single-source vulnerability concentrates in Brazilian sugarcane supply during climate-disrupted harvest seasons. Distribution runs through integrated chemical clusters in Germany and the Netherlands for mill-direct procurement, with regional distributors holding certified inventory for mid-tier converters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass balance accounting platforms are reconfiguring this market toward ecosystem economics, where interoperability between certification schemes and molecular tracing systems determines which suppliers capture premium positioning.
For Market Incumbents: Pre-empt margin erosion from certification scheme fragmentation by securing dual ISCC PLUS and RSB accreditation before compliance deadlines tighten. Deepen backward integration into bio-naphtha co-processing at European cracker assets to defend against South American supply concentration. Lock in five-year offtake agreements with Dutch and German food retailers to anchor volume visibility.
For New Entrants and Emerging Players: Establish a beachhead in agricultural film applications where LLDPE puncture resistance specifications align with bio-based performance and sustainability premiums match crop protection economics. Target mid-tier converters in the Netherlands lacking mill-direct procurement scale but requiring ISCC PLUS documentation for retailer compliance. Lead with technical service partnerships rather than commodity grade competition.
For Investors and Strategic Acquirers: European cracker-integrated producers with bio-naphtha handling capabilities offer the strongest long-term viability through captive feedstock supply and regulatory compliance positioning. Monitor feedstock certification scheme consolidation as the inflection signal—premium capture will compress to dominant standards, rewarding early adopters with stranded documentation assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Naphtha Supply | Captive feedstock access at Rotterdam and Marl chemical clusters insulates margin from agricultural commodity swings. |
| Dual Certification Investment | ISCC PLUS and RSB accreditation opens EU Green Deal-compliant procurement channels for German dairy packaging converters. |
| Long-Term Offtake Contracting | Five-year agreements with Dutch retailers secure volume visibility for LLDPE silage wrap and stretch film output. |
| Agricultural Film Segment Expansion | LLDPE grades for European silage wrap align puncture resistance with bio-based material field performance. |
| Mass Balance Platform Adoption | Digital tracing systems virtualize supply chain transparency for brand owner sustainability claim substantiation. |
Research Methodology
Operator-level perspectives from plant managers at European chemical clusters, procurement leads at German packaging converters, technical R&D directors at bio-naphtha suppliers, and aftermarket service heads at processing equipment vendors anchored the qualitative base. Primary interview insights combined with customs and trade data, European Chemical Industry Council sector reports, SEC 10-K disclosures from listed polymer producers, and ISCC certification registry databases. Bottom-up volume builds across grade tiers and end-use segments triangulated against top-down macroeconomic demand projections.
Scenario-bracketing framed the analytical approach across the projection horizon, with sensitivity testing for agricultural commodity price bands and regulatory compliance timeline shifts. Segmentation dimensions modeled include density grade tier, end-use vertical, certification standard, regional production hub, and converter procurement scale. CAGRs derived from trend extrapolation of historical substitution rates and policy-mandated content threshold implementation curves. Feedstock yield assumptions and cracker co-processing capacity buildouts served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in euro-dollar exchange rates, Brazilian real volatility, or EU carbon border adjustment implementation would shift the trajectory. Forecasts reflect documented assumptions on certification scheme adoption rates and cracker retrofit timelines. Material shifts in EU Green Deal enforcement intensity or breakthroughs in enzymatic polyethylene recycling would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Rigid Spray Polyurethane Foam Market
Polymers & Resins
Polypropylene Filler Sheet Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
Polyacrylic Acid Market
Polymers & Resins
Polysorbate Market
Polymers & Resins
Global Barrier Resins Market
Polymers & Resins
BMI Resins Market
Polymers & Resins
Macroporous Strong Acid Cation Exchange Resin Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
North America Epoxy Resins Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Medical Fluoropolymers Market
Polymers & Resins
Sodium Polyacrylate Market
Polymers & Resins
Polymer Filler Market