
 South America Polycarbonate (PC) Market | 2026-2036
South America Polycarbonate (PC) Market Size, Share, and Industry Trends Forecast 2026-2036
South America Polycarbonate (PC) Market Insights
Multi-source resin procurement is hardening across South America's polycarbonate value chain as compounders and processors reduce dependency on single-origin supply. Covestro AG leverages its Latin American distribution infrastructure to sustain technical service relationships with regional automotive Tier 1 suppliers. Braskem S.A. anchors its position through backward integration into phenol and acetone feedstocks at its Triunfo complex. SABIC competes via its specialized optical-grade resin portfolio targeting medical device and lighting applications.
Polycarbonate is a thermoplastic polymer synthesized from bisphenol A and phosgene, characterized by glass-like transparency, impact resistance exceeding 250 times that of silicate glass, and a Vicat softening point near 145 degrees Celsius. Its primary industrial purpose centers on substituting glass and metal in weight-critical, impact-sensitive applications across transportation, electronics, and construction. Resins dominate volume flows into injection molding and extrusion operations serving automotive and electronics end users, while films and sheets capture margin pools in architectural glazing and safety equipment. Medical devices and optical media represent specialized application segments where optical clarity and sterilization compatibility command formulation premiums.
Brazil's INMETRO and ANVISA shape polycarbonate demand through appliance energy-labeling mandates and medical-device biocompatibility standards, respectively. Argentina's national chemical regulator enforces import quality certifications that filter non-compliant Asian resin shipments. Stakeholders must monitor feedstock cost volatility at the Triunfo petrochemical hub and track regulatory harmonization progress between Mercosur member states to anticipate cross-border formulation approval timelines.
Market Dynamics
Automotive lightweighting mandates and electrical appliance efficiency regulations across Brazil and Argentina are compressing substitution timelines for polycarbonate against glass and metal, concentrating procurement power in the hands of Tier 1 suppliers with multi-source resin qualification capabilities.
Growth Catalysts
- INMETRO energy labeling:Brazil's appliance efficiency mandates accelerate polycarbonate adoption in LED lighting housings, displacing heavier thermoset alternatives in refrigerator interiors and washing machine panels.
- Headlamp lens specification:Automotive safety standards in Argentina require impact-resistant glazing, driving resin volumes into projector and adaptive headlamp modules for compact vehicle platforms.
- São Paulo electronics clustering:Southeast Brazil's manufacturing corridor concentrates injection molding capacity for smartphones, tablets, and consumer electronics, creating localized demand density for optical-grade polycarbonate.
Market Restraints
- Bisphenol A cost volatility:Feedstock price swings at the Triunfo petrochemical hub compress compounder margins and destabilize long-term supply contracts with automotive processors.
- Import certification friction:Argentina's national chemical regulator filters non-compliant Asian resin shipments, extending lead times for processors lacking pre-qualified alternative sources.
- Polymethyl methacrylate substitution:Acrylic resins capture cost-sensitive architectural glazing applications where UV stability requirements do not mandate polycarbonate's impact performance.
Strategic Opportunities
- Medical device biocompatibility:ANVISA's sterilization compatibility standards for surgical instruments and drug delivery devices create formulation premiums for specialized optical-grade resins.
- Recycled content mandates:Emerging post-consumer recycling requirements across Mercosur member states position mechanical recycling investments as compliance-enabling infrastructure.
- Thin-wall electronics miniaturization:Notebook and tablet manufacturers in Brazil's Free Trade Zone of Manaus specify high-flow polycarbonate grades for reduced wall thickness and component weight.
Industry Challenges
- Multi-source qualification timelines:Automotive Tier 1 suppliers require 18-24 month resin approval cycles, locking processors into incumbent relationships and delaying competitive sourcing transitions.
- Optical-grade contamination control:Medical and lighting applications demand cleanroom compounding infrastructure that remains scarce outside São Paulo state's established processor network.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Polycarbonate (PC) Market |
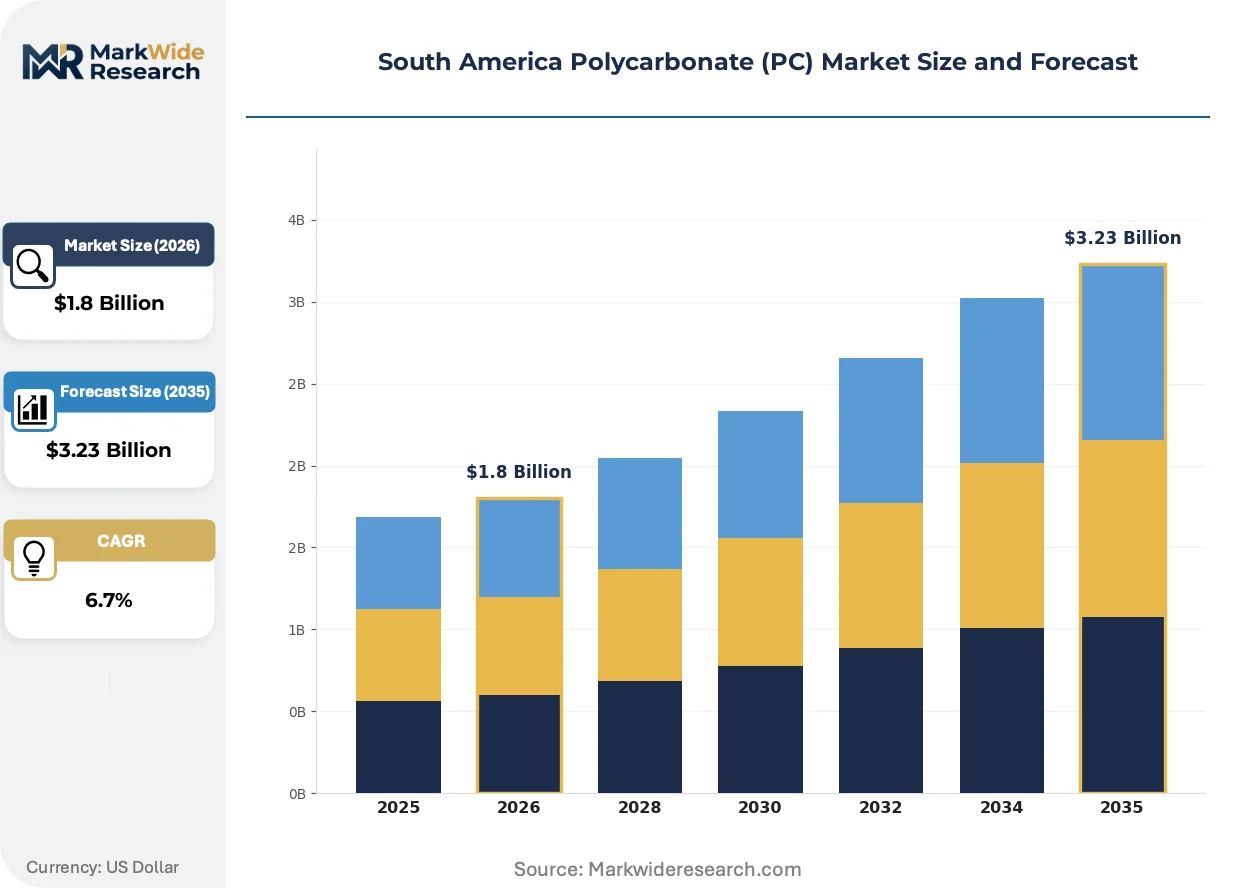
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Films, Sheets, Resins, Beverage Bottles End User: Automotive, Electronics, Construction, Consumer Goods Application: Lighting, Safety Glasses, Optical Media, Medical Devices Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | Covestro AG, SABIC, LG Chem, Mitsubishi Chemical Corporation, Teijin Limited, Trinseo, Braskem S.A., Dow, Inc., Chi Mei Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Polycarbonate (PC) Market Trends and Innovations
Material science advances and regulatory harmonization efforts are restructuring how polycarbonate flows through South American value chains, with sustainability certifications and digital procurement platforms emerging as new competitive battlegrounds.
Bio-based polycarbonate feedstocks synthesized from non-bisphenol A precursors are decentralizing resin supply assumptions among sustainability-focused brand owners. European automotive OEMs with Brazilian assembly operations specify mass-balance certified grades, pressuring local compounders to secure ISCC PLUS chain-of-custody documentation. This feedstock diversification is decentralizing the historical concentration of petrochemical-derived resin sourcing.
Mercosur regulatory harmonization negotiations are converging medical device biocompatibility standards across Brazil, Argentina, Paraguay, and Uruguay. ANVISA and Argentina's national regulator are aligning sterilization validation protocols, reducing formulation re-approval burdens for cross-border resin shipments. Medical device manufacturers with regional assembly footprints capture simplified compliance pathways and compressed product registration timelines.
Digital resin procurement platforms are fragmenting traditional distributor relationships as compounders and processors in Brazil's southeast industrial corridor adopt direct-to-mill sourcing. Covestro and SABIC maintain proprietary customer portals with real-time pricing and technical documentation, while regional distributors defend position through localized inventory positioning and just-in-time delivery commitments. This channel disintermediation concentrates most visibly among mid-volume electronics molders in São Paulo state's ABC industrial region.
South America Polycarbonate (PC) Market Segmentation
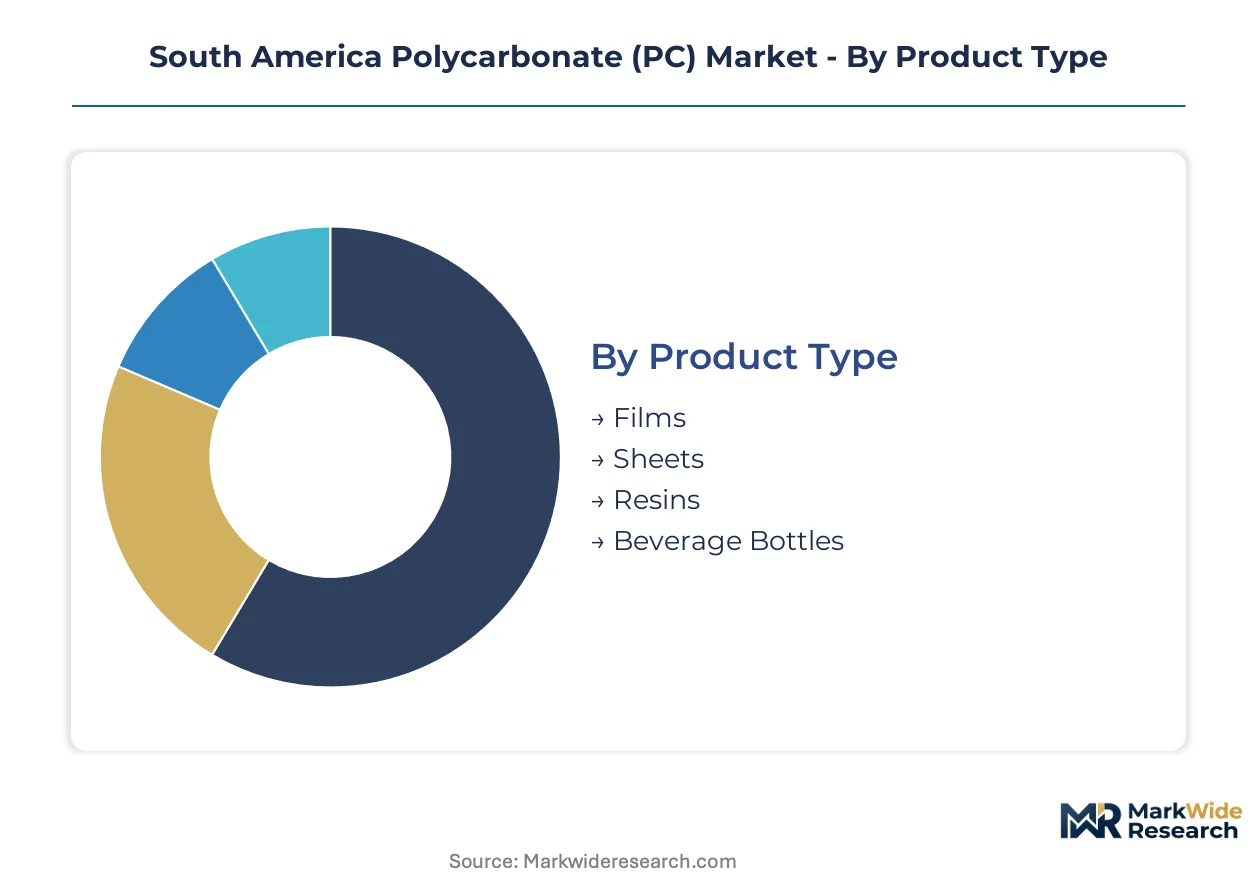
Polycarbonate flows through South American value chains along four distinct axes that determine pricing power, technical service intensity, and margin capture. Product type dictates processing infrastructure requirements; end user concentration shapes procurement leverage; application specificity drives formulation premiums; and channel choice reflects volume scale and geographic reach.
Product Type:
Buyers differentiate by processing method and performance specification, with resin processors seeking melt-flow customization while film and sheet purchasers prioritize dimensional stability and optical clarity.
- Resins:Injection molding and extrusion grades dominate volume flows into São Paulo state's automotive and electronics clusters. Compounders at the Triunfo petrochemical hub blend flame-retardant and high-flow variants for headlamp housings and thin-wall consumer electronics, with INMETRO efficiency labeling accelerating substitution for heavier thermosets in appliance interiors.
- Sheets:Extruded solid and multi-wall configurations serve architectural glazing and safety equipment applications across Brazil's southeastern construction corridor. Specifiers favor polycarbonate over acrylic where impact resistance and thermal insulation converge, particularly in school and hospital retrofit projects subject to ANVISA facility safety guidelines.
- Films:Optical-grade and hard-coated films supply membrane switch overlays and display protection for Manaus Free Trade Zone electronics assemblers.
- Beverage Bottles:Reusable water bottle and infant feeding segments face bisphenol A scrutiny under ANVISA food-contact regulations, constraining formulation flexibility.
Volume sits with Resins; growth tilts toward Sheets.
End User:
Procurement sophistication varies sharply across sectors, with automotive Tier 1 suppliers demanding 18-24 month qualification cycles while construction distributors accept standard off-grade material.
- Automotive:Headlamp lens modules and interior glazing specifications concentrate demand among Brazil's southeastern OEM supply base. Argentina's safety standards mandate impact-resistant projector housings, locking resin volumes into adaptive lighting platforms for compact vehicle segments.
- Electronics:Notebook and tablet manufacturers in Manaus specify high-flow grades for reduced wall thickness, while smartphone molders in São Paulo's ABC region drive optical-grade consumption for transparent housings and display frames.
- Construction:Skylight and safety barrier applications in Brazil's commercial building sector absorb multi-wall sheet volumes, with cost-sensitive residential segments vulnerable to acrylic substitution.
- Consumer Goods:Appliance manufacturers responding to INMETRO labeling requirements specify polycarbonate for refrigerator interiors and washing machine panels where durability and thermal efficiency intersect.
Automotive commands the largest procurement volumes; Electronics expands most quickly on miniaturization trends.
Application:
Performance thresholds and regulatory exposure segment demand, with medical and optical applications commanding formulation premiums while lighting and safety equipment compete on cost-positioning.
- Medical Devices:Surgical instrument housings and drug delivery components require ANVISA-validated sterilization compatibility and biocompatibility certification. Cleanroom compounding capability outside São Paulo state remains scarce, concentrating premium resin flows through qualified processors.
- Lighting:LED housing and diffuser applications dominate volume consumption under INMETRO efficiency mandates, with polycarbonate displacing metal and glass in residential and commercial retrofits.
- Safety Glasses:Industrial and consumer protective eyewear specifications absorb impact-modified grades, with Brazil's manufacturing safety regulations driving replacement cycle frequency.
- Optical Media:Declining physical media consumption compresses this segment, though specialized archival and medical imaging discs retain niche demand.
Lighting holds current volume leadership; Medical Devices captures the steepest expansion trajectory on regulatory premiumization.
Distribution Channel:
Channel selection reflects buyer scale and technical service requirements, with large compounders bypassing intermediaries while mid-volume processors rely on inventory positioning and just-in-time fulfillment.
- Direct Sales:Covestro and SABIC maintain proprietary customer portals with real-time pricing and technical documentation for automotive Tier 1 and large electronics molders in São Paulo state's industrial corridor.
- Distributors:Regional distributors defend position through localized inventory and technical service relationships with mid-volume processors lacking mill-direct qualification.
- Wholesalers:Construction-focused wholesalers aggregate sheet and film volumes for smaller fabrication shops across Brazil's interior states.
- Online Retail:Emerging digital procurement platforms fragment traditional relationships among commodity-grade resin purchasers seeking price transparency.
Direct Sales anchors volume concentration; Online Retail gains share fastest on channel disintermediation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Triunfo petrochemical complex in southern Brazil anchors South American polycarbonate feedstock supply through captive phenol and acetone production. This concentration shapes resin availability across the continent's automotive and electronics manufacturing corridors.
Brazil
INMETRO energy efficiency labeling mandates accelerate polycarbonate substitution in LED lighting housings and appliance interiors. ANVISA biocompatibility standards for medical devices create formulation premiums for optical-grade resins. São Paulo state's southeastern industrial corridor concentrates injection molding capacity for automotive Tier 1 suppliers and electronics manufacturers.
Argentina
Automotive safety regulations mandate impact-resistant headlamp lens specifications for compact vehicle platforms. The national chemical regulator enforces import quality certifications that filter non-compliant Asian resin shipments. Córdoba and Buenos Aires provinces host adaptive lighting module assembly operations drawing qualified resin volumes.
Chile
Mining safety equipment specifications drive consumption of impact-modified grades for protective eyewear and helmet visors. The national standards body aligns with Mercosur technical regulations for cross-border material approvals. Santiago's manufacturing belt concentrates sheet extrusion for architectural glazing in commercial retrofit projects.
Colombia
Construction sector growth absorbs multi-wall polycarbonate sheet for commercial building skylights and safety barriers. The national planning department promotes industrial cluster development in Bogotá's surrounding manufacturing zones. Antioquia department's Medellín metro area emerges as a secondary compounding location for Andean region distribution.
Peru
Infrastructure investment programs specify polycarbonate glazing for public facility retrofits including schools and hospitals. The national quality institute enforces conformity assessment for imported resin shipments. Lima's Callao port district functions as a logistics hub for Pacific coast redistribution to Ecuador and Bolivia.
South America Polycarbonate (PC) Market Competitive Landscape
Backward integration into phenol and acetone feedstocks dominates the current landscape as compounders defend margin positions against raw material volatility. The market structures around three tiers: integrated petrochemical producers with captive feedstock supply, global resin specialists leveraging technical service relationships, and regional distributors maintaining localized inventory positions. Strategic archetypes include feedstock-integrated domestic champions, technology-licensed global suppliers, and logistics-focused channel intermediaries. Capacity expansion at the Triunfo hub and multi-source qualification programs among automotive processors represent the dominant competitive moves reshaping supply relationships.
Among integrated producers with captive feedstock positions, Braskem S.A. anchors the regional supply base through its Triunfo complex operations. Global resin specialists including Covestro AG and SABIC occupy positions emphasizing technical service depth and specialized optical-grade portfolios. These three companies exemplify the competitive tension between backward-integrated domestic scale and technology-differentiated international supply.
| Leading Market Players |
|---|
| Covestro AG |
| SABIC |
| LG Chem |
| Mitsubishi Chemical Corporation |
| Teijin Limited |
| Trinseo |
| Braskem S.A. |
| Dow, Inc. |
| Chi Mei Corporation |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap compounders across Brazil's southeastern industrial corridor anchor pricing discipline through captive relationships with automotive Tier 1 suppliers, while their limited balance-sheet capacity constrains aggressive price competition. This ownership structure reinforces long-term contract stability over spot-market volatility, particularly at the Triunfo petrochemical hub where feedstock integration buffers margin compression.
Pricing Analysis
Warranty and technical service bundling separates premium optical-grade resin contracts from standard injection-molding grades, with Covestro and SABIC portal-based accounts including formulation support and 18-month qualification assistance. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and volume scale, with ANVISA-validated medical resins commanding the widest spreads. Cost compression in commodity extrusion grades is intensifying because acrylic substitution threatens architectural glazing applications. Construction distributors prove most price-sensitive, while medical device processors absorb premiums for sterilization-compatible formulations.
Supply Chain Analysis
Freight cost differentials between Triunfo-complex origin shipments and Asian import alternatives shape procurement decisions for São Paulo state molders, with Argentina's chemical regulator adding landed cost complexity through extended certification timelines. Supply concentrates in Brazil and Argentina for qualified automotive resin, while Asian producers feed cost-sensitive sheet and film segments. Raw material flows hinge on phenol and acetone availability at the Triunfo hub, with bisphenol A price volatility representing the dominant supply chain risk. Distribution runs through mill-direct portals for large compounders and regional distributor networks for mid-volume processors lacking qualification scale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with cleanroom compounding infrastructure scarcity outside São Paulo state propping pricing power for qualified medical-grade resin processors.
For Market Incumbents: Cement feedstock security through backward integration into phenol and acetone at the Triunfo complex, locking in margin stability against bisphenol A volatility. Deepen technical service relationships with automotive Tier 1 suppliers to extend 18-24 month qualification cycles as a competitive moat against emerging Asian resin entrants. Prioritize ISCC PLUS certification investments to capture European OEM mass-balance specifications.
For New Entrants and Emerging Players: Mid-volume electronics molders in Manaus Free Trade Zone represent an underserved buyer archetype seeking high-flow grades with localized technical support. Target Andean region construction distributors in Colombia and Peru where multi-wall sheet demand outpaces qualified extrusion capacity. Pursue distributor partnerships with inventory-positioning capabilities rather than mill-direct qualification battles.
For Investors and Strategic Acquirers: Distressed-cycle entries favor regional distributors with established just-in-time delivery networks in Brazil's interior states, where channel consolidation potential remains unrealized. Long-term viability hinges on exposure to medical device and automotive segments with regulatory barriers to substitution. Watch Mercosur harmonization progress on sterilization validation protocols as the inflection signal for cross-border formulation premium compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol/Acetone | Captive feedstock supply at Triunfo complex shields Braskem from raw material volatility. |
| ISCC PLUS Certification Investment | Mass-balance documentation unlocks European automotive OEM specification requirements. |
| Cleanroom Compounding Capacity Addition | Medical-grade resin premiums concentrate where ANVISA-validated infrastructure remains scarce. |
| Digital Procurement Platform Deployment | Real-time pricing portals disintermediate traditional distributors among São Paulo electronics molders. |
| Mercosur Regulatory Harmonization Engagement | Cross-border sterilization protocol alignment reduces formulation re-approval burdens for regional medical device manufacturers. |
Research Methodology
Independent corroboration across plant managers at Triunfo complex operations, procurement leads at automotive Tier 1 suppliers, and distribution channel partners in São Paulo's ABC industrial region underwrites the qualitative findings. Primary interviews with technical R&D directors and customs/trade data analysis, combined with ANVISA regulatory filings and SEC disclosures from global resin specialists, enabled bottom-up and top-down triangulation across the value chain.
Comparable-period anchoring to historical automotive production cycles and electronics assembly trends in Manaus shaped the projection horizon's baseline assumptions. The analytical framework modeled grade tier, end-use industry, and regional production hub segmentation throughout the forecast period, with CAGRs derived from demand elasticity coefficients and substitution rate analysis. Feedstock cost volatility at the Triunfo hub and regulatory harmonization velocity across Mercosur member states served as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bisphenol A price volatility and acrylic substitution acceleration in construction applications. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
Thermoplastic Starch (TPS) Market
Polymers & Resins
Photocure Resins Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
Global Polyol Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Europe Engineering Plastics Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
South America Polyvinyl Chloride (PVC) Market
Polymers & Resins
Global Polyamide-Imide Resin Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Europe Geopolymer Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Cellulosic Polymers Market