
 Africa Polyamide Market | 2026-2036
Africa Polyamide Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Polyamide Market Insights
Multi-source procurement is restructuring supply relationships across the Africa Polyamide Market as compounders reduce dependence on single European feedstock channels. BASF SE leverages its integrated caprolactam network to secure volume commitments from North African textile producers. LANXESS anchors its position through specialized PA 6 and PA 66 grades tailored to thermal management in automotive engine bays. DSM competes via bio-based polyamide pathways that address sustainability specifications from African automotive OEMs.
Polyamide denotes a class of thermoplastic polymers characterized by repeating amide linkages, with PA 6 and PA 66 representing the dominant aliphatic variants distinguished by monomer chain length and melting points ranging from 220°C to 265°C. These materials deliver tensile strength, chemical resistance, and dimensional stability for engineered components across transportation, electrical, and consumer sectors. PA 6 dominates volume flows into textile fiber and film extrusion due to cost-position and processing latitude. PA 66 commands margin pools in automotive components and electrical insulation where heat resistance thresholds exceed PA 6 capabilities. Granule form factors lead industrial offtake by African compounders serving injection molding and extrusion customers.
South Africa's National Regulator for Compulsory Specifications enforces polymer quality benchmarks for automotive and electrical applications, while Egypt's Egyptian Organization for Standardization and Quality administers import conformity protocols that filter substandard resin shipments. REACH-equivalent chemical registration pressures from European export markets are reshaping formulation transparency requirements for African compounders seeking EU-bound component supply chains. Stakeholders must monitor evolving polymer recycling mandates and extended producer responsibility frameworks as circularity clauses penetrate procurement specifications from multinational automotive and electronics brands operating assembly in Morocco, South Africa, and Egypt.
Market Dynamics
Automotive OEMs in Morocco, South Africa, and Egypt are consolidating polyamide sourcing around integrated compounders capable of delivering REACH-equivalent formulation transparency, compressing spot-market resin trading and favoring long-term volume commitments with technical service attachments.
Growth Catalysts
- Automotive thermal management grades:PA 66 compounds with glass fiber reinforcement are displacing metal in engine bay components as OEMs pursue weight reduction targets.
- Egypt's textile manufacturing corridor:Film-grade PA 6 consumption is accelerating in flexible packaging and industrial yarn extrusion for export-oriented apparel supply chains.
- South Africa's Automotive Production and Development Programme:Incentives for local content sourcing are redirecting Tier 1 supplier footprints toward domestic compounding capacity.
Market Restraints
- Caprolactam import dependency:African compounders rely on European and Middle Eastern feedstock channels, exposing margin structures to freight rate volatility and currency mismatches.
- PA 66 precursor concentration:Adiponitrile supply is controlled by a limited set of integrated producers outside the continent, constraining grade availability for heat-resistant applications.
- Recycling infrastructure gaps:Post-industrial and post-consumer polyamide recovery rates remain minimal, limiting circular feedstock access for sustainability-mandated procurement.
Strategic Opportunities
- Nigeria's industrial clustering:Emerging polymer conversion zones in Lagos and Port Harcourt offer first-mover positioning for compounders serving West African consumer goods manufacturing.
- Bio-based polyamide pathways:Castor oil-derived PA 11 and PA 1010 grades are penetrating automotive and electrical segments where carbon footprint specifications are hardening.
- Direct distribution to mid-tier processors:Bypassing traditional distributor layers through technical sales teams is capturing margin pools in Egypt's Delta region injection molding sector.
Industry Challenges
- Compounding technician scarcity:Formulation expertise for high-temperature PA 66 grades and color-matched automotive specifications is concentrated among a limited workforce pool in South Africa and Morocco.
- Extended producer responsibility compliance:Multinational automotive and electronics brands are imposing circularity clauses that African compounders lack infrastructure to satisfy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Polyamide Market |
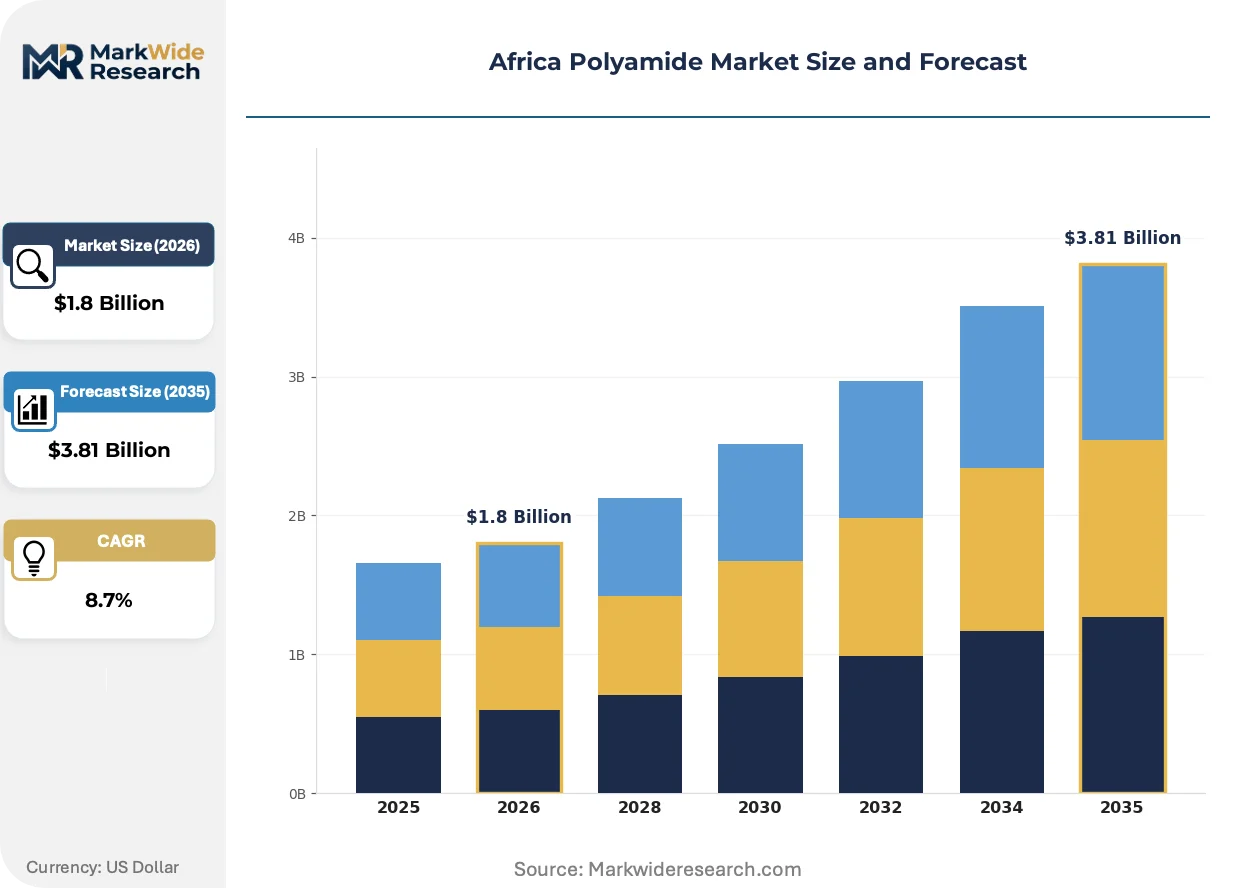
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA 6, PA 66, PA 11, PA 12 Use Case: Textiles, Automotive Components, Electrical Insulation, Packaging Form: Fibers, Granules, Films, Sheets End User: Consumer Goods, Automotive OEMs, Electronics, Industrial Machinery |
| Companies Covered | BASF SE, Arkema S.A., Celanese Corporation, EMS-Chemie Holding AG, LANXESS, Evonik Industries AG, DuPont, DSM, Koch Industries, Inc., Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Polyamide Market Trends and Innovations
Polyamide processing technology and regulatory transparency requirements are converging to reshape competitive positioning across North and Southern African manufacturing corridors, with sustainability specifications now filtering procurement decisions at the compounder level.
Bio-based polyamide feedstocks derived from castor oil are converging with automotive OEM carbon neutrality roadmaps, accelerating adoption in under-the-hood components where heat resistance thresholds previously favored fossil-derived grades. European export market access is compressing formulation disclosure requirements, forcing compounders to document monomer sourcing and additive packages. Moroccan and South African automotive suppliers are prioritizing PA 11 and PA 1010 grades for hose and connector applications.
REACH-equivalent chemical registration pressures from European export markets are tightening formulation transparency mandates for African compounders seeking EU-bound component supply chains. The Egyptian Organization for Standardization and Quality is aligning import conformity protocols with emerging substance restriction lists. Textile and automotive segments in Egypt and Morocco are restructuring supplier qualification processes to preempt regulatory friction.
Buyer concentration among multinational automotive and electronics brands is compressing switching flexibility for African compounders, locking technical service relationships and volume commitments. Long-term supply agreements with embedded R&D collaboration are displacing spot resin purchasing in Morocco's automotive parts ecosystem. Tier 1 suppliers in Tangier and Casablanca are consolidating vendor panels around three to four approved compounders per polymer family.
Africa Polyamide Market Segmentation
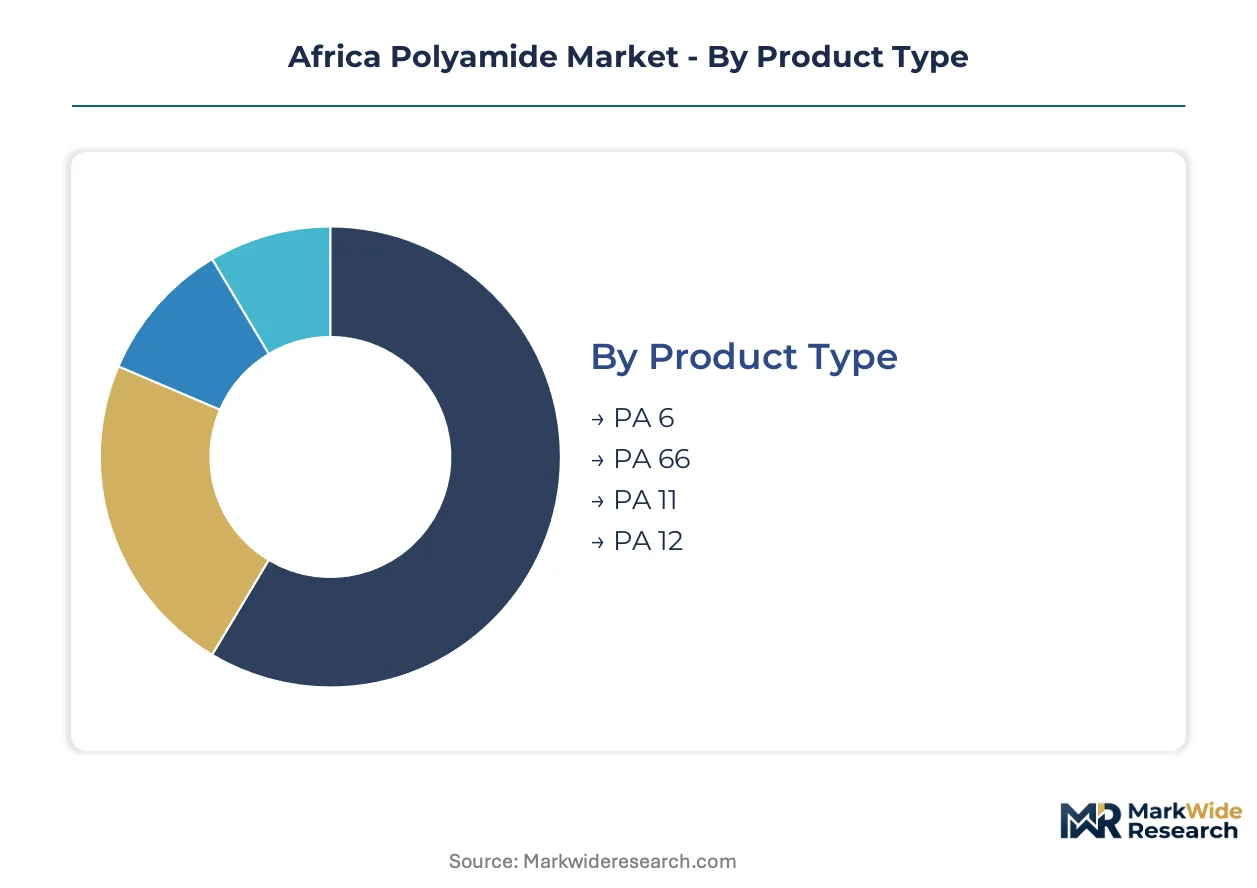
Polyamide segmentation across Africa reveals distinct integration patterns where commodity grades flow into standalone textile and packaging applications while engineering grades embed deeply into automotive and electrical systems requiring technical service attachments.
Product Type:
Standalone polymer grades serve discrete processing channels, whereas specialty variants integrate into compounder formulations with additive packages tailored to end-use thermal and mechanical requirements.
- PA 6:This aliphatic polyamide polymerizes from caprolactam monomer with melting points near 220°C, offering cost-position advantages and broad processing latitude. Egyptian textile manufacturers in the Nile Delta corridor consume film-grade and fiber-grade PA 6 for export-oriented apparel supply chains, though caprolactam import dependency exposes margin structures to freight volatility.
- PA 66:Synthesized from adipic acid and hexamethylenediamine, PA 66 delivers superior heat resistance with melting points reaching 265°C, enabling under-the-hood automotive deployment. Moroccan and South African automotive OEMs specify glass-reinforced PA 66 compounds for engine bay components where thermal management thresholds exceed PA 6 capabilities.
- PA 11:Castor oil-derived bio-based polyamide penetrates sustainability-mandated procurement from multinational automotive brands operating assembly in North Africa.
- PA 12:Long-chain aliphatic variant commands niche positioning in flexible tubing and pneumatic applications across industrial machinery segments.
PA 6 leads volumes today; PA 11 is gaining share fastest.
Use Case:
Application segmentation tracks cost tier stratification, with commodity textile and packaging flows competing on price while automotive and electrical segments extract premium positioning through specification engineering.
- Textiles:PA 6 fiber extrusion dominates Egypt's manufacturing corridor, serving fast-fashion and industrial yarn export markets with cost-competitive positioning against Asian suppliers.
- Automotive Components:Thermal management grades with glass fiber reinforcement displace metal in engine bays as Moroccan and South African OEMs pursue weight reduction targets tied to fuel efficiency mandates.
- Electrical Insulation:PA 66 compounds satisfy dielectric strength requirements for connector housings and cable management systems in electronics manufacturing clusters.
- Packaging:Film-grade PA 6 enables barrier properties in flexible food packaging for Nigerian and Kenyan consumer goods processors.
Textiles anchor volume baselines; automotive components exhibit steepest expansion trajectory.
Form:
Physical form factors determine supply chain configuration, with bulk granule shipments feeding compounder networks while specialty fibers and films demand direct technical sales relationships.
- Fibers:Continuous filament and staple fiber formats serve Egyptian textile mills and Moroccan carpet manufacturing, requiring melt-spinning equipment compatibility and dye-ability specifications.
- Granules:Pelletized resin constitutes the dominant industrial offtake channel, feeding injection molding and extrusion compounders across South Africa's Automotive Production and Development Programme beneficiary facilities.
- Films:Biaxially oriented and cast film structures address barrier packaging requirements in Nigeria's emerging consumer goods conversion zones.
- Sheets:Extruded plate and slab formats serve industrial machinery wear components and electrical insulation barriers in limited specialty applications.
Granules command the largest shipment volumes; fibers maintain the most entrenched supplier relationships.
End User:
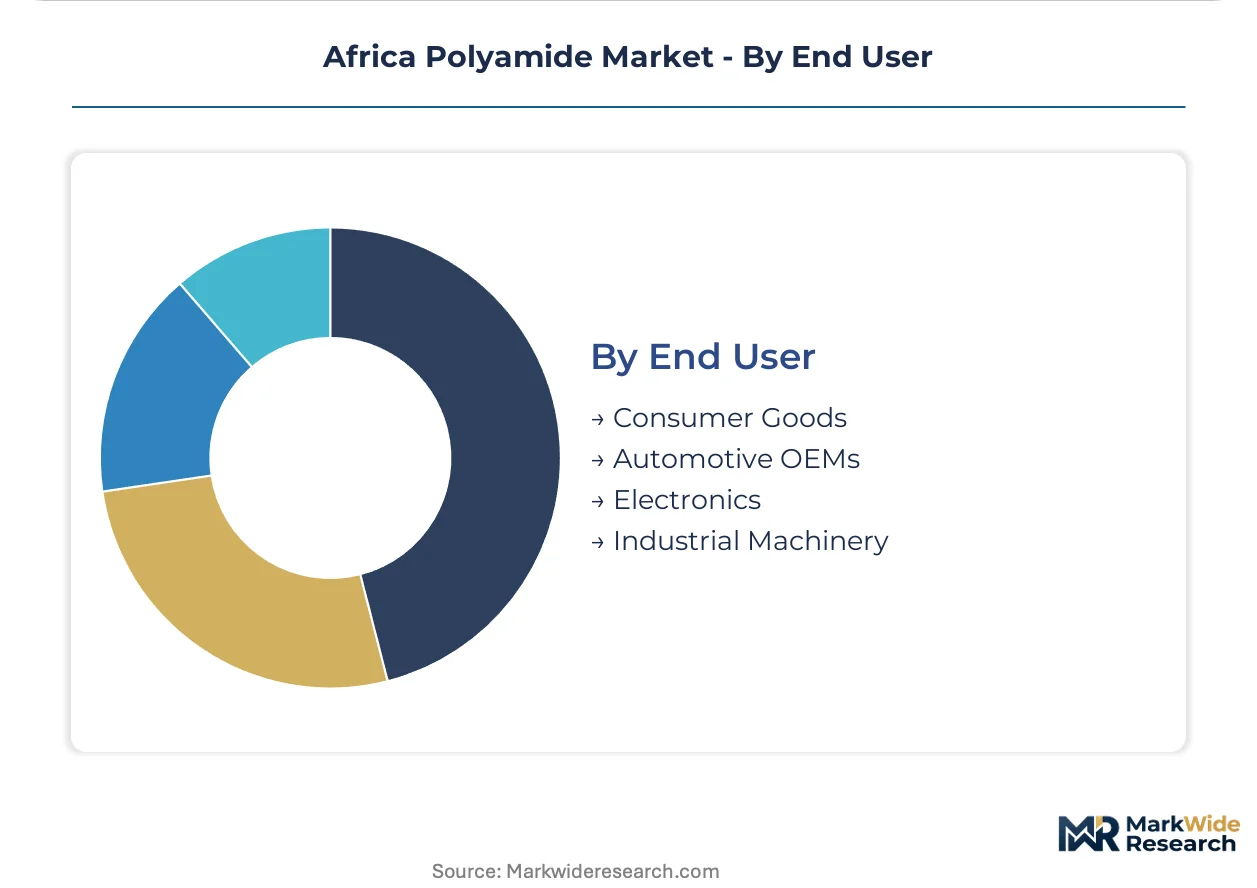
Customer type segmentation concentrates procurement influence, with multinational automotive and electronics brands imposing formulation transparency requirements that cascade through Tier 1 supplier tiers.
- Consumer Goods:Nigerian and Kenyan packaging converters and appliance manufacturers drive commodity-grade PA 6 consumption in household durables and flexible packaging applications.
- Automotive OEMs:Integrated vehicle manufacturers in Morocco's Tangier-Casablanca corridor and South Africa's Eastern Cape specify REACH-equivalent compound grades with embedded carbon footprint documentation.
- Electronics:Connector and cable assembly producers in Egypt's industrial zones source flame-retardant PA 66 grades for electrical insulation meeting European export market access requirements.
- Industrial Machinery:Mining equipment and agricultural machinery fabricators across Southern Africa consume wear-resistant PA 6 and PA 66 formulations for gears, bearings, and structural components.
Automotive OEMs concentrate purchasing power; electronics segments are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production migration toward North and Southern Africa accelerates as European REACH-equivalent compliance costs widen the arbitrage gap for compounders serving export-oriented automotive and textile supply chains.
South Africa
The Automotive Production and Development Programme incentivizes local polyamide compounding for under-the-hood components. The National Regulator for Compulsory Specifications enforces polymer quality benchmarks that filter substandard resin imports. The Eastern Cape automotive cluster around Gqeberha anchors glass-reinforced PA 66 consumption for engine bay thermal management.
Egypt
Film-grade and fiber-grade PA 6 demand concentrates in Nile Delta textile mills serving European fast-fashion supply chains. The Egyptian Organization for Standardization and Quality administers import conformity protocols that restrict non-compliant resin shipments. The 10th of Ramadan industrial city hosts extrusion compounders supplying flexible packaging converters.
Morocco
Tangier-Casablanca automotive OEMs specify REACH-equivalent PA 66 compounds with embedded carbon footprint documentation for EU-bound component exports. The country's investment promotion agency channels industrial zone development toward polymer conversion capacity. The Kenitra Atlantic Free Zone attracts Tier 1 suppliers consolidating vendor panels around approved compounders.
Nigeria
Emerging consumer goods manufacturing in Lagos and Port Harcourt drives commodity-grade PA 6 consumption for packaging and household durables. The country's national standards body implements polymer import inspection regimes that elevate formulation transparency requirements. The Lekki Free Trade Zone hosts mid-tier injection molders bypassing traditional distributor layers through direct technical sales relationships.
Kenya
Flexible food packaging processors in Nairobi's industrial estates source film-grade PA 6 for barrier property applications. The Kenya Bureau of Standards enforces plastics quality regulations that align with East African Community harmonized standards. The Athi River EPZ concentrates polymer conversion activity serving regional consumer goods distribution networks.
Africa Polyamide Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bio-based feedstock differentiation and direct distribution models. The vendor base concentrates around integrated petrochemical groups with captive caprolactam supply and specialized engineering compounders with technical service attachments. Three archetypes dominate: integrated resin producers controlling upstream monomer supply, independent compounders tailoring additive packages to automotive specifications, and regional distributors pivoting toward technical sales capabilities. Capacity expansion and strategic partnerships constitute the dominant competitive moves as firms secure volume commitments with long-term supply agreements.
Among European-integrated producers, BASF SE and LANXESS exemplify the upstream-controlled archetype with integrated caprolactam networks securing North African textile volume commitments. DSM represents the sustainability-differentiated tier through bio-based polyamide pathways addressing automotive OEM carbon neutrality specifications. These three anchors illustrate how formulation transparency mandates and REACH-equivalent compliance requirements are compressing spot-market trading in favor of technical service-embedded relationships.
| Leading Market Players |
|---|
| BASF SE |
| Arkema S.A. |
| Celanese Corporation |
| EMS-Chemie Holding AG |
| LANXESS |
| Evonik Industries AG |
| DuPont |
| DSM |
| Koch Industries, Inc. |
| Others |
Pricing and Supply Chain Analysis
Caprolactam import costs from European and Middle Eastern feedstock channels cascade through African polyamide pricing tiers, with freight rate volatility compressing margins for Egyptian textile compounders while Moroccan automotive suppliers absorb premium-grade PA 66 markups through long-term technical service contracts.
Pricing Analysis
Input-cost pass-through from adiponitrile and caprolactam monomers dominates pricing structures across African compounders. Three-tier pricing separates REACH-equivalent automotive grades from standard industrial PA 6 and commodity textile resins. Cost compression in film-grade PA 6 is intensifying because Egyptian packaging converters face Asian import competition. Textile processors exhibit highest price sensitivity; automotive OEMs prioritize formulation transparency over unit cost.
Supply Chain Analysis
Freight costs from Rotterdam, Antwerp, and Jeddah anchor landed resin pricing for North African compounders serving Tangier-Casablanca automotive corridors and Nile Delta textile mills. Supply draws from Belgium, Germany, and Saudi Arabia for caprolactam; adiponitrile hinges on US and European integrated producers. Single-source vulnerability in PA 66 precursor channels constrains grade availability during supply shocks. Distribution runs through integrated compounders with technical service attachments rather than spot-market traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
African polyamide markets function as stable compounders where automotive OEM consolidation around approved vendor panels generates predictable volume commitments and technical service revenue streams.
For Market Incumbents: Acquire captive compounding capacity in Morocco's Kenitra Atlantic Free Zone and South Africa's Eastern Cape to defend against emerging bio-based entrants. Anchor customer relationships through embedded R&D collaboration on thermal management grades. Certify formulations to REACH-equivalent standards before Egyptian and Moroccan regulatory alignment tightens. For New Entrants and Emerging Players: The premium-economy price gap in Nigerian consumer goods packaging opens white-space positioning for mid-tier PA 6 compounders bypassing traditional distributor layers. Target Lagos and Port Harcourt injection molding clusters with direct technical sales teams. Differentiate through castor oil-derived PA 11 grades for sustainability-mandated automotive procurement. For Investors and Strategic Acquirers: Consolidation pressure builds where formulation transparency mandates and REACH-equivalent compliance costs outstrip mid-tier compounder capabilities. Long-term viability favors integrated producers with captive monomer supply or specialized engineering compounders with automotive technical service relationships. Monitor bio-based polyamide adoption rates in Moroccan and South African OEM specifications as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | BASF SE's integrated network secures volume commitments from Egyptian textile producers against freight volatility. |
| Bio-Based Feedstock Transition | DSM's castor oil-derived pathways address carbon footprint specifications from automotive OEMs in Tangier. |
| Long-Term Supply Agreement | LANXESS anchors Moroccan Tier 1 relationships through embedded R&D on glass-reinforced PA 66 grades. |
| Direct Distribution Model | Technical sales teams capture margin pools in Egypt's Delta region by bypassing traditional resin distributors. |
| Regulatory Certification Investment | REACH-equivalent formulation documentation unlocks EU-bound component supply chains for North African compounders. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer plant managers, automotive Tier 1 procurement leads, textile mill technical directors, and distribution channel partners with secondary validation through customs and trade data, European Chemical Industry Council reports, SEC 10-K filings, and vehicle production databases. Bottom-up resin consumption estimates and top-down automotive content-per-vehicle analysis were triangulated to anchor volume figures.
Comparable-period anchoring linked historical automotive production and textile export data to forward projections across the analysis window. Segmentation dimensions modeled included polymer grade tier, end-use industry vertical, physical form factor, and regional production hub. CAGRs were derived from trend extrapolation of OEM procurement patterns and compounder capacity utilization. Forecast inputs incorporated REACH-equivalent compliance cost trajectories and bio-based polyamide adoption curves.
The model assumes a particular technology adoption path; alternative pathways for castor oil-derived bio-polyamides would alter the outlook if automotive OEM carbon neutrality roadmaps accelerate or stall. Forecasts reflect assumptions about regulatory alignment timing and feedstock channel stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Resin Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Epoxy Resin Reactive Diluent Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
N-Vinylformamide Market
Polymers & Resins
Polycide Market
Polymers & Resins
Vinyl Acetate Ethylene (VAE) Market
Polymers & Resins
Scleroglucan Market
Polymers & Resins
Polar Polymers Market
Polymers & Resins
Polymer Antioxidants Market
Polymers & Resins
France Engineering Plastics Market
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
Global Polyamide Market
Polymers & Resins
Low Density Polyethylene Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
TPEE in Automotive Industry Market