
 North America Plastic Compounding Market | 2026-2036
North America Plastic Compounding Market Size, Share, and Industry Trends Forecast 2026-2036
North America Plastic Compounding Market Outlook
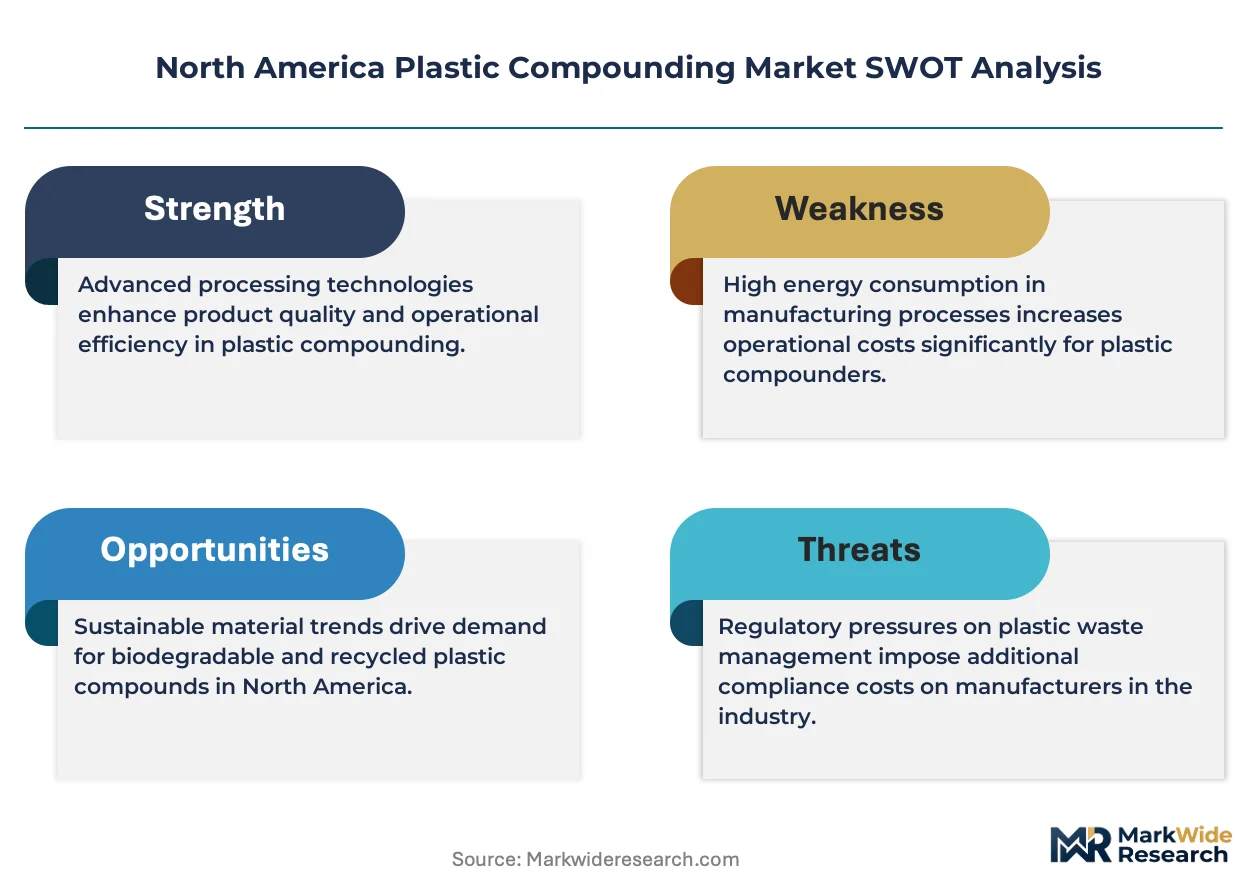
Automotive demand is shifting toward lighter-weight under-hood components and structural interior parts, pulling compounded resins with higher mineral and fiber loadings. Dow, Inc. leverages its Midland, Michigan polymer science campus to sustain development of impact-modified polypropylene grades for tier-one suppliers. LyondellBasell Industries Holdings B.V. anchors its compounding network around Houston-channel polyethylene supply, controlling feedstock cost volatility through backward integration into steam-cracker operations.
Plastic compounding denotes the melt-blending of base polymers with additives, fillers, reinforcements, and colorants to achieve defined mechanical, thermal, or aesthetic specifications; typical outputs include glass-fiber-reinforced polypropylene with tensile strengths exceeding 80 MPa for metal replacement in automotive assemblies. Polypropylene compounds dominate volume throughput across the region, reflecting the resin's balance of cost and performance in injection-molded parts. High-performance grades command disproportionate margin pools, particularly in medical device housings and electrical connectors where flammability and dimensional stability requirements exceed standard specifications.
The EPA enforces emissions and chemical safety standards that constrain phthalate plasticizer use in flexible PVC compounding, while NHTSA fuel-economy rules indirectly amplify demand for lighter compounded materials in vehicle platforms. State-level extended producer responsibility frameworks in California and Maine are beginning to mandate minimum recycled content thresholds, forcing compounders to qualify post-consumer feedstocks without sacrificing lot-to-lot consistency. Stakeholders must monitor how rapidly these state mandates proliferate and whether mechanical recycling infrastructure can scale to meet quality specifications for engineering-grade applications.
Market Dynamics
Automotive lightweighting mandates and EPA restrictions on virgin plastics are forcing compounders to reconfigure feedstock sourcing and formulation chemistry simultaneously. The tension between performance specifications and recycled-content quotas is restructuring supplier relationships across the value chain.
Growth Catalysts
- NHTSA Fuel-Economy Standards:Corporate Average Fuel Economy rules compel automakers to substitute glass-filled polypropylene for metal in under-hood components. Tier-one suppliers now specify compounded resins with tensile properties exceeding 80 MPa.
- State Extended Producer Responsibility:California and Maine mandate minimum post-consumer recycled thresholds in packaging applications. Compounders must qualify mechanically recycled feedstocks for injection-molding grades without lot-to-lot variation.
- Gulf Coast Petrochemical Integration:Steam-cracker proximity in Texas and Louisiana provides captive ethylene and propylene supply. Backward integration into resin production insulates compounders from feedstock price volatility.
Market Restraints
- Propylene Monomer Volatility:Steam-cracker feedstock shifts between ethane and naphtha create unpredictable propylene supply. Gulf Coast compounders face margin compression when cracker operators prioritize ethylene output.
- Mechanical Recycling Quality Ceiling:Post-consumer polypropylene exhibits property degradation and contamination inconsistent with medical device or electrical connector specifications. Engineering-grade applications remain dependent on virgin resin.
- Phthalate Restrictions in Flexible PVC:EPA emissions and chemical safety standards constrain plasticizer selection. Compounders serving wire-and-cable and flooring markets face reformulation costs and performance trade-offs.
Strategic Opportunities
- Chemical Recycling Scale-Up:Pyrolysis and depolymerization technologies promise food-contact-grade recycled polypropylene. Early movers in Texas and Ohio are securing offtake agreements with brand owners facing California recycled-content mandates.
- Medical Device Housing Specialization:Flammability and dimensional stability requirements exceed standard specifications. Compounders with USP Class VI and ISO 10993 certification command disproportionate margin pools in diagnostic equipment and surgical instruments.
- Midwest Automotive Cluster Proximity:Michigan and Ohio assembly plants require just-in-time compounded resin delivery. Regional compounders can displace Gulf Coast suppliers through logistics advantages and co-development relationships with Detroit-area molders.
Industry Challenges
- Color-Matching Consistency with Recycled Feedstock:Post-consumer resin exhibits batch-to-batch color variation that complicates brand-owner specifications. Compounders must invest in spectrophotometric sorting and additive dosing systems to meet automotive and consumer goods aesthetic requirements.
- Compounding Technician Shortage:Twin-screw extrusion operation and polymer rheology expertise are aging out of the workforce. Technical colleges in Texas and Louisiana have not scaled polymer processing programs to replacement rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Plastic Compounding Market |
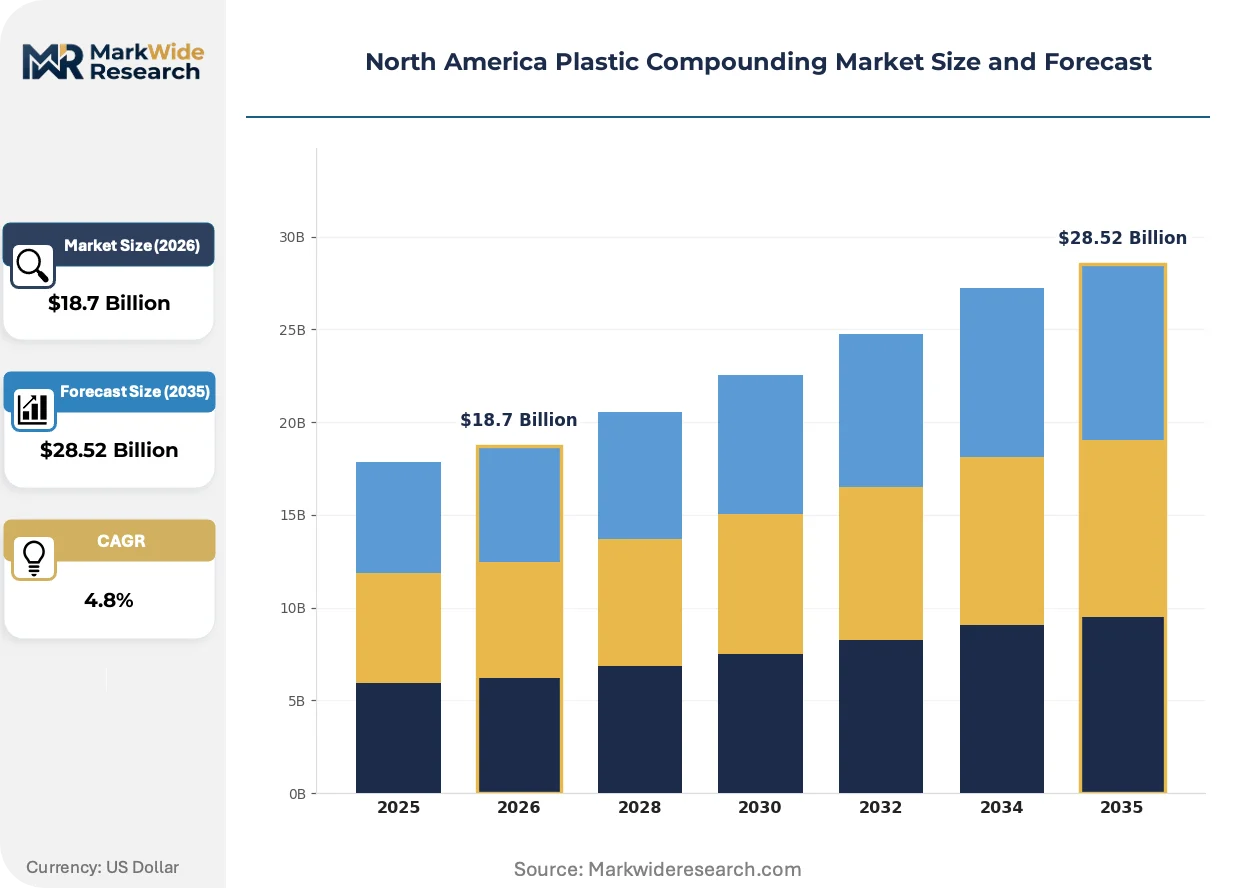
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polyethylene, Polyvinyl Chloride, Polystyrene End Use Industry: Automotive, Consumer Goods, Packaging, Construction Grade: High-Performance, Engineering, Standard, Specialty Technology: Extrusion, Injection Molding, Blow Molding, Compounding |
| Companies Covered | BASF SE, LyondellBasell Industries Holdings B.V., Dow, Inc., DuPont de Nemours, Inc., SABIC, RTP Company, Asahi Kasei Corporation, Covestro AG, Avient Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Plastic Compounding Market Strategic Shifts
Digital formulation tools and advanced recycling infrastructure are compressing product development cycles while expanding the addressable feedstock pool. These capabilities are redrawing competitive boundaries between integrated resin producers and independent compounders.
Reactive extrusion technology is modularizing compounding operations by enabling in-situ polymerization and grafting within the same processing step. Automotive suppliers in Michigan and Ohio are adopting these systems to customize impact-modified polypropylene properties without inventorying multiple base grades. The technology is compressing minimum order quantities and shortening qualification timelines for platform-specific formulations.
EPA enforcement of chemical safety standards under the Toxic Substances Control Act is tightening phthalate and heavy-metal restrictions in flexible PVC compounding. Wire-and-cable manufacturers face reformulation mandates that degrade processing windows and finished-product flexibility. The electrical infrastructure segment is responding by accelerating bio-based plasticizer qualification and migrating certain applications to thermoplastic elastomer alternatives.
Automotive procurement departments are consolidating approved supplier lists and demanding full material disclosure for sustainability scorecarding. Tier-one seating and interior suppliers now require compounders to provide mass-balance certificates and recycled-content attestations. This behavioral shift is most visible in Michigan and Ontario, where Detroit Three purchasing organizations have embedded circularity metrics into source-selection criteria.
North America Plastic Compounding Market Segmentation
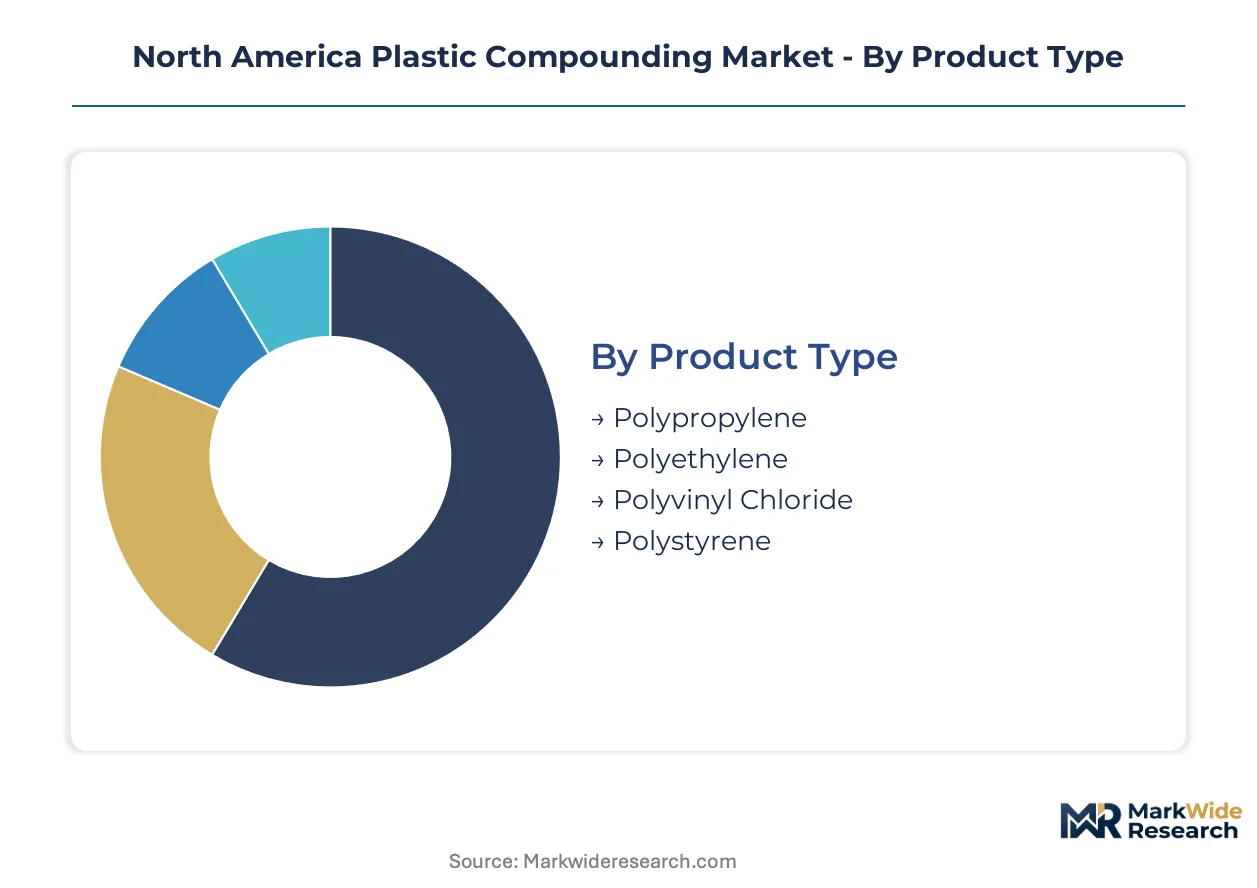
Segmentation in plastic compounding reflects how resin producers and independent compounders allocate capital across divergent technical requirements and margin profiles. Each category captures distinct supply chain configurations, from captive Gulf Coast polypropylene operations to specialized medical-grade compounders serving FDA-regulated device markets.
Product Type:
Supply concentration along the Texas-Louisiana petrochemical corridor dictates competitive positioning across polymer families, with steam-cracker proximity determining feedstock cost structures.
- Polypropylene:Glass-filled and impact-modified grades dominate automotive under-hood and interior applications, with tensile specifications exceeding 80 MPa now standard for metal replacement programs. Michigan and Ohio assembly plants pull material through just-in-time logistics networks from both Gulf Coast integrated producers and regional compounders.
- Polyethylene:HDPE and LDPE compounds serve blow-molded packaging and construction geomembranes, with demand concentrating in California where state recycled-content mandates force qualification of post-consumer feedstocks. Houston-channel supply integration insulates large compounders from ethylene monomer volatility.
- Polyvinyl Chloride:Flexible and rigid formulations face EPA phthalate restrictions in wire-and-cable and flooring segments, requiring bio-based plasticizer migration or thermoplastic elastomer substitution in electrical infrastructure.
- Polystyrene:High-impact and expandable grades retain packaging and insulation applications despite lightweighting pressures, with Maine extended producer responsibility frameworks beginning to constrain virgin resin specifications.
Polypropylene absorbs the bulk of installed capacity; high-performance polyethylene compounds are expanding most quickly under California packaging mandates.
End Use Industry:
Customer procurement consolidation and sustainability scorecarding are restructuring how compounders qualify for approved supplier lists across end-use segments.
- Automotive:NHTSA fuel-economy rules compel tier-one suppliers to specify mineral and fiber-loaded compounds for structural interior and under-hood components. Detroit Three purchasing organizations embed circularity metrics and mass-balance certificates into source-selection criteria.
- Consumer Goods:Brand owners facing Maine and California recycled-content thresholds demand lot-to-lot consistency from mechanically recycled feedstocks. Color-matching specifications complicate post-consumer resin deployment in aesthetic applications.
- Packaging:Food-contact safety requirements and state extended producer responsibility laws create dual pressure for chemical recycling scale-up. Pyrolysis-derived polypropylene promises compliance with California mandates.
- Construction:Pipe, siding, and geomembrane applications favor rigid PVC and HDPE compounds with weathering stability specifications. Building code adoption varies across Texas, Florida, and California jurisdictions.
Automotive commands the deepest technical qualification barriers; packaging is gaining share fastest under proliferating state recycling mandates.
Grade:
Margin stratification across performance tiers reflects certification requirements and formulation complexity rather than volume throughput.
- High-Performance:USP Class VI and ISO 10993 certification for medical device housings and diagnostic equipment creates defensible margin pools. Flammability and dimensional stability specifications exceed standard injection-molding grades.
- Engineering:PA, PBT, and PC compounds serve electrical connectors and industrial components where heat resistance and electrical properties command premium pricing over commodity alternatives.
- Standard:Unfilled and lightly modified polypropylene and polyethylene grades compete on logistics cost and minimum order quantity flexibility in high-volume automotive and packaging applications.
- Specialty:Conductive, laser-markable, and metal-replacement formulations address niche aerospace and electronics segments with formulation confidentiality requirements.
Standard grades move the highest tonnage; high-performance medical certification is climbing the fastest as device manufacturing reshoring accelerates.
Technology:
Equipment sophistication and process control capabilities determine which compounders can serve multi-cavity automotive tooling versus single-cavity medical device molds.
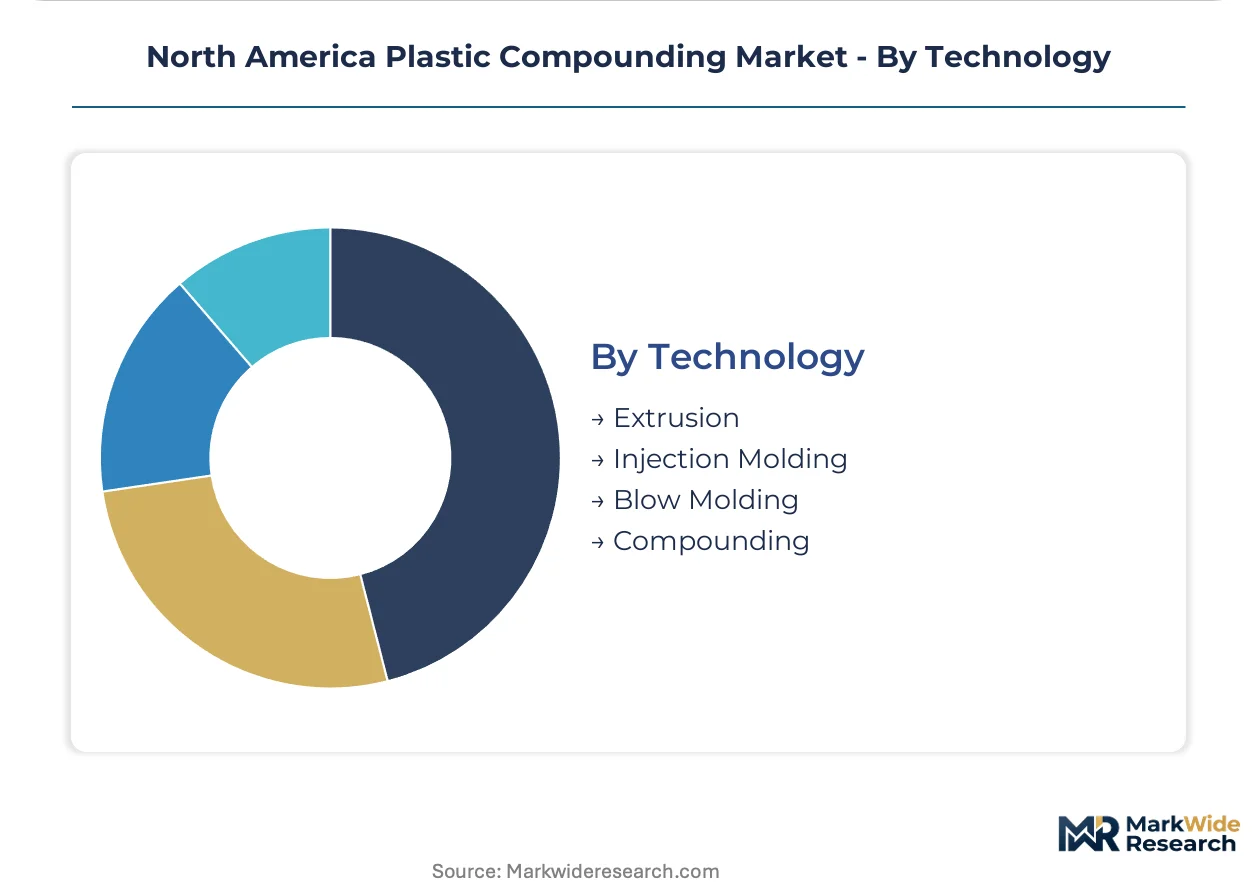
- Extrusion:Twin-screw compounding lines enable precise filler dispersion and reactive grafting for impact-modified polypropylene. Technician shortages in Texas and Louisiana constrain capacity expansion.
- Injection Molding:Direct-feed compounded resin systems compress automotive qualification timelines by eliminating pellet inventory. Michigan and Ohio molders adopt these configurations for platform-specific formulations.
- Blow Molding:HDPE and PET compounds for packaging and fuel tanks require melt-strength optimization and parison programming expertise.
- Compounding:Standalone toll compounding services serve brand owners with captive resin supply but lacking extrusion infrastructure, particularly for color-matching and additive masterbatch production.
Extrusion underpins the majority of captive capacity; injection molding direct-feed configurations are expanding most quickly among tier-one automotive suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast petrochemical corridor anchors North American plastic compounding capacity, with Texas and Louisiana offering property tax abatements and infrastructure credits that concentrate resin production and captive compounding operations.
United States
Automotive lightweighting programs in Michigan and Ohio pull glass-filled polypropylene compounds with tensile specifications exceeding 80 MPa for under-hood metal replacement. NHTSA Corporate Average Fuel Economy rules indirectly amplify demand through tier-one supplier procurement consolidation. The Detroit Three purchasing organizations embed circularity metrics and mass-balance certificates into source-selection criteria for seating and interior components.
Canada
Ontario's automotive assembly plants near Windsor and Oshawa require just-in-time compounded resin delivery for platform-specific formulations. Health Canada regulations on food-contact materials constrain recycled-content deployment in packaging applications. Regional compounders in the Quebec-Ontario corridor leverage logistics proximity to displace US Gulf Coast suppliers for certain automotive grades.
Mexico
Nuevo León and the Bajío Region host expanding automotive manufacturing clusters that consume impact-modified polypropylene for interior and structural parts. Mexico's federal environmental authority enforces emissions standards that align with EPA frameworks for phthalate restrictions in flexible applications. Querétaro-based molders are qualifying regional compounders to reduce cross-border logistics exposure.
California
State extended producer responsibility mandates impose minimum post-consumer recycled thresholds in packaging applications that force compounders to qualify mechanically recycled feedstocks. The California Air Resources Board oversees emissions compliance that affects compounding facility siting decisions. Los Angeles and Central Valley packaging converters are securing pyrolysis-derived polypropylene offtake agreements to meet food-contact safety requirements.
Texas
The Houston Ship Channel and Beaumont-Port Arthur corridor host integrated steam-cracker operations that supply captive ethylene and propylene to compounders. Texas Commission on Environmental Quality permitting frameworks govern emissions from twin-screw extrusion facilities. Corpus Christi and Lake Charles area compounders benefit from backward integration into resin production that insulates margins from monomer price volatility.
North America Plastic Compounding Market Competitive Environment
Top-tier vendors anchor integrated resin-to-compound operations, while mid-scale independents specialize in color-matching and additive masterbatch services. The market structure reflects concentration among Gulf Coast petrochemical producers with captive compounding networks, alongside regional specialists serving automotive and medical device clusters. Three archetypes dominate: backward-integrated resin producers controlling feedstock costs, toll compounders offering formulation flexibility, and certified medical-grade specialists commanding premium positioning. Competitive moves center on chemical recycling partnerships to secure California-compliant recycled feedstocks, and reactive extrusion technology licensing to compress automotive qualification timelines.
Within the integrated-producer tier, BASF SE and LyondellBasell Industries Holdings B.V. exemplify archetypes combining resin production with captive compounding capacity. Dow, Inc. occupies a position emphasizing polymer science campus capabilities for impact-modified grade development. These entities represent the dominant competitive vector through Gulf Coast petrochemical integration and direct supply relationships with tier-one automotive suppliers.
| Leading Market Players |
|---|
| BASF SE |
| LyondellBasell Industries Holdings B.V. |
| Dow, Inc. |
| DuPont de Nemours, Inc. |
| SABIC |
| RTP Company |
| Asahi Kasei Corporation |
| Covestro AG |
| Avient Corporation |
| Others |
Value Chain & Pricing Dynamics
Backward-integrated Gulf Coast resin producers with captive steam-cracker access command pricing discipline through feedstock cost insulation, while independent compounders face margin compression when propylene monomer volatility spikes. This ownership pattern concentrates supply-side power along the Texas-Louisiana corridor and amplifies price differentiation between integrated and non-integrated competitors.
Pricing Analysis
Short lead-time premiums distinguish automotive just-in-time contracts from standard-volume packaging agreements in this market. Pricing stratifies across medical-grade certification tiers, USP Class VI compounds commanding substantial premiums over standard injection-molding grades. Cost compression in commodity polypropylene intensifies because Gulf Coast cracker operators prioritize ethylene output during feedstock shifts. Tier-one automotive suppliers demonstrate lowest price sensitivity due to qualification barriers, while packaging converters in California exhibit highest sensitivity under recycled-content mandate compliance costs.
Supply Chain Analysis
Single-source vulnerability sits with propylene monomer supply concentrated in Texas and Louisiana steam-cracker operations. Raw material dependencies encompass ethane and naphtha feedstocks, phthalate plasticizers for flexible PVC, and glass fiber reinforcements sourced domestically. Tariff exposure on specialty additives from Asian suppliers creates intermittent supply risk for conductive and laser-markable compounds. Distribution runs through direct mill-to-molder pipelines for automotive clusters, with packaging segments relying on regional distributor networks for smaller lot sizes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with twin-screw extrusion technician shortages in Texas and Louisiana capping capacity expansion and propping pricing for qualified compounders.
For Market Incumbents: Cement Gulf Coast resin integration through captive steam-cracker offtake agreements to defend against propylene monomer volatility. Expand USP Class VI certification coverage to capture medical device reshoring demand. Prioritize reactive extrusion technology licensing to compress automotive qualification timelines before tier-one supplier consolidation hardens.
For New Entrants and Emerging Players: Midwest automotive molders represent the most penetrable channel partner type for displacing Gulf Coast suppliers through logistics proximity. Target Michigan and Ohio assembly plant corridors with just-in-time delivery capabilities. Qualify post-consumer recycled feedstocks for California packaging mandates as the fastest route to volume offtake.
For Investors and Strategic Acquirers: California recycled-content mandate enforcement acceleration is the leading indicator that chemical recycling infrastructure will command scarcity premiums. Frame long-term viability around pyrolysis and depolymerization scale-up within a five-to-ten year window. Pursue acquisition targets with existing automotive qualification relationships and toll-compounding flexibility. Monitor NHTSA fuel-economy standard tightening as the signal for glass-filled polypropylene demand inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Scale-Up | Pyrolysis-derived polypropylene secures California Air Resources Board compliance for food-contact packaging mandates. |
| Reactive Extrusion Licensing | In-situ polymerization capability compresses qualification timelines with Detroit Three purchasing organizations. |
| Medical Grade Certification Investment | USP Class VI and ISO 10993 credentials unlock diagnostic equipment and surgical instrument margin pools. |
| Midwest Logistics Hub Establishment | Regional compounding proximity to Michigan and Ohio assembly plants displaces Gulf Coast suppliers on delivery speed. |
| Post-Consumer Feedstock Qualification | Mechanical recycling consistency meets Maine and California extended producer responsibility thresholds. |
Study Parameters
Document review covered American Chemistry Council production data, EPA enforcement records, and SEC filings from integrated resin producers, complemented by interviews with twin-screw extrusion plant managers, tier-one automotive supplier procurement leads, and California packaging converter technical directors. Secondary validation drew from NHTSA fuel-economy rulemaking dockets, state extended producer responsibility legislative text, and customs trade data on specialty additive imports. Bottom-up capacity modeling and top-down demand segmentation were triangulated against primary field intelligence.
Historical volume trajectories were cross-referenced against expert panel input on recycled-content mandate proliferation and automotive lightweighting program acceleration. The analytical framework segmented across product type, end-use industry, performance grade, and processing technology dimensions throughout the forecast period. CAGRs were derived from elasticity modeling against resin price scenarios and regulatory compliance cost curves, with specific inputs including steam-cracker feedstock shift patterns and medical device manufacturing reshoring indices.
Caveats apply where EPA phthalate restriction enforcement intensity or NHTSA rulemaking timeline acceleration could materially shift the outlook for flexible PVC and automotive demand segments respectively. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyether Block Amide Market
Polymers & Resins
Synthetic Latex Polymers Market
Polymers & Resins
Synthetic and Bio-Based PMMA (Polymethyl Methacrylate) Market
Polymers & Resins
Global One Component Polyurethane Foam Market
Polymers & Resins
Global High Temperature Resin Market
Polymers & Resins
Global Thermally Conductive Plastics Market
Polymers & Resins
Polymer Plastic Plain Bearings Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
North America Polypropylene Copolymer Market
Polymers & Resins
Bio-Based Polycarbonate Market
Polymers & Resins
Seed Polymers Market
Polymers & Resins
Hybrid Polymer Market
Polymers & Resins
Liquid Polybutadiene [LPBD] Market
Polymers & Resins
Global Polyamide 6 Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Asia-Pacific Geopolymer Market