
 Polycarbonate Glazing Market | 2026-2036
Polycarbonate Glazing Market Size, Share, and Industry Trends Forecast 2026-2036
Polycarbonate Glazing Market Outlook
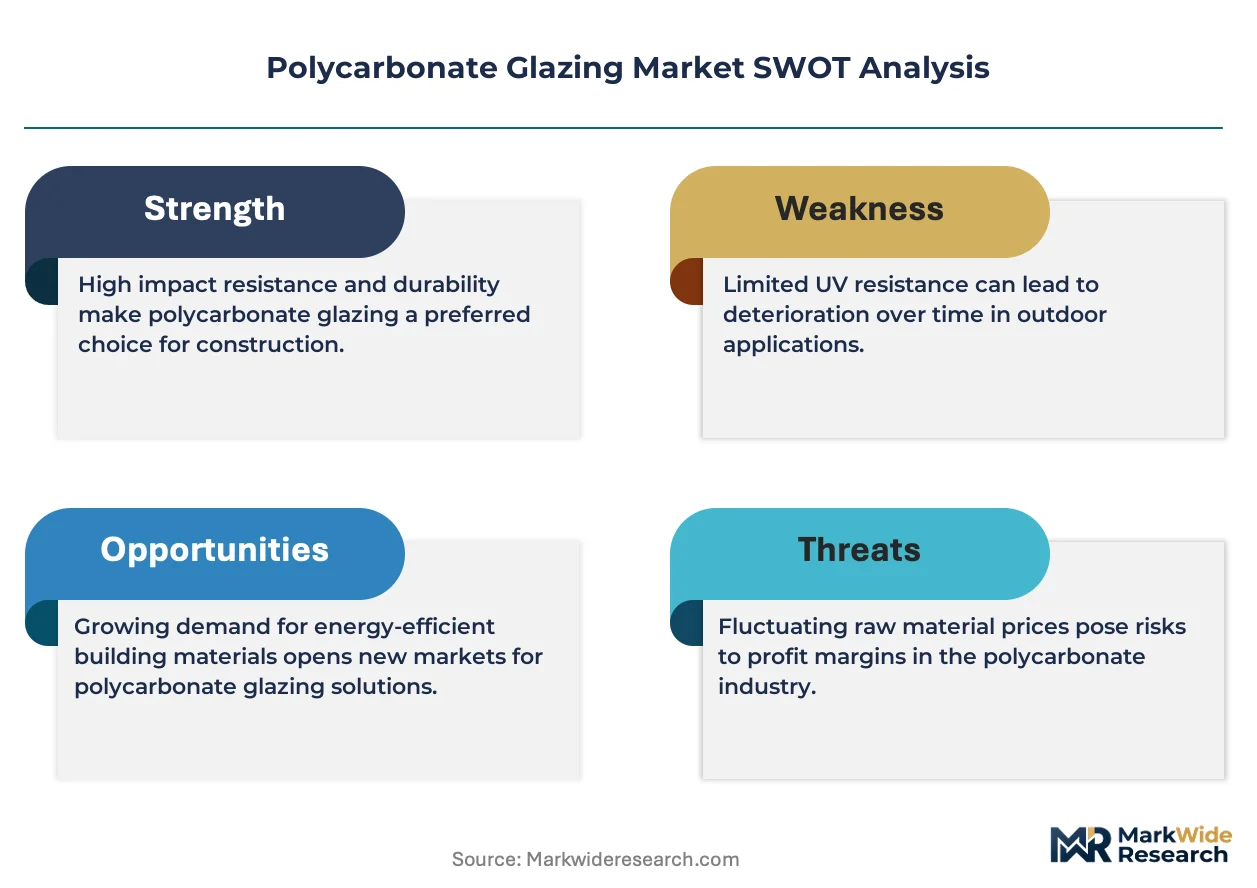
Architectural specification channels is reshaping how polycarbonate glazing reaches commercial contractors and greenhouse developers. SABIC leverages its petrochemical feedstock integration to control resin cost volatility across Middle Eastern and Asian supply corridors. Covestro anchors European demand through specialized solid sheet formulations certified under stringent thermal performance protocols. Teijin Limited competes in East Asian markets with advanced optical-grade products serving precision greenhouse and aerospace applications.
Polycarbonate glazing comprises thermoplastic polymer sheets manufactured through extrusion or injection molding processes, typically achieving impact resistance approximately 250 times that of equivalent glass thickness while transmitting visible light in the 80-90% range. Its primary commercial purpose centers on delivering lightweight, shatter-resistant transparent barriers for architectural envelopes, vehicle glazing, and controlled-environment agriculture. Multiwall sheet configurations dominate volume demand in European and North American construction markets due to superior thermal insulation coefficients and structural spanning capability. Solid sheets command premium positioning in automotive and aerospace segments where optical clarity and ballistic resistance justify higher material costs. Specialty sheet grades incorporating UV stabilizers and abrasion-resistant coatings represent the fastest-expanding margin pool as greenhouse operators and skylight specifiers extend replacement cycles.
REACH registration requirements and RoHS substance restrictions govern polycarbonate additive formulations entering European Union member states, while China's GB standards and MEE enforcement protocols set emission and performance baselines for domestic manufacturing and import clearance. The US EPA and OSHA frameworks regulate workplace exposure limits during sheet fabrication and on-site installation, shaping contractor training and equipment investment requirements. Stakeholders must monitor evolving Ecodesign requirements under the EU Green Deal and corresponding state-level building code amendments in California and New York that increasingly mandate embodied carbon disclosure for facade materials.
Market Dynamics
Dual carbon mandates across East Asia and tightening F-Gas thresholds in Europe are compressing specification timelines for thermal-performance glazing, forcing resin producers and sheet extruders to coordinate certification cycles with construction procurement windows.
Growth Catalysts
- Greenhouse agriculture intensification:Controlled-environment horticulture in the Netherlands and Spain is absorbing multiwall sheet volumes for climate-optimized growing environments. Operators prioritize UV-stabilized grades that extend replacement intervals.
- Japan's METI building efficiency codes:Thermal transmittance requirements for commercial envelopes are accelerating specification of high-performance insulated glazing systems in Tokyo and Osaka metropolitan construction.
- Extrusion co-extrusion advances:Multi-layer sheet manufacturing now integrates abrasion-resistant and IR-blocking functionalities in single-pass production, reducing lamination costs for skylight fabricators.
Market Restraints
- Bisphenol-A feedstock volatility:Polycarbonate resin pricing tracks benzene and propylene oxide fluctuations, compressing margin predictability for sheet extruders serving price-sensitive construction segments.
- Glass substitution in premium architectural:Structural silicone glazing and low-iron tempered glass retain specification dominance in high-visibility facade applications where optical clarity commands priority over impact resistance.
- REACH authorization bottlenecks:Flame-retardant additive reclassifications under ECHA review are delaying formulation approvals for interior-grade polycarbonate partitions in German and French commercial fit-outs.
Strategic Opportunities
- India's PLI scheme for advanced materials:Domestic manufacturing incentives for polymer processing equipment are attracting extrusion line investments to serve subcontinent greenhouse and warehouse roofing demand.
- Photovoltaic-integrated glazing convergence:Building-integrated solar manufacturers are specifying translucent backsheet configurations combining polycarbonate weathering layers with crystalline silicon cell arrays.
- Direct contractor procurement platforms:Digital specification tools are disintermediating traditional distributor networks for standard multiwall sheet grades in North American agricultural construction.
Industry Challenges
- Thermal bridging calculation expertise:Curtain wall engineers face skill gaps in modeling multiwall cavity performance under dynamic solar load conditions, slowing specification approval cycles.
- Co-extrusion line capex requirements:Width expansion to serve architectural panel demand demands multi-million dollar extruder investments with 5-7 year payback horizons.
- Multi-jurisdiction certification parallelism:Simultaneous GB standard testing for China, CE marking for Europe, and ICC-ES evaluation for US markets strains product development bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polycarbonate Glazing Market |
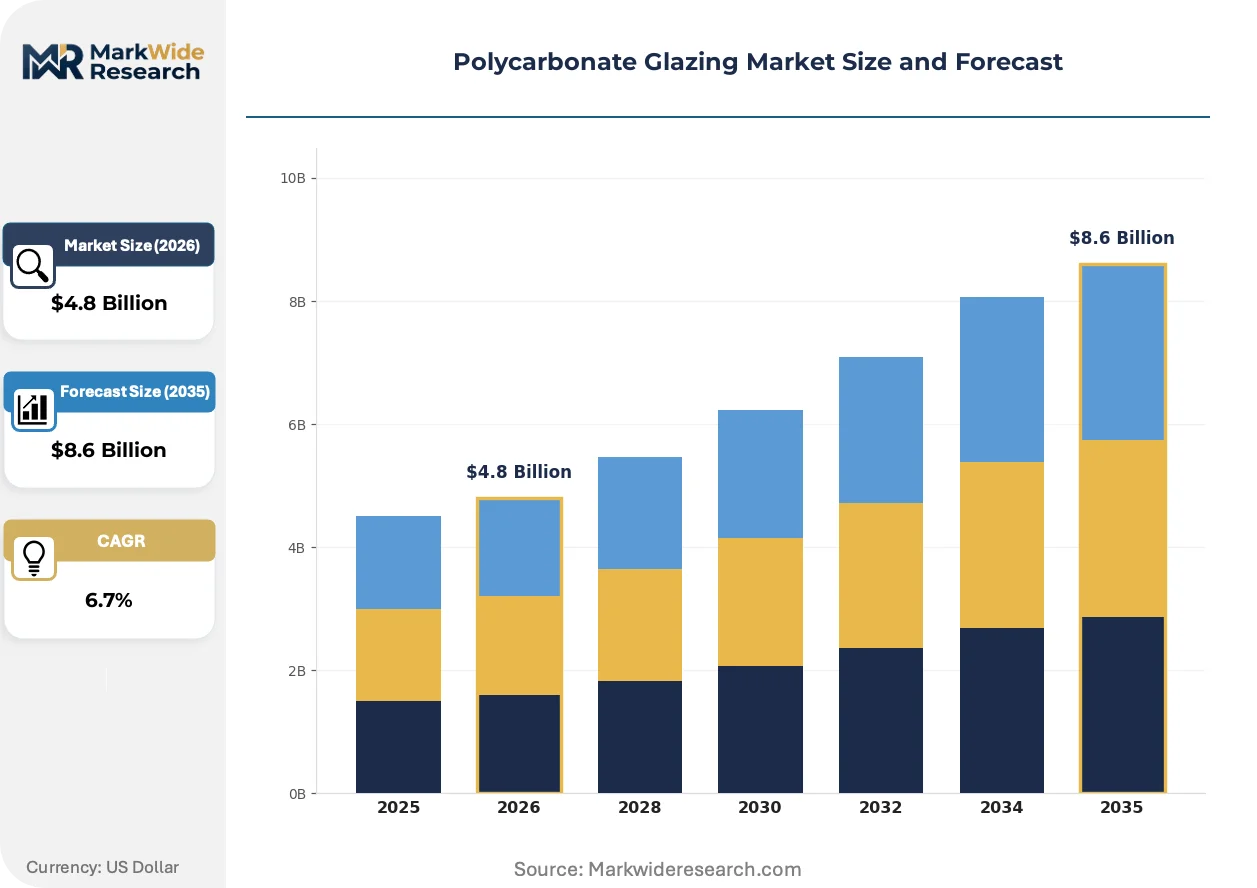
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multiwall Sheets, Solid Sheets, Corrugated Sheets, Specialty Sheets End User: Construction, Automotive, Electrical, Aerospace Application: Roofing, Greenhouse, Windows, Skylights Thickness: 2mm, 4mm, 6mm, 8mm |
| Companies Covered | Plazit Polygal Group, Excelite Plastic Co.,Ltd, SABIC, Suzhou Omay Optical Materials Co Ltd., Plaskolite, Inc., Covestro, Teijin Limited, Arla Plast AB, Palram Industries Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polycarbonate Glazing Market Strategic Shifts
Advanced surface engineering and digital specification workflows are compressing product development cycles while expanding polycarbonate glazing into energy-generating building envelopes.
Nano-structured anti-reflective coatings applied through plasma-enhanced chemical vapor deposition are reducing surface reflectance losses in greenhouse applications. Dutch horticulture technology providers are specifying these treatments for year-round vegetable production facilities. Conventional etched-glass diffusers are rendering obsolete in controlled-agriculture lighting systems.
China's MEE enforcement protocols for industrial emissions are tightening volatile organic compound limits at extrusion facilities. Domestic sheet manufacturers are retrofitting thermal oxidizers and switching to water-based coating systems. Imported polycarbonate systems face extended customs clearance timelines as GB standard compliance verification intensifies.
Building information modeling integration is shifting specification authority from distributor sales teams to facade consultants and energy modelers. Three-dimensional thermal bridging simulations now precede material selection in German and Austrian passive house projects. This behavioral pivot is most pronounced in Central European markets where energy performance certificates determine asset valuation.
Polycarbonate Glazing Market Segmentation
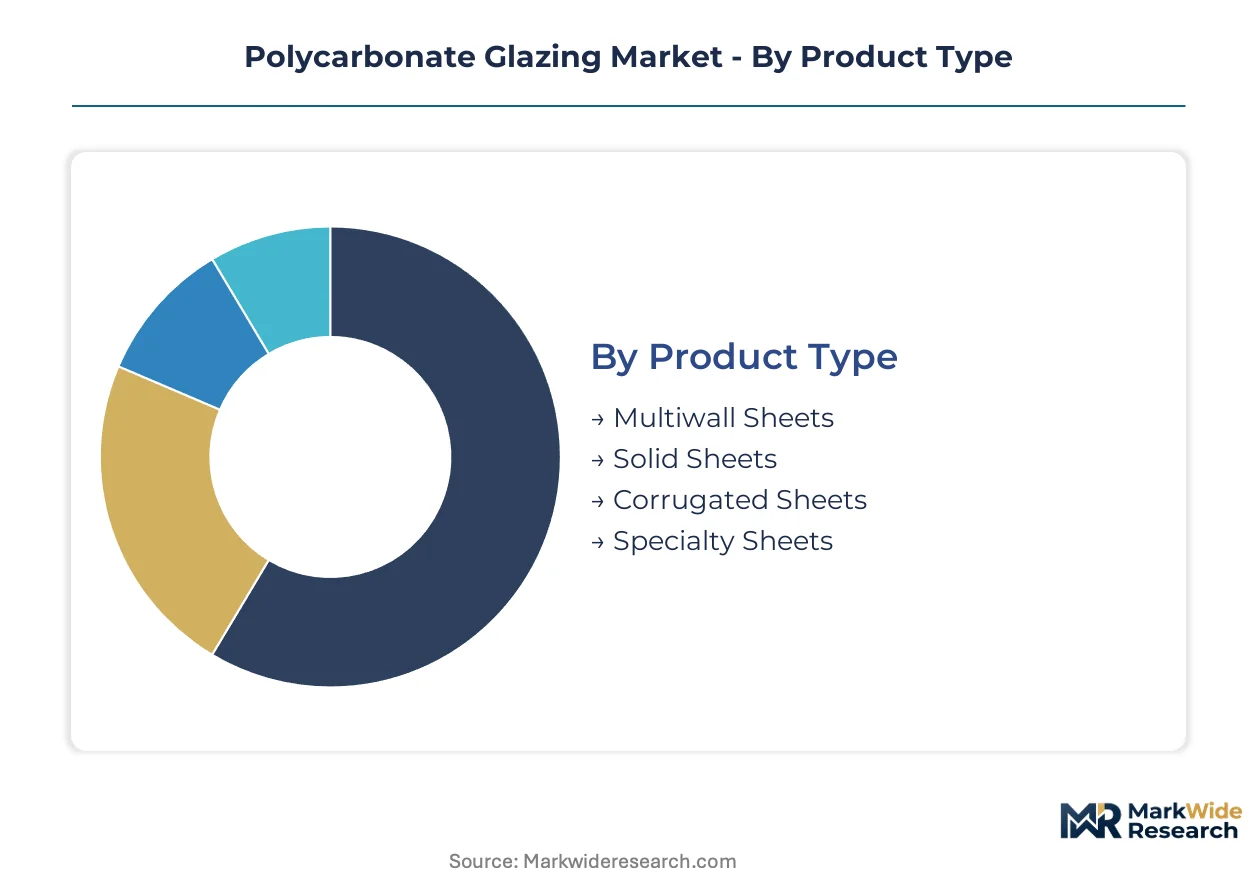
Polycarbonate glazing procurement diverges sharply across product configurations and end-use requirements. Specification authority sits with distinct stakeholder groups in each segment, from greenhouse operators optimizing light transmission to facade engineers calculating thermal bridging.
Product Type:
Cost tier differentiation separates commodity sheet grades from performance-engineered configurations serving premium applications.
- Multiwall Sheets:Extruded cellular structures with internal rib configurations deliver thermal insulation coefficients superior to monolithic alternatives. Construction procurement in Germany and the Netherlands concentrates on 16mm and 25mm configurations for commercial roofing and horticultural envelopes.
- Solid Sheets:Monolithic cast or extruded panels achieve optical clarity approaching glass with 250x impact resistance. Automotive glazing and aerospace cabin windows specify optical-grade formulations certified under stringent surface quality protocols.
- Corrugated Sheets:Profiled configurations spanning industrial warehouse roofing in India and Brazil prioritize rapid installation and structural spanning capability over thermal performance.
- Specialty Sheets:UV-stabilized and abrasion-resistant coated grades extend replacement cycles for greenhouse operators. Co-extrusion advances integrate IR-blocking layers in single-pass production.
Multiwall sheets command the established base. The steepest expansion runs through specialty coated grades.
End User:
Application maturity varies dramatically across customer industries, with construction standardizing specifications while aerospace demands custom certification cycles.
- Construction:Commercial envelope specification drives volume absorption across Germany, India, and Brazil. Greenhouse agriculture intensification in the Netherlands and Spain concentrates procurement of UV-stabilized multiwall systems.
- Automotive:Interior partition glazing and panoramic roof modules specify solid sheet formulations balancing weight reduction with optical clarity. OEM qualification timelines extend 18-24 months for new material approvals.
- Electrical:Electrical insulation and equipment housings utilize flame-retardant grades subject to REACH authorization reviews delaying formulation approvals.
- Aerospace:Cabin window and cockpit transparency applications demand optical-grade polycarbonate with documented lot traceability. Teijin Limited serves this segment with advanced formulations.
Construction represents the volume anchor. Aerospace delivers the highest margin realization per kilogram processed.
Application:
Functional performance requirements dictate material selection, with thermal bridging calculations and light diffusion properties driving specification divergence.
- Roofing:Commercial and industrial building envelopes in Germany and Brazil specify multiwall configurations for spanning capability and snow load resistance. Thermal transmittance requirements under Japan's METI codes accelerate high-performance insulated glazing adoption.
- Greenhouse:Controlled-environment horticulture operators prioritize UV-stabilized grades extending replacement intervals. Dutch technology providers specify nano-structured anti-reflective coatings for year-round vegetable production.
- Windows:Impact-resistant residential and commercial fenestration competes with tempered glass in hurricane-prone US markets. Solid sheet grades penetrate where shatter resistance outweighs optical clarity priorities.
- Skylights:Daylighting systems integrate multiwall configurations with IR-blocking co-extruded layers. Three-dimensional thermal bridging simulations now precede material selection in German passive house projects.
Roofing absorbs the highest tonnage. Greenhouse applications are climbing the fastest as controlled-agriculture investment intensifies.
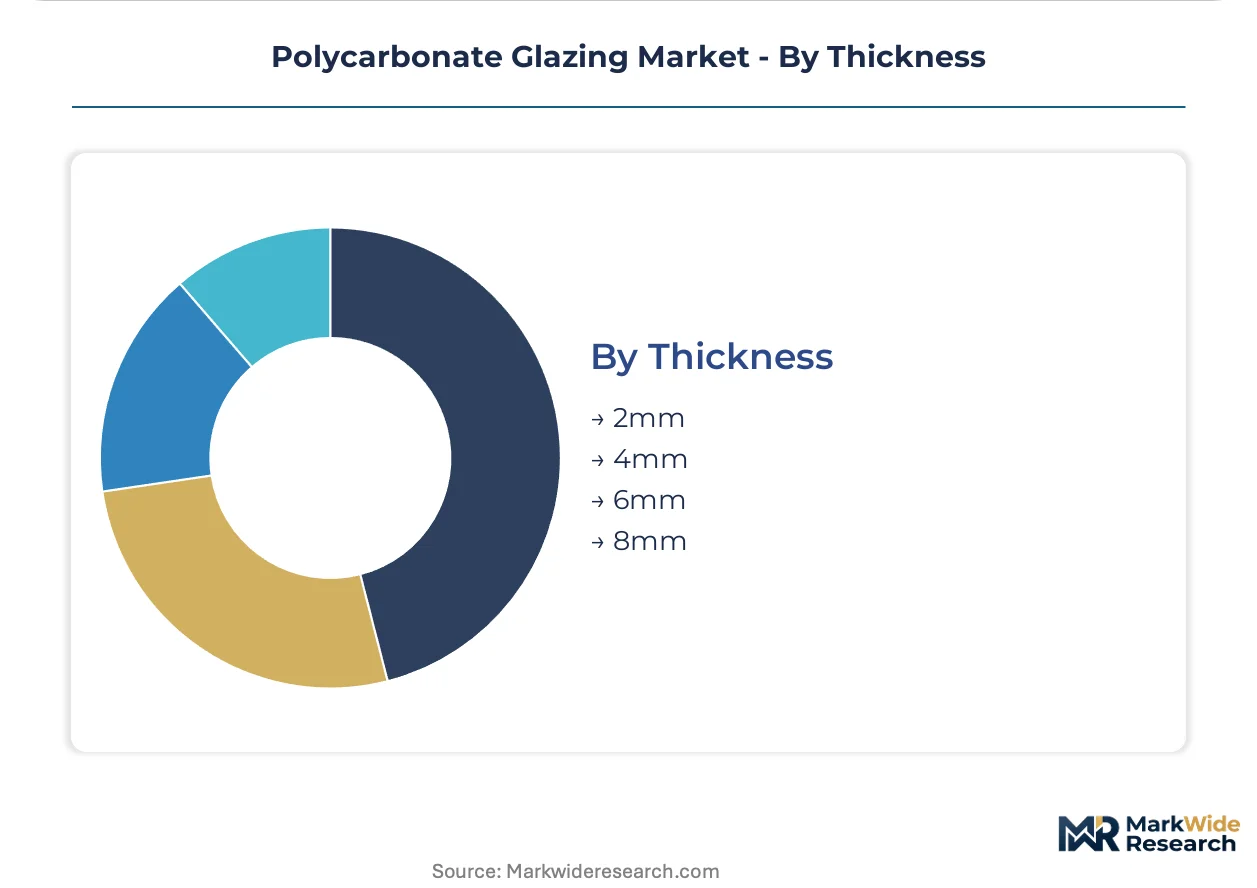
Thickness:
Structural load requirements and thermal performance targets segment demand across dimensional specifications, with thicker configurations commanding premium positioning.
- 2mm:Lightweight interior partitions and signage applications prioritize cost efficiency over structural performance. Price-sensitive construction segments in India specify this grade for temporary enclosure systems.
- 4mm:Standard greenhouse cladding and residential skylight applications balance light transmission with basic impact protection. Volume production economies concentrate at this specification.
- 6mm:Commercial roofing and facade systems requiring enhanced spanning capability specify this intermediate thickness. German and Austrian passive house projects favor this grade for thermal performance optimization.
- 8mm:Heavy-duty industrial roofing and ballistic-resistant applications demand maximum structural integrity. Premium positioning reflects higher resin consumption per square meter.
4mm specifications hold the volume core. 6mm configurations are gaining share fastest as thermal performance codes tighten across European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MEE enforcement protocols in China anchor the dominant geography, where dual carbon mandates and GB standard compliance verification are reshaping procurement timelines for thermal-performance glazing systems across East Asian construction markets.
Germany
Commercial envelope specification drives multiwall sheet absorption for commercial roofing and greenhouse applications. REACH authorization reviews under ECHA jurisdiction delay flame-retardant formulation approvals for interior-grade partitions. The Rhine-Ruhr industrial corridor hosts extrusion facilities serving Central European passive house projects with thermal bridging-optimized configurations.
China
Dual carbon goals accelerate specification of high-performance thermal insulation glazing in metropolitan construction. MEE protocols tighten volatile organic compound limits at extrusion facilities, extending customs clearance timelines for imported systems. The Yangtze River Delta cluster concentrates domestic sheet manufacturing serving greenhouse and skylight demand.
India
PLI scheme incentives for polymer processing equipment attract extrusion line investments to serve subcontinent warehouse roofing demand. BIS standards and DGFT import protocols set performance baselines for domestic manufacturing clearance. Maharashtra and Gujarat industrial zones concentrate greenhouse cladding procurement from domestic fabricators.
Japan
METI building efficiency codes accelerate specification of high-performance insulated glazing systems in Tokyo and Osaka metropolitan construction. JIS standards govern optical-grade formulations for precision applications. The Kanto region anchors demand for advanced thermal transmittance solutions in commercial envelope retrofit projects.
Brazil
Industrial warehouse roofing specification prioritizes corrugated configurations for rapid installation and structural spanning capability. ANVISA protocols regulate additive formulations for interior applications. São Paulo state concentrates procurement of multiwall systems for commercial roofing in expanding logistics infrastructure.
Polycarbonate Glazing Market Competitive Environment
Petrochemical-integrated resin producers and specialized sheet extruders split the market into distinct capability tiers. Consolidation pressure concentrates among feedstock-anchored players controlling benzene and propylene oxide supply corridors, while regional fabricators compete on specification responsiveness and certification agility. Three archetypes dominate: upstream-integrated resin suppliers, application-specialized extruders, and optical-grade precision manufacturers. Capacity expansion in co-extrusion width capabilities and strategic partnerships for photovoltaic-integrated glazing configurations represent the dominant competitive vectors.
Within the upstream-integrated tier, SABIC leverages Middle Eastern feedstock positioning to anchor resin cost structures across Asian supply corridors. Covestro exemplifies the European specialized extruder archetype through solid sheet formulations certified under stringent thermal performance protocols. Teijin Limited occupies the optical-grade precision position, serving advanced applications requiring documented lot traceability and surface quality certification.
| Leading Market Players |
|---|
| Plazit Polygal Group |
| Excelite Plastic Co.,Ltd |
| SABIC |
| Suzhou Omay Optical Materials Co Ltd. |
| Plaskolite, Inc. |
| Covestro |
| Teijin Limited |
| Arla Plast AB |
| Palram Industries Ltd |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese extrusion facilities is compressing spot pricing for standard multiwall grades while forcing Middle Eastern resin suppliers to prioritize contract offtake over merchant sales. This utilization imbalance rewards integrated producers with captive benzene supply and punishes standalone sheet fabricators exposed to propylene oxide volatility.
Pricing Analysis
East Asian spot quotations for commodity multiwall sheet currently undercut European delivered prices by margins that absorb ocean freight and import duties. Pricing stratifies across optical-grade, thermal-performance-certified, and unbranded commodity tiers, with UV-stabilized and abrasion-resistant coatings commanding substantial premiums. Cost compression in standard greenhouse cladding intensifies as Indian domestic capacity ramps under PLI incentives. Warehouse roofing contractors in Brazil exhibit the highest price sensitivity, while aerospace transparency purchasers prioritize lot traceability over unit cost.
Supply Chain Analysis
Export-control restrictions on advanced co-extrusion equipment limit technology transfer to certain jurisdictions, constraining width-expansion capabilities in emerging manufacturing zones. Supply concentrates in China, Germany, and Saudi Arabia, with resin production anchored in Middle Eastern petrochemical complexes and sheet extrusion distributed across consumption markets. Feedstock draws from benzene crackers and propylene oxide plants, with additive formulations resting on flame-retardant and UV-stabilizer chemistries. Single-source vulnerability runs through bisphenol-A monomer supply. Distribution runs through regional distributor networks for standard grades and direct specification channels for architectural projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polycarbonate glazing market is exiting a cyclical trough as construction procurement rebounds and greenhouse agriculture investment accelerates across temperate climate zones.
For Market Incumbents: Entrench position through backward integration into specialty additive formulations and co-extrusion width expansion in the Rhine-Ruhr corridor. Prioritize REACH pre-registration for flame-retardant grades to preempt ECHA authorization bottlenecks. Channel control through digital specification platforms defends margin position against distributor disintermediation in North American agricultural construction. For New Entrants and Emerging Players: Mid-market commercial roofing in India's Maharashtra and Gujarat industrial zones represents the most penetrable entry point given PLI equipment incentives and underdeveloped domestic thermal-performance certification. Specialty greenhouse cladding with nano-structured anti-reflective coatings offers a second white-space target where Dutch technology providers currently source from European incumbents. Go-to-market execution should emphasize direct contractor procurement platforms bypassing traditional distribution markups. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multi-layer co-extrusion lines as width expansion demands exceed standard equipment specifications. The five-to-ten-year viability window favors acquisition targets with established GB standard compliance for China access and existing METI code certification for Japanese commercial envelope retrofit. Monitor India's BIS enforcement timelines as an inflection signal for domestic manufacturing preference intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Co-extrusion Width Expansion | Enables architectural panel formats demanded by German passive house projects. |
| Backward Integration into Additives | Secures flame-retardant formulation supply against REACH authorization delays. |
| Photovoltaic-Integrated Glazing Partnerships | Captures building-integrated solar convergence specifying translucent polycarbonate backsheets. |
| Digital Specification Platform Launch | Disintermediates distributor networks for standard multiwall sheet in agricultural construction. |
| GB Standard Pre-Certification Investment | Accelerates China customs clearance timelines as MEE enforcement intensifies. |
Study Parameters
The analysis maps multiwall sheet, solid sheet, corrugated sheet, and specialty coated sub-sectors, each validated through extrusion plant managers, architectural specification consultants, greenhouse procurement directors, and distributor channel heads. Primary interview findings triangulate against customs trade data, REACH registration databases, SEC filings from petrochemical-integrated producers, and national building code amendment records. Bottom-up volume builds from named extrusion line capacities and utilization estimates reconcile with top-down construction spend allocation models.
Assumptions regarding feedstock cost trajectories, regulatory enforcement intensity, and construction procurement cycle timing were held fixed across baseline scenarios while regional carbon-mandate acceleration and F-Gas threshold tightening were stress-tested as upside variants. Segmentation modeling incorporates product configuration, end-use industry, application function, and thickness specification as dimensional drivers. CAGRs derive from logistic diffusion curves fitted to historical adoption patterns in greenhouse agriculture and commercial envelope retrofit, with polycarbonate substitution rates against glass and thermal performance code stringency as key forecast inputs.
Practitioners should monitor benzene-propylene oxide spread compression, ECHA flame-retardant reclassification timelines, and India's BIS certification enforcement for early signals requiring forecast revision. Material shifts in dual carbon mandate implementation pace or photovoltaic-integrated glazing specification traction would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyetherketoneketone (PEKK) Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Global Low Density Polyethylene (LDPE) Foams Market
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Asia-Pacific Flooring Resins Market
Polymers & Resins
Global Polycarbonate Market
Polymers & Resins
Global Specialty Polystyrene Resin Market
Polymers & Resins
Bio-Based Construction Polymers Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Emulsion PVC Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
Global Barrier Resins Market
Polymers & Resins
Sugar Polymers Market
Polymers & Resins
Conductive Polymers Market
Polymers & Resins
Global Polyol and Polyurethane Market