
 Europe Polyamide Market | 2026-2036
Europe Polyamide Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Polyamide Market Insights
Automotive electrification is restructuring polyamide consumption patterns across Europe, with high-heat-resistant grades displacing conventional formulations in battery housings and thermal management systems. BASF leverages its integrated caprolactam chain to anchor supply security for OEM qualification programs. Evonik Industries AG specializes in high-performance PA12 variants for fuel lines and pneumatic systems, sustaining niche margin pools amid commoditization pressure. LANXESS competes through glass-filled PA6 compounds tailored to electric powertrain components, extending its historical strength in automotive engineering plastics.
Polyamide denotes a class of thermoplastic polymers characterized by repeating amide linkages, with PA6 and PA66 representing the dominant aliphatic variants produced through ring-opening polymerization and condensation chemistry respectively; these materials exhibit melting points between 220°C and 265°C, tensile strengths exceeding 80 MPa in reinforced grades, and inherent resistance to hydrocarbons and abrasion that underpins their use in load-bearing mechanical components. PA6 dominates European volume consumption due to its cost-position and adaptability to compounding, while PA66 commands premium placement in under-hood automotive applications where thermal aging resistance is non-negotiable. PA12 and PA46 occupy narrower but defensible positions in fuel system infrastructure and high-temperature electrical connectors respectively, with margin structures reflecting feedstock scarcity and specialized polymerization asset requirements.
REACH registration obligations and the EU Green Deal carbon-border adjustments are reshaping feedstock sourcing economics for European polyamide producers, favoring regional caprolactam and adipic acid supply over import-dependent alternatives. ECHA substance restrictions on certain plasticizers and flame retardants are accelerating reformulation cycles, particularly in electrical insulation and consumer goods applications where legacy additive packages face sunset dates. The F-Gas Regulation indirectly influences polyamide demand in HVAC and refrigeration components, channeling specification shifts toward materials compatible with lower-global-warming-potential refrigerants. Stakeholders must monitor the interplay between EU taxonomy alignment requirements and recycling infrastructure scaling, as post-industrial and post-consumer polyamide feedstock availability will determine cost competitiveness against virgin material in the latter half of the forecast horizon.
Market Dynamics
Automotive electrification is compressing qualification timelines and forcing polyamide suppliers to recalibrate thermal performance specifications for battery housings, thermal management modules, and high-voltage connectors across the continent.
Growth Catalysts
- EU Green Deal carbon-border adjustments:Domestic caprolactam producers gain cost advantages over import-dependent competitors, reinforcing regional supply security for automotive OEMs.
- High-heat PA66 grades:Electric powertrain thermal management requirements are pulling reinforced formulations into battery module housings and inverter enclosures.
- Poland's industrial corridor:Injection molding clusters around Wrocław and Kraków are concentrating demand for glass-filled PA6 compounds in white goods and automotive components.
Market Restraints
- Adipic acid supply concentration:European adipic acid production remains concentrated among a limited set of petrochemical complexes, exposing polyamide 66 supply to feedstock disruption.
- REACH substance restrictions:ECHA sunset dates on legacy plasticizers and halogenated flame retardants are forcing reformulation cycles that compress margin structures in electrical insulation grades.
- Mechanical property trade-offs:Bio-based polyamide alternatives from castor oil derivatives exhibit moisture absorption and dimensional stability limitations that restrict deployment in precision automotive components.
Strategic Opportunities
- Czech automotive supplier ecosystem:Tier-1 and Tier-2 component manufacturers around Mladá Boleslav and Ostrava present underpenetrated demand for specialty PA12 variants in fuel line and pneumatic applications.
- Chemical recycling infrastructure:Pyrolysis and depolymerization investments by European waste processors are creating pathways for post-industrial polyamide feedstock to re-enter automotive qualification programs.
- F-Gas Regulation compliance:HVAC and refrigeration OEMs are specifying polyamide grades compatible with lower-global-warming-potential refrigerants, opening specification windows for hydrolysis-resistant formulations.
Industry Challenges
- Polymer characterization expertise:Automotive electrification is compressing the timeline for thermal aging and electrical tracking testing, creating bottlenecks in accredited laboratory capacity.
- Multi-material bonding complexity:Battery housings require polyamide-to-aluminum and polyamide-to-polypropylene interfaces that demand novel surface treatment and adhesive qualification protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Polyamide Market |
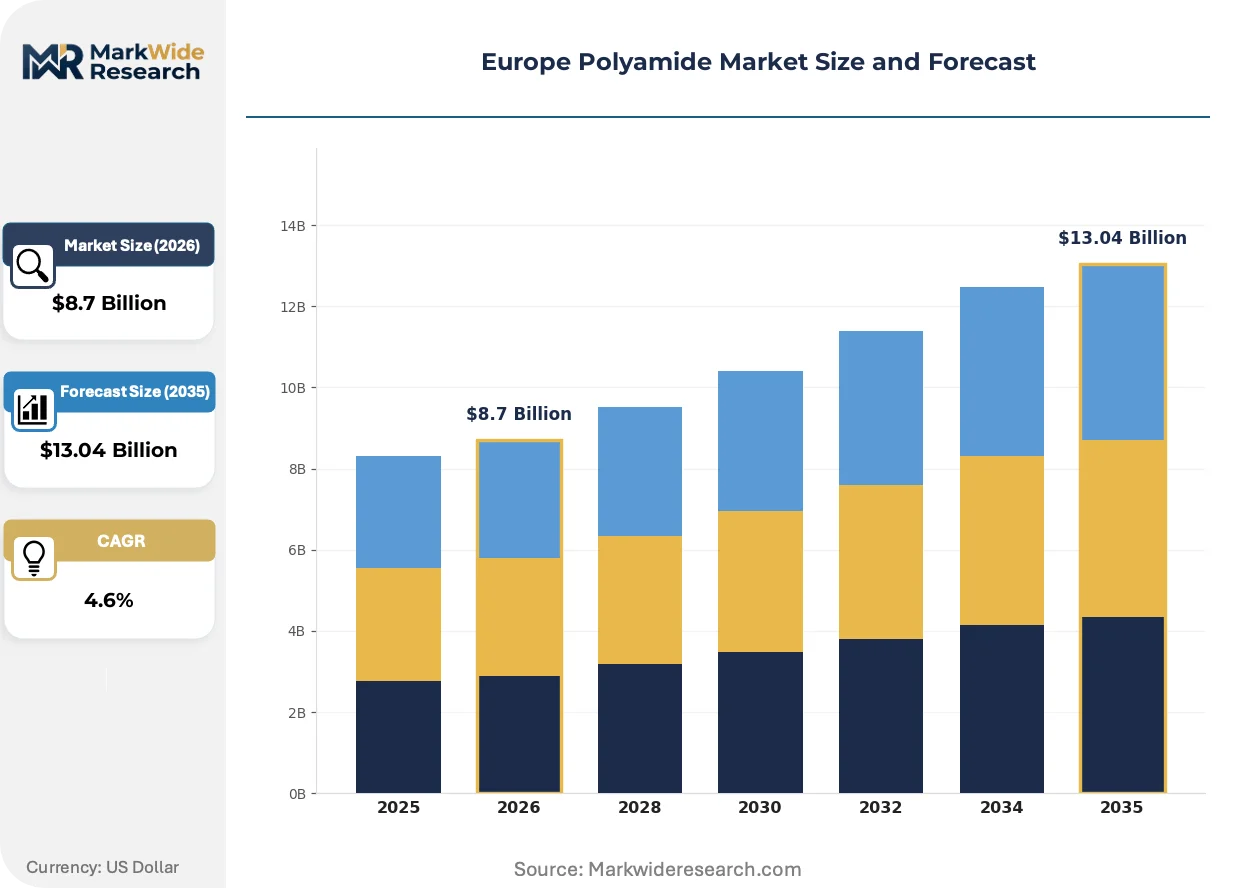
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PA6, PA66, PA12, PA46 Application: Automotive Components, Electrical Insulation, Industrial Textiles, Consumer Goods Form: Granules, Fibers, Films, Sheets End User: Manufacturers, OEMs, End-Users, Construction |
| Companies Covered | DSM-Firmenich, Evonik Industries AG, BASF, Arkema Group, Celanese Corporation, LANXESS, Radici Partecipazioni SpA, Grupa Azoty S A, Domo Chemicals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Polyamide Market Trends and Innovations
Material specification workflows are compressing as automotive electrification forces simultaneous optimization of thermal performance, electrical insulation, and recyclability credentials. Formulation science is converging with circular economy infrastructure development.
Hybrid reinforcement systems combining glass fiber with mineral fillers are modularizing compounding workflows for electric vehicle battery trays. Tier-1 suppliers in Germany's automotive corridor are adopting these formulations to reduce warpage in large structural components. The technology is modularizing the traditional separation between structural and thermal management grades, enabling single-material solutions that simplify recycling streams.
REACH registration obligations are tightening disclosure requirements for polymer additives and processing aids used in electrical and electronic equipment. ECHA's expanded substance evaluation program is accelerating the phase-out of legacy flame retardant packages. Electrical connector manufacturers are responding by accelerating qualification of phosphorus-based and metal hydroxide alternatives in high-temperature polyamide grades.
Automotive OEMs are consolidating supplier panels and demanding full material lifecycle documentation aligned with EU taxonomy technical screening criteria. Procurement teams are prioritizing suppliers with certified post-industrial recycling streams and verified carbon footprint data. This consolidation is most visible in Germany, where Volkswagen, BMW, and Mercedes-Benz have established unified polyamide qualification protocols that exclude non-compliant compounders from platform programs.
Europe Polyamide Market Segmentation
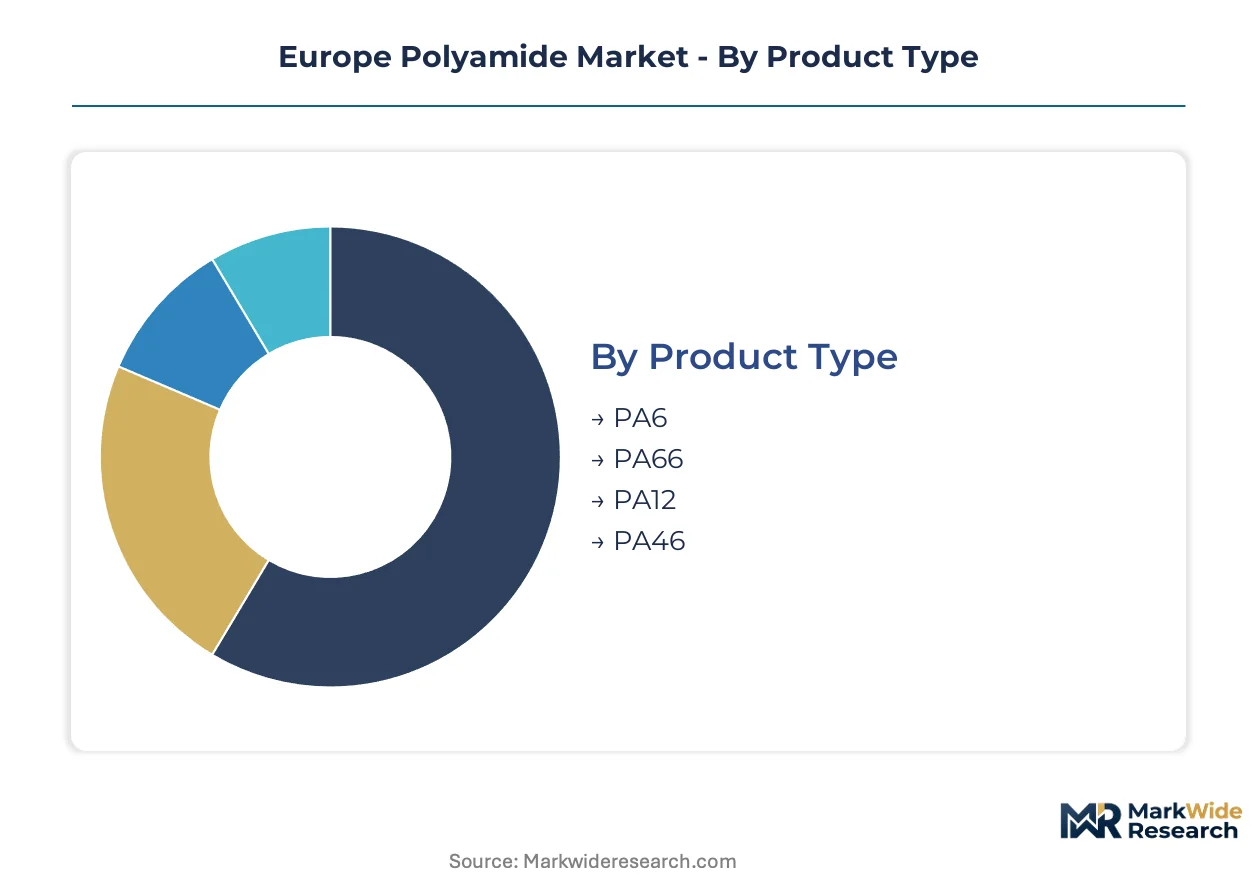
Polyamide segmentation across Europe reflects divergent supply chain economics and qualification barriers that separate commodity volume from specialty margin pools. Each category reveals distinct concentration patterns tied to automotive electrification timelines and REACH compliance cycles.
Product Type:
Caprolactam and adipic acid supply concentration determines competitive positioning across these four polymer families, with integrated producers commanding cost advantages in qualification-intensive automotive programs.
- PA6:Ring-opening polymerization of caprolactam yields this aliphatic polyamide with melting points near 220°C. German automotive corridors around Stuttgart and Wolfsburg concentrate consumption for under-hood components where cost-performance balance outweighs thermal extremes. REACH registration obligations favor regional caprolactam supply over import-dependent alternatives.
- PA66:Condensation polymerization of hexamethylenediamine and adipic acid produces this higher-melting variant. Battery housing and inverter enclosure specifications in Bavaria and Baden-Württemberg are pulling reinforced grades into thermal management applications where 265°C melting points prove non-negotiable. Adipic acid supply concentration among limited European petrochemical complexes exposes this segment to feedstock disruption risk.
- PA12:Laurolactam-based polymerization creates this lower-density specialty with exceptional moisture resistance. Czech fuel line manufacturers around Mladá Boleslav represent underpenetrated demand for this grade.
- PA46:Stanyl-grade polymerization chemistry delivers highest thermal performance among aliphatic variants. High-temperature electrical connector specifications in French industrial zones sustain niche positioning.
Today's leader: PA6. Tomorrow's challenger: PA66.
Application:
End-use fragmentation across these four sectors tracks divergent margin structures and regulatory exposure, with automotive and electrical facing the most compressed qualification timelines.
- Automotive Components:Structural, thermal, and electrical applications span powertrain, chassis, and interior systems. Poland's injection molding clusters around Wrocław concentrate white goods and automotive component demand for glass-filled compounds. ECHA substance restrictions on legacy plasticizers are forcing reformulation cycles in interior applications.
- Electrical Insulation:Wire jackets, connectors, and switch housings require flame retardancy and tracking resistance. REACH sunset dates on halogenated flame retardants are accelerating phosphorus-based alternative qualification in German electrical manufacturing zones.
- Industrial Textiles:Rope, belt, and filtration fabrics exploit high tenacity and abrasion resistance. Czech technical textile producers anchor regional consumption.
- Consumer Goods:Sporting equipment, kitchen utensils, and personal care items prioritize surface finish and colorability. Italian compounders serving this segment face margin compression from Asian import competition.
Automotive Components commands current volume primacy. Electrical Insulation exhibits the steepest expansion trajectory as electrification multiplies connector counts per vehicle platform.
Form:
Processing technology concentration shapes geographic demand patterns, with extrusion and injection molding infrastructure determining regional form preferences.
- Granules:Standard pellet form for injection molding and extrusion compounding. German automotive Tier-1 suppliers around Ingolstadt and Dingolfing represent the continent's densest concentration of high-volume granule consumption.
- Fibers:Melt-spun continuous filament and staple for textile and industrial yarn applications. Italian and Czech technical textile clusters sustain regional fiber demand.
- Films:Cast and oriented sheet for packaging and industrial lamination. French and Spanish flexible packaging converters anchor this form's consumption base.
- Sheets:Extruded and compression-molded plate for machining and thermoforming. Benelux industrial distributors stock broad sheet inventories for job shop fabrication.
Granules dominate present volume. Fibers are gaining share fastest as industrial textile specifications tighten.
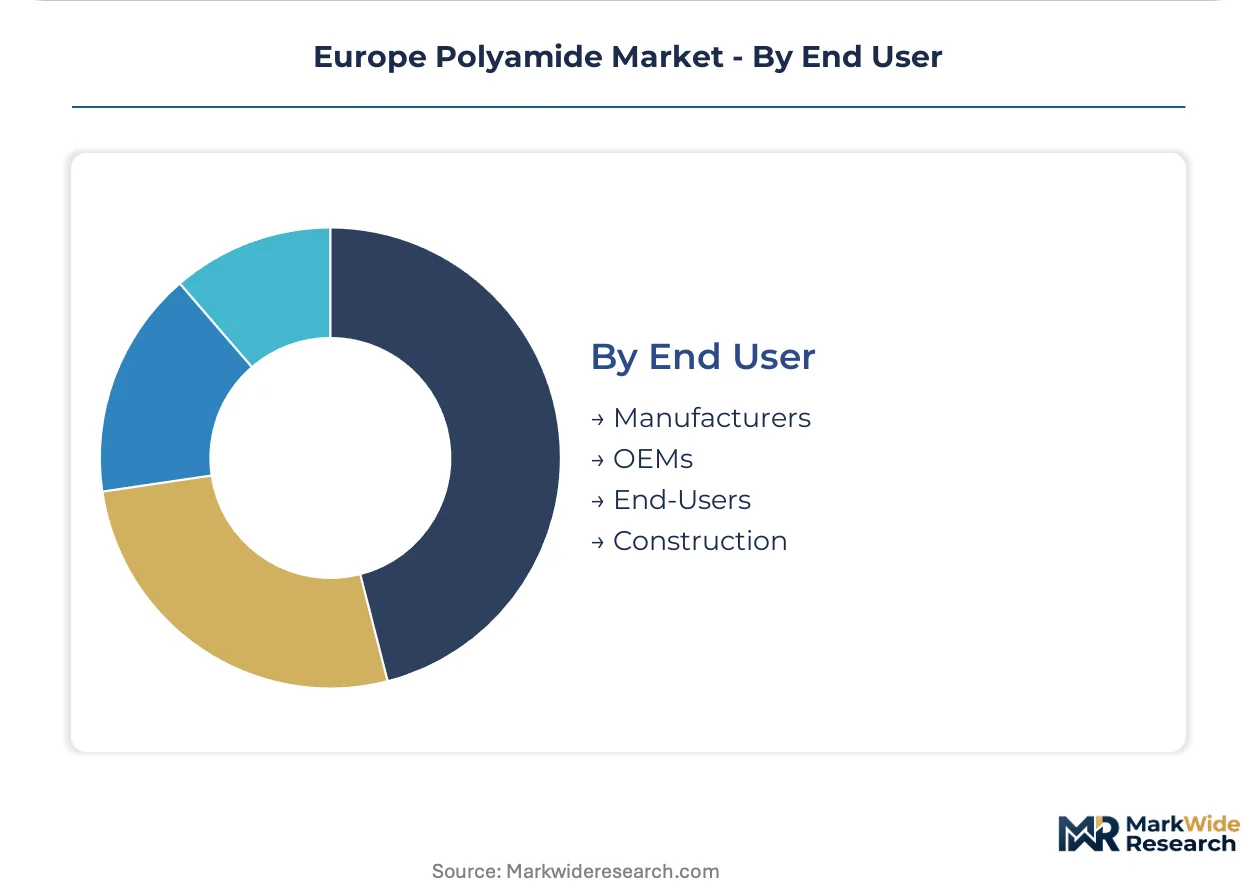
End User:
Customer type segmentation reveals divergent procurement sophistication and sustainability documentation requirements that separate integrated OEM programs from distributor-mediated spot buying.
- Manufacturers:Compounders and converters purchasing resin for formulation or direct processing. Poland's Wrocław-Kraków industrial corridor concentrates mid-tier manufacturer demand for glass-filled PA6.
- OEMs:Original equipment manufacturers with direct material qualification and lifecycle documentation mandates. Volkswagen, BMW, and Mercedes-Benz procurement teams have established unified polyamide qualification protocols excluding non-compliant compounders.
- End-Users:Final product assemblers purchasing specified compounds through distributor channels. Construction sector end-users in Spain and Italy represent price-sensitive spot demand.
- Construction:Infrastructure and building applications including cable ties, pipe fittings, and formwork components. German civil engineering contractors specify recycled-content grades for public procurement compliance.
Manufacturers hold current volume leadership. OEMs are climbing the fastest as platform consolidation concentrates purchasing power among fewer qualified suppliers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH compliance costs and carbon-border adjustment mechanisms are redistributing polyamide production capacity across Europe, with integrated producers in Germany and Poland capturing share from import-dependent compounders facing tariff exposure.
Germany
Automotive electrification programs at BMW, Mercedes-Benz, and Volkswagen are pulling high-heat PA66 grades into battery housings and inverter enclosures. The EU Green Deal's carbon-border adjustments favor domestic caprolactam supply chains around Ludwigshafen and Marl. Stuttgart and Wolfsburg anchor the continent's densest concentration of granule consumption for under-hood components.
Poland
Injection molding clusters around Wrocław and Kraków are concentrating demand for glass-filled PA6 compounds in white goods and automotive supplier networks. ECHA substance restrictions on legacy plasticizers are accelerating reformulation cycles among compounders serving export markets. The country's industrial corridor is capturing volume from German OEMs seeking cost-advantaged processing capacity.
Czech Republic
Tier-1 and Tier-2 automotive suppliers around Mladá Boleslav and Ostrava present expanding demand for specialty PA12 variants in fuel line and pneumatic applications. The F-Gas Regulation is channeling specification shifts toward hydrolysis-resistant formulations in HVAC components. Technical textile producers in Liberec anchor regional fiber demand for industrial applications.
Italy
Compounders serving consumer goods and sporting equipment segments face margin compression from Asian import competition in surface-finish-sensitive applications. REACH registration obligations are tightening disclosure requirements for additives used in electrical connectors manufactured in Lombardy and Piedmont. Milan-based distributors are consolidating procurement for premium-grade specialty polymers.
France
High-temperature electrical connector specifications in the Auvergne-Rhône-Alpes industrial zone sustain niche demand for PA46 grades. Flexible packaging converters in the Paris Basin anchor film-form consumption for lamination applications. ECHA's expanded substance evaluation program is accelerating phase-out timelines for halogenated flame retardants in electrical insulation grades produced in the region.
Europe Polyamide Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated petrochemical producers commanding automotive qualification pipelines while regional compounders serve price-sensitive industrial applications. The market structures around three tiers: global resin producers with captive feedstock, European compounders with formulation expertise, and distributor-mediated spot suppliers. M&A activity concentrates on recycling technology capabilities, while capacity investments prioritize pyrolysis and depolymerization infrastructure for circular feedstock.
Among integrated European producers, DSM-Firmenich and Evonik Industries AG occupy positions anchored in high-performance specialty grades, while BASF represents the scale-driven archetype with backward integration into caprolactam supply chains. LANXESS exemplifies the automotive-focused compounder segment with glass-filled formulation expertise. These three entities sit within distinct competitive vectors—specialty margin pools, feedstock security, and application engineering—rather than direct overlap.
| Leading Market Players |
|---|
| DSM-Firmenich |
| Evonik Industries AG |
| BASF |
| Arkema Group |
| Celanese Corporation |
| LANXESS |
| Radici Partecipazioni SpA |
| Grupa Azoty S A |
| Domo Chemicals |
| Others |
Pricing and Supply Chain Analysis
Certification-grade divergence between REACH-compliant specialty formulations and commodity spot material creates parallel pricing architectures that feed back into sourcing decisions across European automotive corridors. Premium-grade compounders in Germany's Ludwigshafen and Marl clusters command qualification-linked price premiums while import-dependent distributors face carbon-border adjustment compression.
Pricing Analysis
Distributor margin layers separate automotive Tier-1 direct contracts from spot market transactions through European industrial distributors. Three-tier pricing structure across automotive-qualified, industrial-standard, and economy spot grades reflects REACH registration burden and carbon footprint verification costs. Pricing pressure stems from Asian import competition in consumer goods segments where surface finish sensitivity commands premium positioning. OEM procurement teams exhibit lowest price sensitivity due to platform consolidation and lifecycle documentation mandates.
Supply Chain Analysis
Dual-sourcing requirements from Volkswagen, BMW, and Mercedes-Benz procurement protocols mandate qualified backup suppliers for battery housing and inverter enclosure grades. Feedstock concentration in Germany, Belgium, and the Netherlands anchors caprolactam and adipic acid availability for regional polymerization assets. Raw material dependencies on benzene, cyclohexane, and ammonia draw from integrated petrochemical complexes along the Rhine corridor. Single-source vulnerability in adipic acid supply exposes PA66 producers to feedstock disruption. Distribution runs through compounder-direct OEM channels for automotive qualification programs and distributor-mediated spot buying for industrial applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunity concentrates in high-heat PA66 grades as electrification multiplies thermal management content per vehicle platform. Carbon-border adjustment mechanisms favor integrated European producers with verified supply chain documentation.
For Market Incumbents: Cement automotive qualification pipelines through accelerated thermal aging and electrical tracking testing capacity investments. Defend against specialty compounder encroachment by locking long-term offtake agreements with Czech and Polish Tier-1 suppliers. Backward integration into caprolactam supply secures cost position against import-dependent competitors facing tariff exposure. For New Entrants and Emerging Players: Capture underpenetrated PA12 demand in Czech fuel line and pneumatic applications around Mladá Boleslav and Ostrava. White-space availability concentrates in chemical recycling feedstock qualification where pyrolysis and depolymerization investments lack established compounder relationships. Go-to-market leverage rests on post-industrial recycling stream certification aligned with EU taxonomy technical screening criteria. For Investors and Strategic Acquirers: Asymmetric upside sits with recycling technology specialists possessing automotive-qualified feedstock pathways. Five-to-ten year viability hinges on scaling post-consumer polyamide collection infrastructure ahead of virgin material cost parity inflection. Acquisition target archetype: mid-cap compounders with REACH-registered formulation libraries and established OEM qualification protocols. Signal to monitor: carbon-border adjustment rate implementation timeline and its compression effect on import-dependent competitor margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Caprolactam | BASF's Ludwigshafen complex demonstrates feedstock security for automotive OEM qualification programs. |
| Chemical Recycling Infrastructure Investment | Pyrolysis and depolymerization assets create circular feedstock pathways for post-industrial polyamide requalification. |
| High-Heat PA66 Grade Development | Battery housing specifications in Bavaria pull reinforced formulations into thermal management applications. |
| REACH Compliance Certification | ECHA substance restrictions accelerate reformulation cycles favoring pre-registered additive packages. |
| Long-Term Supply Agreement with OEMs | Volkswagen, BMW, and Mercedes-Benz procurement consolidation rewards qualified compounders with platform access. |
Research Methodology
Bottom-up automotive electrification modeling reconciled against top-down caprolactam and adipic acid supply tracking forms the analytical core of this study. Primary interviews with polymer plant managers, Tier-1 supplier procurement leads, automotive platform engineers, and technical R&D directors at European compounders were cross-validated against secondary sources including Cefic industry reports, customs trade data, SEC 10-K filings from listed chemical producers, and ECHA substance registration databases. Triangulation between demand-side qualification timelines and supply-side feedstock concentration patterns ensures segmentation integrity.
Historical trendline analysis of PA6 and PA66 consumption patterns across German automotive corridors, Polish injection molding clusters, and Czech supplier ecosystems established baseline growth trajectories. Segmentation modeling incorporated product type tier, end-use industry concentration, form factor preference, and OEM qualification status across the projection horizon. CAGR derivation rested on electric vehicle platform rollout schedules and thermal management content per vehicle assumptions. Industry-specific forecast inputs included REACH sunset date timelines and carbon-border adjustment implementation phasing.
Adipic acid supply disruption, REACH substance restriction acceleration, and electric vehicle platform delay are the dominant revision risks to modeled outcomes. Deviation in automotive electrification adoption velocity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Europe Thermoplastics Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Bismaleimide Monomer Market
Polymers & Resins
Bio-Sourced Nylon Market
Polymers & Resins
Global Thermosetting Polymer Market
Polymers & Resins
Fluoropolymers in Healthcare Market
Polymers & Resins
Polyacrylate Market
Polymers & Resins
Global Structural Foam Market
Polymers & Resins
Polycarbonate Diols Market
Polymers & Resins
Styrenics Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Africa Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Acrylic Resins Market
Polymers & Resins
Terpene Resins Market