
 Singapore Sealants Market | 2026-2036
Singapore Sealants Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Sealants Market Analytics
Advanced low-VOC silicone chemistry is reshaping specification standards across Singapore's commercial construction sector. Sika AG leverages its regional formulation centers to sustain technical service proximity to major infrastructure tenders. Henkel AG & Co. KGaA anchors its position through specialized adhesive-sealant hybrid portfolios targeting electronics manufacturing clients in the city-state. Dow competes on silicone feedstock integration, extending cost advantages into high-performance glazing applications for tropical climates.
Sealants are elastomeric compounds formulated from silicone, polyurethane, acrylic, or butyl polymers that cure to form flexible, impermeable barriers between substrates; silicone variants typically achieve Shore A hardness of 20-40 and elongation at break exceeding 400%, making them essential for joint movement accommodation in curtain wall systems and waterproofing assemblies. Silicone sealants dominate value capture due to their UV stability and 25-year service life in equatorial exposure conditions, while polyurethane sealants represent the fastest-growing product category driven by demand from marine and industrial maintenance applications. Construction applications absorb the majority of volume, though electronics OEM demand for precision dispensing grades is expanding rapidly as semiconductor packaging operations scale locally.
Singapore's Building and Construction Authority mandates Green Mark certification for new developments, directly elevating demand for low-emission sealant formulations that meet stringent indoor air quality protocols. The country's national environmental regulator enforces hazardous substances controls aligned with REACH principles, restricting certain isocyanate and solvent chemistries in polyurethane and acrylic product lines. BIS-equivalent material standards administered by Enterprise Singapore govern import conformity, shaping competitive access for multinational suppliers. Stakeholders must monitor evolving green building code tiers and biocide registration requirements to anticipate specification shifts in public-sector procurement.
Market Dynamics
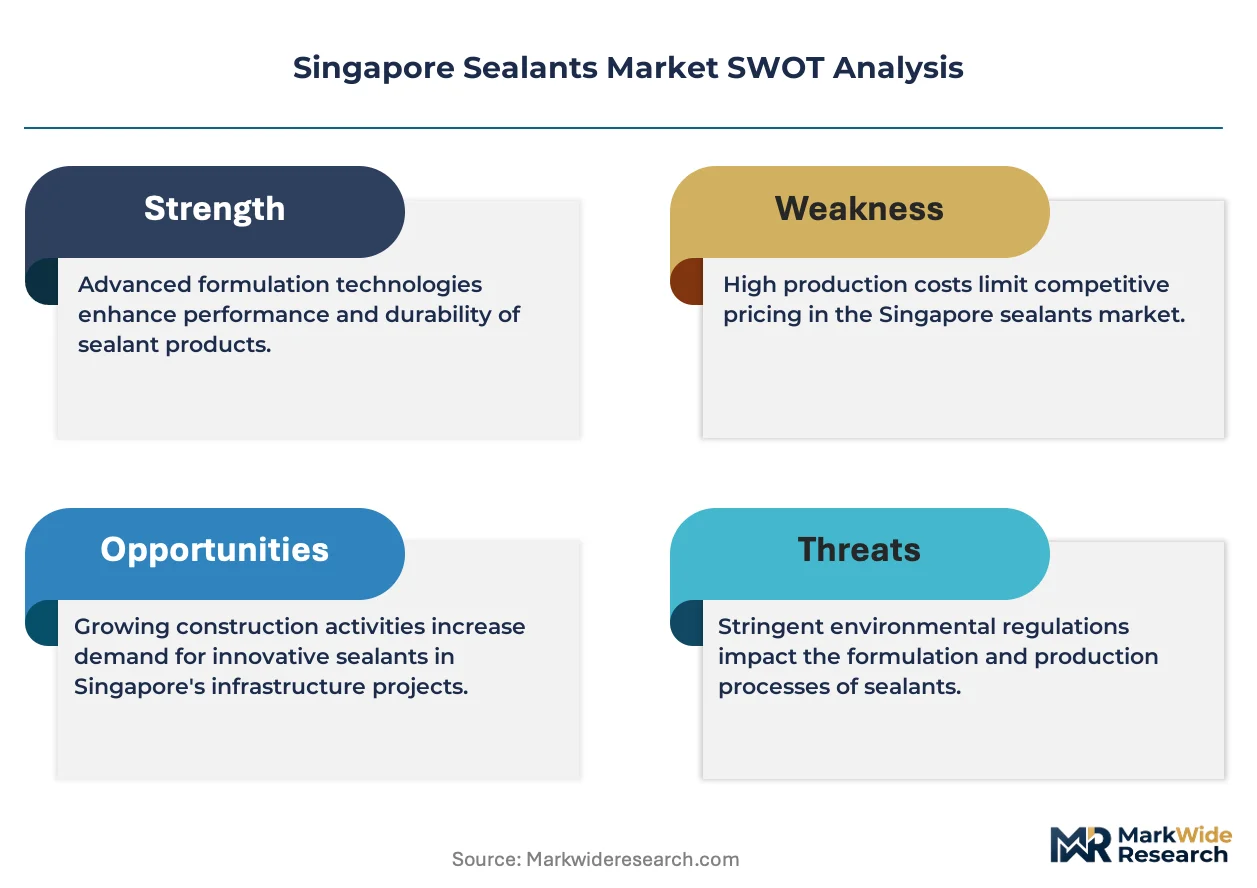
Green Mark certification tiers from Singapore's Building and Construction Authority are compressing specification windows for sealant suppliers, forcing rapid reformulation of silicone and polyurethane portfolios to meet indoor air quality thresholds in commercial high-rise tenders.
Growth Catalysts
- Green Mark Platinum mandates:Singapore's Building and Construction Authority requires top-tier certification for new commercial developments, elevating demand for low-VOC silicone formulations in curtain wall applications.
- Semiconductor packaging expansion:Precision dispensing grades are capturing new volume as electronics OEMs scale advanced packaging operations in the city-state's wafer fabrication parks.
- Marine maintenance cycles:Polyurethane sealants are displacing conventional coatings in shipyard repair workflows across Tuas and Jurong Port facilities.
Market Restraints
- Silicone feedstock concentration:Dow and Wacker control regional organosilicon supply, exposing formulators to monomer price volatility and allocation constraints.
- Isocyanate hazard restrictions:Singapore's national environmental regulator limits certain polyurethane precursors under REACH-aligned hazardous substances controls, complicating import compliance.
- Acrylic UV degradation:Acrylic sealants suffer accelerated chalking and elastomeric failure in equatorial UV exposure, restricting their specification to interior applications.
Strategic Opportunities
- Jurong Lake District precinct buildout:Mixed-use development clusters are creating concentrated demand for high-movement joint sealants in integrated transport and residential towers.
- Biocide-free formulations:Enterprise Singapore's evolving registration requirements for fungicidal additives are opening first-mover advantage for suppliers with compliant hybrid chemistries.
- Electronics OEM direct contracting:Semiconductor fabricators are bypassing traditional distributor channels for precision-grade supply agreements with technical service attachments.
Industry Challenges
- Formulation chemist scarcity:Singapore's tight labor market for specialized polymer scientists is extending R&D cycle times for Green Mark-compliant product launches.
- Multi-certification stacking:Suppliers must synchronize BIS-equivalent material standards, biocide registrations, and project-specific indoor air quality testing, compressing margin on public-sector tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Sealants Market |
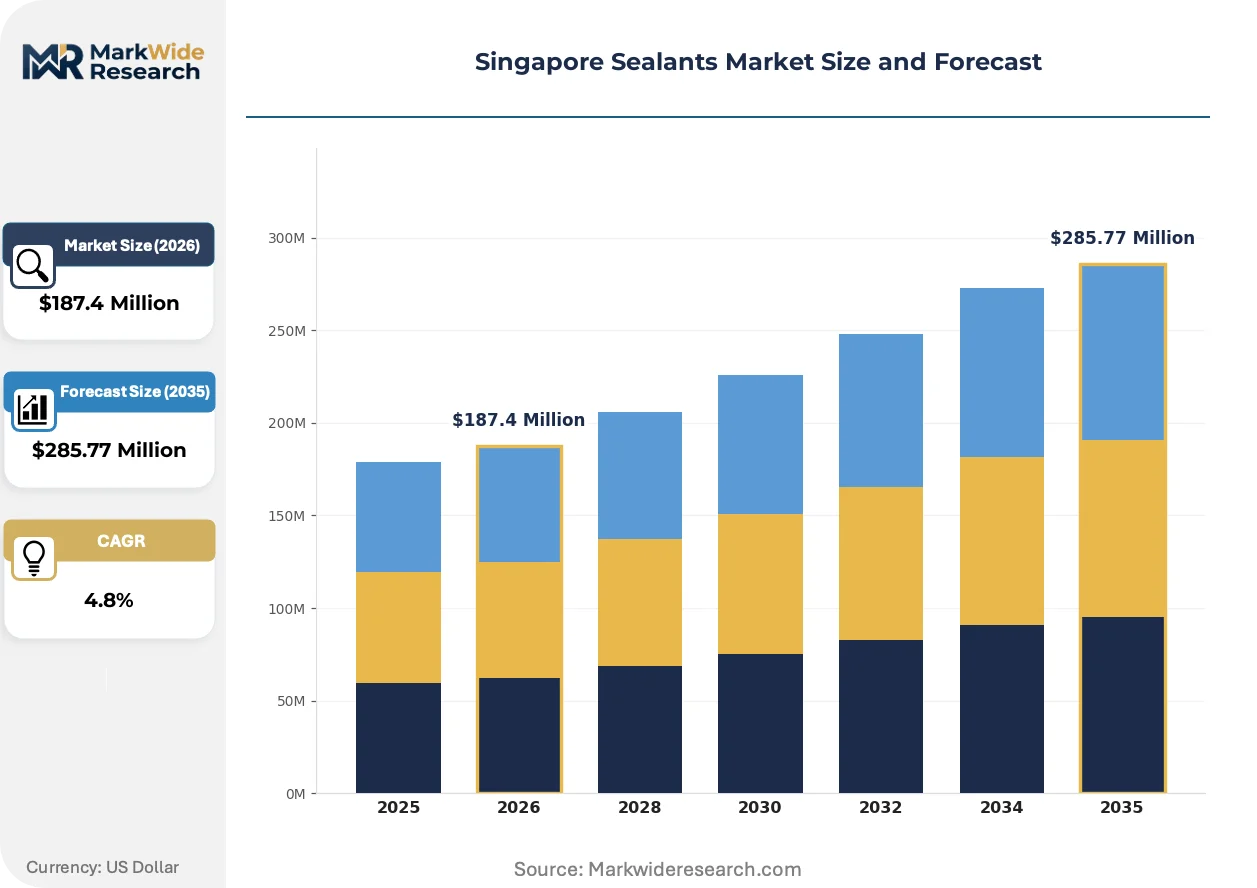
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silicone Sealants, Polyurethane Sealants, Acrylic Sealants, Butyl Sealants Application: Construction, Automotive, Electronics, Industrial End User: Contractors, OEMs, Retailers, Maintenance Providers Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | 3M, Sika AG, Henkel AG & Co. KGaA, Dow, H.B. Fuller, Mapei, Tremco Illbruck, Bostik, Shin-Etsu Chemical Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Sealants Market Evolving Landscape
Formulation chemistry is converging with digital specification tools and circular material mandates, compressing traditional product lifecycles while opening premium positioning for suppliers with verified environmental credentials.
Hybrid silicone-urethane chemistry is hybridizing performance characteristics for tropical glazing applications. Sika and regional formulators are deploying these intermediates in Marina Bay commercial towers where joint movement exceeds 35% and UV exposure demands 25-year service life. The technology is hybridizing procurement criteria, forcing specification engineers to abandon pure-type material categories.
Singapore's Building and Construction Authority tightened Green Mark 2021 standards, mandating third-party emission testing for all wet-applied sealants in new construction. This policy shift is disqualifying incumbent suppliers lacking ISO 16000 indoor air quality certification from public-sector tenders. High-rise commercial developers in the Central Business District are responding by pre-qualifying only two sealant vendors per project.
Contractor procurement teams are consolidating purchase authority into centralized technical procurement functions, displacing site-level material selection. This behavioral shift concentrates volume with distributors offering bonded inventory and same-day delivery to Jurong and Tuas construction clusters. The concentration is most visible in public housing authority projects where package bidding now bundles sealants with waterproofing membranes.
Singapore Sealants Market Segmentation
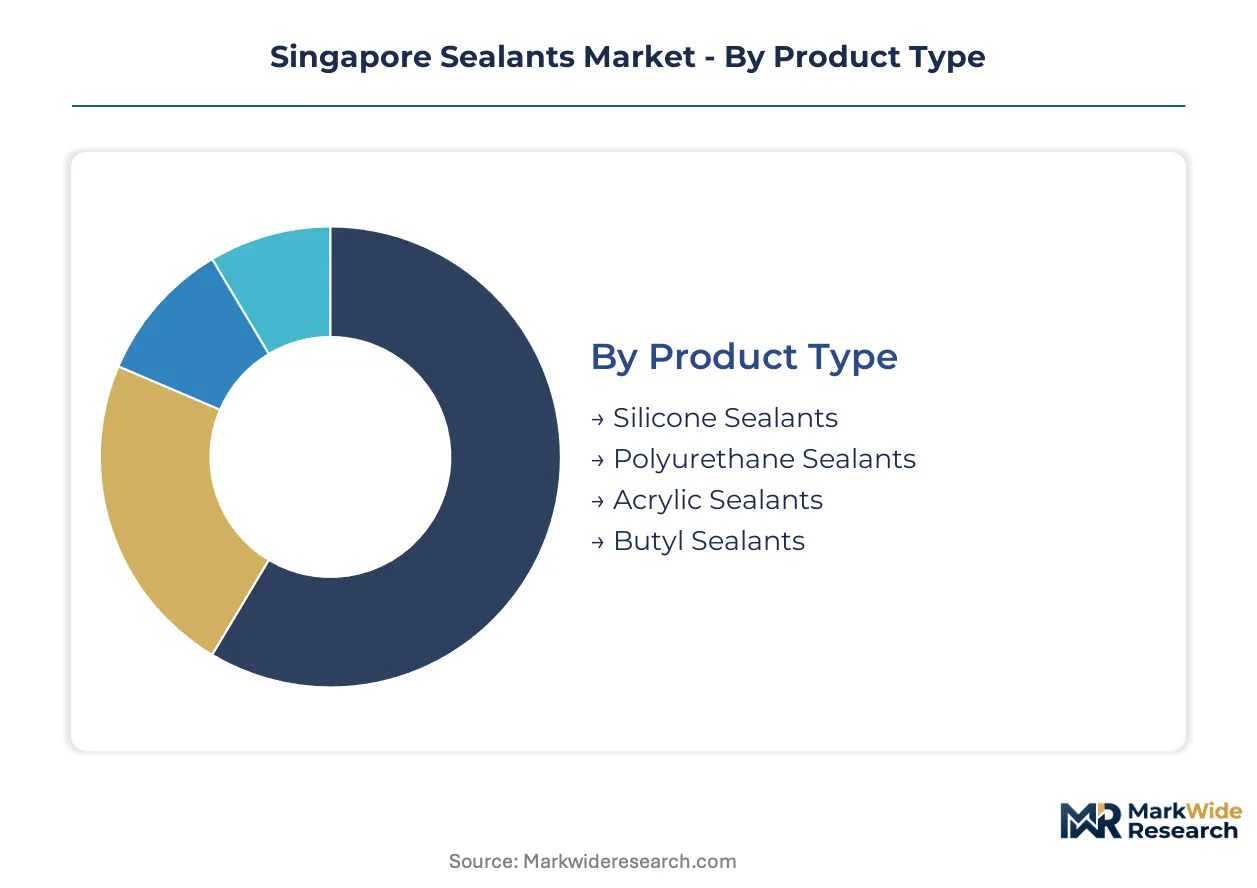
Segmentation in Singapore's sealants market reveals how procurement cycles and specification authority vary dramatically across product chemistries and end-use channels. Understanding these structural differences exposes where margin concentrates and where volume turns over fastest.
Product Type:
Silicone formulations command the longest replacement cycles due to tropical durability requirements, while polyurethane and acrylic alternatives turn over faster in maintenance-intensive applications.
- Silicone Sealants:Formulated from cross-linked polydimethylsiloxane polymers achieving Shore A hardness of 20-40 and elongation exceeding 400%. Demand concentrates in Marina Bay and Jurong Lake District commercial towers where Building and Construction Authority Green Mark Platinum mandates specify 25-year service life for curtain wall joints exposed to equatorial UV.
- Polyurethane Sealants:Isocyanate-terminated prepolymer systems offering superior abrasion resistance and paintability compared to silicone alternatives. Procurement is accelerating across Tuas and Jurong Port marine maintenance facilities where polyurethane is displacing conventional coatings in shipyard repair workflows subject to REACH-aligned hazardous substances controls.
- Acrylic Sealants:Water-based emulsion polymers restricted primarily to interior applications due to accelerated UV degradation and elastomeric failure under equatorial exposure.
- Butyl Sealants:Preformed tape and hot-applied formulations serving secondary glazing and metal roofing applications with limited movement accommodation.
Silicone Sealants dominate installed base. Polyurethane Sealants are where expansion concentrates.
Application:
Construction absorbs the majority of procurement volume through project-tied specifications, while Electronics and Industrial segments operate on fundamentally different replenishment rhythms driven by fabrication schedules.
- Construction:Curtain wall glazing, waterproofing membranes, and structural movement joints in high-rise commercial and residential towers. Specification authority has consolidated into centralized technical procurement functions at contractor headquarters serving Marina Bay and Jurong Lake District precincts.
- Electronics:Precision dispensing grades for semiconductor packaging operations in Singapore's wafer fabrication parks. OEMs are bypassing traditional distributor channels for direct supply agreements with technical service attachments.
- Automotive:Limited local assembly presence restricts demand primarily to aftermarket repair and imported vehicle finishing applications.
- Industrial:Marine maintenance, manufacturing equipment sealing, and infrastructure repair workflows across Tuas industrial zones.
Construction commands specification authority. Electronics is climbing the fastest as advanced packaging operations scale locally.
End User:
Contractors and OEMs operate on divergent procurement calendars, with contractors tied to project milestones and OEMs running continuous fabrication schedules.
- Contractors:Centralized technical procurement teams at major construction firms now control material selection previously delegated to site supervisors. Package bidding for public housing authority projects bundles sealants with waterproofing membranes.
- OEMs:Semiconductor fabricators and electronics manufacturers demanding precision-grade formulations with batch certification and same-day technical response.
- Retailers:Hardware stores and trade counters serving renovation contractors and maintenance trades with standard-grade silicone and acrylic products.
- Maintenance Providers:Facility management firms and specialized repair contractors executing cyclical refurbishment of commercial building envelopes.
Contractors dominate project-tied volume. OEMs are gaining share fastest through direct contracting bypass.
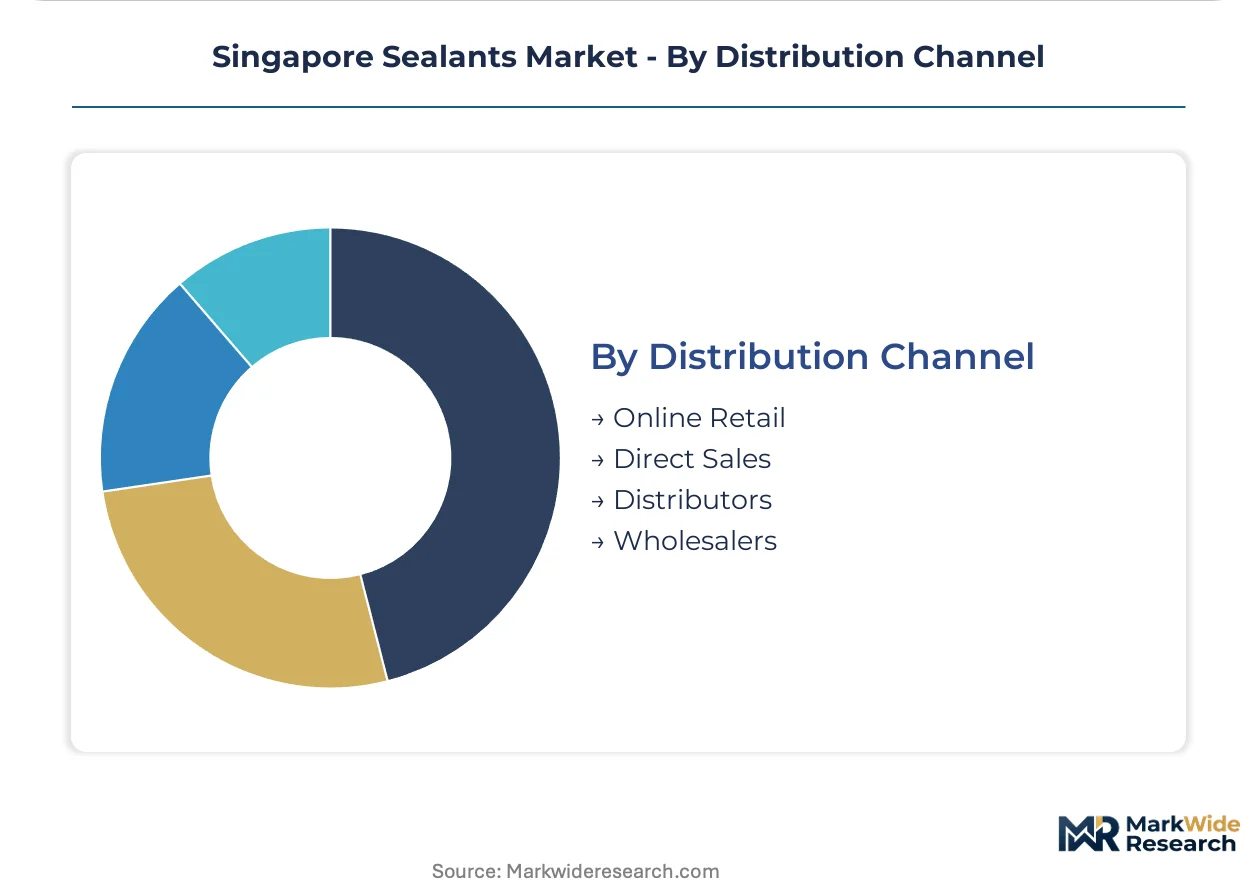
Distribution Channel:
Channel economics in Singapore reflect inventory carrying costs against delivery velocity requirements, with bonded stock and same-day fulfillment becoming decisive competitive factors.
- Distributors:Regional specialists maintaining bonded inventory and technical service capabilities proximate to Jurong and Tuas construction clusters. Concentration is most visible where contractor procurement has centralized.
- Direct Sales:Multinational suppliers serving Electronics OEMs and major infrastructure tenders through dedicated account teams with formulation center backing.
- Online Retail:Emerging channel for standardized grades among smaller contractors and maintenance trades, constrained by technical specification requirements for Green Mark-compliant projects.
- Wholesalers:Volume aggregators supplying retailers and smaller distributors with limited technical service attachment.
Distributors dominate construction procurement. Direct Sales is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian sealant exports flow into Singapore's construction pipeline, supplying contractors executing Marina Bay and Jurong Lake District precinct developments. This trade corridor reflects broader ASEAN chemical specialization patterns.
Central Region
Marina Bay commercial towers concentrate specification-grade silicone demand under Building and Construction Authority Green Mark Platinum mandates. The precinct's curtain wall contractors pre-qualify vendors based on ISO 16000 indoor air quality certification. Joint movement requirements exceeding 35% strain favor high-elongation formulations.
Jurong Lake District
Mixed-use transport and residential clusters are scaling procurement of high-movement joint sealants. Enterprise Singapore's biocide registration requirements are reshaping supplier compliance burdens. Technical procurement teams at contractor headquarters now control material selection previously delegated to site supervisors.
Tuas Industrial Zone
Marine maintenance facilities are accelerating polyurethane sealant procurement for shipyard repair workflows. REACH-aligned hazardous substances controls from the national environmental regulator restrict certain isocyanate precursors. Polyurethane formulations are displacing conventional coatings in cyclical refurbishment schedules.
Western Water Catchment
Wafer fabrication parks in this corridor are scaling precision dispensing grade demand for semiconductor packaging operations. Electronics OEMs are bypassing traditional distributor channels for direct supply agreements with technical service attachments. Batch certification and same-day technical response are becoming standard procurement criteria.
Singapore Sealants Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Singapore's procurement landscape. Distributors maintaining bonded inventory near Jurong and Tuas construction clusters capture contractor volume through same-day fulfillment capabilities. Three archetypes dominate: multinational chemical conglomerates with regional formulation centers, specialized adhesive-sealant hybrid suppliers, and regional distributors with technical service attachments. Competitive moves concentrate on centralized procurement relationship-building and Green Mark compliance certification stacking.
Among multinational suppliers, Sika AG, Henkel AG & Co. KGaA, and Dow occupy positions aligned with distinct technical service and feedstock integration strategies. Sika exemplifies the regional formulation center archetype, anchoring proximity to major infrastructure tenders. Henkel represents specialized adhesive-sealant hybrid positioning. Dow sits within the silicone feedstock integration tier, extending cost advantages into tropical climate applications.
| Leading Market Players |
|---|
| 3M |
| Sika AG |
| Henkel AG & Co. KGaA |
| Dow |
| H.B. Fuller |
| Mapei |
| Tremco Illbruck |
| Bostik |
| Shin-Etsu Chemical Co., Ltd. |
| Others |
Value Network & Pricing Analysis
The Tuas-Jurong Port freight corridor funnels Malaysian and Thai chemical feedstock into Singapore's sealant manufacturing nodes, with logistics cost dynamics amplifying the pricing power held by Dow and Wacker in organosilicon supply while compressing margins for downstream formulators serving price-sensitive contractor procurement.
Pricing Analysis
Next-generation low-VOC silicone formulations command 15-25% premiums over conventional high-VOC grades, while prior-generation solvent-based acrylics trade at distressed levels due to Green Mark disqualification. Pricing stratifies across Green Mark Platinum-certified premium tiers, BIS-equivalent standard grades, and uncertified economy tiers for interior maintenance. Cost compression in the standard tier intensifies as contractor procurement centralization squeezes distributor markups. Public housing authority contractors exhibit highest price sensitivity due to package bidding structures, while semiconductor OEMs prioritize technical service over unit cost.
Supply Chain Analysis
Regional contract manufacturing capacity concentrates with Sika's Jurong formulation center, Henkel's Singapore technical hub, and Dow's ASEAN silicone compounding facilities. Raw material sourcing draws from Malaysian petrochemical complexes for polyurethane precursors, Thai specialty chemical producers for silicone intermediates, and Chinese manufacturers for acrylic emulsion polymers. Single-source vulnerability in organosilicon monomer supply exposes formulators to allocation constraints during demand spikes. Distribution runs through bonded inventory specialists maintaining same-day fulfillment to Jurong and Tuas construction clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Singapore's sealants market sits in early-cycle expansion, with Green Mark 2021 tier upgrades and semiconductor packaging localization providing sustained adoption tailwinds through the projection horizon.
For Market Incumbents: Pre-empt biocide-free formulation registration to capture first-mover positioning ahead of Enterprise Singapore's evolving fungicidal additive requirements. Anchor technical service teams at Jurong Lake District precinct developments to defend specification authority against hybrid chemistry entrants. Backward integration into silicone feedstock partnerships with Dow or Wacker mitigates monomer allocation risk. For New Entrants and Emerging Players: Tuas marine maintenance facilities represent underpenetrated demand for REACH-compliant polyurethane alternatives to conventional coatings. Electronics OEM direct contracting channels offer white-space access as semiconductor fabricators bypass traditional distributors. Lead with precision dispensing technical service capabilities and batch certification speed to differentiate against established construction-focused suppliers. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational chemical conglomerates seeking to divest non-core sealant portfolios lacking Green Mark certification infrastructure. Long-term viability centers on compliance-capable formulation assets with regional technical service density. Monitor biocide registration timelines and Green Mark tier evolution as inflection signals for specification authority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Green Mark Certification Investment | ISO 16000 indoor air quality certification unlocks public-sector tender access under BCA mandates. |
| Biocide-Free Formulation Development | Enterprise Singapore registration requirements favor early movers with compliant hybrid chemistries. |
| Electronics OEM Direct Contracting | Bypassing distributor channels captures precision dispensing volume from wafer fabrication parks. |
| Bonded Inventory Proximity | Same-day fulfillment to Jurong and Tuas clusters wins centralized contractor procurement. |
| Hybrid Silicone-Urethane R&D | Marina Bay high-movement joint specifications favor intermediates exceeding 35% elongation. |
Research Methodology
A standing panel of sealant formulators, contractor procurement directors, and Building and Construction Authority specification engineers provided ongoing calibration against secondary validation from customs trade data, Enterprise Singapore biocide registration filings, and BCA Green Mark certification databases. Primary interviews with distributor technical service heads and electronics OEM supply chain managers combined with SEC 10-K disclosures from multinational chemical suppliers. Bottom-up volume estimates from construction project pipelines and semiconductor fabrication capacity expansions triangulated against top-down chemical consumption models.
Scenario-bracketing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product chemistry, application channel, and certification tier. CAGRs derived from elasticity-adjusted demand curves incorporating Green Mark adoption rates and electronics packaging localization trends. Forecast inputs included BCA public housing authority tender schedules and wafer fabrication park expansion timelines.
Practitioners should monitor BCA Green Mark tier revisions and Enterprise Singapore biocide registration deadlines for early signals of specification shifts. Quarterly review of contractor procurement centralization metrics and semiconductor OEM channel bypass rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
Deoiler Chemicals Market
Industrial Chemicals
Pickling Chemicals Market
Industrial Chemicals
Industrial Phenol Market
Industrial Chemicals
Lignin Market
Industrial Chemicals
Dimethylacetamide (Dmac) Market
Industrial Chemicals
Thermic Fluids Market
Industrial Chemicals
Carbamate Insecticides Market
Industrial Chemicals
Global Bio Based Isoprene Market
Industrial Chemicals
North America Paper Machine Oil Market
Industrial Chemicals
Global Plating on Plastics Market
Industrial Chemicals
Global Continuous Stirred Tank Reactors Market
Industrial Chemicals
Global Molluscicides Market
Industrial Chemicals
Fluorine-Based Plasma Surface Treatment Machine for Leather Market
Industrial Chemicals
Liquid Electrolyte Market
Industrial Chemicals
Glycidyl Ether Market
Industrial Chemicals
Mining Chemicals Market