
 Thermoplastic Micro Molding Market | 2026-2036
Thermoplastic Micro Molding Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Micro Molding Market Outlook
Asset-light leasing arrangements for multi-cavity micro-molding tooling is tilting competitive dynamics toward mid-tier processors that previously faced capital barriers. Accumold leverages captive toolmaking to sustain rapid prototyping cycles for medical device clients. MTD Micro Molding anchors its position through deep specialization in bioabsorbable polymer micro-molding. Makuta Technics Inc competes via high-speed automation integration across its Asian manufacturing footprint.
Thermoplastic micro molding produces precision components with feature sizes below 1 millimeter using engineered polymers injected at high pressure into specialized tooling. The process demands exacting control of melt temperature, injection velocity, and cooling rates to achieve dimensional stability in parts weighing fractions of a gram. Medical Devices dominates value generation among product type segments, driven by stringent cleanliness requirements and long-term supply agreements with healthcare OEMs. Polypropylene leads material consumption volume due to its chemical resistance and favorable flow characteristics in thin-wall geometries, while polycarbonate commands premium positioning in optical applications requiring light transmission precision.
FDA quality system regulations and EU MDR technical documentation requirements shape validation protocols and traceability standards across the supply chain. ISO 13485 certification functions as a de facto market access threshold for molders targeting regulated medical end users. REACH substance restrictions influence material selection for European-bound components, particularly where phthalate-free formulations face compliance scrutiny. Stakeholders must monitor evolving biocompatibility testing standards and polymer recycling mandates that will determine which material platforms retain commercial viability across the next technology cycle.
Market Dynamics
Medical device OEMs are consolidating supplier relationships around molders with captive ISO 13485 certification and validated cleanroom operations, compressing procurement cycles for micro-molded surgical components.
Growth Catalysts
- EU MDR technical documentation mandates:Device manufacturers must demonstrate full polymer traceability and biocompatibility testing, favoring molders with established quality management systems over commodity processors.
- Minimally invasive surgical instrument proliferation:Laparoscopic and robotic surgery platforms require micro-molded polymer components with sub-millimeter feature resolution, driving specialized tooling investments.
- Polypropylene thin-wall flow optimization:Advances in high-flow nucleated grades enable 0.3mm wall thicknesses in drug delivery devices, expanding addressable applications in injectable medicine systems.
Market Restraints
- Multi-cavity steel tooling capex concentration:Precision micro-molds for medical applications require hardened tool steels and wire EDM finishing, with single tools exceeding capital thresholds that exclude smaller processors.
- Specialized polymer supply concentration:Medical-grade polycarbonate and bioabsorbable PLA/PLGA compounds depend on a limited base of compounders with FDA master file documentation, creating single-source vulnerability.
- REACH substance restriction compliance friction:Phthalate-free plasticizer transitions and emerging PFAS scrutiny force reformulation cycles that delay European market entry for new device programs.
Strategic Opportunities
- India medical device manufacturing expansion:CDSCO regulatory harmonization with IMDRF standards and PLI scheme incentives for domestic production create first-mover advantage for molders establishing Bengaluru or Hyderabad operations.
- Implantable bioabsorbable polymer convergence:Combination drug-device products using micro-molded PLGA scaffolds with API integration open orthopedic and cardiovascular application white space.
- Asset-light tooling lease channels:Third-party tool ownership models reduce capital barriers for mid-tier processors serving diagnostic device startups with variable volume forecasts.
Industry Challenges
- Micro-molding process technician scarcity:Operating high-speed electric presses with cavity pressure sensors and scientific molding protocols requires specialized training pipelines that few technical institutes currently offer.
- ISO 13485 certification timeline compression:Notified body backlogs and documentation requirements extend validation cycles, delaying revenue recognition for new medical device contracts.
- Legacy ERP integration with serialization mandates:FDA UDI and EU MDR traceability requirements force middleware investments to connect shop-floor molding data with enterprise quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Micro Molding Market |
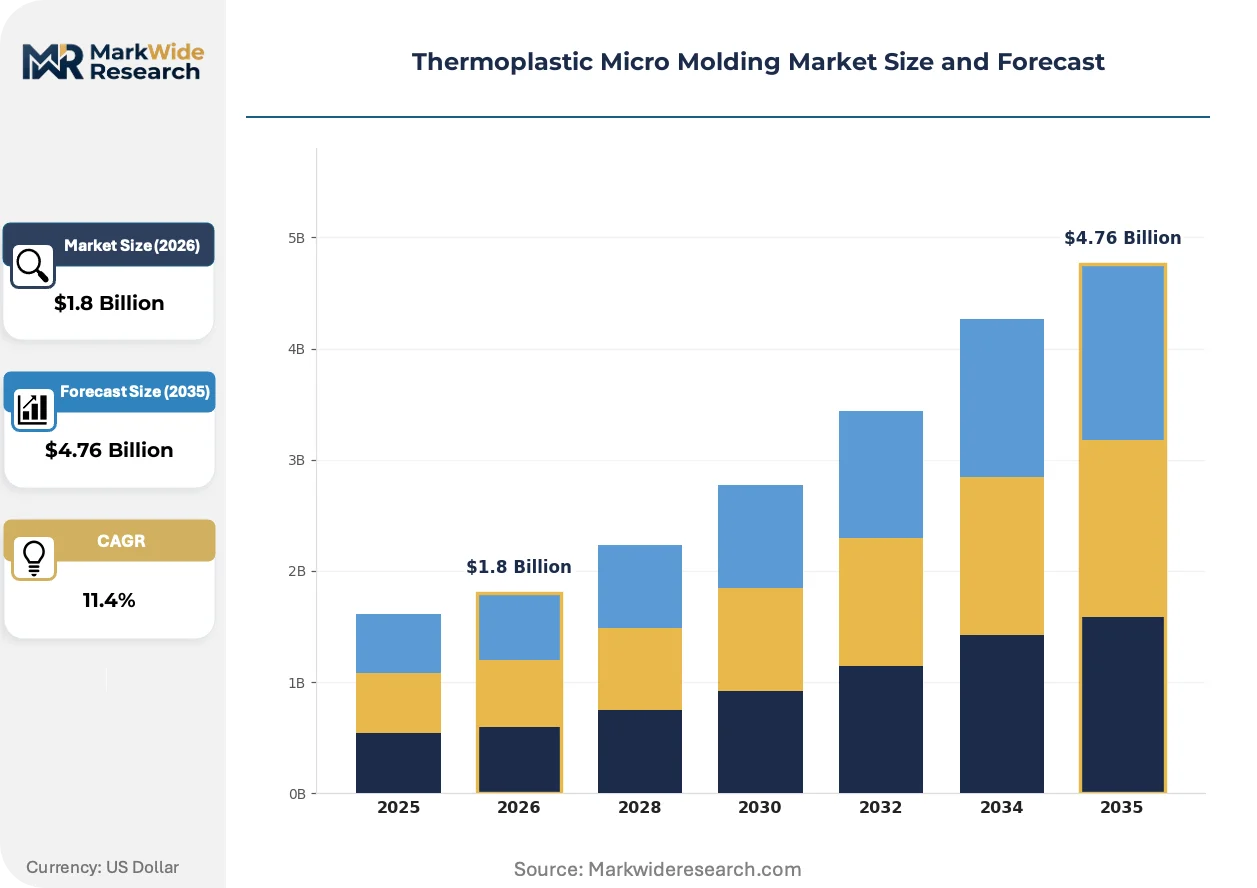
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Medical Devices, Automotive Components, Consumer Electronics, Industrial Equipment Material: PVC, Polycarbonate, Polypropylene, Polystyrene Application: Biomedical, Optics, Connectors, Sensors End User: Healthcare, Automotive, Electronics, Telecom |
| Companies Covered | Accumold, MTD Micro Molding, Makuta Technics Inc, Stack Plastics, SMC Corporation, Isometric Micro Molding Inc, American Precision Products, ACCU Mold LLC, Stamm AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Micro Molding Market Strategic Shifts
Process control systems and polymer formulation science are converging to enable sub-gram precision components at production scales previously confined to prototype volumes.
Scientific molding platforms with integrated cavity pressure transducers and real-time viscosity compensation are digitizing quality assurance for medical micro-components. Tier-one device manufacturers in Germany and Switzerland are adopting these systems to eliminate offline inspection bottlenecks. The technology is digitizing the feedback loop between melt preparation and dimensional stability, compressing validation timelines for FDA submission packages.
REACH Annex XVII expansion on intentionally added microplastics is forcing polymer selection reviews for European-bound diagnostic consumables. Compounders must now document biodegradation pathways and environmental fate data for materials used in single-use devices. Diagnostic OEMs with distributed European manufacturing are consolidating specification control to minimize multi-site compliance overhead.
Consignment inventory arrangements are displacing traditional purchase-order procurement for high-volume drug delivery devices. Device manufacturers in Massachusetts and Minnesota are transferring mold ownership to processors while retaining cavity design control, converting fixed tooling costs to variable unit economics. This model concentrates most visibly in diabetes care and auto-injector platforms where demand volatility rewards supply chain flexibility.
Thermoplastic Micro Molding Market Segmentation
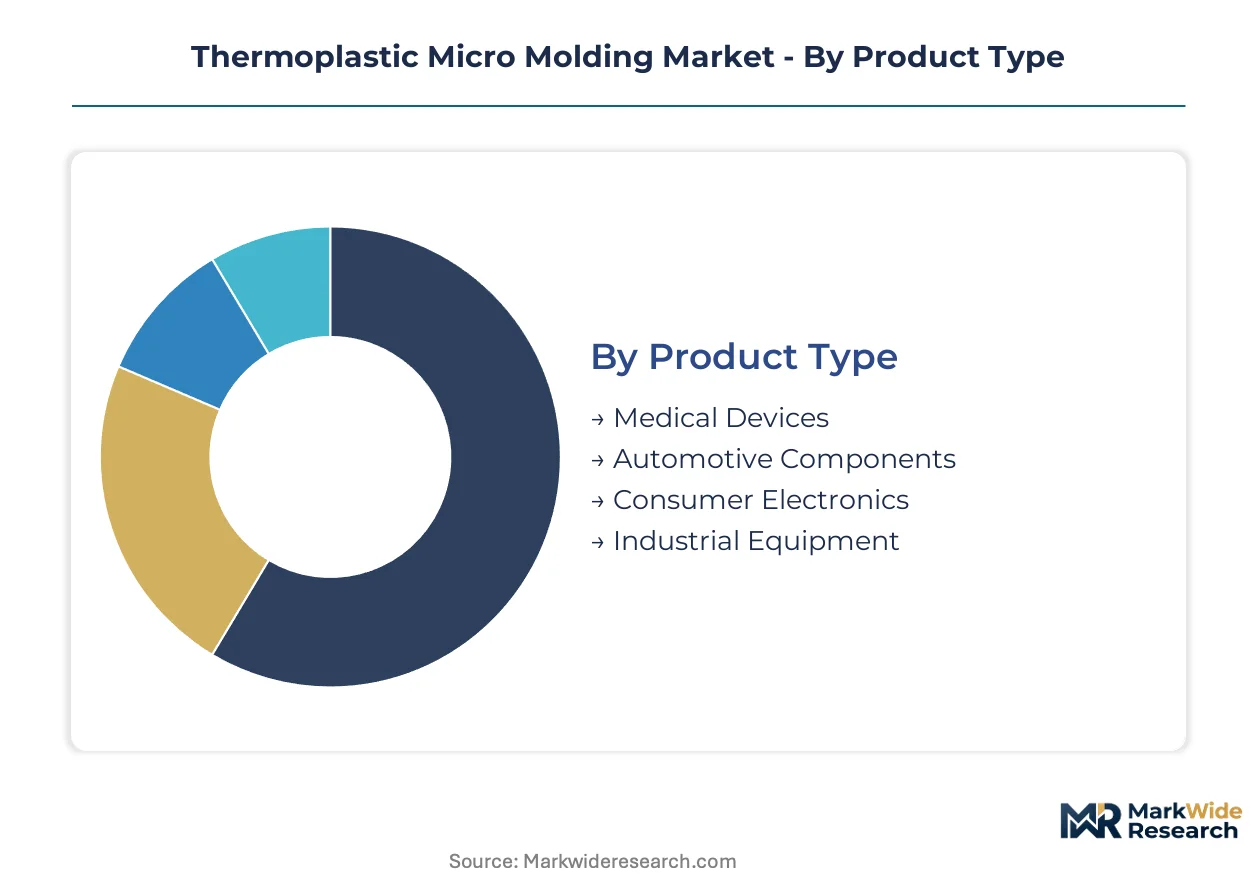
Segmentation in thermoplastic micro molding reveals how capital intensity and regulatory validation requirements concentrate value across distinct material, application, and end-use boundaries. Procurement patterns diverge sharply between medical device OEMs demanding ISO 13485-certified supply chains and automotive buyers prioritizing high-volume cost efficiency.
Product Type:
Cycle times vary dramatically across product categories, with diagnostic consumables turning inventory weekly while implantable surgical components remain in validation queues for months.
- Medical Devices:Micro-molded components for minimally invasive instruments and drug delivery systems command premium positioning through FDA master file requirements and long-term supply agreements. Demand concentrates in German precision engineering clusters around Stuttgart and Munich, where medical technology OEMs consolidate procurement around molders with captive cleanroom operations and validated sterilization protocols.
- Automotive Components:Precision connectors and sensor housings for electric vehicle powertrains leverage polypropylene thin-wall capabilities in high-cavity tooling configurations. Expansion concentrates in Asian manufacturing footprints where Makuta Technics integrates high-speed automation to achieve unit economics competitive with conventional precision machining.
- Consumer Electronics:Miniature structural components for wearables and hearables prioritize rapid prototyping cycles over validation depth.
- Industrial Equipment:Fluidic manifolds and micro-valve bodies serve analytical instrumentation with moderate regulatory overhead.
Medical Devices dominates installed base. Automotive Components is where expansion concentrates.
Material:
Material selection stratifies processors by technical capability, with medical-grade compounders commanding margins three to four times above commodity resin distributors.
- Polypropylene:High-flow nucleated grades enable 0.3mm wall thicknesses in drug delivery devices through optimized shear heating profiles and rapid cooling channel design. Demand clusters in Massachusetts and Minnesota diabetes care manufacturing, where consignment inventory arrangements convert fixed tooling costs to variable unit economics.
- Polycarbonate:Optical-grade formulations with light transmission precision above 90% serve diagnostic imaging and surgical navigation systems. European REACH Annex XVII scrutiny on intentionally added microplastics forces compounders to document biodegradation pathways, consolidating specification control among FDA master file holders.
- PVC:Phthalate-free plasticizer transitions face compliance friction delaying European market entry.
- Polystyrene:Crystal and high-impact grades serve cost-sensitive diagnostic consumables with limited regulatory exposure.
Polypropylene anchors volume throughput. Polycarbonate captures margin expansion.
Application:
Application complexity determines validation burden, with implantable scaffolds requiring biocompatibility testing cycles an order of magnitude longer than passive optical components.
- Biomedical:Bioabsorbable PLGA scaffolds with API integration for orthopedic and cardiovascular combination products represent the steepest expansion trajectory. MTD Micro Molding anchors positioning through deep specialization in this white space, leveraging polymer science partnerships to accelerate degradation profile customization.
- Optics:Micro-lens arrays and light guides for surgical illumination and diagnostic imaging demand sub-micron surface finish control through scientific molding platforms with real-time viscosity compensation. German and Swiss tier-one device manufacturers adopt these systems to eliminate offline inspection bottlenecks.
- Connectors:High-density electrical interfaces for robotic surgery platforms require plated polymer metallization compatibility.
- Sensors:Miniature pressure and flow transducer housings integrate cavity pressure transducer feedback for dimensional stability.
Biomedical commands development resources. Optics scales production efficiency.
End User:
End-user concentration shapes geographic facility placement, with healthcare procurement consolidating around regulatory harmonization zones while automotive chases labor arbitrage.
- Healthcare:Device manufacturers in Germany, Switzerland, and the US consolidate supplier relationships around molders with captive ISO 13485 certification, compressing procurement cycles for micro-molded surgical components. EU MDR technical documentation mandates and FDA quality system regulations function as de facto market access thresholds.
- Automotive:Electric vehicle powertrain sensor demand concentrates in Asian manufacturing corridors where high-speed automation integration achieves throughput volumes incompatible with medical validation timelines.
- Electronics:Wearable and hearable OEMs prioritize rapid prototyping partnerships over long-term supply agreements.
- Telecom:Fiber optic connector demand fluctuates with infrastructure deployment cycles, rewarding flexible capacity arrangements.
Healthcare locks in contract duration. Automotive drives capacity utilization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government incentives for domestic medical device manufacturing are redirecting investment flows across major precision molding corridors. CDSCO regulatory harmonization in India, PLI scheme extensions, and FDA master file documentation requirements collectively reshape facility placement decisions for micro-molding capacity.
United States
Diabetes care OEMs in Massachusetts and Minnesota are consolidating procurement around molders with captive ISO 13485 certification. FDA quality system regulations and UDI traceability mandates compress supplier qualification timelines. Device manufacturers in these states increasingly favor consignment inventory arrangements that convert fixed tooling costs to variable unit economics.
Germany
Precision engineering clusters around Stuttgart and Munich anchor European medical technology supply chains for micro-molded surgical components. EU MDR technical documentation requirements and REACH Annex XVII scrutiny on intentionally added microplastics accelerate validation investments. Tier-one device manufacturers in these regions adopt scientific molding platforms with real-time viscosity compensation to eliminate offline inspection bottlenecks.
India
CDSCO regulatory harmonization with IMDRF standards and PLI scheme incentives for domestic production create first-mover advantage for molders establishing Bengaluru or Hyderabad operations. Diagnostic device startups with variable volume forecasts drive demand for asset-light tooling lease channels. The country's central pharmaceutical regulator is tightening biocompatibility testing standards for polymer-based medical devices.
Switzerland
Swissmedic certification requirements and proximity to German precision engineering networks position the country as a high-margin medical micro-molding hub. Optical-grade polycarbonate applications for surgical navigation systems concentrate around Basel and Zurich. Manufacturers leverage scientific molding digitization to compress FDA submission package timelines for combination drug-device products.
Japan
PMDA quality management system requirements and METI industrial policy support precision polymer processing for minimally invasive surgical instruments. High-speed automation integration in manufacturing corridors serves robotic surgery platform OEMs. Domestic compounders with FDA master file documentation supply medical-grade polycarbonate for diagnostic imaging applications requiring light transmission precision above 90 percent.
Thermoplastic Micro Molding Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented supply tiers. The vendor base separates into molders with captive toolmaking capabilities, processors leveraging high-speed automation integration, and specialists in bioabsorbable polymer formulations. Two strategic archetypes dominate: vertically integrated precision engineering groups and asset-light mid-tier processors serving diagnostic startups. Competitive moves concentrate on strategic partnerships for polymer science collaboration and geographic expansion into regulatory harmonization zones.
Within the medical-specialist tier, Accumold and MTD Micro Molding exemplify divergent positioning archetypes. Accumold represents the captive toolmaking model that sustains rapid prototyping cycles, while MTD Micro Molding anchors positioning through deep specialization in bioabsorbable polymer micro-molding. Makuta Technics Inc occupies a position at the automation-integrated end of the spectrum, with high-speed manufacturing footprints serving cost-sensitive volume applications. These three entities collectively illustrate how competitive advantage segments across tooling control, material science depth, and production velocity.
| Leading Market Players |
|---|
| Accumold |
| MTD Micro Molding |
| Makuta Technics Inc |
| Stack Plastics |
| SMC Corporation |
| Isometric Micro Molding Inc |
| American Precision Products |
| ACCU Mold LLC |
| Stamm AG |
| Others |
Value Chain & Pricing Dynamics
Stuttgart's precision engineering cluster concentrates multi-cavity micro-mold tooling capacity, translating hardened steel scarcity into pricing power for ISO 13485-certified molders serving German medical device OEMs.
Pricing Analysis
Certification level creates the primary spread between medical-grade processors and commodity molders. Three-tier pricing structure across FDA master file holders, ISO 13485-certified suppliers, and uncertified generalists reflects validation depth. Cost compression in the uncertified tier is intensifying because diagnostic startups demand asset-light tooling leases. Automotive buyers in Asian manufacturing corridors exhibit highest price sensitivity, while Swiss and German healthcare OEMs prioritize traceability over unit cost.
Supply Chain Analysis
Export control regimes on wire EDM finishing equipment and hardened tool steel alloys limit technology transfer to emerging manufacturing hubs. Supply concentrates in Germany, Switzerland, and Japan for medical-grade polycarbonate and bioabsorbable PLGA compounds. The chain draws from FDA master file compounders, precision tool steel foundries, and high-flow nucleated polypropylene resin specialists. Single-source vulnerability in medical-grade polymer compounding creates structural risk. Distribution runs through consignment inventory arrangements that convert fixed tooling costs to variable unit economics for diabetes care OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scientific molding platforms with real-time cavity pressure feedback are creating platform-economics inflection, as interoperability between melt preparation systems and enterprise quality software compresses FDA submission timelines.
For Market Incumbents: Insulate positioning through captive bioabsorbable polymer formulation capabilities and backward integration into wire EDM toolmaking. Accumold's rapid prototyping model demonstrates how tool ownership control defends against asset-light lease channels eroding margin. Prioritize Swissmedic and FDA dual-certification investments to lock out mid-tier processors from combination drug-device contracts. For New Entrants and Emerging Players: CDSCO-harmonized diagnostic device manufacturing in Bengaluru and Hyderabad represents the most penetrable entry point, given PLI scheme incentives and variable volume demand from startups. Bioabsorbable scaffold applications for orthopedic combination products offer white-space positioning away from established polycarbonate optical component suppliers. Pursue polymer science partnerships with academic medical centers to accelerate degradation profile customization without captive R&D infrastructure. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-moat play because EU MDR and FDA quality system requirements are extending validation timelines beyond capital-constrained competitors' endurance. Target molders with existing ISO 13485 certification and cleanroom operations in regulatory harmonization zones rather than greenfield capacity. Watch for CDSCO biocompatibility testing standard tightening as the signal for India's market access threshold hardening.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Bioabsorbable Polymer Formulation | Enables orthopedic and cardiovascular scaffold customization with API integration for combination products. |
| Scientific Molding Platform Integration | Eliminates offline inspection bottlenecks for German and Swiss tier-one surgical navigation OEMs. |
| CDSCO Regulatory Harmonization Positioning | Captures PLI scheme incentives before India's biocompatibility testing standards tighten. |
| Consignment Inventory Arrangements | Converts fixed multi-cavity tooling costs to variable unit economics for diabetes care manufacturers. |
| Wire EDM Toolmaking Backward Integration | Protects rapid prototyping cycles from export control friction on precision finishing equipment. |
Study Parameters
Desk research of FDA master file databases, EU MDR technical documentation repositories, and polymer compounder regulatory filings preceded structured interviews with biomedical engineers, GPO contracts managers, micro-molding process technicians, and diagnostic device procurement leads. Primary fieldwork across German precision engineering clusters, Massachusetts diabetes care manufacturing corridors, and Bengaluru medical device zones combined with customs trade data and SEC filings from publicly held precision polymer processors. Bottom-up capacity modeling triangulated against top-down healthcare OEM procurement spend analysis.
Assumptions held fixed include current EU MDR and FDA quality system regulatory frameworks, REACH Annex XVII substance restrictions, and existing polymer compounding capacity configurations across the projection horizon. Segmentation dimensions modeled encompass product type, material grade tier, application complexity, and end-user regulatory cluster. CAGRs derived from elasticity-adjusted demand projections for minimally invasive surgical instrument proliferation and bioabsorbable scaffold adoption. Forecast inputs incorporated cavity pressure sensor penetration rates and cleanroom validation timeline compression.
Practitioners should monitor CDSCO biocompatibility testing standard evolution, REACH microplastics restriction expansion, and FDA UDI serialization mandate enforcement for early signals. Forecasts reflect these documented assumptions. Material shifts in export control classification for wire EDM finishing equipment or hardened tool steel alloys would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
EVA Resins and Films Market
Polymers & Resins
Global Linear Low Density Polyethylene Market
Polymers & Resins
Polysiloxane Market
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Virgin Resin Market
Polymers & Resins
High-Density Polyethylene (HDPE) Resins Market
Polymers & Resins
Calendering Resins Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Polymers for Electric Vehicle (EV) Market
Polymers & Resins
Europe Polyurethane Market