
 Medical Polymers Market | 2026-2036
Medical Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Polymers Market Analysis
Minimally invasive surgery is restructuring demand toward catheter-grade and implantable polymers with superior mechanical resilience. Celanese Corporation leverages its engineered materials portfolio to dominate high-performance implant applications. Evonik Industries AG anchors its position through bioresorbable polymer leadership in drug delivery matrices. BASF SE sustains manufacturing scale across medical-grade polyamide and polycarbonate supply chains.
Medical polymers encompass thermoplastic and thermoset materials formulated to meet ISO 10993 biocompatibility standards, with melt flow indices, tensile strength, and sterilization resistance tailored for bodily contact durations ranging from transient to permanent implantation. These materials serve as the structural foundation for devices where chemical inertness, processability, and patient safety converge. Polyethylene retains volume leadership in packaging and orthopedic bearing surfaces due to decades of clinical validation and cost-efficient processing. Biodegradable polyesters capture the fastest expansion trajectory as sutures, stent scaffolds, and controlled-release platforms shift toward resorbable architectures. Medical grade classifications command premium positioning because regulatory documentation burdens and batch consistency requirements create defensible margin pools.
FDA 510(k) and PMA pathways govern US market access, while EMA's Medical Device Regulation imposes stricter clinical evidence requirements for polymer-based implants across European member states. REACH chemical registration and ISO 10993 biological evaluation series collectively determine which polymer chemistries achieve commercial viability in regulated jurisdictions. Stakeholders must monitor evolving biocompatibility testing protocols and polymer recycling mandates as sustainability criteria infiltrate procurement specifications.
Market Dynamics
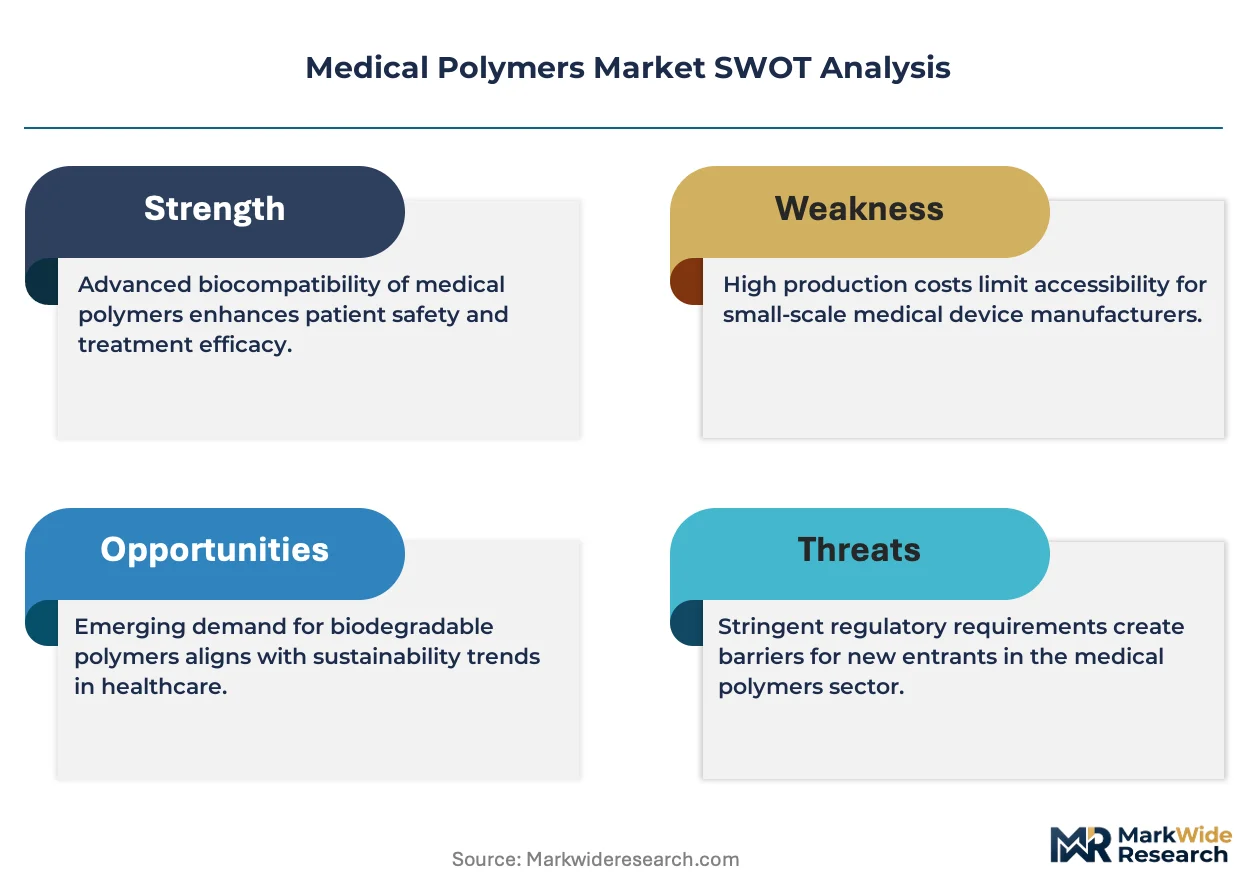
Bioresorbable polymer chemistry is compressing implant lifecycles from permanent to transient architectures, forcing manufacturers to rebuild material qualification pipelines around enzymatic degradation kinetics rather than decades-long durability metrics.
Growth Catalysts
- EU MDR clinical evidence mandates:Stricter biocompatibility documentation under EMA's Medical Device Regulation is accelerating reformulation toward pre-qualified polymer grades with existing ISO 10993 master files.
- Catheter-grade fluoropolymers:Minimally invasive surgical expansion is pulling demand for thin-wall tubing materials with precise melt flow control and radio-opacity.
- Germany's precision device corridor:Concentrated orthopedic and cardiovascular manufacturing around Tuttlingen and Freiburg sustains dedicated medical polymer compounding infrastructure.
Market Restraints
- Medical-grade monomer supply:Purified caprolactone and glycolide feedstocks face oligopolistic supply from specialized chemical producers, exposing compounders to input volatility.
- ISO 10993-18 chemical characterization:Extractables and leachables testing requirements for novel polymer additives extend qualification timelines by 18-24 months.
- Silicone substitution in long-term implants:Platinum-cured silicone elastomers retain preference in chronic neurological and cardiac applications due to superior fatigue resistance.
Strategic Opportunities
- India's CDSCO fast-track pathway:Streamlined approval for polymers with US FDA or EU MDR pre-qualification opens diagnostic device manufacturing expansion.
- 3D-printed patient-specific implants:Powder bed fusion and material extrusion of PEEK and PEKK is enabling geometrically complex cranial and spinal constructs.
- China NMPA innovation corridor:Priority review for domestically produced bioresorbable stent scaffolds accelerates local polymer synthesis investments.
Industry Challenges
- Polymer physicochemical characterization expertise:Scarce analytical chemists with ISO 17025 laboratory management and GMP documentation experience command premium compensation.
- Ethylene oxide sterilization validation:Residual EO and ethylene chlorohydrin testing protocols under tightening EPA emissions scrutiny extend batch release cycles.
- Legacy injection molding asset reconfiguration:Converting automotive or packaging equipment to medical-grade cleanroom standards requires costly servo-electric retrofits and ISO 13485 quality system overlays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Polymers Market |
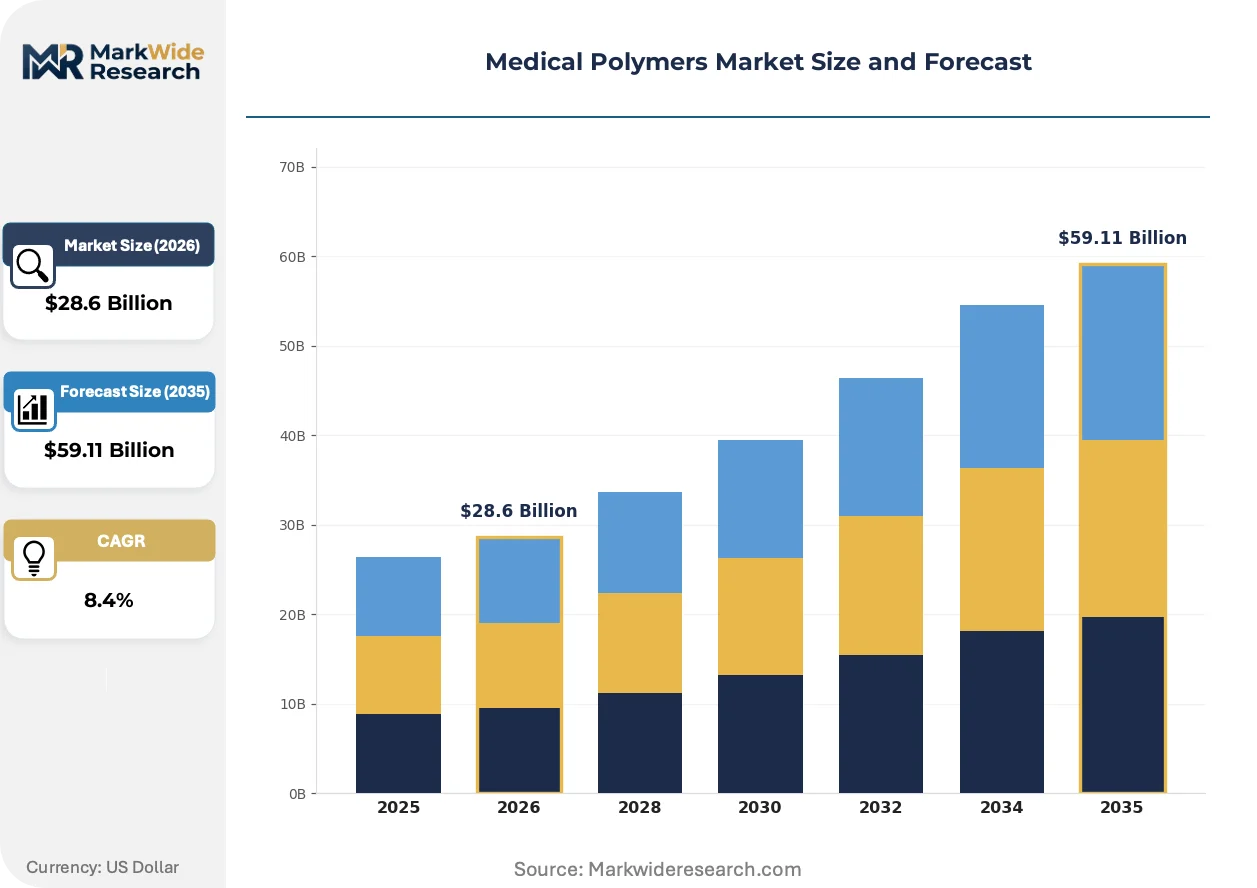
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodegradable Polyesters, Polyethylene, Polyvinyl Chloride, Polycarbonate Application: Medical Packaging, Implants, Drug Delivery, Catheters End User: Hospitals, Clinics, Research Institutions, Diagnostic Laboratories Grade: Medical Grade, Engineering Grade, High Purity Grade, Specialty Grade |
| Companies Covered | Celanese Corporation, Arkema, BASF SE, Dow Inc., Eastman Chemical Corporation, SABIC, Evonik Industries AG, NatureWorks LLC, Covestro AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Polymers Market Emerging Trajectories
Active pharmaceutical ingredient-polymer conjugation and surface biofunctionalization are dissolving the boundary between structural materials and therapeutic delivery systems, creating hybrid product categories that straddle device and drug regulatory frameworks.
4D-printed shape-memory polymers is rewriting stent and suture deployment protocols by enabling minimally invasive insertion followed by thermally triggered expansion to anatomically conformal geometries. Interventional cardiologists in Japan's university hospitals are piloting nitinol-polymer composite stents with programmed degradation timelines. This convergence of mechanical actuation and controlled resorption is compressing the addressable market for permanent metallic implants.
REACH polymer-of-low-concern reclassification under ECHA's 2024 microplastics restriction is forcing reformulation of diagnostic consumables toward water-soluble or biodegradable alternatives. Compounders serving European IVD manufacturers are accelerating polyvinyl alcohol and modified starch blend development. The clinical chemistry segment faces the steepest compliance curve due to high-volume disposable cuvette and pipette tip consumption.
Hospital procurement consortia are consolidating polymer specification authority from individual surgeons to centralized value-analysis committees, compressing approved vendor lists and demanding total-cost-of-ownership documentation. Germany's university hospital purchasing alliances now mandate lifecycle sterilization durability data and carbon footprint disclosures alongside unit pricing. Orthopedic implant manufacturers report elongated sales cycles but improved contract tenure under this centralized model.
Medical Polymers Market Segmentation
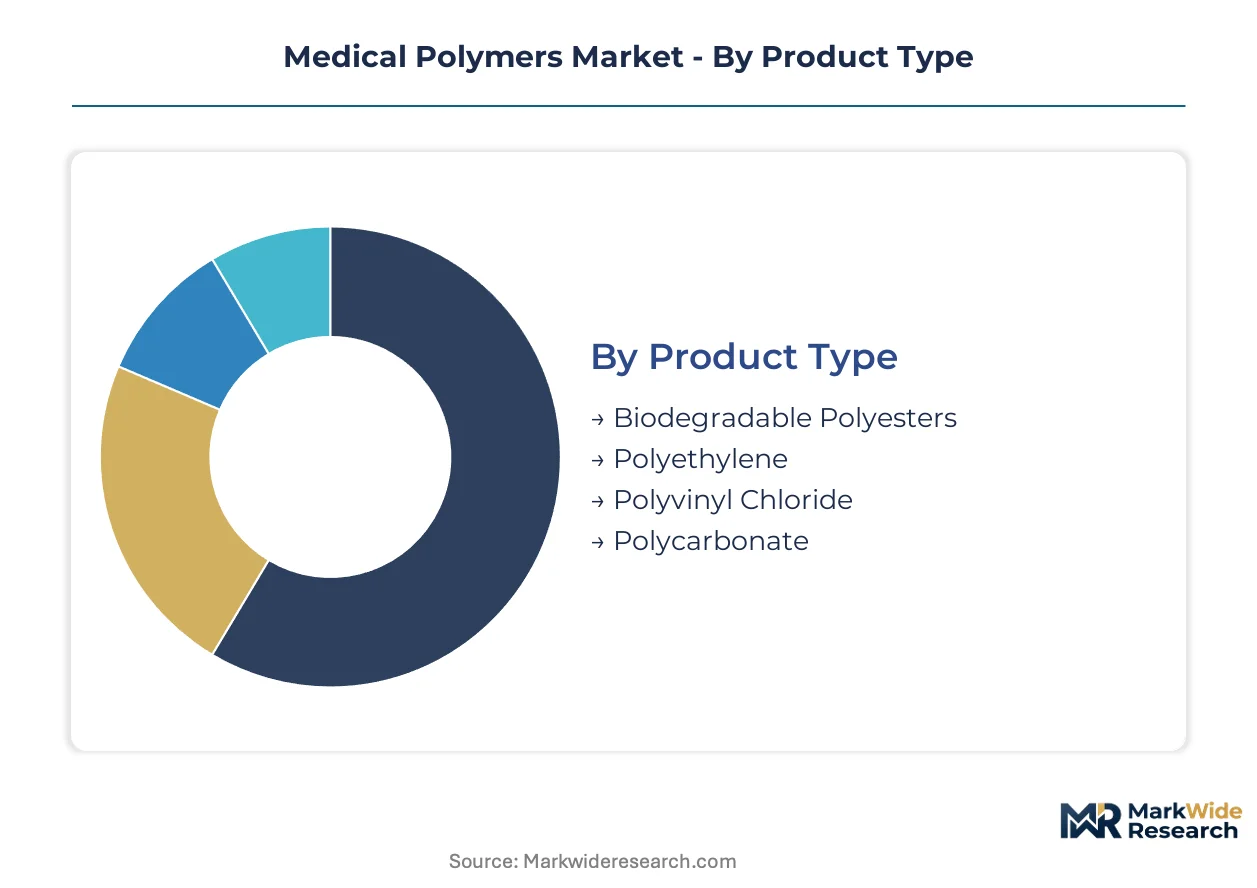
Medical polymer purchasing decisions split between high-volume commodity grades and premium-certified formulations. Segment boundaries blur as packaging polymers migrate toward implantable applications through upgraded purification protocols.
Product Type:
Polyethylene dominates tonnage while biodegradable polyesters command the steepest price premiums per kilogram.
- Biodegradable Polyesters:Enzymatically hydrolyzable aliphatic polyesters including PLGA, PCL, and polylactic acid formulations. Drug-eluting stent manufacturers in Germany's Freiburg medical technology cluster specify these for programmed resorption timelines matched to tissue healing windows.
- Polyethylene:Ultra-high molecular weight and high-density variants processed for orthopedic bearing surfaces and sterile barrier packaging. China's NMPA-registered joint replacement producers in Suzhou Industrial Park anchor volume demand for implantable-grade UHMWPE with validated gamma sterilization resistance.
- Polyvinyl Chloride:Plasticized formulations for blood bags and tubing, facing substitution pressure from TPE alternatives under REACH phthalate restrictions.
- Polycarbonate:Transparent, impact-resistant engineering thermoplastic for fluid management components and surgical instrument housings.
Today's leader: Polyethylene. Tomorrow's challenger: Biodegradable Polyesters.
Application:
Implantable applications generate margin pools that dwarf packaging volumes despite fractional tonnage.
- Medical Packaging:Sterile barrier films, blister packs, and vial closures requiring validated seal integrity and EO sterilization compatibility. FDA-registered contract manufacturers in Minnesota's Twin Cities medical device corridor specify multilayer coextrusions with extractables documentation.
- Implants:Permanent and resorbable structural polymers for orthopedic, cardiovascular, and neurological applications. ISO 10993-5 cytotoxicity testing and master file submissions create qualification moats around qualified suppliers.
- Drug Delivery:Matrix materials for controlled-release formulations and implantable pumps.
- Catheters:Thin-wall tubing requiring precise melt flow indices and radio-opaque filler integration for fluoroscopic visualization.
Implantable applications absorb the majority of R&D investment despite packaging's volume dominance.
End User:
Procurement authority is centralizing from individual surgeons toward hospital value-analysis committees with total-cost-of-ownership mandates.
- Hospitals:Acute care institutions with consolidated purchasing agreements spanning implantable devices, surgical consumables, and diagnostic disposables. Germany's university hospital purchasing alliances now require lifecycle sterilization durability data alongside unit pricing.
- Clinics:Ambulatory surgical centers and specialty practices with fragmented purchasing patterns and limited polymer specification expertise.
- Research Institutions:Academic medical centers and contract research organizations driving preclinical polymer evaluation for novel device architectures.
- Diagnostic Laboratories:High-throughput clinical chemistry and molecular testing facilities consuming disposable cuvettes, pipette tips, and microplates. REACH microplastics restrictions are forcing accelerated migration toward water-soluble alternatives in European IVD manufacturing.
Hospital procurement consolidation favors suppliers with comprehensive regulatory documentation and multi-site distribution capabilities.
Grade:
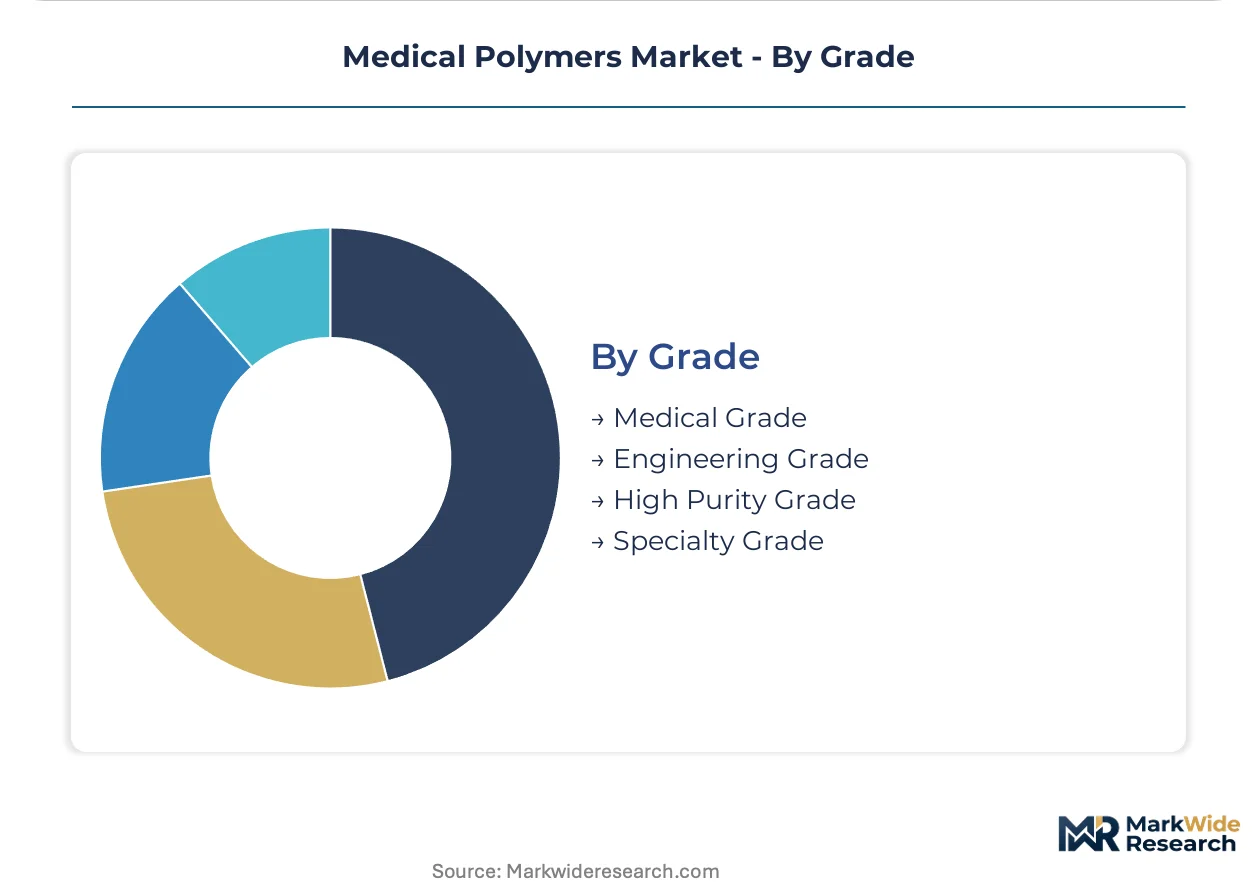
Certification tier determines accessible end-use markets and sustainable margin capture.
- Medical Grade:ISO 10993 biocompatibility-tested formulations with batch consistency documentation and DMF/MAF availability. FDA 510(k) and PMA pathway submissions require this tier for permanent implant applications.
- Engineering Grade:High-performance thermoplastics with mechanical specifications approaching medical grade but without full biological evaluation documentation. Surgical instrument housings and diagnostic equipment chassis represent primary demand.
- High Purity Grade:Ultra-low extractables formulations for pharmaceutical packaging and short-term fluid contact applications.
- Specialty Grade:Custom-compounded materials with proprietary additive packages for niche device requirements.
Medical grade captures the premium positioning that justifies reformulation investments under tightening EMA MDR clinical evidence mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting medical polymer compounding capacity toward jurisdictions with streamlined biocompatibility approval pathways, compressing qualification timelines for manufacturers serving multiple export markets.
United States
FDA 510(k) and PMA pathways anchor demand for implantable-grade polymers with validated ISO 10993 master files. EPA scrutiny of ethylene oxide sterilization emissions is extending batch release cycles for domestic manufacturers. Minnesota's Twin Cities corridor concentrates contract sterilization and polymer compounding infrastructure serving orthopedic device OEMs.
Germany
EMA Medical Device Regulation mandates are accelerating reformulation toward pre-qualified polymer grades with existing clinical evidence packages. REACH microplastics restrictions are forcing diagnostic consumable manufacturers toward water-soluble alternatives. Tuttlingen's precision device cluster sustains dedicated medical polymer compounding lines for orthopedic and cardiovascular applications.
China
NMPA priority review for domestically produced bioresorbable stent scaffolds is accelerating local polymer synthesis investments. Dual carbon goals are pressuring petrochemical-based medical polymer producers toward bio-based feedstock transitions. Suzhou Industrial Park anchors NMPA-registered joint replacement manufacturing with validated gamma sterilization resistance for UHMWPE.
India
CDSCO fast-track pathways for polymers with US FDA or EU MDR pre-qualification are opening diagnostic device manufacturing expansion. PLI scheme incentives for medical device components are attracting polymer compounders to dedicated zones. Gujarat's pharmaceutical manufacturing belt is extending into medical-grade polymer compounding for export-oriented device assembly.
Japan
PMDA's stringent biological evaluation requirements favor established polymer grades with decades of clinical validation in neurological and cardiac applications. METI funding for advanced medical materials is supporting shape-memory polymer development for interventional devices. Kansai's Osaka-Kobe manufacturing zone concentrates catheter-grade fluoropolymer processing for minimally invasive surgical platforms.
Medical Polymers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with implant-grade compounders commanding premium positioning against packaging-focused volume producers. Market structure consolidates around three tiers: integrated petrochemical giants with medical-grade certification, specialized polymer compounders with ISO 13485 quality systems, and regional toll manufacturers serving diagnostic disposables. Dominant competitive moves include strategic partnerships between compounders and device OEMs for co-developed formulations, plus geographic expansion through qualified supplier status in multiple regulatory jurisdictions.
Among diversified chemical conglomerates with medical-grade portfolios, Celanese Corporation and BASF SE exemplify scale-driven compounders with engineered materials expertise spanning implantable and packaging applications. Evonik Industries AG occupies a specialized position within the bioresorbable polymer segment, anchoring demand for drug delivery matrices and controlled-release platforms. These three entities collectively represent the competitive archetypes—scale, diversification, and specialization—that define procurement options for device manufacturers navigating tightening EMA and FDA biocompatibility mandates.
| Leading Market Players |
|---|
| Celanese Corporation |
| Arkema |
| BASF SE |
| Dow Inc. |
| Eastman Chemical Corporation |
| SABIC |
| Evonik Industries AG |
| NatureWorks LLC |
| Covestro AG |
| Others |
Supply Flow & Price Mechanics
Caprolactone spot price indices cascade through medical polymer supply chains into three distinct pricing tiers anchored by certification burden and batch consistency requirements. Contract manufacturers serving FDA-registered device OEMs absorb upstream volatility through long-term offtake agreements with specialized monomer suppliers, while diagnostic disposable producers face spot-market exposure.
Pricing Analysis
Distributor margins compress implant-grade polymer pricing by 12-18% before reaching hospital value-analysis committees, whereas direct-to-OEM channels preserve compounder profitability through volume commitments. Three-tier pricing structure across medical-grade, engineering-grade, and packaging-grade levels separates ISO 10993-certified formulations with DMF availability from uncertified alternatives. Cost compression in commodity polyethylene runs through gamma sterilization validation requirements and REACH documentation burdens. Packaging polymer buyers exhibit highest price sensitivity due to disposable high-volume consumption patterns, while orthopedic implant manufacturers prioritize batch traceability over unit cost.
Supply Chain Analysis
Reverse-logistics flows for expired or recalled implantable polymers remain underdeveloped, with most medical-grade materials diverted to industrial incineration rather than chemical recycling due to biocompatibility contamination protocols. Germany, China, and the United States anchor global compounding capacity for catheter-grade fluoropolymers and bioresorbable polyesters. Purified caprolactone, glycolide, and radio-opaque filler feedstocks draw from oligopolistic specialty chemical producers in Belgium and Japan. Single-source vulnerability concentrates in platinum-cured silicone elastomer supply for neurological applications. Distribution runs through qualified supplier networks with ISO 13485 certification rather than commodity chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Medical polymer manufacturing presents a geographic-arbitrage opportunity between EMA MDR-mandated reformulation costs in Europe and CDSCO fast-track advantages for pre-qualified materials in India.
For Market Incumbents: Anticipate bioresorbable polymer substitution compressing permanent implant addressable markets by prioritizing enzymatic degradation kinetics R&D and securing captive supply of purified lactide monomers through backward integration into fermentation-based feedstock production. For New Entrants and Emerging Players: CDSCO fast-track pathways in India open a window for diagnostic consumable manufacturing expansion targeting European IVD OEMs seeking REACH microplastics compliance through water-soluble polymer alternatives, with Gujarat's pharmaceutical belt offering established GMP infrastructure for medical-grade compounding scale-up. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized bioresorbable polymer compounders holding ISO 10993 master files and existing EMA clinical evidence packages, given the decade-long qualification moats protecting implant-grade supply relationships. Practitioners should monitor ECHA polymer-of-low-concern reclassification timelines and NMPA domestic bioresorbable stent approval velocity as inflection indicators for specialty grade demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993 Master File Expansion | EMA MDR clinical evidence mandates favor compounders with existing biocompatibility documentation. |
| Backward Integration into Lactide Monomers | Fermentation-based caprolactone production reduces oligopolistic feedstock exposure for bioresorbable grades. |
| CDSCO Fast-Track Qualification | India's streamlined approval opens diagnostic device manufacturing for export-oriented polymer compounders. |
| Water-Soluble Polymer Development | REACH microplastics restrictions force European IVD manufacturers toward biodegradable diagnostic consumables. |
| 3D-Printed PEEK Implant Partnerships | Patient-specific cranial and spinal constructs enable premium pricing through geometric complexity unattainable via injection molding. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with polymer compounder technical directors, hospital purchasing committee members, biomedical engineers at orthopedic OEMs, and GPO contracts managers with secondary validation against FDA 510(k) filings, EMA MDR submission databases, REACH registration dossiers, and customs trade data for medical-grade polymer imports. Bottom-up segment sizing and top-down macro constraint triangulation anchored volume estimates.
Historical reference periods spanning pre-pandemic baseline, supply disruption interval, and normalization phase informed projection anchor points across the analysis window. Segmentation modeling incorporated product type, application, end user, and grade tier dimensions alongside regional regulatory cluster variations. CAGRs derived from elasticity-adjusted demand curves and capacity expansion announcements. Forecast inputs included ethylene oxide sterilization facility commissioning timelines and NMPA bioresorbable stent priority review velocities.
Revisions become necessary when ECHA polymer reclassification timelines accelerate, EPA ethylene oxide emission restrictions tighten, or major orthopedic OEMs consolidate approved vendor lists beyond modeled concentration thresholds. Practitioners should monitor CDSCO fast-track application volumes and Germany's university hospital purchasing alliance contract awards for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Global Polymeric Adsorbents Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Phthalonitrile Resin Market
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Polymer Filler Market
Polymers & Resins
Europe Epoxy Resins Market
Polymers & Resins
Silyl Acrylate Polymer (SAP) Market
Polymers & Resins
Europe Polyols Market
Polymers & Resins
Polymer Seals Market
Polymers & Resins
EVA Foam Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Polymer Resin Market