
 Fluorinated Ethylene Propylene (FEP) Market | 2026-2036
Fluorinated Ethylene Propylene (FEP) Market Size, Share, and Industry Trends Forecast 2026-2036
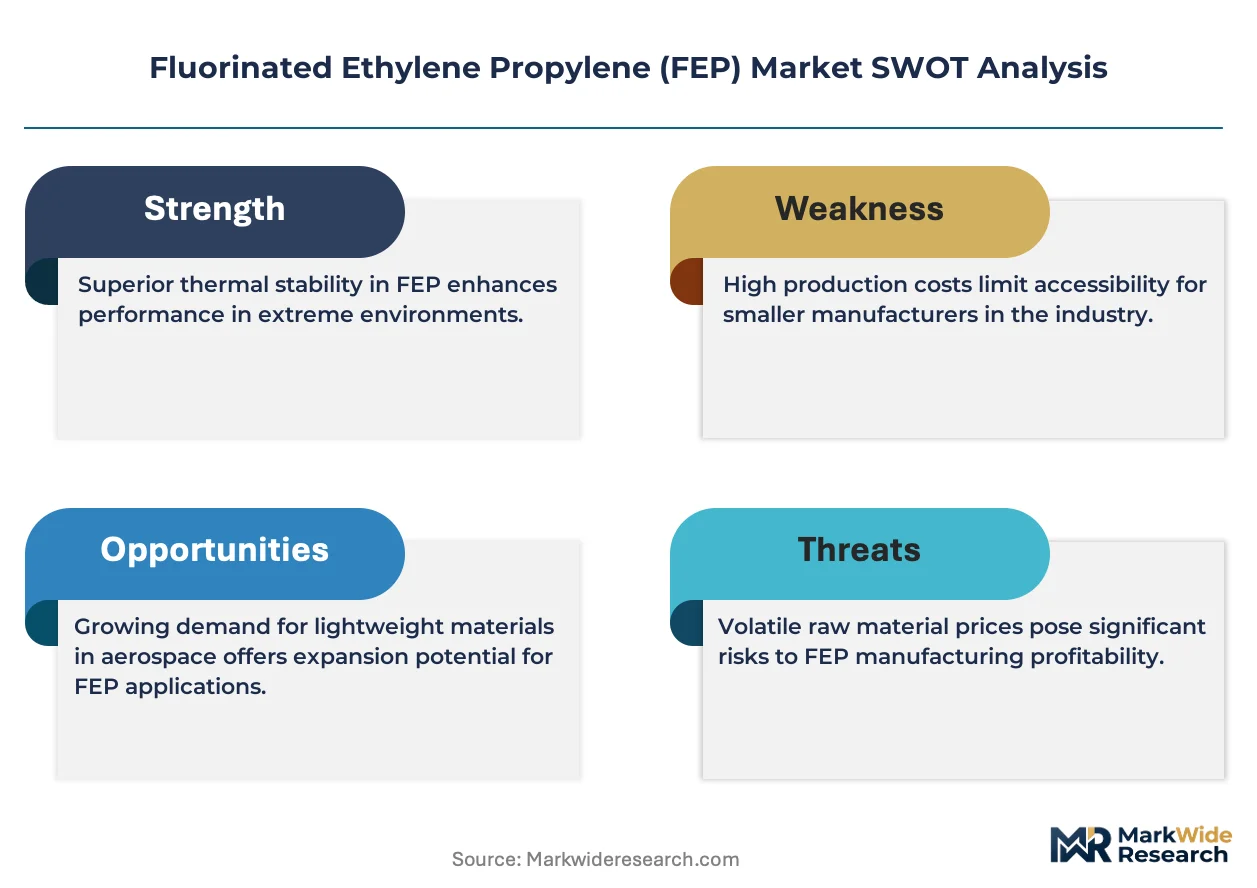
Fluorinated Ethylene Propylene (FEP) Market Analysis
Asset-light leasing models for fluoropolymer processing equipment are reshaping competitive entry in FEP, allowing mid-scale compounders to access extrusion capacity without full capital commitment. The Chemours Company leverages its integrated tetrafluoroethylene feedstock position to sustain margin stability across film and tubing grades. Daikin Industries Ltd anchors Asian supply through Osaka-based resin production and regional compounding partnerships. Solvay SA differentiates via specialty semiconductor-grade formulations that command specification premiums from European equipment OEMs.
Fluorinated ethylene propylene is a fully fluorinated copolymer of tetrafluoroethylene and hexafluoropropylene, melting between 260°C and 280°C and retaining chemical inertness across pH extremes from strong oxidizers to molten alkalis. Manufacturers produce it through aqueous dispersion or suspension polymerization, then extrude or sinter it into forms that serve primarily as corrosion barriers, electrical insulators, and release surfaces in aggressive process environments. Film and tubing categories dominate current volume, with semiconductor manufacturing applications expanding fastest as wafer fabrication nodes advance and cleanliness specifications tighten. Coating formulations for chemical processing equipment represent a mature but steady margin pool, particularly in North American and European replacement cycles. Rod and sheet forms occupy narrower niches in aerospace sealing and medical device prototyping where machinability matters.
The EPA oversees fluoropolymer emissions reporting under TSCA Section 8(a), while REACH governs per- and polyfluoroalkyl substance restrictions across EU member states, creating divergent compliance pathways for exporters. China's MEE enforces GB standards on fluorochemical production emissions, tightening environmental scrutiny on domestic resin plants that supply global FEP value chains. FDA 21 CFR 177.1550 and ISO 10993 biocompatibility protocols govern healthcare tubing approvals, extending product development timelines but erecting durable barriers for qualified suppliers. Stakeholders must monitor how evolving PFAS regulatory thresholds in multiple jurisdictions reshape material substitution economics and capital allocation across the FEP value chain.
Market Dynamics
Semiconductor fabs in Taiwan and South Korea are compressing cleanliness specifications at advanced nodes, forcing FEP tubing and coating suppliers to certify for sub-10nm wafer processing environments. This specification ratchet is concentrating procurement among resin compounders with captive tetrafluoroethylene feedstock and in-house dispersion polymerization capabilities.
Growth Catalysts
- EU F-Gas Regulation phase-down:Hydrofluorocarbon restrictions are redirecting sealing and lining applications toward FEP as a lower-GWP fluoropolymer alternative in chemical processing equipment.
- Wafer fabrication node advancement:Sub-7nm semiconductor manufacturing in Hsinchu and Pyeongtaek is specifying ultra-high-purity FEP for fluid handling systems where metallic ion contamination must stay below parts-per-trillion thresholds.
- Shanghai-Suzhou electronics cluster expansion:Contract manufacturers in China's eastern coastal provinces are consolidating orders for FEP film and tubing to serve display panel and printed circuit board production lines.
Market Restraints
- Tetrafluoroethylene feedstock concentration:Four integrated chemical producers control the majority of TFE monomer supply, exposing downstream FEP compounders to price volatility and allocation risk during plant turnarounds.
- Per- and polyfluoroalkyl substance scrutiny under REACH:ECHA's evolving restriction proposals on PFAS create regulatory overhang that delays capital commitments for new FEP production capacity in European member states.
- Perfluoroalkoxy alkane substitution in medical tubing:PFA's superior mechanical properties at elevated temperatures are displacing FEP in certain catheter and endoscope sheath applications where wall thickness minimization matters.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO's tightening good manufacturing practice enforcement is creating specification-grade demand for FEP-lined vessels and tubing in active pharmaceutical ingredient synthesis.
- Green hydrogen electrolyzer scaling:Proton exchange membrane electrolysis systems are specifying FEP as a cell separator and sealing material where fluorinated ionomers face cost constraints.
- Asset-light equipment leasing:Mid-scale compounders are accessing extrusion capacity through operating leases rather than capital expenditure, lowering barriers to specialty film and tubing production.
Industry Challenges
- Fluoropolymer processing technician scarcity:Extrusion and sintering expertise for high-melt-viscosity resins concentrates among aging workforces in Osaka and Wilmington, constraining capacity expansion timelines.
- Multi-jurisdiction PFAS compliance synchronization:Divergent EPA TSCA Section 8(a) reporting thresholds, REACH restriction timelines, and China's MEE GB standards force parallel regulatory strategies that extend product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fluorinated Ethylene Propylene (FEP) Market |
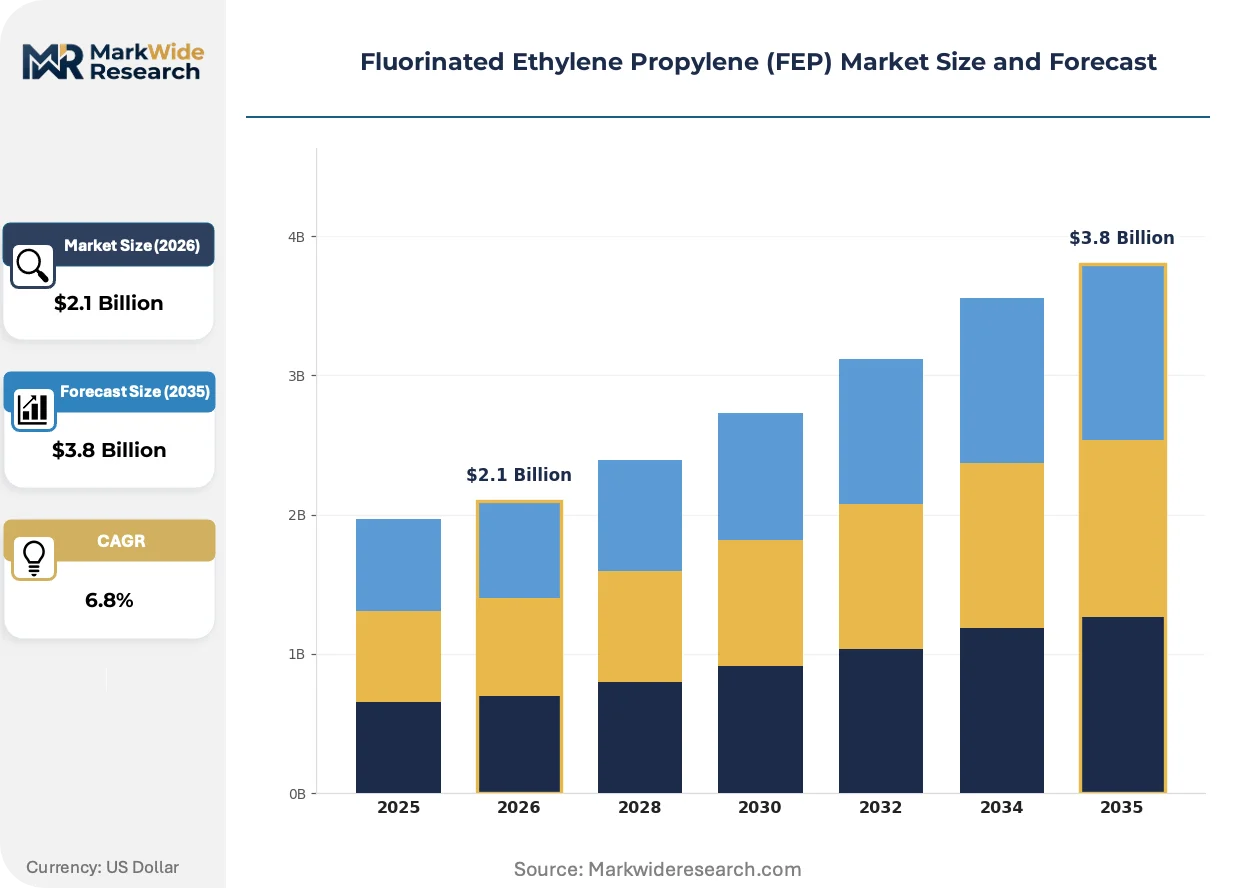
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film, Coating, Tubing, Rod Application: Wires & Cables, Medical Technology, Chemical Processing, Semiconductor Manufacturing End User: Aerospace, Electronics, Healthcare, Automotive Form: Sheet, Liquid, Powder, Paste |
| Companies Covered | The Chemours Company, Saint-Gobain Performance Plastics, 3M, Dongyue Chemical, INOFLON, Daikin Industries Ltd, Shanghai 3F New Materials Co. Ltd, Solvay SA, AGC Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fluorinated Ethylene Propylene (FEP) Market Emerging Trajectories
Digital twin deployment is compressing qualification timelines for FEP components in semiconductor fluid systems, allowing virtual validation of cleanliness and dimensional stability before physical prototyping. This simulation-first approach is reshaping how resin suppliers and fabricators collaborate on specification development.
Multi-layer coextrusion with ethylene tetrafluoroethylene is virtualizing the performance envelope for chemical processing linings, combining ETFE's mechanical toughness with FEP's release properties in single-step manufacturing. Petrochemical operators in Rotterdam and Houston are specifying these hybrid constructions for sulfuric acid storage tanks where traditional single-material linings required thicker gauges. The technology is virtualizing capital allocation decisions by reducing lining thickness requirements and installation labor.
EPA's proposed enhancements to TSCA Section 8(a) fluoropolymer reporting are expanding emissions disclosure obligations for FEP resin producers and processors. The rulemaking would capture previously exempt low-volume conversion activities, compelling compounders to install continuous monitoring systems. Medical device tubing manufacturers in Minnesota and Massachusetts are responding by consolidating supplier audits to preempt compliance gaps in their upstream supply chains.
Specification-driven procurement consolidation is compressing vendor lists for semiconductor-grade FEP, with foundries in Taichung and Yongin reducing qualified suppliers from dozens to single-digit panels. Tier-one equipment OEMs are replacing spot purchasing with multi-year offtake agreements that bundle resin supply, extrusion services, and cleanliness certification. This concentration is most visible in South Korea's Gyeonggi Province, where Samsung and SK Hynix fabs have aligned their FEP tubing specifications to secure volume pricing and supply security.
Fluorinated Ethylene Propylene (FEP) Market Segmentation
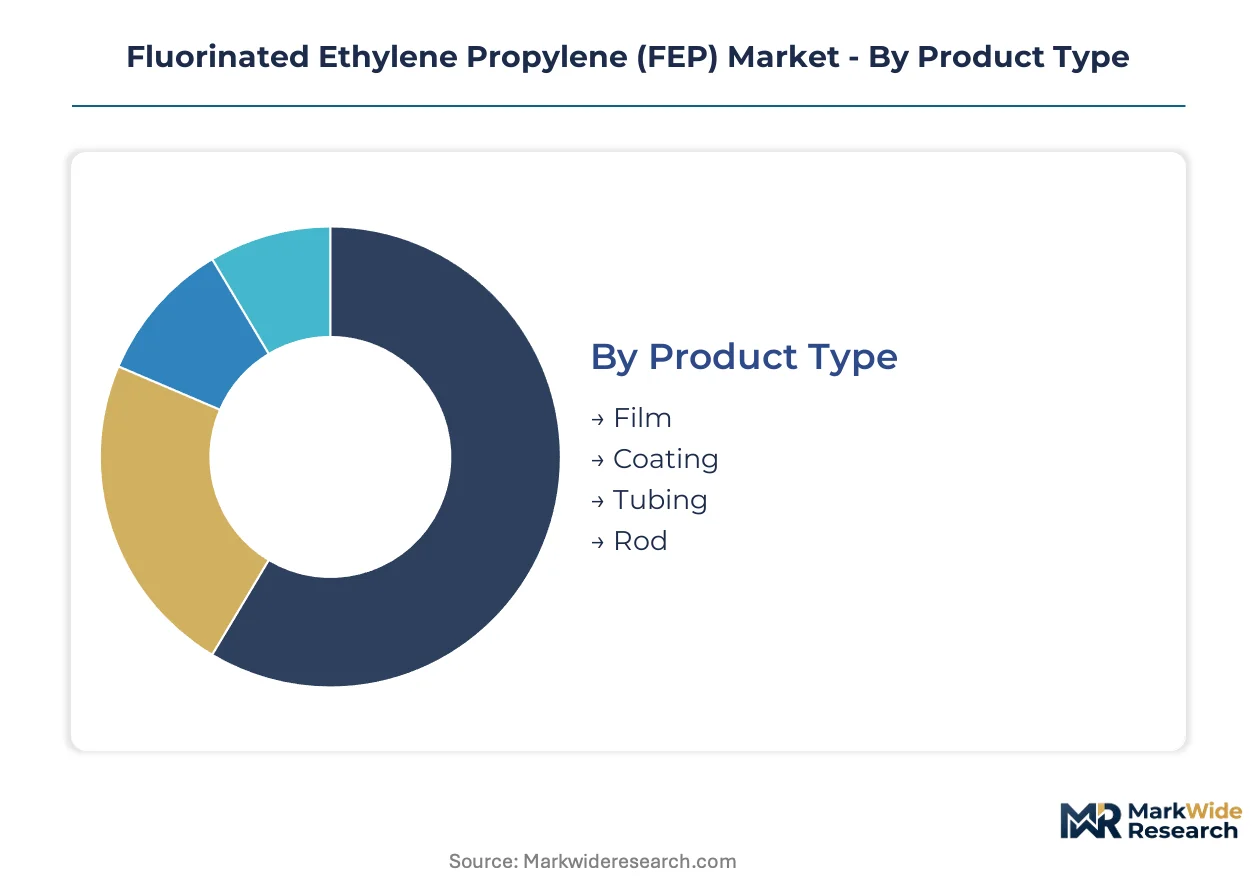
Segmentation in the FEP market reveals how specification requirements diverge across end-use environments. Product form and purity grades determine qualification pathways, while application-specific certifications erect barriers that concentrate procurement among qualified suppliers.
Product Type:
After-sales service intensity varies sharply across product categories, with tubing and film demanding ongoing technical support for cleanliness certification and dimensional troubleshooting while rod and coating require less post-sale engagement.
- Film:Thin-gauge extrusions serve as release liners and electrical insulation in flexible printed circuit manufacturing. Semiconductor fabs in Hsinchu specify ultra-pure FEP film for wafer handling applications where metallic ion contamination must remain below parts-per-trillion thresholds.
- Coating:Dispersion formulations provide corrosion barriers for chemical processing equipment through spray or dip application. Petrochemical operators in Rotterdam and Houston specify these linings for sulfuric acid storage tanks where traditional materials fail.
- Tubing:Extruded forms dominate fluid handling in aggressive process environments.
- Rod:Solid profiles serve machining-intensive applications in aerospace sealing prototypes.
Film holds the largest share; momentum sits with tubing as semiconductor cleanliness specifications tighten.
Application:
Cost tier stratification separates specification-grade semiconductor applications from commodity chemical processing uses, with medical technology occupying a premium middle tier governed by biocompatibility certification costs.
- Wires & Cables:Insulation formulations provide dielectric stability across temperature extremes from cryogenic to 200°C. Data center operators in Ashburn and Frankfurt specify FEP-jacketed cabling for high-frequency signal transmission where capacitance consistency matters.
- Medical Technology:Tubing and catheter components require ISO 10993 biocompatibility validation and FDA 21 CFR 177.1550 compliance. Device manufacturers in Massachusetts and Minnesota extend development timelines to secure durable supplier qualifications.
- Chemical Processing:Linings and seals protect equipment against pH extremes and oxidizing media.
- Semiconductor Manufacturing:Ultra-high-purity fluid handling components serve advanced wafer fabrication nodes.
Wires & cables holds the largest share; semiconductor manufacturing is climbing the fastest as sub-7nm nodes proliferate.
End User:
Customer type concentration drives specification divergence, with aerospace and electronics demanding traceable lot documentation while healthcare and automotive prioritize volume scale and supply security.
- Aerospace:Sealing and insulation components must satisfy FAA flammability and outgassing requirements. OEMs in Toulouse and Seattle specify FEP for fuel system seals and wire insulation where altitude cycling induces thermal stress.
- Electronics:Contract manufacturers in Shanghai-Suzhou cluster consume film and tubing for display panel and PCB production lines.
- Healthcare:Device tubing and pharmaceutical processing equipment require regulatory validation.
- Automotive:Wire harness insulation serves electric vehicle thermal management systems.
Electronics holds the largest share; healthcare is gaining share fastest as CDSCO enforcement tightens in Indian pharmaceutical manufacturing.
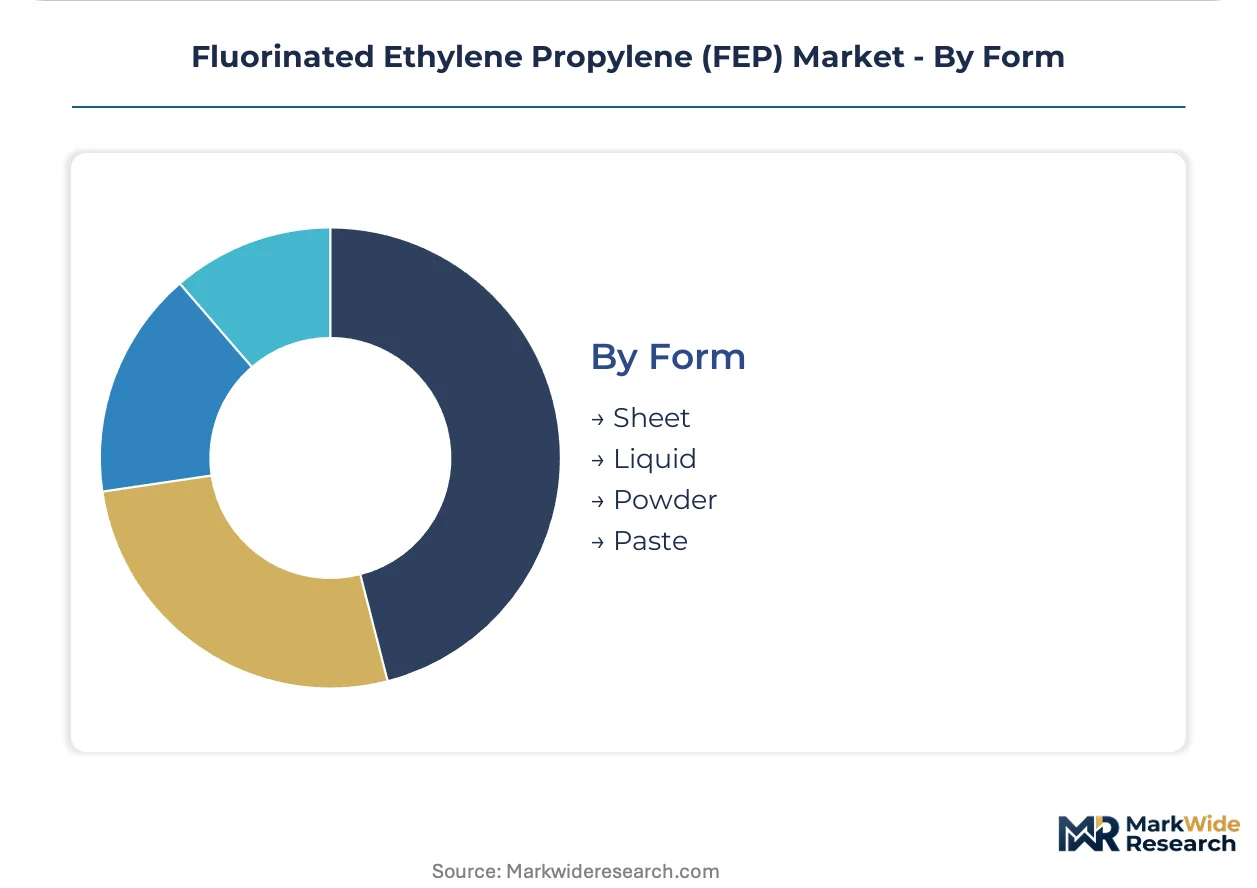
Form:
Supply concentration in dispersion polymerization capabilities favors liquid and powder forms, while sheet and paste occupy narrower niches served by specialized compounders with sintering or compounding expertise.
- Sheet:Compression-molded plates provide machinable stock for prototype fabrication and small-batch gasket production. Aerospace machine shops in Wichita and Burbank specify these forms for rapid turnaround on custom sealing geometries.
- Liquid:Aqueous dispersions enable spray coating of complex vessel geometries in chemical processing equipment.
- Powder:Fine-ground resin serves rotational molding and electrostatic coating applications.
- Paste:High-viscosity formulations facilitate brush or trowel application in repair and maintenance contexts.
Liquid holds the largest share; sheet shows steepest expansion trajectory as aerospace prototyping demand intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances concentrate resin supply in integrated chemical complexes while semiconductor fabs in East Asia drive premium-grade demand. Trade flows favor tetrafluoroethylene feedstock from integrated producers reaching compounders in electronics manufacturing clusters. Regulatory divergence on per- and polyfluoroalkyl substances fragments compliance strategies across jurisdictions.
China
Electronics contract manufacturers in Shanghai and Suzhou consume film and tubing for display panel production lines. The Ministry of Ecology and Environment enforces tightening GB standards on fluorochemical emissions from domestic resin plants. Yangtze River Delta processors are consolidating orders to secure volume pricing from state-owned tetrafluoroethylene suppliers.
United States
Medical device tubing manufacturers in Minnesota and Massachusetts extend development timelines for FDA 21 CFR 177.1550 compliance. The EPA oversees fluoropolymer emissions reporting under TSCA Section 8(a) with proposed enhancements expanding disclosure obligations. Wilmington-area resin producers maintain captive feedstock positions serving aerospace sealing applications.
South Korea
Samsung and SK Hynix fabs in Gyeonggi Province specify ultra-high-purity FEP for sub-7nm wafer processing environments. The Ministry of Food and Drug Safety aligns with international biocompatibility protocols for medical tubing imports. Pyeongtaek semiconductor clusters are reducing qualified supplier panels from dozens to single-digit rosters.
Germany
Petrochemical operators in Rotterdam-adjacent Rhine-Ruhr corridors specify multi-layer ETFE-FEP hybrid linings for sulfuric acid storage. The EU F-Gas Regulation phase-down redirects sealing applications toward lower-GWP fluoropolymer alternatives. Bavarian chemical processors face ECHA restriction proposals creating regulatory overhang on new capacity commitments.
Japan
Osaka-based resin producers anchor Asian supply through regional compounding partnerships serving semiconductor equipment OEMs. METI oversees industrial chemical production standards while PMDA governs medical device material approvals. Kansai-region fabricators concentrate extrusion expertise for high-melt-viscosity resins amid aging workforce constraints.
Fluorinated Ethylene Propylene (FEP) Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and dispersion polymerization. Tetrafluoroethylene supply concentrates among four integrated chemical producers, exposing downstream compounders to allocation risk during plant turnarounds. Two strategic archetypes dominate: resin producers with captive monomer supply, and fabricators with cleanliness certification capabilities. Competitive moves center on multi-year offtake agreements bundling resin supply with extrusion services, and asset-light equipment leasing lowering barriers to specialty production.
Within the integrated resin tier, The Chemours Company and Daikin Industries Ltd exemplify upstream control strategies. Solvay SA occupies a position among specialty semiconductor-grade formulators. Chinese fabricators including Dongyue Chemical and Shanghai 3F New Materials Co. Ltd represent regional scale players. Saint-Gobain Performance Plastics and AGC Inc. sit within the diversified materials conglomerate archetype. INOFLON and 3M exemplify technology-driven positioning in niche application segments.
| Leading Market Players |
|---|
| The Chemours Company |
| Saint-Gobain Performance Plastics |
| 3M |
| Dongyue Chemical |
| INOFLON |
| Daikin Industries Ltd |
| Shanghai 3F New Materials Co. Ltd |
| Solvay SA |
| AGC Inc. |
| Others |
Supply Flow & Price Mechanics
Tetrafluoroethylene monomer supply concentrates among four integrated chemical producers in the United States, Japan, and China, anchoring margin pools downstream with resin compounders who control dispersion polymerization capabilities. Semiconductor fabs in Hsinchu and Pyeongtaek pay specification premiums for ultra-high-purity grades, while chemical processors in Rotterdam and Houston negotiate volume contracts for standard lining formulations.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Semiconductor-grade FEP commands substantial premiums over chemical processing grades due to metallic ion certification and sub-10nm cleanliness protocols. Price differentiation hinges on ISO 10993 biocompatibility tiers and captive tetrafluoroethylene supply positions. Pricing pressure stems from REACH restriction proposals delaying European capacity investments. Medical device manufacturers in Massachusetts and Minnesota exhibit lowest price sensitivity; display panel contract manufacturers in Suzhou show highest elasticity.
Supply Chain Analysis
Extended payment terms from South Korean semiconductor equipment OEMs cascade through resin suppliers and compounding partners. Raw material flows center on fluorite concentrate from Mexico and Mongolia, sulfuric acid from domestic Chinese producers, and chloroform from Gulf Coast petrochemical complexes. Supply chain risk concentrates in single-source tetrafluoroethylene dependencies during Japanese plant maintenance cycles. Distribution runs through regional compounding hubs in Osaka, Shanghai, and Wilmington serving fabrication clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wafer fabrication node advancement toward sub-3nm architectures is disrupting material qualification timelines, compressing procurement consolidation into multi-year offtake agreements that favor integrated resin producers.
For Market Incumbents: Insulate specification-grade market share by deepening captive tetrafluoroethylene positions and accelerating semiconductor cleanliness certification beyond current parts-per-trillion thresholds. Perfluoroalkoxy alkane substitution in medical tubing threatens FEP's catheter applications; respond by co-developing hybrid ETFE-FEP multi-layer constructions with Rotterdam petrochemical operators. Capacity addition in South Korea's Gyeonggi Province secures proximity to Samsung and SK Hynix fabs. For New Entrants and Emerging Players: Indian pharmaceutical manufacturing underpenetration by qualified FEP-lined vessel suppliers offers white-space entry as CDSCO enforcement tightens good manufacturing practice compliance. Target active pharmaceutical ingredient synthesis equipment in Hyderabad and Ahmedabad clusters through asset-light leasing partnerships with domestic fabricators. Green hydrogen electrolyzer scaling in European markets presents secondary entry point for proton exchange membrane cell separator specifications. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed specialty chemical compounders in North America and Europe holding FDA 21 CFR 177.1550 qualifications but lacking captive monomer supply. Long-term viability favors upstream-integrated positions or downstream cleanliness certification capabilities rather than mid-scale extrusion-only operations. Watch ECHA's PFAS restriction timeline as inflection signal for European capacity rationalization and import substitution economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tetrafluoroethylene | Chemours and Daikin secure margin stability through captive monomer supply during allocation crunches. |
| Semiconductor-Grade Cleanliness Certification | Solvay commands specification premiums from ASML and Applied Materials through sub-ppt metallic ion protocols. |
| Asset-Light Extrusion Equipment Leasing | Mid-scale compounders in China's Yangtze River Delta access capacity without capital expenditure commitments. |
| Multi-Layer ETFE-FEP Coextrusion Partnerships | Rotterdam petrochemical operators specify hybrid linings reducing installation labor for sulfuric acid tanks. |
| Indian Pharmaceutical Manufacturing Qualification | CDSCO enforcement in Hyderabad creates specification-grade demand for FEP-lined active pharmaceutical ingredient vessels. |
Methodological Framework
A spread of perspectives from fluoropolymer plant managers, semiconductor fab procurement leads, chemical processing equipment OEMs, and medical device regulatory affairs directors converged on the working assumptions. Primary interviews combined with secondary validation from EPA TSCA Section 8(a) filings, ECHA restriction proposal documentation, China MEE GB standard releases, and SEC 10-K disclosures from integrated resin producers. Bottom-up demand modeling across tubing, film, coating, and rod product categories triangulated against top-down tetrafluoroethylene feedstock capacity assessments.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product form, application purity grade, and regional regulatory cluster. CAGRs derived from annualized growth rate convergence between historical shipment data and forward capacity expansion announcements. Industry-specific forecast inputs included wafer fabrication node transition schedules and EU F-Gas Regulation phase-down compliance timelines.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by Chinese state-owned chemical producers would shift outcomes. Macroeconomic deviation in semiconductor capital expenditure cycles, regulatory acceleration on PFAS restrictions, or breakthroughs in non-fluorinated material substitutes would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Global Polyolefin Resins Market
Polymers & Resins
Concrete Containing Polymer Market
Polymers & Resins
Polybutene-1 Market
Polymers & Resins
Asia-Pacific Polymer Emulsion Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Thermoplastic Polyester Engineering Resin (TPER) Market
Polymers & Resins
Polyether Polyols Market
Polymers & Resins
United States Polymer Emulsion Market
Polymers & Resins
Filled Fluoropolymer Market
Polymers & Resins
ASEAN Ethylene Vinyl Acetate (EVA) Resins Market
Polymers & Resins
Semi-Crystalline Polymers Market
Polymers & Resins
Polyisobutene Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
Global Impregnating Resins Market
Polymers & Resins
PET Foam Market