
 Europe Ceramic Ball Bearings Market | 2026-2036
Europe Ceramic Ball Bearings Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ceramic Ball Bearings Market Intelligence
Aerospace and electric vehicle manufacturing is realigning demand patterns for ceramic ball bearings across Europe. SKF leverages its Nordic manufacturing footprint to supply high-reliability hybrid bearings to Scandinavian aerospace contractors. Schaeffler Group anchors German automotive OEM relationships through precision-grade ceramic solutions for electrified powertrains. CeramicSpeed competes on cycling and industrial niche applications where friction reduction commands premium positioning.
Ceramic ball bearings employ silicon nitride or zirconia rolling elements with steel or ceramic rings, delivering corrosion immunity, electrical insulation, and thermal stability beyond 800°C for extreme-duty rotation systems. Full ceramic configurations dominate medical device and semiconductor applications where magnetic permeability must approach zero. Hybrid ceramic bearings lead automotive and aerospace volumes due to their cost-performance balance and established reconditioning infrastructure. The size dimension fragments across miniature instrument bearings and large-diameter wind turbine main shaft units with divergent margin structures.
EMA medical device regulations, REACH substance restrictions, and CE marking under the EU Machinery Directive shape material selection, lubricant chemistry, and surface finish requirements for European bearing suppliers. The EU Green Deal's embodied carbon tracking pushes manufacturers toward energy-dense sintering processes and regionalized powder sourcing. Stakeholders must monitor evolving F-Gas Regulation impacts on ceramic synthesis atmospheres and anticipate stricter lifecycle disclosure rules under the Corporate Sustainability Reporting Directive.
Market Dynamics
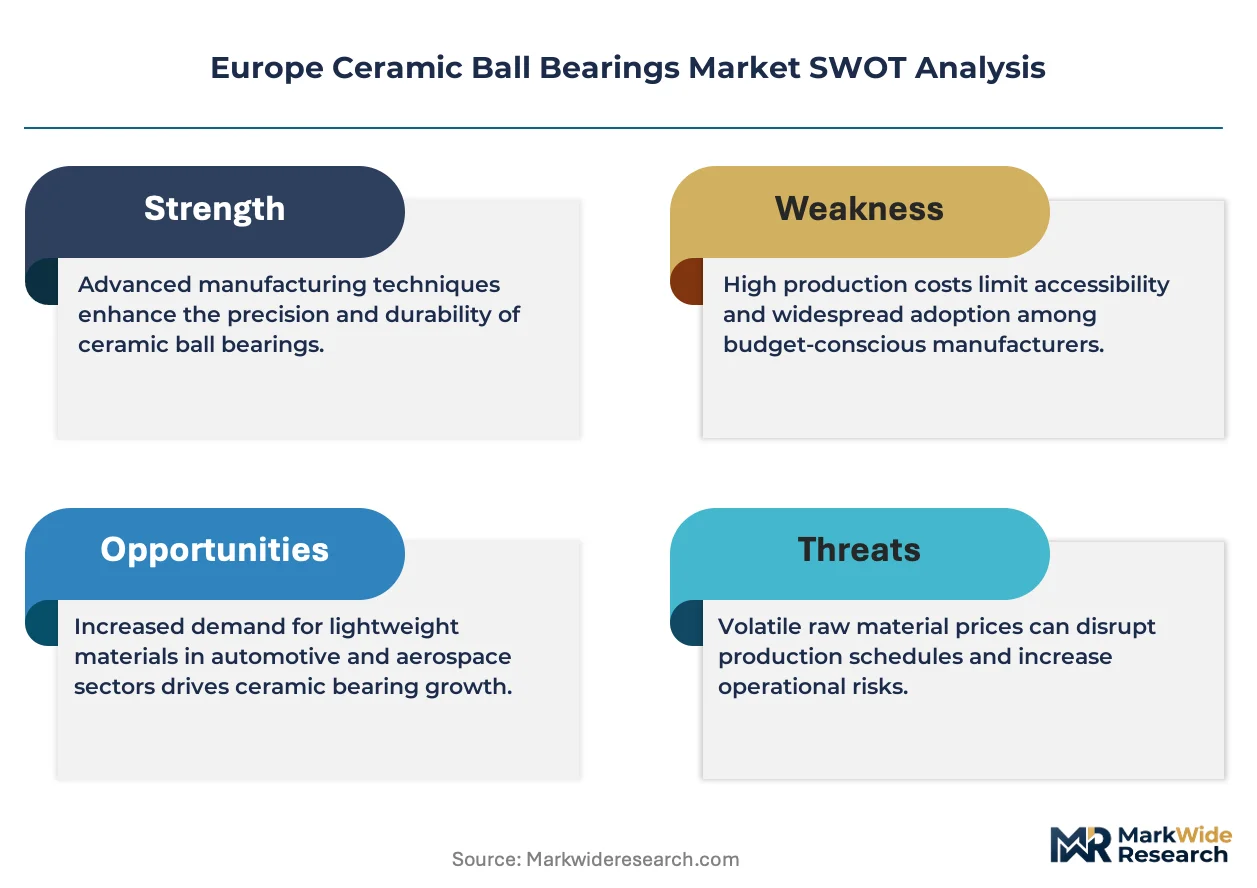
REACH substance restrictions and the EU Green Deal's embodied carbon mandates are forcing bearing suppliers to requalify material streams and relocate powder synthesis closer to European end-users, compressing legacy supply chains.
Growth Catalysts
- EMA Medical Device Regulation:Zero-magnetic-permeability requirements in diagnostic imaging equipment are accelerating full-ceramic bearing adoption across German and Dutch medical device clusters.
- Electric vehicle powertrain electrification:Insulated ceramic rolling elements eliminate electrical pitting in motor bearings, with German and French OEMs specifying hybrid configurations for 800V architectures.
- Silicon nitride powder regionalization:EU Green Deal carbon-border adjustments incentivize sintering capacity expansion in Poland and the Czech Republic, shortening lead times for Scandinavian wind turbine manufacturers.
Market Restraints
- Raw material concentration:High-purity silicon nitride precursor supply concentrates among Asian chemical processors, exposing European bearing makers to input cost volatility and currency risk.
- F-Gas Regulation synthesis constraints:Nitrogen atmosphere requirements for ceramic sintering face tightening fluorinated gas phase-out schedules, limiting furnace throughput and raising compliance costs.
- Steel bearing residual performance:Advanced vacuum-melted steel bearings retain cost advantages in non-corrosive, moderate-temperature automotive applications, delaying ceramic substitution in mass-market segments.
Strategic Opportunities
- Portuguese and Spanish aerospace sub-tier:Emerging satellite constellation programs in Iberia lack qualified local bearing suppliers, creating first-mover positioning for hybrid ceramic specialists.
- CSRD lifecycle disclosure mandates:Corporate Sustainability Reporting Directive requirements favor ceramic bearings with quantified carbon footprints, rewarding suppliers with verified powder-to-finish traceability.
- Additive manufacturing convergence:Ceramic matrix composite bearing cages produced via binder jetting enable topology-optimized designs for Formula E and motorsport niche volumes.
Industry Challenges
- Ceramic grinding technician scarcity:Precision lapping of silicon nitride balls to G5 tolerance requires multi-year apprenticeship pipelines that German and Swiss training systems struggle to replenish.
- OEM qualification timeline compression:Automotive platform cycles now demand 18-month bearing validation against historical 36-month windows, straining testing laboratory capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ceramic Ball Bearings Market |
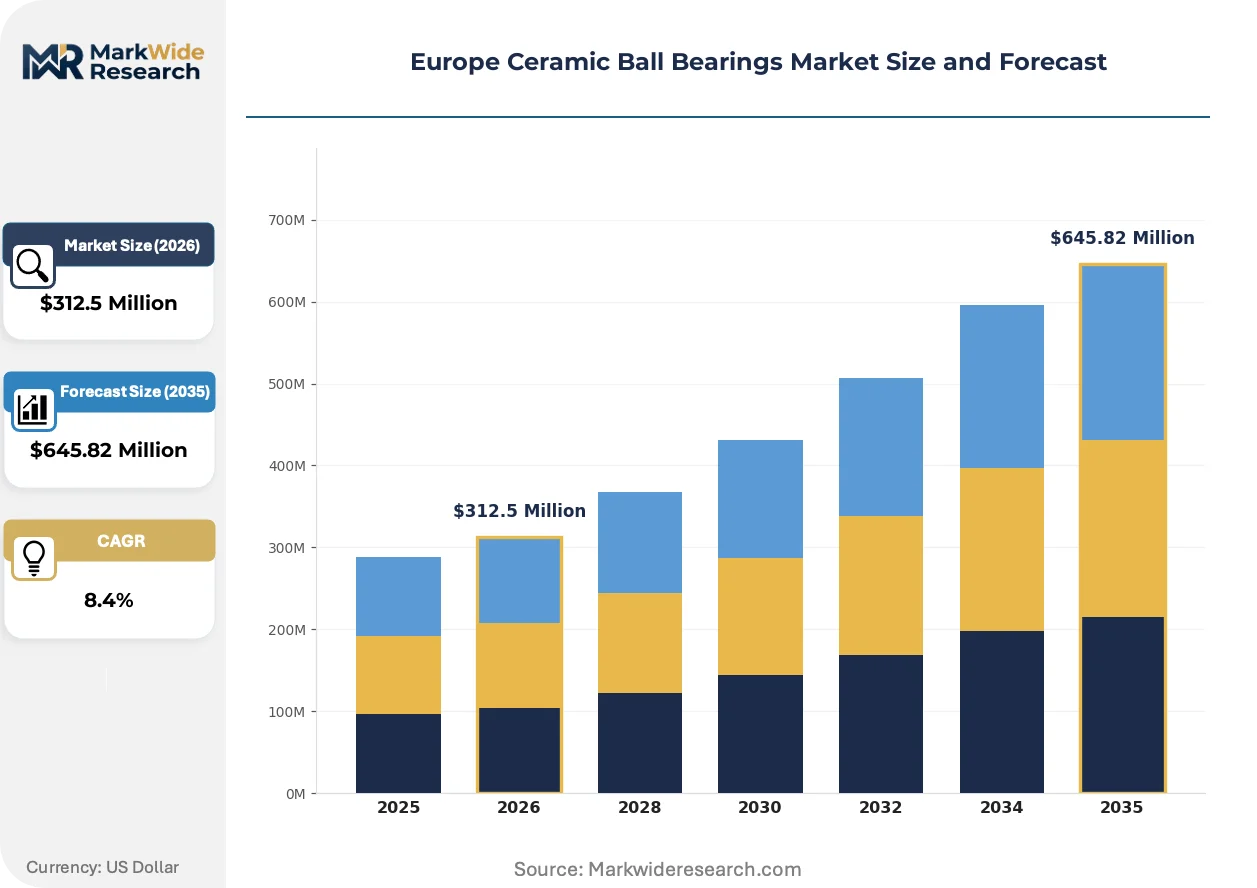
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full Ceramic, Hybrid Ceramic, Ceramic Coated, Plastic End User: Aerospace, Automotive OEMs, Medical Devices, Industrial Equipment Application: High-Speed Applications, Precision Instruments, Robotics, Electric Motors Size: Miniature, Standard, Large, Custom |
| Companies Covered | NSK, Timken, SKF, Ortech Advanced Ceramics, CeramicSpeed, Schaeffler Group, JTEKT, NTN-SNR, NTN, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ceramic Ball Bearings Market Strategic Shifts & Innovations
European ceramic bearing technology is converging around predictive maintenance integration and regionalized powder metallurgy, with regulatory carbon tracking becoming a design input rather than a reporting afterthought.
Silicon nitride rolling elements with engineered surface textures are consolidating market share in high-speed spindle applications. Machine tool builders in Italy and Germany specify these for 30,000+ RPM machining centers. The technology is consolidating supplier tiers by rewarding integrated powder-to-component manufacturers with validated thermal shock resistance data.
REACH Annex XIV authorization requirements for cobalt-containing grinding compounds are reshaping European finishing operations. Polish and Romanian bearing plants face process revalidation costs exceeding seven figures. Medical device and semiconductor segments are responding fastest, specifying cobalt-free certified supply chains in procurement tenders.
Buyers are unbundling aftermarket service from initial equipment contracts, forcing bearing suppliers to price rolling elements and predictive monitoring separately. German automotive tier-ones now negotiate sensor-integrated bearing cartridges on a per-kilometer basis. This shift is most visible in Nordic electric bus and rail applications where uptime guarantees dominate vendor selection.
Europe Ceramic Ball Bearings Market Segmentation
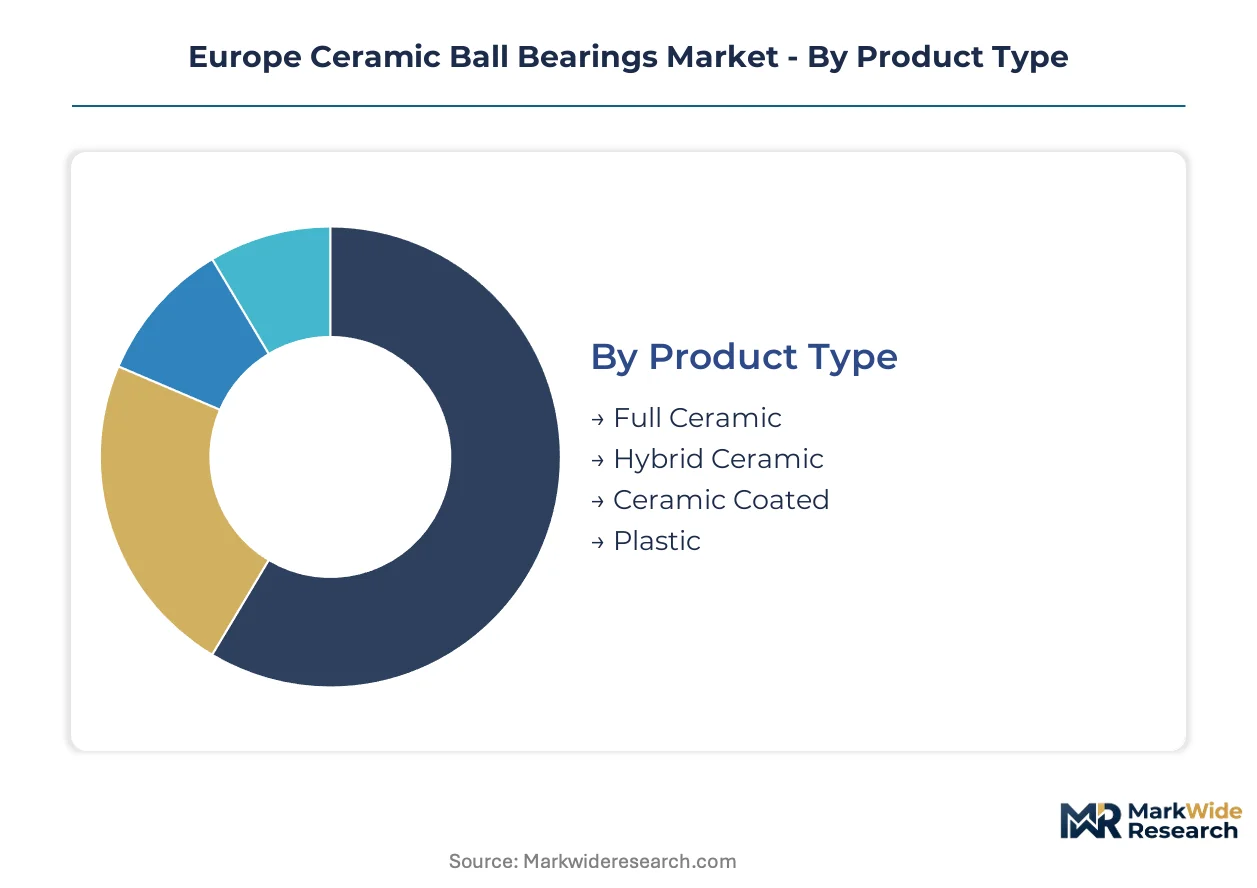
Ceramic ball bearing segmentation in Europe reflects divergent margin structures between commoditized hybrid configurations and premium full-ceramic systems. Procurement patterns across German automotive OEMs and Dutch medical device clusters demonstrate how end-use specifications reshape supplier tiering and qualification timelines.
Product Type:
Volume concentration favors hybrid architectures, while premium pricing attaches to corrosion-immune full-ceramic systems and surface-engineered coatings.
- Full Ceramic:Silicon nitride or zirconia rolling elements paired with ceramic rings deliver zero magnetic permeability and thermal stability beyond 800°C. German and Dutch diagnostic imaging equipment manufacturers specify these for EMA-compliant MRI and CT scanner gantries where electrical insulation is mandatory.
- Hybrid Ceramic:Ceramic rolling elements with steel rings balance cost-performance ratios and leverage established reconditioning infrastructure. French and German automotive OEMs dominate procurement for 800V electric powertrain motor bearings where electrical pitting elimination justifies unit premiums.
- Ceramic Coated:Steel substrates with ceramic deposition layers address moderate-corrosion environments at reduced cost points.
- Plastic:Polymer-ceramic composites serve limited-load instrument applications where weight minimization outweighs thermal constraints.
Mature deployment sits with Hybrid Ceramic. Newer deployment is concentrated in Full Ceramic.
End User:
Customer type determines specification stringency, with medical and aerospace buyers imposing qualification protocols that industrial purchasers rarely match.
- Aerospace:Satellite constellation programs across Iberia and Scandinavian defense contractors demand hybrid configurations with validated thermal shock resistance. SKF's Nordic manufacturing footprint supplies these segments through established aerospace certification channels.
- Automotive OEMs:Powertrain electrification is displacing conventional steel bearings in German and French 800V architectures. Procurement contracts now specify sensor-integrated ceramic cartridges with per-kilometer pricing structures.
- Medical Devices:Zero-magnetic-permeability requirements under EMA regulations accelerate full-ceramic adoption in German imaging equipment clusters.
- Industrial Equipment:Machine tool builders in Italy specify textured silicon nitride elements for 30,000+ RPM machining centers.
Procurement concentration clusters with Automotive OEMs. Specification intensity peaks with Medical Devices.
Application:
Rotational speed and positioning precision create divergent technical requirements that fragment supplier capabilities across European manufacturing clusters.
- High-Speed Applications:Engineered surface textures on silicon nitride rolling elements reduce friction coefficients for spindle applications exceeding 30,000 RPM. Italian and German machine tool OEMs consolidate supplier tiers by demanding integrated powder-to-component manufacturing with validated thermal shock data.
- Precision Instruments:G5 tolerance lapping requirements for miniature bearings serve semiconductor lithography and metrology equipment. Swiss and German apprenticeship pipelines struggle to replenish ceramic grinding technician capacity.
- Robotics:Compact hybrid configurations address payload-to-precision ratios in collaborative automation systems.
- Electric Motors:Insulated ceramic elements eliminate electrical discharge machining damage in variable-frequency drive applications.
Established demand centers on High-Speed Applications. Expanding most quickly is Electric Motors.
Size:
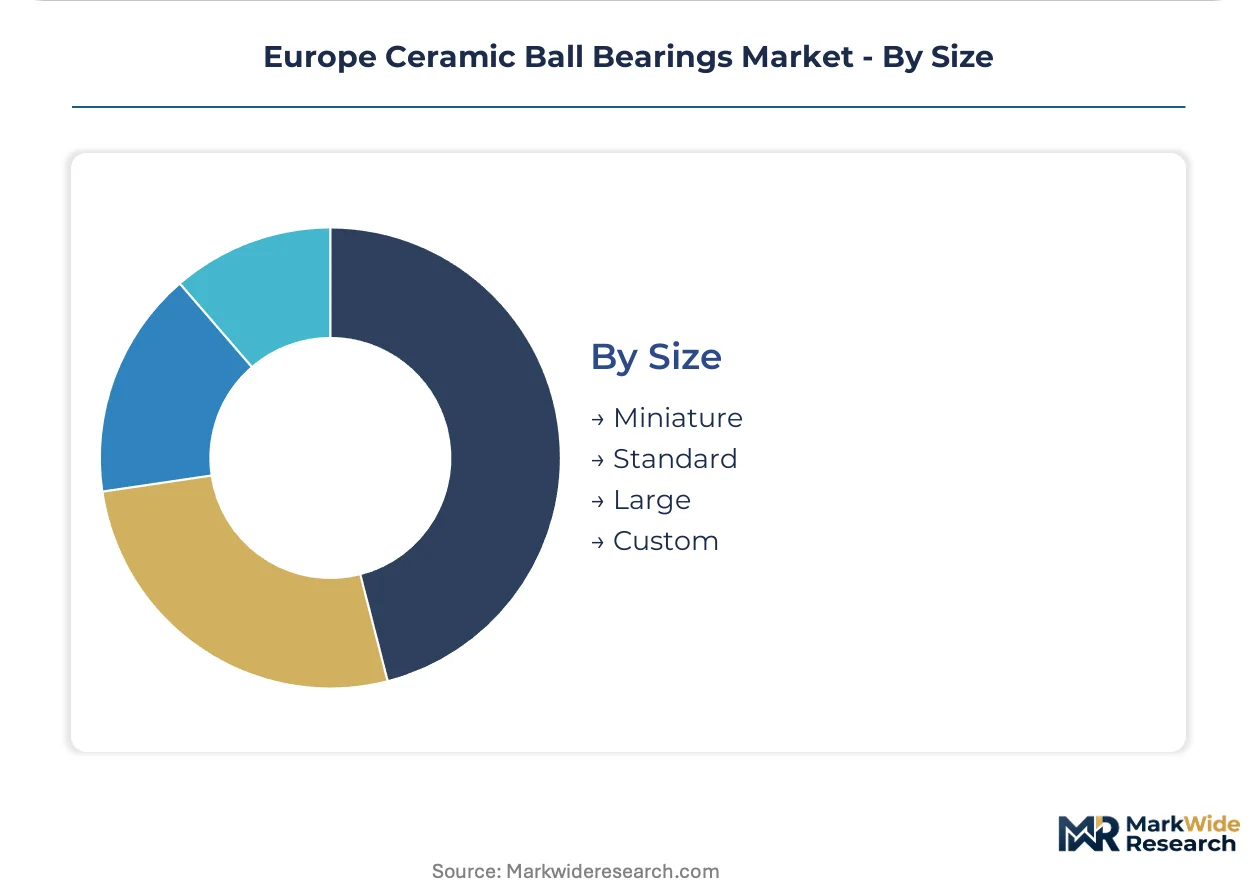
Dimensional scale determines manufacturing process economics, with miniature and custom segments requiring specialized lapping infrastructure that standard and large configurations bypass.
- Miniature:Sub-10mm bore diameters serve medical instruments and semiconductor handling equipment. Polish and Romanian finishing plants face REACH Annex XIV revalidation costs exceeding seven figures for cobalt-free grinding compound substitution.
- Standard:ISO dimension series dominate industrial maintenance volumes with established distribution channels.
- Large:Wind turbine main shaft units exceed 300mm bore diameters with divergent margin structures from precision miniature segments.
- Custom:Topology-optimized bearing cages via binder jetting enable Formula E and motorsport niche volumes with rapid design iteration cycles.
Volume concentration rests with Standard. Technical differentiation concentrates in Custom.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Poland's Special Economic Zones attract silicon nitride sintering investments under EU Green Deal carbon-border adjustments. Czech manufacturing corridors shorten lead times for Scandinavian wind turbine OEMs. German precision clusters anchor specification authority for automotive and medical device applications.
Germany
Baden-Württemberg and Bavaria concentrate automotive powertrain electrification programs specifying hybrid ceramic bearings for 800V architectures. REACH compliance mandates drive material requalification across Stuttgart and Munich supplier networks. The KBA enforces type-approval standards that compress OEM qualification timelines to eighteen months.
France
Paris-Saclay and Grenoble aerospace clusters demand hybrid configurations with validated thermal shock resistance for satellite constellation programs. ANSM medical device oversight aligns with EMA zero-magnetic-permeability requirements for diagnostic imaging equipment. Lyon industrial zones host reconditioning infrastructure serving European maintenance volumes.
Italy
Emilia-Romagna and Lombardy machine tool builders specify textured silicon nitride elements for 30,000+ RPM machining centers. CE marking under the EU Machinery Directive shapes surface finish requirements for precision spindles. Bologna and Milan supplier tiers consolidate around integrated powder-to-component manufacturers.
Poland
Katowice and Wrocław special economic zones attract EU-funded sintering capacity expansion for wind turbine bearing supply. ECHA substance restrictions force cobalt-free grinding compound substitution in finishing plants. Polish ceramic grinding technician pipelines struggle to replenish precision lapping capacity for G5 tolerance requirements.
Netherlands
Eindhoven semiconductor equipment manufacturers drive miniature full-ceramic bearing procurement for lithography systems. CSRD lifecycle disclosure mandates favor suppliers with verified powder-to-finish traceability. Dutch medical device clusters in Utrecht and Leiden specify zero-magnetic-permeability bearings for MRI gantry applications.
Europe Ceramic Ball Bearings Market Key Industry Players
Top-tier vendors anchor German and Nordic precision manufacturing, while mid-tier specialists occupy cycling and industrial niche segments. The vendor base stratifies across integrated powder-to-component manufacturers, bearing reconditioning service providers, and ceramic element specialists. Three archetypes dominate: aerospace-certified hybrid suppliers, automotive powertrain integrators, and friction-reduction specialists. Capacity expansion and strategic qualification partnerships represent the dominant competitive moves.
Among Nordic-integrated manufacturers, SKF anchors aerospace supply chains through established certification channels. Schaeffler Group exemplifies the automotive powertrain archetype with precision-grade solutions for electrified platforms. CeramicSpeed occupies the premium friction-reduction tier in cycling and industrial applications where performance differentiation commands positioning.
| Leading Market Players |
|---|
| NSK |
| Timken |
| SKF |
| Ortech Advanced Ceramics |
| CeramicSpeed |
| Schaeffler Group |
| JTEKT |
| NTN-SNR |
| NTN |
| Others |
Cost & Logistics Intelligence
Captive silicon nitride powder production in Germany and Poland anchors supply positions while insulating integrated manufacturers from Asian precursor volatility. This backward integration into sintering capacity simultaneously compresses lead times for Scandinavian wind turbine OEMs and commands premium positioning in automotive qualification programs.
Pricing Analysis
Premium positioning attaches to sub-12-week lead times for EMA-qualified full-ceramic bearings serving Dutch and German medical device clusters. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and powder traceability depth. Cost compression in standard hybrid configurations is intensifying because Polish sintering expansion adds regional capacity. Industrial maintenance buyers exhibit highest price sensitivity; aerospace satellite programs show least.
Supply Chain Analysis
Aerospace-grade qualification gates concentrate supply among German, Swedish, and Swiss manufacturers with validated thermal shock resistance protocols. High-purity silicon nitride precursor draws from Japanese and Chinese chemical processors, exposing European bearing makers to currency risk. Single-source vulnerability concentrates in medical-grade powder batches certified for zero-magnetic-permeability applications. Distribution runs through authorized distributor networks serving Tier 1 automotive procurement teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into powder synthesis and forward integration into sensor-integrated bearing cartridges define the competitive race. Players capturing both levers control cost structures and pricing power across electrified powertrain and aerospace segments.
For Market Incumbents: Hedge against Asian precursor volatility by expanding captive sintering in Katowice and Wrocław special economic zones. Secure aerospace qualification pipelines before Iberian satellite constellation programs mature. Reinforce technician apprenticeship partnerships with Stuttgart and Munich technical institutes to address ceramic grinding capacity constraints. For New Entrants and Emerging Players: Tier 2 automotive suppliers in France and Spain represent the most penetrable channel partner type for hybrid bearing qualification. Target reconditioning service bundling where established infrastructure gaps exist in Portuguese aerospace sub-tiers. Pursue CSRD-compliant powder-to-finish traceability as the go-to-market wedge against legacy steel bearing incumbents. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap ceramic element specialists with validated EMA medical device certifications. Five-to-ten year viability hinges on sintering capacity location within EU carbon-border adjustment zones. Watch for F-Gas Regulation phase-out acceleration as the inflection signal requiring furnace technology reinvestment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Powder Synthesis | Captive silicon nitride production in Poland reduces carbon-border exposure for Scandinavian wind OEMs. |
| Sensor-Integrated Bearing Cartridge Development | Per-kilometer pricing contracts with German automotive tier-ones lock in long-term service revenue. |
| Cobalt-Free Grinding Process Revalidation | REACH Annex XIV compliance secures medical device procurement tenders in Dutch imaging clusters. |
| Apprenticeship Pipeline Expansion | German-Swiss ceramic grinding technician programs address G5 tolerance capacity bottlenecks. |
| Iberian Aerospace Qualification Partnership | First-mover positioning in Spanish satellite constellation programs bypasses Nordic incumbent channels. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Europe Ceramic Ball Bearings Market assessment. Primary interviews with bearing procurement managers at German automotive OEMs, biomedical engineers at Dutch imaging equipment manufacturers, and aftermarket service heads at Scandinavian wind turbine operators combined with ECHA substance restriction databases, EU Green Deal policy trackers, and CE marking compliance registries. Bottom-up volume modeling and top-down value triangulation validated segment-level outputs.
Granularity-level modeling deployed product type, end user, application, and size dimensions at the country level across Germany, France, Italy, Poland, and Netherlands. CAGRs derived from regression analysis of historical procurement volumes and forward projection of electrified powertrain penetration rates. Analysis window spans from base year through forecast horizon without annual disaggregation. Industry-specific inputs included silicon nitride powder regionalization trends and F-Gas Regulation compliance cost curves.
Caveats apply where EMA medical device regulation amendments or EU Green Deal carbon-border adjustment rate changes could materially shift the outlook. Forecasts reflect assumptions on powder synthesis capacity expansion timelines and automotive platform cycle compression. A model refresh is warranted upon material change in REACH Annex XIV authorization schedules for grinding compound chemistry.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Alloys
Battery Alloys Market
Advanced Alloys
Oxide Dispersion Strengthened (ODS) Alloys Market
Advanced Alloys
Aluminum Composite Panel Market
Advanced Alloys
Global High Performance Alloys Market
Advanced Alloys
Molybdenum Disilicide Market
Advanced Alloys
Ballistic Material Market
Advanced Alloys
High Strength Steel (HSS) Market
Advanced Alloys
Brazing Alloys Market
Advanced Alloys
Multi-Metal Aluminum Sandwich Panels Market
Advanced Alloys
Cobalt Alloy Powder Market
Advanced Alloys
Medium Entropy Alloys Market
Advanced Alloys
Global Aluminum Foams Market
Advanced Alloys
Europe Aluminum Casting Market
Advanced Alloys
Global Metal Injection Molding Market
Advanced Alloys
Precipitation Hardening Market
Advanced Alloys
Global Shape Memory Alloys Market