
 North America Geopolymer Market | 2026-2036
North America Geopolymer Market Size, Share, and Industry Trends Forecast 2026-2036
North America Geopolymer Market Insights
Modular pre-mixed binder systems is repositioning procurement patterns across the North America geopolymer market, letting contractors order site-specific activator-to-precursor ratios rather than bulk raw materials. CEMEX leverages its established ready-mix distribution network to push pre-blended geopolymer skids into municipal infrastructure bids. BASF anchors its position through formulation intellectual property around alkali-activated slag chemistry. Wagners competes on geographic dominance, operating production nodes tied to Queensland-derived fly ash import channels into western Canadian oil sands remediation.
Geopolymers are inorganic aluminosilicate binders formed through alkali activation of industrial byproducts or natural pozzolans, typically achieving compressive strengths of 20–80 MPa within 24 hours without Portland cement hydration chemistry. Their primary commercial purpose centers on carbon-intensive infrastructure substitution, delivering 60–80% lower embodied CO2 than conventional concrete in structural and non-structural applications. Fly ash formulations currently lead volume uptake across the North American installed base, reflecting abundant utility waste stream access and ASTM C618 compliance pathways. Construction applications command the dominant value share, though oil and gas well abandonment and fire-resistant tunnel linings represent faster-growing margin pools where thermal stability above 1000°C commands specification premiums.
The EPA coal combustion residuals rule and ASTM international standards govern precursor sourcing and leachate performance, while Canada's CSA A3001 permits geopolymer classification under supplementary cementing materials, creating cross-border specification harmonization pressure. State-level buy-clean procurement mandates in California and New York directly embed embodied carbon thresholds that favor alkali-activated binders in public project bids. Stakeholders must monitor pending MEE-equivalent federal classification debates in Ottawa and Washington, as geopolymer recognition under national building codes will determine whether insurance and bonding markets treat these materials as equivalent-risk substitutes for conventional concrete.
Market Dynamics
Modular pre-mixed binder systems are restructuring procurement economics across the North America geopolymer market, compressing the traditional bulk-material supply chain into site-specific activator-to-precursor formulations delivered via established ready-mix networks.
Growth Catalysts
- EPA Coal Combustion Residuals Rule:Federal classification of fly ash as non-hazardous under Subtitle D accelerates utility waste stream valorization into ASTM C618-compliant supplementary cementitious materials for infrastructure concrete.
- Buy-Clean Procurement Mandates:California and New York state-level embodied carbon thresholds in public project bids directly specify alkali-activated binders over Portland cement for bridge decks and marine structures.
- Hurricane-Resistant Infrastructure:Gulf Coast petrochemical facility construction and coastal hardening projects specify geopolymer concrete for chloride resistance and thermal stability in marine pilings.
Market Restraints
- Alkali Activator Cost Volatility:Sodium hydroxide and sodium silicate prices fluctuate with industrial chemical feedstock markets, compressing formulation margins against fixed-bid municipal infrastructure contracts.
- Precursor Supply Concentration:Fly ash availability concentrates in utility corridors tied to coal-fired generation retirement schedules, creating regional sourcing gaps in the Northeast and Pacific Northwest.
- Building Code Recognition Gaps:Pending MEE-equivalent federal classification debates in Ottawa and Washington delay insurance and bonding market equivalence treatment for geopolymer structural applications.
Strategic Opportunities
- Western Canadian Oil Sands Remediation:Alberta well abandonment regulations create demand for thermally stable geopolymer grouts in thermal recovery zone plugging and fire-resistant tunnel lining specifications.
- CSA A3001 Harmonization Pressure:Canadian supplementary cementing material classification creates cross-border specification momentum for US producers seeking unified North American product certifications.
- Pre-Blended Skid Distribution:Ready-mix channel partnerships enable contractor bypass of on-site batching complexity, opening municipal infrastructure segments previously blocked by technical qualification barriers.
Industry Challenges
- Alkali-Activation Chemistry Expertise Gap:Formulation chemistry skill scarcity constrains quality control at ready-mix plants transitioning from Portland cement hydration protocols to aluminosilicate dissolution kinetics.
- ASTM C618 Certification Timelines:Supplementary cementitious material testing protocols extend project qualification cycles, delaying first-pour approvals on fixed-schedule public works contracts.
- Legacy Concrete Specification Inertia:Structural engineering firms and municipal procurement departments maintain Portland cement default clauses despite demonstrated geopolymer performance equivalence in comparable applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Geopolymer Market |
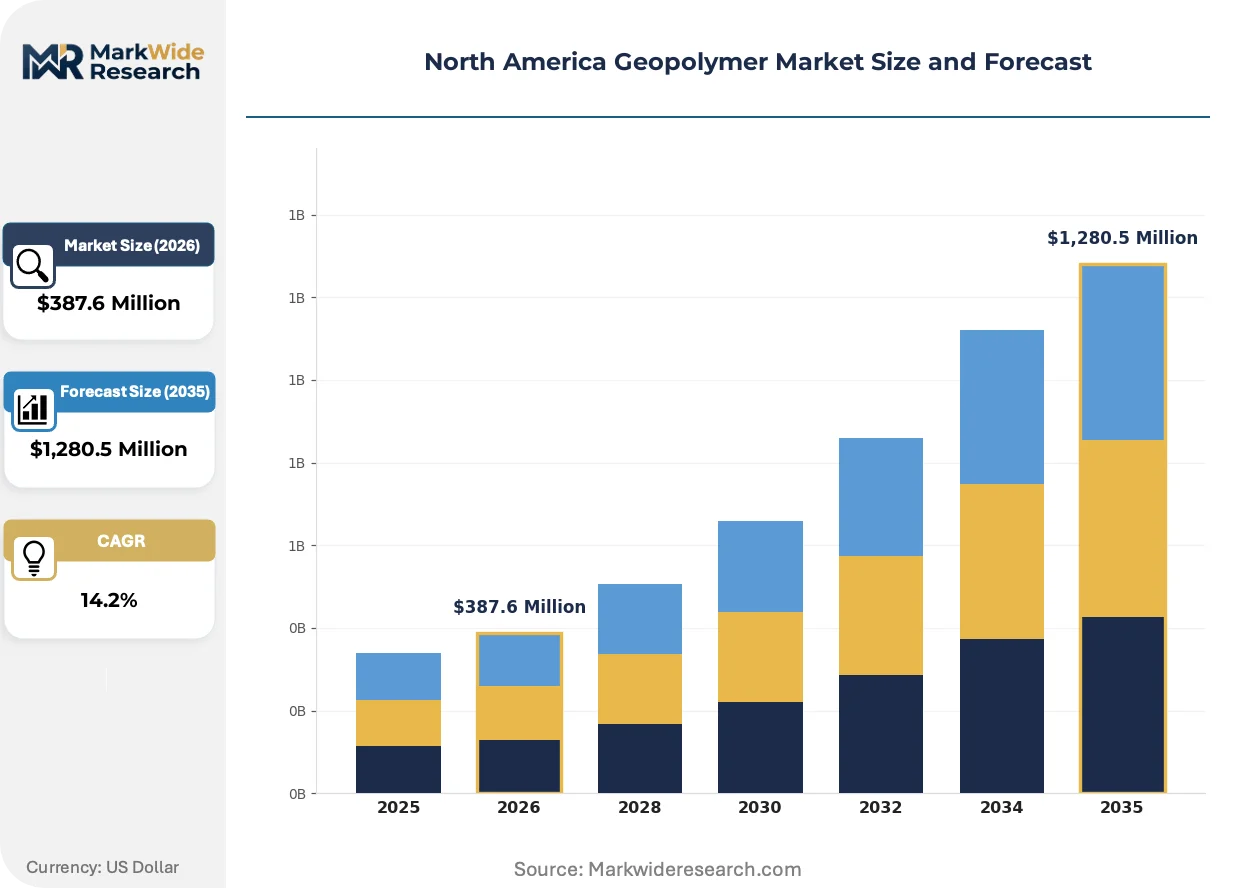
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,280.5 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metakaolin, Fly Ash, GGBS, Others Application: Construction, Waste Management, Fire Resistant Materials, Oil & Gas End User: Infrastructure, Manufacturing, Energy, Automotive Delivery Mode: Pre-mixed, On-site Mixing, Ready-to-use, Custom Solutions |
| Companies Covered | Alchemy Geopolymer Solutions, PCI Augsburg GmbH, CEMEX, Commercial Metals Company, Betolar PLC, SLB, Wagners, BASF, Critica Infrastructure, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Geopolymer Market Trends and Innovations
Formulation chemistry and distribution logistics are converging to compress the traditional bulk-material supply chain into precision-delivered binder systems, reshaping how contractors source and deploy alkali-activated materials on project sites.
Pre-blended geopolymer binder technology is modularizing site logistics for municipal infrastructure contractors. Gulf Coast bridge deck projects now receive activator-to-precursor ratios pre-calibrated to local aggregate chemistry, eliminating on-site batching errors that previously delayed first-pour approvals. This modularization collapses the qualification timeline from months to weeks, opening public works segments that specification inertia had blocked.
California's Buy-Clean procurement mandate and New York's analogous embodied carbon thresholds are embedding geopolymer concrete into public infrastructure specifications. State agencies now require environmental product declarations comparing alkali-activated binders against Portland cement baselines for bridge and marine contracts. Municipal procurement departments across both states are rewriting default material clauses to accommodate these verified lower-carbon alternatives.
Contractor purchasing behavior is pivoting from bulk raw material procurement to outcome-based binder system subscriptions. Petrochemical facility operators in Texas and Louisiana now specify compressive strength guarantees rather than mix design compliance, transferring formulation risk to ready-mix suppliers. This performance contracting model concentrates volume with distributors capable of site-specific quality assurance, marginalizing traditional bulk-precursor merchants.
North America Geopolymer Market Segmentation
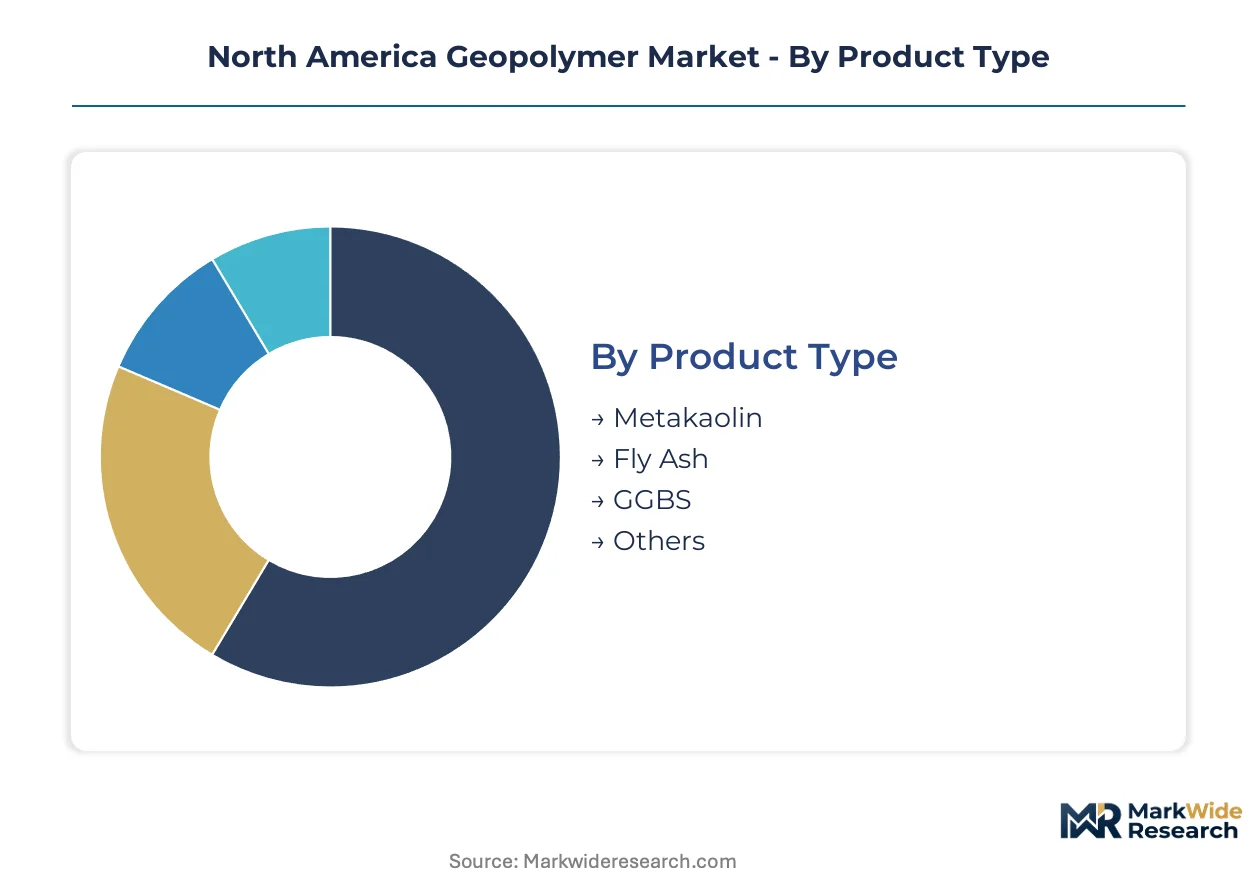
Segmentation in the North America geopolymer market reveals how precursor chemistry, application requirements, and procurement logistics intersect to determine competitive positioning. Each dimension exposes different margin structures and technical barriers that shape supplier strategy across the United States and Canada.
Product Type:
Fly ash supply concentrates in utility corridors along the Ohio River Valley and Texas lignite belt, creating geographic lock-in for producers seeking ASTM C618-compliant feedstock.
- Fly Ash:Coal combustion byproduct with aluminosilicate content exceeding 70% by mass, forming the dominant installed base across Gulf Coast infrastructure projects. Demand clusters in Texas and Louisiana bridge deck specifications where chloride resistance commands premium pricing.
- GGBS:Ground granulated blast-furnace slag delivering superior sulfate resistance and lower alkali-silica reactivity compared to fly ash formulations. Steel mill proximity in Indiana and Ontario determines viable sourcing radii for municipal concrete suppliers.
- Metakaolin:Calcined kaolin clay with controlled amorphous silica content for high-performance architectural applications.
- Others:Natural pozzolans including volcanic ash and rice husk ash serving niche regional specifications.
Fly Ash absorbs the bulk of installed capacity; GGBS is expanding most quickly.
Application:
Construction dominates volume throughput while specialized industrial applications capture disproportionate margin pools through thermal performance premiums.
- Construction:Structural and non-structural concrete applications spanning bridge decks, marine pilings, and precast elements. California Buy-Clean mandates and New York embodied carbon thresholds are redirecting public procurement toward alkali-activated binders for highway infrastructure.
- Oil & Gas:Well abandonment grouts and zonal isolation materials requiring thermal stability above 300°C in thermal recovery zones. Alberta regulatory pressure on orphaned well remediation is accelerating specification shifts in western Canadian oil sands.
- Fire Resistant Materials:Tunnel linings and passive fire protection systems leveraging geopolymer refractory properties.
- Waste Management:Stabilization and solidification matrices for hazardous waste encapsulation.
Construction commands the dominant share of production volume; Oil & Gas applications are climbing the fastest on a value-per-ton basis.
End User:
Infrastructure agencies and energy operators maintain divergent procurement protocols that fragment supplier relationships across the value chain.
- Infrastructure:State departments of transportation and municipal public works specifying geopolymer concrete for bridge rehabilitation and coastal hardening. FHWA demonstration projects in Florida and South Carolina are establishing performance baselines for chloride exposure environments.
- Energy:Power utilities and oil field service companies sourcing thermally stable grouts for well plugging and fire containment. Alberta Energy Regulator timelines for thermal recovery zone abandonment are compressing qualification cycles for Canadian suppliers.
- Manufacturing:Precast concrete producers and refractory manufacturers integrating alkali-activated binders into product lines.
- Automotive:Lightweight composite applications and fire-resistant component housings.
Infrastructure accounts for the majority of contracted volume; Energy sector uptake is gaining share fastest through regulatory-driven well abandonment demand.
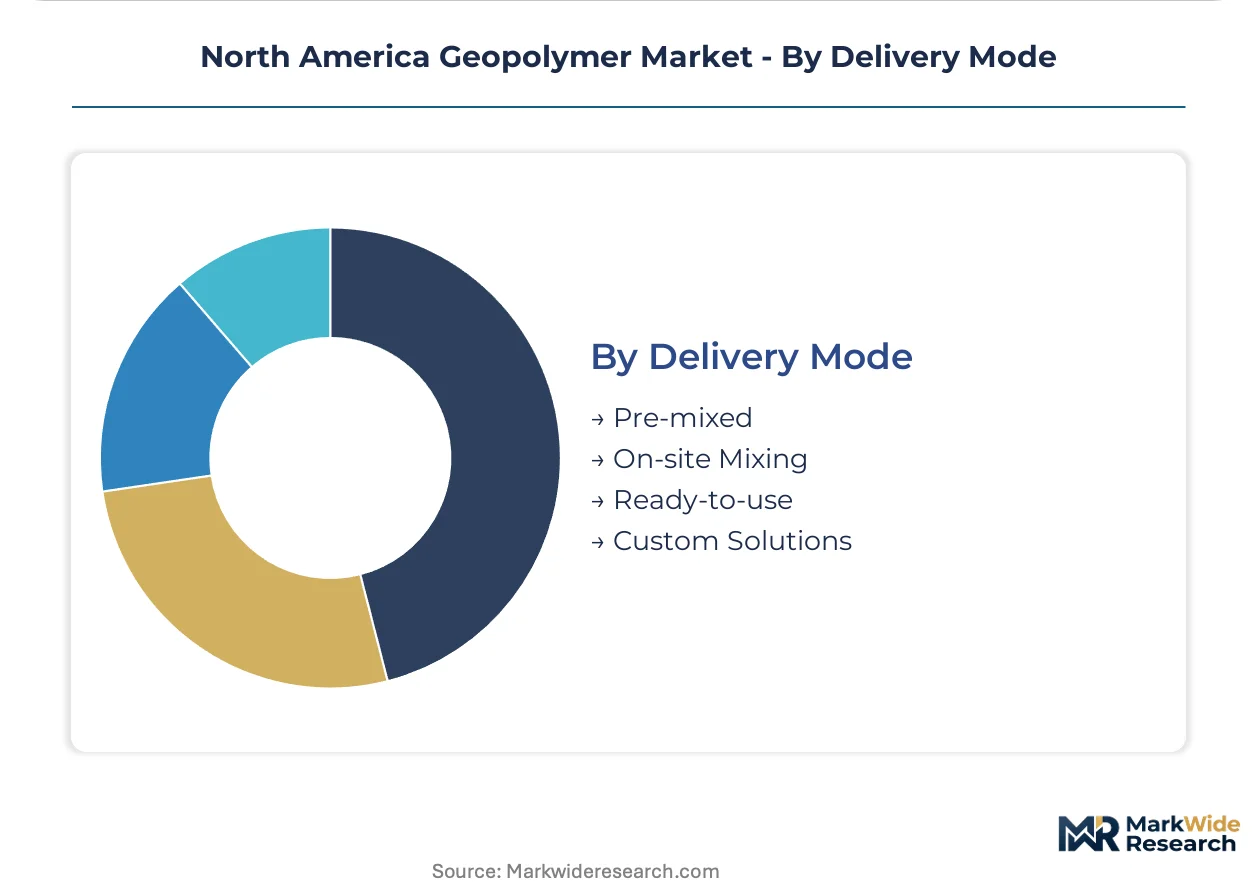
Delivery Mode:
Procurement patterns are shifting from bulk raw material purchasing toward outcome-based supply arrangements that transfer formulation risk to distributors.
- Pre-mixed:Activator-to-precursor blends calibrated to regional aggregate chemistry and delivered via established ready-mix networks. CEMEX distribution partnerships in Texas municipal markets are eliminating on-site batching barriers that previously delayed first-pour approvals.
- Ready-to-use:Single-component binder systems requiring only water addition at point of placement. Gulf Coast petrochemical contractors are migrating toward compressive strength guarantees rather than mix design compliance, concentrating volume with suppliers capable of site-specific quality assurance.
- On-site Mixing:Separate precursor and activator delivery for large-scale projects with dedicated batching facilities.
- Custom Solutions:Project-specific formulations engineered for unique performance or environmental constraints.
Pre-mixed delivery captures the largest share of new contract awards; Ready-to-use systems are expanding most quickly among contractors lacking in-house alkali-activation expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in utility corridors along the Ohio River Valley and Texas lignite belt, while consumption clusters in Gulf Coast infrastructure corridors and western Canadian oil sands regions. This geographic mismatch shapes logistics costs and precursor availability across the continent.
United States
Bridge deck rehabilitation and marine piling projects drive specification volumes in Florida and South Carolina coastal zones. The EPA's Coal Combustion Residuals Rule under Subtitle D accelerates fly ash valorization into ASTM C618-compliant supplementary cementitious materials. Texas and Louisiana petrochemical facility construction commands premium pricing for chloride-resistant formulations along the Gulf Coast corridor.
Canada
Alberta's orphaned well abandonment regulations compress qualification cycles for thermally stable geopolymer grouts in thermal recovery zones. CSA A3001 classification permits geopolymer recognition under supplementary cementing materials, creating specification harmonization pressure with US markets. Western Canadian oil sands remediation projects in Alberta and Saskatchewan specify fire-resistant tunnel linings for thermal recovery zone plugging.
Mexico
Infrastructure modernization along the T-MEC trade corridor generates demand for low-carbon concrete alternatives in bridge and highway construction. The country's national standards body develops alignment pathways with ASTM C618 for cross-border project specifications. Northern border states concentrate pilot projects testing alkali-activated binders in municipal public works contracts.
North America Geopolymer Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across a bifurcated market structure. Ready-mix distribution networks anchor one strategic cluster, while formulation chemistry intellectual property anchors another. The third archetype centers on geographic dominance through precursor supply control. Capacity expansion through modular pre-blended skid systems and strategic partnerships with municipal procurement departments constitute the dominant competitive moves reshaping market access.
Among diversified construction material conglomerates, CEMEX and BASF occupy positions that exemplify scale-driven distribution leverage and formulation chemistry specialization respectively. Wagners represents the geographic dominance archetype through production nodes tied to fly ash import channels. These three companies illustrate how procurement pattern shifts toward outcome-based supply arrangements favor entities combining ready-mix network access with site-specific quality assurance capabilities.
| Leading Market Players |
|---|
| Alchemy Geopolymer Solutions |
| PCI Augsburg GmbH |
| CEMEX |
| Commercial Metals Company |
| Betolar PLC |
| SLB |
| Wagners |
| BASF |
| Critica Infrastructure |
| Others |
Pricing and Supply Chain Analysis
California's Buy-Clean procurement mandate and New York's embodied carbon thresholds are forcing municipal contractors toward pre-blended geopolymer systems, compressing margins for bulk-precursor merchants while rewarding suppliers with ready-mix network access and site-specific quality assurance capabilities.
Pricing Analysis
Cost-down pressure on municipal infrastructure tiers accelerates as fixed-bid contracts collide with sodium hydroxide and sodium silicate price volatility tied to industrial chemical feedstock markets. Three-tier pricing structure across performance-guaranteed, specification-compliant, and bulk-raw-material levels separates contractors with in-house alkali-activation expertise from those dependent on distributor quality assurance. Price differentiation hinges on ASTM C618 certification status and volume scale, with state DOTs least sensitive to per-ton premiums when environmental product declarations demonstrate embodied carbon reductions.
Supply Chain Analysis
Specialized geopolymer formulation chemists concentrate in Texas Gulf Coast petrochemical corridors and Ontario steel-belt regions, creating workforce bottlenecks that constrain quality control at ready-mix plants transitioning from Portland cement protocols. Supply draws from Ohio River Valley fly ash utility corridors, Indiana steel-slag processing nodes, and Queensland-import channels serving western Canadian oil sands remediation. Single-source vulnerability concentrates in coal-fired generation retirement schedules, while distribution runs through CEMEX and BASF ready-mix partnerships that bypass on-site batching complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America geopolymer market is consolidating around suppliers combining formulation chemistry IP with ready-mix distribution scale, as alkali-activation expertise scarcity and ASTM C618 certification timelines force weaker bulk-precursor merchants toward acquisition or exit.
For Market Incumbents: To counter margin compression from sodium silicate feedstock volatility, deepen captive supply of alkali activators through backward integration into chemical manufacturing partnerships, and lock municipal infrastructure volume through pre-blended skid distribution agreements that transfer formulation risk to contractors. For New Entrants and Emerging Players: Modular pre-mixed binder technology offers entry into Texas and Louisiana petrochemical facility construction, where compressive strength guarantees displace mix-design compliance as the procurement standard. Target Alberta orphaned well abandonment demand, where thermally stable grout specifications outpace established supplier qualification cycles. For Investors and Strategic Acquirers: The window for entry favors ready-mix distributors with dormant alkali-activation capability and ASTM C618 testing infrastructure. Watch for CSA A3001 harmonization momentum with US building codes as the inflection signal that triggers insurance and bonding market equivalence treatment for geopolymer structural applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alkali Activator Supply | CEMEX and BASF partnerships with sodium silicate producers hedge feedstock volatility threatening municipal contract margins. |
| Pre-Blended Skid Distribution Expansion | Ready-mix channel partnerships compress qualification timelines from months to weeks for Gulf Coast bridge deck projects. |
| CSA A3001 Harmonization Investment | Cross-border certification alignment opens unified North American product positioning for US producers seeking Canadian infrastructure access. |
| ASTM C618 Testing Infrastructure Buildout | In-house supplementary cementitious material protocols accelerate first-pour approvals on fixed-schedule public works contracts. |
| Alberta Oil Sands Remediation Partnership | Wagners' Queensland fly ash import channels anchor western Canadian thermal recovery zone abandonment demand. |
Research Methodology
EPA coal combustion residuals filings, ASTM International standards documentation, and state procurement database records formed the secondary backbone, cross-referenced with primary interviews of ready-mix plant managers, municipal public works procurement officers, geopolymer formulation chemists, and oil field service company supply chain directors. Bottom-up and top-down triangulation validated volume estimates against utility fly ash production data and construction material customs records.
Bottom-up modeling aggregated project-level specifications across Texas, Louisiana, California, New York, Alberta, and Saskatchewan infrastructure contracts, while top-down analysis calibrated against ACC construction material forecasts and Canadian cement association demand surveys. Segmentation dimensions included precursor chemistry type, application requirement, delivery mode, and end-user procurement protocol. CAGRs derived from regression analysis of historical specification adoption rates and regulatory mandate implementation timelines, with oil and gas well abandonment regulatory pressure and state-level embodied carbon thresholds as key forecast inputs.
Several conditions sit outside the modeled scope, including pending MEE-equivalent federal classification outcomes in Ottawa and Washington, coal-fired generation retirement schedules affecting fly ash availability, and sodium hydroxide commodity price shocks. Forecasts reflect documented assumptions regarding cross-border specification harmonization and insurance market equivalence treatment. Material deviation in CSA A3001-US building code alignment or alkali activator cost volatility warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Biaxially Oriented Polypropylene Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Water-Borne Resins Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
Germany Engineering Plastics Market
Polymers & Resins
C9 Resin Market
Polymers & Resins
Europe Polyolefin Foam Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
North America Polyisoprene Market
Polymers & Resins
Emulsion PVC Market
Polymers & Resins
Glutathione Resin Market
Polymers & Resins
Global VAE Emulsion Market
Polymers & Resins
Polyamide 12 Market