
 Italy Automotive Thermoplastic Polymer Composites Market | 2026-2036
Italy Automotive Thermoplastic Polymer Composites Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive Thermoplastic Polymer Composites Market Foresight
Tier-1 suppliers is bifurcating from traditional OEM-direct procurement as EV platform architects specify thermoplastic composites earlier in design cycles. Celanese Corporation leverages its European compounding network to supply high-flow nylon grades for powertrain housings. Solvay Group anchors its position through fluoropolymer-modified blends targeting thermal management applications. DuPont de Nemours differentiates via Zytel RS bio-based polyamide lines qualified by Italian luxury automakers.
Automotive thermoplastic polymer composites are fiber-reinforced or mineral-filled thermoplastic matrices processed by injection molding, compression molding, or thermoforming, typically achieving densities below 1.5 g/cm³ while retaining tensile strengths above 100 MPa. These materials substitute metal stampings to reduce vehicle curb weight and enable parts consolidation in crash-critical structures. Polypropylene dominates volume consumption in interior door panels and bumper beams where cost-performance ratios favor commodity grades. Nylon captures premium margin pools in under-the-hood charge air coolers and transmission covers requiring continuous-use temperatures above 150°C. Structural applications represent the fastest-expanding category as unidirectional tape overmolding gains traction in seat back frames and front-end carriers.
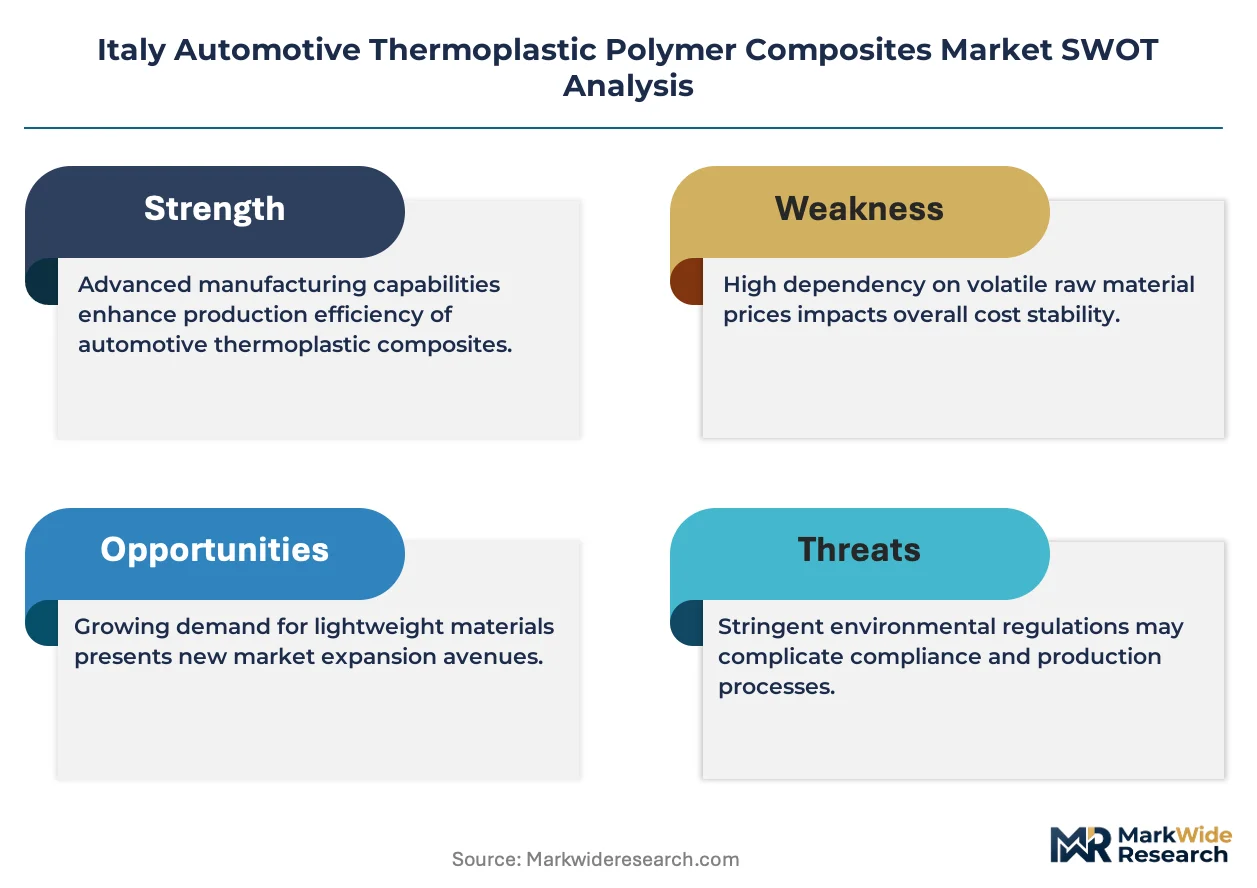
Italy's Ministry of Enterprise and Made in Italy administers automotive supplier transition grants tied to EU Green Deal decarbonization benchmarks. ECHA REACH restrictions on legacy flame retardants are forcing reformulation of polycarbonate blends for interior applications. The National Recovery and Resilience Plan allocates dedicated funding streams for circular material verification and recycling infrastructure. Stakeholders must monitor evolving EU End-of-Life Vehicle Directive recyclability mandates and pre-qualify next-generation short-glass polypropylene compounds before platform engineering lock dates.
Market Dynamics
Electric vehicle platform architecture is restructuring supplier-OEM relationships in Italy's automotive thermoplastic polymer composites sector, with Stellantis engineering teams now embedding material specifications three to four years ahead of production ramp.
Growth Catalysts
- EU Green Deal decarbonization benchmarks:Italy's Ministry of Enterprise ties automotive supplier transition grants to these targets, redirecting capital toward recycled-content thermoplastic compounds.
- Lightweighting mandates in powertrain housings:High-flow nylon grades are capturing design slots previously held by aluminum castings as thermal management requirements intensify.
- Piedmont-Turin supplier clustering:Tier-1 compounders co-locating near Stellantis headquarters compress development cycles and enable same-day technical troubleshooting.
Market Restraints
- PA66 feedstock volatility:Caprolactam and adipic acid price swings compress margin predictability for nylon composite processors serving under-the-hood applications.
- ECHA REACH flame retardant restrictions:Legacy halogenated additives face phase-out timelines, forcing polycarbonate blend reformulations with unproven alternative chemistries.
- Steel substitution economics:Hot-stamped ultra-high-strength steel retains cost advantage in A and B pillar applications where thermoplastic composites cannot match crash energy absorption per euro.
Strategic Opportunities
- Lombardy battery enclosure supply chain:Northern Italian automotive electronics manufacturers are qualifying short-glass polypropylene for module housings as EV battery production scales.
- National Recovery and Resilience Plan circular material verification:Dedicated funding streams enable pre-competitive testing infrastructure for post-industrial recycled feedstocks.
- Unidirectional tape overmolding convergence:Continuous fiber thermoplastics are penetrating seat back frames and front-end carriers as automated placement equipment reaches Italian Tier-1 shops.
Industry Challenges
- End-of-Life Vehicle Directive recyclability pre-qualification:OEM platform engineering lock dates now precede full material certification, forcing suppliers to commit to unvalidated recycling pathways.
- Multi-material bonding expertise scarcity:Italian compounders lack sufficient polymer-metals adhesion specialists for hybrid structural assemblies combining thermoplastic composites with aluminum castings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive Thermoplastic Polymer Composites Market |
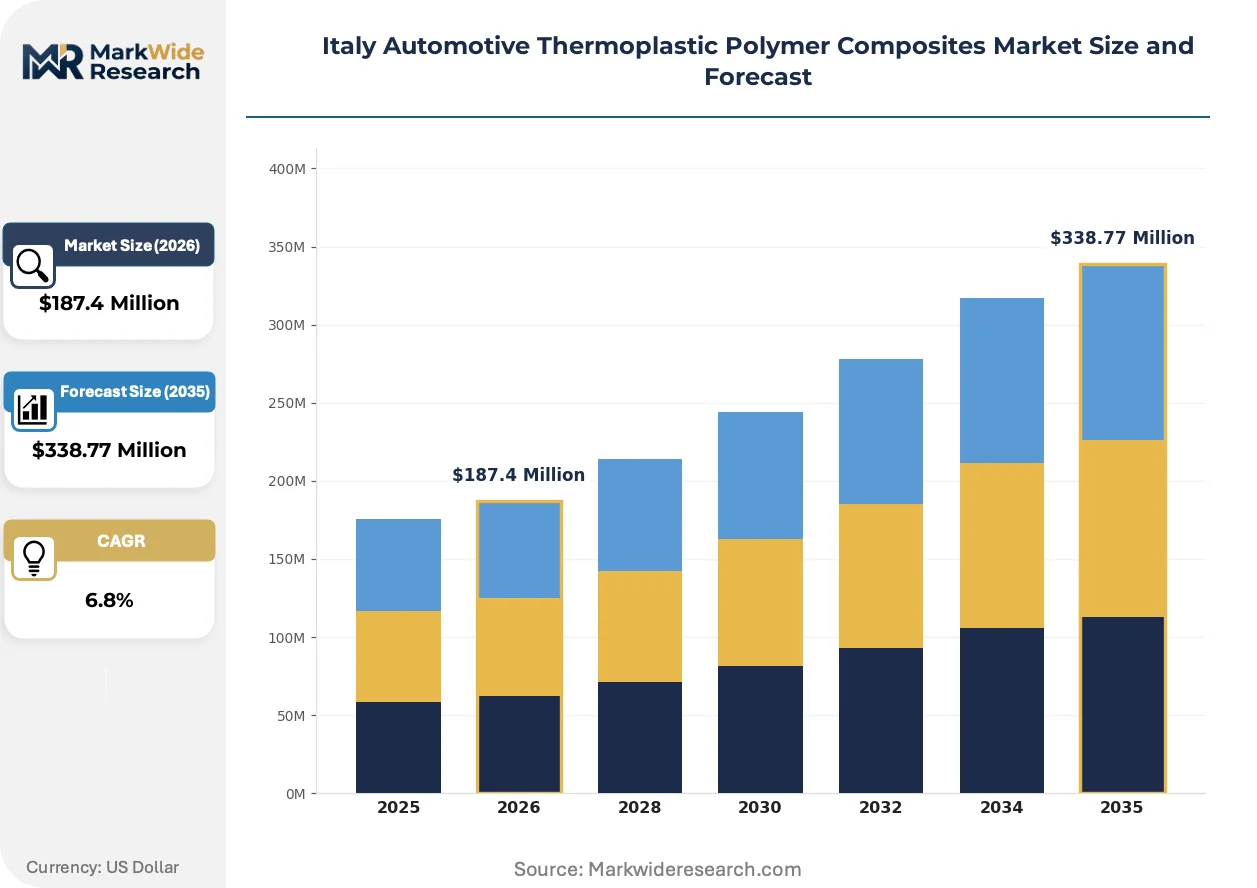
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polypropylene, Polycarbonate, Nylon, ABS Application: Interior, Exterior, Structural, Under-the-Hood End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Form: Sheets, Molds, Films, Blends |
| Companies Covered | 3B-Fiberglass, DuPont de Nemours, Solvay Group, Hexcel Corporation, Celanese Corporation, BASF SE, Gurit Holding, Base Group, Arkema Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive Thermoplastic Polymer Composites Market Shifts & Advancements
Material-process combinations are proliferating across Italy's automotive supply base as EV thermal management requirements and circular economy mandates rewrite established qualification protocols.
Continuous fiber-reinforced thermoplastic tapes are fragmenting the structural composites landscape. Tier-1 suppliers in Emilia-Romagna are adopting automated fiber placement for battery tray reinforcements. This technology is fragmenting incumbent sheet molding compound positions in load-bearing applications.
REACH restrictions on legacy brominated flame retardants are forcing interior polycarbonate blend reformulations. Compounders must validate phosphorus-based alternatives without sacrificing Vicat softening temperatures above 140°C. Italian luxury automakers are demanding accelerated certification timelines that compress standard two-year validation cycles.
Platform engineering teams now specify recycled-content grades at concept phase rather than post-design optimization. Stellantis procurement is embedding circular material requirements into RFQ templates. This pattern concentrates most acutely in Turin-area development centers where sustainability scorecards influence supplier selection.
Italy Automotive Thermoplastic Polymer Composites Market Segmentation
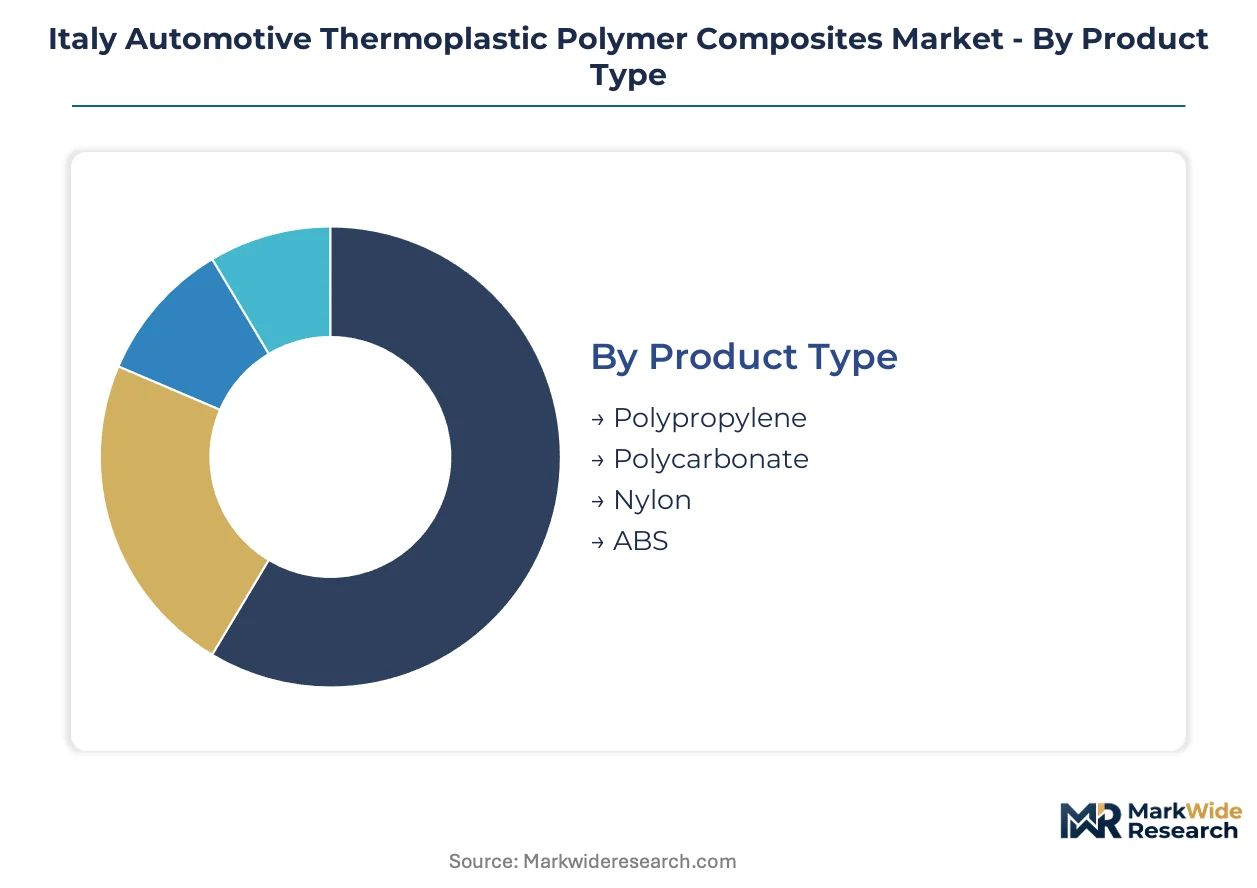
Material selection in Italy's automotive thermoplastic composites sector hinges on thermal performance thresholds and recyclability mandates under EU Green Deal frameworks. Segmentation reveals how regulatory pressure and EV platform requirements are redistributing volume across resin grades and application categories.
Product Type:
ECHA REACH restrictions on legacy additives and thermal management specifications in EV powertrains are creating divergent compliance pathways across resin families.
- Polypropylene:Short-glass reinforced grades dominate bumper beams and interior door panels due to density advantages below 1.2 g/cm³. Stellantis procurement in Turin specifies recycled-content PP for non-structural components to meet National Recovery and Resilience Plan circular economy benchmarks.
- Nylon:PA6 and PA66 compounds with 30-50% glass fiber reinforcement capture charge air coolers and transmission housings requiring continuous-use temperatures above 150°C. Caprolactam feedstock volatility from European adipic acid suppliers compresses margin stability for compounders serving Piedmont's automotive cluster.
- Polycarbonate:Flame-retardant blends face reformulation pressure as brominated additives phase out under REACH timelines.
- ABS:Interior trim applications favor this resin for surface aesthetics and processability in injection molding operations.
Polypropylene handles the majority of throughput; Nylon is the fastest mover on share as thermal management demands intensify.
Application:
Cost tier differentiation separates commodity interior parts from premium structural assemblies requiring automated fiber placement equipment.
- Under-the-Hood:Nylon composites displace aluminum castings in powertrain housings where thermal conductivity and chemical resistance intersect. Stellantis engineering teams in Turin now embed these specifications three to four years ahead of production ramp.
- Structural:Unidirectional tape overmolding penetrates seat back frames and front-end carriers as continuous fiber thermoplastics gain automated placement capabilities at Tier-1 suppliers in Emilia-Romagna.
- Interior:Polycarbonate and ABS blends serve dashboard carriers and trim panels where Vicat softening temperatures must exceed 140°C under revised flame retardant protocols.
- Exterior:Polypropylene-based solutions retain position in bumper systems and fender liners where impact resistance and paint adhesion requirements balance.
Under-the-Hood commands the premium margin pool; Structural applications are climbing the fastest as EV platform architectures proliferate.
End User:
Customer type determines qualification timelines and technical collaboration intensity across Italy's supplier ecosystem.
- Tier-1 Suppliers:Compounders co-located near Stellantis headquarters in Piedmont compress development cycles through same-day engineering troubleshooting and rapid prototyping capabilities.
- OEMs:Stellantis procurement embeds circular material requirements into RFQ templates, concentrating sustainability scorecard influence in Turin-area development centers.
- Vehicle Assemblers:Final assembly operations in Lombardy and Piedmont specify material grades at platform engineering lock dates preceding full recycling pathway validation.
- Aftermarket Providers:Replacement part manufacturers face delayed access to certified recycled-content grades due to OEM exclusivity periods on new compound formulations.
Tier-1 Suppliers manage the deepest technical integration; OEMs are gaining share fastest as direct material specification authority consolidates.
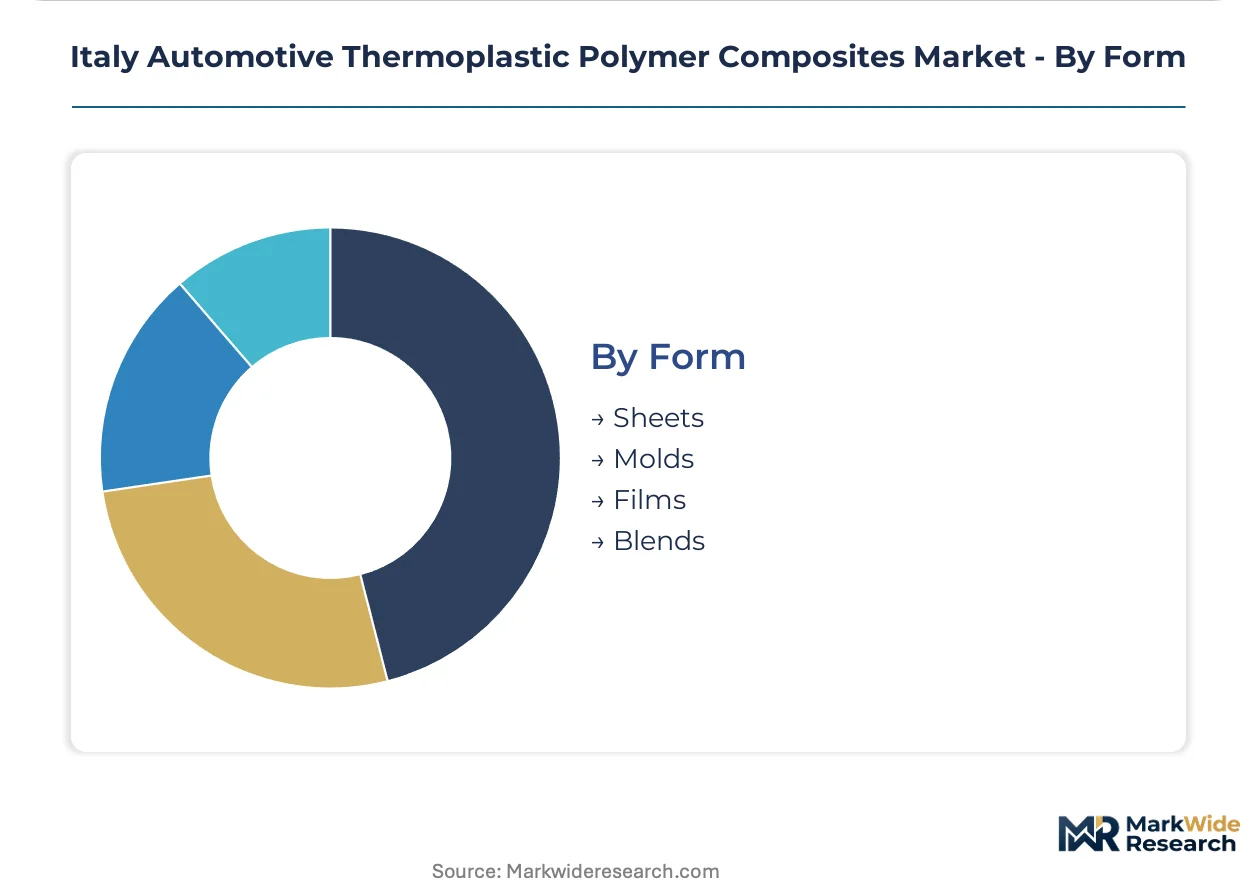
Form:
Supply concentration in northern Italy favors formats compatible with existing injection molding and compression molding infrastructure.
- Molds:Injection molding compounds in pellet form dominate high-volume interior and exterior applications where cycle time optimization drives equipment utilization rates at Piedmont processing facilities.
- Sheets:Thermoformable GMT and LWRT formats serve semi-structural applications including underbody shields and load floors where drapability and impact absorption intersect.
- Blends:Custom compounded formulations with mineral fillers or hybrid fiber reinforcements address specific thermal expansion or acoustic damping requirements.
- Films:Decorative and functional surface layers integrate with substrate materials for Class A interior finishes.
Molds handle the highest production volumes; Sheets are expanding most quickly as semi-structural applications multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stellantis procurement teams concentrate material specification authority in northern Italian engineering centers, while Tier-1 compounders cluster within same-day logistics radius of Turin and Milan.
Piedmont
Turin anchors Italy's automotive thermoplastic composites demand through Stellantis engineering headquarters and co-located Tier-1 supplier compounds. The National Recovery and Resilience Plan channels supplier transition grants toward recycled-content grade verification in this cluster. Celanese Corporation and Solvay Group maintain technical service laboratories in the province to compress development cycles for powertrain housing specifications.
Lombardy
Milan's automotive electronics manufacturers drive qualification of short-glass polypropylene for EV battery module housings as production scales. EU Green Deal decarbonization benchmarks shape procurement templates issued by vehicle assemblers in the region. Brescia and Bergamo host compounding operations serving under-the-hood thermal management applications with nylon grades.
Emilia-Romagna
Modena and Bologna house automated fiber placement equipment installations for unidirectional tape overmolding in seat back frames. Tier-1 suppliers in this corridor adopt continuous fiber thermoplastics for battery tray reinforcements. The region's machine tool heritage accelerates equipment integration timelines for structural composite processes.
Veneto
Vicenza and Verona process mineral-filled polypropylene compounds for interior door panels and bumper systems serving premium vehicle programs. ECHA REACH restrictions on legacy flame retardants force reformulation of polycarbonate blends at compounding facilities in the province. Suppliers here specialize in Class A surface finishes for luxury automaker specifications.
Italy Automotive Thermoplastic Polymer Composites Market Competitive Landscape
Player mix skews toward integrated material science conglomerates with European compounding networks and specialized fiber reinforcement suppliers. Three archetypes dominate: resin compounders with automotive qualification expertise, glass fiber manufacturers controlling upstream reinforcement supply, and diversified chemical groups leveraging fluoropolymer modification capabilities. Competitive moves concentrate on co-location near Stellantis engineering centers and pre-competitive testing infrastructure for recycled-content grades under National Recovery and Resilience Plan funding.
Within the integrated chemical group tier, DuPont de Nemours, Solvay Group, and Celanese Corporation exemplify positioning strategies. DuPont occupies a role representing bio-based polyamide development for luxury automaker specifications. Solvay anchors fluoropolymer-modified blend capabilities targeting thermal management applications. Celanese sits within the high-flow nylon grade segment for powertrain housing substitution. Among fiber reinforcement specialists, 3B-Fiberglass and Hexcel Corporation represent distinct technology vectors in glass and advanced fiber formats respectively.
| Leading Market Players |
|---|
| 3B-Fiberglass |
| DuPont de Nemours |
| Solvay Group |
| Hexcel Corporation |
| Celanese Corporation |
| BASF SE |
| Gurit Holding |
| Base Group |
| Arkema Group |
| Others |
Supply & Pricing Matrix
EU Green Deal decarbonization benchmarks gate both supplier qualification and price differentiation simultaneously, as Italian OEM procurement teams embed circular material requirements into RFQ templates before compounders can validate full recycling pathways. This regulatory sequencing compresses margin predictability for nylon composite processors while rewarding early movers with premium positioning in Stellantis engineering specifications.
Pricing Analysis
Current-generation short-glass polypropylene compounds trade at commodity parity, while next-generation unidirectional tape overmolding commands substantial premiums for structural applications. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments. Price differentiation hinges on ECHA REACH compliance status and National Recovery and Resilience Plan circular economy verification. Pricing pressure stems from caprolactam feedstock volatility squeezing nylon compound margins. Tier-1 suppliers serving Piedmont's automotive cluster exhibit lowest price sensitivity due to co-location advantages; aftermarket providers face highest sensitivity from OEM exclusivity periods on recycled-content grades.
Supply Chain Analysis
Adipic acid supply from European petrochemical complexes constitutes a chokepoint for PA66 compounders serving under-the-hood thermal management applications. Raw material sourcing draws from Germany, Belgium, and the Netherlands for caprolactam and specialty additives; glass fiber reinforcement feeds from Italian and German melting operations. Supply chain risk centers on single-source vulnerability for fluoropolymer-modified blend components specified by Solvay Group for battery thermal management. Distribution runs through just-in-time pellet delivery networks from Piedmont compounding facilities to Stellantis assembly plants in Turin and Milan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EV platform architecture fragmentation creates multiple entry points as powertrain electrification splinters material specifications across thermal management, structural, and interior application clusters.
For Market Incumbents: Fortify compounding operations in Piedmont through backward integration into post-industrial recycled feedstock processing, securing National Recovery and Resilience Plan verification ahead of platform engineering lock dates. Expand technical service laboratories near Stellantis headquarters to compress development cycles for high-flow nylon grades. Counter threat from continuous fiber thermoplastic entrants in Emilia-Romagna by pre-qualifying hybrid material solutions for seat back frame applications. For New Entrants and Emerging Players: Differentiate on automated fiber placement equipment integration for battery tray reinforcements, targeting the structural segment where incumbent sheet molding compound positions fragment. Penetrate Lombardy's battery enclosure supply chain through short-glass polypropylene module housing specifications. Pursue go-to-market partnerships with Italian machine tool builders to accelerate equipment qualification timelines at Tier-1 suppliers. For Investors and Strategic Acquirers: EU End-of-Life Vehicle Directive recyclability mandates reshape the acquisition landscape toward compounders with validated circular material pathways and pre-competitive testing infrastructure access. Long-term viability favors integrated material science groups with European compounding networks and fluoropolymer modification capabilities. Target acquisition archetype: mid-cap compounders with Stellantis qualification history and unidirectional tape overmolding pilot lines. Signal to monitor: acceleration of platform engineering lock dates preceding full recycling pathway certification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycled Feedstock Processing | Captures National Recovery and Resilience Plan funding streams while securing circular material verification ahead of competitor qualification cycles. |
| Automated Fiber Placement Equipment Installation | Enables penetration of battery tray and seat back frame applications as continuous fiber thermoplastics displace incumbent sheet molding compounds. |
| Technical Service Laboratory Co-location | Compresses development cycles for high-flow nylon powertrain specifications through same-day engineering troubleshooting with Stellantis platform teams. |
| Fluoropolymer Modification Capability Expansion | Addresses thermal management application growth as EV battery production scales in Lombardy and Piedmont assembly corridors. |
| Pre-competitive Testing Infrastructure Partnership | Secures early access to post-industrial recycled feedstock validation protocols under EU Green Deal circular economy benchmarks. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement directors, compounder technical service managers, and automotive recycling facility operators and refined through secondary validation against vehicle production databases, IHS Markit registration data, SEC filings from listed chemical groups, and EU customs trade statistics. Bottom-up volume estimates from resin grade consumption patterns were triangulated with top-down value projections derived from OEM bill-of-materials analysis.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within each segmentation dimension. The analytical framework models vehicle class, propulsion architecture, content per vehicle, and regional production cluster as core segmentation axes. CAGRs were derived from logistic diffusion curves fitted to EV platform adoption timelines and material substitution elasticity estimates. Industry-specific forecast inputs include Stellantis engineering specification roadmaps and ECHA REACH restriction implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal funding continuity and stable adipic acid feedstock availability would require recalibration. Forecasts reflect documented assumptions regarding platform engineering lock date sequencing and circular material certification timelines. Practitioners should keep alternative scenarios live as ECHA flame retardant restriction timelines and End-of-Life Vehicle Directive recyclability mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Styrene Acrylic Emulsion Polymer Market
Polymers & Resins
N-Vinylformamide Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
Thermosetting Plastics Market
Polymers & Resins
Asia-Pacific Epoxy Resins Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Global Flexible Polyurethane Foam Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Fluorine Polymer Films Market
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Casting Resin Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
Poly (1-Decene) Market
Polymers & Resins
Global Corrosion Resistant Resin Market