
 Europe Medical Polyethylene Market | 2026-2036
Europe Medical Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Medical Polyethylene Market Intelligence
Germany is tilting toward expanded medical-grade polyethylene compounding capacity to serve orthopedic and packaging converters. SABIC sustains polymer science leadership through high-purity resin platforms validated for long-term implant applications. Dow Inc. leverages its European extrusion technology base to supply drug delivery system manufacturers with tight-tolerance tubing grades. LyondellBasell Industries Holdings B.V. anchors the region's high-density polyethylene supply for surgical instrument molds requiring gamma sterilization stability.
Medical polyethylene encompasses thermoplastic resins formulated with ultra-high purity, narrow molecular weight distribution, and validated biocompatibility per ISO 10993 for patient-contact applications. These polymers typically exhibit density ranges from 0.910 to 0.965 g/cm³, melt flow indices tuned to 0.1–50 g/10 min, and are processed via injection molding, extrusion, or blow molding into devices and packaging. Ultra-low molecular weight polyethylene dominates orthopedic bearing surfaces due to its exceptional wear resistance and oxidative stability in joint replacements. Medical packaging applications of low-density polyethylene are expanding fastest as hospitals transition to sterile barrier systems with enhanced seal integrity and peelability.
The EU Medical Device Regulation (MDR) and REACH framework administered by EMA and ECHA are elevating material traceability and substance restriction requirements for implantable and patient-contact polymers. CE marking under MDR now demands extended clinical evidence and supply chain documentation that favors established European compounders with quality management systems. The EU AI Act and forthcoming CSRD disclosures will add algorithmic transparency and sustainability reporting layers to manufacturing operations. Stakeholders must monitor regulatory harmonization between national competent authorities and the evolving interface between polymer chemistry and digital health device classifications.
Market Dynamics
EU MDR compliance deadlines are compressing certification timelines for implant-grade polyethylene converters, forcing compounders to rebuild quality management systems around extended clinical evidence requirements and supply chain documentation protocols.
Growth Catalysts
- Orthopedic bearing surface demand:Aging demographics across Germany, France, and Italy are expanding joint replacement volumes. Hospitals require ultra-low molecular weight polyethylene with validated oxidative stability for hip and knee implants.
- REACH substance restriction evolution:ECHA's expanding SVHC candidate list is disqualifying legacy polymer additives. Medical compounders reformulating with bio-based stabilizers gain first-mover certification advantages under updated safety data sheet requirements.
- Sterile barrier packaging transition:Low-density polyethylene grades with enhanced seal integrity are displacing PVC and PETG in hospital sterile field systems. French and Dutch hospital networks now mandate peelable barrier validation for all inbound surgical kits.
Market Restraints
- Naphtha feedstock volatility:European crackers rely on naphtha priced against Brent crude differentials. Medical-grade polyethylene margins compress when olefin spreads tighten without corresponding resin price pass-through mechanisms.
- Compounding capacity concentration:Germany hosts over sixty percent of EU medical polyethylene compounding infrastructure. Disruptions at Rotterdam or Antwerp logistics hubs cascade through just-in-time orthopedic device supply chains.
- Gamma sterilization degradation limits:High-density polyethylene surgical instrument handles exhibit embrittlement after repeated sterilization cycles. Alternative radiation-stable polymers threaten specification capture in reusable device categories.
Strategic Opportunities
- Spanish and Portuguese hospital modernization:Iberian health systems are replacing legacy sterilization departments with centralized sterile processing facilities. This creates specification windows for LDPE-based sterile barrier systems in regional tender processes.
- EU AI Act algorithmic transparency requirements:Smart packaging with embedded sensors for cold chain monitoring must declare polymer-sensor interface materials. Medical polyethylene grades with validated electromagnetic compatibility become specified inputs for connected drug delivery devices.
- 3D-printed orthopedic implant convergence:Powder bed fusion and material extrusion systems are adopting medical polyethylene filament feedstocks. Polish and Czech additive manufacturing clusters lack qualified polymer suppliers for patient-specific implant prototyping.
Industry Challenges
- Polymer toxicology assessment capacity:ISO 10993 biocompatibility testing for new medical polyethylene grades requires twelve to eighteen month study timelines. European contract research organizations face backlogs that delay MDR technical documentation submissions.
- Legacy sterilization asset reconfiguration:Ethylene oxide sterilization facilities face ECHA restriction proposals. Converters must validate alternative radiation or vaporized hydrogen peroxide protocols without compromising polyethylene molecular weight integrity.
- Cross-border notified body capacity:MDR designation of polymer-focused conformity assessment bodies concentrates in Germany and the Netherlands. Italian and Spanish compounders face extended audit scheduling delays for CE marking renewal.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Medical Polyethylene Market |
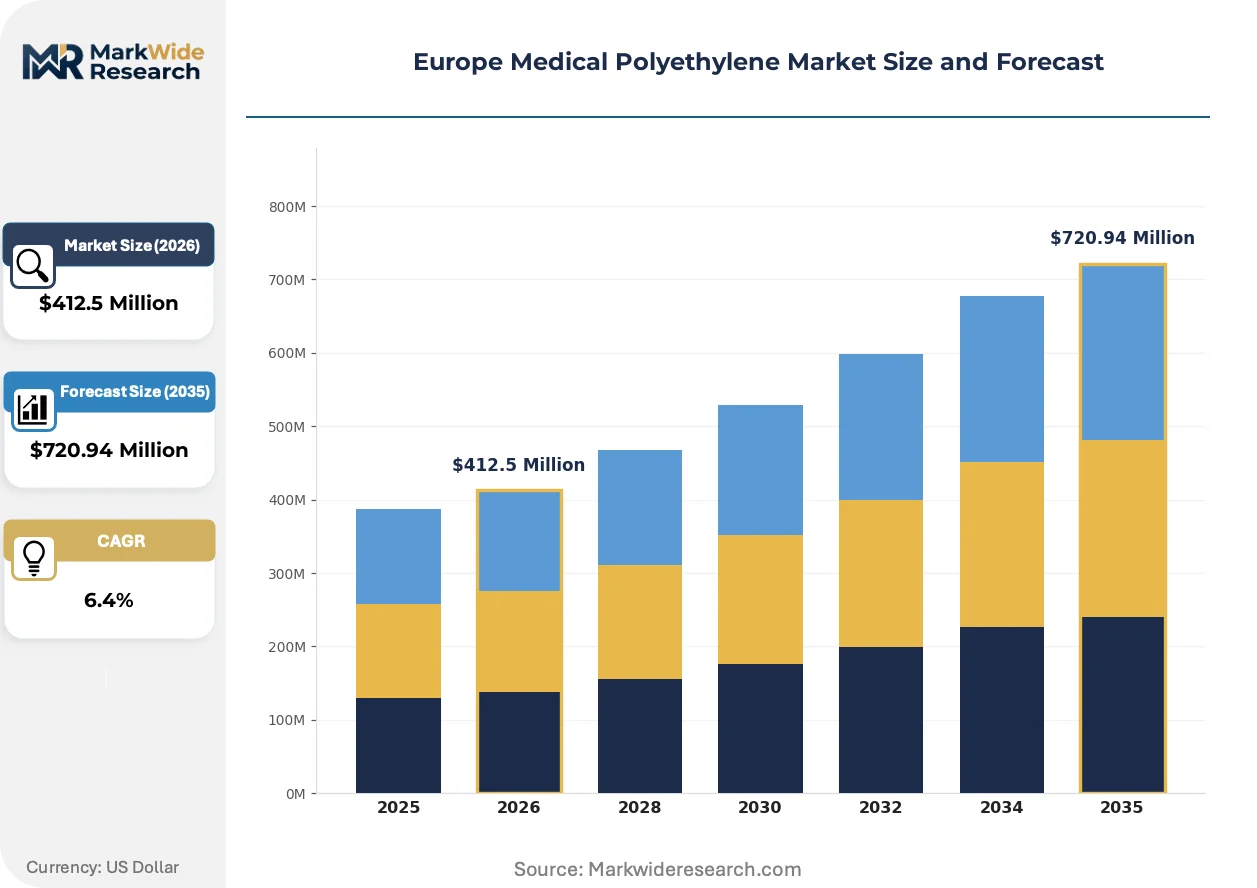
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $720.94 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Density Polyethylene, Low-Density Polyethylene, Ultra-Low Molecular Weight Polyethylene, Linear Low-Density Polyethylene Application: Surgical Instruments, Drug Delivery Systems, Medical Packaging, Orthopedic Devices End User: Hospitals, Clinics, Research Laboratories, Contract Manufacturers Technology: Injection Molding, Extrusion, Blow Molding, 3D Printing |
| Companies Covered | SABIC, Dow Inc., Celanese Corporation, LyondellBasell Industries Holdings B.V., Exxon Mobil Corporation, Tekni-Plex Inc., Orthoplastics Ltd., Biesterfeld AG, BASF SE, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Medical Polyethylene Market Strategic Shifts & Innovations
Material science advances and regulatory disclosure mandates are converging to redefine specification criteria for patient-contact polymers across European device manufacturing.
Antioxidant-stabilized ultra-high molecular weight polyethylene is migrating from conventional joint replacement bearings into spinal implant and extremity reconstruction applications. Swiss and German orthopedic device manufacturers are qualifying these grades for cervical disc and ankle replacement systems. This migration is compressing the qualification timeline for second-source polymer suppliers as OEMs consolidate approved material lists under MDR technical documentation requirements.
EMA's extended mandate for implantable device post-market surveillance is forcing compounders to maintain batch-level traceability for twenty-year service life projections. Polyethylene resin producers must now integrate serialization systems linking polymerization catalyst batches to finished device sterilization records. High-volume hip and knee implant manufacturers in Ireland and the Netherlands are demanding blockchain-anchored supply chain documentation to satisfy notified body audit protocols.
Hospital procurement consortia in Scandinavia and the Benelux are consolidating sterile barrier purchasing through centralized tender platforms. Traditional distributor networks face disintermediation as direct manufacturer-to-health system contracts capture eighty percent of LDPE packaging volumes in Denmark and Sweden. This consolidation is compressing margin structures for regional packaging converters unable to scale ISO 13485 quality systems to consortium compliance requirements.
Europe Medical Polyethylene Market Segmentation
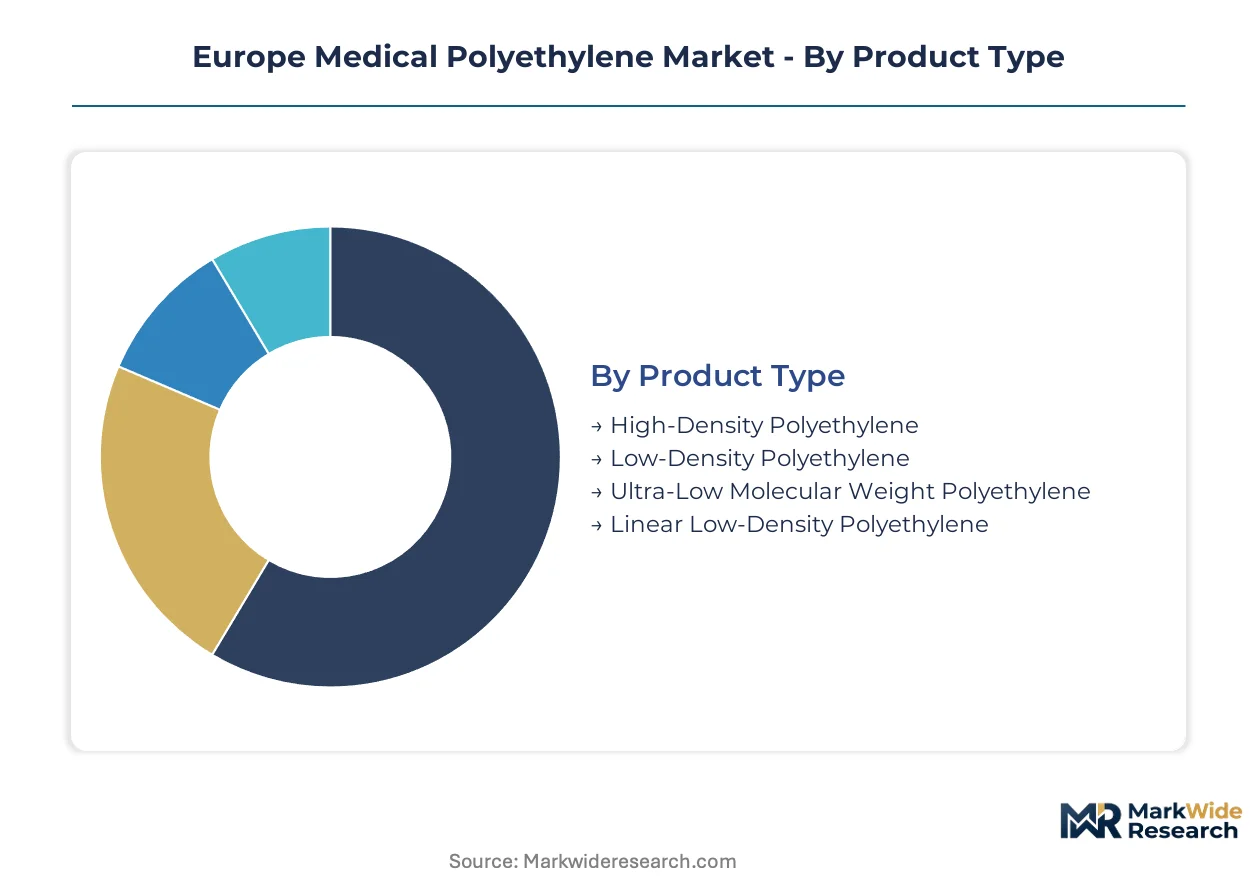
Segmentation of the Europe Medical Polyethylene Market reveals how polymer specifications align with distinct sterilization protocols, device performance requirements, and regulatory documentation burdens. Each category carries unique after-sales service intensity, from batch-level traceability for implant grades to technical support for additive manufacturing feedstocks.
Product Type:
After-sales service intensity varies sharply across polyethylene densities, with implant-bearing surfaces demanding decades-long batch traceability and packaging grades requiring rapid complaint resolution.
- Ultra-Low Molecular Weight Polyethylene:Engineered with narrow molecular weight distribution and antioxidant stabilization for articulating joint surfaces. German and Swiss orthopedic OEMs concentrate demand for hip and knee bearings under MDR extended clinical evidence requirements. REACH-compliant stabilizer packages now dominate new formulations.
- High-Density Polyethylene:Gamma sterilization-stable grades serve surgical instrument handles and sterilization trays. French hospital procurement consortia specify HDPE for reusable device categories facing ethylene oxide substitution pressures.
- Low-Density Polyethylene:Enhanced seal integrity grades displace PVC in Dutch and Danish sterile barrier systems.
- Linear Low-Density Polyethylene:Peelable film structures serve centralized sterile processing facilities in Spain and Portugal.
Ultra-Low Molecular Weight Polyethylene holds the largest share; momentum sits with Low-Density Polyethylene in packaging conversion.
Application:
Application segmentation tracks how MDR technical documentation requirements concentrate polymer qualification resources toward implantable versus non-implantable device categories.
- Orthopedic Devices:Bearing surfaces, spinal implants, and extremity reconstruction systems require ISO 10993 biocompatibility validation and twenty-year batch traceability. Irish and Dutch high-volume manufacturers demand blockchain-anchored supply chain documentation from compounders.
- Medical Packaging:Sterile barrier systems with validated seal integrity and peelability are displacing legacy materials. Scandinavian hospital consortia capture eighty percent of LDPE packaging volumes through direct manufacturer contracts.
- Surgical Instruments:Reusable device handles face gamma sterilization embrittlement constraints.
- Drug Delivery Systems:Tight-tolerance tubing grades serve connected devices under EU AI Act algorithmic transparency requirements.
Orthopedic Devices commands the greatest revenue concentration; Medical Packaging is expanding most quickly through hospital procurement consolidation.
End User:
End user segmentation reflects divergent quality system requirements, with hospitals and contract manufacturers driving distinct specification and volume patterns.
- Hospitals:Centralized sterile processing departments in Iberia and the Benelux specify LDPE barrier systems through tender platforms. Direct procurement contracts are disintermediating traditional distributor networks in Denmark and Sweden.
- Contract Manufacturers:MDR compliance deadlines compress certification timelines, forcing compounders to rebuild quality management systems around extended clinical evidence protocols for implant-grade conversions.
- Clinics:Smaller volume demand concentrates on standard-grade packaging and disposable instruments.
- Research Laboratories:Prototyping requirements for 3D-printed implants drive filament feedstock qualification in Polish and Czech additive manufacturing clusters.
Hospitals represent the dominant volume sink; Contract Manufacturers face the steepest regulatory compliance cost escalation.
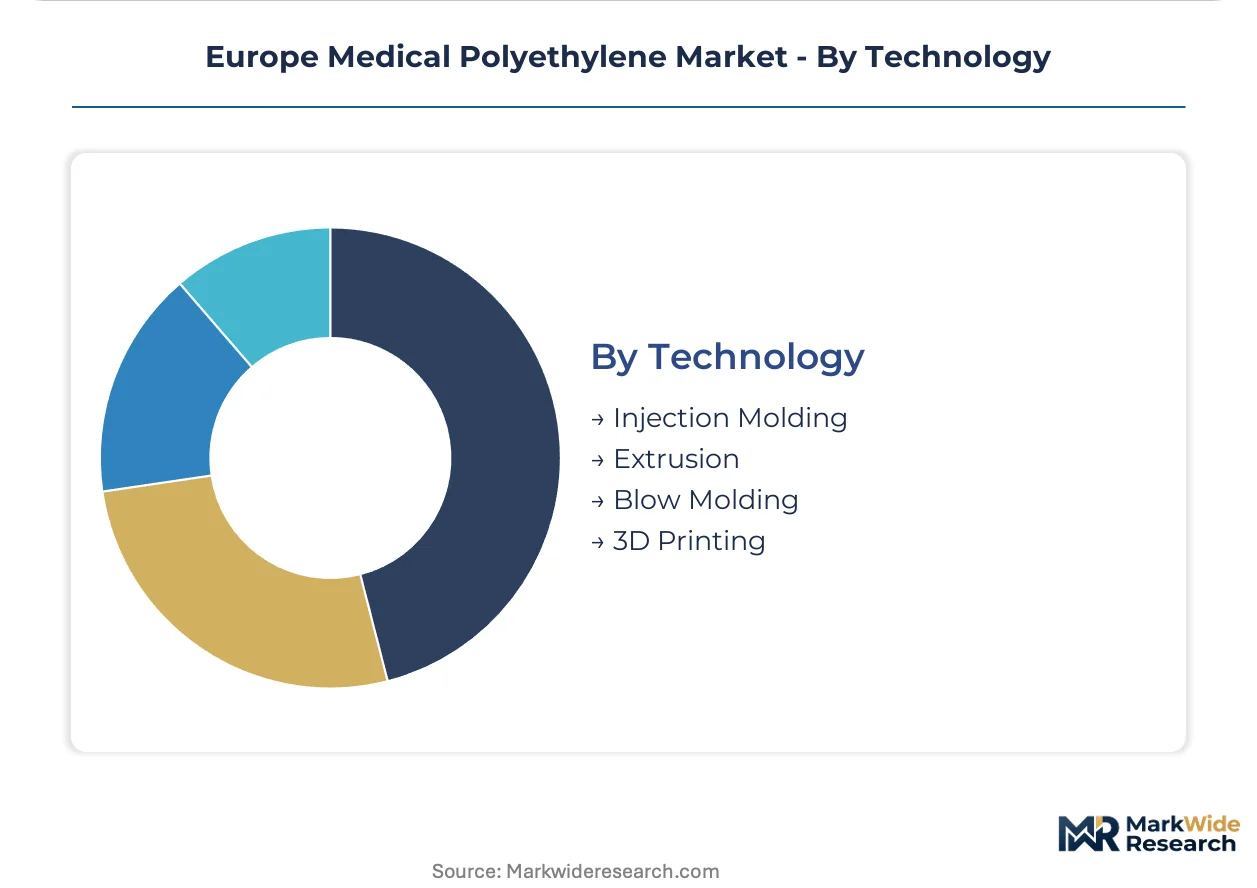
Technology:
Technology segmentation tracks processing method constraints on molecular weight integrity, dimensional tolerance, and sterilization compatibility.
- Extrusion:Tight-tolerance tubing production for drug delivery systems leverages European extrusion technology bases. Dow Inc. supplies validated grades for connected devices requiring electromagnetic compatibility declaration under EU AI Act.
- Injection Molding:Surgical instrument handle production demands gamma sterilization stability without molecular weight degradation. High-density polyethylene grades from LyondellBasell serve molders requiring dimensional precision.
- Blow Molding:Pharmaceutical bottle and container production utilizes LDPE grades with enhanced barrier properties.
- 3D Printing:Powder bed fusion and material extrusion systems adopt medical polyethylene filament for patient-specific orthopedic prototyping.
Extrusion maintains the broadest installed base; 3D Printing is gaining share fastest through additive manufacturing cluster expansion in Central Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Over sixty percent of EU medical polyethylene compounding infrastructure clusters in Germany, with Rotterdam and Antwerp logistics hubs serving as critical distribution nodes for just-in-time orthopedic device supply chains across the continent.
Germany
Orthopedic device manufacturers in Baden-Württemberg and Bavaria drive demand for ultra-low molecular weight polyethylene bearings. EMA's extended clinical evidence requirements under MDR are compressing certification timelines for compounders in the Rhine-Ruhr industrial corridor. Frankfurt and Hamburg host the bulk of sterilization infrastructure serving Central European hospital networks.
France
French hospital procurement consortia specify high-density polyethylene for reusable surgical instrument categories facing ethylene oxide substitution pressures. ANSM oversees post-market surveillance protocols that demand batch-level traceability from resin producers. Lyon and Paris concentrate medical packaging conversion capacity serving Benelux distribution channels.
Netherlands
Irish and Dutch high-volume hip and knee implant manufacturers demand blockchain-anchored supply chain documentation from polyethylene compounders. REACH substance restriction evolution is disqualifying legacy polymer additives in Rotterdam port processing zones. Eindhoven's medical technology cluster is consolidating sterile barrier purchasing through centralized tender platforms.
Italy
Italian compounders face extended audit scheduling delays for CE marking renewal due to limited notified body capacity outside Germany and the Netherlands. Lombardy's orthopedic device manufacturers require antioxidant-stabilized grades for spinal implant applications. Milan's polymer distributors are rebuilding quality management systems around MDR technical documentation protocols.
Spain
Iberian health systems are replacing legacy sterilization departments with centralized sterile processing facilities in Madrid and Barcelona. This creates specification windows for low-density polyethylene sterile barrier systems in regional tender processes. Spanish additive manufacturing clusters lack qualified polymer suppliers for patient-specific implant prototyping.
Europe Medical Polyethylene Market Key Industry Players
Integrated petrochemical majors and specialized medical compounders split the market between scale-driven resin supply and application-specific formulation services. The vendor base concentrates around established European quality management systems capable of MDR-compliant documentation. Three archetypes dominate: upstream resin producers with medical-grade purification capabilities, downstream compounders with ISO 13485-certified facilities, and distribution intermediaries with regulatory navigation expertise. Capacity expansion and strategic partnerships represent the dominant competitive moves as MDR deadlines compress qualification timelines.
Within the integrated resin producer tier, SABIC and Dow Inc. occupy positions defined by high-purity polymer science platforms and European extrusion technology bases respectively. LyondellBasell Industries Holdings B.V. anchors the high-density polyethylene supply segment for gamma sterilization-stable applications. These entities exemplify the scale-driven archetype, with their geographic naming conventions indicating Saudi and American origins alongside Dutch operational structuring.
| Leading Market Players |
|---|
| SABIC |
| Dow Inc. |
| Celanese Corporation |
| LyondellBasell Industries Holdings B.V. |
| Exxon Mobil Corporation |
| Tekni-Plex Inc. |
| Orthoplastics Ltd. |
| Biesterfeld AG |
| BASF SE |
| Others |
Cost & Logistics Intelligence
Rotterdam-Antwerp logistics corridors concentrate over sixty percent of EU medical polyethylene compounding capacity, granting German and Dutch resin suppliers substantial pricing leverage over downstream orthopedic device manufacturers facing MDR-mandated material requalification deadlines.
Pricing Analysis
EU MDR dictates the pricing tier structure across implant-grade polyethylene, separating ISO 10993-validated bearing surface grades from standard packaging resins. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, batch traceability scope, and sterilization stability validation. Pricing pressure stems from REACH-compliant stabilizer reformulation costs that compounders struggle to pass through to hospital procurement consortia. Contract manufacturers exhibit highest price sensitivity due to compressed MDR compliance margins, while high-volume hip and knee implant OEMs in Ireland and the Netherlands absorb premiums for blockchain-anchored supply chain documentation.
Supply Chain Analysis
Tariff exposure between Middle Eastern naphtha suppliers and European crackers dominates supply chain risk assessment for medical polyethylene producers. Germany, the Netherlands, and Belgium concentrate polymerization and compounding infrastructure, drawing from Saudi and Qatari ethylene feedstocks. Raw material dependencies rest on naphtha pricing against Brent crude differentials, antioxidant stabilizer packages, and gamma sterilization-compatible additive systems. Single-source vulnerability concentrates at Rotterdam port processing zones where REACH substance restriction enforcement disqualifies legacy formulations. Distribution runs through just-in-time orthopedic device supply chains anchored by Frankfurt and Hamburg sterilization hubs serving Central European hospital networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's medical polyethylene market functions as a regulatory-moat business where MDR technical documentation requirements and ISO 10993 biocompatibility validation create switching costs that entrench established compounders against new entrants.
For Market Incumbents: Build certification depth as the primary moat by extending batch-level traceability systems to twenty-year service life projections for implant grades, while adding compounding capacity in the Rhine-Ruhr corridor to capture orthopedic OEM consolidation. Threat from radiation-stable alternative polymers in reusable surgical instrument categories demands accelerated antioxidant stabilization R&D. Backward integration into REACH-compliant bio-based stabilizer supply secures formulation flexibility against ECHA restriction proposals. For New Entrants and Emerging Players: Spanish and Portuguese centralized sterile processing facility tenders represent the most penetrable entry point for LDPE barrier system suppliers lacking MDR implant-grade certification depth. Polish and Czech additive manufacturing clusters for 3D-printed orthopedic implants offer second white-space opportunity given qualified polymer supplier scarcity. Go-to-market angle should emphasize rapid ISO 13485 quality system deployment and direct contracting with hospital procurement consortia disintermediating traditional distributors. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because MDR compliance cost escalation and extended clinical evidence requirements favor scaled compounders with established notified body relationships. Acquisition target archetype: mid-cap European compounders with ISO 13485-certified facilities and existing orthopedic OEM approvals but limited capital for REACH-compliant reformulation. Signal to watch is ECHA SVHC candidate list expansion pace, which accelerates disqualification of legacy additive packages and triggers replacement demand for validated stabilizer systems.| Strategic Initiative | Industry Significance |
|---|---|
| MDR Technical Documentation Investment | Extended clinical evidence requirements compress certification timelines for implant-grade polyethylene converters. |
| REACH-Compliant Stabilizer Reformulation | ECHA SVHC candidate list expansion disqualifies legacy additives, creating first-mover certification advantages. |
| Blockchain-Anchored Supply Chain Deployment | Irish and Dutch hip and knee implant OEMs demand serialized batch traceability for twenty-year service life projections. |
| Iberian Sterile Processing Facility Expansion | Spanish and Portuguese hospital modernization creates specification windows for LDPE barrier systems in regional tenders. |
| Central European Additive Manufacturing Feedstock Qualification | Polish and Czech 3D-printed implant clusters lack qualified polyethylene filament suppliers for patient-specific prototyping. |
Research Approach
Findings reconcile primary fieldwork against secondary review of EMA MDR guidance documents, ECHA SVHC candidate list updates, and orthopedic device manufacturer SEC filings. Primary interviews engaged polymer compounder quality managers, hospital procurement consortium directors, biomedical engineers at German and Swiss orthopedic OEMs, and notified body audit specialists. Secondary validation drew from ISO 10993 biocompatibility testing standards, REACH substance restriction databases, and EU AI Act algorithmic transparency requirements. Bottom-up volume modeling triangulated against top-down resin production capacity assessments across the European petrochemical corridor.
Forecast inputs include orthopedic device implant volumes by procedure type, hospital sterile barrier system procurement consolidation rates, and additive manufacturing cluster expansion trajectories across Central Europe. Segmentation dimensions span polyethylene density grade, application category, end-user archetype, and processing technology. CAGRs derive from procedure volume elasticity to aging demographics, sterilization protocol substitution patterns, and regulatory compliance cost pass-through assumptions. Industry-specific inputs incorporate MDR designation timelines for polymer-focused conformity assessment bodies and ECHA restriction proposal implementation schedules.
Macroeconomic conditions sit as an overlay; deviation in naphtha-to-ethylene spreads, Brent crude volatility, or euro-denominated medical device export demand would shift the trajectory. Forecasts embed assumptions regarding REACH substance restriction evolution pace and notified body capacity expansion that material regulatory acceleration or delay would revise. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polyethylene Terephthalate (PET) Compounding Market
Polymers & Resins
Polyethylene Furanoate (PEF) Barrier Resin Market
Polymers & Resins
Polysulfide Market
Polymers & Resins
Middle East and Africa Polyethylene Wax Market
Polymers & Resins
Formaldehyde-Free Resin Market
Polymers & Resins
Calendering Resins Market
Polymers & Resins
Middle East Fluoropolymer Market
Polymers & Resins
1-Hexene Based Polyethylene Market
Polymers & Resins
Europe Polyvinyl Chloride (PVC) Market
Polymers & Resins
Canada Bioresorbable Polymers Market
Polymers & Resins
Polyimide Resin Market
Polymers & Resins
Phenolic Resin Market
Polymers & Resins
Europe Super Absorbent Polymers (SAP) Market
Polymers & Resins
HDPE Large Blow Molded Products Market
Polymers & Resins
Rotomolding Compound Market
Polymers & Resins
Global Medical Superabsorbent Polymers Market