
 Global Ion Exchange Resin Market | 2026-2036
Global Ion Exchange Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ion Exchange Resin Market Foresight
Aftermarket service revenue is narrowing as a margin pool toward resin regeneration and on-site technical support. DuPont de Nemours, Inc. leverages its film-forming polymer expertise to dominate high-performance anion resin supply for semiconductor fabs. Purolite Corporation anchors European demand through specialized chelating resins for hydrometallurgy. LANXESS competes on manufacturing scale across its Leverkusen and Bitterfeld production sites.
Ion exchange resins are synthetic polymer beads, typically 0.3–1.2 mm in diameter, functionalized with acidic or basic groups that reversibly exchange ions in aqueous solutions for water softening, demineralization, or selective metal recovery. Cation resins lead volume consumption across power generation and municipal water treatment where calcium and magnesium removal remains the primary application. Chelating resins represent the fastest-growing product category as mining operations and battery recycling facilities adopt selective metal capture for lithium, cobalt, and rare earth recovery.
The EPA enforces Maximum Contaminant Level Goals for drinking water that compel municipal utilities to upgrade aging ion exchange systems. China's MEE implements stricter wastewater discharge standards for heavy metals that drive replacement demand across industrial parks. The EU's REACH regulation governs chemical safety in resin manufacturing and restricts certain crosslinking agents. Stakeholders must monitor regulatory divergence between jurisdictions to align product portfolios with evolving compliance requirements.
Market Dynamics
Boiler feedwater polishing at power generation utilities is accelerating resin consumption as utilities retrofit aging demineralization trains to meet stricter conductivity specifications. China's MEE and the EU's Industrial Emissions Directive are forcing simultaneous facility upgrades across multiple industrial clusters.
Growth Catalysts
- Power sector water treatment:Coal and nuclear utilities in China and the United States are expanding resin capacity for high-purity boiler feedwater. These installations prioritize cation-anion mixed beds for silica removal.
- MEE wastewater rules:China's Ministry of Ecology and Environment mandates heavy metal discharge limits that compel electroplating and battery manufacturing facilities to install chelating resin systems for selective metal capture.
- Semiconductor ultrapure water:Wafer fabrication plants in Taiwan, South Korea, and Germany require sub-ppt ionic contamination levels that only high-performance anion resins can achieve.
Market Restraints
- Styrene feedstock volatility:Crude oil price swings directly impact divinylbenzene crosslinker costs, compressing margins for standard-grade cation resin producers.
- Supply concentration in China:Over half of global gel-type resin manufacturing capacity sits in Shandong and Jiangsu provinces, creating single-source vulnerability for European distributors.
- Membrane substitution threat:Reverse osmosis and electrodeionization systems are displacing mixed-bed polishers in municipal desalination projects where brine disposal constraints are absent.
Strategic Opportunities
- Battery recycling hydrometallurgy:Spent lithium-ion battery processing facilities in Germany and Canada are adopting iminodiacetic acid chelating resins for cobalt and nickel separation from leach liquors.
- EU Green Deal chemistry:The EU's chemical sustainability framework incentivizes bio-based resin feedstocks and regenerable systems that reduce hazardous waste generation.
- On-site regeneration services:Technical service contracts for resin regeneration at industrial sites are displacing bulk replacement purchasing in Japan's electronics corridor.
Industry Challenges
- Specialized polymer chemist scarcity:Formulation expertise for high-selectivity chelating resins concentrates among retiring specialists at German and Japanese research centers.
- REACH compliance timelines:ECHA registration requirements for novel functional groups delay product commercialization by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ion Exchange Resin Market |
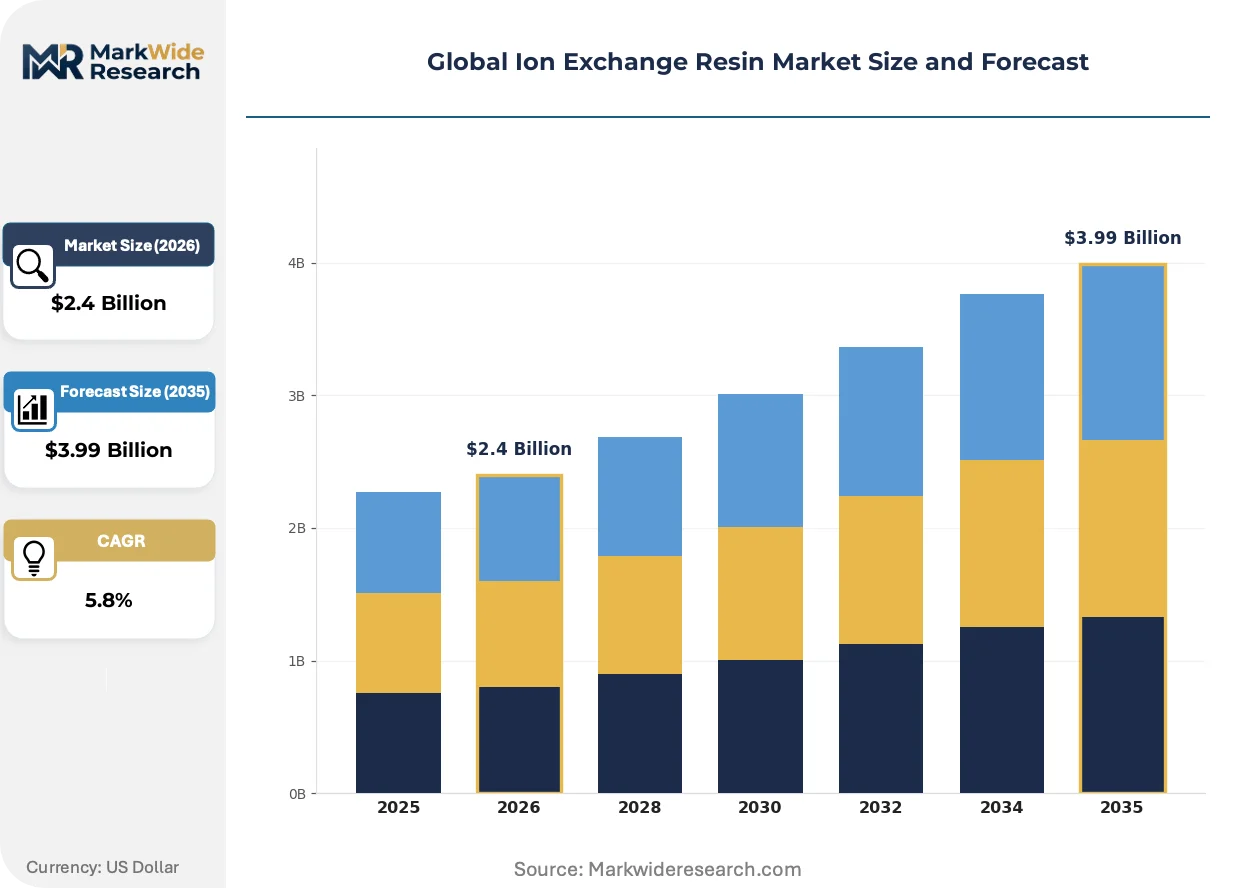
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cation Resin, Anion Resin, Mixed Bed Resin, Chelating Resin Application: Water Purification, Food & Beverage Processing, Pharmaceutical Production, Chemical Synthesis End User Industry: Power Generation, Mining Operations, Electronics Manufacturing, Municipal Water Treatment Form: Beads, Powders, Pellets, Sheets |
| Companies Covered | Ecolab Inc., Samyang Corporation, DuPont de Nemours, Inc., Thermax Limited, Purolite Corporation, LANXESS, Jacobi Carbons Group, Sunresin New Materials Co., Ltd., Mitsubishi Chemical Group Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ion Exchange Resin Market Shifts & Advancements
Continuous resin monitoring systems and predictive regeneration algorithms are compressing operating costs for large-volume industrial users. These digital layers are reshaping how utilities manage ion exchange asset life cycles.
Magnetic ion exchange resins functionalized with iron oxide nanoparticles enable rapid separation from mixed suspensions without filtration. Water treatment operators in Australia's municipal sector are piloting these materials for dissolved organic carbon removal. This technology is digitizing backwash sequencing through automated magnetic recovery cycles that eliminate manual bed separation steps.
The EU's F-Gas Regulation is phasing down hydrofluorocarbon use in cooling systems that support resin manufacturing plants. Chemical producers in Belgium and the Netherlands are retrofitting process cooling loops to comply with 2024 quota reductions. High-performance anion resin grades requiring cryogenic polymerization are most affected, with manufacturers shifting to ammonia-based refrigeration or relocating sensitive production steps.
Electronics manufacturers are unbundling resin supply from technical service contracts, directly procuring regeneration chemicals and spare capacity. This disintermediation pressures traditional distributor margins in Taiwan's semiconductor supply chain. Original equipment manufacturers now specify resin performance guarantees independently of the suppliers providing them, forcing resin makers to certify directly to fab water quality protocols.
Global Ion Exchange Resin Market Segmentation
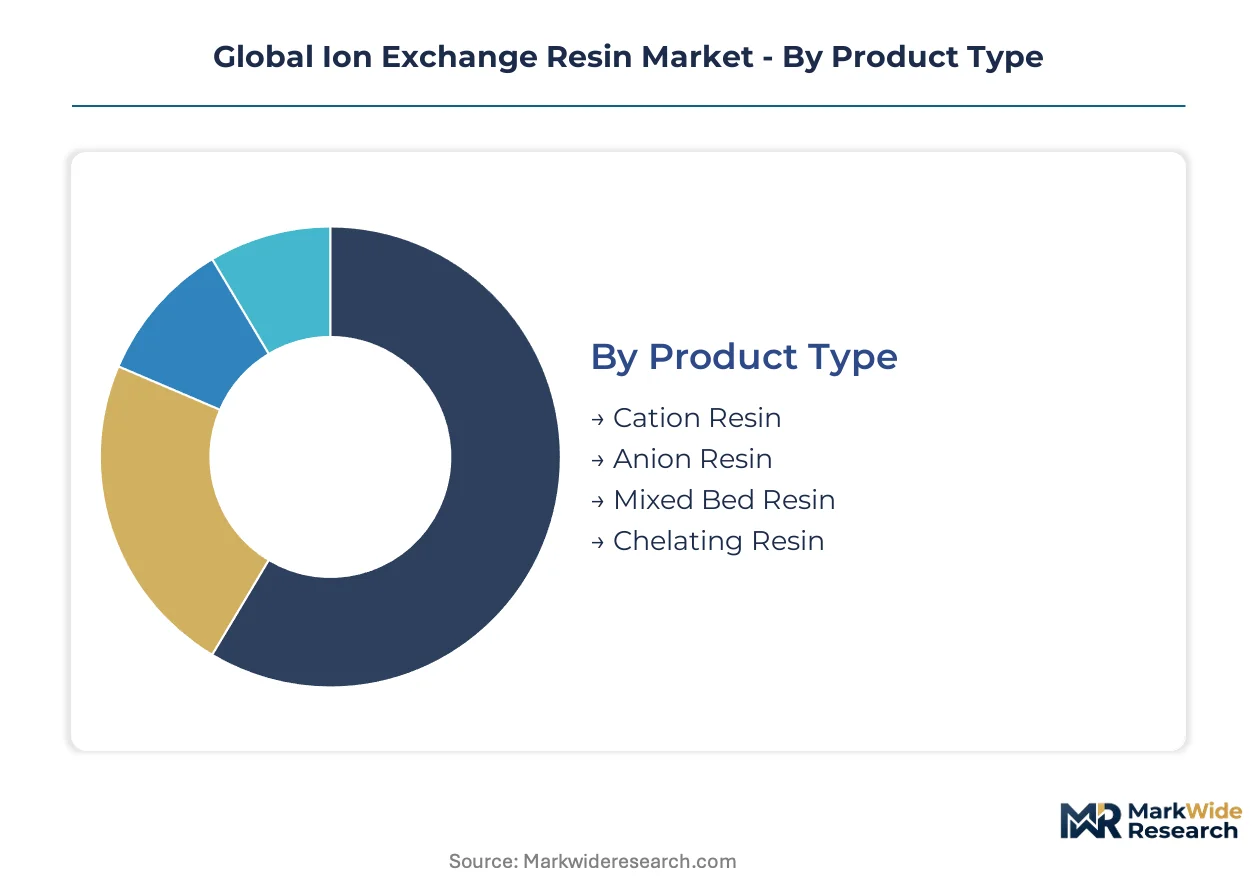
Segmentation in the ion exchange resin market reveals how polymer chemistry, application severity, and end-use specifications create distinct value tiers. Manufacturers configure production lines and pricing architectures around these boundaries.
Product Type:
Volume concentration and margin structure vary sharply across polymer functionalization chemistries, with standard-grade commodities competing against high-selectivity specialty grades.
- Cation Resin:Sulfonic acid-functionalized polystyrene matrices dominate boiler feedwater softening and demineralization trains. Power utilities in China and the United States consume bulk volumes for calcium and magnesium removal, though styrene feedstock volatility compresses producer margins.
- Chelating Resin:Iminodiacetic acid and aminophosphonic functional groups enable selective capture of transition metals from complex leach liquors. Battery recycling facilities in Germany and hydrometallurgy operations in Canada are expanding capacity for cobalt, nickel, and rare earth separation.
- Anion Resin:Quaternary ammonium-functionalized polymers remove silica and weakly ionized acids from process water.
- Mixed Bed Resin:Intimate blends of cation and anion resins achieve ultralow conductivity in final polishing stages.
Cation resin commands the established base. The steepest expansion runs through chelating resin.
Application:
Regulatory stringency and contamination tolerance thresholds segment demand into distinct technical specifications and service intensity levels.
- Water Purification:Municipal utilities and industrial facilities deploy cation-anion systems for hardness removal and total dissolved solids reduction. EPA Maximum Contaminant Level Goals compel system upgrades across aging US infrastructure.
- Pharmaceutical Production:USP-grade resins meet pyrogen and endotoxin specifications for active pharmaceutical ingredient processing. FDA validation requirements extend qualification timelines and lock in supplier relationships.
- Food & Beverage Processing:Decolorization and deashing applications in sugar refining and juice purification.
- Chemical Synthesis:Catalysis and product recovery operations in specialty chemical manufacturing.
Water purification anchors volume demand. Pharmaceutical production is expanding most quickly.
End User Industry:
Customer technical capabilities and procurement sophistication determine whether resin supply bundles with regeneration services or disaggregates into chemical and hardware components.
- Power Generation:Coal, nuclear, and combined-cycle plants operate large-volume demineralization systems with continuous resin attrition. China's utilities are retrofitting aging trains to meet stricter conductivity specifications.
- Electronics Manufacturing:Wafer fabrication plants in Taiwan, South Korea, and Germany require sub-ppt ionic contamination levels. These customers are unbundling resin supply from service contracts and certifying suppliers directly to fab water quality protocols.
- Municipal Water Treatment:Drinking water and wastewater facilities under EPA and MEE jurisdiction.
- Mining Operations:Hydrometallurgical extraction and process water recycling.
Power generation holds the volume base. Electronics manufacturing is climbing the fastest.
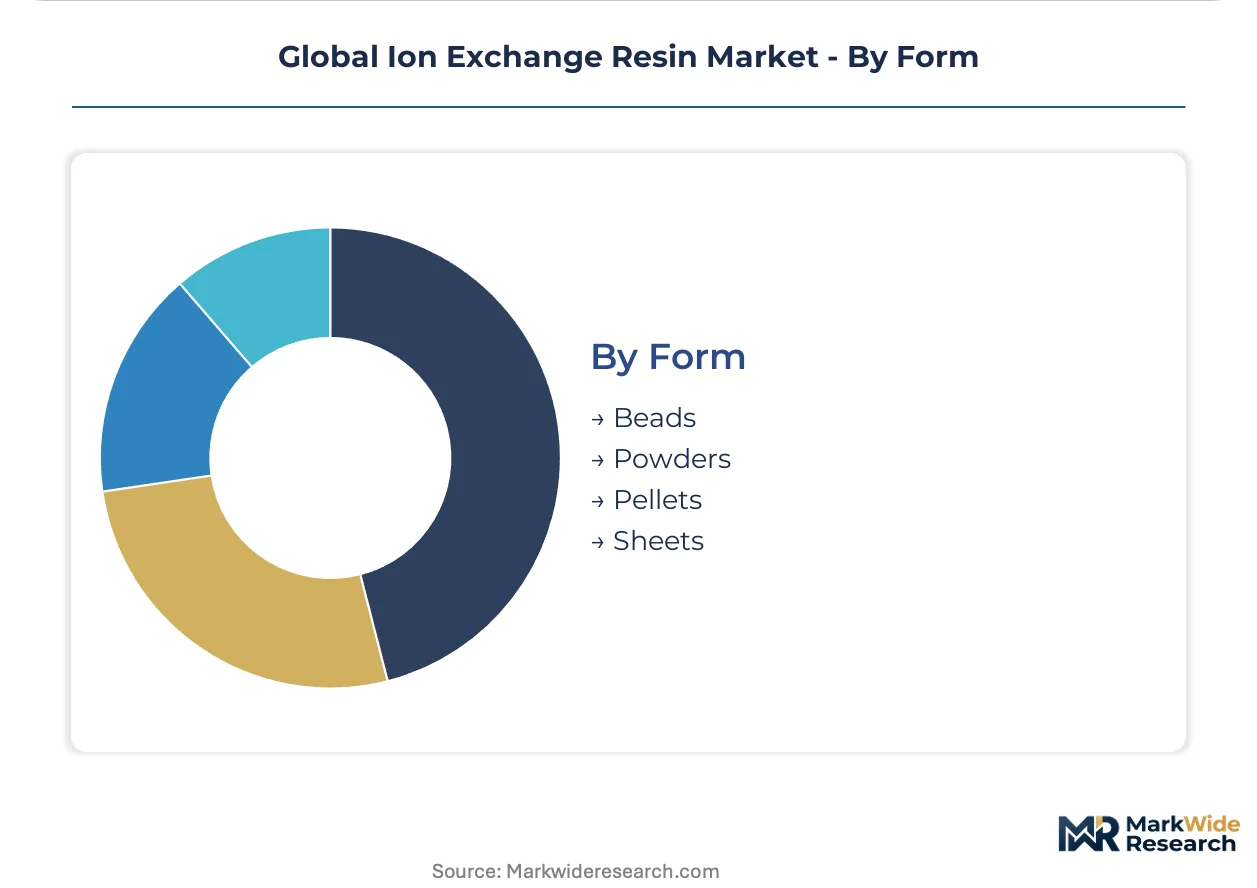
Form:
Physical configuration determines mass transfer efficiency, pressure drop characteristics, and compatibility with fixed-bed versus continuous contactor designs.
- Beads:Spherical gel and macroporous particles 0.3–1.2 mm in diameter constitute the standard configuration for fixed-bed columns. Bead uniformity controls pressure drop and regeneration efficiency across power generation and municipal installations.
- Pellets:Larger extruded forms for specialized high-flow applications.
- Powders:Finely ground resins for batch processing and slurry applications.
- Sheets:Membrane-integrated formats for electrochemical and specialized separation processes.
Beads dominate installed capacity. Pellets are gaining share fastest in high-throughput industrial designs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China consumes ion exchange resins primarily for power generation and industrial wastewater treatment, while Germany and the United States concentrate demand in semiconductor ultrapure water and pharmaceutical processing. This consumption-mix differential shapes regional product specifications and service intensity levels.
China
Coal-fired and nuclear utilities in Shandong and Jiangsu provinces are retrofitting aging demineralization trains to meet stricter conductivity specifications. MEE wastewater discharge standards for heavy metals compel electroplating facilities in the Pearl River Delta to install chelating resin systems. Battery manufacturing clusters in Fujian and Sichuan are expanding selective metal capture capacity for lithium recovery.
Germany
Wafer fabrication plants in Dresden and Munich require sub-ppt ionic contamination levels that drive demand for high-performance anion resins. The EU's F-Gas Regulation is forcing resin manufacturers in Leverkusen and Bitterfeld to retrofit cryogenic polymerization cooling systems. Spent battery processing facilities in the Ruhr region are adopting iminodiacetic acid chelating resins for cobalt and nickel separation.
United States
EPA Maximum Contaminant Level Goals compel municipal utilities in California and Texas to upgrade aging ion exchange infrastructure. Power generation utilities in the Ohio River Valley are expanding cation-anion mixed bed capacity for boiler feedwater polishing. Pharmaceutical manufacturers in New Jersey and North Carolina lock in USP-grade resin suppliers through extended FDA validation timelines.
Japan
Electronics manufacturers in the Tokyo-Yokohama corridor are unbundling resin supply from technical service contracts and certifying suppliers directly to fab water quality protocols. METI industrial water recycling mandates drive on-site regeneration service adoption. Chemical synthesis operations in Osaka-Kobe are deploying specialized resins for catalysis and product recovery.
South Korea
Memory and logic chip fabs in Gyeonggi Province require continuous resin monitoring systems to maintain sub-ppt contamination thresholds. National semiconductor self-sufficiency programs are expanding domestic ultrapure water treatment capacity. Busan-Ulsan petrochemical complexes are upgrading demineralization systems to meet stricter effluent standards.
Global Ion Exchange Resin Market Competitive Landscape
Capability concentration sits with German and Japanese specialists who command formulation expertise for high-selectivity chelating resins; scale advantage sits with integrated chemical conglomerates operating multi-site manufacturing networks. The market structures around three archetypes: diversified materials science conglomerates with polymer expertise, dedicated ion exchange specialists with application engineering depth, and regional chemical producers serving price-sensitive industrial segments. Dominant competitive moves include backward integration into specialty monomer supply and geographic expansion through technical service partnerships.
Within the diversified materials tier, DuPont de Nemours, Inc. and Mitsubishi Chemical Group Corporation exemplify integrated polymer science capabilities spanning resin functionalization and adjacent membrane technologies. Among dedicated specialists, Purolite Corporation and Jacobi Carbons Group occupy positions defined by application-specific resin engineering rather than commodity scale. LANXESS represents the European integrated chemical producer archetype with manufacturing concentration across the Rhine-Ruhr industrial corridor.
| Leading Market Players |
|---|
| Ecolab Inc. |
| Samyang Corporation |
| DuPont de Nemours, Inc. |
| Thermax Limited |
| Purolite Corporation |
| LANXESS |
| Jacobi Carbons Group |
| Sunresin New Materials Co., Ltd. |
| Mitsubishi Chemical Group Corporation |
| Others |
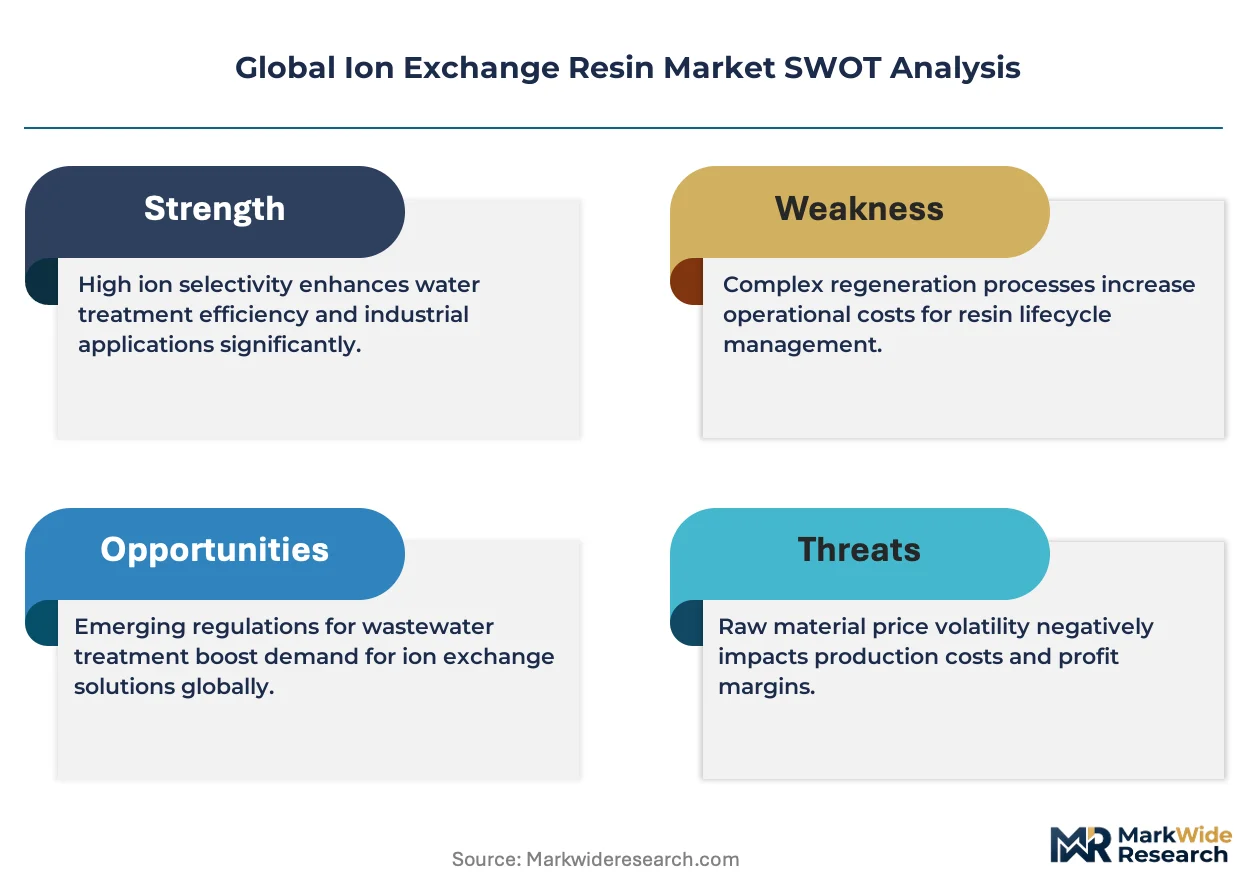
Supply & Pricing Matrix
Styrene feedstock volatility in Shandong and Jiangsu provinces compresses margins for standard-grade cation resin producers while simultaneously widening spreads between commodity and high-performance specialty grades. This single-source dependency for gel-type resin manufacturing forces European distributors to absorb freight premiums or accept longer lead times, reshaping procurement strategies across power generation and electronics manufacturing verticals.
Pricing Analysis
Long-term offtake contracts dominate procurement between power utilities and major resin suppliers, insulating boiler feedwater operations from spot styrene price swings while semiconductor fabs negotiate project-based pricing tied to sub-ppt contamination guarantees. Three-tier pricing structure across premium, standard, and economy levels separates USP-grade pharmaceutical resins from municipal water treatment commodities, with certification investment and after-sales regeneration bundling as primary differentiation drivers. Cost compression in standard cation resins is intensifying because Chinese manufacturers are expanding capacity faster than global demand growth. Municipal utilities exhibit highest price sensitivity due to constrained capital budgets, whereas electronics manufacturers prioritize performance guarantees over unit economics.
Supply Chain Analysis
Extended payment terms from 60 to 90 days have become standard for European distributors sourcing from Shandong manufacturers, reflecting working capital pressure throughout the value chain. Manufacturing gravity centers on China, Germany, and the United States, with divinylbenzene crosslinkers and quaternary ammonium functionalization agents as critical raw material dependencies. Single-source vulnerability persists for high-selectivity chelating resins, where formulation expertise concentrates among German and Japanese specialists. Distribution runs through authorized technical service partnerships for regeneration chemicals and on-site support, particularly in Japan's electronics corridor where disintermediation pressures traditional distributor margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital monitoring platforms and predictive regeneration algorithms are transforming ion exchange resin from a commodity chemical into an integrated water treatment service, creating platform-economics dynamics where data interoperability between resin suppliers and utility control systems determines competitive positioning.
For Market Incumbents: Entrench formulation expertise for high-selectivity chelating resins through captive R&D centers in Leverkusen and Tokyo, defending against membrane substitution threats in municipal desalination by embedding continuous monitoring systems that lock in long-term service contracts. Deepen backward integration into specialty monomer supply to offset styrene volatility exposure. For New Entrants and Emerging Players: Establish a beachhead in battery recycling hydrometallurgy, where iminodiacetic acid resin demand from German and Canadian facilities outpaces incumbent capacity expansion. White-space opportunity exists in on-site regeneration services for Japan's electronics corridor, where technical service contracts are displacing bulk replacement purchasing. Go-to-market angle should emphasize direct certification to fab water quality protocols. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors application-engineering specialists over commodity scale players, with mid-cap resin manufacturers possessing chelating formulation capabilities commanding scarcity premiums. Acquisition target archetype: regional European producers with REACH-registered functional groups and existing technical service networks. Signal to watch is unbundling velocity in Taiwan's semiconductor supply chain, where direct procurement trends indicate distributor margin compression ahead.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Monomers | Captive divinylbenzene supply insulates margins from crude oil volatility in Shandong. |
| Green Manufacturing Transition | EU F-Gas Regulation compliance requires ammonia-based refrigeration retrofit at Leverkusen sites. |
| Long-term Supply Agreement | Power utilities in China's Shandong province lock in cation resin volumes through decade contracts. |
| Joint Venture | Taiwanese semiconductor fabs partner directly with resin makers to bypass distributor markups. |
| Capacity Expansion | German battery recyclers expand iminodiacetic acid resin capacity for cobalt separation from leach liquors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs/trade data, SEC 10-K filings, Cefic industry reports, and MEE wastewater discharge filings. Plant managers at Shandong and Jiangsu resin facilities, procurement leads at power utilities in the Ohio River Valley, technical R&D directors at German semiconductor fabs, and distribution channel partners across Europe's Rhine-Ruhr corridor provided operational validation. Bottom-up demand modeling triangulates against top-down chemical consumption benchmarks.
Forecast inputs span product type segmentation across cation, anion, chelating, and mixed-bed chemistries; application severity tiers from municipal water to pharmaceutical USP-grade; and end-user procurement sophistication distinguishing bundled service contracts from disaggregated chemical supply. CAGRs derive from installed base attrition rates, regulatory upgrade cycles, and technology substitution elasticity across the projection horizon. Semiconductor fab capacity expansion in Taiwan and South Korea, plus MEE enforcement intensity in China's Pearl River Delta, anchor volume assumptions.
Stress conditions across styrene price volatility bands, REACH registration delays for novel functional groups, and membrane substitution rates in desalination were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and feedstock supply continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polystyrene Foam Market
Polymers & Resins
Global Polymethyl Methacrylate Market
Polymers & Resins
Europe Expanded Polystyrene (EPS) Market
Polymers & Resins
Flame Retardant Polyester Resins Market
Polymers & Resins
Polyetherketone Market
Polymers & Resins
North America Polyamide Market
Polymers & Resins
Formaldehyde-Free Resin Market
Polymers & Resins
Thermoplastic Micro Molding Market
Polymers & Resins
Gel Polymer Electrolytes Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Conditioning Polymers Market
Polymers & Resins
PET Foam Core Market
Polymers & Resins
Saudi Arabia Engineering Plastics Market
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Middle-East and Africa Polyethylene Terephthalate (PET) Resin Market