
 High Density Polyethylene (HDPE) Market | 2026-2036
High Density Polyethylene (HDPE) Market Size, Share, and Industry Trends Forecast 2026-2036
High Density Polyethylene (HDPE) Market Analysis
Buyer concentration across municipal water utilities and large packaging converters is broadening as smaller regional recyclers and specialty compounders enter the procurement base. Dow Inc. leverages its integrated Gulf Coast feedstock position to serve North American pipe and packaging accounts. LyondellBasell Industries N.V. anchors European supply through its Rotterdam hub and circular polymer investments. SABIC competes across Middle Eastern and Asian markets with advantaged ethane-based production economics.
High density polyethylene is a thermoplastic polymer produced through catalytic polymerization of ethylene, typically exhibiting density between 0.941 and 0.965 g/cm³, with high tensile strength, chemical resistance, and stiffness suited to rigid applications. Manufacturers employ slurry-phase or gas-phase processes with Ziegler-Natta or metallocene catalysts to control molecular weight distribution and melt flow index for targeted end uses. Pipe-grade HDPE commands durable infrastructure contracts with long offtake visibility, while recycled-content bottle grades capture premium positioning under extended producer responsibility frameworks. Packaging applications dominate volume offtake, though construction-oriented pipe and sheet segments retain higher margin stability across project cycles.
The EPA regulates HDPE manufacturing emissions under Clean Air Act provisions, while REACH and the EU Green Deal impose recycled content thresholds and carbon intensity disclosures on European-sourced material. FDA food-contact approvals and state-level recycled content laws in California shape product formulation and market access for domestic suppliers. Stakeholders must track regulatory divergence between jurisdictions, as compliance costs and specification requirements will determine which production assets retain competitive supply positions.
Market Dynamics
The HDPE market is undergoing structural reconfiguration as recycled-content mandates and ethane feedstock economics simultaneously reshape production investment and offtake patterns across packaging and infrastructure segments.
Growth Catalysts
- EU Green Deal recycled thresholds:European converters are securing long-term contracts for post-consumer recycled grades to meet binding packaging waste regulations, pulling capital into chemical recycling infrastructure.
- Municipal water infrastructure:Utilities in China, India, and the United States are specifying PE100 pipe grades for pressure-rated distribution networks, locking in multi-year procurement volumes.
- Metallocene catalyst diffusion:Narrow molecular weight distribution resins are penetrating thin-wall injection molding applications, enabling lightweighting in rigid containers without performance trade-offs.
Market Restraints
- Ethane price volatility:Gulf Coast crackers face margin compression when natural gas liquids benchmarks spike, constraining expansion timing for export-oriented assets.
- Mechanical recycling contamination limits:Food-contact approvals for post-consumer flake remain restricted under FDA and EFSA frameworks, capping circular material penetration in sensitive packaging.
- Polypropylene substitution in automotive:Interior trim and under-hood applications are migrating to reinforced PP compounds, eroding historical HDPE volumes in vehicle platforms.
Strategic Opportunities
- India flexible packaging expansion:Domestic film converters are underserved by local resin supply, creating import substitution potential for Middle Eastern producers with freight-advantaged positions.
- California SB 54 implementation:Extended producer responsibility rules are forcing brand owners to source certified recycled content, generating premium pricing tiers for verified circular grades.
- Digital watermark sorting integration:Machine-readable packaging markers combined with near-infrared separation are converging to unlock food-grade mechanical recycling at commercial scale.
Industry Challenges
- Polymer characterization skill scarcity:Laboratories capable of certifying recycled content chain of custody and melt flow consistency are concentrated in Western Europe and the US Gulf Coast, creating bottlenecks for Asian converters seeking export market access.
- Legacy extrusion line retrofit costs:Converting sheet and thermoforming assets to process higher-viscosity recycled blends requires screw and die modifications that compress near-term returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | High Density Polyethylene (HDPE) Market |
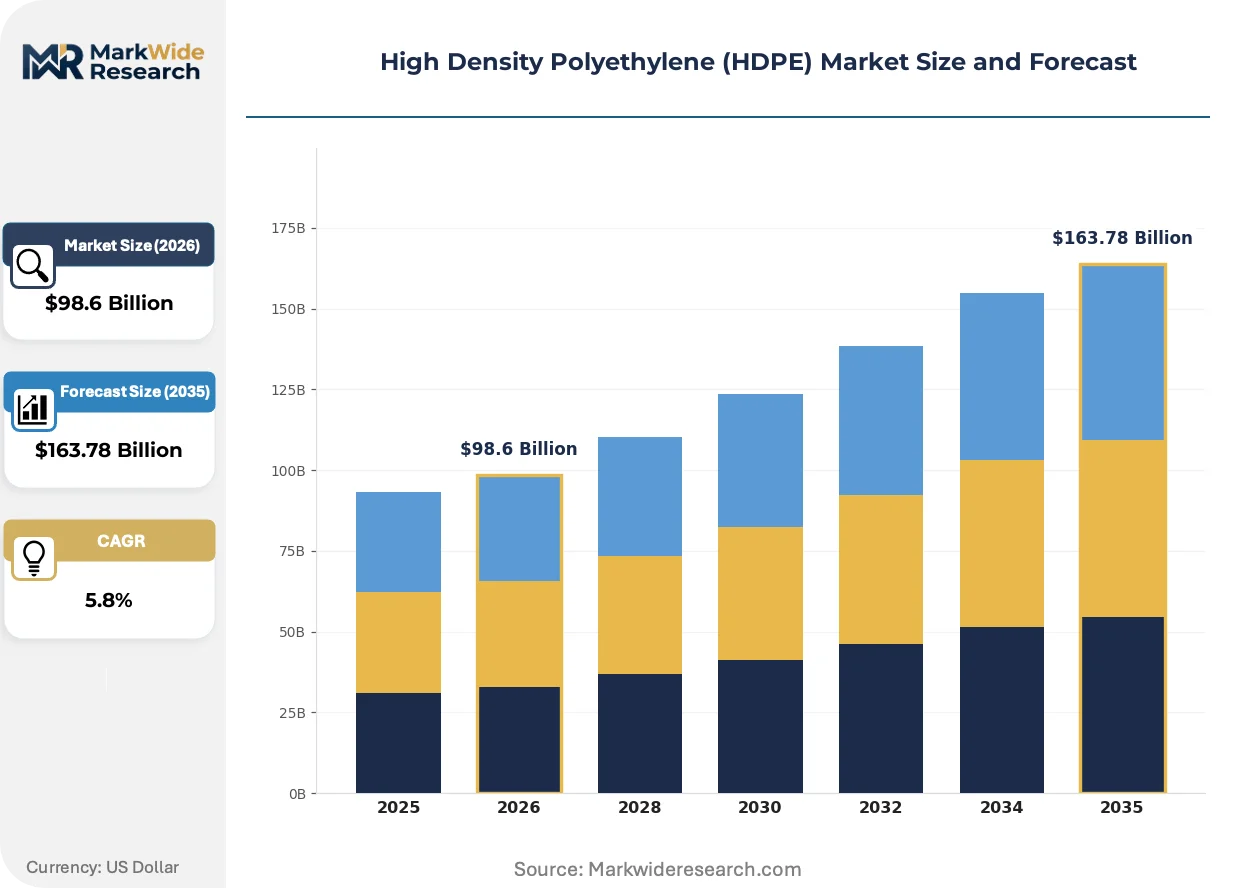
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $163.78 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Pipes, Sheets Application: Packaging, Construction, Automotive, Consumer Goods End User: Food & Beverage, Consumer Electronics, Healthcare, Agriculture Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | ExxonMobil Chemical Company, Dow Inc., LyondellBasell Industries N.V., SABIC, Chevron Phillips Chemical Company LLC, INEOS Group Holdings S.A., Borealis AG, Reliance Industries Limited, China Petroleum & Chemical Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
High Density Polyethylene (HDPE) Market Emerging Trajectories
Advanced catalyst systems and regulatory compliance architectures are compressing product development cycles while fragmenting the supplier base between integrated majors and specialty compounders.
Metallocene single-site catalyst technology is consolidating control over molecular architecture in slurry-phase HDPE production. Pipe-grade and film-grade producers are adopting these systems to reduce gel content and improve impact resistance. The technology is consolidating specification power among resin suppliers capable of delivering narrow polydispersity indices under long-term infrastructure contracts.
REACH substance of very high concern listings are forcing reformulation of legacy stabilizer packages in European-sourced material. Compounders are substituting phenolic antioxidants with phosphite blends to maintain processing stability while meeting disclosure thresholds. Construction-grade pipe extruders in Germany and the Netherlands are absorbing compliance costs through specification premiums on certified low-emission grades.
Brand-owner sustainability scorecards are compressing supplier qualification timelines and fragmenting procurement across multiple resin sources. Large packaging converters in the United States are unbundling volume commitments among three to four suppliers to secure recycled-content diversity. This pattern is most visible in blow-molded personal care bottles, where California-based brands are requiring mass-balance certification for virgin displacement claims.
High Density Polyethylene (HDPE) Market Segmentation
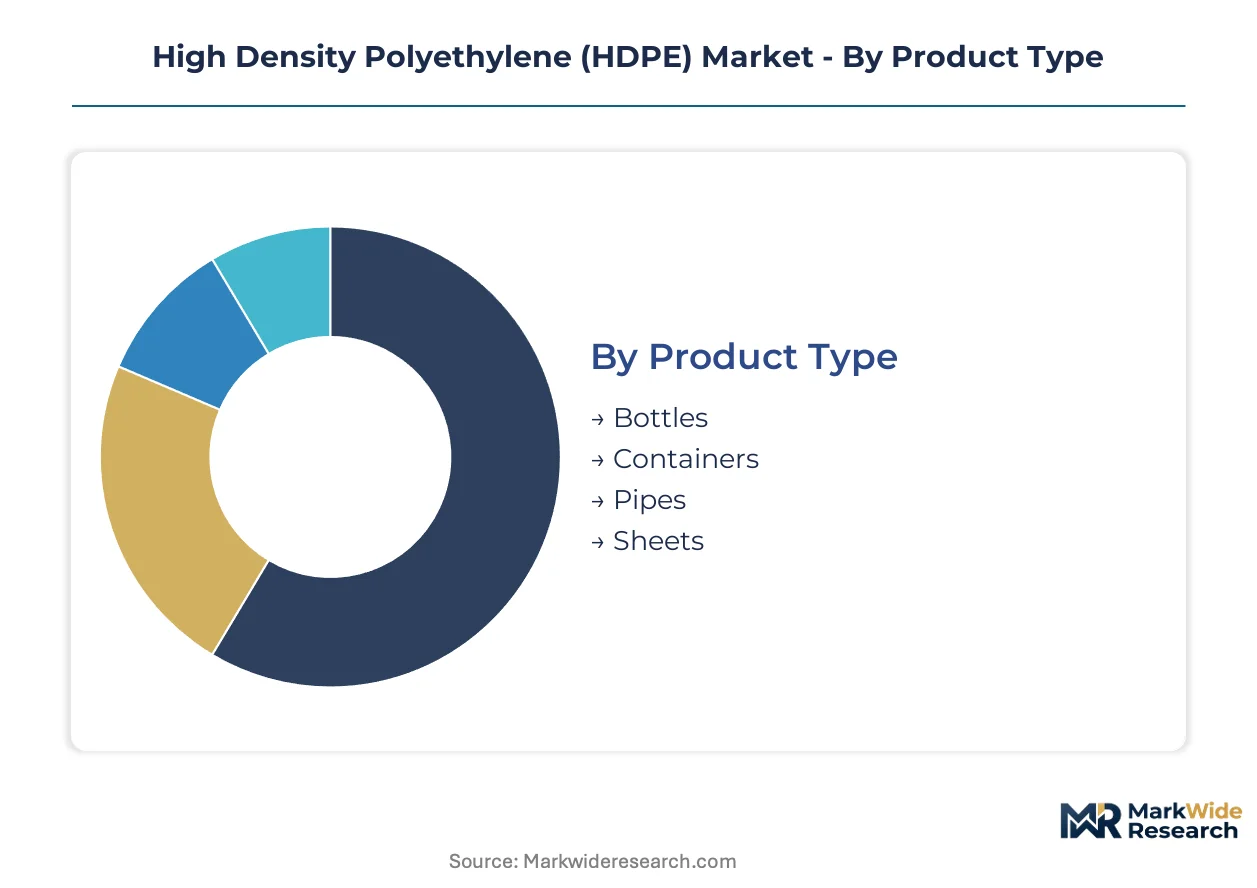
HDPE procurement patterns diverge sharply across end-use specifications, with pipe-grade buyers prioritizing melt flow consistency over decades-long infrastructure lifecycles while packaging converters chase lightweighting targets and recycled-content certifications. Segment boundaries are blurring as multi-layer blow molding and metallocene catalyst diffusion enable grade substitution that reshapes traditional volume allocations.
Product Type:
Buyers differentiate primarily by processing viscosity requirements and regulatory certification burdens rather than resin chemistry alone.
- Pipes:PE100 and PE80 grades dominate pressure-rated municipal water infrastructure with density specifications between 0.941 and 0.965 g/cm³ and stringent slow-crack-growth resistance standards. Demand concentrates in China, India, and the United States as utilities replace aging cast-iron networks; procurement locks into multi-year offtake agreements with integrated producers capable of lot-traceable certification.
- Bottles:Blow-molded containers for milk, detergents, and personal care rely on narrow molecular weight distribution resins for uniform wall thickness and drop-impact performance. California SB 54 recycled-content mandates and EU Green Deal thresholds are forcing brand owners to source certified post-consumer grades, fragmenting supply chains between virgin and circular-certified tiers.
- Containers:Injection-molded pails, crates, and industrial totes utilize higher-melt-flow grades for thin-wall cycle speed. Food-contact FDA approvals restrict recycled flake incorporation, capping circular penetration in dairy and edible-oil applications.
- Sheets:Extruded thermoforming substrates for geomembranes and recreational vehicle construction emphasize stiffness-to-weight ratios and UV stabilization packages. Construction project cyclicality drives volatile spot purchasing patterns distinct from contract-heavy pipe segments.
Volume sits with pipes; growth tilts toward bottles.
Application:
Margin stability varies inversely with commoditization pressure, separating project-tied infrastructure from high-turnover consumer packaging.
- Packaging:Rigid containers, films, and caps absorb the majority of resin offtake, with converters in India and Southeast Asia expanding blown-film capacity ahead of local supply growth. REACH substance-of-very-high-concern listings are forcing antioxidant package reformulations that compress compounder margins on European-sourced material.
- Construction:Geothermal ground-loop piping, geomembrane liners, and structural wall panels command specification premiums tied to engineering certification and installation warranty terms. German and Dutch regulators are imposing carbon-intensity disclosures on construction-grade material that favor low-emission production assets.
- Automotive:Fuel tanks, interior trim, and under-hood ducting face displacement from reinforced polypropylene compounds in weight-reduction programs. Tier-1 suppliers are consolidating resin qualifications to reduce supplier audit burdens.
- Consumer Goods:Toys, housewares, and furniture components compete with polypropylene and polystyrene on cost, with HDPE retaining share only in durability-critical applications like outdoor storage.
Revenue concentrates in packaging; margin stability favors construction.
End User:
Certification requirements and volume scale separate regulated food-contact buyers from discretionary industrial purchasers.
- Food & Beverage:Dairy bottles, edible-oil containers, and beverage crates demand FDA and EFSA food-contact approvals that restrict mechanical recycling feedstock. Mass-balance certification for chemical recycling is emerging as a compliance pathway under extended producer responsibility frameworks.
- Healthcare:Pharmaceutical bottles, medical device housings, and diagnostic consumables require USP Class VI biocompatibility and gamma-sterilization stability. Lot traceability and cleanroom handling protocols exclude most recycled-content grades.
- Agriculture:Irrigation pipe, greenhouse film, and silage wrap prioritize UV resistance and cost minimization over aesthetic quality. Seasonal purchasing patterns concentrate volume in pre-planting procurement windows.
- Consumer Electronics:Laptop chassis, cable jacketing, and appliance housings specify flame-retardant compounded grades with restricted substance compliance under RoHS and REACH.
Procurement scale sits with food and beverage; technical barriers protect healthcare premiums.
Distribution Channel:
Logistics economics and buyer sophistication determine channel selection, with large converters bypassing intermediaries while smaller processors rely on distributor technical support.
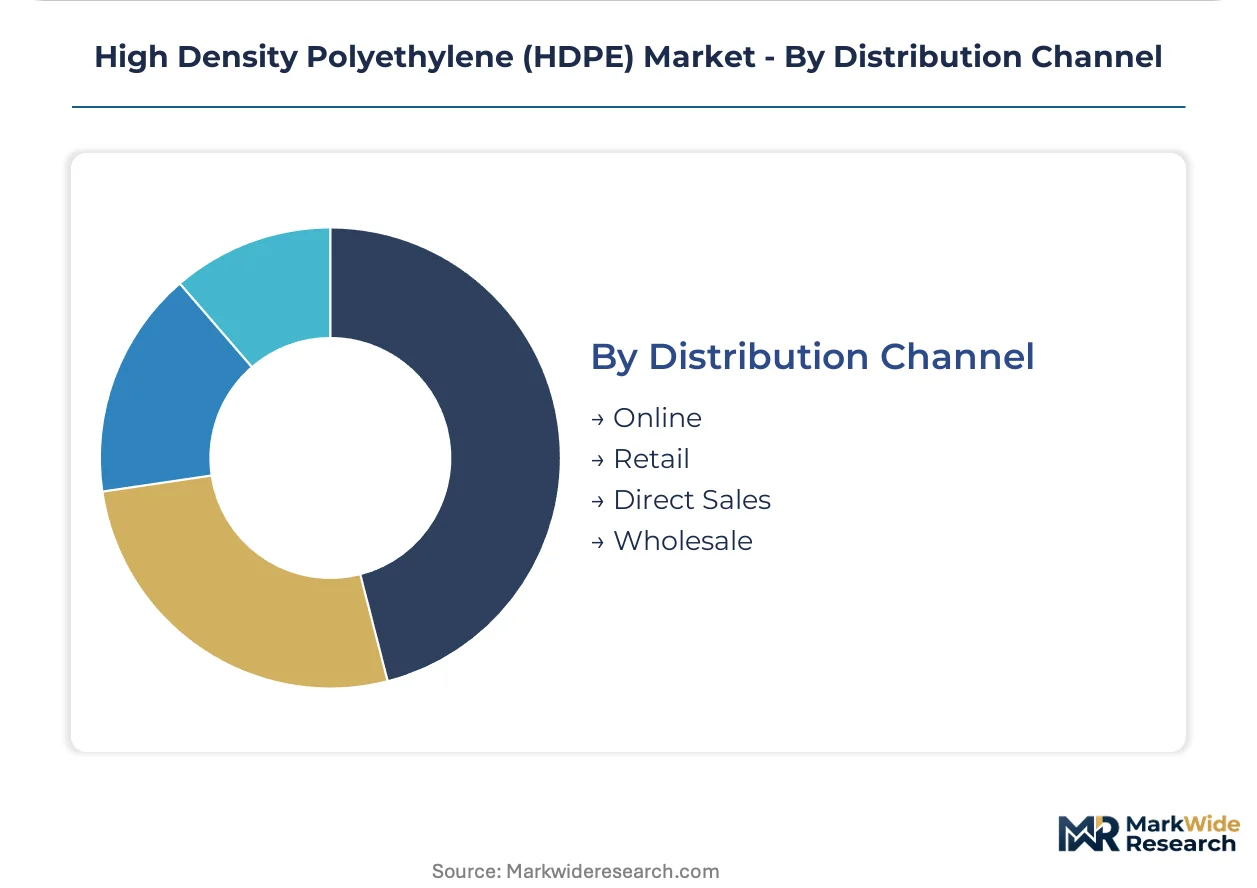
- Direct Sales:Integrated majors like Dow and LyondellBasell serve municipal utilities and multinational packaging converters through dedicated account teams. Long-term contracts embed volume commitments, price formulas tied to ethane or naphtha benchmarks, and technical service provisions for extrusion line optimization.
- Wholesale:Regional distributors aggregate spot purchases for mid-tier processors lacking storage infrastructure or credit lines for railcar-quantity orders. Inventory positioning in Rotterdam, Houston, and Singapore hubs enables just-in-time delivery to European, North American, and Asian converters.
- Retail:Small-lot bagged resin for prototype molding, hobbyist 3D printing filament, and repair applications sells through industrial supply chains with significant markup over bulk pricing.
- Online:Digital platforms are penetrating specialty compound and color-concentrate procurement, though bulk virgin resin remains ill-suited to e-commerce logistics.
Contract volume sits with direct sales; spot flexibility concentrates in wholesale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in China, the United States, and India as municipal water infrastructure expansion and packaging capacity buildouts absorb the majority of resin volumes. Regulatory divergence across jurisdictions is fragmenting procurement specifications, with recycled-content mandates in California and Germany pulling supply chains in distinct compliance directions. Production assets align with feedstock economics, favoring ethane-advantaged Gulf Coast crackers and Middle Eastern export hubs.
China
Utilities in the Yangtze River Delta and Pearl River Delta are specifying PE100 pipe grades for pressure-rated water distribution networks under the national water security program. The Ministry of Ecology and Environment imposes carbon intensity disclosures on petrochemical assets, favoring newer crackers with integrated power generation. Sinopec operates integrated complexes in Zhenhai and Maoming that supply both domestic converters and Southeast Asian export markets.
United States
Municipal water utilities in Texas and California are locking into multi-year procurement contracts for pipe-grade material as lead service line replacement accelerates. California SB 54 mandates 30 percent recycled content in single-use packaging by 2028, forcing brand owners to source certified post-consumer grades. Gulf Coast crackers from Corpus Christi to Lake Charles leverage advantaged ethane feedstock economics to serve North American and Latin American export demand.
Germany
Construction-grade pipe extruders in the Ruhr industrial cluster absorb compliance costs for REACH substance-of-very-high-concern reformulations through specification premiums on certified low-emission grades. The EU Green Deal imposes binding recycled-content thresholds on packaging waste, pulling capital into chemical recycling infrastructure at the Rotterdam-Antwerp hub. BASF and LyondellBasell anchor European supply through integrated complexes in Ludwigshafen and Rotterdam.
India
Domestic film converters in Maharashtra and Gujarat expand blown-film capacity ahead of local resin supply growth, creating import substitution potential for Middle Eastern producers. The Bureau of Indian Standards mandates quality certification for potable water pipe applications, tightening procurement specifications for municipal utilities. Reliance Industries operates integrated crackers in Jamnagar that supply both domestic packaging converters and export markets across South Asia.
Saudi Arabia
SABIC leverages advantaged ethane-based production economics to compete across Middle Eastern and Asian markets with freight-advantaged positions. The Saudi Vision 2030 program drives downstream petrochemical diversification into specialty grades for construction and packaging applications. Industrial clusters in Jubail and Yanbu concentrate export-oriented capacity serving South Asian and East African demand growth.
High Density Polyethylene (HDPE) Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue circular-certified and specialty compounded segments. The market structures around integrated majors with captive feedstock positions, regional specialists with logistics advantages, and technology licensors with catalyst differentiation. Strategic archetypes include ethane-advantaged exporters, naphtha-integrated European compounders, and recycled-content specialists with mass-balance certification. Dominant competitive moves center on backward integration into chemical recycling assets and geographic expansion into underserved South Asian flexible packaging markets.
Among North American integrated majors, Dow Inc., ExxonMobil Chemical Company, and Chevron Phillips Chemical Company LLC exemplify the ethane-advantaged archetype with Gulf Coast production positions. Dow anchors supply relationships with municipal water utilities and multinational packaging converters through dedicated account teams. ExxonMobil represents the technology-licensing vector with catalyst and process expertise deployed across joint venture positions. Chevron Phillips occupies a position in pipe-grade specialization with PE100 certification capabilities for infrastructure contracts.
| Leading Market Players |
|---|
| ExxonMobil Chemical Company |
| Dow Inc. |
| LyondellBasell Industries N.V. |
| SABIC |
| Chevron Phillips Chemical Company LLC |
| INEOS Group Holdings S.A. |
| Borealis AG |
| Reliance Industries Limited |
| China Petroleum & Chemical Corporation |
| Others |
Supply Flow & Price Mechanics
Captive ethane cracking on the US Gulf Coast anchors both supply security and pricing power for integrated producers serving North American pipe and packaging accounts. This backward integration into natural gas liquids feedstock insulates margin structures from naphtha volatility that compresses European compounder economics.
Pricing Analysis
Volume concentrates in commodity pipe and film grades while margin stability sits with certified recycled-content tiers. Three-tier pricing structure across premium circular-certified, standard virgin, and economy spot grades reflects California SB 54 compliance premiums and REACH disclosure costs. Pricing pressure stems from ethane benchmark spikes that squeeze Gulf Coast cracker margins. Municipal utilities exhibit lowest price sensitivity due to multi-year infrastructure contracts; spot-buying sheet converters show highest sensitivity to resin index movements.
Supply Chain Analysis
Specialized polymer technicians in Rotterdam, Houston, and Singapore constrain qualification throughput for Asian converters seeking export market access. Supply concentrates in the United States, Saudi Arabia, and China, with each hub drawing from distinct feedstock slates—ethane, associated gas, and coal-to-olefins respectively. Raw material dependencies center on ethane, naphtha, and hydrogen for metallocene catalyst activation. Single-source vulnerability runs through catalyst technology licensors controlling narrow polydispersity resin production. Distribution runs through direct railcar contracts for large converters and regional distributor hubs for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around producers with integrated feedstock positions and circular certification capabilities, as regulatory compliance costs force sub-scale compounders toward exit or acquisition.
For Market Incumbents: Deepen backward integration into chemical recycling assets to secure mass-balance certification for California and EU Green Deal compliance. Expand PE100 pipe-grade capacity in Texas and Louisiana to capture municipal water infrastructure replacement cycles. Reinforced polypropylene substitution in automotive applications threatens historical HDPE volumes; defend position through metallocene catalyst differentiation in thin-wall packaging. For New Entrants and Emerging Players: Capture import substitution opportunity in Maharashtra and Gujarat flexible packaging markets where domestic resin supply lags converter capacity expansion. Target certified post-consumer recycled grades for personal care bottle applications under extended producer responsibility frameworks. Pursue toll-compounding partnerships with established distributors to bypass capital-intensive cracker investments. For Investors and Strategic Acquirers: Exit pathways concentrate in specialty compounders with FDA food-contact approvals and mass-balance certification infrastructure. Long-term viability favors assets with ethane feedstock access and circular polymer technology licenses. Watch for inflection in digital watermark sorting adoption rates, which unlock food-grade mechanical recycling economics at commercial scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemical Recycling | Secures mass-balance certification for EU Green Deal and California SB 54 compliance thresholds. |
| Metallocene Catalyst Technology Licensing | Enables narrow polydispersity PE100 grades that command specification premiums in municipal water contracts. |
| Long-term Supply Agreement with Municipal Utilities | Locks in decade-long offtake visibility for pipe-grade production assets against spot price volatility. |
| Joint Venture in South Asian Flexible Packaging | Captures import substitution demand in Maharashtra and Gujarat ahead of local resin supply growth. |
| Green Manufacturing Transition to Low-emission Grades | Meets German and Dutch carbon-intensity disclosure requirements for construction-grade pipe extruders. |
Methodological Framework
Document review covered trade customs data, SEC 10-K petrochemical disclosures, and ACC industry reports, complemented by interviews with plant managers at integrated crackers, procurement leads at multinational packaging converters, technical R&D directors at catalyst licensors, and distribution channel partners in Rotterdam and Singapore hubs. Bottom-up resin demand modeling triangulated against top-down ethylene derivative capacity analysis.
Segmented volume and value trajectories emerged from grade-tier splits across pipe, bottle, container, and sheet specifications crossed with regional production hub economics. CAGRs derived from ethane-naphtha spread projections, infrastructure spending pipelines, and regulatory mandate implementation schedules. Forecast inputs incorporated metallocene diffusion rates and chemical recycling capacity buildout assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ethane price volatility, REACH substance listing expansions, and mechanical recycling contamination threshold revisions. A small set of named triggers—digital watermark sorting adoption, California SB 54 enforcement intensity, and PE100 specification updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Silicone Resins Market
Polymers & Resins
Extruded Polystyrene Market
Polymers & Resins
Cross-Linked Polyethylene (XLPE) Market
Polymers & Resins
Global Injection Molding Plastic Market
Polymers & Resins
Global Chromatography Resin Market
Polymers & Resins
Welan Gum Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market
Polymers & Resins
North America Linear Low-Density Polyethylene Market
Polymers & Resins
Bio-Based Construction Polymers Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
Polystyrene (PS) and Expanded Polystyrene (EPS) Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Italy Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Ethylene Acrylic Acid (EAA) Copolymers Market