
 Scleroglucan Market | 2026-2036
Scleroglucan Market Size, Share, and Industry Trends Forecast 2026-2036
Scleroglucan Market Analytics
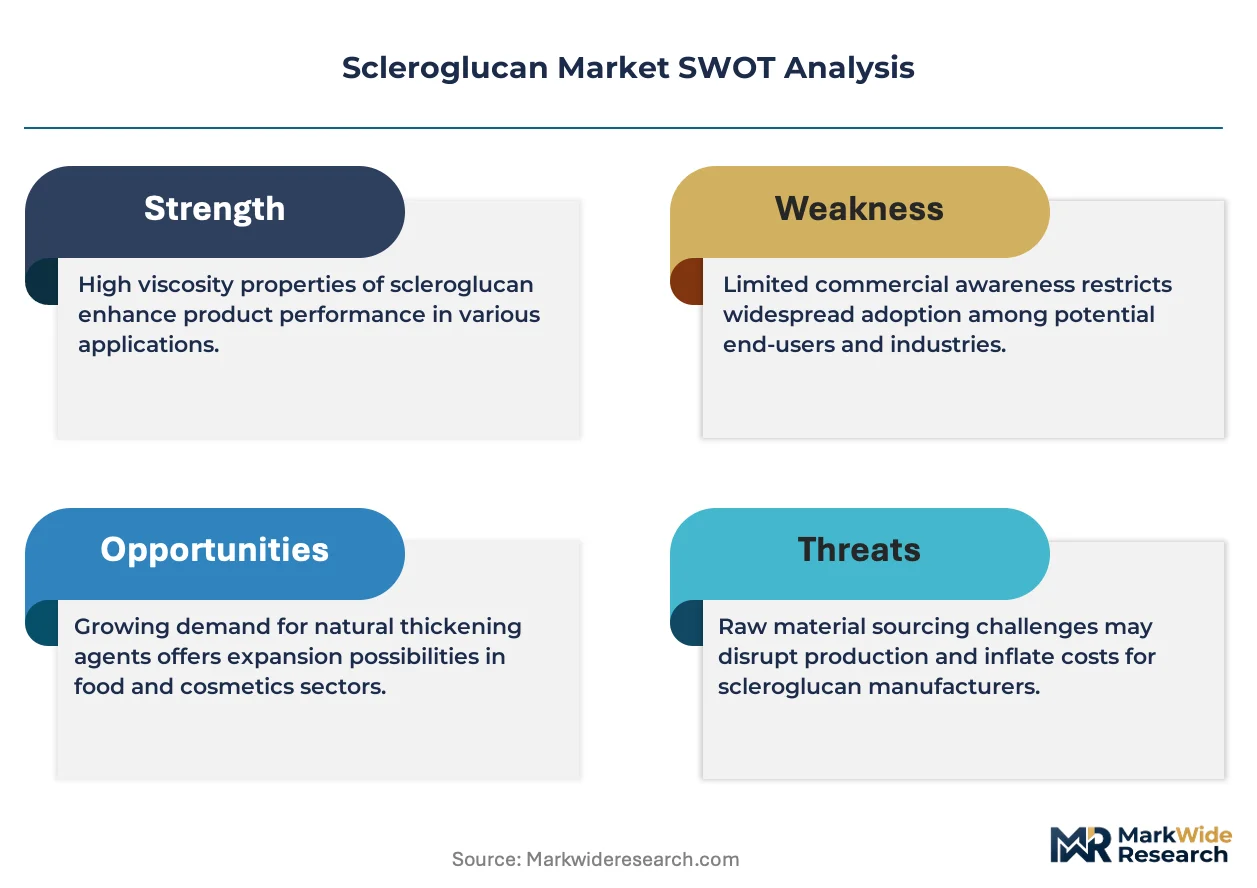
REACH is broadening the cost-of-entry calculus for petroleum-derived rheology modifiers across European cosmetics and pharmaceuticals. Cargill leverages its agricultural feedstock network to secure fermentation substrate cost advantages. ELICITYL anchors its position through specialized biofermentation expertise in carbohydrate polymers. CP Kelco competes with established gellan gum and xanthan infrastructure that extends into scleroglucan co-production.
Scleroglucan is a non-ionic extracellular polysaccharide produced by Sclerotium rolfsii fermentation, composed of a linear beta-1,3-glucan backbone with single glucose side chains at every third unit, yielding high thermal stability and viscosity retention across pH 2-12. It functions primarily as a suspending, stabilizing, and film-forming agent in oilfield chemicals, personal care, and pharmaceutical formulations. Powder grades dominate volume due to extended shelf stability and freight efficiency, while gel forms capture premium positioning in cosmetic emulsions where cold-process compatibility reduces energy input. Thickening agent applications lead across food and beverage stabilization, though gelling agent demand accelerates in biotechnology cell-culture media where lot-to-lot consistency commands specification adherence.
EMA pharmaceutical excipient guidelines and EU REACH chemical registration requirements shape purity thresholds and toxicological documentation burdens for scleroglucan suppliers targeting European drug manufacturers. EFSA food additive evaluations determine acceptable daily intake thresholds that gate entry into European beverage stabilization applications. Stakeholders must monitor regulatory divergence between EU chemical and food frameworks while assessing fermentation capacity expansion against bio-based polymer certification timelines.
Market Dynamics
REACH chemical registration requirements are restructuring competitive entry costs for biopolymer rheology modifiers across European cosmetics and pharmaceuticals, favoring fermentation-based suppliers with existing toxicological documentation.
Growth Catalysts
- EU Green Deal biopolymer mandates:Petroleum-derived thickener substitution accelerates as member states implement national packaging and formulation targets aligned with circular economy action plans.
- Clean-label cosmetic formulation:Premium personal care clusters in France and Germany specify non-ionic stabilizers for cold-process emulsions that reduce energy input and water consumption.
- Fermentation substrate optimization:Agricultural feedstock networks secure cost-advantaged glucose supply chains for Sclerotium rolfsii cultivation at commercial scale.
Market Restraints
- Input cost volatility:Agricultural commodity price swings for corn-derived glucose directly compress fermentation margins without long-term supply contracts.
- Supply concentration risk:Fermentation capacity clusters in Western Europe create geographic vulnerability to regional energy price shocks and logistics disruptions.
- Petroleum-derived substitute persistence:Carbomer and acrylate-based thickeners retain cost advantages in mass-market personal care despite regulatory headwinds.
Strategic Opportunities
- Biotechnology cell-culture media:Lot-to-lot consistency specifications for pharmaceutical-grade scleroglucan command premium positioning in protein production applications.
- EMA pharmaceutical excipient qualification:Toxicological documentation investments open formulation access to sterile injectable and ophthalmic drug categories.
- Cold-chain food stabilization:EFSA food additive evaluations for beverage applications create pathway into premium ready-to-drink formulations requiring freeze-thaw stability.
Industry Challenges
- Fermentation scale-up talent scarcity:Specialized carbohydrate polymer expertise concentrates at legacy biofermentation facilities, constraining rapid capacity expansion.
- REACH registration timeline compression:ECHA substance evaluation deadlines force simultaneous toxicological study investment across multiple polymer grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scleroglucan Market |
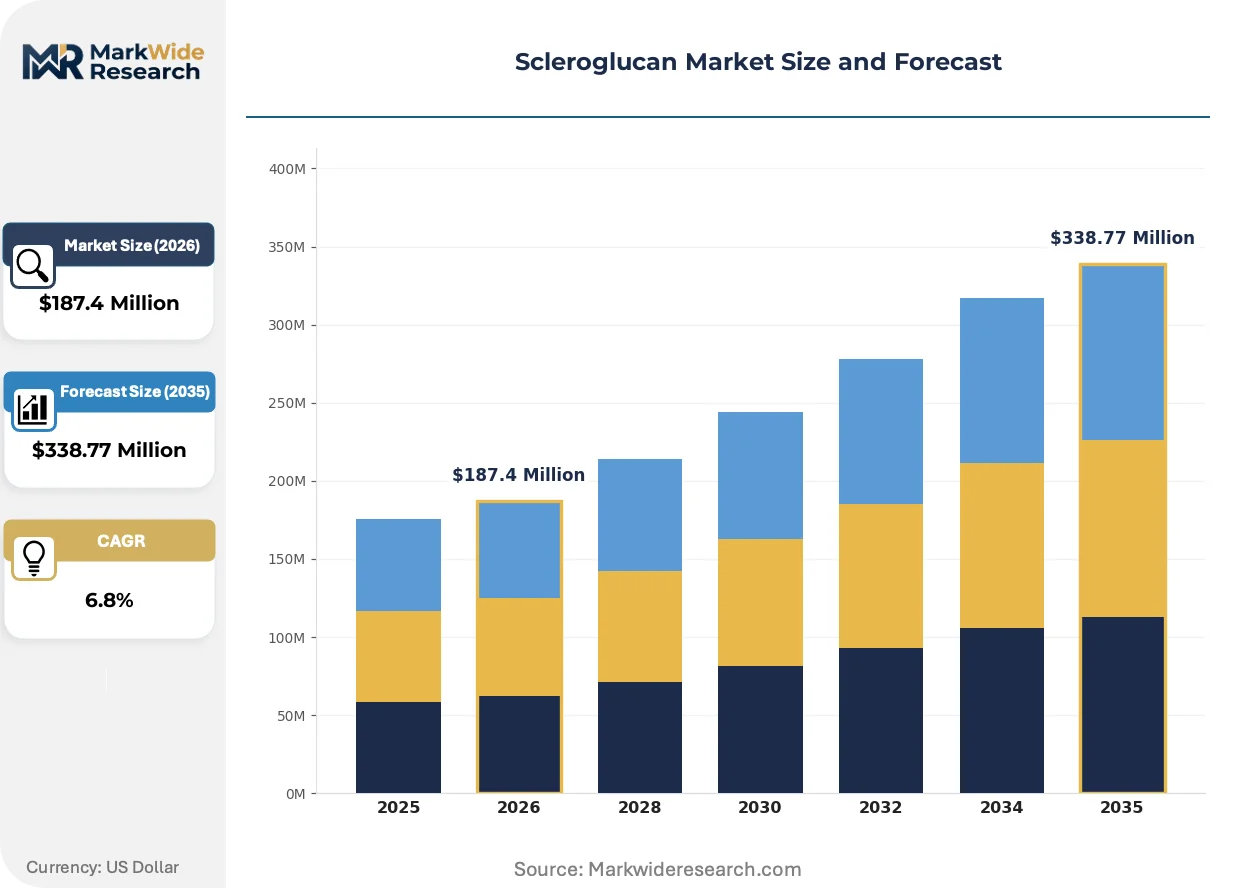
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Gel, Liquid, Paste End User: Cosmetics, Food & Beverage, Pharmaceuticals, Biotechnology Application: Thickening Agent, Stabilizer, Gelling Agent, Emulsifier Form: Natural, Modified, Organic, Synthetic |
| Companies Covered | Cargill, ELICITYL, Carbosynth, CarboMer, Shandong Qilu Biotechnology Group, General Mills, Arkema, Sanofi, CP Kelco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scleroglucan Market Evolving Landscape
Formulation chemistry is pivoting toward thermal stability and pH tolerance as functional differentiators, with cold-process compatibility emerging as a decisive specification for energy-conscious manufacturing.
High-purity powder grades engineered for extended shelf stability are expanding into pharmaceutical excipient specifications previously dominated by cellulose derivatives. Contract manufacturers in Germany and France specify these grades for sterile formulation lines requiring validated supply security. The technology is expanding into ophthalmic and parenteral drug categories where viscosity retention across autoclave cycles commands formulation preference.
REACH authorization requirements for petroleum-based acrylates are tightening toxicological documentation burdens across cosmetic and pharmaceutical supply chains. ECHA substance evaluation timelines are compressing registration windows for incumbent synthetic thickeners. Biopolymer suppliers with pre-existing dossiers capture specification momentum in premium personal care clusters where brand owners face consumer transparency pressure.
Specification-driven procurement now prioritizes lot-to-lot consistency documentation over unit cost in pharmaceutical and biotechnology applications. Quality agreement structures are displacing transactional purchasing for cell-culture media and sterile formulation inputs. This pattern concentrates in Switzerland and the Netherlands where contract manufacturing organizations aggregate demand for validated excipient supply chains.
Scleroglucan Market Segmentation
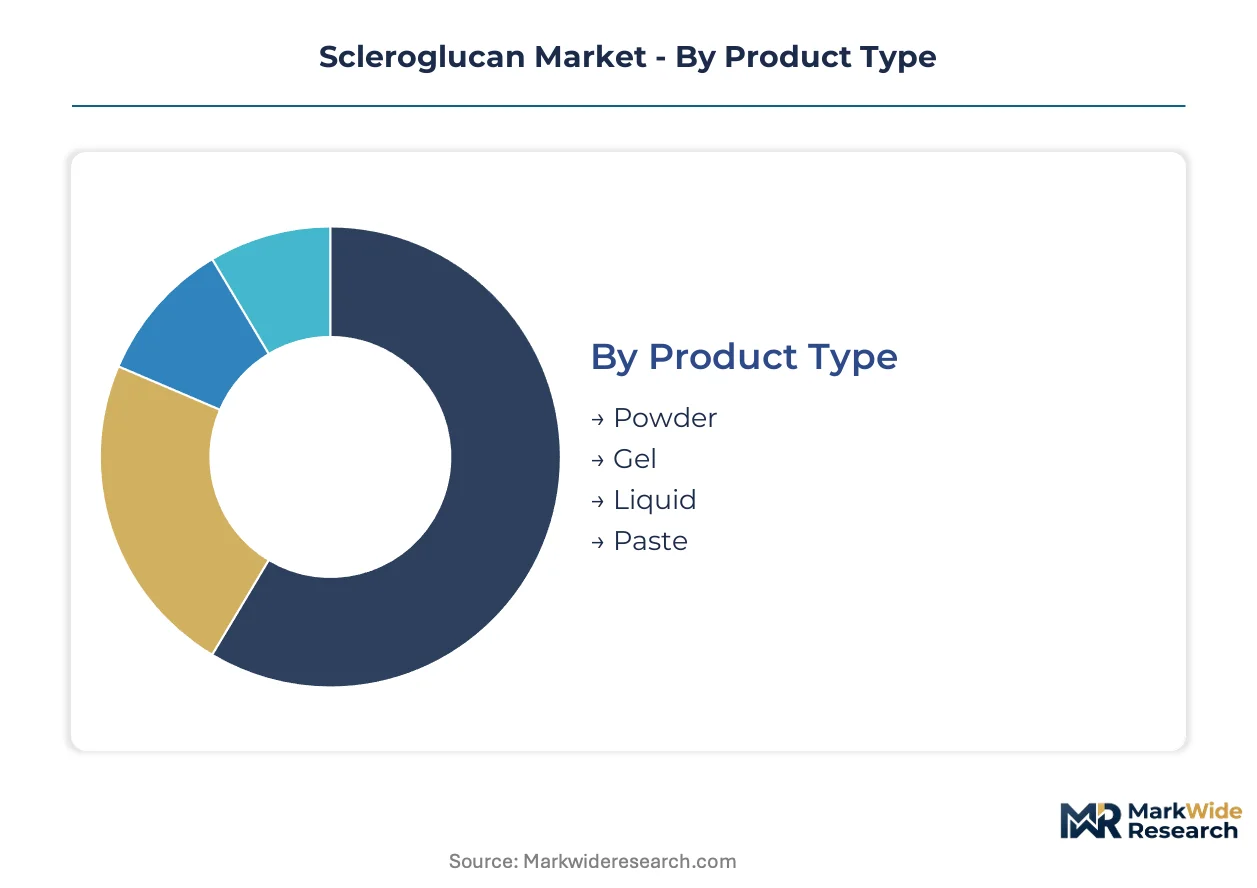
Scleroglucan specification tiers map directly to regulatory documentation burdens across pharmaceutical, food, and cosmetic applications. Each segment carries distinct certification requirements that reshape supplier competitive positioning and customer procurement criteria.
Product Type:
Powder grades require EMA excipient qualification for sterile injectable access, while gel and liquid forms face EFSA food additive dossier requirements for beverage stabilization.
- Powder:Dried beta-1,3-glucan particulate engineered for extended shelf stability and freight efficiency. Demand concentrates in German and French pharmaceutical contract manufacturing where validated supply security commands specification preference.
- Gel:Hydrated scleroglucan suspension optimized for cold-process cosmetic emulsions. Premium personal care clusters in France specify this grade to reduce energy input during manufacturing.
- Liquid:Pre-hydrated solution targeting ready-to-drink beverage stabilization. EFSA evaluation timelines determine acceptable daily intake thresholds for European food applications.
- Paste:High-concentration semi-solid for industrial oilfield chemical formulations. Specialized rheology modification drives specification in upstream drilling operations.
Leading the category by volume: Powder. Growing fastest: Gel.
End User:
Pharmaceutical and biotechnology segments command premium positioning through lot-to-lot consistency documentation, while cosmetics and food applications scale through clean-label specification expansion.
- Cosmetics:Clean-label rheology modification for cold-process emulsions and suspending systems. REACH scrutiny of petroleum-derived thickeners accelerates biopolymer substitution in French and German premium personal care clusters.
- Food & Beverage:Stabilization for freeze-thaw resistant beverages and texture-modified formulations. EFSA additive evaluations gate entry into premium ready-to-drink categories.
- Pharmaceuticals:EMA-qualified excipient for sterile injectable, ophthalmic, and parenteral drug categories. Toxicological documentation investments open formulation access to validated supply chains.
- Biotechnology:Cell-culture media component requiring stringent lot-to-lot consistency for protein production. Quality agreement structures displace transactional purchasing in Swiss and Dutch contract manufacturing organizations.
Pharmaceuticals anchor margin capture. Biotechnology exhibits steepest expansion trajectory.
Application:
Functional differentiation separates commodity thickening from premium gelling and emulsification where thermal stability across pH 2-12 commands specification adherence.
- Thickening Agent:Viscosity building across food, beverage, and personal care formulations. Volume concentrates in mass-market applications where petroleum-derived substitutes retain cost advantages despite regulatory headwinds.
- Stabilizer:Suspension maintenance and phase separation prevention in emulsion systems. Cold-process compatibility drives specification in energy-conscious French cosmetic manufacturing.
- Gelling Agent:Three-dimensional network formation for cell-culture media and controlled-release matrices. Biotechnology applications command premium positioning through specification adherence.
- Emulsifier:Oil-water interface stabilization for cosmetic and pharmaceutical formulations. Film-forming properties differentiate scleroglucan from ionic alternatives.
Thickening Agent dominates volume throughput. Gelling Agent climbs the fastest.
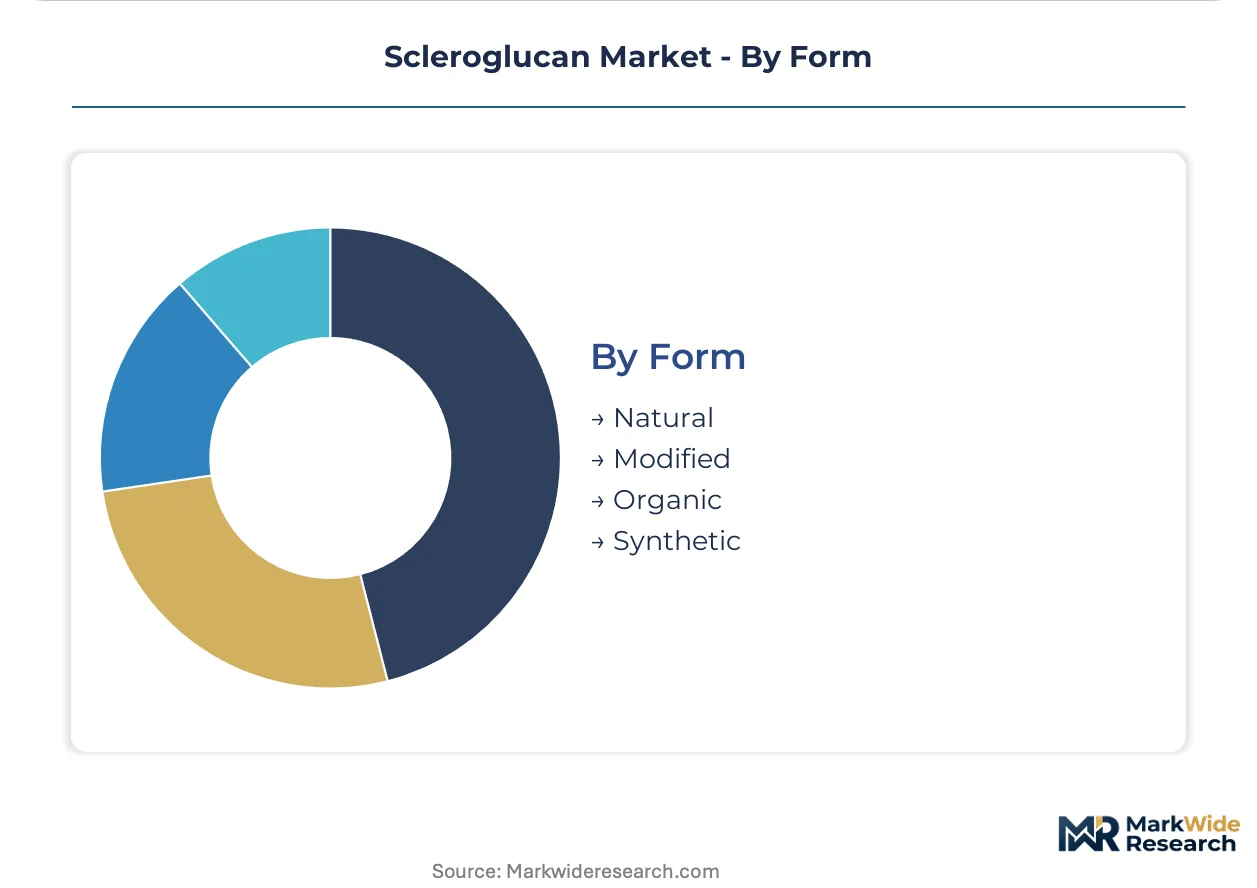
Form:
Natural and organic certifications carry EU bio-based polymer documentation requirements, while modified grades face additional toxicological study burdens under REACH substance evaluation timelines.
- Natural:Unmodified beta-1,3-glucan from Sclerotium rolfsii fermentation. EU Green Deal biopolymer mandates accelerate substitution for petroleum-derived alternatives in packaging and formulation applications.
- Modified:Chemically or enzymatically altered scleroglucan for enhanced solubility or functional properties. ECHA registration windows compress toxicological documentation timelines for multi-grade suppliers.
- Organic:Certified fermentation substrate traceability from agricultural feedstock networks. Premium positioning in clean-label cosmetic and food segments justifies cost premiums.
- Synthetic:Bio-identical polymer from non-fermentation routes. Limited commercial penetration due to cost disadvantages against fermentation-based production.
Natural form leads volume. Modified form gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic formulators in France and Germany drive premium scleroglucan specification, while biotechnology clusters in Switzerland and the Netherlands validate supply chains for pharmaceutical-grade material.
France
Premium personal care clusters in Île-de-France and Provence-Alpes-Côte d'Azur specify cold-process cosmetic emulsions. ANSM cosmetic ingredient guidelines reinforce clean-label positioning for non-ionic stabilizers. Lyon and Grasse formulation houses expand scleroglucan use in fragrance microemulsion systems.
Germany
Pharmaceutical contract manufacturers in North Rhine-Westphalia and Bavaria demand EMA-qualified excipient grades. REACH substance evaluation timelines compress registration windows for petroleum-derived alternatives. Frankfurt and Munich sterile formulation lines validate supply security for beta-1,3-glucan powder grades.
Switzerland
Biotechnology cell-culture media producers in Basel and Zurich command lot-to-lot consistency documentation. Swissmedic pharmaceutical excipient requirements gate entry into sterile injectable categories. Contract manufacturing organizations aggregate demand for validated carbohydrate polymer supply chains.
Netherlands
Food and beverage stabilization applications concentrate in Randstad ready-to-drink formulation clusters. EFSA additive evaluations determine acceptable daily intake thresholds for beverage applications. Amsterdam and Rotterdam contract manufacturers specify freeze-thaw stable hydrocolloids for premium drink categories.
United States
Oilfield chemical formulators in Texas and Louisiana utilize scleroglucan for high-temperature drilling fluid stabilization. FDA pharmaceutical excipient guidelines shape toxicological documentation requirements for sterile formulation access. Houston upstream chemical suppliers specify thermal-stable rheology modifiers for deepwater operations.
Scleroglucan Market Competitive Landscape
European fermentation specialists anchor the premium documentation tier; Asian agricultural feedstock integrators hold scale-driven positions. The vendor base separates into three strategic archetypes: diversified agricultural conglomerates with captive glucose supply, specialized carbohydrate polymer biofermentation houses, and hydrocolloid portfolio players with multi-product infrastructure. Capacity expansion and REACH dossier filing represent the dominant competitive moves across 2024-2026.
Within the specialized biofermentation tier, ELICITYL and CP Kelco exemplify contrasting geographic and capability positioning. ELICITYL occupies a position among French carbohydrate polymer specialists with concentrated expertise in Sclerotium rolfsii cultivation. CP Kelco anchors a multi-hydrocolloid portfolio that extends gellan gum and xanthan infrastructure into scleroglucan co-production capabilities. Cargill represents the agricultural conglomerate archetype, leveraging upstream feedstock control into fermentation substrate cost structuring.
| Leading Market Players |
|---|
| Cargill |
| ELICITYL |
| Carbosynth |
| CarboMer |
| Shandong Qilu Biotechnology Group |
| General Mills |
| Arkema |
| Sanofi |
| CP Kelco |
| Others |
Value Network & Pricing Analysis
Pharmaceutical-grade powder certification diverges sharply from commodity gel and liquid tiers, compressing margins in mass-market cosmetic supply chains while concentrating pricing power with EMA-qualified producers in Germany and France. This bifurcation manifests in procurement patterns: validated sterile formulation lines command long-term offtake agreements, whereas beverage and personal care buyers negotiate spot-adjacent contracts sensitive to agricultural glucose price swings.
Pricing Analysis
Volume throughput concentrates in standard-grade powder and gel forms where petroleum-derived substitutes exert persistent cost pressure, while margin capture clusters in pharmaceutical and biotechnology tiers. Three-tier pricing structure across premium, standard, and economy levels reflects EMA excipient qualification status, lot-to-lot consistency documentation, and fermentation substrate traceability. Price differentiation hinges on toxicological dossier completeness and cold-chain compatibility certification. Cost compression in mass-market cosmetic grades is intensifying because carbomer and acrylate-based thickeners retain unit cost advantages despite REACH regulatory headwinds. Food and beverage stabilization buyers exhibit highest price sensitivity, whereas Swiss and Dutch contract manufacturing organizations prioritize supply security over unit economics.
Supply Chain Analysis
Direct-to-pharmaceutical-manufacturer channels handle EMA-qualified excipient demand, while distribution through specialized hydrocolloid distributors serves cosmetic and food formulation clusters. Fermentation capacity concentrates in France, Germany, and Switzerland, with agricultural glucose supply chains drawing from corn-derived feedstock networks in Western Europe. Raw material dependencies center on fermentation substrate quality, Sclerotium rolfsii strain consistency, and downstream purification resin supply. Single-source vulnerability runs through concentrated biofermentation expertise at legacy carbohydrate polymer facilities. Distribution runs through validated cold-chain logistics for pharmaceutical grades and standard freight for shelf-stable powder forms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive agricultural glucose supply and in-house fermentation capacity determine cost positioning against petroleum-derived substitutes.
For Market Incumbents: Deploy REACH dossier filing as a competitive moat to capture specification momentum in premium personal care and pharmaceutical segments. Cargill and CP Kelco should extend gellan gum and xanthan infrastructure into scleroglucan co-production to dilute fixed costs across hydrocolloid portfolios. Capacity addition in North Rhine-Westphalia and Bavaria addresses pharmaceutical contract manufacturing demand concentration. Certification investment in EMA sterile injectable qualification defends margin position against emerging Asian fermentation specialists. For New Entrants and Emerging Players: E-commerce-enabled direct sampling to mid-sized French cosmetic formulators bypasses incumbent distributor relationships. White-space targets include organic-certified fermentation substrates for clean-label food applications and biotechnology cell-culture media where lot-to-lot consistency documentation gaps persist. Cold-process cosmetic emulsion compatibility offers the most penetrable specification entry point. Digital-channel route through formulation chemistry platforms enables technical specification comparison against carbomer benchmarks. For Investors and Strategic Acquirers: Re-rating potential sits with specialized carbohydrate polymer biofermentation houses given REACH authorization timeline compression for petroleum-derived alternatives. Long-term viability over the next decade favors producers with backward integration into agricultural feedstock networks and forward integration into pharmaceutical excipient qualification. Acquisition target archetype: mid-cap French or German fermentation specialists with existing EMA dossiers and idle capacity expansion potential. Signal to watch: ECHA substance evaluation acceleration for acrylate-based thickeners as inflection indicator for biopolymer substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Glucose Supply | Cargill's agricultural feedstock network secures fermentation substrate cost advantages against spot-market dependent competitors. |
| EMA Excipient Qualification Investment | Toxicological documentation opens sterile injectable and ophthalmic drug categories previously dominated by cellulose derivatives. |
| Fermentation Capacity Co-Production | CP Kelco extends gellan gum infrastructure into scleroglucan to dilute fixed costs across hydrocolloid portfolios. |
| Cold-Chain Logistics Validation | Pharmaceutical-grade powder requires temperature-controlled distribution to maintain lot-to-lot consistency specifications. |
| Organic Certification Program | EU Green Deal biopolymer mandates accelerate premium positioning for traceable fermentation substrate supply chains. |
Research Methodology
Trade association filings, ECHA registration databases, and EMA excipient qualification records formed the secondary backbone of this analysis. Primary interviews with fermentation plant managers, cosmetic formulation chemists, pharmaceutical procurement leads, and hydrocolloid distribution channel partners validated production capacity estimates and specification demand patterns. Bottom-up triangulation across Sclerotium rolfsii cultivation volumes and top-down cross-check against end-use industry consumption patterns ensured convergence in market sizing.
Bottom-up modeling of powder, gel, liquid, and paste grade volumes combined with top-down validation against regional hydrocolloid trade flows anchored the analytical framework across the projection horizon. Segmentation dimensions included product type, end-user industry, functional application, and form certification tier. CAGRs were derived from elasticity-adjusted demand projections incorporating REACH regulatory substitution effects and EU Green Deal biopolymer mandate implementation. Industry-specific forecast inputs comprised agricultural glucose price volatility indices and pharmaceutical sterile formulation line expansion pipelines.
The model holds under stable REACH enforcement intensity and continued EU Green Deal implementation; deviation in ECHA substance evaluation acceleration or petroleum-derived thickener cost collapse would shift substitution trajectories. Forecasts reflect assumptions regarding fermentation scale-up talent availability and toxicological documentation investment continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Thermoplastic Ester Elastomer (TPEE) Market
Polymers & Resins
High Density Polyethylene (HDPE) Market
Polymers & Resins
US Polycarbonate Market
Polymers & Resins
Wood Coating Resins Market
Polymers & Resins
Global Polyether Ether Ketone (PEEK) Market
Polymers & Resins
Biobased Polypropylene PP Size Market
Polymers & Resins
Global Polymerization Initiator Market
Polymers & Resins
Heat Resistant Polymer Market
Polymers & Resins
Global High Performance Polyethylene Market
Polymers & Resins
Global Acrylic Emulsions Market
Polymers & Resins
Bio-Based Emulsion Polymers Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Europe Engineering Plastics Market
Polymers & Resins
Resorbable Polymers Market
Polymers & Resins
Polyalkylene Glycols (Pags) Market
Polymers & Resins
Polypropylene Powder Market