
 Global Protein a Resin Market | 2026-2036
Global Protein a Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Global Protein a Resin Market Foresight
The EU Green Deal is realigning bioprocessing supply chains toward lower-carbon resin production and solvent recovery systems. Danaher Corporation (Cytiva) leverages its chromatography platform dominance to control premium capture segments. Merck KGaA anchors European supply through its MilliporeSigma bioprocessing division. Repligen Corporation specializes in single-use ancillary technologies that complement protein A resin workflows.
Protein A resin comprises an immobilized Staphylococcus aureus-derived protein A ligand covalently bound to porous agarose or synthetic polymer matrices, engineered for selective binding of immunoglobulin G Fc regions at neutral pH with acidic elution. Pharmaceutical-grade powder formulations command the highest margin pools due to batch-to-batch consistency requirements for GMP biologics manufacturing. Liquid protein A resin formats represent the fastest-growing configuration as continuous bioprocessing adoption accelerates perfusion chromatography integration.
FDA enforces Current Good Manufacturing Practice guidelines that mandate resin lot traceability and extractables testing for therapeutic antibody purification. EMA's MDR and REACH frameworks impose leachable substance characterization and supplier qualification protocols across European biopharma operations. China's NMPA aligns with ICH Q5A viral safety standards while accelerating domestic biosimilar approvals. Stakeholders must monitor regulatory divergence between FDA process validation requirements and emerging NMPA biologics guidelines as manufacturing regionalization reshapes supplier qualification burdens.
Market Dynamics
Continuous bioprocessing adoption is compressing batch chromatography cycles and forcing resin suppliers to engineer higher-capacity ligand densities for perfusion-compatible capture steps.
Growth Catalysts
- FDA Process Validation Guidelines:Mandated resin lot traceability for therapeutic antibody purification drives replacement demand and premium-grade procurement across GMP facilities.
- Single-Use Manufacturing:Pre-sterilized, disposable chromatography systems reduce cross-contamination risk and accelerate turnaround times in multi-product biologics plants.
- China Biosimilar Pipeline:NMPA's accelerated approval pathways for follow-on biologics expand downstream processing capacity requirements in Shanghai and Suzhou manufacturing clusters.
Market Restraints
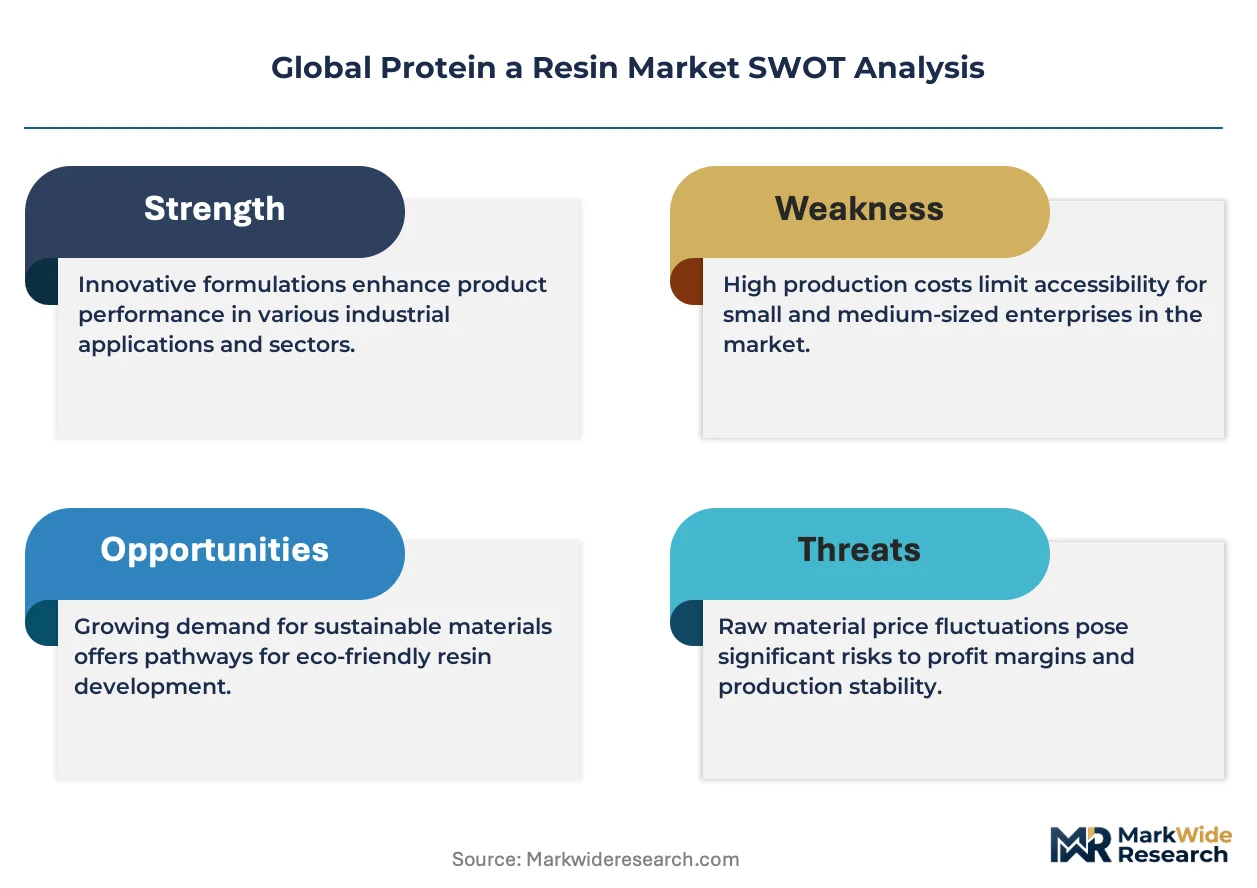
- Protein A Ligand Supply Concentration:Recombinant protein A production concentrates among specialized fermentation suppliers in Denmark and Japan, creating single-source vulnerability.
- Agarose Bead Cost Volatility:Cross-linked polysaccharide matrix materials fluctuate with marine harvest yields and purification-grade chemical input prices.
- EMA REACH Compliance Burden:Leachable substance characterization requirements extend supplier qualification timelines by 12-18 months for European biopharma operators.
Strategic Opportunities
- India Biologics Manufacturing:CDSCO's harmonization with ICH Q5A standards and PLI scheme incentives attract contract manufacturing investment requiring protein A resin infrastructure.
- Synthetic Polymer Matrices:Non-agarose alternatives offer improved alkaline stability and longer cycle lifetimes for continuous processing applications.
- EU Green Deal Alignment:Lower-carbon resin production methods and solvent recovery systems qualify for CSRD-linked procurement preferences among European biopharma sustainability officers.
Industry Challenges
- Chromatography Process Development Talent:Specialized expertise in resin screening, binding kinetics modeling, and scale-up validation remains scarce relative to biologics pipeline expansion.
- Legacy Batch System Integration:Retrofitting continuous capture steps into existing stainless-steel downstream trains requires significant capex and validation rework.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Protein a Resin Market |
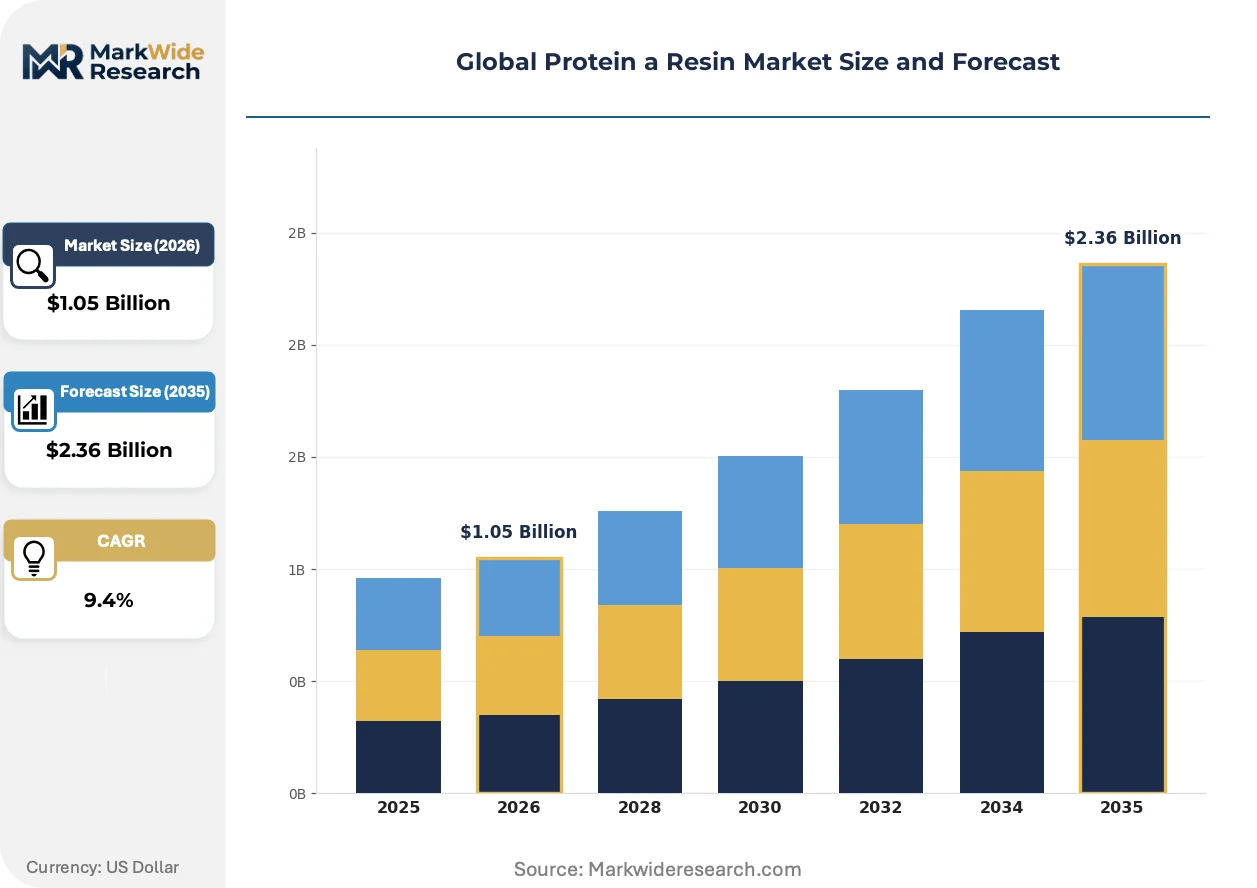
| Market Size in 2026 | $1.05 Billion |
| Market Size in 2035 | $2.36 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Casein, Gelatin, Soy Protein, Pea Protein Form: Powder, Granule, Liquid, Sheet End Use: Food & Beverage, Pharmaceuticals, Cosmetics, Nutraceuticals Distribution Channel: Online, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Danaher Corporation (Cytiva), Merck KGaA, Repligen Corporation, Thermo Fisher Scientific Inc., Tosoh Bioscience LLC, Bio-Rad Laboratories, Inc., Agilent Technologies, GenScript Biotech Corp., Ecolab (Purolite), Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Protein a Resin Market Shifts & Advancements
Resin engineering priorities are pivoting from static capacity metrics toward dynamic performance under continuous flow conditions. This shift redefines competitive differentiation around alkaline stability, pressure-flow characteristics, and regulatory documentation depth.
Multi-modal protein A ligand variants are integrating charged and hydrophobic interaction domains alongside traditional Fc binding sites. Contract development and manufacturing organizations in Germany and Switzerland are adopting these next-generation resins for bispecific antibody programs. The technology is integrating perfusion chromatography workflows by reducing step counts and buffer consumption in capture trains.
EMA's Medical Device Regulation and REACH framework revisions are tightening extractables and leachables testing protocols for chromatography resins used in parenteral biologics. Manufacturers must now submit comprehensive chemical characterization data spanning accelerated aging studies. European biopharma quality assurance departments are responding by consolidating supplier bases to those with dedicated regulatory affairs capabilities.
Biopharma procurement functions are unbundling resin supply from equipment service contracts, creating direct purchasing relationships with ligand developers. This disintermediation compresses pricing transparency and shifts technical support burdens toward resin suppliers. The pattern is most visible among mid-cap biotech firms in Massachusetts and California seeking to reduce total cost of ownership in early-phase manufacturing.
Global Protein a Resin Market Segmentation
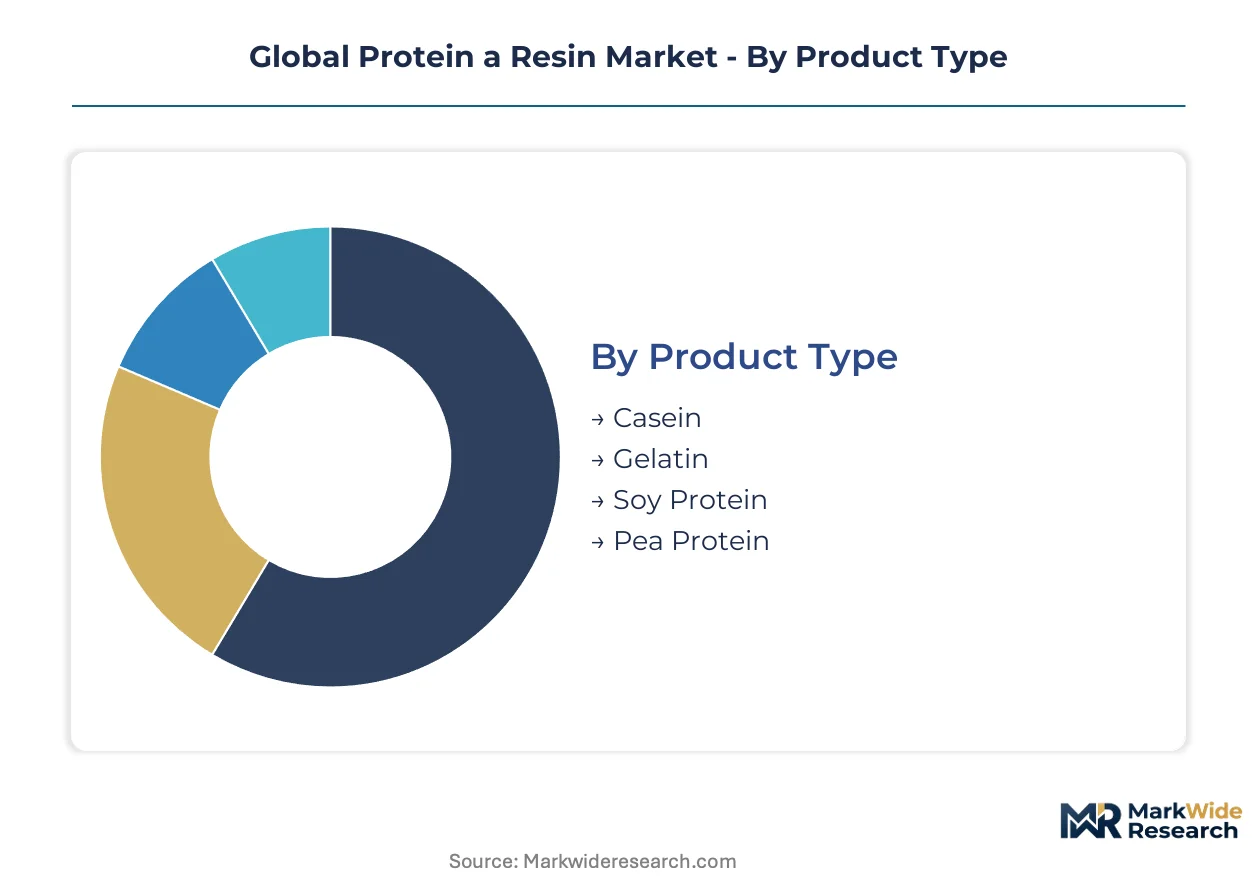
Protein A resin segmentation reveals how purification workflows fragment across product formats, physical configurations, and downstream customer requirements. Manufacturers configure supply chains differently for GMP biopharmaceutical clients versus research-grade purchasers, creating distinct margin pools within each segment cluster.
Product Type:
Native protein A variants dominate standalone capture applications, while recombinant engineered ligands embed into continuous processing systems with modified binding kinetics.
- Casein:Derived from bovine milk through acid precipitation and enzymatic treatment, this phosphoprotein matrix offers emulsification stability and slow-release amino acid profiles. Dairy processors in Wisconsin and Bavaria source casein for infant formula fortification where hypoallergenic properties command formulation premiums.
- Gelatin:Collagen hydrolysate extracted through acid or alkaline processing yields thermally reversible gelling behavior with bloom strength gradations from 50 to 300. Pharmaceutical capsule manufacturers in Gujarat and Hainan province specify type A gelatin for soft-shell applications requiring precise dissolution kinetics.
- Soy Protein:Isolate and concentrate grades from defatted soybean flakes serve meat analog applications with 90% protein content and neutral flavor profiles.
- Pea Protein:Yellow split pea isolate with 80-85% protein content addresses allergen-free positioning in plant-based beverage formulations.
Casein leads volumes today; pea protein is gaining share fastest.
Form:
Physical configuration determines handling automation compatibility and reconstitution protocols across batch versus continuous manufacturing architectures.
- Powder:Spray-dried or freeze-dried particulate with moisture content below 5% enables extended shelf stability and bulk pneumatic conveying. Biopharma facilities in Massachusetts and Basel integrate powder protein A resin into pre-packed chromatography columns where lot-to-lot consistency supports process validation requirements.
- Granule:Agglomerated particles with defined mesh sizes improve flow properties in high-shear mixing equipment. Nutraceutical contract manufacturers in Utah and Ontario specify granule formats for tablet compression where uniform particle distribution reduces weight variability.
- Liquid:Ready-to-use suspensions in buffered solutions eliminate hydration steps and support perfusion chromatography integration.
- Sheet:Cast film configurations for specialized coating and edible film applications in controlled-release delivery systems.
Powder dominates current procurement volumes; liquid formats are expanding most quickly in continuous bioprocessing adoption.
End Use:
Application-specific purity grades and documentation requirements create four distinct customer segments with divergent technical service needs.
- Food & Beverage:Protein fortification in sports nutrition and dairy alternatives drives volume procurement with emphasis on solubility and sensory neutrality. Formulation labs in California and São Paulo specify protein A resin companion products for beverage clarification where haze stability determines shelf appeal.
- Pharmaceuticals:Injectable-grade protein A resin with endotoxin specifications below 0.25 EU/mL supports monoclonal antibody purification under FDA process validation guidelines. Fill-finish operations in Singapore and Ireland require resin lot traceability spanning fermentation source to final chromatography pack.
- Cosmetics:Film-forming and moisture-binding properties in anti-aging formulations leverage hydrolyzed protein fractions.
- Nutraceuticals:Dietary supplement applications emphasize bioavailability claims and clean-label positioning in capsule and powder formats.
Pharmaceuticals commands the steepest expansion trajectory; food and beverage maintains the largest installed base.
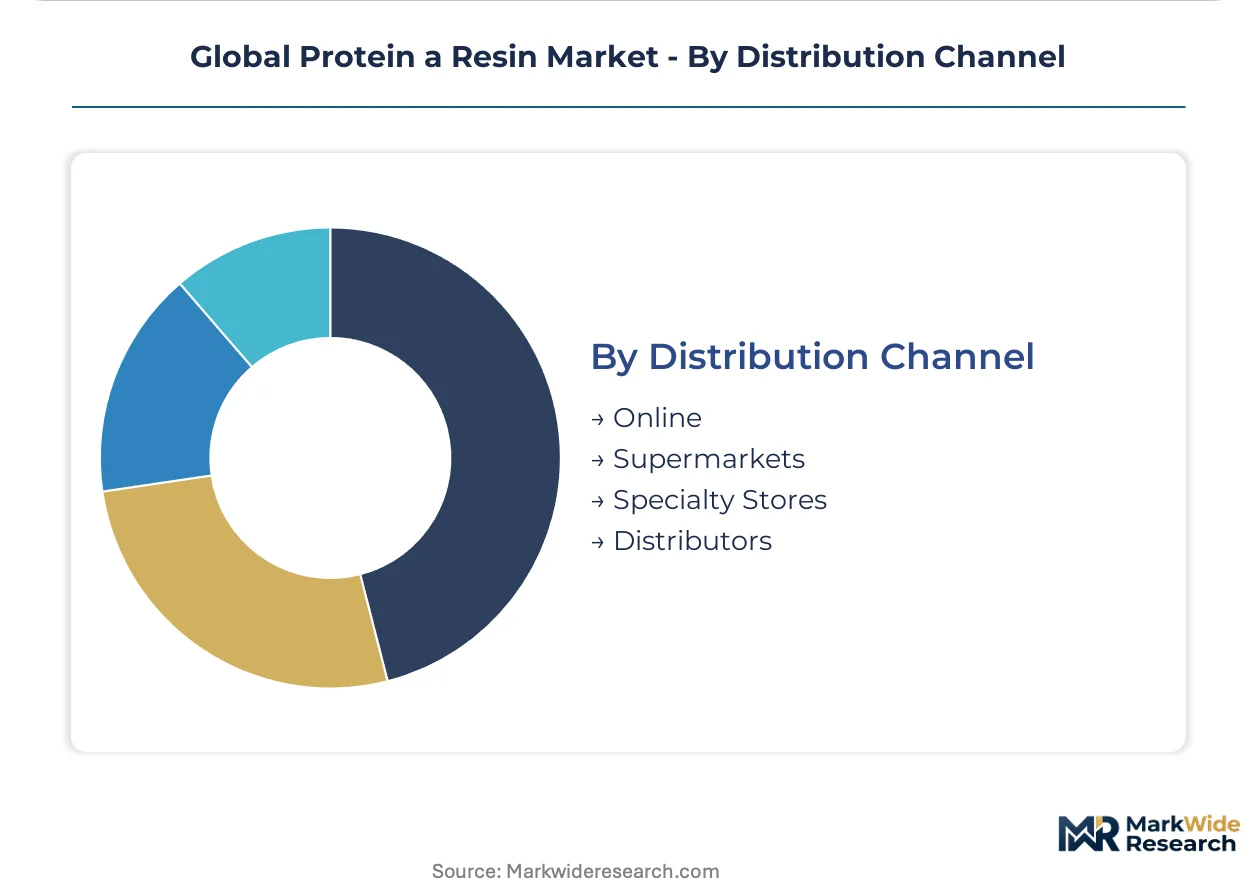
Distribution Channel:
Channel selection reflects purchase frequency, technical support requirements, and inventory carrying cost tolerance across customer segments.
- Online:E-procurement platforms with technical documentation repositories serve research-scale purchasers requiring rapid SKU comparison. Academic labs in Cambridge and Heidelberg source protein A resin through specialized bioprocessing marketplaces where certificate of analysis availability accelerates qualification timelines.
- Supermarkets:Mass-market protein powder and supplement retail in urban centers with private-label penetration.
- Specialty Stores:Nutrition and wellness-focused retailers with educated staff supporting sports nutrition selection.
- Distributors:Regional warehousing with local technical sales support for GMP biopharma accounts requiring just-in-time delivery and vendor-managed inventory programs.
Distributors lead transaction value today; online channels are climbing the fastest in research-grade segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Protein A resin manufacturing originated in Scandinavian fermentation science and Swiss chromatography engineering during the 1980s biotech revolution. The industry subsequently dispersed across North American biopharma corridors, German chemical processing zones, and East Asian biosimilar production clusters. Today, regulatory divergence and supply chain regionalization reshape procurement geography.
United States
Monoclonal antibody pipeline expansion in Massachusetts and California drives resin consumption for GMP manufacturing. FDA process validation guidelines mandate lot traceability and extractables documentation, extending supplier qualification timelines. The Greater Boston biotech corridor concentrates downstream processing infrastructure alongside specialized chromatography service providers.
Germany
Contract development and manufacturing organizations in Baden-Württemberg and Bavaria integrate protein A capture steps into continuous bioprocessing workflows. EMA's Medical Device Regulation and REACH framework impose leachable substance characterization requirements. The Rhine-Main manufacturing triangle anchors European biologics purification capacity with integrated resin-to-column supply chains.
China
NMPA's accelerated biosimilar approval pathways expand downstream processing demand in Shanghai and Suzhou biomanufacturing clusters. Domestic suppliers align with ICH Q5A viral safety standards while scaling recombinant protein A ligand production. The Yangtze River Delta concentrates perfusion chromatography adoption for continuous capture applications.
Switzerland
Specialized chromatography engineering firms around Basel engineer high-capacity ligand densities for perfusion-compatible systems. Swissmedic enforces stringent supplier qualification protocols for parenteral biologics manufacturing. The Basel-Zürich corridor hosts contract manufacturing organizations adopting multi-modal protein A variants for bispecific antibody programs.
India
CDSCO's harmonization with ICH Q5A standards and PLI scheme incentives attract contract manufacturing investment requiring protein A resin infrastructure. Domestic biologics manufacturers in Maharashtra and Telangana build downstream purification capacity. The Hyderabad-Bengaluru pharmaceutical corridor expands biosimilar production with imported resin supply chains.
Global Protein a Resin Market Competitive Landscape
Premium-margin players sit above commodity-margin players across documentation depth and regulatory affairs capabilities. The vendor base stratifies into three tiers: diversified life science conglomerates with chromatography platform dominance, specialized bioprocessing technology firms, and regional fermentation suppliers. Archetypes include integrated system providers, ligand specialists, and synthetic matrix innovators. Competitive moves concentrate on strategic partnerships for continuous processing integration and geographic expansion into Asian biosimilar manufacturing clusters.
Among diversified life science conglomerates, Danaher Corporation and Merck KGaA occupy positions anchoring premium capture segments through chromatography platform breadth. Repligen Corporation exemplifies the specialized bioprocessing technology archetype, complementing resin workflows with single-use ancillary systems. These three entities represent distinct strategic postures: diversified platform control, European supply anchoring, and continuous processing enablement respectively.
| Leading Market Players |
|---|
| Danaher Corporation (Cytiva) |
| Merck KGaA |
| Repligen Corporation |
| Thermo Fisher Scientific Inc. |
| Tosoh Bioscience LLC |
| Bio-Rad Laboratories, Inc. |
| Agilent Technologies |
| GenScript Biotech Corp. |
| Ecolab (Purolite) |
| Others |
Supply & Pricing Matrix
EU Green Deal carbon intensity thresholds gate qualified supply for European biopharma procurement teams, restricting premium-tier pricing access to resin suppliers with verified solvent recovery systems and lower-carbon fermentation footprints. Buyers in Germany and Switzerland now embed sustainability metrics into supplier scorecards, compressing margins for non-compliant producers while rewarding documented environmental performance with contract preference.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates GMP-validated pharmaceutical-grade resin from research-grade and bulk industrial formats. Price differentiation rests on FDA master file documentation depth and ICH Q7 compliance certification, with contract manufacturers in Massachusetts showing lowest sensitivity due to downstream biologics value capture. Cost compression in standard-tier powder formats intensifies as domestic Chinese suppliers scale recombinant protein A ligand production. Academic and early-stage biotech purchasers in California and Cambridge exhibit highest price elasticity, driving spot-market discounting for non-GMP inventory.
Supply Chain Analysis
Dual-sourcing mandates from FDA process validation guidelines force biopharma quality departments to qualify secondary suppliers for protein A ligand and agarose matrix inputs, extending procurement timelines. Geographic supply concentration centers on Denmark and Japan for recombinant protein A fermentation, Sweden for cross-linked agarose bead engineering, and China for synthetic polymer matrix alternatives. Raw material dependencies include marine-derived polysaccharides, fermentation-grade yeast extract, and chromatography-purity epichlorohydrin cross-linkers. Single-source vulnerability in Danish protein A ligand production creates concentration risk for global mAb purification capacity. Distribution runs through authorized distributors with regional warehousing in Basel, Singapore, and Shanghai for just-in-time GMP delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Protein A Resin Market compounds steadily as monoclonal antibody pipeline expansion across Massachusetts, California, and Shanghai manufacturing clusters sustains replacement demand and capacity addition requirements.
For Market Incumbents: Acquire synthetic polymer matrix technology capabilities to offset agarose cost volatility and position for continuous bioprocessing adoption. Consolidate regulatory affairs documentation depth against emerging Chinese suppliers by investing in FDA master file expansions for multi-modal ligand variants. Backward integration into recombinant protein A fermentation in Denmark or Japan reduces single-source exposure from specialized fermentation houses. For New Entrants and Emerging Players: CDSCO harmonization with ICH Q5A standards in India opens a window for resin qualification programs targeting Maharashtra and Telangana contract manufacturing investment. Target perfusion-compatible liquid format resin for continuous capture steps in Suzhou and Shanghai biomanufacturing clusters where domestic supply gaps persist. Partner with German CDMOs for co-development validation to accelerate European market access without standalone regulatory infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for specialized bioprocessing technology firms because fragmented ligand engineering and synthetic matrix development creates multiple sub-scale assets with complementary IP positions. Focus on five-to-ten year viability windows anchored by biosimilar manufacturing regionalization and continuous processing retrofit cycles. Signal to watch: NMPA domestic supplier preference policies shifting procurement share toward China-qualified resin producers.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Master File Expansion | FDA documentation depth accelerates GMP supplier qualification timelines for mAb manufacturers. |
| Synthetic Matrix Technology Acquisition | Alkaline-stable polymer alternatives extend cycle lifetimes in continuous perfusion chromatography systems. |
| Dual-Sourcing Partnership | Secondary supplier qualification mitigates concentration risk in Danish protein A ligand production. |
| Continuous Processing Format Development | Liquid resin suspensions integrate with perfusion workflows reducing buffer consumption in capture trains. |
| Sustainability Certification Program | EU Green Deal alignment qualifies suppliers for CSRD-linked procurement preferences among European biopharma. |
Research Methodology
Multiple input streams — technical discussions with downstream processing engineers, regulatory affairs directors at biopharma manufacturers, chromatography platform specialists, and procurement leads at CDMOs — were reconciled against secondary validation from FDA master file databases, EMA qualification records, NMPA biosimilar approval filings, and trade data on chromatography resin imports. Bottom-up capacity modeling across Shanghai, Suzhou, Massachusetts, and Basel manufacturing clusters was cross-checked against top-down biologics pipeline forecasts.
Historical capacity utilization patterns were cross-referenced against expert panel assessments of continuous bioprocessing adoption rates. Segmentation modeling spanned product format, physical configuration, end-use purity grade, and regional regulatory cluster. CAGRs were derived from demand elasticity analysis against mAb approval trajectories and biosimilar penetration curves. Forecast inputs included perfusion chromatography adoption timelines, synthetic matrix substitution rates, and supplier qualification backlog durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory divergence between FDA and NMPA validation requirements or sustained agarose harvest disruptions. Deviation in Chinese domestic supplier preference policies would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Cyclic Olefin Copolymers Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Polyethylene Terephthalate (PET) Foam Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Thermoplastic Polyimide Market
Polymers & Resins
Super Absorbent Polymer Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Molding and Trim Materials Market
Polymers & Resins
APAC Polyethylene Terephthalate Market
Polymers & Resins
Thermoplastic Polyolefin Market
Polymers & Resins
Novolac Resins Market
Polymers & Resins
Poly (Butylene Adipate-Co-Terephthalate) Market
Polymers & Resins
Synthetic and Bio Thermosets Market
Polymers & Resins
Indonesia Polypropylene Market
Polymers & Resins
Global Unsaturated Polyester Resins Market
Polymers & Resins
Styrenics Market