
 Global Pelvic Floor Electric Stimulator Market | 2026-2036
Global Pelvic Floor Electric Stimulator Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pelvic Floor Electric Stimulator Market Foresight
Capital-intensity divergence between R&D-heavy manufacturers and assembly-focused competitors is redrawing competitive boundaries in pelvic floor stimulation. Laborie Medical Technologies leverages its clinical systems portfolio to dominate hospital procurement channels. TensCare Ltd anchors its position through portable unit specialization for home care segments. Zynex Inc competes by extending direct-to-patient distribution across North American physiotherapy networks.
A pelvic floor electric stimulator delivers controlled electrical impulses to pelvic musculature through transcutaneous or implantable electrodes, typically operating at frequencies between 2-100 Hz with pulse widths of 50-400 microseconds to induce neuromuscular contraction or pain modulation. These devices serve primarily to restore continence function, reduce chronic pelvic pain, and accelerate post-surgical rehabilitation in clinical and home settings. Portable units are capturing expanding margin pools as home care patients shift from clinic-dependent protocols, while implantable devices remain concentrated among high-acuity cases due to surgical overhead and regulatory burden. Neuromuscular electrical stimulation technology leads volume across gynecology clinics, whereas biofeedback-integrated systems command premium positioning in physiotherapy clinics seeking measurable patient outcomes.
The FDA's 510(k) pathway for electrical stimulation devices shapes product development timelines and clinical trial investment for US market entrants, while the EU MDR and CE marking requirements under EMA oversight are elevating documentation burdens for European commercialization. Japan's PMDA maintains distinct technical standards for implantable stimulators that create additional compliance layers for multinational manufacturers. Stakeholders must monitor reimbursement coding evolution in Germany and the United States, where coverage determinations will decisively shape home care versus clinical system deployment economics.
Market Dynamics
EU MDR clinical evidence requirements are compressing product development timelines for electrical stimulation devices while simultaneously elevating barriers for new entrants without established regulatory infrastructure.
Growth Catalysts
- Postpartum rehabilitation protocols:Gynecology clinics across Germany and the United States are embedding pelvic floor stimulators into standardized recovery pathways, creating institutional demand pull.
- CE marking pathway evolution:The EU MDR's tightened documentation standards favor manufacturers with existing technical files, accelerating consolidation among compliant device producers.
- Neuromuscular electrical stimulation:Frequency-modulation advances in the 2-100 Hz range are expanding treatable patient populations beyond stress incontinence into mixed and urge subtypes.
Market Restraints
- Implantable device surgical overhead:Operating room requirements and specialist surgeon availability constrain high-acuity segment penetration to tertiary medical centers.
- Electrode supply concentration:Medical-grade conductive polymer production clusters in Germany and Switzerland, creating single-source vulnerability for transcutaneous device manufacturers.
- Biofeedback integration complexity:Real-time pressure-sensor calibration demands specialized technical support that home care channels struggle to provision profitably.
Strategic Opportunities
- Direct-to-patient distribution:North American physiotherapy networks are experimenting with subscription-based home device programs, bypassing traditional durable medical equipment channels.
- Japan's PMDA technical standards:Distinct implantable stimulator requirements create first-mover advantage for manufacturers willing to invest in parallel compliance infrastructure.
- Portable-biofeedback convergence:Smartphone-integrated pressure monitoring is opening premium positioning in post-surgical rehabilitation segments previously served only by clinic-based systems.
Industry Challenges
- Clinical evidence generation timelines:The EU MDR's expanded patient follow-up requirements for electrical stimulation devices extend pre-market authorization cycles by 18-24 months.
- Reimbursement coding fragmentation:Germany's well-established pelvic health pathways contrast with patchy US coverage determinations, forcing manufacturers to maintain dual commercialization playbooks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pelvic Floor Electric Stimulator Market |
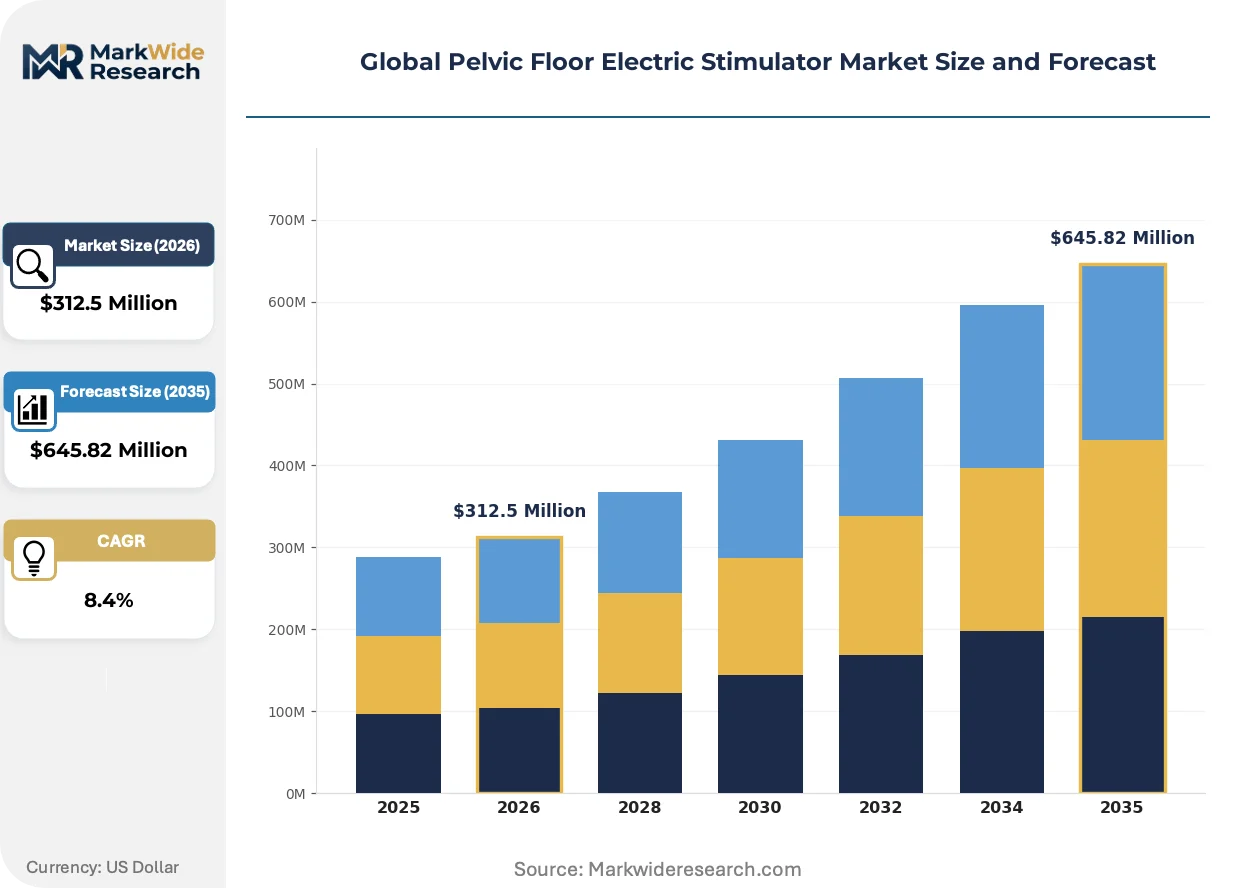
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Stimulators, Implantable Devices, Portable Units, Clinical Systems Application: Urinary Incontinence, Pelvic Organ Prolapse, Chronic Pelvic Pain, Postpartum Recovery, Sexual Dysfunction End User: Gynecology Clinics, Urology Centers, Rehabilitation Facilities, Home Care Patients, Physiotherapy Clinics Technology: Transcutaneous Electrical Nerve Stimulation, Neuromuscular Electrical Stimulation, Interferential Therapy, Biofeedback Devices |
| Companies Covered | Atlantic Therapeutics, Laborie Medical Technologies, InControl Medical, TensCare Ltd, Verity Medical Ltd, Zynex Inc, Everyway Medical Instruments Co., Ltd., The Prometheus Group, BTL Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pelvic Floor Electric Stimulator Market Shifts & Advancements
Device miniaturization and sensor integration are compressing the boundary between clinical-grade and consumer-grade pelvic floor systems, forcing incumbents to defend premium positioning against agile home care entrants.
Wireless electrode arrays with embedded impedance sensing are fragmenting traditional product categories by enabling real-time tissue response monitoring without tethered console architecture. Physiotherapy clinics in Germany and the United Kingdom are piloting these systems for remote patient monitoring, collapsing the distinction between in-clinic and home-based treatment protocols. This capability compression threatens standalone biofeedback device margins while opening software-as-a-service revenue streams.
The EU MDR's post-market surveillance requirements are extending clinical obligation periods for electrical stimulation manufacturers, forcing sustained investment in real-world evidence collection infrastructure. Device producers must now maintain active implant registries and periodic safety update reports that were previously voluntary. German notified bodies are applying these standards most stringently, creating competitive differentiation for manufacturers with established European regulatory affairs capabilities.
Patient acquisition through telehealth platforms is displacing traditional physician-referral pathways for home care stimulator segments. Direct-to-consumer channels in the United States are capturing growing volume by bundling device provision with virtual pelvic floor therapy sessions, bypassing the durable medical equipment reimbursement maze. This channel shift concentrates marketing spend on digital patient education rather than clinical sales force deployment, favoring brands with established direct-response capabilities.
Global Pelvic Floor Electric Stimulator Market Segmentation
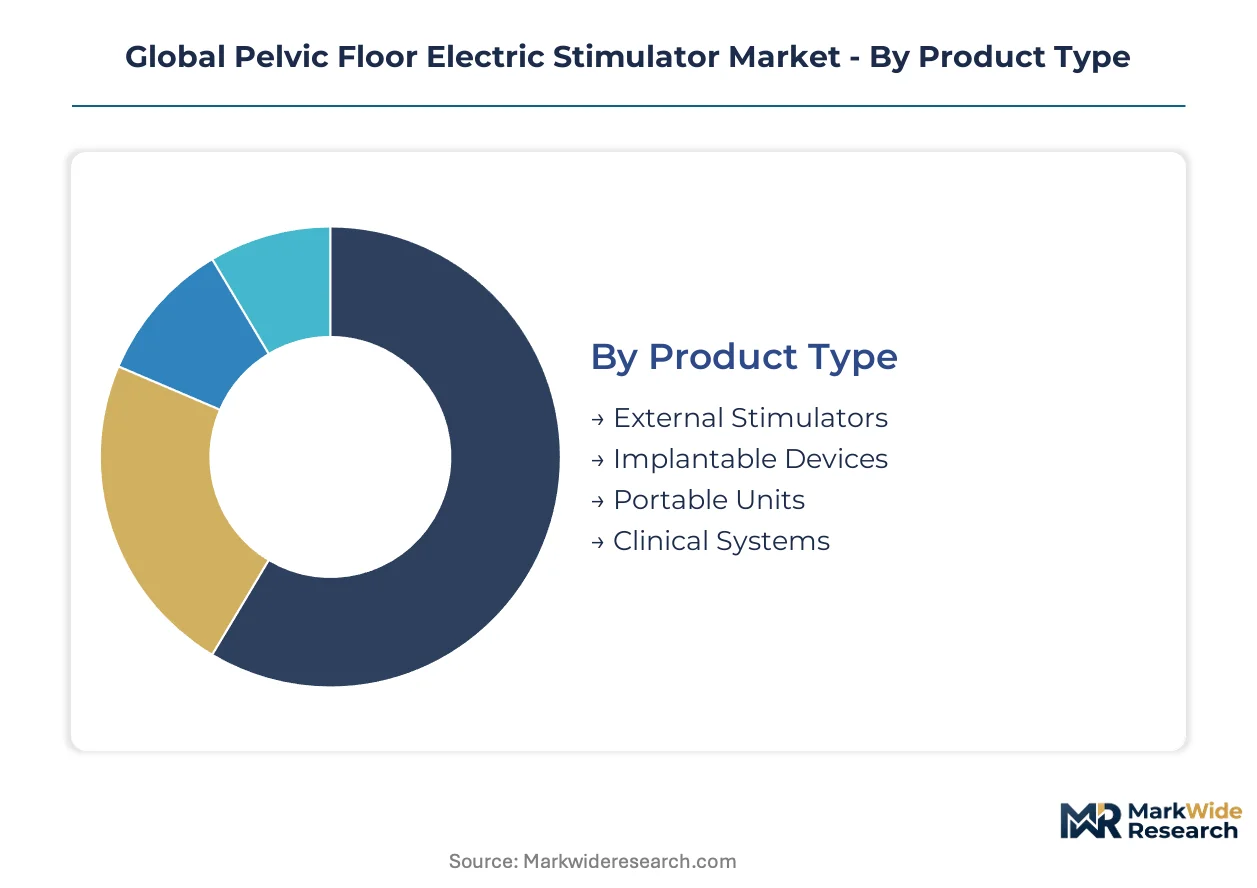
Pelvic floor electric stimulator procurement patterns diverge sharply across clinical and home settings, with reimbursement pathways and device portability driving category-specific demand concentration. Manufacturers must align technical specifications and distribution strategies to distinct end-user workflows rather than pursuing undifferentiated market coverage.
Product Type:
External stimulators dominate domestic consumption in Germany and the United States, while implantable devices travel through specialized export channels to tertiary medical centers in Japan and Switzerland.
- External Stimulators:Console-based systems deliver controlled electrical impulses through surface electrodes at 2-100 Hz frequencies. German gynecology clinics embed these into postpartum recovery protocols, creating institutional procurement pull for multi-channel hospital-grade units.
- Portable Units:Battery-operated devices enable patient-managed therapy outside clinical settings. Home care demand concentrates in North American physiotherapy networks, where direct-to-patient distribution models bypass traditional durable medical equipment channels.
- Implantable Devices:Surgically placed pulse generators serve high-acuity incontinence cases requiring continuous stimulation.
- Clinical Systems:Multi-modality platforms integrate electrical stimulation with biofeedback capabilities for comprehensive pelvic rehabilitation.
External stimulators hold the largest share; momentum sits with portable units.
Application:
Cost tier stratification separates premium implantable solutions for refractory cases from economy external devices for first-line therapy.
- Urinary Incontinence:Stress, urge, and mixed subtypes drive the majority of device prescriptions. German reimbursement pathways cover neuromuscular electrical stimulation for documented incontinence severity, accelerating clinical adoption.
- Postpartum Recovery:Protocol standardization across gynecology clinics creates predictable demand cycles tied to birth rates. United States health systems increasingly bundle pelvic floor therapy into maternity care packages.
- Chronic Pelvic Pain:Transcutaneous electrical nerve stimulation at lower frequencies modulates pain signaling without muscular contraction.
- Pelvic Organ Prolapse:Pre- and post-surgical rehabilitation protocols employ electrical stimulation to maintain muscular support.
- Sexual Dysfunction:Emerging application with limited established reimbursement coding.
Urinary incontinence commands the dominant revenue position; postpartum recovery is expanding most quickly.
End User:
Volume concentration favors institutional procurement channels, though patient acquisition through telehealth platforms is displacing traditional physician-referral pathways.
- Gynecology Clinics:Primary site for postpartum and female-specific pelvic floor disorders. German clinics lead European adoption through established pelvic health reimbursement infrastructure.
- Home Care Patients:Direct-to-consumer channels in the United States bundle device provision with virtual therapy sessions. Digital patient education replaces clinical sales force deployment in this segment.
- Urology Centers:Male pelvic floor dysfunction and post-prostatectomy incontinence drive specialized demand.
- Physiotherapy Clinics:Biofeedback-integrated systems command premium positioning through measurable outcome documentation.
- Rehabilitation Facilities:Post-surgical recovery protocols for oncology and trauma patients.
Gynecology clinics anchor institutional volume; home care patients are gaining share fastest.
Technology:
Supply concentration in electrode manufacturing clusters shapes technology adoption patterns, with German and Swiss conductive polymer production favoring transcutaneous approaches.
- Neuromuscular Electrical Stimulation:Frequency-modulated contraction induction at 2-100 Hz restores muscular function. Gynecology clinics deploy this technology across urinary incontinence subtypes beyond traditional stress incontinence boundaries.
- Biofeedback Devices:Real-time pressure-sensor integration enables patient-directed muscular training. Physiotherapy clinics in Germany and the United Kingdom pilot smartphone-integrated systems for remote monitoring.
- Transcutaneous Electrical Nerve Stimulation:Surface electrode delivery for pain modulation without muscular contraction.
- Interferential Therapy:Medium-frequency carrier waves penetrate deeper tissues for pain management applications.
Neuromuscular electrical stimulation leads volume; biofeedback devices follow the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys pelvic floor stimulators primarily through institutional reimbursement pathways, while the United States channels growing volume through direct-to-patient home care models that bypass traditional clinical procurement.
United States
Direct-to-consumer telehealth platforms bundle device provision with virtual pelvic floor therapy sessions, displacing physician-referral pathways. The FDA's 510(k) pathway shapes product development timelines for electrical stimulation devices. Digital patient education concentrates marketing spend in California and New York Metro health technology corridors.
Germany
Gynecology clinics embed external stimulators into standardized postpartum recovery protocols through established pelvic health reimbursement infrastructure. The EU MDR elevates documentation burdens for CE marking, with German notified bodies applying standards most stringently. Medical-grade conductive polymer production clusters in Baden-Württemberg supply electrode components across European device manufacturers.
Japan
PMDA maintains distinct technical standards for implantable stimulators that create additional compliance layers for multinational manufacturers. METI oversees medical device commercialization frameworks that favor domestic-foreign joint ventures. Tokyo and Osaka medical centers concentrate high-acuity surgical implantation capacity for refractory incontinence cases.
United Kingdom
Physiotherapy clinics pilot smartphone-integrated biofeedback systems for remote patient monitoring, collapsing distinctions between in-clinic and home-based protocols. The MHRA operates post-Brexit regulatory alignment with EU MDR requirements. London and Southeast England health technology clusters drive portable-biofeedback convergence development.
Switzerland
Swissmedic oversees medical device authorization with emphasis on post-market surveillance for electrical stimulation products. Tertiary medical centers in Zurich and Geneva concentrate implantable device surgical expertise for high-acuity pelvic floor dysfunction. Swiss conductive polymer manufacturing supplies electrode arrays to transcutaneous device producers across German-speaking Europe.
Global Pelvic Floor Electric Stimulator Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hospital procurement channel dominance separating scale players from home care-focused competitors. The competitive terrain stratifies between R&D-intensive manufacturers pursuing multi-modality clinical systems and assembly-focused competitors optimizing portable unit economics. Two dominant competitive moves are reshaping positioning: direct-to-patient distribution experiments in North American physiotherapy networks, and regulatory infrastructure investments to secure EU MDR compliance ahead of smaller rivals.
Among clinically integrated manufacturers, Laborie Medical Technologies and The Prometheus Group exemplify the hospital systems tier, anchoring procurement relationships through multi-channel platform offerings. TensCare Ltd occupies a position within the portable specialization archetype, representing home care segment focus. Zynex Inc sits within the direct-distribution vector, exemplifying North American physiotherapy network penetration strategies.
| Leading Market Players |
|---|
| Atlantic Therapeutics |
| Laborie Medical Technologies |
| InControl Medical |
| TensCare Ltd |
| Verity Medical Ltd |
| Zynex Inc |
| Everyway Medical Instruments Co., Ltd. |
| The Prometheus Group |
| BTL Industries |
| Others |
Supply & Pricing Matrix
Electrode manufacturing scale economies in Baden-Württemberg and Swiss polymer clusters concentrate component supply among three dominant producers, compressing price floors for transcutaneous device assemblers while elevating margin capture for conductive material specialists. This concentration cascades through distribution tiers, with hospital procurement channels absorbing premium markups and direct-to-patient platforms forcing cost transparency in home care segments.
Pricing Analysis
After-sales consumables and electrode replacement contracts drive lifetime value capture for external stimulator manufacturers. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared clinical systems from CE-marked home units and unregistered direct-import alternatives. Pricing pressure stems from telehealth platforms disintermediating traditional durable medical equipment channels, compressing distributor margins by fifteen to twenty points. Home care patients exhibit highest price sensitivity, while German gynecology clinics prioritize reimbursement alignment over unit cost.
Supply Chain Analysis
Medical-grade conductive polymer production clusters in Germany, Switzerland, and Japan create single-source vulnerability for transcutaneous electrode arrays. Device assembly draws from Taiwanese PCB fabrication, South Korean battery cell supply, and German sensor module production. Tariff exposure on Chinese-sourced electronic components threatens margin stability for portable unit specialists. Distribution runs through hospital GPO contracts in institutional segments and direct-response logistics in home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity concentrates in postpartum recovery protocol standardization, where gynecology clinic procurement patterns diverge sharply from telehealth-acquired home care demand. This demand-side shift creates distinct competitive arenas with divergent success requirements.
For Market Incumbents: Fortify regulatory infrastructure ahead of EU MDR post-market surveillance expansions, extending clinical obligation periods that smaller rivals cannot sustain. Deepen backward integration into electrode manufacturing to neutralize Baden-Württemberg supply concentration risk. Prioritize hospital GPO contract renewals as direct-to-patient channels erode traditional procurement relationships.
For New Entrants and Emerging Players: Anchor in smartphone-integrated biofeedback convergence, where physiotherapy clinic pilot programs in the United Kingdom and Germany validate remote monitoring architectures. Target post-surgical rehabilitation segments previously served only by clinic-based systems. Pursue subscription-based home device programs that bundle hardware provision with virtual pelvic floor therapy sessions.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among portable-biofeedback convergent specialists with established direct-to-patient distribution. Long-term viability favors manufacturers with parallel FDA and EU MDR compliance infrastructure already operational. Monitor reimbursement coding evolution in the United States as inflection indicator for home care segment economics.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Compliance Infrastructure | Post-market surveillance requirements extend clinical obligation periods beyond smaller rival capacity. |
| Direct-to-Patient Distribution | Telehealth platforms in California and New York Metro bypass durable medical equipment reimbursement complexity. |
| Electrode Manufacturing Integration | Captive supply of conductive polymer components neutralizes German-Swiss production cluster vulnerability. |
| Smartphone-Biofeedback Convergence | Remote patient monitoring collapses distinctions between in-clinic and home-based treatment protocols. |
| Reimbursement Strategy Investment | German pelvic health pathway alignment secures institutional procurement volume against price-sensitive alternatives. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation, hospital procurement databases, and GPO contract disclosures. Clinicians, hospital purchasing committees, biomedical engineers, and regulatory affairs leads at notified bodies provided qualitative input. Bottom-up demand modeling triangulates against top-down market sizing from customs records and medical device trade flow analysis.
Segmentation dimensions modeled include product type hierarchy, application severity tier, end-user channel structure, and technology modality across the projection horizon. CAGRs derive from installed base growth rates, replacement cycle compression, and penetration assumptions by reimbursement status. Forecast inputs incorporate birth rate trajectories for postpartum segments and prostatectomy volume projections for urology center demand.
Decision-makers should treat outputs as directional under stable regulatory enforcement and reimbursement coding continuity; material deviation in FDA clearance timelines or German pelvic health pathway revision would warrant model refresh. Practitioners should keep alternative scenarios live as EU MDR notified body capacity constraints and telehealth platform regulatory classification evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vortex Mixer Market
Medical Devices
Global Mobile C-Arm Market
Medical Devices
Global Syringe Pumps Market
Medical Devices
Vaginal Specula Market
Medical Devices
Next Generation Blood Gas Monitors System Market
Medical Devices
At-Home Blood Collection Kits and Devices Market
Medical Devices
UK Surgical Devices Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Europe Ventilator Market
Medical Devices
Global Anesthesia Gas Blender Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Needle-Free Drug Delivery Devices Market
Medical Devices
Europe Ultrasound Devices Market
Medical Devices
Global Ureteral Stent Market
Medical Devices
Global Surgical Polypropylene Mesh Market