
 Adsorption Apheresis Devices Market | 2026-2036
Adsorption Apheresis Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Adsorption Apheresis Devices Market Analytics
The premium-commodity split in adsorption apheresis is restructuring around membrane biocompatibility grades and automation depth. Fresenius SE & Co. KGaA leverages its integrated dialysis-apheresis platform to dominate European hospital procurement. Haemonetics Corporation anchors North American supply through specialized disposables and service networks. Asahi Kasei Medical Co., Ltd. competes on hollow-fiber membrane precision for sepsis and autoimmune protocols.
Adsorption apheresis devices selectively remove pathogenic substances from blood or plasma using adsorbent columns, membrane separators, or combined filtration systems operating at controlled flow rates and anticoagulation parameters. Their primary purpose centers on treating autoimmune disorders, transplant rejection, and sepsis by extracting specific antibodies, cytokines, or lipoproteins without depleting essential blood components. Plasmapheresis devices lead installed base volumes due to decades of clinical validation in neurological and renal indications, while hemoadsorption systems represent the fastest-expanding category as intensivists adopt cytokine-adsorption protocols for septic shock. Continuous flow technology sustains premium pricing through reduced treatment duration and improved patient throughput in high-volume hospital settings.
FDA 510(k) pathways and EU MDR conformity requirements shape device approval timelines and clinical evidence burdens for manufacturers entering either market. Japan's PMDA enforces stringent post-market surveillance for blood purification devices, elevating compliance costs while rewarding established domestic suppliers. Stakeholders must weigh regulatory capital requirements against the margin premium commanded by next-generation adsorption columns and software-integrated therapeutic platforms.
Market Dynamics
Adsorption apheresis device manufacturers face intensifying pressure from Japan's PMDA post-market surveillance mandates, which compress product development cycles while elevating compliance capital requirements across hollow-fiber membrane and adsorbent column portfolios.
Growth Catalysts
- Sepsis Protocol Expansion:Intensive care units in tertiary hospitals are integrating cytokine-adsorption columns into septic shock treatment pathways, creating pull-through demand for integrated hemoadsorption systems.
- METI Domestic Manufacturing Incentives:Japan's Ministry of Economy, Trade and Industry subsidizes local production of blood purification devices, strengthening indigenous supply chains for hollow-fiber membrane fabrication.
- FDA 510(k) Streamlining:The FDA's evolving guidance on blood purification device safety is accelerating biocompatibility testing standardization, reducing time-to-market for next-generation adsorption columns.
Market Restraints
- Adsorbent Material Cost Volatility:Synthetic polymer resins and activated carbon matrices face price instability from petrochemical feedstock fluctuations, compressing gross margins on disposable columns.
- European Supply Concentration:Germany and Switzerland dominate precision membrane extrusion equipment, creating bottleneck risk for manufacturers outside this cluster seeking EU MDR certification.
- Technical Limitation in Selectivity:Current adsorbent chemistries exhibit incomplete specificity for target cytokines versus essential plasma proteins, limiting clinical efficacy in complex autoimmune protocols.
Strategic Opportunities
- Underpenetrated Indian Market:India's CDSCO regulatory pathway for blood purification devices remains less stringent than Japan or the US, offering first-mover positioning for automated plasmapheresis platforms in emerging transplant centers.
- Software-Integrated Therapeutic Platforms:Convergence of real-time biomarker monitoring with adsorption flow control enables closed-loop therapy adjustment, differentiating premium device tiers.
- Home-Based Chronic Care:Ambulatory apheresis protocols for familial hypercholesterolemia create channel innovation toward specialized home infusion services, bypassing traditional hospital procurement.
Industry Challenges
- Biocompatibility Certification Timeline:ISO 10993 testing protocols for novel membrane materials extend development cycles by 18-24 months, delaying revenue recognition on R&D investments.
- Perfusionist Training Scarcity:Specialized operators capable of managing continuous-flow anticoagulation parameters remain concentrated in academic medical centers, constraining treatment capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adsorption Apheresis Devices Market |
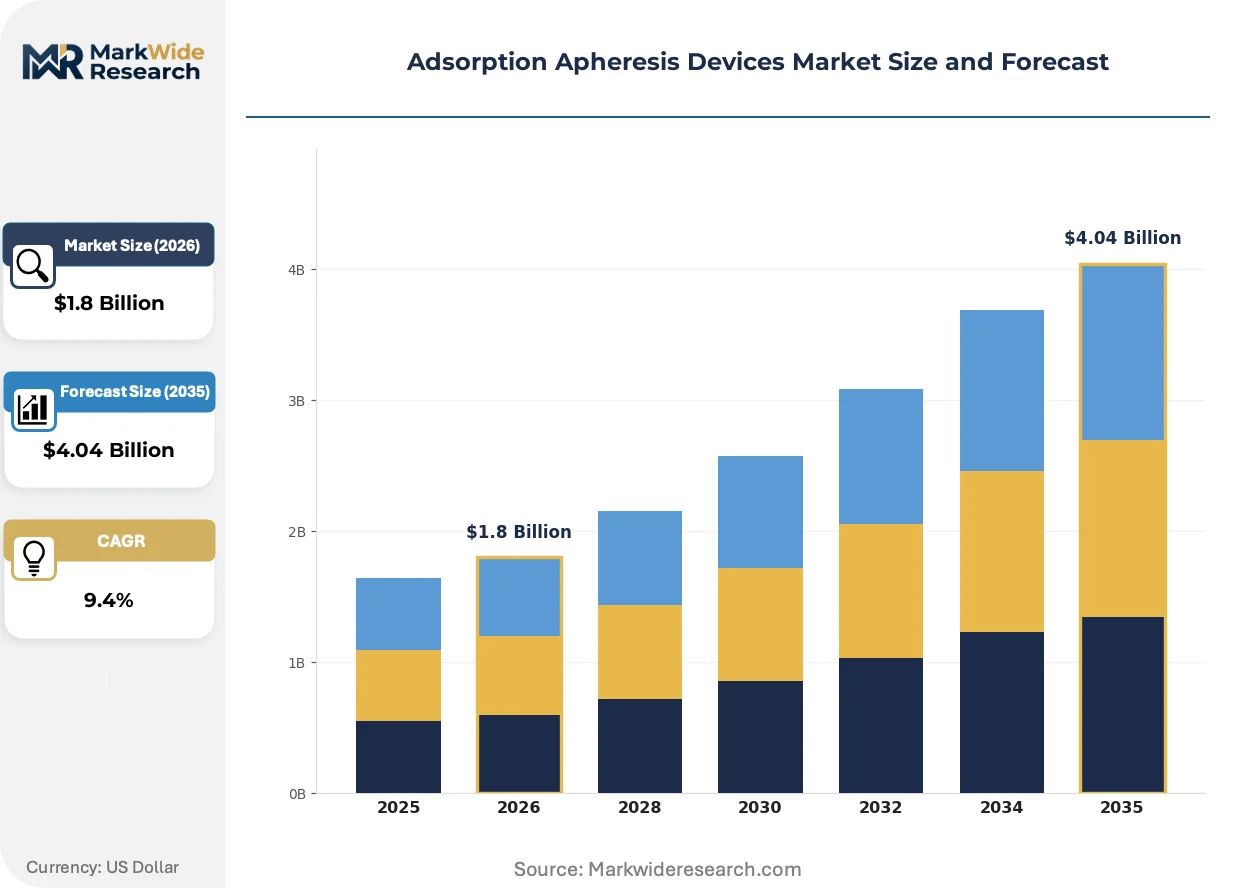
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Plasmapheresis Devices, Hemoadsorption Systems, Therapeutic Apheresis Machines, Blood Purification Units Application: Autoimmune Disorders, Organ Transplantation, Hyperlipidemia, Sepsis Treatment End User: Hospitals, Clinics, Blood Banks, Research Laboratories Technology: Continuous Flow Technology, Batch Processing, Membrane Separation, Filtration Techniques |
| Companies Covered | Fresenius SE & Co. KGaA, Haemonetics Corporation, Terumo Corporation, Asahi Kasei Medical Co., Ltd., B. Braun SE, Cerus Corporation, Baxter International Inc., Nikkiso Co., Ltd., Kaneka Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adsorption Apheresis Devices Market Evolving Landscape
Device architecture is fragmenting into interchangeable column-cartridge systems that separate the durable control unit from disposable treatment modules, enabling indication-specific customization without full platform replacement.
Polymethyl methacrylate hollow-fiber membranes with gradient pore density are modularizing the separation stage from adsorption columns, allowing hospitals to source membrane separators and adsorbent units from different suppliers while maintaining closed-loop sterility. Academic medical centers in Germany and Japan are piloting this architecture for simultaneous plasma separation and cytokine removal. The decoupling is compressing capital expenditure per treatment indication while expanding addressable procedure volumes.
The EU MDR's heightened clinical evidence requirements for Class III blood purification devices are extending conformity assessment timelines, forcing manufacturers to front-load pivotal studies before notified body submission. Small and mid-cap device firms without legacy clinical databases are exiting the European market, consolidating procurement options around established suppliers with pre-2021 MDD-certified portfolios. Swiss and German notified bodies report 40% longer review queues for novel adsorption column submissions compared to 2019 baselines.
Hospital procurement departments are unbundling after-sales service contracts from device acquisition, sourcing preventive maintenance and disposable replenishment through third-party logistics providers rather than original equipment manufacturers. This disintermediation is most pronounced in United States health systems with centralized supply chain operations, where GPO-negotiated service agreements now cover multi-vendor apheresis fleets. The shift compresses manufacturer service margins while elevating price transparency on replacement column pricing.
Adsorption Apheresis Devices Market Segmentation
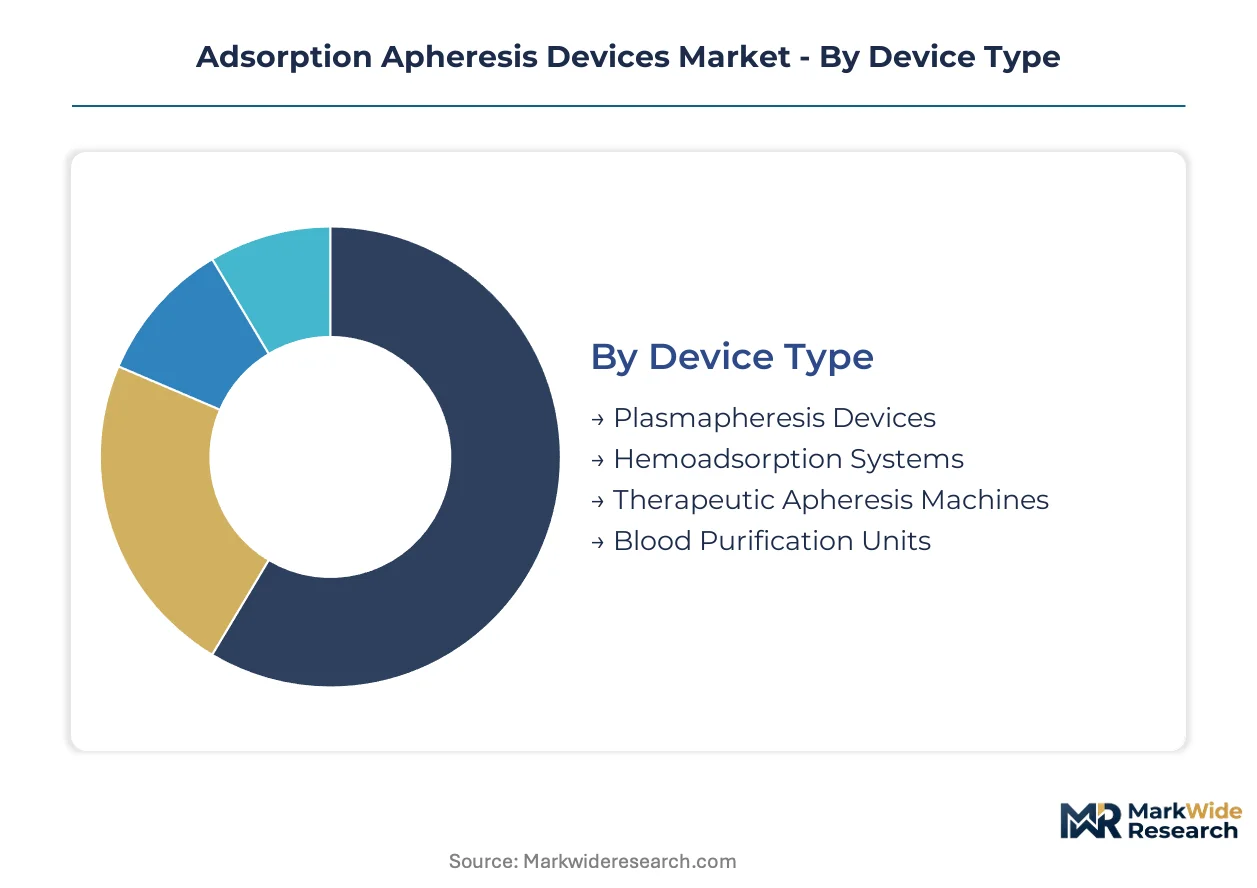
Device architecture in adsorption apheresis fragments across treatment modality, clinical indication, and care setting. Procurement patterns diverge sharply between high-volume hospital systems and specialized transplant centers, reshaping how manufacturers configure platform specifications and service contracts.
Device Type:
Volume concentration sits with established plasmapheresis platforms, while premium expansion flows toward next-generation hemoadsorption systems with integrated biomarker feedback.
- Plasmapheresis Devices:These systems separate plasma from whole blood through centrifugation or membrane filtration, returning cellular components to the patient. Demand concentrates in United States academic medical centers managing Guillain-Barré syndrome and myasthenia gravis protocols, where decades of clinical validation sustain installed base loyalty despite longer treatment durations.
- Hemoadsorption Systems:Cytokine-adsorption columns target circulating inflammatory mediators in septic shock and systemic inflammation. German and Japanese intensive care units are expanding adoption fastest, driven by intensivist demand for adjunctive therapies that modulate hyperinflammatory response without hemodialysis infrastructure.
- Therapeutic Apheresis Machines:Multi-modality platforms support plasma exchange, red cell exchange, and leukapheresis through interchangeable kits.
- Blood Purification Units:Integrated systems combining separation and adsorption stages for complex autoimmune protocols.
Today's leader: Plasmapheresis Devices. Tomorrow's challenger: Hemoadsorption Systems.
Application:
Clinical indication shapes device specification more than any other variable, with sepsis protocols demanding real-time flow modulation that autoimmune treatments rarely require.
- Sepsis Treatment:Cytokine-adsorption protocols in septic shock require hemoadsorption columns with high surface-area polymethyl methacrylate membranes. Japanese tertiary hospitals lead procedure volume, supported by METI-funded domestic manufacturing and PMDA post-market surveillance frameworks that accelerate clinical evidence accumulation.
- Autoimmune Disorders:Plasma exchange for neuromyelitis optica, ANCA-associated vasculitis, and catastrophic antiphospholipid syndrome relies on membrane-based separation with albumin replacement. United States hospital systems dominate volumes through expanding therapeutic apheresis programs, though reimbursement variability across Medicare Advantage plans constrains treatment access.
- Organ Transplantation:Desensitization protocols and antibody-mediated rejection management drive demand for high-efficiency plasma removal.
- Hyperlipidemia:Familial hypercholesterolemia refractory to pharmacotherapy creates niche demand for LDL apheresis, with German and Japanese centers pioneering ambulatory protocols.
Sepsis Treatment commands the steepest expansion trajectory as intensivist adoption accelerates; Autoimmune Disorders anchor current revenue concentration through established reimbursement pathways.
End User:
Procurement authority concentrates in hospital supply chain departments, while technical specification influence resides with perfusionists and apheresis nurses in academic medical centers.
- Hospitals:Tertiary and quaternary centers account for the majority of installed base, with continuous-flow platforms preferred for throughput efficiency. United States health systems with centralized GPO contracts increasingly unbundle service agreements from device acquisition, compressing manufacturer margins while expanding third-party logistics penetration.
- Clinics:Outpatient dialysis centers and specialized apheresis clinics in Germany and Japan are piloting ambulatory LDL apheresis and chronic autoimmune maintenance protocols.
- Blood Banks:Donor apheresis for platelet and plasma collection operates on distinct regulatory and technical specifications from therapeutic applications.
- Research Laboratories:Academic centers in Japan and Germany drive preclinical evaluation of novel adsorbent chemistries and membrane materials.
Hospitals dominate current procurement volume; Clinics represent the frontier for indication expansion into chronic maintenance protocols.
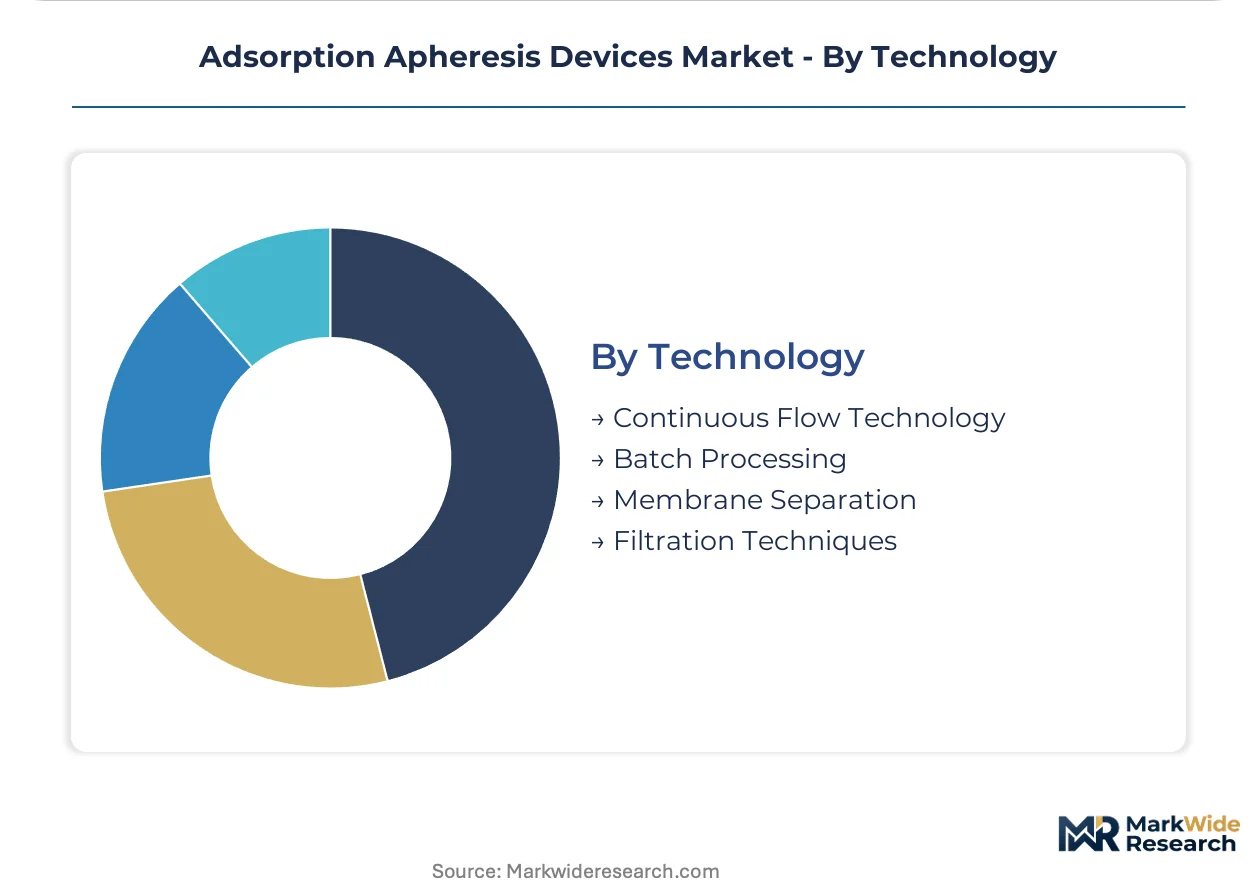
Technology:
Flow architecture determines treatment duration, operator skill requirements, and capital intensity more than any hardware component.
- Continuous Flow Technology:Simultaneous blood withdrawal and return through dual-lumen access enables shorter procedure times and higher patient throughput. Premium pricing persists in United States and German hospital markets where labor costs amplify the value of reduced operator time, though anticoagulation complexity elevates perfusionist training requirements.
- Membrane Separation:Hollow-fiber plasma separators with gradient pore density enable modular sourcing from specialized membrane manufacturers. Japanese suppliers leverage METI incentives for domestic precision extrusion equipment, reducing import dependency for critical separation components.
- Batch Processing:Intermittent flow systems retain relevance in resource-constrained settings with lower procedure volumes.
- Filtration Techniques:Combined membrane and adsorbent configurations target specific molecular weight ranges for selective pathogen removal.
Continuous Flow Technology sustains premium positioning; Membrane Separation is gaining share fastest as modular architectures decouple separation from adsorption stages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized perfusionists and apheresis nurses concentrate in tertiary hospital clusters across Germany, Japan, and the United States, anchoring regional capacity for complex autoimmune and sepsis protocols.
United States
Academic medical centers in Boston and the Research Triangle drive therapeutic apheresis program expansion for Guillain-Barré and myasthenia gravis management. FDA 510(k) pathways for blood purification devices compress approval timelines for manufacturers with standardized biocompatibility testing. Hospital systems with centralized GPO contracts in the Midwest increasingly unbundle service agreements from device acquisition.
Germany
Intensive care units in Bavaria and North Rhine-Westphalia lead European adoption of cytokine-adsorption columns for septic shock protocols. EU MDR conformity requirements extend review timelines for Class III blood purification submissions, consolidating procurement around established suppliers. Swiss and German notified bodies manage concentrated precision membrane extrusion equipment manufacturing.
Japan
Tertiary hospitals in Tokyo and Osaka generate the highest per-capita procedure volumes for hemoadsorption therapies among aging populations. METI domestic manufacturing incentives strengthen indigenous hollow-fiber membrane fabrication capabilities. PMDA post-market surveillance mandates elevate compliance costs while accelerating clinical evidence accumulation for domestic suppliers.
India
Emerging transplant centers in Maharashtra and Karnataka create pull-through demand for automated plasmapheresis platforms. CDSCO regulatory pathways for blood purification devices remain less stringent than Japan or the United States, enabling faster market entry. Specialized training programs for perfusionists concentrate in Delhi-NCR and Chennai medical institutes.
Switzerland
Precision medical device engineering clusters around Basel and Zurich support membrane separator innovation for plasma exchange applications. Swissmedic maintains alignment with EU MDR frameworks while offering specialized pathways for breakthrough blood purification technologies. Research laboratories in Lausanne pilot modular column-cartridge architectures for indication-specific customization.
Adsorption Apheresis Devices Market Competitive Landscape
Top-tier vendors anchor integrated platform supply, while mid-cap specialists occupy modular component niches. The vendor base stratifies across three tiers: diversified dialysis-apheresis conglomerates, hollow-fiber membrane precision manufacturers, and disposable-focused service network operators. Two strategic archetypes dominate: integrated platform providers leveraging cross-selling from dialysis installed bases, and membrane technology specialists monetizing precision extrusion capabilities. Competitive moves concentrate on M&A for regulatory database access and capacity expansion for adsorbent column production.
Among diversified healthcare conglomerates, Fresenius SE & Co. KGaA and Baxter International Inc. exemplify integrated platform strategies spanning dialysis and therapeutic apheresis. Haemonetics Corporation occupies a position within the specialized disposables and service network archetype, anchoring North American supply relationships. Asahi Kasei Medical Co., Ltd. represents the precision membrane technology tier, with Japanese manufacturing heritage supporting hollow-fiber innovation for cytokine-adsorption applications.
| Leading Market Players |
|---|
| Fresenius SE & Co. KGaA |
| Haemonetics Corporation |
| Terumo Corporation |
| Asahi Kasei Medical Co., Ltd. |
| B. Braun SE |
| Cerus Corporation |
| Baxter International Inc. |
| Nikkiso Co., Ltd. |
| Kaneka Corporation |
| Others |
Value Network & Pricing Analysis
Perfusionist concentration in German tertiary hospitals anchors labor-cost differentials that widen pricing-tier spreads between automated continuous-flow platforms and labor-intensive batch systems. METI-subsidized Japanese membrane fabrication compresses domestic production costs against imported European precision extrusion equipment, creating geographic arbitrage in hollow-fiber separator sourcing.
Pricing Analysis
The bundled-vs-unbundled service split now dominates procurement negotiations in United States health systems with centralized GPO operations. Three-tier pricing structure across premium, standard, and economy levels reflects automation depth and biocompatibility certification grade, with FDA 510(k) pathway acceleration intensifying cost compression in mid-tier segments. Academic medical centers demonstrate lowest price sensitivity due to reimbursement stability for established autoimmune protocols, while emerging Indian transplant centers prioritize capital expenditure minimization over feature depth.
Supply Chain Analysis
Japan's local-content-rule trajectory under METI manufacturing incentives is reshaping sourcing patterns for hollow-fiber membrane extrusion equipment. Germany, Switzerland, and Japan anchor precision component fabrication, drawing from synthetic polymer resins, activated carbon matrices, and polymethyl methacrylate feedstocks. Single-source vulnerability concentrates in Bavarian precision extrusion tooling, while distribution runs through hospital GPO contracts and third-party logistics providers rather than OEM direct channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
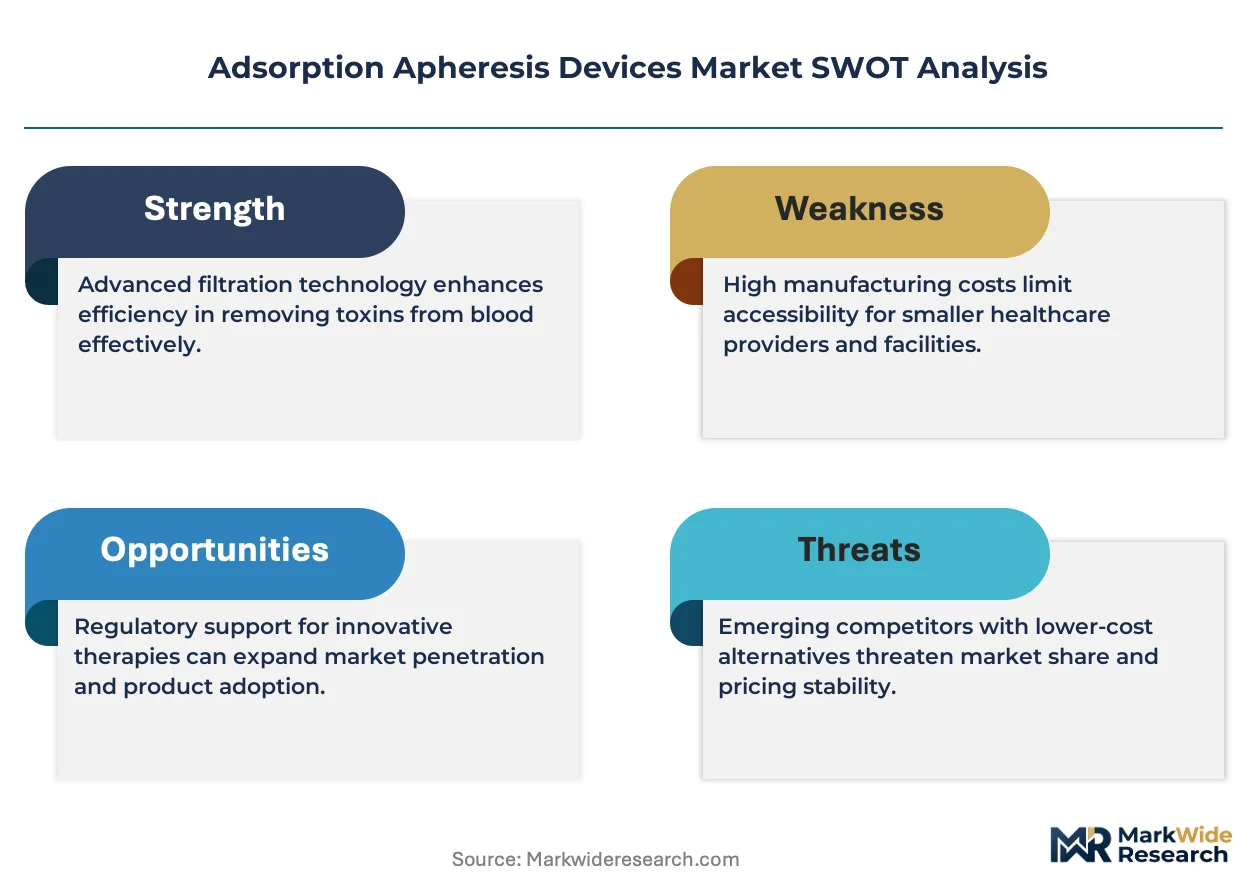
This market offers margin-expansion pathways through software-integrated therapeutic platforms that command premium positioning while reducing per-procedure labor intensity. Automation depth and real-time biomarker feedback integration enable pricing power separation from commodity disposable tiers.
For Market Incumbents: Lock in perfusionist training partnerships with academic medical centers to constrain competitor capacity expansion. Deepen backward integration into adsorbent column chemistry to defend margin position against synthetic resin cost volatility, while accelerating PMDA clinical database accumulation to exploit Japanese post-market surveillance barriers.
For New Entrants and Emerging Players: The premium-economy price-point gap in Indian transplant centers offers white-space positioning for automated plasmapheresis platforms with streamlined CDSCO pathways. Target Maharashtra and Karnataka emerging centers with service-unbundled acquisition models, leveraging third-party logistics partnerships to bypass entrenched OEM service networks.
For Investors and Strategic Acquirers: Diversified dialysis-apheresis conglomerates represent the most active acquirer category in this space, seeking regulatory database access and membrane fabrication capabilities. Mid-cap membrane specialists with ISO 10993 pre-submission histories offer viable acquisition profiles. Watch intensivist adoption velocity in German cytokine-adsorption protocols as the inflection signal for hemoadsorption category maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Real-time biomarker monitoring with adsorption flow control differentiates premium device tiers from commodity platforms. |
| Hospital System Partnership | GPO-negotiated multi-vendor fleet agreements in United States health systems compress OEM service margins while expanding addressable volumes. |
| CE Marking Pathway | EU MDR conformity front-loading for Class III submissions extends timelines but consolidates procurement around pre-certified portfolios. |
| FDA Submission Strategy | 510(k) streamlining on biocompatibility testing standardization accelerates time-to-market for next-generation adsorption columns. |
| Reimbursement Strategy | Medicare Advantage plan variability across United States regions constrains autoimmune protocol access, requiring indication-specific coding investment. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down membrane fabrication capacity tracking forms the analytical core of this study. Primary interviews with perfusionists, hospital GPO contracts managers, biomedical engineers, and regulatory affairs specialists at notified bodies combined with secondary validation from FDA 510(k) filings, PMDA post-market surveillance reports, METI manufacturing incentive disclosures, and EU MDR notified body review queue data. Triangulation across these sources ensures segmentation integrity.
Historical trendline analysis of installed base volumes and procedure frequency across device architectures established baseline trajectory parameters. The projection horizon models segmentation across treatment modality, clinical indication, care setting, and geographic regulatory cluster, with CAGRs derived from elasticity-adjusted adoption curves and capital expenditure cycle timing. Forecast inputs incorporate intensivist protocol adoption rates and domestic manufacturing incentive program maturation.
Caveats apply where PMDA surveillance mandate intensification or EU MDR review timeline extension could materially shift the outlook for new entrant viability and category expansion pacing. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Bone Densitometer Devices Market
Medical Devices
Surgical Mesh Market
Medical Devices
Parenteral Feeding Devices Market
Medical Devices
Non-Invasive Glucose Monitoring Devices Market
Medical Devices
Interphalangeal Fusion Market
Medical Devices
UK Artificial Organs and Bionic Implants Market
Medical Devices
Myopia Management Lenses Market
Medical Devices
Diabetic Eye Disease Devices Market
Medical Devices
Ovulation Microscope Market
Medical Devices
Central Venous Catheter Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Global Adult and Pediatric Hemoconcentrators Market
Medical Devices
Minimally Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Near Vision Devices Market
Medical Devices
Baby Thermometer Market
Medical Devices
Global Medical Dynamometer Market