
 Medical Coatings for Implants Market | 2026-2036
Medical Coatings for Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Coatings for Implants Market Intelligence
Orthopedic implant demand is recalibrating toward antimicrobial and hydrophilic coating solutions as hospitals prioritize infection control protocols. Himed leverages its calcium phosphate coating expertise to anchor supply relationships with major orthopedic OEMs across North America and Europe. Medicoat AG specializes in vacuum plasma spray technology for titanium and hydroxyapatite coatings, sustaining its position in hip and knee revision segments. Lincotek Group S.p.A. dominates European coating service networks through its multi-site manufacturing footprint in Italy and Switzerland.
Medical coatings for implants comprise functional surface layers applied to metallic, ceramic, or polymer substrates to enhance biocompatibility, reduce friction, enable localized drug delivery, or prevent bacterial colonization; these coatings typically range from 5 to 150 micrometers in thickness and are deposited through plasma spray, dip-coating, or chemical vapor deposition processes. Drug-eluting coatings command premium positioning due to complex formulation requirements and extended regulatory validation timelines, while antimicrobial segments are attracting accelerated R&D investment from coating houses responding to hospital-acquired infection liability concerns. Orthopedic implant types remain the largest volume application, though cardiovascular stent coatings retain higher per-unit value margins due to polymer degradation profile specifications.
FDA 510(k) and PMA pathways govern U.S. market access for implantable coatings, while EMA Medical Device Regulation and ISO 10993 biocompatibility standards shape European commercialization requirements. China's NMPA has tightened clinical evidence rules for imported orthopedic coatings, extending registration timelines for foreign suppliers. Stakeholders must monitor evolving sterilization compatibility requirements and polymer degradation testing standards that will determine which coating platforms qualify for next-generation implant contracts.
Market Dynamics
Antimicrobial coating validation protocols are compressing development timelines as orthopedic OEMs race to secure FDA 510(k) clearance ahead of competitors. Plasma spray deposition capacity constraints in Switzerland and Italy are forcing manufacturers to qualify secondary coating houses.
Growth Catalysts
- Biocompatibility mandates:EMA Medical Device Regulation and ISO 10993 standards are compelling implant manufacturers to upgrade surface treatments. Coating providers with established biocompatibility dossiers capture accelerated procurement cycles.
- Revision surgery volume:Aging patient demographics in Germany and the United States are expanding demand for hydroxyapatite-coated revision implants. Vacuum plasma spray capacity is tightening as OEMs secure multi-year supply agreements.
- Infection liability exposure:Hospital-acquired infection protocols are elevating antimicrobial coating specifications in joint replacement tenders. Silver-ion and copper-alloy surface treatments are penetrating standard of care discussions.
Market Restraints
- Polymer degradation testing costs:Drug-eluting coating validation requires extended ISO 10993-13 stability studies that extend development budgets by 18-24 months. Small coating houses lack capital to absorb these timelines.
- Plasma spray equipment concentration:Vacuum plasma spray system manufacturing concentrates in German and Swiss industrial clusters. Equipment lead times now exceed 14 months, constraining coating service expansion.
- Calcium phosphate raw material volatility:Synthetic hydroxyapatite precursor supply hinges on phosphate rock processing capacity in Morocco and China. Input cost swings compress margin predictability for coating formulators.
Strategic Opportunities
- Cardiovascular stent coating expansion:Polymer degradation profile specifications for next-generation drug-eluting stents are creating premium coating tiers. Bioresorbable polymer platforms command 3-4x per-unit value multiples versus orthopedic applications.
- China NMPA pathway acceleration:Local clinical evidence generation for imported orthopedic coatings is shortening registration timelines for joint-venture manufacturing structures. Domestic coating service partnerships are unlocking hospital procurement networks.
- 3D-printed implant integration:Additive manufacturing of titanium lattice structures is converging with in-situ coating deposition. Coating houses with electron beam melting compatibility are securing exclusive development contracts.
Industry Challenges
- Sterilization compatibility validation:Gamma and ethylene oxide sterilization protocols degrade specific polymer coating chemistries. Coating houses must maintain parallel validation tracks for multiple sterilization modalities.
- Cross-functional talent scarcity:Surface engineering expertise combining plasma physics, biomaterials science, and regulatory affairs concentrates in Basel and Boston corridor universities. Compensation inflation is compressing R&D unit economics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Coatings for Implants Market |
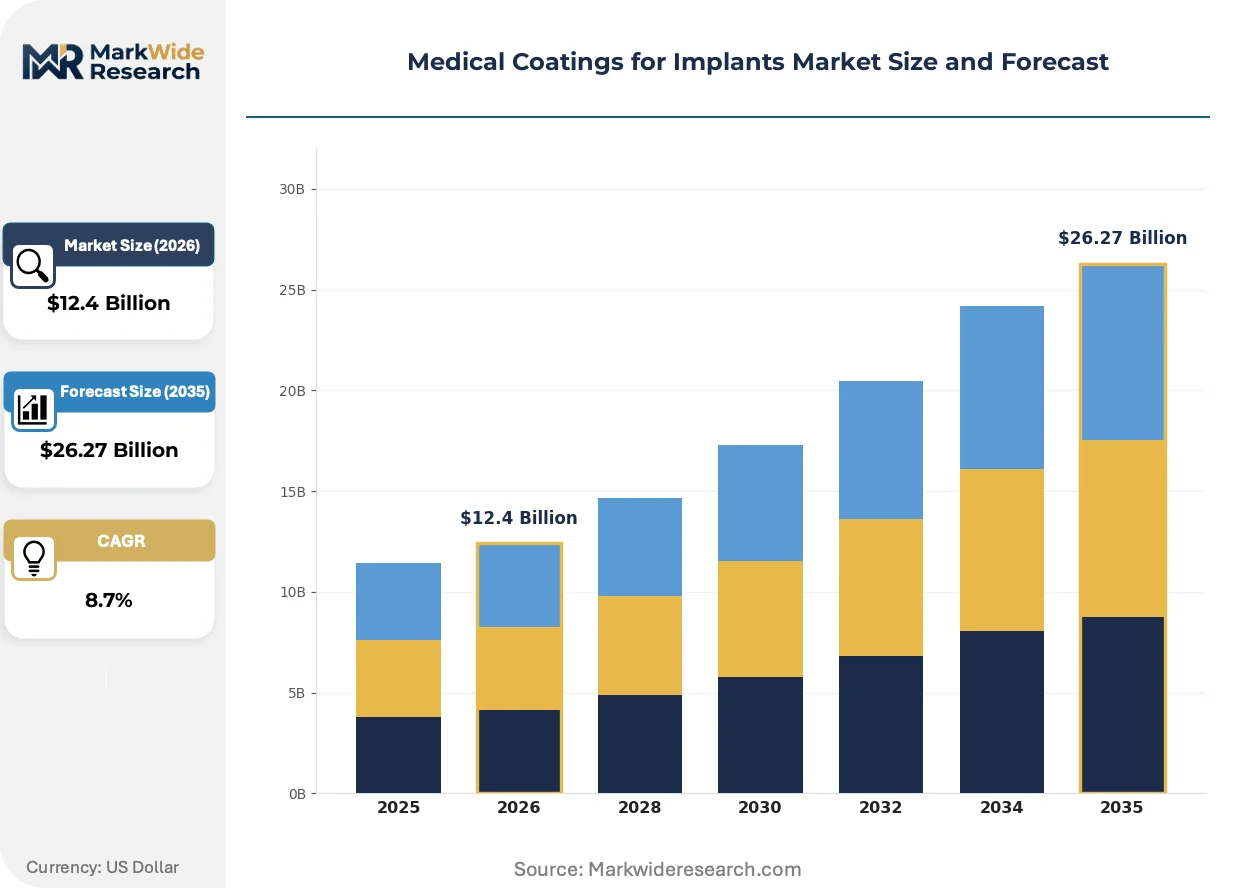
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coating Type: Hydrophilic, Hydrophobic, Drug-Eluting, Antimicrobial Material: Polymer, Metal, Ceramic, Composite Implant Type: Orthopedic, Dental, Cardiovascular, Neurological Application: Prosthetics, Stents, Surgical Instruments, Orthopedic Devices |
| Companies Covered | Himed, Hydromer, DOT GmbH, Lincotek Group S.p.A., Medicoat AG, CAM Bioceramics B.V., APS Materials, Inc., Freudenberg Medical, Accentus Medical Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Coatings for Implants Market Strategic Shifts & Innovations
Surface engineering is pivoting from passive biocompatibility toward active therapeutic functionality as coating houses integrate drug delivery and antimicrobial release into single deposition processes. This convergence is redrawing competitive boundaries between materials suppliers and pharmaceutical formulators.
Photocatalytic titanium dioxide coatings with UV-activated antibacterial properties are overtaking silver-ion treatments in ambulatory surgical center procurement specifications. Outpatient joint replacement providers favor TiO2 platforms for reduced systemic toxicity profiles. The technology is compressing silver-based coating price premiums by 15-20 percent across standard hip and knee implant tiers.
China's NMPA has tightened clinical evidence requirements for imported orthopedic coatings, mandating domestic patient enrollment for Class III device registrations. Foreign coating suppliers are establishing Shanghai and Suzhou joint ventures to generate local trial data. European coating houses with existing China partnerships are capturing accelerated registration timelines versus direct exporters.
Hospital procurement committees are consolidating coating specifications into centralized tender documents that favor multi-technology coating houses over single-process specialists. Integrated providers offering plasma spray, dip-coating, and chemical vapor deposition under one quality system are displacing niche coating shops. This concentration is most visible in United States IDN purchasing agreements where supply base reduction targets favor vertically capable coating service networks.
Medical Coatings for Implants Market Segmentation
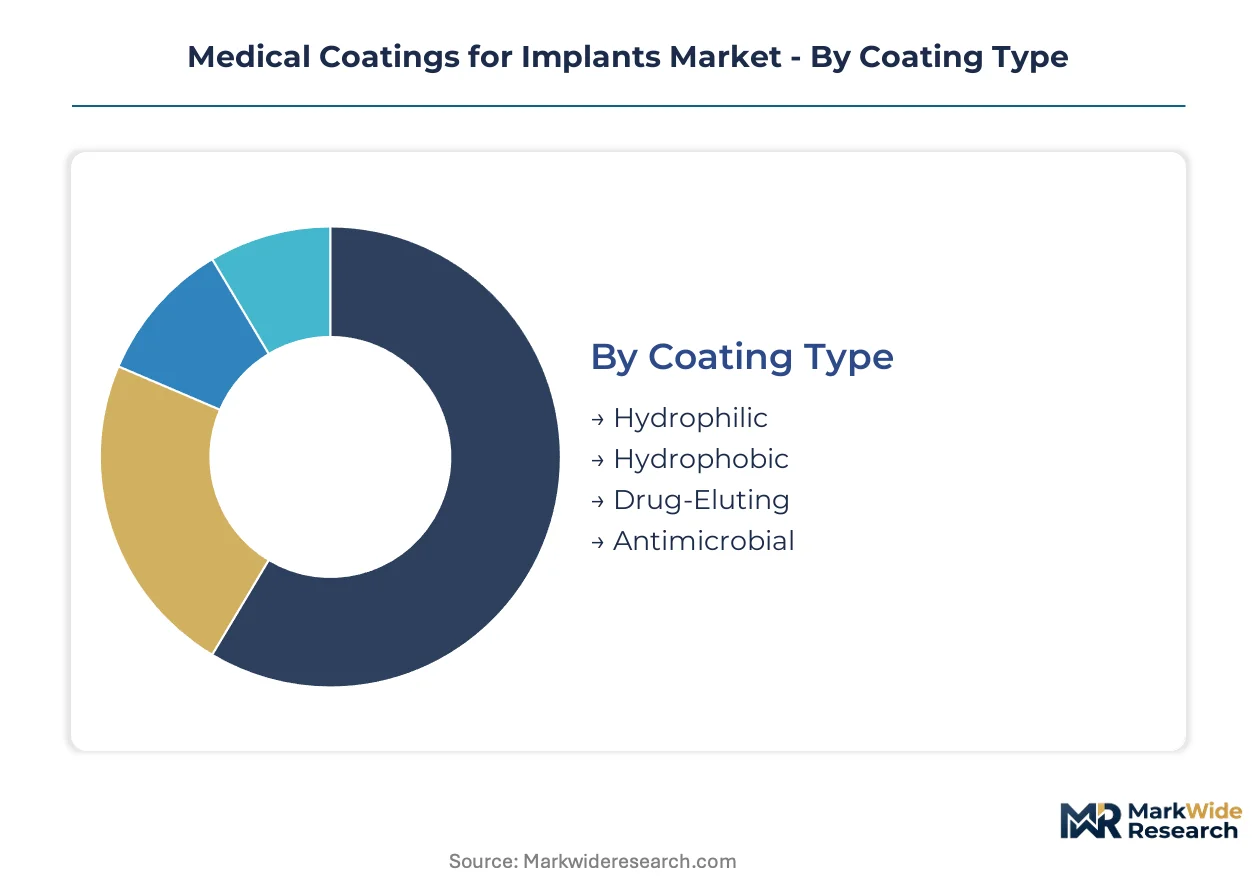
Coating specification determines regulatory pathway complexity and manufacturing margin structure across implant categories. Material chemistry and deposition method selection cascade into sterilization compatibility constraints and clinical validation timelines.
Coating Type:
Surface energy and therapeutic functionality define performance benchmarks and procurement specifications.
- Drug-Eluting:Polymer matrices encapsulate antiproliferative agents for controlled release kinetics over 30-90 day windows. Cardiovascular stent manufacturers in Germany and the United States prioritize these coatings for restenosis prevention, though ISO 10993-13 stability studies extend development cycles substantially.
- Antimicrobial:Silver-ion, copper-alloy, and photocatalytic titanium dioxide chemistries inhibit bacterial colonization on implant surfaces. Hospital procurement committees in Switzerland and the United States are elevating these specifications in joint replacement tenders to mitigate infection liability exposure.
- Hydrophilic:Polyvinylpyrrolidone and polyethylene glycol surface modifications reduce friction coefficients for catheter and guidewire applications.
- Hydrophobic:Fluoropolymer and silicone-based treatments repel biological fluids for specific neurological and ocular implant applications.
Drug-eluting coatings lead on scale; antimicrobial coatings lead on momentum.
Material:
Substrate chemistry governs deposition process compatibility and long-term biostability profiles.
- Polymer:Bioresorbable polyesters and permanent silicone platforms enable drug encapsulation and tunable degradation rates. Cardiovascular applications in Boston and Basel corridor manufacturing clusters drive specification refinement for next-generation stent platforms.
- Ceramic:Hydroxyapatite and calcium phosphate coatings promote osseointegration through biomimetic mineral composition. Orthopedic OEMs in Italy and Switzerland secure multi-year supply agreements for vacuum plasma spray deposition capacity.
- Metal:Titanium nitride and tantalum oxide layers enhance wear resistance and radiopacity for specific load-bearing applications.
- Composite:Hybrid organic-inorganic systems combine mechanical durability with biological signaling capacity for complex implant geometries.
Polymer platforms command premium pricing tiers; ceramic coatings anchor volume throughput.
Implant Type:
Clinical indication determines coating thickness tolerances and functional performance requirements.
- Orthopedic:Hip, knee, and spinal implants utilize hydroxyapatite and antimicrobial surface treatments to accelerate bone ingrowth and prevent periprosthetic infection. Revision surgery volumes in Germany and the United States are expanding demand for enhanced coating specifications.
- Cardiovascular:Coronary and peripheral stents require precise polymer degradation profiles to match endothelialization timelines. Drug-eluting formulations for these devices attract 3-4x per-unit value multiples versus orthopedic applications.
- Dental:Implant fixtures and abutments employ thin calcium phosphate layers to improve primary stability and soft tissue attachment.
- Neurological:Deep brain stimulation leads and shunt systems utilize insulating and anti-fouling coatings for chronic implantation.
Orthopedic implants dominate unit volumes; cardiovascular applications generate highest per-unit margins.
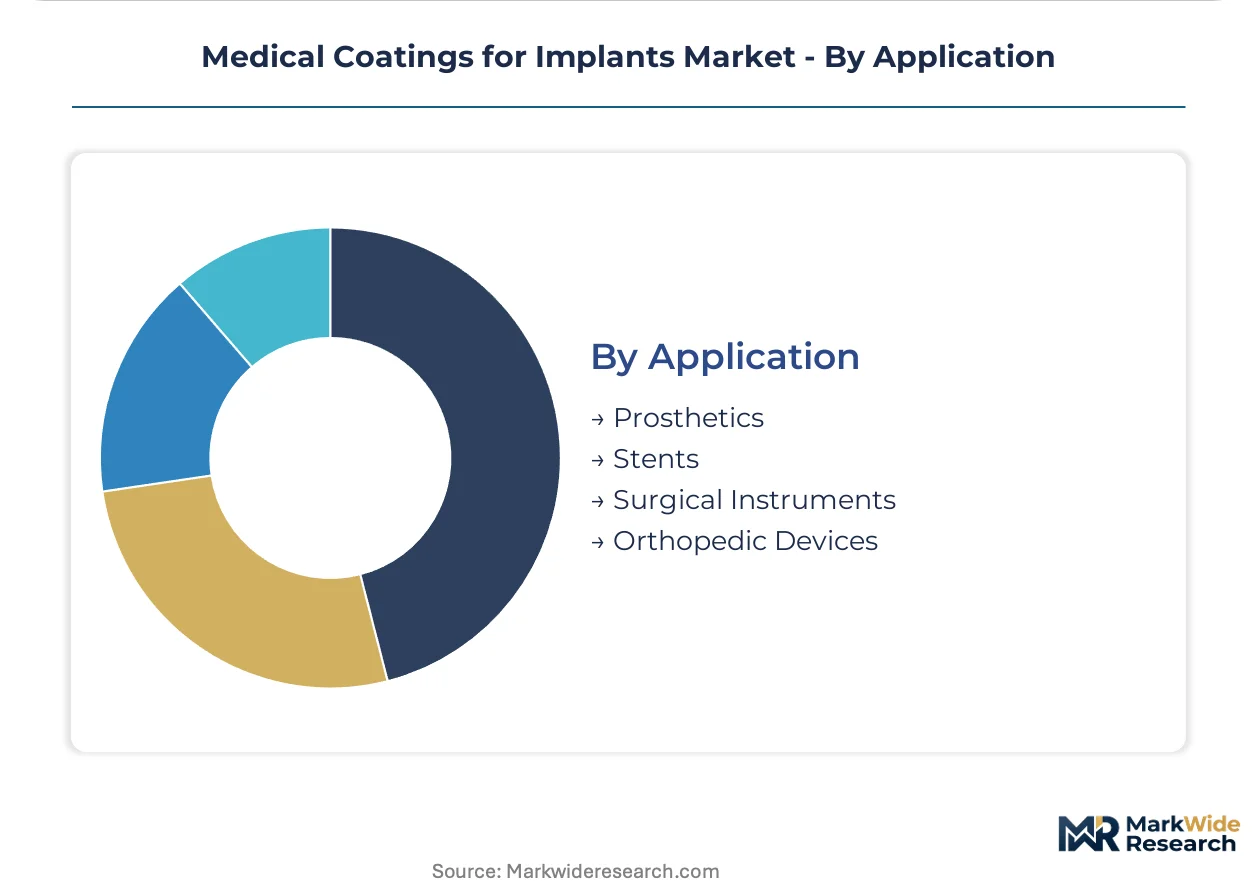
Application:
End-use environment shapes sterilization compatibility requirements and surface finish specifications.
- Stents:Drug-eluting and bare-metal coronary devices demand sub-micron coating uniformity to prevent thrombogenicity and ensure consistent drug release. FDA 510(k) and PMA pathways govern U.S. market access with extended validation timelines.
- Orthopedic Devices:Joint replacement components and spinal fixation hardware integrate antimicrobial and osteoconductive layers. China's NMPA has tightened clinical evidence requirements, mandating domestic patient enrollment for Class III device registrations.
- Prosthetics:External and internal limb replacement systems utilize low-friction coatings for articulating surfaces.
- Surgical Instruments:Electrosurgical and cutting tools employ insulating and anti-stick surface treatments for procedure efficiency.
Stent coatings lead on technical complexity; orthopedic devices lead on procurement volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as coating houses migrate production toward jurisdictions with streamlined biocompatibility validation pathways. Switzerland and Germany retain premium positioning for plasma spray deposition despite elevated compliance costs. China is capturing volume migration through joint-venture structures that satisfy NMPA clinical evidence mandates.
United States
Hospital procurement consolidation and infection liability protocols are elevating antimicrobial coating specifications in joint replacement tenders. FDA 510(k) and PMA pathways govern market access with extended validation timelines for drug-eluting platforms. The Boston corridor anchors surface engineering talent pools combining plasma physics and biomaterials expertise.
Germany
Aging demographics and revision surgery volumes are expanding demand for hydroxyapatite-coated orthopedic implants. EMA Medical Device Regulation and ISO 10993 standards compel manufacturers to upgrade surface treatment dossiers. The Basel industrial cluster concentrates vacuum plasma spray system manufacturing with equipment lead times now exceeding fourteen months.
Switzerland
Orthopedic OEMs secure multi-year supply agreements for ceramic coating capacity amid tightening deposition service availability. Swissmedic oversees biocompatibility requirements for long-term implantable devices with rigorous stability study protocols. The Zurich-Basel corridor houses specialized coating service networks serving European hip and knee revision segments.
China
Domestic patient enrollment mandates for Class III device registrations are extending timelines for direct foreign suppliers. NMPA pathway acceleration through joint-venture manufacturing structures is unlocking hospital procurement networks. Shanghai and Suzhou are emerging as coating service hubs generating local clinical trial data for imported orthopedic platforms.
Italy
Multi-site manufacturing footprints in northern Italy support European coating service networks with integrated quality systems. REACH and RoHS compliance requirements shape material chemistry selection for export-oriented production. The Emilia-Romagna region concentrates ceramic precursor processing capacity serving hydroxyapatite formulation supply chains.
Medical Coatings for Implants Market Key Industry Players
Capacity expansion dominates the current landscape as coating houses race to secure vacuum plasma spray equipment ahead of fourteen-month delivery backlogs. The vendor base stratifies between integrated multi-technology providers and single-process specialists facing procurement committee consolidation. Three archetypes occupy distinct positions: European coating service networks with established biocompatibility dossiers, North American antimicrobial technology licensors, and Asian joint-venture platforms capturing NMPA registration advantages. Geographic expansion and strategic partnerships represent the dominant competitive vectors as manufacturers qualify secondary deposition houses in Switzerland and Italy.
Within the European integrated service tier, Lincotek Group S.p.A. and Medicoat AG exemplify multi-site manufacturing structures spanning Italy and Switzerland. Himed occupies a position among calcium phosphate specialists leveraging established orthopedic OEM relationships across North America. These three entities represent contrasting strategic postures: network-scale coverage versus specialized ceramic expertise versus North American market anchoring.
| Leading Market Players |
|---|
| Himed |
| Hydromer |
| DOT GmbH |
| Lincotek Group S.p.A. |
| Medicoat AG |
| CAM Bioceramics B.V. |
| APS Materials, Inc. |
| Freudenberg Medical |
| Accentus Medical Ltd. |
| Others |
Cost & Logistics Intelligence
Hospital procurement committee consolidation into centralized tender documents is forcing coating houses to absorb validation cost burdens while maintaining multi-technology service portfolios under unified quality systems. This buyer-side concentration compresses margin buffers for single-process specialists and rewards integrated providers with pricing power anchored in sterilization compatibility breadth.
Pricing Analysis
Direct-to-OEM contracting dominates volume transactions, with coating service houses negotiating multi-year supply agreements that embed volume-scaled unit pricing and technical service bundling. Price differentiation hinges on ISO 10993 biocompatibility certification tier and plasma spray deposition capacity guarantees. Pricing pressure stems from photocatalytic titanium dioxide platforms displacing silver-ion premiums by fifteen to twenty percent across standard orthopedic tiers. Ambulatory surgical centers exhibit highest price sensitivity due to outpatient reimbursement constraints, while cardiovascular stent manufacturers demonstrate lowest sensitivity given polymer degradation specification complexity.
Supply Chain Analysis
Refurbishment flows for vacuum plasma spray equipment concentrate in German and Swiss industrial clusters, with remanufactured system components feeding capacity expansion timelines. Raw material sourcing draws from Moroccan phosphate rock processing for hydroxyapatite precursors and Chinese synthetic mineral production. Single-source vulnerability concentrates in vacuum plasma spray system manufacturing, where equipment lead times now extend beyond fourteen months. Distribution runs through orthopedic OEM technical service networks and coating house direct sales organizations serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
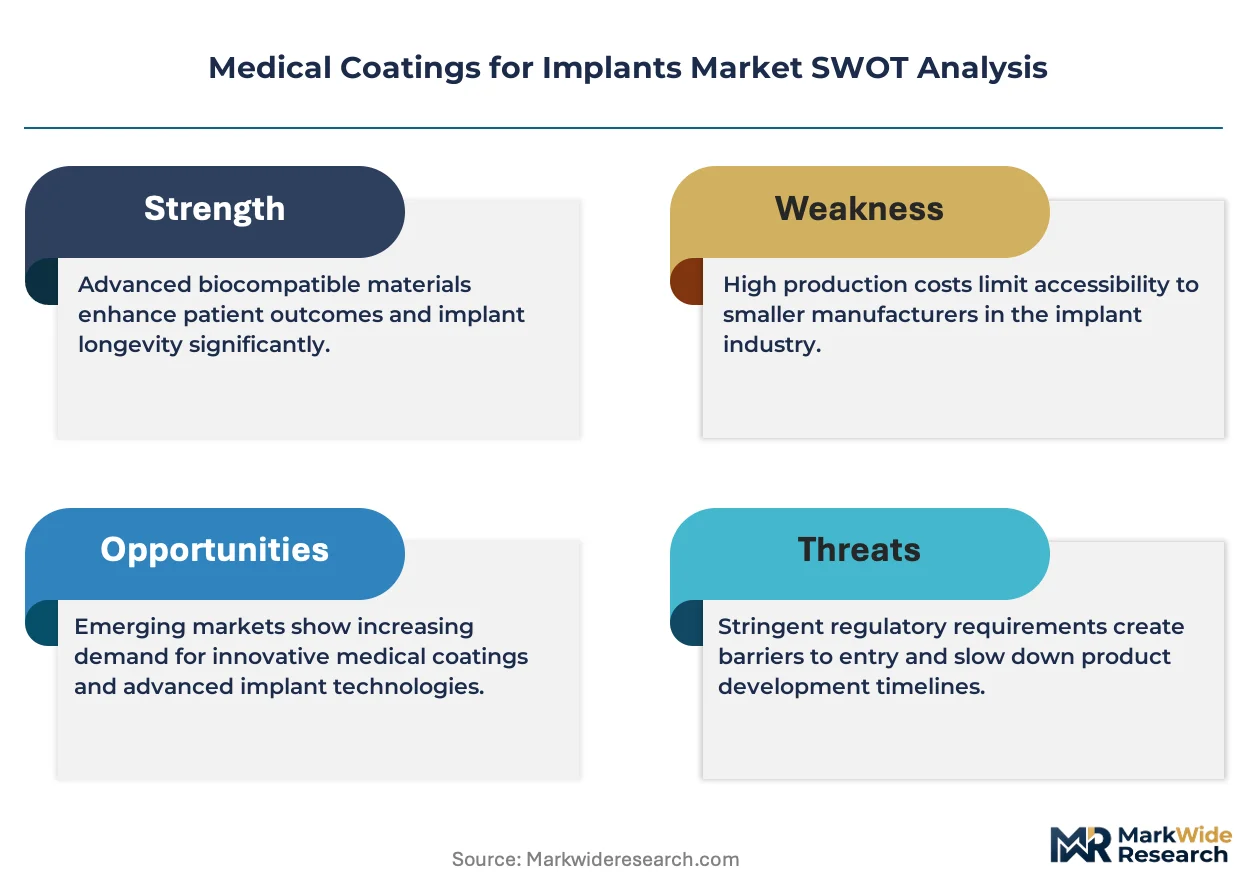
This market operates as a regulatory compounder where EMA Medical Device Regulation implementation is mandating surface treatment upgrades across European implant portfolios. The tightening biocompatibility validation timeline creates sustained demand for coating houses with established ISO 10993 dossiers.
For Market Incumbents: Deepen vacuum plasma spray capacity commitments in Switzerland and Italy ahead of equipment delivery backlogs, while securing parallel sterilization modality validations to defend against photocatalytic titanium dioxide substitution threats. Prioritize backward integration into calcium phosphate precursor processing to buffer Moroccan supply volatility. For New Entrants and Emerging Players: Launch via joint-venture structures in Shanghai and Suzhou to generate NMPA-mandated domestic clinical evidence for imported orthopedic coating platforms. The most penetrable white-space sits in antimicrobial coating specifications for ambulatory surgical center procurement, accessed through GPO contract participation and technical service partnerships. For Investors and Strategic Acquirers: Asymmetric upside sits with European coating service networks possessing multi-site manufacturing footprints and established EMA biocompatibility dossiers. The five-to-ten year viability window favors integrated providers over single-process specialists. Monitor NMPA registration timeline compression for joint-venture structures as the inflection signal indicating China market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Site Manufacturing Expansion | Geographic redundancy in Switzerland and Italy secures OEM supply continuity amid equipment constraints. |
| Joint-Venture Localization | Shanghai and Suzhou partnerships unlock NMPA pathways and hospital procurement network access. |
| Antimicrobial Technology Licensing | Silver-ion and photocatalytic platforms address infection liability protocols in IDN tender specifications. |
| Biocompatibility Dossier Investment | ISO 10993 validation depth accelerates procurement cycles under EMA Medical Device Regulation. |
| 3D-Printed Implant Integration | Electron beam melting compatibility secures exclusive development contracts for titanium lattice structures. |
Research Approach
Direct dialogue with orthopedic OEM procurement directors, coating house regulatory affairs managers, hospital purchasing committee chairs, and GPO contracts specialists grounded primary intelligence. Secondary validation drew from FDA 510(k) and PMA filing databases, EMA Medical Device Regulation guidance documents, NMPA registration records, and ISO 10993 biocompatibility standards. Bottom-up coating service capacity modeling and top-down implant volume projections were triangulated against hospital procurement database trends.
Bottom-up analysis segmented the market by coating type, material chemistry, implant category, and application across the projection horizon. Modeled dimensions encompassed deposition method compatibility, sterilization modality requirements, and regional regulatory cluster variations. CAGRs were derived from implant procedure volume trajectories, coating specification penetration curves, and per-unit value tier evolution. Forecast inputs incorporated revision surgery demographic projections and NMPA pathway timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under phosphate rock supply disruption or sterilization protocol shifts. Practitioners should monitor vacuum plasma spray equipment delivery schedules and NMPA joint-venture approval velocities for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Vascular Guidewires Market
Medical Devices
Global Cosmetic Contact Lens Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Surgical Monitors Market
Medical Devices
Breathing Exercise Devices Market
Medical Devices
Medical Machine Battery Market
Medical Devices
Global Pulse Oximeters Market
Medical Devices
Non-Invasive Pulse Oximeter Market
Medical Devices
United States Minimally Invasive Surgery Device Market
Medical Devices
Global Eye Massage Machine Market
Medical Devices
Medical Smart Glasses Market
Medical Devices
Single Use Contact Lenses Market
Medical Devices
France Contraceptive Devices Market
Medical Devices
Dialysis Device and Concentrates Market
Medical Devices
Europe Minimally Invasive Surgery Devices Market
Medical Devices
Wearable Artificial Kidney Market