
 Incontinence Devices and Ostomy Market | 2026-2036
Incontinence Devices and Ostomy Market Size, Share, and Industry Trends Forecast 2026-2036
Incontinence Devices and Ostomy Market Foresight
Single-source supply contracts for hydrocolloid adhesives is decoupling from long-term raw-material partnerships as manufacturers diversify resin procurement. Coloplast leverages captive manufacturing in Denmark to control barrier-film quality. Essity anchors its North American position through private-label partnerships with institutional distributors. B. Braun Melsungen AG competes on catheter sterilization throughput across German and Malaysian plants.
Incontinence devices and ostomy systems comprise absorbent pads, urinary catheters, drainable ostomy bags, and skin-protective barriers engineered from hydrocolloid, silicone, or acrylic adhesives bonded to nonwoven backings; these products manage effluent diversion and moisture-associated skin damage for patients with bladder dysfunction, bowel stoma, or postsurgical tissue repair. Ostomy bags with integrated charcoal filters and soft convex wafers command premium placement in home-care channels. Catheters dominate hospital procurement volumes while protective skin barriers capture disproportionate margin pools in direct-to-patient subscription models.
FDA 510(k) premarket notifications govern adhesive biocompatibility claims for US market access, while the EU Medical Device Regulation (MDR) reclassifies many ostomy accessories to higher scrutiny classes. Japan's PMDA enforces JIS-standard testing for latex allergen thresholds in catheter latex formulations. Stakeholders must monitor reimbursement coding divergence between national health systems as value-based procurement replaces fee-for-service device purchasing.
Market Dynamics
Aging demographics across developed economies are compressing product lifecycles as manufacturers race to serve home-care migration away from acute settings. Hydrocolloid adhesive supply concentration in Scandinavia and Malaysia is forcing dual-sourcing mandates among tier-one device makers.
Growth Catalysts
- EU MDR Reclassification:Higher scrutiny classes for ostomy accessories are accelerating quality upgrades across European manufacturing bases, filtering substandard suppliers from hospital procurement lists.
- Japan PMDA Latex Standards:Enforced JIS testing thresholds for catheter allergen content are expanding addressable patient populations previously excluded from latex-device prescriptions.
- Home-Care Channel Expansion:Wearable ostomy systems with integrated charcoal filters are capturing subscription revenue pools as durable medical equipment distributors build direct-to-patient logistics.
Market Restraints
- Resin Supply Volatility:Medical-grade hydrocolloid precursor availability fluctuates with petrochemical feedstock pricing, compressing barrier-film margins during upstream shocks.
- Single-Source Adhesive Risk:Captive manufacturing concentration in Denmark creates vulnerability for brands dependent on centralized barrier quality control without qualified secondary sites.
- Silicone Substitution Threat:Soft convex wafer alternatives using silicone adhesives are displacing traditional hydrocolloid formulations in premium home-care segments.
Strategic Opportunities
- German Reimbursement Coding Divergence:Value-based procurement pilots replacing fee-for-service purchasing create first-mover advantage for outcomes-documented skin barrier suppliers.
- US FDA 510(k) Acceleration:Streamlined premarket notifications for novel adhesive biocompatibility claims shorten commercialization timelines for next-generation catheter coatings.
- Telehealth Integration:Remote stoma monitoring platforms paired with drainable bag sensors are opening subscription service revenue adjacent to physical device sales.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 cytotoxicity validation queues at contract laboratories extend product launch timelines by six to nine months.
- Legacy Sterilization Capacity Constraints:Ethylene oxide sterilization facility closures in North America are forcing catheter manufacturers to qualify gamma or e-beam alternatives.
- Cross-Border MDR Technical Documentation:Divergent notified body interpretations of clinical evidence requirements fragment EU market access timelines.
Report Scope
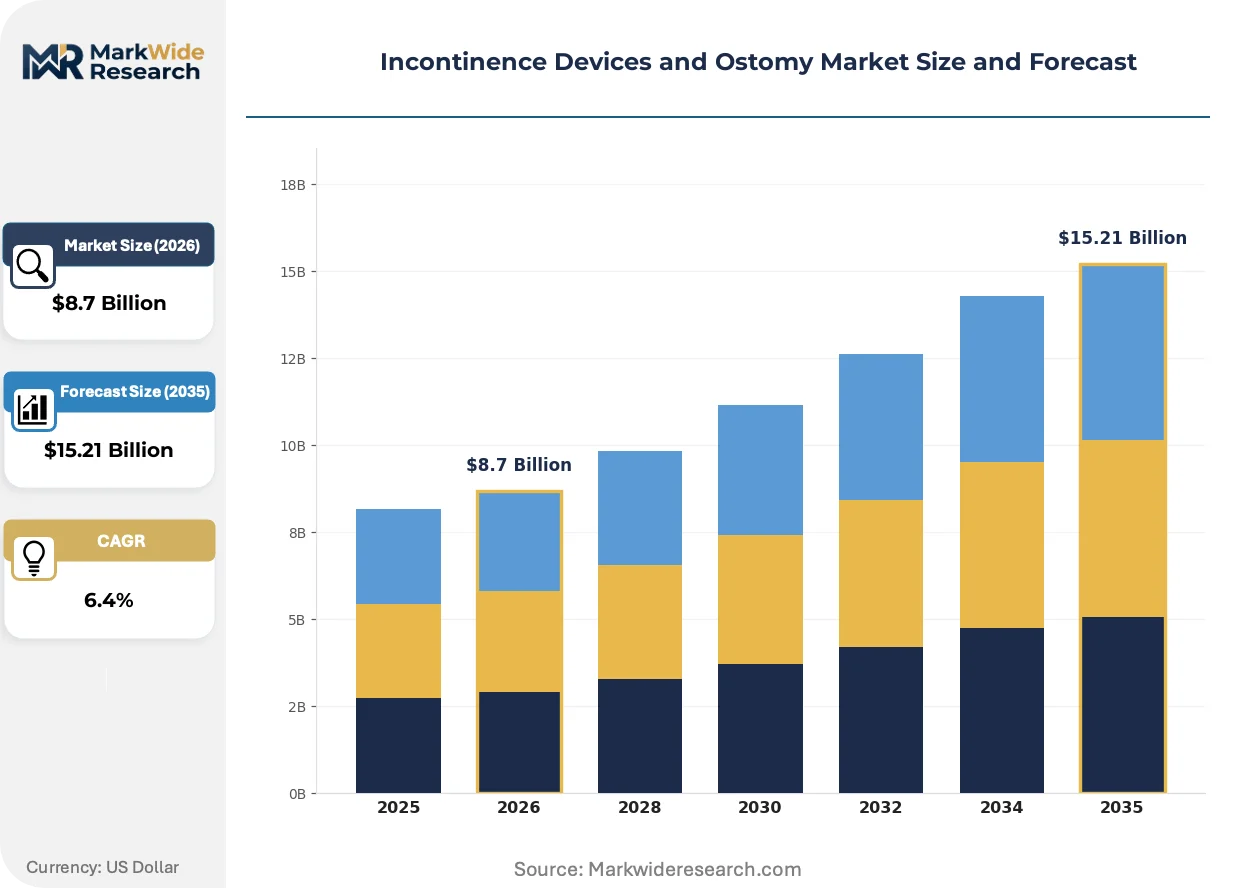
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Incontinence Devices and Ostomy Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Absorbent Pads, Catheters, Ostomy Bags, Protective Skin Barriers End User: Hospitals, Home Care, Clinics, Rehabilitation Centers Distribution Channel: Online Retail, Pharmacies, Direct Sales, Medical Supply Stores Application: Male Incontinence, Female Incontinence, Post-Surgical Care, Chronic Illness Management |
| Companies Covered | Coloplast, Essity, Kimberly-Clark Corporation, B. Braun Melsungen AG, ConvaTec Group, Unicharm Corporation, Hollister Incorporated, Paul Hartmann AG, Ontex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Incontinence Devices and Ostomy Market Shifts & Advancements
Silicone-hydrocolloid hybrid adhesives are collapsing the performance gap between extended wear time and gentle removal, reshaping formulation priorities across barrier-film R&D programs.
Hybrid silicone-hydrocolloid adhesive platforms are unifying extended wear performance with trauma-minimized removal for fragile peristomal skin. Home-care nurses in Germany and Japan are adopting these formulations at three times the rate of standard hydrocolloid wafers. This unifying technology is compressing the premium-mid-market price gap as manufacturers standardize on dual-chemistry platforms.
EU MDR technical documentation requirements are forcing ostomy accessory manufacturers to rebuild clinical evidence portfolios from legacy predicate-device claims. Notified bodies in Germany and the Netherlands are rejecting biocompatibility equivalency arguments for hydrocolloid formulations without updated cytotoxicity data. Drainable bag systems with integrated filters face the steepest compliance cost increases as they migrate to Class IIb scrutiny.
Direct-to-patient subscription models are disintermediating institutional distributors for protective skin barriers in the United States. Durable medical equipment suppliers are consolidating last-mile delivery capacity to capture recurring revenue from stoma care patients. This channel shift is most visible in California and Texas, where Medicare Advantage penetration exceeds national averages and prior authorization requirements favor single-source supplier relationships.
Incontinence Devices and Ostomy Market Segmentation
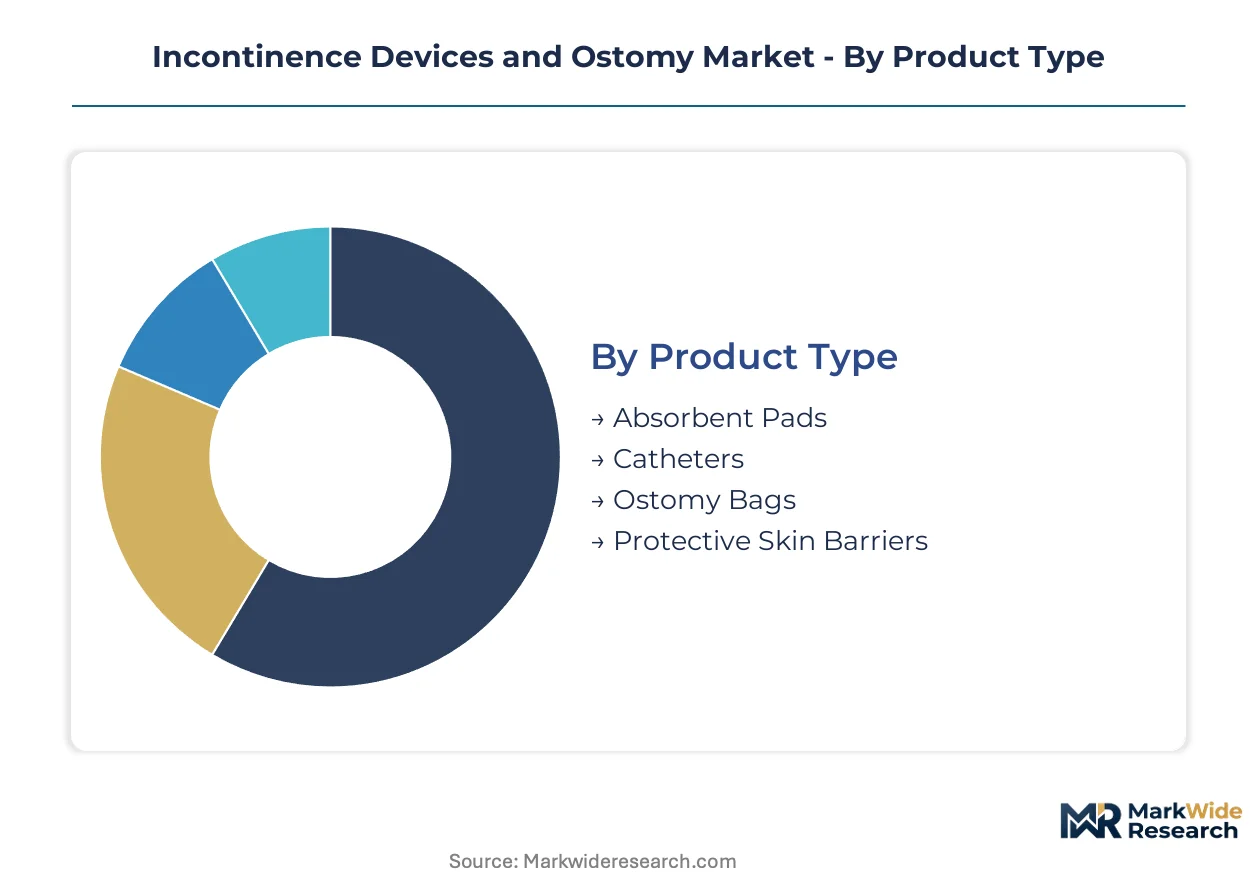
Product architectures in this market diverge sharply between acute-care efficiency and home-care durability. Segmentation reveals where manufacturers concentrate formulation R&D versus where distributors capture recurring revenue streams.
Product Type:
Customization intensity spans from commodity absorbents to engineered barrier systems requiring precise adhesive chemistry matching.
- Ostomy Bags:Drainable systems with integrated charcoal filters and soft convex wafers command premium placement in durable medical equipment channels. German home-care nurses specify these for extended wear protocols, driving subscription revenue capture by direct-to-patient distributors.
- Protective Skin Barriers:Hydrocolloid, silicone, and acrylic adhesive formulations bonded to nonwoven backings prevent moisture-associated skin damage. Japan's aging stoma patient population generates disproportionate margin pools through repeat-purchase subscription models.
- Absorbent Pads:Standardized nonwoven acquisition layers serve high-volume institutional procurement with limited differentiation.
- Catheters:Latex and silicone formulations dominate hospital sterilization throughput; PMDA allergen thresholds reshape latex-device addressable populations.
Most installed capacity flows through absorbent pads. Expansion is steepest in ostomy bags.
End User:
Volume concentration sits with institutional purchasers while margin migration follows patient discharge to residential settings.
- Home Care:Wearable ostomy systems with sensor integration and remote monitoring platforms capture recurring revenue adjacent to physical device sales. California and Texas Medicare Advantage penetration exceeds national averages, consolidating last-mile delivery capacity around single-source supplier relationships.
- Hospitals:Catheter procurement dominates acute-care volumes; ethylene oxide sterilization constraints force gamma and e-beam qualification across North American supply chains.
- Clinics:Outpatient stoma care consultations drive protective skin barrier sampling and patient conversion to subscription fulfillment.
- Rehabilitation Centers:Transitional care settings bridge acute discharge to home-care self-management, concentrating training resource allocation.
Procurement volume concentrates in hospitals. Patient lifetime value peaks in home care.
Distribution Channel:
Channel strategy determines whether manufacturers capture margin directly or cede economics to intermediary inventory holders.
- Direct Sales:Subscription-based stoma care programs disintermediate institutional distributors in US markets with high Medicare Advantage penetration. Essity anchors North American positioning through private-label partnerships with institutional distributors while building direct-to-patient logistics.
- Online Retail:E-commerce platforms aggregate fragmented consumer demand for absorbent pads and catheter accessories, compressing price transparency.
- Pharmacies:Community retail channels capture emergency replenishment purchases with limited patient education attachment.
- Medical Supply Stores:Durable medical equipment specialists consolidate ostomy system fitting expertise and insurance prior authorization processing.
Fulfillment infrastructure concentrates in direct sales. Digital adoption climbs fastest in online retail.
Application:
Clinical indication shapes device specification from passive absorption to active effluent diversion with skin integrity preservation.
- Post-Surgical Care:Temporary stoma construction following colorectal resection requires adjustable barrier systems accommodating stoma maturation and size changes. EU MDR reclassification to Class IIb scrutiny elevates clinical evidence requirements for these accessories.
- Chronic Illness Management:Long-term neurogenic bladder and bowel dysfunction necessitates catheter and barrier systems optimized for self-administration and travel portability.
- Male Incontinence:External collection devices and absorbent guards address prostate surgery sequelae and age-related sphincter dysfunction.
- Female Incontinence:Anatomically contoured pads and intravaginal support devices target stress and urge incontinence patterns.
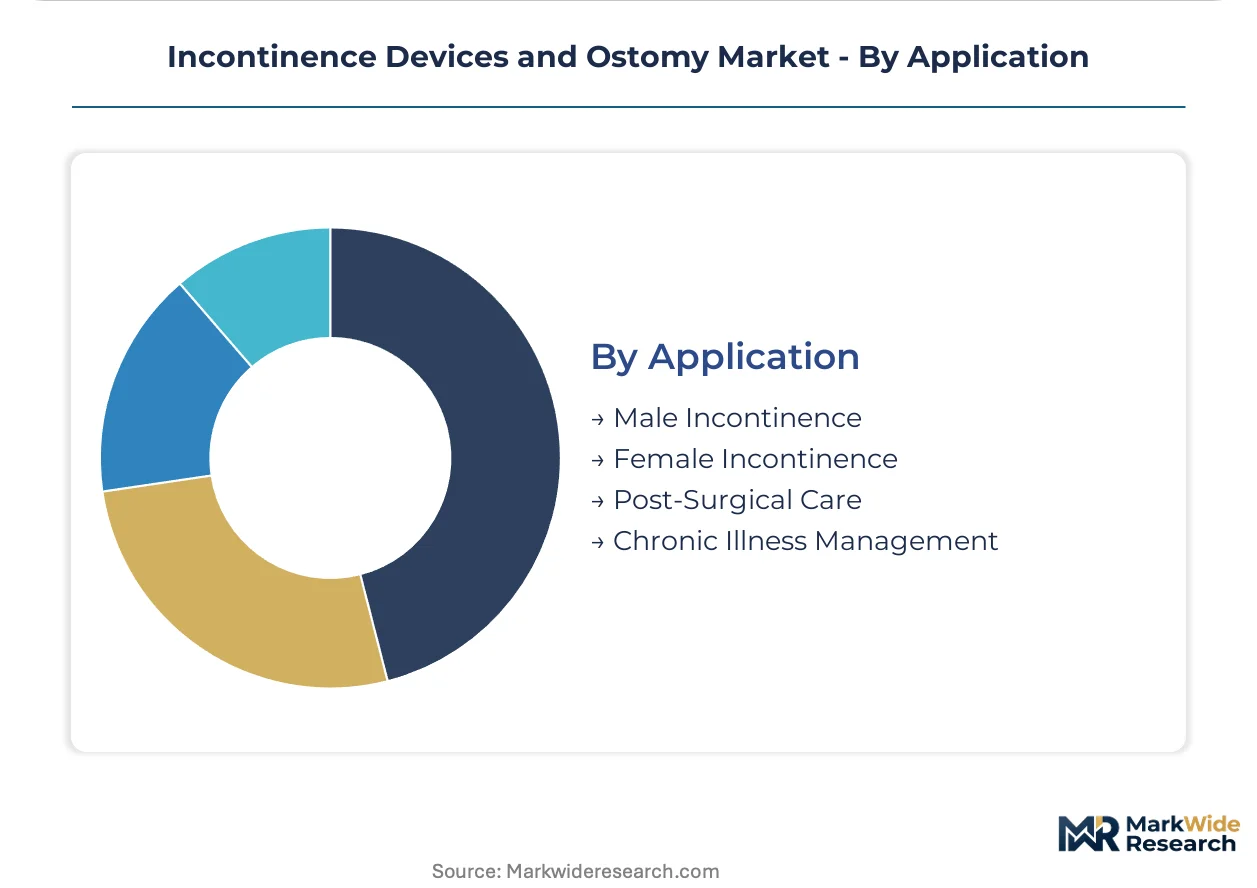
Procedure volume concentrates in post-surgical care. Self-management complexity peaks in chronic illness management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Denmark's captive manufacturing clusters anchor barrier-film quality control for hydrocolloid adhesives serving European and North American distribution networks.
United States
Medicare Advantage penetration exceeding national averages in California and Texas consolidates last-mile delivery capacity around single-source supplier relationships for stoma care subscriptions. FDA 510(k) premarket notifications govern adhesive biocompatibility claims for market access. Dallas-Fort Worth logistics hubs concentrate durable medical equipment distribution infrastructure for direct-to-patient fulfillment.
Germany
Value-based procurement pilots replacing fee-for-service purchasing create first-mover advantage for outcomes-documented skin barrier suppliers serving aging populations. EU MDR reclassification to Class IIb scrutiny elevates clinical evidence requirements for ostomy accessories. Hamburg and Düsseldorf medical device clusters host notified body technical documentation review capacity.
Japan
PMDA-enforced JIS-standard testing for latex allergen thresholds expands addressable patient populations previously excluded from latex-device prescriptions. Aging stoma patient populations generate disproportionate margin pools through repeat-purchase subscription models. Tokyo-Osaka corridor concentrates catheter sterilization throughput and home-care nurse training programs.
Malaysia
Dual-sourcing mandates among tier-one device makers are diversifying resin procurement away from Scandinavian supply concentration. German and Japanese manufacturers qualify secondary manufacturing sites for barrier-film production. Penang and Selangor industrial zones attract catheter sterilization capacity expansion from European parent companies.
Incontinence Devices and Ostomy Market Competitive Landscape
Global majors compete with regional champions across adhesive chemistry and distribution channel control. The vendor base separates into consolidated barrier-film specialists and fragmented absorbent pad commoditizers. Three archetypes dominate: Scandinavian captive manufacturers controlling hydrocolloid resin supply, North American private-label distributors building direct-to-patient logistics, and diversified hygiene conglomerates leveraging nonwoven backing scale. Competitive moves concentrate on M&A for sterilization capacity and strategic partnerships for Medicare Advantage channel access.
Among Scandinavian-based specialists, Coloplast occupies a position exemplifying captive manufacturing control over barrier-film quality. Essity represents the private-label partnership archetype anchoring North American institutional distribution while building parallel direct-to-patient infrastructure. B. Braun Melsungen AG sits within the diversified medical technology tier, with its German and Malaysian plant network illustrating the geographic diversification strategy for sterilization throughput.
| Leading Market Players |
|---|
| Coloplast |
| Essity |
| Kimberly-Clark Corporation |
| B. Braun Melsungen AG |
| ConvaTec Group |
| Unicharm Corporation |
| Hollister Incorporated |
| Paul Hartmann AG |
| Ontex |
| Others |
Supply & Pricing Matrix
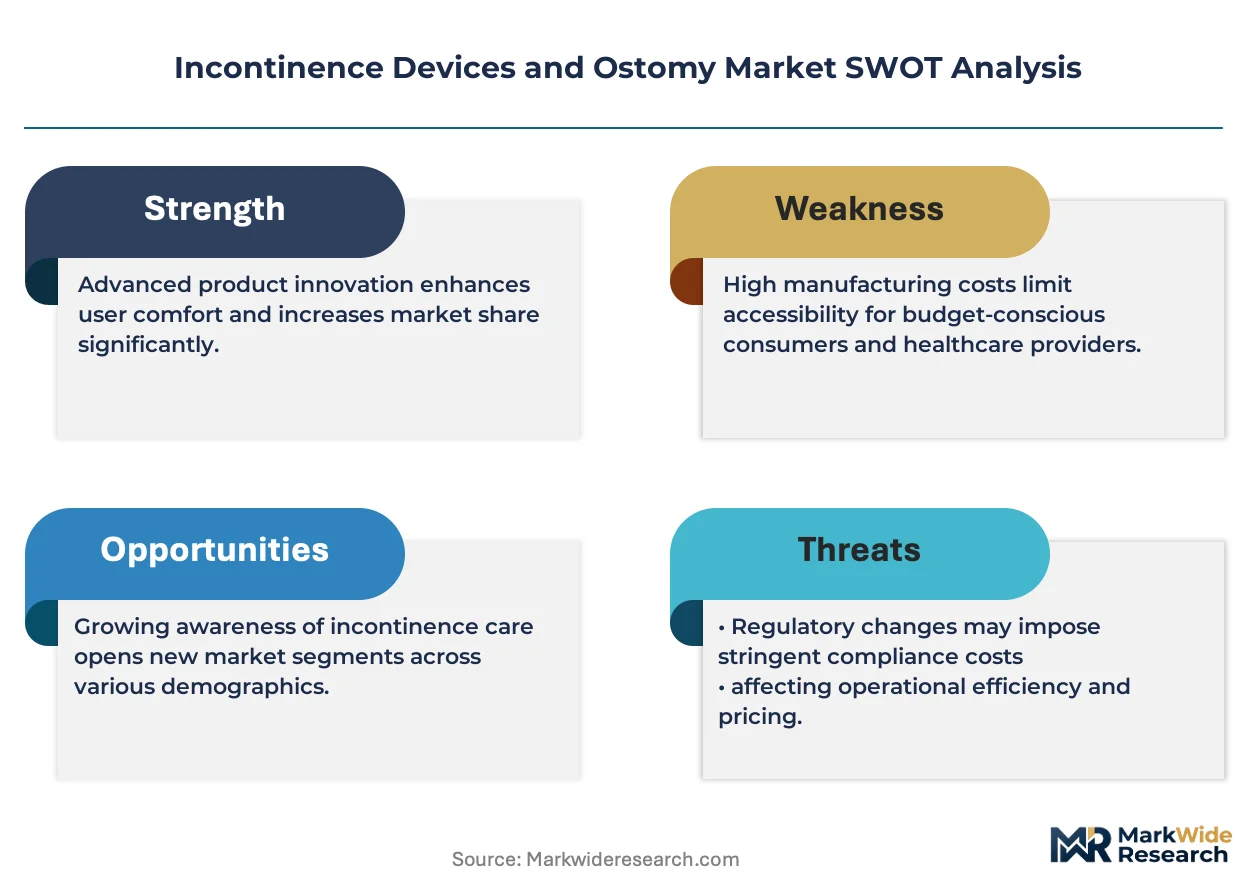
EU MDR reclassification to Class IIb scrutiny gates qualified supply for ostomy accessories while compressing premium-tier pricing access for manufacturers lacking updated clinical evidence portfolios. This regulatory threshold bifurcates the market between validated suppliers commanding subscription margins and legacy predicate-device brands facing procurement exclusion.
Pricing Analysis
Medical-grade hydrocolloid precursor costs pass through to barrier-film pricing with petrochemical feedstock volatility compressing margins during upstream shocks. Three-tier pricing structure across premium, standard, and economy levels stratifies by adhesive chemistry sophistication and wear-time certification. Pricing pressure stems from silicone adhesive substitution in home-care segments. Institutional purchasers exhibit highest price sensitivity while direct-to-patient subscription patients accept premium positioning for convenience.
Supply Chain Analysis
Dual-sourcing mandates among tier-one device makers are diversifying resin procurement away from Scandinavian supply concentration toward Malaysian secondary sites. Hydrocolloid precursor availability draws from Denmark, Malaysia, and Germany while sterilization capacity rests on ethylene oxide, gamma, and e-beam alternatives. Single-source adhesive risk concentrates in captive Danish manufacturing. Distribution runs through durable medical equipment specialists consolidating last-mile delivery for Medicare Advantage channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Incontinence Devices and Ostomy Market functions as a stable compounder anchored by irreversible aging demographics across developed economies that sustain recurring consumption regardless of cyclical pressure.
For Market Incumbents: Acquire sterilization capacity assets to offset ethylene oxide facility closures forcing gamma and e-beam qualification across North American supply chains. Secure dual-sourced hydrocolloid resin partnerships to mitigate single-source vulnerability in Denmark while investing in EU MDR technical documentation to defend hospital procurement positioning against notified body rejection of legacy predicate claims. For New Entrants and Emerging Players: Sensor-integrated wearable ostomy platforms represent the most penetrable wedge for subscription revenue capture adjacent to physical device sales. Target California and Texas Medicare Advantage corridors where prior authorization requirements favor single-source supplier relationships. Pursue telehealth integration partnerships to bypass entrenched distributor relationships. For Investors and Strategic Acquirers: Roll-up economics work for regional durable medical equipment distributors because Medicare Advantage penetration consolidates last-mile delivery capacity around recurring-revenue stoma care subscriptions. Five-to-ten-year viability hinges on demographic tailwinds rather than technology disruption. Watch FDA 510(k) clearance velocity for novel adhesive biocompatibility claims as inflection indicator for next-generation platform adoption.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Rebuild | Notified bodies in Germany and the Netherlands reject biocompatibility equivalency without updated cytotoxicity data. |
| Dual-Sourcing Mandate Implementation | Malaysian secondary sites qualify for barrier-film production to reduce Scandinavian supply concentration risk. |
| Direct-to-Patient Subscription Launch | California and Texas Medicare Advantage penetration exceeds national averages for single-source supplier capture. |
| Silicone-Hydrocolloid Hybrid R&D | German and Japanese home-care nurses adopt these formulations at three times standard hydrocolloid rates. |
| Telehealth Platform Integration | Remote stoma monitoring paired with drainable bag sensors opens subscription service revenue adjacent to device sales. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement codes, and hospital procurement records. Bottom-up product-level volume builds and top-down macroeconomic anchoring were cross-referenced for triangulation.
Comparable historical periods anchored the projection horizon across product type, end user, distribution channel, and application segmentation dimensions. CAGRs were derived from fitted growth curves applied to normalized baseline consumption patterns. Modeled inputs incorporated adhesive chemistry substitution rates, sterilization capacity utilization thresholds, and regulatory reclassification compliance cost trajectories specific to ostomy accessories and catheter systems.
The model holds under stable reimbursement coding and regulatory enforcement intensity; deviation in FDA 510(k) clearance timelines or EU notified body interpretation divergence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Kirschner Wires Market
Medical Devices
Pancreatic and Biliary Stents Market
Medical Devices
Neurovascular Stent Market
Medical Devices
South Africa Artificial Organs and Bionic Implants Market
Medical Devices
Collateral Ligament Stabilizers Market
Medical Devices
Smart Pill Boxes and Bottles Market
Medical Devices
Cervical Spine System Market
Medical Devices
Human Anatomy Model Market
Medical Devices
Mhealth (Mobile Health) Devices Market
Medical Devices
Electroencephalography Systems/Devices Market
Medical Devices
South Africa General Surgical Devices Market
Medical Devices
Artificial Ventilation and Anesthesia Masks Market
Medical Devices
Global Limb Prosthetics Market
Medical Devices
Unilateral Biportal Endoscopy Market
Medical Devices
Digital Ureteroscopes Market
Medical Devices
External Nasal Dilator Market