
 EEG and EMG Equipment Market | 2026-2036
EEG and EMG Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
EEG and EMG Equipment Market Intelligence
The capability gap between integrated neurotechnology platforms and standalone device manufacturers is unwinding competitive dynamics across the EEG and EMG Equipment landscape. Medtronic Plc leverages its deep vertical integration in neurostimulation and monitoring to bundle hardware with surgical navigation systems. Nihon Kohden Corporation anchors its position through dominant channel control in Japanese hospital neurology departments and Asian diagnostic laboratories. Cadwell Industries Inc. specializes in ambulatory EEG systems for sleep studies, competing on signal fidelity in home-based monitoring environments.
Electroencephalographs and electromyographs are bioelectrical recording instruments that capture neural and muscular action potentials through surface or invasive electrodes, with typical sampling rates ranging from 256 Hz to 2 kHz and analog-to-digital resolution of 16–24 bits for clinical-grade diagnostic fidelity. These systems serve primary commercial purposes in neurological disease detection, perioperative monitoring, and neurorehabilitation outcome tracking. Electroencephalographs command the largest installed base among product types due to entrenched use in epilepsy and sleep disorder protocols, while wireless solutions within the deployment dimension represent the fastest-expanding margin pool as reimbursement frameworks adapt to remote patient monitoring. Brain-computer interface applications attract concentrated R&D investment from research institutes, though neurological diagnostics retains the deepest revenue concentration across end users.
FDA 510(k) clearance pathways and the EU MDR technical documentation requirements shape product development timelines and market access barriers for manufacturers seeking multi-jurisdiction commercialization. ISO 13485 quality management standards and IEC 60601-1 electrical safety benchmarks further constrain design choices for amplifiers and signal processors deployed in critical care settings. Stakeholders must monitor evolving software-as-a-medical-device classification precedents that will determine whether AI-enhanced waveform analysis triggers additional premarket scrutiny or accelerates competitive differentiation.
Market Dynamics
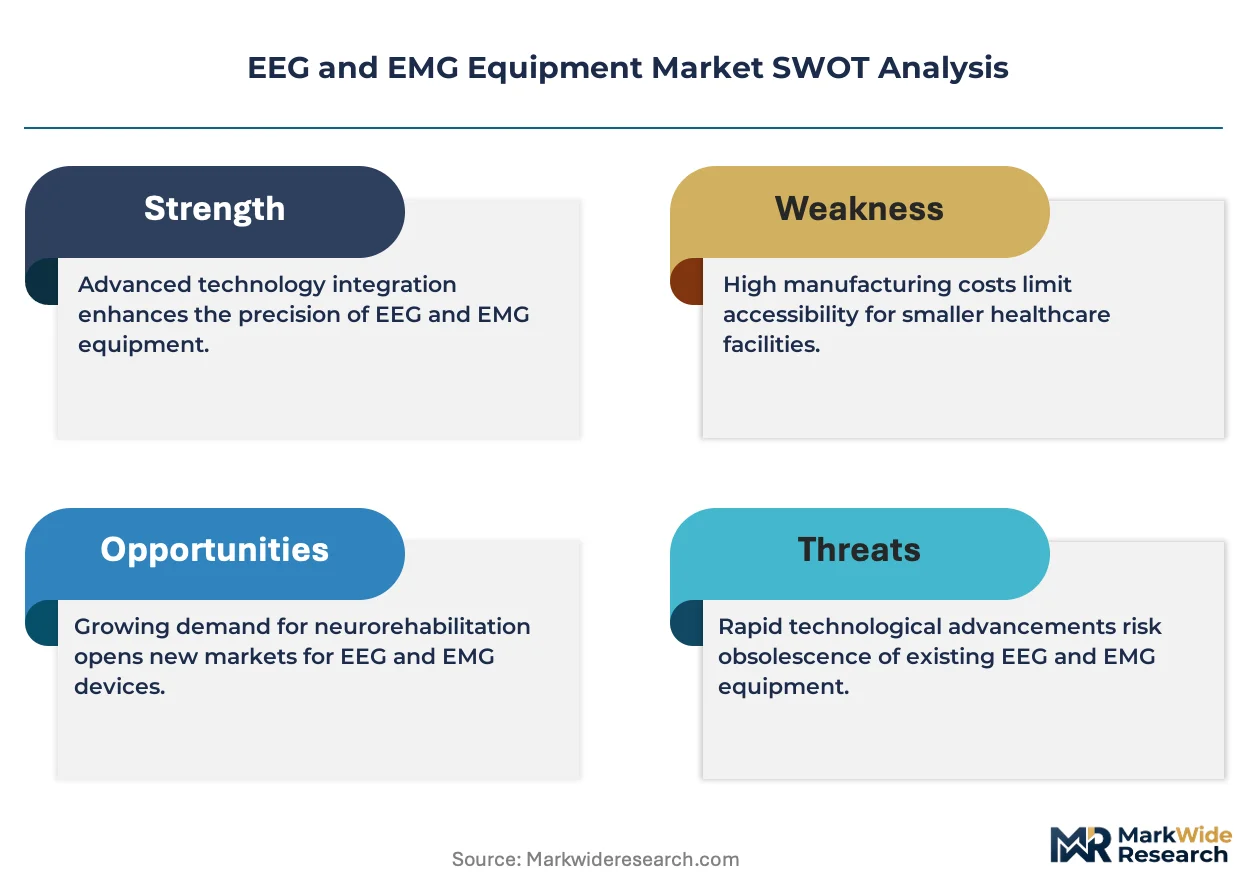
The EEG and EMG Equipment market is undergoing structural recalibration as wireless telemetry and cloud-native architectures dismantle the hardware-software bundling that long protected incumbent margins. This shift forces manufacturers to unbundle signal acquisition from analytic software, compressing pricing power while opening new revenue pools in subscription-based diagnostics.
Growth Catalysts
- EU MDR software validation mandates:Stricter technical documentation requirements for neurodiagnostic devices are accelerating hospital procurement cycles as facilities upgrade legacy systems ahead of compliance deadlines.
- Epilepsy monitoring units:Hospital neurology departments in Germany, the United States, and Japan are expanding long-term video-EEG capacity to address surgical candidacy assessment backlogs.
- Remote patient monitoring reimbursement:CMS and parallel frameworks in Japan are establishing coverage codes for ambulatory EEG, unlocking capital deployment into wireless monitoring infrastructure.
Market Restraints
- Electrode consumable cost volatility:Silver-silver chloride electrode prices fluctuate with precious metal markets, squeezing gross margins for high-volume disposable-dependent operators.
- Amplifier component concentration:Precision analog-to-digital converters and isolated instrumentation amplifiers rely on concentrated semiconductor fabrication in East Asia, exposing supply continuity risk.
- Biopotential signal artifact:Motion and electrical interference in non-clinical environments limits diagnostic yield of home-based EMG, constraining ambulatory market expansion.
Strategic Opportunities
- Brain-computer interface research institutes:DARPA and NIH-funded neurotechnology programs are procuring high-density EEG arrays for motor prosthesis development, creating premium hardware demand outside clinical diagnostics.
- AI-enhanced waveform classification:Machine learning algorithms trained on institutional epilepsy databases promise automated seizure detection, potentially differentiating software offerings.
- Sleep disorder home diagnostics:Reimbursement clarity for home sleep apnea testing is extending to nocturnal seizure monitoring, opening ambulatory EEG deployment in cardiology and pulmonology practices.
Industry Challenges
- Clinical neurophysiologist staffing:Fellowship-trained readers capable of interpreting complex epilepsy and neuromuscular studies remain concentrated in academic medical centers, limiting service expansion.
- FDA 510(k) software-as-medical-device reclassification:Evolving precedents for AI-enhanced diagnostic algorithms create regulatory uncertainty, extending premarket submission timelines and compliance costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | EEG and EMG Equipment Market |
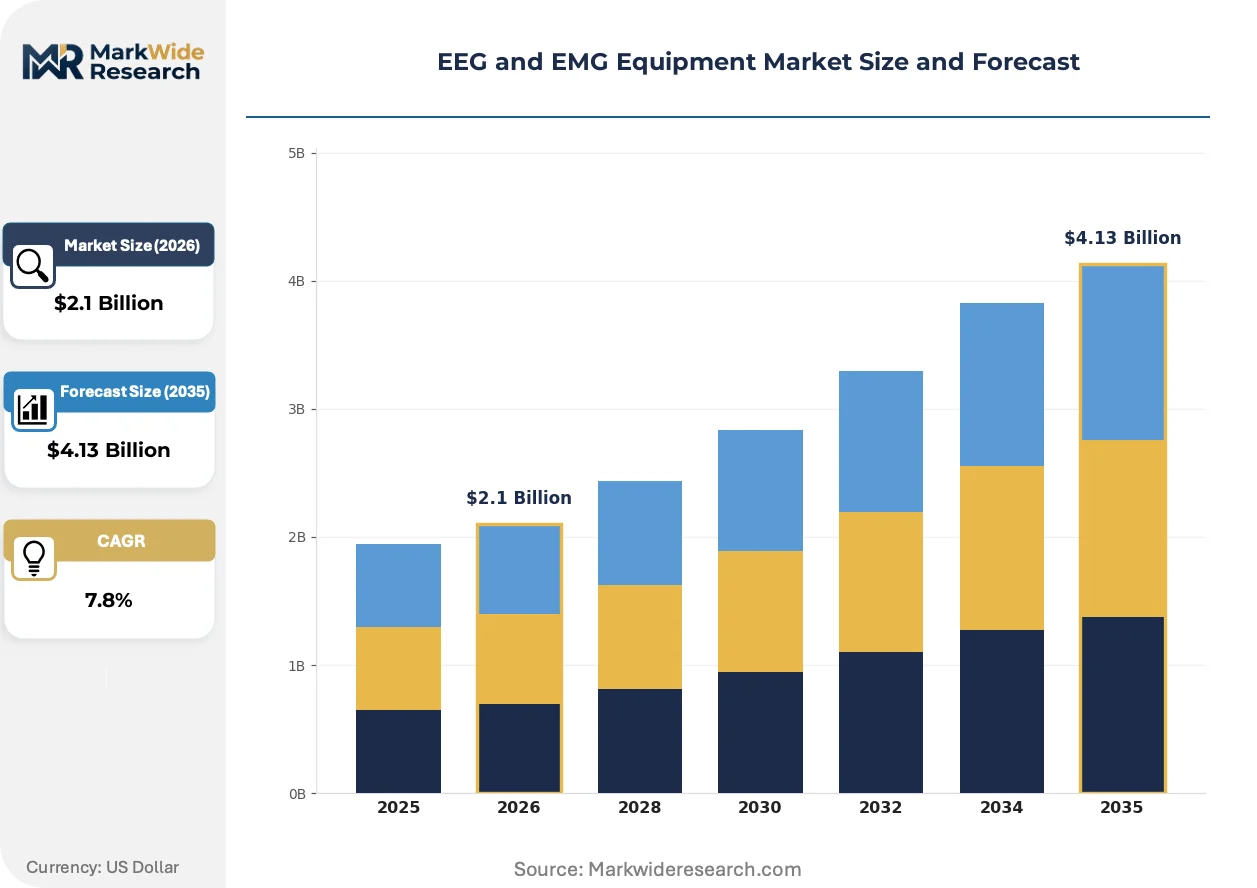
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.13 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electroencephalographs, Electromyographs, Amplifiers, Signal Processors, Adhesive Electrodes Application: Neurological Diagnostics, Sleep Studies, Rehabilitation Monitoring, Muscle Disorder Evaluation, Brain-Computer Interface End User: Hospital Neurology Departments, Diagnostic Laboratories, Rehabilitation Centers, Research Institutes, Neurodiagnostic Clinics Deployment: Stationary Systems, Portable Devices, Wearable Equipment, Wireless Solutions, Bedside Monitors |
| Companies Covered | Medtronic Plc, Koninklijke Philips N.V., General Electric Company, Natus Medical Incorporated, Nihon Kohden Corporation, Cadwell Industries Inc., Masimo Corporation, Compumedics Limited, Brain Products GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
EEG and EMG Equipment Market Strategic Shifts & Innovations
Wireless dry-electrode systems and edge-computing architectures are dissolving the boundary between clinical-grade and consumer neurotechnology, forcing established manufacturers to defend diagnostic fidelity claims against lower-cost entrants while pursuing new form factors.
Dry-electrode EEG headsets with active impedance compensation are decomposing the traditional wet-electrode preparation workflow that required skilled technicians and conductive gel application. Hospital outpatient neurology clinics and pharmaceutical trial sites are piloting these systems for rapid screening protocols. The technology is decomposing the service-revenue model tied to electrode placement labor, compressing per-study costs while expanding throughput capacity.
The EU MDR's Annex I general safety and performance requirements for active implantable and diagnostic devices are mandating expanded clinical evidence for neurophysiology software updates. Manufacturers must now submit technical documentation for algorithm modifications that previously qualified as routine maintenance. This regulatory friction most acutely affects multi-jurisdiction operators maintaining parallel FDA 510(k) and CE-marked product lines, driving consolidation of software release cycles.
Hospital procurement departments are unbundling hardware acquisition from multiyear service contracts that historically bundled calibration, electrode supply, and clinical training. Group purchasing organizations and integrated delivery networks in the United States are negotiating direct electrode sourcing and third-party preventive maintenance, pressuring manufacturer attach rates. This disintermediation is most visible in California and Texas health systems where capital budget autonomy has shifted to regional supply chain executives.
EEG and EMG Equipment Market Segmentation
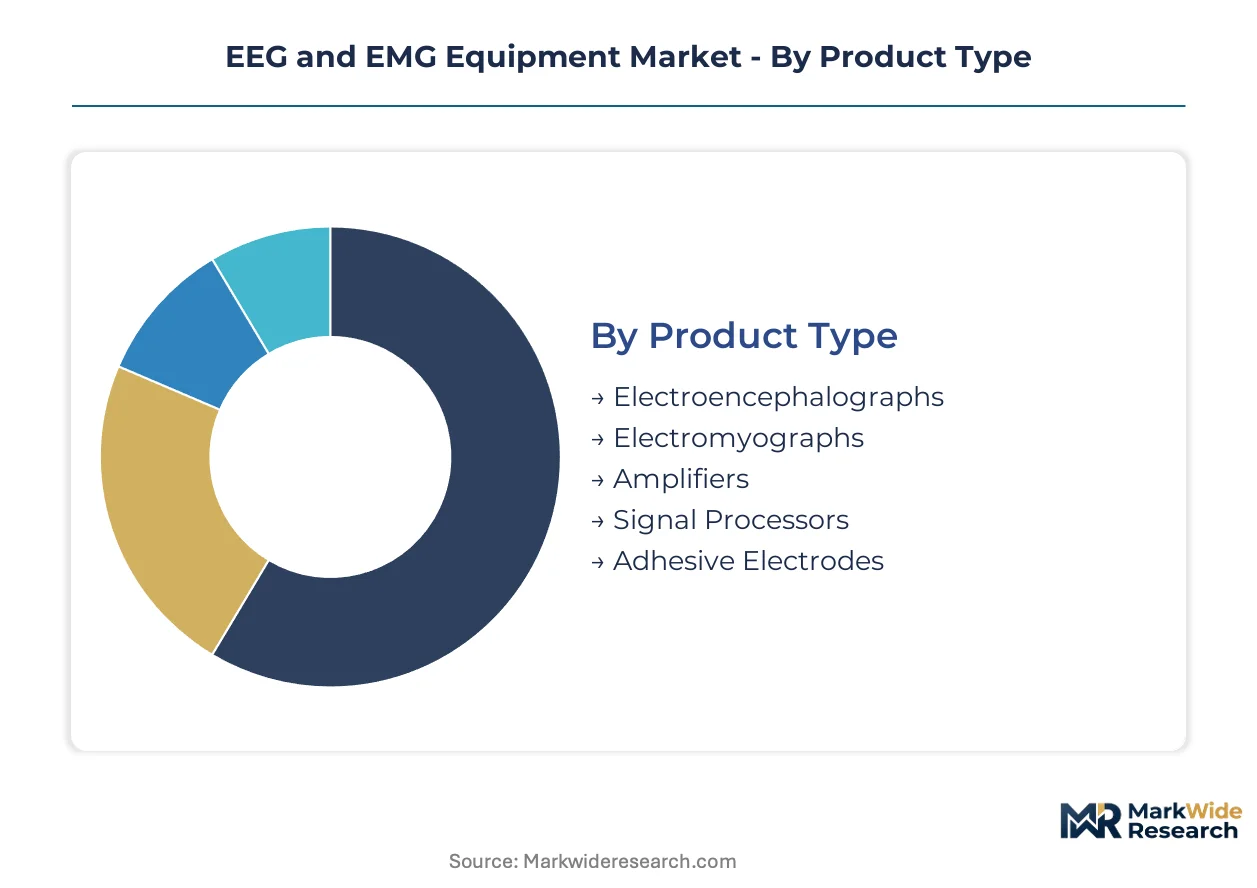
Segmentation in EEG and EMG equipment reveals how technological substitution pressures reshape procurement priorities across clinical and research settings. Understanding these divides exposes where hardware-software bundling persists and where unbundling accelerates competitive displacement.
Product Type:
Substitution pressure from wireless telemetry and cloud-native analytics most intensely threatens standalone amplifiers and signal processors, which face disintermediation by integrated platform vendors.
- Electroencephalographs:Multi-channel bioelectrical recording systems with 16–256 channel configurations and 16–24 bit resolution capture cortical activity through scalp electrodes. Hospital neurology departments in Germany and the United States concentrate procurement for epilepsy monitoring units, driven by surgical candidacy assessment backlogs and reimbursement clarity for long-term video-EEG.
- Electromyographs:Instruments measuring muscle electrical activity via needle or surface electrodes, with typical bandwidth of 10 Hz–10 kHz for motor unit potential detection. Demand clusters in Japanese diagnostic laboratories and US rehabilitation centers, constrained by clinical neurophysiologist staffing shortages that limit service expansion.
- Amplifiers:Isolated instrumentation amplifiers with high common-mode rejection ratio for microvolt-level signal conditioning.
- Signal Processors:Digital filtering and artifact rejection modules for real-time waveform analysis.
- Adhesive Electrodes:Silver-silver chloride disposable electrodes for stable skin-electrode impedance.
Electroencephalographs anchor the volume base while wireless-enabled portable systems gain share at the steepest rate.
Application:
Cost tier stratification separates high-acuity hospital diagnostics from emerging home-based monitoring segments with divergent reimbursement pathways.
- Neurological Diagnostics:Epilepsy, stroke, and encephalopathy detection protocols requiring high-density montages and trained interpretation. Academic medical centers in Japan and Germany drive capital deployment, supported by national dementia strategies and aging demographics.
- Sleep Studies:Nocturnal EEG and EMG recording for parasomnia and sleep-disordered breathing assessment. US cardiology and pulmonology practices expand ambulatory deployment as CMS extends remote patient monitoring codes beyond traditional sleep lab settings.
- Rehabilitation Monitoring:Neuroplasticity tracking during post-stroke motor recovery protocols.
- Muscle Disorder Evaluation:Neuromuscular junction and myopathy diagnostic protocols in specialist clinics.
- Brain-Computer Interface:Research-grade high-density arrays for motor prosthesis development funded by DARPA and NIH programs.
Neurological diagnostics commands the largest revenue pool while brain-computer interface applications expand most quickly through non-clinical research funding.
End User:
Customer type fragmentation reflects divergent procurement autonomy between integrated delivery networks and independent diagnostic operators.
- Hospital Neurology Departments:Inpatient and outpatient units with 24-hour video-EEG monitoring capability. German university hospitals and US academic medical centers lead capital investment, pressured by EU MDR compliance deadlines to upgrade legacy systems.
- Diagnostic Laboratories:Independent and hospital-affiliated facilities processing referred neurophysiology studies. Japanese laboratory chains exploit dominant channel control for bundled electrode and service contracts.
- Rehabilitation Centers:Post-acute facilities tracking neuromuscular recovery outcomes.
- Research Institutes:Academic and government laboratories procuring high-channel-count systems for neurotechnology development.
- Neurodiagnostic Clinics:Specialized outpatient facilities focusing on epilepsy and sleep disorder evaluation.
Hospital neurology departments anchor the volume base while research institutes climb the fastest on federal neurotechnology program funding.
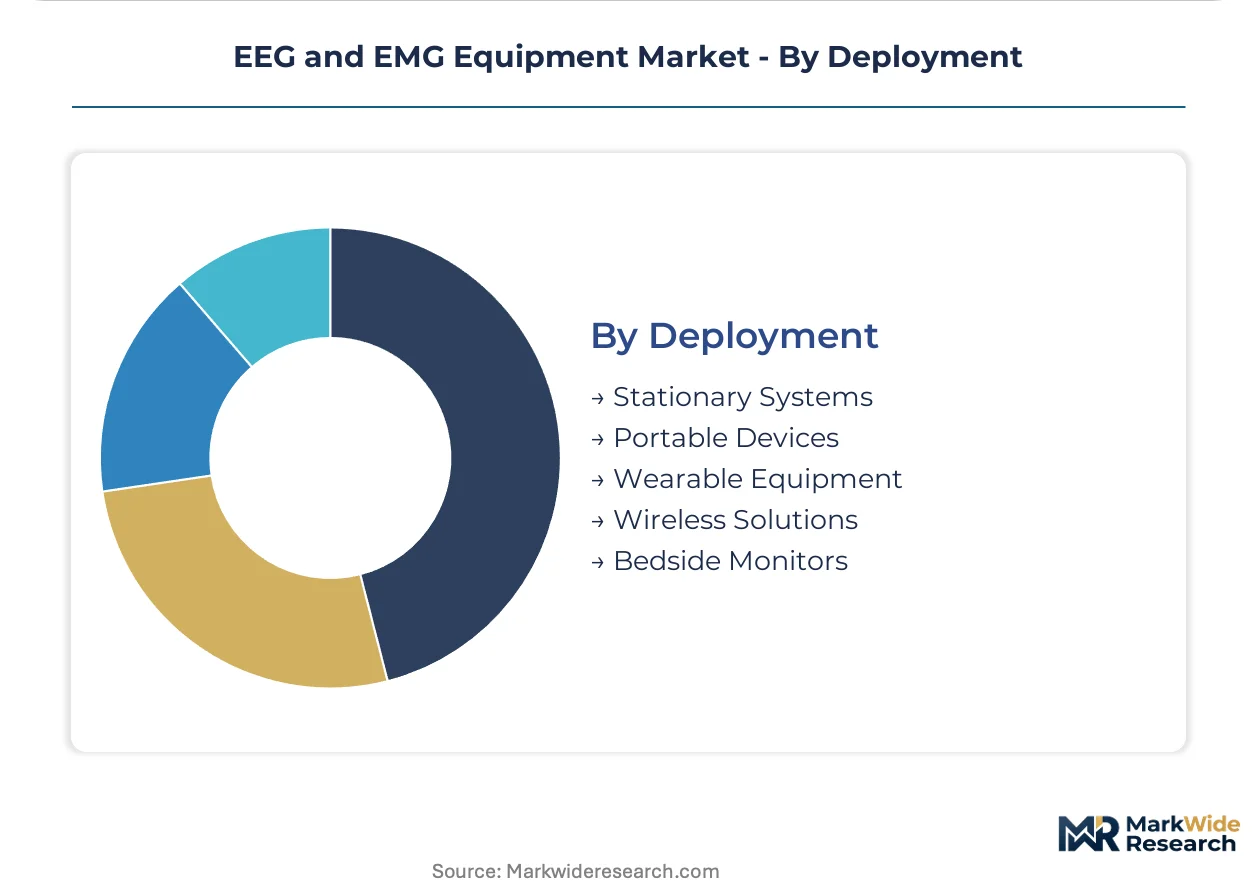
Deployment:
Supply concentration in East Asian semiconductor fabrication constrains amplifier availability for wireless and wearable form factors.
- Stationary Systems:Cart-mounted or fixed-installation units with full-channel capability and wired electrode arrays. German epilepsy monitoring units and Japanese hospital neurology departments maintain installed base, though procurement cycles lengthen as facilities evaluate wireless migration paths.
- Wireless Solutions:Bluetooth or proprietary RF telemetry systems enabling patient mobility during long-term monitoring. US ambulatory EEG providers deploy these systems aggressively as CMS reimbursement codes stabilize, despite motion artifact challenges in non-clinical environments.
- Portable Devices:Battery-operated compact units for bedside or transportable diagnostics.
- Wearable Equipment:Dry-electrode headsets and EMG armbands for continuous monitoring.
- Bedside Monitors:ICU-integrated systems for perioperative neurophysiological monitoring.
Stationary systems anchor the volume base while wireless solutions gain share at the steepest rate on remote patient reimbursement expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in EEG and EMG equipment tilt toward import-dependent markets with aging demographics, while manufacturing concentrates in economies with precision electronics clusters. Reimbursement clarity and regulatory harmonization determine where capital deployment accelerates.
United States
Hospital neurology departments in Boston and Houston expand long-term video-EEG capacity for surgical candidacy assessments. FDA 510(k) pathways for neurodiagnostic software are tightening validation requirements ahead of anticipated AI-enhanced waveform classification rulings. The Greater Boston medical technology corridor anchors domestic demand for high-density EEG arrays in academic medical centers.
Germany
University hospitals in Bavaria and North Rhine-Westphalia upgrade legacy systems ahead of EU MDR compliance deadlines for active diagnostic devices. The country's national medical device regulator enforces expanded clinical evidence requirements for software updates that previously qualified as routine maintenance. The Munich-Stuttgart industrial corridor hosts precision amplifier component suppliers serving domestic manufacturers.
Japan
Diagnostic laboratory chains in Tokyo and Osaka exploit dominant channel control for bundled electrode and service contracts. METI reimbursement frameworks for remote patient monitoring are stabilizing codes for ambulatory EEG deployment. The Kansai region concentrates manufacturing of isolated instrumentation amplifiers for export markets.
United Kingdom
NHS neurology trusts in London and Manchester pilot dry-electrode EEG headsets for rapid outpatient screening protocols. MHRA post-Brexit regulatory alignment with EU MDR technical documentation requirements is extending product development timelines. The Oxford-Cambridge arc attracts DARPA and NIH-funded brain-computer interface research procurement.
China
Provincial hospital networks in Shanghai and Beijing deploy portable EMG systems for rehabilitation monitoring in tier-two cities. NMPA medical device registration pathways are harmonizing with international electrical safety benchmarks for critical care amplifiers. The Yangtze River Delta semiconductor fabrication cluster constrains supply continuity for precision analog-to-digital converters.
EEG and EMG Equipment Market Key Industry Players
Concentration sits with diversified medical technology conglomerates that bundle neurodiagnostic hardware with surgical navigation and neurostimulation platforms. The vendor base stratifies across three tiers: integrated hospital system suppliers, specialized ambulatory monitoring firms, and research-grade instrumentation specialists. Dominant competitive moves include backward integration into electrode consumable manufacturing and strategic partnerships with cloud-native analytics vendors.
Among diversified medical technology conglomerates, Medtronic Plc and Koninklijke Philips N.V. exemplify the integrated platform archetype that bundles hardware with broader perioperative monitoring ecosystems. Nihon Kohden Corporation occupies a position within the regional channel control archetype, anchoring procurement relationships in Japanese diagnostic laboratories. Cadwell Industries Inc. represents the specialized ambulatory monitoring tier, with organizational structure suggesting concentrated focus on sleep study and home-based monitoring applications.
| Leading Market Players |
|---|
| Medtronic Plc |
| Koninklijke Philips N.V. |
| General Electric Company |
| Natus Medical Incorporated |
| Nihon Kohden Corporation |
| Cadwell Industries Inc. |
| Masimo Corporation |
| Compumedics Limited |
| Brain Products GmbH |
| Others |
Cost & Logistics Intelligence
Long-term electrode supply contracts with silver-silver chloride price hedging clauses lock in both consumable access and margin visibility for hospital neurology departments and diagnostic laboratory chains across Germany, Japan, and the United States. These arrangements insulate high-volume operators from precious metal volatility while compressing pricing power for standalone electrode manufacturers lacking backward integration into conductive material refining.
Pricing Analysis
Hospital purchasing committees anchor three-tier pricing structure across premium, standard, and economy levels in EEG and EMG equipment procurement. FDA 510(k) clearance tier and ISO 13485 certification status drive price differentiation between integrated platform vendors and specialized ambulatory monitoring firms. Cost compression in wireless telemetry hardware is intensifying because semiconductor component shortages constrain amplifier availability. Independent diagnostic laboratories exhibit highest price sensitivity due to reimbursement pressure, while academic medical centers prioritize signal fidelity over unit economics.
Supply Chain Analysis
East Asian semiconductor fabrication chokepoints in Taiwan and South Korea underwrite precision analog-to-digital converter availability for clinical-grade amplifiers. Silver-silver chloride electrode production draws from Japanese and German precious metal refiners, while disposable adhesive manufacturing rests on Malaysian and Chinese polymer converters. Single-source vulnerability concentrates in isolated instrumentation amplifier chipsets. Distribution runs through group purchasing organizations and integrated delivery networks that unbundle hardware from multiyear service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EEG and EMG equipment market sits at an inflection where EU MDR software validation mandates and CMS reimbursement expansion for remote patient monitoring are simultaneously accelerating procurement cycles and compressing legacy margin structures. This dual-force environment rewards operators who can navigate regulatory friction while capturing ambulatory deployment growth.
For Market Incumbents: Secure captive electrode manufacturing capabilities to defend against silver price volatility and consumable margin erosion. Consolidate software release cycles across FDA 510(k) and CE-marked product lines to reduce EU MDR compliance overhead. Channel control in Japanese diagnostic laboratories represents a defensible moat against wireless platform entrants. For New Entrants and Emerging Players: FDA breakthrough device designation fast-tracks market access for AI-enhanced seizure detection algorithms, opening white-space in automated waveform classification. Home sleep apnea testing extension to nocturnal seizure monitoring offers the most penetrable reimbursement pathway. Target cardiology and pulmonology practices with dry-electrode screening protocols that eliminate skilled technician dependencies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among ambulatory EEG providers with established CMS coverage codes and patient monitoring subscriptions. Long-term viability favors operators with demonstrated compliance navigation across multi-jurisdiction regulatory frameworks. Watch FDA software-as-medical-device reclassification precedents as the critical inflection signal for AI-enhanced diagnostic algorithm valuations.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Completion | Accelerates hospital procurement cycles ahead of compliance deadlines in German university hospitals. |
| CMS Reimbursement Strategy Development | Unlocks capital deployment into wireless monitoring infrastructure across US ambulatory providers. |
| Cloud-Native Analytics Platform Integration | Enables subscription-based diagnostics that unbundle software from hardware acquisition. |
| Backward Integration into Electrode Manufacturing | Insulates margins from silver-silver chloride price volatility in high-volume disposable operations. |
| Brain-Computer Interface Research Partnership | Captures DARPA and NIH-funded procurement outside clinical diagnostics revenue pools. |
Research Approach
Operator-level perspectives from hospital neurology department heads, diagnostic laboratory procurement managers, biomedical engineers, and clinical neurophysiologists anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) clearance databases, EU MDR technical documentation filings, CMS Medicare reimbursement code updates, and hospital GPO contract records. Bottom-up equipment shipment estimates and top-down healthcare capital expenditure patterns were triangulated to constrain forecast variance.
Sensitivity analysis tested forecast robustness across alternative reimbursement adoption curves and semiconductor supply continuity scenarios throughout the projection horizon. Segmentation dimensions modeled include product type, deployment configuration, end-user facility type, and regional regulatory cluster. CAGRs were derived from installed base growth rates and replacement cycle dynamics. Forecast inputs incorporated EU MDR compliance deadline impacts and CMS remote patient monitoring code expansion trajectories.
Decision-makers should treat outputs as directional under stable reimbursement policy and supply continuity assumptions; material deviation in FDA software classification precedents or East Asian semiconductor export restrictions would warrant model refresh. Practitioners should keep alternative scenarios live as AI-enhanced diagnostic algorithm regulatory pathways and silver commodity price trajectories evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
On-Body Drug Delivery Devices Market
Medical Devices
Surgical Robotics Performance and Safety Validation Test Platforms Market
Medical Devices
South Africa Aesthetic Devices Market
Medical Devices
Catheter Securement Devices Market
Medical Devices
Contrast Injection Lines Market
Medical Devices
MRI-Compatible IV Infusion Pump Systems Market
Medical Devices
Artificial Eye Lenses Market
Medical Devices
Global Orthopedic Power Tools Market
Medical Devices
Mandibular Advancement Devices Market
Medical Devices
Organ Care Market
Medical Devices
Intravascular Ultrasound [IVUS] Devices Market
Medical Devices
Medication Management System Market
Medical Devices
Medical Laser Cutting Device Market
Medical Devices
EEG Electrodes Market
Medical Devices
North America Non-Surgical Procedures Market
Medical Devices
Healthcare Additive Manufacturing Market