
 South America Digital X-Ray Devices Market | 2026-2036
South America Digital X-Ray Devices Market Size, Share, and Industry Trends Forecast 2026-2036
South America Digital X-Ray Devices Market Analytics
The transition from analog to fully digital detector technology is narrowing the performance gap between premium and mid-tier equipment across South America. Siemens Healthineers leverages its regional service infrastructure to sustain long-term contracts with major hospital chains. GE Healthcare anchors its position through localized manufacturing partnerships that reduce import dependency. Fujifilm Holdings Corporation differentiates by specializing in compact digital radiography units tailored for outpatient clinics with space constraints.
Digital X-ray devices capture ionizing radiation through solid-state detectors and convert it into high-resolution electronic images for diagnostic interpretation, with flat panel detector systems achieving spatial resolution exceeding 3.5 line pairs per millimeter. Their primary commercial purpose centers on rapid, repeatable anatomical imaging with minimal radiation exposure compared to legacy film-based methods. Portable X-Ray Systems command expanding share as point-of-care diagnostics gain traction in remote and rural settings across the Andean region. Hospitals represent the most entrenched end user segment, though diagnostic imaging centers are capturing faster growth due to decentralized healthcare policies in Brazil and Argentina.
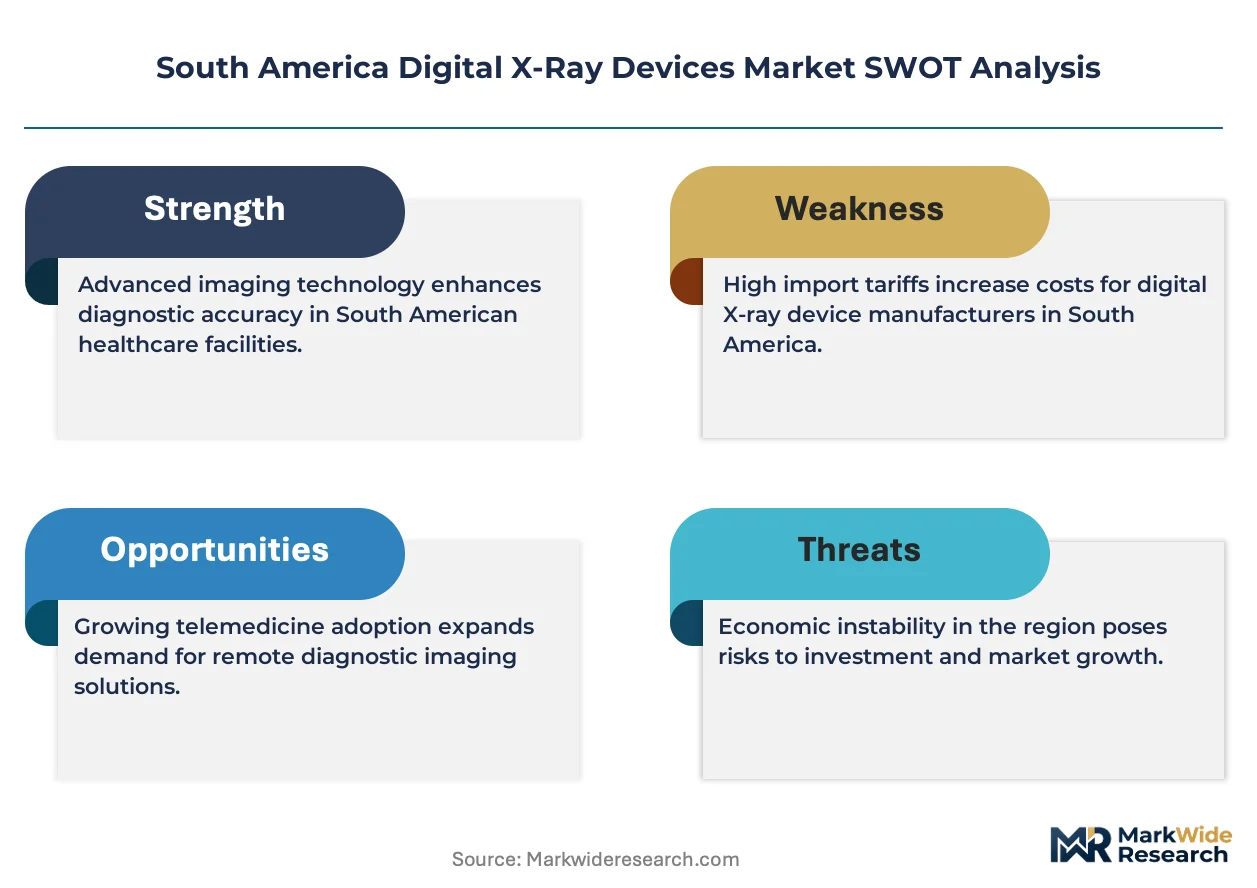
ANVISA governs medical device registration and post-market surveillance in Brazil, while Argentina's national pharmaceutical regulator oversees import licensing and clinical safety standards for radiological equipment. These frameworks shape demand by mandating software traceability, cybersecurity protocols, and periodic calibration reporting that favor established suppliers with dedicated regulatory affairs teams. Stakeholders must monitor evolving radiation safety ordinances and reimbursement code updates that determine which digital modalities qualify for public procurement programs.
Market Dynamics
Flat panel detector technology is compressing equipment replacement cycles across South American healthcare networks, forcing radiology departments to retire analog systems faster than capital budgeting traditionally permits. Brazil's public hospital modernization mandates are accelerating this structural transition.
Growth Catalysts
- ANVISA streamlined registration pathways:Brazil's medical device regulator has reduced approval timelines for digital radiography systems, enabling faster market entry for international equipment suppliers.
- Diagnostic imaging center expansion:Decentralized healthcare policies in Argentina and Colombia are driving construction of outpatient imaging facilities requiring compact digital X-ray units.
- Flat panel detector performance convergence:Solid-state detector technology has narrowed image quality gaps between premium and mid-tier equipment, expanding addressable demand.
Market Restraints
- Import dependency for core components:Detector panels and high-voltage generators concentrate supply in East Asian manufacturing clusters, exposing buyers to currency volatility and shipping disruptions.
- Radiation safety ordinance compliance costs:Periodic calibration reporting and software traceability mandates under ANVISA and Argentina's national pharmaceutical regulator impose recurring operational burdens on smaller clinics.
- Limited domestic technical service capacity:Brazil and Argentina lack sufficient trained biomedical engineers to support rapid installation and maintenance scaling.
Strategic Opportunities
- Andean region point-of-care penetration:Portable X-ray systems remain underdeployed in rural Peru, Bolivia, and Ecuador where terrain limits fixed-site infrastructure.
- Cybersecurity protocol premiumization:ANVISA's emerging cybersecurity requirements for connected medical devices create differentiation space for suppliers with hardened software architectures.
- Artificial intelligence integration:Convergence of machine learning diagnostic assistance with digital radiography hardware offers workflow automation in understaffed public hospitals.
Industry Challenges
- Biomedical engineering talent scarcity:Brazil's technical institutes produce insufficient graduates trained in digital detector calibration and DICOM networking protocols.
- Legacy PACS integration complexity:Hospital information systems in Argentina and Colombia run heterogeneous software generations that resist seamless connectivity with new digital radiography suites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Digital X-Ray Devices Market |
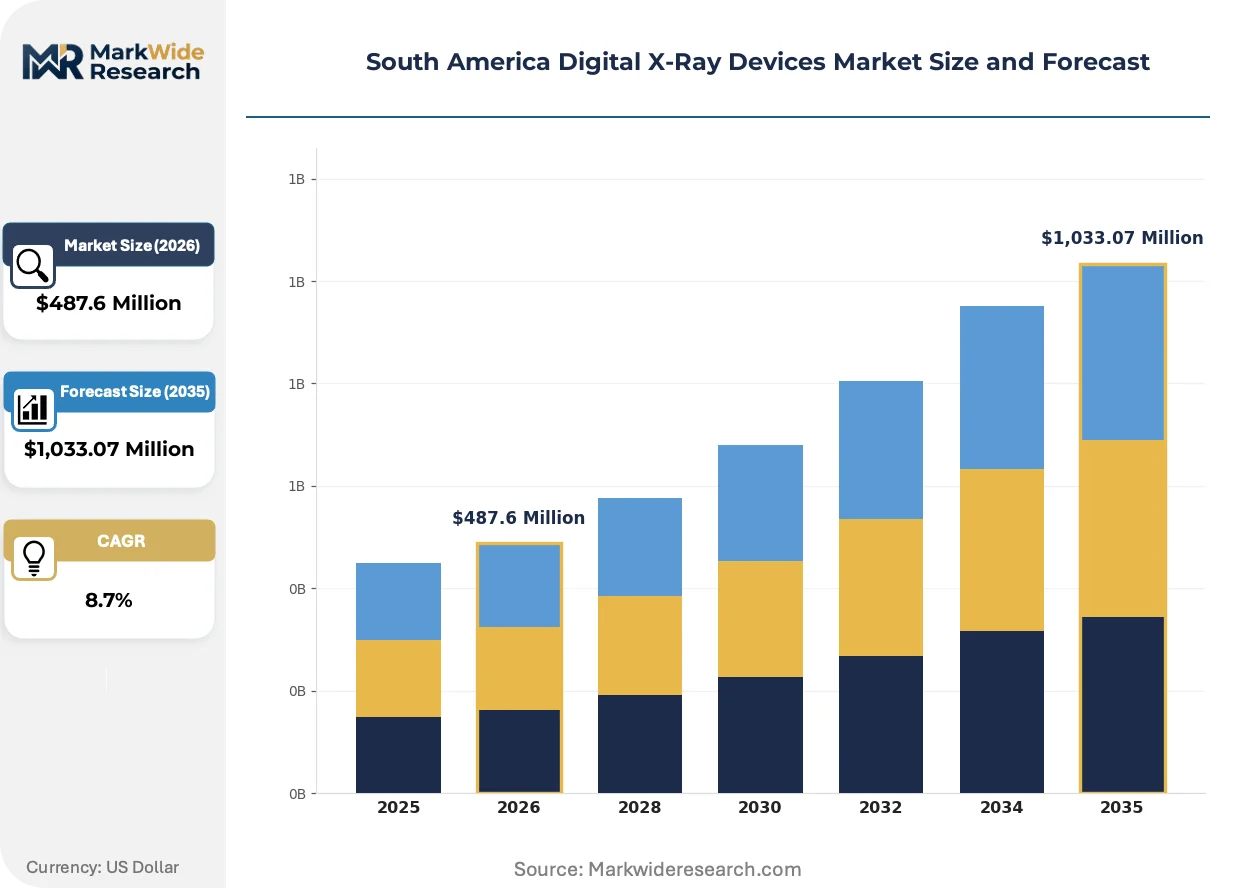
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable X-Ray Systems, Fixed X-Ray Systems, Mobile X-Ray Units, Digital Fluoroscopy Systems End User: Hospitals, Diagnostic Imaging Centers, Outpatient Facilities, Research Institutions Technology: Flat Panel Detectors, Computed Radiography, Digital Radiography, Screen-Film Radiography Application: Pediatrics, Orthopedics, Oncology, Cardiovascular |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips NV, Canon Medical Systems Corporation, Fujifilm Holdings Corporation, Shimadzu Corporation, Agfa-Gevaert Group, Carestream Health, Hitachi Ltd, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Digital X-Ray Devices Market Evolving Landscape
Wireless detector technology is dismantling fixed-room radiography economics across South American outpatient networks. Three developments are compressing traditional equipment deployment models.
Wireless flat panel detectors eliminate tethered cabling between X-ray tube assemblies and image receptors, enabling single-detector mobility across multiple examination rooms. Diagnostic imaging centers in São Paulo and Buenos Aires are adopting these systems to maximize equipment utilization rates. Fixed-room analog installations are rendering obsolete as outpatient facilities prioritize floorplan flexibility over dedicated radiography suites.
ANVISA's updated software traceability requirements for Class III medical devices mandate version-controlled firmware documentation and post-market cybersecurity monitoring. Equipment suppliers must now maintain dedicated regulatory affairs teams capable of real-time incident reporting. Brazil's public hospital procurement programs are screening tenders for compliance depth, favoring vendors with established local certification infrastructure.
Service contract unbundling is separating hardware acquisition from maintenance and software subscription components. Large hospital chains in Brazil are negotiating direct detector calibration and tube replacement agreements with third-party biomedical service firms. Colombia's diagnostic imaging center segment exhibits the most aggressive disaggregation, with buyers sourcing equipment, installation, and ongoing support from distinct vendors to optimize capital allocation.
South America Digital X-Ray Devices Market Segmentation
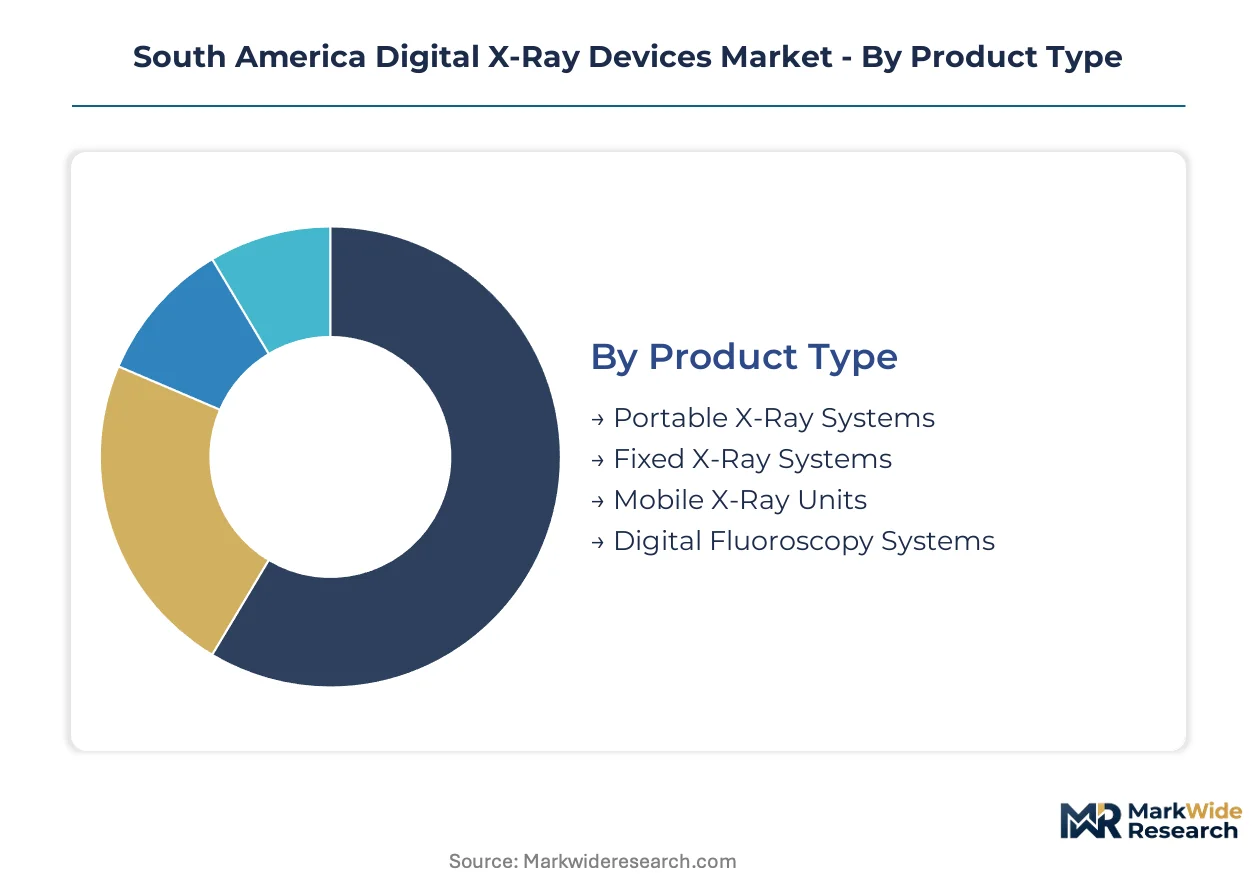
Equipment replacement cycles and procurement priorities differ sharply across digital X-ray modalities in South America. Understanding segment-specific turnover rates enables suppliers to align inventory and service deployment with actual purchasing rhythms.
Product Type:
Fixed X-ray systems endure the longest replacement cycles while portable configurations refresh most rapidly due to mechanical wear and battery degradation.
- Portable X-Ray Systems:Battery-powered mobile units with wireless detector connectivity enable bedside and field imaging. Demand concentrates in Brazil's interior municipalities where road infrastructure limits patient transport to centralized hospitals. ANVISA's streamlined registration for Class II portable devices accelerates procurement timelines for municipal health departments.
- Fixed X-Ray Systems:Ceiling-suspended or floor-mounted installations with integrated generator-tube assemblies deliver high-throughput screening. Brazil's public hospital modernization mandates drive replacement of analog fixed rooms in state-run facilities across São Paulo and Minas Gerais.
- Mobile X-Ray Units:Motorized cart-based systems bridge fixed and portable applications with onboard power generation. Diagnostic imaging centers in Buenos Aires deploy these for multi-room flexibility without construction costs.
- Digital Fluoroscopy Systems:Real-time imaging platforms with pulsed X-ray generation for dynamic studies. Cardiology departments in Colombia's private hospital networks represent the primary uptake channel.
Fixed X-ray systems anchor the volume base while portable X-ray systems gain share at the steepest rate.
End User:
Capital allocation patterns separate institutional buyers with depreciated equipment bases from emerging purchasers building first-time digital capabilities.
- Hospitals:Integrated acute-care facilities with 24-hour radiology departments and PACS infrastructure. Brazil's SUS-funded hospital networks in the Northeast region prioritize detector upgrades over full system replacement.
- Diagnostic Imaging Centers:Specialized outpatient facilities delivering elective imaging services with volume-based revenue models. Argentina's decentralized healthcare policies license independent imaging centers in Córdoba and Rosario at accelerating rates.
- Outpatient Facilities:Primary care clinics and specialty practices with limited radiology footprints. Compact digital radiography units serve orthopedic and urgent care clinics in Chile's Santiago metropolitan area.
- Research Institutions:Academic medical centers and clinical trial sites requiring calibrated imaging for protocol compliance. São Paulo's university hospitals drive demand for high-resolution detector specifications.
Hospitals dominate installed base value while diagnostic imaging centers expand their share of annual procurement most aggressively.
Technology:
Detector architecture determines image acquisition speed, dose efficiency, and total cost of ownership across South American price-sensitive procurement environments.
- Flat Panel Detectors:Direct-conversion amorphous selenium or indirect-conversion cesium iodide scintillator arrays achieving sub-second readout. Brazil's diagnostic imaging center segment standardizes on wireless flat panel configurations for room-sharing efficiency.
- Computed Radiography:Photostimulable phosphor plate systems requiring mechanical scanning for digital conversion. Smaller municipal hospitals in Peru's Andean region retain CR for capital cost containment.
- Digital Radiography:Integrated detector-and-generator architectures with automated exposure control. Argentina's public hospital tenders specify DR compliance for filmless operation mandates.
- Screen-Film Radiography:Analog cassette-based systems with chemical processing dependency. Legacy installations persist in Bolivia's rural health posts with limited electricity reliability.
Flat panel detectors command the revenue concentration while digital radiography configurations climb the fastest in unit terms.
Application:
Clinical imaging requirements vary by anatomical target, patient population, and throughput demands across South American healthcare settings.
- Orthopedics:Weight-bearing extremity and spinal imaging with high spatial resolution requirements. Sports medicine clinics in Colombia's major cities drive demand for dedicated extremity radiography systems.
- Cardiovascular:Angiographic and interventional imaging with rapid frame-rate capabilities. Brazil's private hospital cardiology departments in Rio de Janeiro and Brasília invest in digital fluoroscopy suites.
- Oncology:Staging and treatment response monitoring with low-dose repeatability protocols. Argentina's cancer institute network standardizes on digital radiography for chest surveillance imaging.
- Pediatrics:Size-adaptive exposure protocols and motion-tolerant acquisition for non-cooperative patients. Maternal-child hospitals in Chile's public system specify pediatric-optimized detector calibration.
Orthopedics generates the procedure volume foundation while cardiovascular applications deliver the highest equipment value per installation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil exports digital radiography systems to Argentina and Colombia while importing detector panels from East Asian manufacturing clusters. This trade-flow configuration concentrates procurement decision-making in São Paulo and Rio de Janeiro hospital networks.
Brazil
ANVISA's streamlined Class III device registration accelerates procurement timelines for municipal health departments. The SUS-funded hospital modernization program targets state-run facilities across the Northeast region for detector upgrades. São Paulo's diagnostic imaging center segment leads adoption of wireless flat panel configurations for room-sharing efficiency.
Argentina
Decentralized healthcare policies license independent imaging centers in Córdoba and Rosario at accelerating rates. The national pharmaceutical regulator mandates filmless operation compliance for public hospital tenders. Buenos Aires hospital chains negotiate unbundled service contracts separating hardware acquisition from maintenance agreements.
Colombia
Private hospital cardiology departments in Bogotá invest in digital fluoroscopy suites for interventional procedures. The national health regulator enforces radiation safety ordinances with periodic calibration reporting requirements. Medellín's diagnostic imaging center segment exhibits aggressive procurement disaggregation across equipment, installation, and support vendors.
Chile
Orthopedic and urgent care clinics in the Santiago metropolitan area specify compact digital radiography units. The national medical device authority aligns with international standards for cybersecurity protocol implementation. University hospitals in the capital drive demand for high-resolution detector specifications in research applications.
Peru
Andean region municipalities deploy portable X-ray systems where terrain limits fixed-site infrastructure development. The national health ministry prioritizes point-of-care diagnostics in rural provinces with unreliable electricity. Lima's private diagnostic chains source mobile cart-based systems for multi-room flexibility without construction investment.
South America Digital X-Ray Devices Market Competitive Landscape
On the supply side, the industry is consolidated around multinational imaging equipment manufacturers with established regional service infrastructures. Three strategic archetypes dominate: integrated healthcare conglomerates with localized manufacturing partnerships, specialized radiography equipment vendors with compact system portfolios, and diversified industrial technology groups with medical imaging divisions. Competitive positioning hinges on regulatory certification depth and long-term service contract penetration rather than hardware pricing alone.
Within the integrated healthcare conglomerate tier, GE Healthcare and Siemens Healthineers anchor market presence through sustained contracts with major hospital chains. Fujifilm Holdings Corporation occupies a distinct position among specialized vendors, exemplifying the compact equipment archetype tailored for space-constrained outpatient environments. Koninklijke Philips NV represents the diversified technology group model with cross-modal imaging portfolios. These three companies collectively illustrate how supplier positioning stratifies across service infrastructure depth, product specialization, and portfolio breadth.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips NV |
| Canon Medical Systems Corporation |
| Fujifilm Holdings Corporation |
| Shimadzu Corporation |
| Agfa-Gevaert Group |
| Carestream Health |
| Hitachi Ltd |
| Others |
Value Network & Pricing Analysis
East Asian manufacturing clusters for amorphous selenium detector panels and high-voltage generators concentrate upstream supply, anchoring margin pools with equipment integrators who control ANVISA certification infrastructure and long-term service contracts in São Paulo and Rio de Janeiro hospital networks.
Pricing Analysis
Current-generation wireless flat panel detectors command substantial premiums against prior-generation tethered systems and next-generation AI-integrated configurations still awaiting regulatory clearance. Pricing stratifies across premium, standard, and economy tiers based on detector resolution specifications and after-sales service bundling depth. Cost compression in mid-tier equipment is intensifying because Brazilian diagnostic imaging centers disaggregate procurement across hardware, installation, and maintenance vendors. Municipal health departments in Brazil's interior exhibit the highest price sensitivity, while private hospital cardiology departments in Colombia absorb premium pricing for digital fluoroscopy suites.
Supply Chain Analysis
Contract manufacturing for flat panel detector arrays concentrates with specialized electronics manufacturing service providers in South Korea, Japan, and Taiwan. Amorphous selenium deposition equipment, cesium iodide scintillator crystals, and high-voltage generator assemblies feed from these East Asian production hubs. Single-source vulnerability for detector panel substrates exposes Brazilian assemblers to shipping disruption through the Panama Canal logistics chokepoint. Distribution runs through authorized distributor networks with ANVISA-certified technical service capabilities rather than direct manufacturer-to-hospital sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ANVISA's streamlined Class III device registration and emerging cybersecurity mandates are compressing competitive windows, rewarding suppliers with pre-positioned regulatory affairs teams and hardened software architectures.
For Market Incumbents: Entrench service contract penetration by acquiring third-party biomedical calibration firms in São Paulo and Minas Gerais, countering the unbundling threat from diagnostic imaging centers. Deepen backward integration into detector panel refurbishment capabilities to capture recurring revenue streams as hardware margins compress across Brazil's public hospital modernization program.
For New Entrants and Emerging Players: Establish a beachhead in Peru's Andean region portable X-ray segment, where terrain-constrained municipalities lack incumbent service infrastructure. Prioritize ANVISA Class II registration for battery-powered wireless systems, leveraging accelerated approval timelines against fixed-room competitors. Target direct municipal procurement channels with simplified maintenance training programs addressing Brazil's biomedical engineering talent scarcity.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic imaging center rollups in Argentina's Córdoba and Rosario markets, where decentralized healthcare licensing creates consolidation opportunities. Favor targets with established cybersecurity protocol documentation ahead of ANVISA's connected device requirements. Monitor quarterly procurement disclosure from Brazil's SUS-funded hospital networks as the inflection indicator for detector upgrade cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Cybersecurity Certification | Pre-positions suppliers for connected device mandates before competitors complete compliance documentation. |
| Wireless Detector Portfolio Expansion | Captures diagnostic imaging center demand for room-sharing efficiency in São Paulo and Buenos Aires. |
| Biomedical Engineer Training Partnership | Addresses installation and maintenance scaling constraints across Brazil's state-run hospital networks. |
| Third-Party Service Firm Acquisition | Defends against procurement disaggregation by controlling calibration and tube replacement revenue streams. |
| Andean Region Distribution Buildout | Establishes point-of-care presence in rural Peru, Bolivia, and Ecuador ahead of infrastructure investment. |
Research Methodology
Desk research of ANVISA registration databases, hospital procurement records, and medical device trade flow statistics preceded structured interviews with biomedical engineering directors, diagnostic imaging center operators, GPO contracts managers, and regulatory affairs specialists across Brazil, Argentina, and Colombia. Primary fieldwork with equipment installers and maintenance technicians validated secondary data on replacement cycle timing and service contract structures. Bottom-up unit shipment estimates by detector technology and end-user segment were triangulated against top-down market value reconstructions from import customs data and manufacturer revenue disclosures.
Assumptions held fixed include ANVISA's current Class III registration timelines and Brazil's SUS hospital modernization funding levels, while detector technology substitution rates and cybersecurity compliance cost trajectories were varied across sensitivity scenarios. Segmentation modeling incorporated product type, end-user category, detector technology architecture, and application area dimensions. CAGRs were derived from logistic diffusion curves fitted to analog-to-digital transition patterns observed in prior radiography equipment upgrade cycles, with explicit inputs for public health infrastructure budget elasticity and decentralized healthcare policy implementation pace.
Sensitivities concentrate around ANVISA registration pathway revisions, Brazilian real currency volatility affecting import-dependent equipment pricing, and radiation safety ordinance amendments altering calibration reporting burdens. Forecasts reflect documented assumptions regarding technology transition speed and regulatory enforcement intensity. Quarterly review of SUS procurement announcements, ANVISA cybersecurity guideline updates, and biomedical engineering graduate pipeline data from Brazilian technical institutes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
France Computed Tomography Market
Medical Imaging
Japan Magnetic Resonance Imaging Market
Medical Imaging
Global Stroke Post Processing Software Market
Medical Imaging
Global Pediatric Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Dermatology Imaging Market
Medical Imaging
United States Nuclear Imaging Market
Medical Imaging
Mexico Diagnostic Imaging Equipment Market
Medical Imaging
Veterinary Computed Tomography Scanner Market
Medical Imaging
Contrast Media Market
Medical Imaging
Global Single-Photon Emission Computed Tomography (SPECT) Market
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
Australia Computed Tomography Market
Medical Imaging
Global Digital Radiography Market
Medical Imaging
Global Technetium-99M Market