
 Portable Ultrasound Devices Market | 2026-2036
Portable Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Portable Ultrasound Devices Market Intelligence
Increased manufacturing capacity in China is narrowing the price gap between established and emerging device manufacturers. GE Healthcare leverages its extensive hospital network to deploy cart-based and handheld systems. Philips Healthcare differentiates through advanced imaging software and integration with its broader digital health ecosystem. Butterfly Network specializes in semiconductor-based, single-probe whole-body imaging technology, targeting individual practitioners and smaller clinics.
Portable ultrasound devices are compact, battery-operated medical imaging systems that use high-frequency sound waves, typically from 2 to 18 megahertz, to create real-time images of internal body structures. Their primary purpose is to provide rapid, non-invasive diagnostic capabilities at the point of care, outside of traditional radiology departments. Handheld devices represent the fastest-growing product type, driven by their affordability and ease of use in emergency medicine. Within applications, cardiology and obstetrics remain high-value segments, while diagnostic use in primary care is expanding.
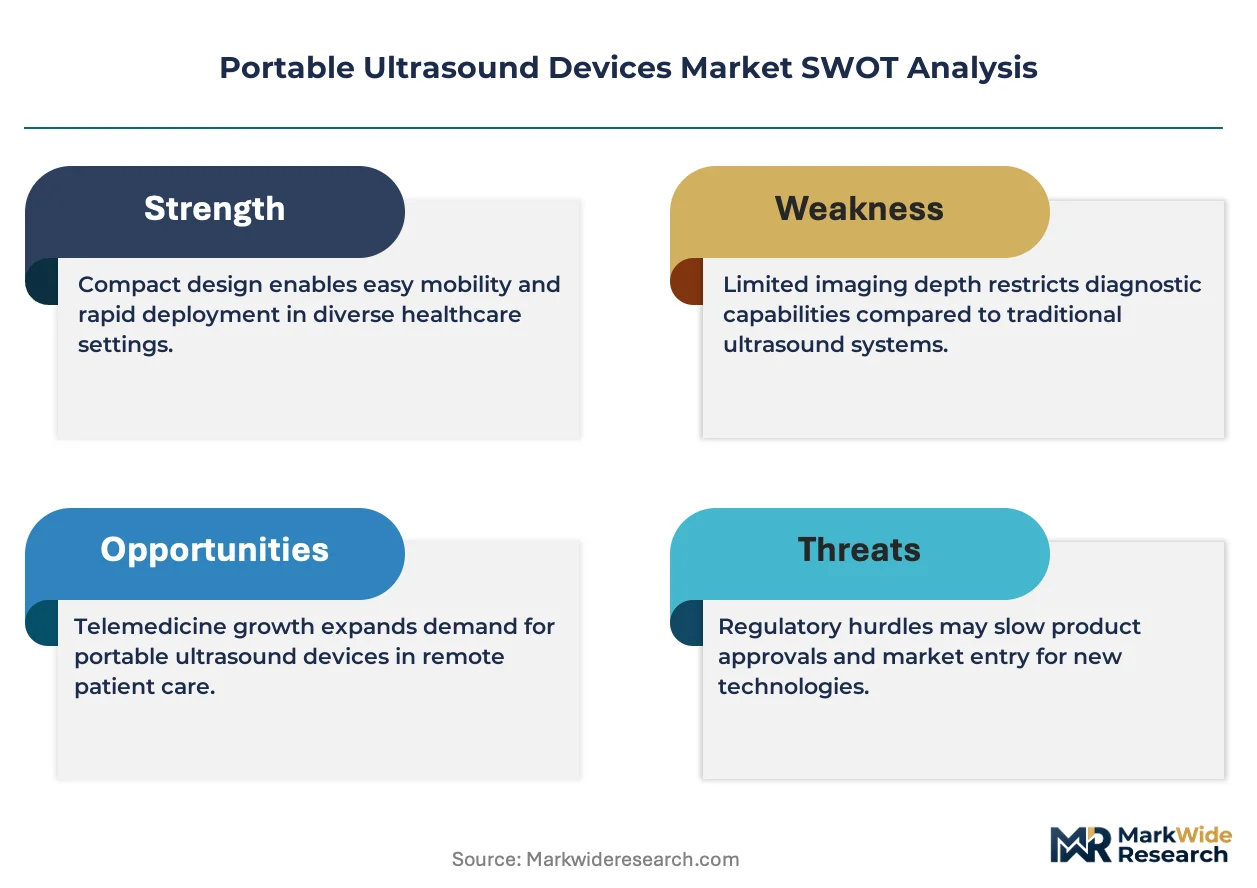
Market access is governed by stringent regulatory approvals from bodies like the U.S. FDA, the European Union under its Medical Device Regulation (MDR), and China's NMPA. These regulations mandate specific performance standards, cybersecurity protocols for connected devices, and clinical validation for diagnostic claims, influencing product design. Vendor success depends on navigating varied reimbursement policies and demonstrating clear clinical and economic value to healthcare providers.
Market Dynamics
The decentralization of diagnostic imaging from dedicated radiology departments to the point of care is the central force shaping the market. This shift is enabled by device miniaturization, cost reduction, and the integration of AI-driven interpretation tools.
Growth Catalysts
- Government Healthcare Initiatives:China's policies aimed at modernizing rural healthcare infrastructure create sustained demand for affordable, easy-to-use diagnostic tools, with portable ultrasound being a primary beneficiary of this government-led investment cycle.
- AI-Powered Automation:The integration of artificial intelligence for tasks like automated measurements and preliminary image analysis lowers the skill threshold for operation, accelerating adoption among non-specialist clinicians in primary and emergency care settings.
- Expanding Clinical Applications:Use in point-of-care settings for fast-track diagnostics in emergency medicine and anesthesiology is expanding, driven by demonstrated improvements in patient outcomes and workflow efficiency within ambulatory surgical centers.
Market Restraints
- Stringent Regulatory Hurdles:Navigating complex and divergent regulatory requirements from bodies like the U.S. FDA, the EU's MDR, and China's NMPA, especially for cybersecurity in connected devices, creates significant barriers to market entry.
- Reimbursement Policy Fragmentation:Inconsistent and often inadequate reimbursement policies for ultrasound procedures performed outside of traditional hospital radiology departments limit the economic incentive for adoption in primary care clinics across many countries.
- High Transducer Development Costs:The research and development investment required to create specialized, high-fidelity transducer technology for niche applications like intravascular or ophthalmic imaging remains substantial, constraining price reductions for advanced systems.
Strategic Opportunities
- Tele-Ultrasound Integration:Integrating portable devices with telehealth platforms offers a significant opportunity to provide expert-guided diagnostics in remote or underserved areas, connecting local practitioners with specialized radiologists via cloud-based systems.
- Veterinary Medicine Expansion:The veterinary market represents a largely underpenetrated field for advanced portable ultrasound, with applications in companion animal and equine practice offering a new, high-growth revenue stream for device manufacturers.
- Subscription-Based Business Models:Shifting from capital sales to Hardware-as-a-Service (HaaS) models, bundling the device, software, training, and cloud storage, can lower the upfront cost barrier for individual practitioners and smaller clinics.
Industry Challenges
- User Training and Credentialing:Ensuring clinical competency and proper use by a growing base of non-radiologist users, such as paramedics and primary care physicians, presents a major training and credentialing challenge for healthcare systems.
- Data Integration Complexity:Integrating the large volume of imaging data generated by fleets of portable devices into existing hospital PACS and Electronic Health Record systems securely and efficiently is a major technical and workflow hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable Ultrasound Devices Market |
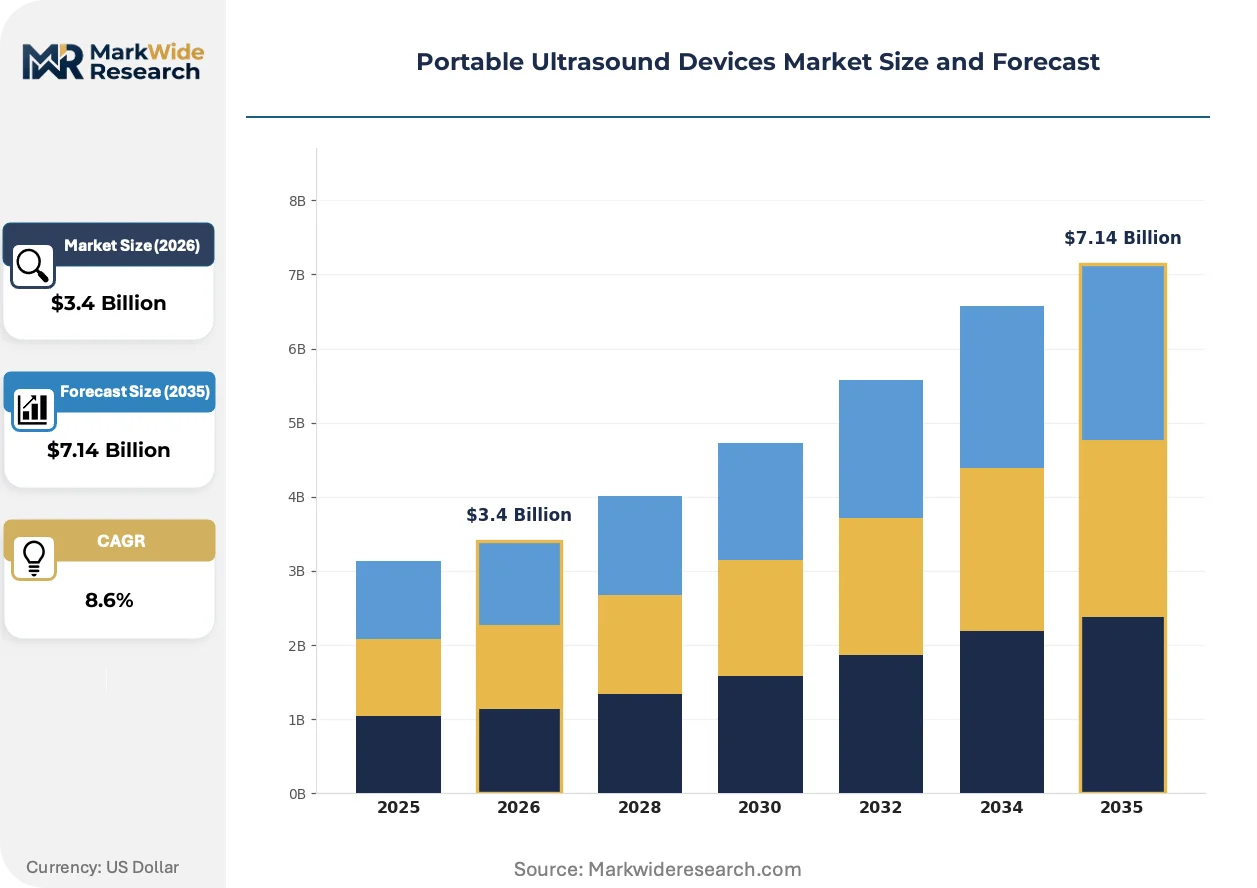
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $7.14 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld, Laptop-based, Cart-based, POC Devices Technology: Analog, Digital, 3D Imaging, Doppler End User: Hospitals, Clinics, Ambulatory Surgical Centers, Home Care Application: Diagnostics, Therapeutics, Obstetrics, Cardiology |
| Companies Covered | FUJIFILM Sonosite, Canon Medical Systems Corporation, GE Healthcare, Clarius Mobile Health, Mindray, Philips Healthcare, Butterfly Network, Samsung Medison, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable Ultrasound Devices Market Strategic Shifts & Innovations
The market's evolution is defined by the unbundling of hardware and software, transforming the ultrasound device from a monolithic system into a sensor connected to a broader digital health ecosystem. This software-defined approach is democratizing access to advanced imaging capabilities.
Software-defined ultrasound separates the transducer hardware from image processing, which runs on a connected smartphone or tablet. Adoption is accelerating among individual practitioners and emergency medical services who value the extreme portability and lower initial cost. This technology is virtualizing the traditional console-based system, turning commodity consumer electronics into powerful medical imaging platforms through sophisticated applications.
The European Union's Medical Device Regulation (MDR) imposes more rigorous requirements for clinical evidence, post-market surveillance, and cybersecurity. This directive increases compliance costs and can extend the development timeline for manufacturers aiming to sell within the EU. Devices incorporating AI and cloud connectivity face the highest scrutiny, demanding robust validation for both diagnostic claims and data protection under GDPR.
A notable behavioral shift is occurring in how healthcare providers acquire this technology, moving away from large, one-time capital expenditures. This trend favors subscription or pay-per-use models that bundle hardware with ongoing software updates, cloud storage, and virtual training. This model is most prominent in outpatient clinics and private practices in North America and Europe looking to manage operational costs more effectively.
Portable Ultrasound Devices Market Segmentation
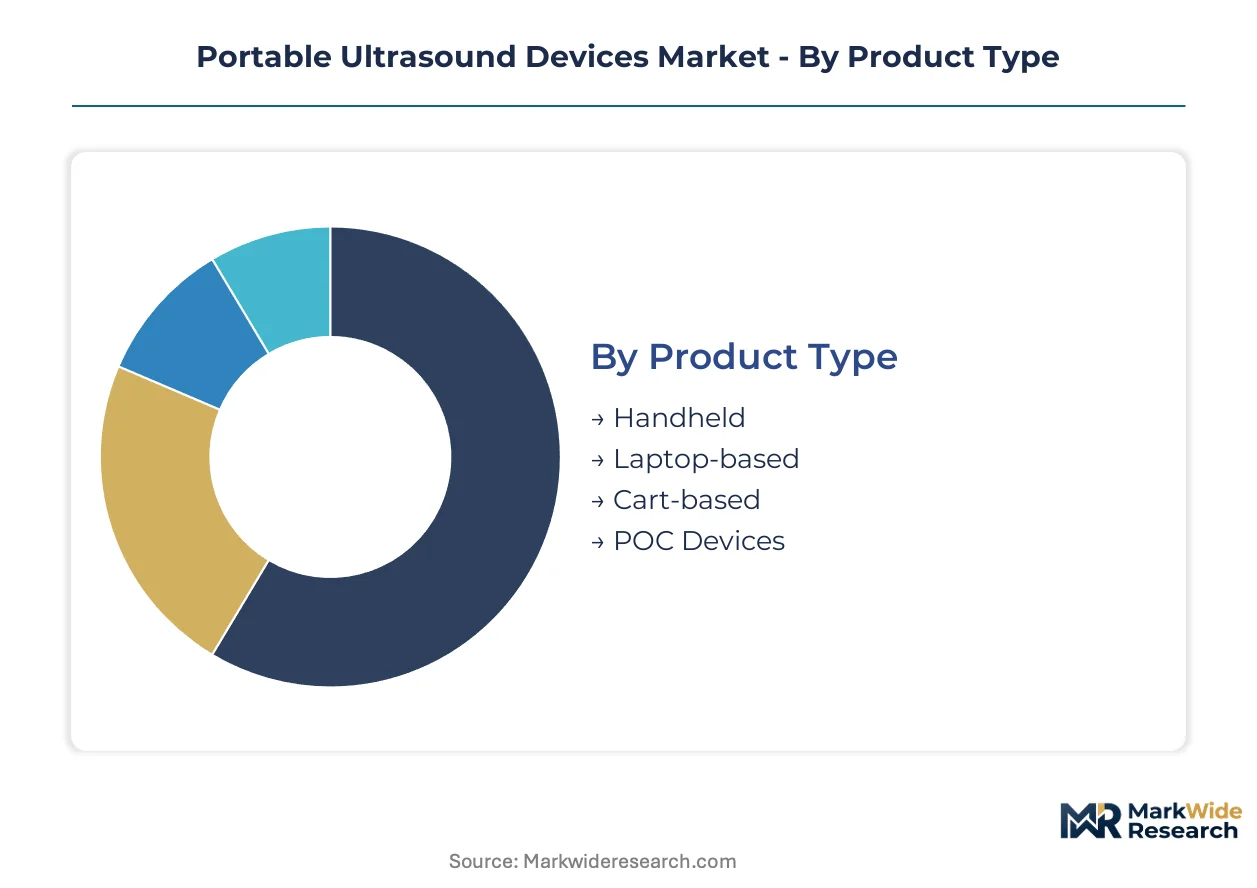
The Portable Ultrasound Devices Market is segmented to provide a granular understanding of product adoption across diverse clinical environments and technological preferences. This segmentation helps identify specific demand pockets and the most impactful innovation vectors shaping market evolution.
Product Type:
Device cycle times vary significantly across product types, reflecting differing technological complexity and user deployment models.
- Handheld:These compact, battery-operated devices integrate transducer and display, often connecting to smartphones or tablets. Demand concentrates in emergency medicine and primary care settings across North America, driven by their extreme portability and rapid diagnostic capabilities, making it the fastest-growing product type.
- Cart-based:Larger, console-style systems mounted on wheeled carts offer advanced imaging features and multiple probe options. Hospitals and large clinics in Europe utilize these systems for comprehensive departmental imaging, requiring more dedicated space and power.
- Laptop-based:Portable ultrasound systems that connect dedicated transducers to standard laptop computers, providing a balance of mobility and processing power for specialized clinics.
- POC Devices:A broad category encompassing devices designed for immediate diagnostic use at the patient's bedside, emphasizing ease of use and quick results in diverse medical environments.
Cart-based devices anchor the volume base while Handheld devices gain share at the steepest rate.
Technology:
The cost tiers for portable ultrasound technology reflect the sophistication of image processing and data acquisition methods.
- Digital:This technology uses digital signal processing for superior image clarity and enables advanced features like AI integration and cloud connectivity. Demand for digital systems is concentrating in ambulatory surgical centers in the US, driven by efficiency gains and diagnostic accuracy.
- 3D Imaging:These systems capture volumetric data, allowing for multi-planar reconstruction and detailed anatomical visualization, particularly valuable in complex diagnostic cases. Obstetric and cardiology applications in Japan utilize 3D imaging for enhanced fetal assessment and cardiac function analysis.
- Analog:Older technology relying on analog signal processing, offering basic imaging capabilities suitable for fundamental diagnostic checks in resource-limited settings.
- Doppler:A specialized ultrasound mode that measures blood flow and velocity, crucial for assessing vascular conditions and cardiac function in various clinical environments.
Digital technology drives feature innovation, while 3D Imaging expands its clinical footprint.
End User:
Customer types for portable ultrasound devices range from large institutional buyers to individual practitioners, each with distinct procurement needs.
- Hospitals:Large medical institutions represent significant buyers, integrating portable devices across emergency departments, ICUs, and specialized clinics. Demand in Chinese hospitals is supported by government initiatives to modernize healthcare infrastructure, especially in rural areas.
- Ambulatory Surgical Centers:These outpatient facilities increasingly adopt portable ultrasound for pre-operative assessments, guided procedures, and post-operative monitoring. Demand in European ASCs is driven by the need for efficient workflows and reduced patient recovery times.
- Clinics:Smaller private practices and specialized clinics use portable ultrasound for routine diagnostics and point-of-care imaging, valuing affordability and ease of integration into existing services.
- Home Care:Portable devices enable healthcare professionals to conduct diagnostic imaging in patients' homes, improving access to care for immobile or remote populations.
Hospitals remain the primary purchasing segment, with Ambulatory Surgical Centers demonstrating rapid expansion.
Application:
The utility of portable ultrasound spans a diverse range of medical applications, from routine screening to complex interventional procedures.
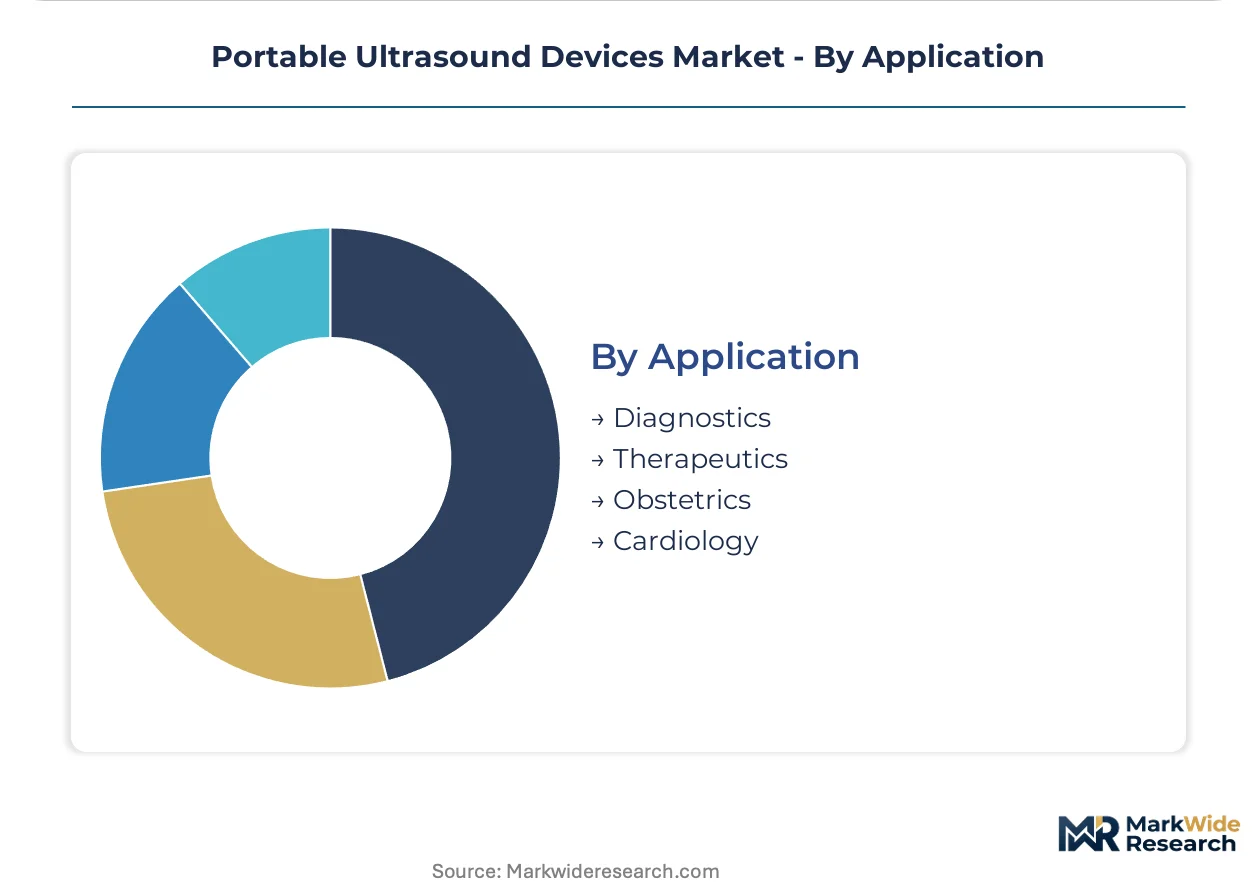
- Diagnostics:Portable ultrasound provides rapid, non-invasive imaging for identifying various medical conditions across multiple body systems. Primary care physicians in Canada utilize these devices for initial diagnostic screenings, reducing referral times.
- Cardiology:These devices are essential for assessing heart structure and function, diagnosing cardiac abnormalities, and monitoring treatment efficacy. Demand in US cardiology departments focuses on advanced handheld systems for quick bedside assessments and follow-up.
- Therapeutics:Portable ultrasound guides minimally invasive procedures like biopsies, nerve blocks, and fluid aspirations, enhancing precision and patient safety.
- Obstetrics:Used for prenatal care, fetal monitoring, and assessing pregnancy progression, providing vital information for maternal and infant health.
Diagnostics forms the foundational application, while Cardiology applications exhibit strong value growth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Portable Ultrasound Devices Market exhibits varied consumption-mix differentials across key geographies. China's demand is driven by government initiatives to modernize rural healthcare infrastructure, contrasting with North America's focus on point-of-care applications within ambulatory surgical centers. European markets prioritize integration with broader digital health ecosystems and adherence to stringent regulatory frameworks.
China
Chinese demand for portable ultrasound devices stems from government policies aimed at modernizing rural healthcare infrastructure. The NMPA's regulatory framework supports the adoption of affordable, easy-to-use diagnostic tools. Hospitals in Beijing and Shanghai increasingly integrate these devices to expand diagnostic reach into underserved areas.
United States
United States adoption is concentrated in point-of-care applications within ambulatory surgical centers and cardiology departments. U.S. FDA approvals for new devices influence market entry, alongside complex reimbursement policies. Technology hubs in California and Massachusetts drive the adoption of digital systems for enhanced efficiency and diagnostic accuracy.
Germany
Germany's market for portable ultrasound devices focuses on comprehensive departmental imaging in hospitals and efficient workflows in European ASCs. The European Union's Medical Device Regulation (MDR) imposes rigorous requirements for clinical evidence and cybersecurity. Medical technology clusters around Bavaria and Baden-Württemberg foster innovation in advanced imaging software.
Japan
Japanese demand emphasizes enhanced fetal assessment and cardiac function analysis, particularly utilizing 3D imaging technology. PMDA oversight ensures high standards for medical devices and diagnostic claims. Research institutions in Tokyo and Kyoto actively collaborate on developing next-generation transducer technology for niche applications.
Canada
Canadian primary care physicians increasingly utilize portable ultrasound for initial diagnostic screenings, aiming to reduce referral times and improve patient access. Health Canada approvals govern market access for these devices within the public healthcare system. Urban centers like Toronto and Vancouver see increased deployment of handheld devices in emergency medical services.
Portable Ultrasound Devices Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another in the portable ultrasound devices market. This market structure features a blend of established medical device giants and agile, technology-focused innovators. Three strategic archetypes emerge: diversified healthcare conglomerates, specialized imaging solution providers, and disruptive semiconductor-based platform developers. Strategic partnerships and technology licensing are dominant competitive moves for market players.
Diversified healthcare conglomerates like GE Healthcare and Philips Healthcare leverage extensive hospital networks and broad digital health ecosystems to deploy a range of cart-based and handheld systems. These established players focus on advanced imaging software and integration capabilities. In contrast, Butterfly Network exemplifies the specialized innovator archetype, focusing on semiconductor-based, single-probe whole-body imaging technology that targets individual practitioners and smaller clinics.
| Leading Market Players |
|---|
| FUJIFILM Sonosite |
| Canon Medical Systems Corporation |
| GE Healthcare |
| Clarius Mobile Health |
| Mindray |
| Philips Healthcare |
| Butterfly Network |
| Samsung Medison |
| Siemens Healthineers |
| Others |
Cost & Logistics Intelligence
Specialized transducer manufacturing in Japan and South Korea dictates upstream cost structures, influencing downstream device pricing for advanced systems. Digital component fabrication in China creates cost efficiencies for handheld device producers.
Pricing Analysis
Long-term contract agreements with large hospital networks often define pricing for cart-based systems, while handheld devices increasingly adopt subscription-based models. Advanced imaging software and U.S. FDA or EU MDR regulatory approvals differentiate premium offerings. Pricing softness reflects increased manufacturing capacity in China, particularly for entry-level handheld units. Individual practitioners and smaller clinics exhibit the highest price sensitivity, favoring lower upfront costs.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities support the complex global manufacturing ecosystem for portable ultrasound devices. Geographic supply concentrates in China for digital components and assembly, with specialized transducer production primarily in Japan and South Korea. Reliance on semiconductor chips and piezoelectric materials creates a raw material dependency. Single-source vulnerability for high-fidelity transducer technology represents a structural risk. Distribution runs through direct sales teams to hospitals and value-added resellers for smaller clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Portable Ultrasound Devices Market presents a defensive moat opportunity, primarily due to regulatory entrenchment requiring extensive clinical validation and U.S. FDA approvals. High switching costs for integrated digital health ecosystems further protect incumbent positions.
For Market Incumbents:Build regulatory moats by accelerating U.S. FDA and EU MDR submissions for AI-powered diagnostic algorithms. Deepen digital health ecosystem integration within existing hospital networks to counter disruptive semiconductor-based technologies from agile new entrants. Invest in R&D for next-generation software-defined ultrasound platforms. Expand training and certification programs for non-specialist users to maintain market share.
For New Entrants and Emerging Players:Build out Hardware-as-a-Service (HaaS) models to lower upfront cost barriers for individual practitioners and smaller clinics. Target underpenetrated segments like veterinary medicine and remote diagnostics in underserved areas of Canada. Focus on software-defined devices compatible with commodity consumer electronics, offering extreme portability and ease of use. Rapid market entry can occur by securing Health Canada approvals for specific niche applications.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting downwards across the handheld device segment, driven by software-defined architecture leveraging consumer electronics. Investors should prioritize agile software developers with AI-driven interpretation capabilities as acquisition targets. Specialized transducer manufacturers with unique intellectual property also present strategic value. Monitor tele-ultrasound platform integration rates as a key inflection indicator for future growth over the next five to ten years.
| Strategic Initiative | Industry Significance |
|---|---|
| AI-Powered Image Interpretation | Enhances diagnostic accuracy for non-specialist clinicians in primary care. |
| Tele-Ultrasound Platform Integration | Expands diagnostic reach into remote or underserved areas of China. |
| Subscription-Based Device Models | Lowers entry barriers for individual practitioners and ambulatory surgical centers. |
| Advanced Transducer R&D | Improves imaging fidelity for specialized applications like cardiology in Japan. |
| EU MDR Compliance Investment | Secures market access and strengthens trust for devices sold across Europe. |
Research Approach
Cross-validation between primary interviews and secondary data sources anchors the qualitative findings and quantitative estimates within this study. Interviews included clinicians, hospital purchasing committees, biomedical engineers, and GPO contracts managers across North America and Europe. Secondary validation utilized U.S. FDA filings, NMPA reports, EU MDR guidance documents, and medical device databases. Bottom-up and top-down triangulation ensured robust market size and growth rate estimations.
The calibration approach integrated quantitative models with qualitative expert insights to project market dynamics across the analysis window. Segmentation dimensions modeled included product type, technology, end user, application, and regional regulatory environment. Compound annual growth rates were derived from historical trends and projected adoption rates. Key forecast inputs included government healthcare infrastructure investment in China and AI integration rates.
Practitioners should monitor geopolitical trade policies and significant shifts in reimbursement policies for early signals of market disruption. Forecasts reflect assumptions regarding technological adoption and regulatory stability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Pipetting Systems Market
Medical Devices
Power Wheelchairs and Mobility Scooters Market
Medical Devices
Interphalangeal Fusion Market
Medical Devices
Ingestible Thermometers Market
Medical Devices
Vascular Boot Market
Medical Devices
Skull Deformity Implants Market
Medical Devices
Metered Dose Squeeze Dispenser Market
Medical Devices
Anti-Blue Ray Myopia Lenses Market
Medical Devices
Multi Dose Drug Vial Adapters Market
Medical Devices
Arthroscopic Shaver Market
Medical Devices
Digital Respiratory Devices Market
Medical Devices
Transcatheter Pulmonary Valve Replacement Market
Medical Devices
Bilirubin Meters Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Global Concussion Market
Medical Devices
Global Implantable Cardioverter Defibrillators (ICD) Market