
 Infant Incubator Market | 2026-2036
Infant Incubator Market Size, Share, and Industry Trends Forecast 2026-2036
Infant Incubator Market Outlook
CE marking under the EU Medical Device Regulation is reorganizing competitive entry in Europe, forcing smaller manufacturers toward notified-body partnerships. Drägerwerk AG & Co. KGaA leverages its German engineering base to sustain dominance in transport incubator systems. GE HealthCare anchors North American hospital procurement through integrated NICU workflows. Fanem competes aggressively in Latin America with cost-optimized open care warmers.
An infant incubator is a thermoregulated enclosure maintaining neutral thermal environment for preterm or low-birth-weight neonates through servo-controlled heating, humidity management, and oxygen delivery systems; its primary purpose is reducing hypothermia-related morbidity in critical early life stages. Convertible incubators command premium positioning as hospitals seek flexible capital equipment spanning transport and stationary care. Neonatal intensive care units concentrate margin pools where bundled device-and-service contracts prevail. Forced air technology segments displace conventional radiant warmers in tertiary facilities prioritizing temperature uniformity.
FDA premarket notification and CE marking under MDR frame product clearance timelines, with ISO 10993 biocompatibility testing adding cost layers for polymer component suppliers. The EPA's energy efficiency guidelines increasingly shape incubator design specifications in the United States. Stakeholders must monitor evolving harmonization between FDA's software-as-medical-device guidance and incubator digital control platforms to preempt compliance gaps.
Market Dynamics
EU Medical Device Regulation (MDR) recertification deadlines are compressing manufacturer timelines and restructuring competitive entry in Europe, forcing notified-body queue management to the center of strategic planning.
Growth Catalysts
- MDR Compliance Deadlines:CE marking under the EU Medical Device Regulation creates replacement demand as legacy certificates expire, pulling forward hospital capital expenditure cycles.
- Neonatal Transport Networks:Regional health systems in Germany and the United States are expanding mobile NICU capabilities, requiring specialized transport incubator configurations.
- Humidity Control Advances:Servo-controlled humidification systems reduce evaporative heat loss in extremely low birth weight infants, improving clinical outcomes and justifying premium equipment procurement.
Market Restraints
- Polymer Input Volatility:Medical-grade polycarbonate and silicone prices fluctuate with petrochemical feedstock costs, compressing margin predictability for enclosure manufacturers.
- Notified Body Bottlenecks:European Union accreditation capacity constraints extend CE marking timelines by 12-18 months for novel incubator designs.
- Radiant Warmer Substitution:Open care warming systems compete for capital budget allocation in secondary care settings, limiting incubator penetration in cost-constrained facilities.
Strategic Opportunities
- India NICU Expansion:Government hospital infrastructure programs under the National Health Mission create first-time equipment demand in tier-2 and tier-3 cities.
- Software-as-Medical-Device Convergence:FDA guidance on SaMD enables predictive thermal algorithm licensing separate from hardware, opening recurring revenue streams.
- Refurbishment Channel Formalization:Third-party certified pre-owned equipment programs address budget constraints in Latin American and Southeast Asian markets.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Servo-control firmware development and thermal modeling expertise concentrates in Germany and the United States, constraining R&D scaling.
- Legacy System Integration:New incubator platforms must interface with proprietary hospital information systems, extending deployment timelines and customization costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Infant Incubator Market |
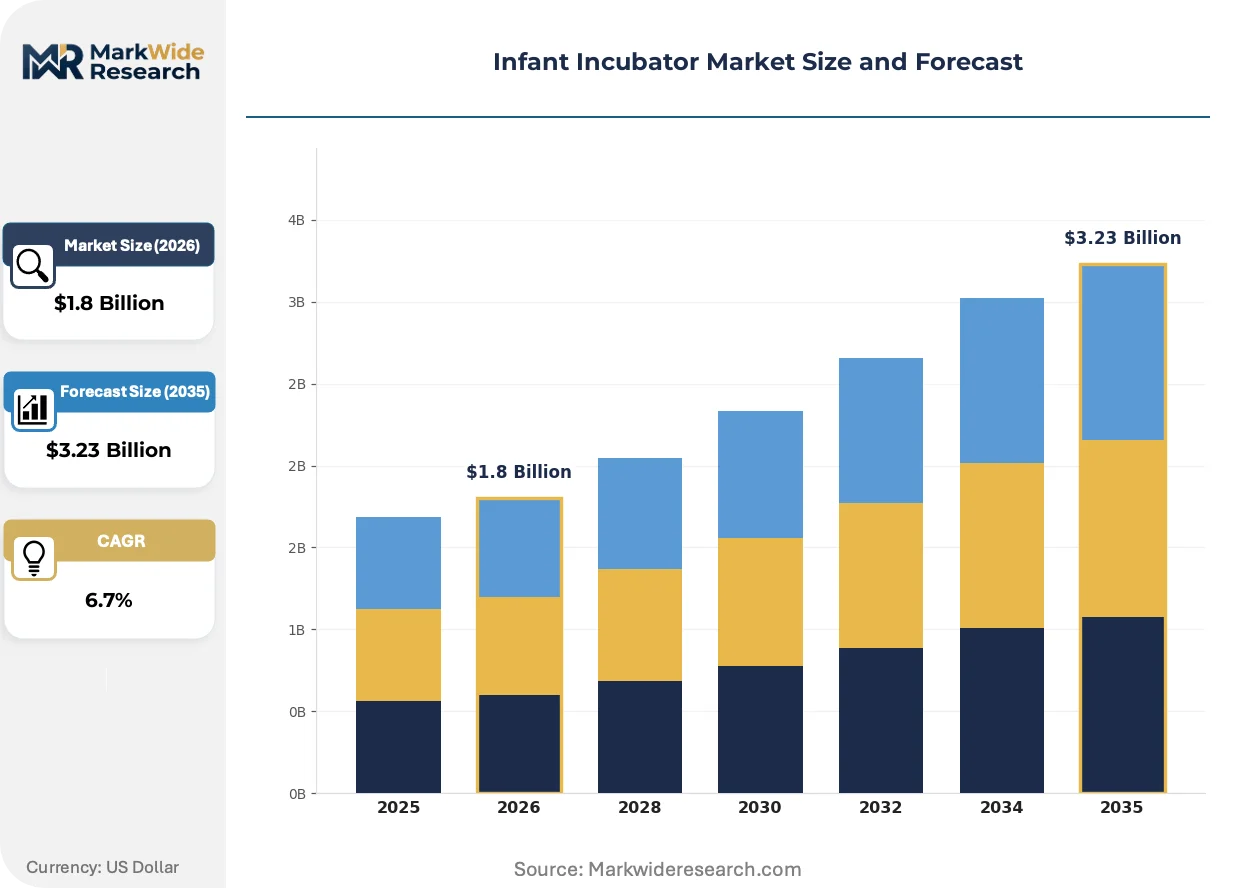
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Convertible Incubators, Open Care Warmers, Transport Incubators, Neonatal Intensive Care Units End User: Hospitals, Clinics, Pediatric Care Centers, Home Care Settings Technology: Conventional, Forced Air, Hybrid Systems, User-Friendly Interface Installation Type: Fixed, Portable, Wall-Mounted, Table-Top |
| Companies Covered | Fanem, Koninklijke Philips N.V., Atom Medical Corp., Inspiration Healthcare Group, International Biomedical, Drägerwerk AG & Co. KGaA, Bistos Co., Ltd., NOVOS, GE HealthCare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Infant Incubator Market Strategic Shifts
Thermal management architectures are converging with digital health platforms, creating new value pools around data integration and predictive intervention rather than hardware specifications alone.
Microprocessor-based servo control systems with embedded machine learning are miniaturizing thermal regulation components while maintaining precision. Tertiary NICU facilities in the United States and Germany are adopting these compact control modules to enable incubator footprint reduction. This miniaturization is compressing the physical envelope of transport incubators without sacrificing temperature stability during ambulance or aircraft transfer.
CE marking under the EU Medical Device Regulation is reorganizing quality management system requirements for software components. Manufacturers must now demonstrate cybersecurity validation and post-market surveillance capabilities that exceed previous Medical Device Directive standards. Transport incubator systems with integrated telemetry face the steepest compliance cost increases, favoring incumbents with established notified-body relationships.
Hospital procurement departments are unbundling device acquisition from service contracts, reversing decades of bundled pricing dominance. Group purchasing organizations in the United States are negotiating separate maintenance agreements with third-party biomedical service firms. This unbundling is most visible in California and Texas health systems, where independent service organizations now capture 30-40% of annual maintenance spend previously retained by original equipment manufacturers.
Infant Incubator Market Segmentation
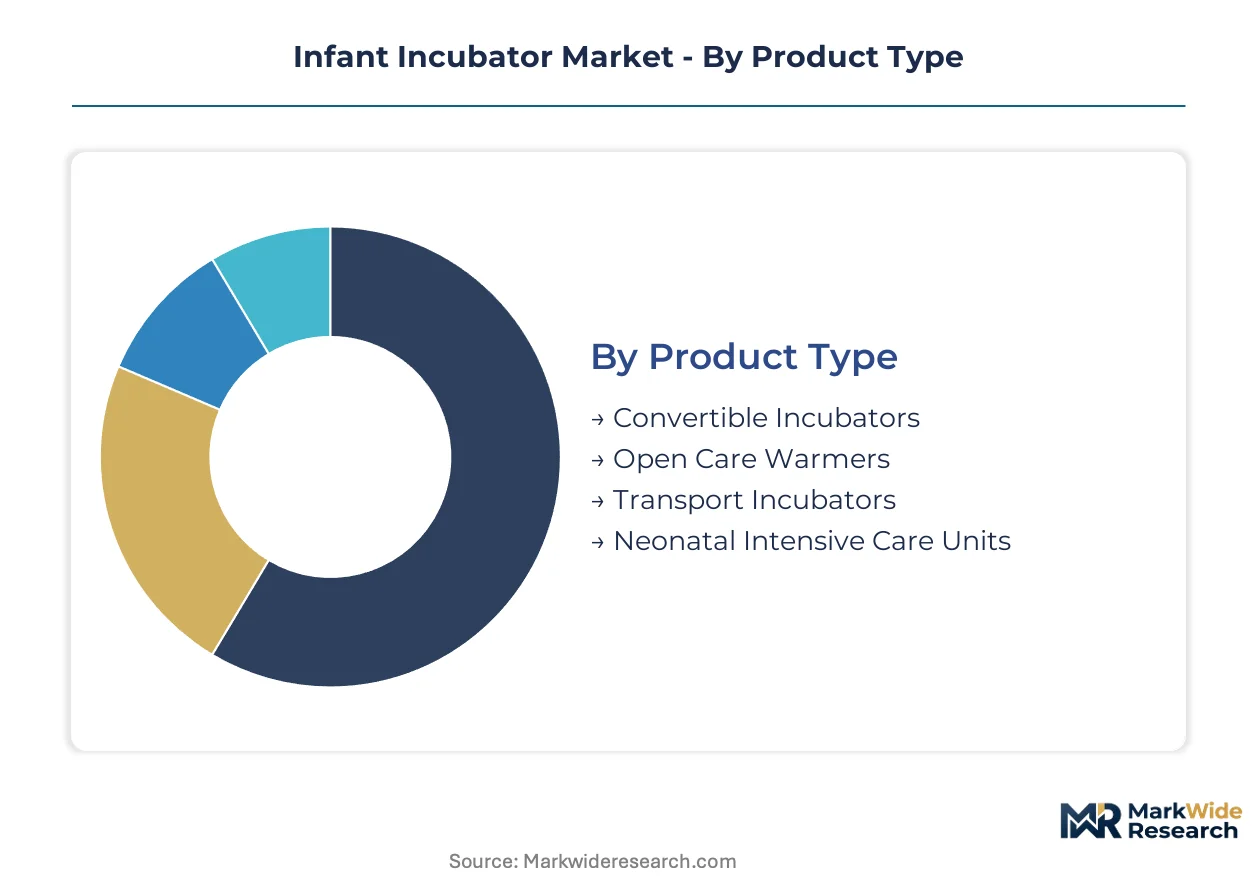
Incubator purchasing decisions fragment across clinical workflow requirements, capital budget tiers, and regulatory compliance pathways. Each segmentation dimension carries distinct margin profiles and competitive dynamics that shape manufacturer positioning.
Product Type:
FDA premarket notification and CE marking under MDR impose divergent technical documentation burdens across enclosure configurations, with transport systems facing the steepest validation requirements for electromagnetic compatibility and thermal stability during vibration.
- Convertible Incubators:Modular platforms switch between stationary NICU deployment and ambulance transport through detachable chassis systems. Tertiary hospitals in Germany and the United States prioritize these configurations to consolidate capital expenditure across multiple care settings.
- Transport Incubators:Self-contained thermal regulation units with integrated battery power and shock-absorbing suspension maintain servo-controlled environments during air and ground medical evacuation. Regional health systems expanding mobile NICU networks drive procurement concentration.
- Open Care Warmers:Radiant heat platforms provide immediate access for resuscitation procedures without enclosure barriers. Secondary care facilities in cost-constrained markets select these for routine thermoregulation.
- Neonatal Intensive Care Units:Comprehensive incubator systems bundled with ventilator interfaces and multi-parameter monitoring occupy dedicated NICU pods. Academic medical centers anchor demand for these integrated platforms.
Convertible Incubators handle the majority of throughput; Transport Incubators are gaining share fastest among product configurations.
End User:
Procurement authority concentrates differently across facility types, with hospital group purchasing organizations wielding volume leverage while pediatric specialty centers negotiate on clinical outcome metrics.
- Hospitals:Integrated delivery networks consolidate incubator procurement through centralized supply chain functions, with NICU directors specifying thermal performance requirements. These facilities command priority allocation from manufacturers during supply constraints.
- Pediatric Care Centers:Dedicated neonatal facilities outside hospital systems optimize workflow around high-acuity cases, selecting incubators with advanced humidity servo-control for extremely low birth weight infants.
- Clinics:Limited-service facilities deploy basic radiant warmers for stabilization prior to transfer, with equipment decisions driven by acquisition cost rather than feature depth.
- Home Care Settings:Emerging demand from rural discharge planning programs requires simplified interfaces and remote monitoring capabilities for family-operated thermal management.
Hospitals absorb the dominant share of unit volume; Pediatric Care Centers show the steepest expansion trajectory on a percentage basis.
Technology:
Energy efficiency standards from the EPA and thermal uniformity specifications under ISO 10993 biocompatibility frameworks differentiate technology tiers in procurement evaluations.
- Forced Air:Circulating heated air through microprocessor-controlled fan arrays achieves superior temperature distribution compared to radiant sources. Tertiary NICU facilities in the United States displace conventional warmers with these systems.
- Hybrid Systems:Configurations combining radiant and convective heating modes adapt to procedural requirements without equipment swaps. Surgical suites and resuscitation bays specify these for workflow flexibility.
- Conventional:Basic radiant warming elements without servo-feedback control occupy budget-sensitive procurement categories. These persist in secondary markets where capital constraints override performance specifications.
- User-Friendly Interface:Touchscreen control panels with alarm prioritization and trend visualization reduce training burden for rotating clinical staff. These interface upgrades increasingly determine competitive selection.
Forced Air technology commands the largest installed base; Hybrid Systems are climbing the fastest on new installation share.
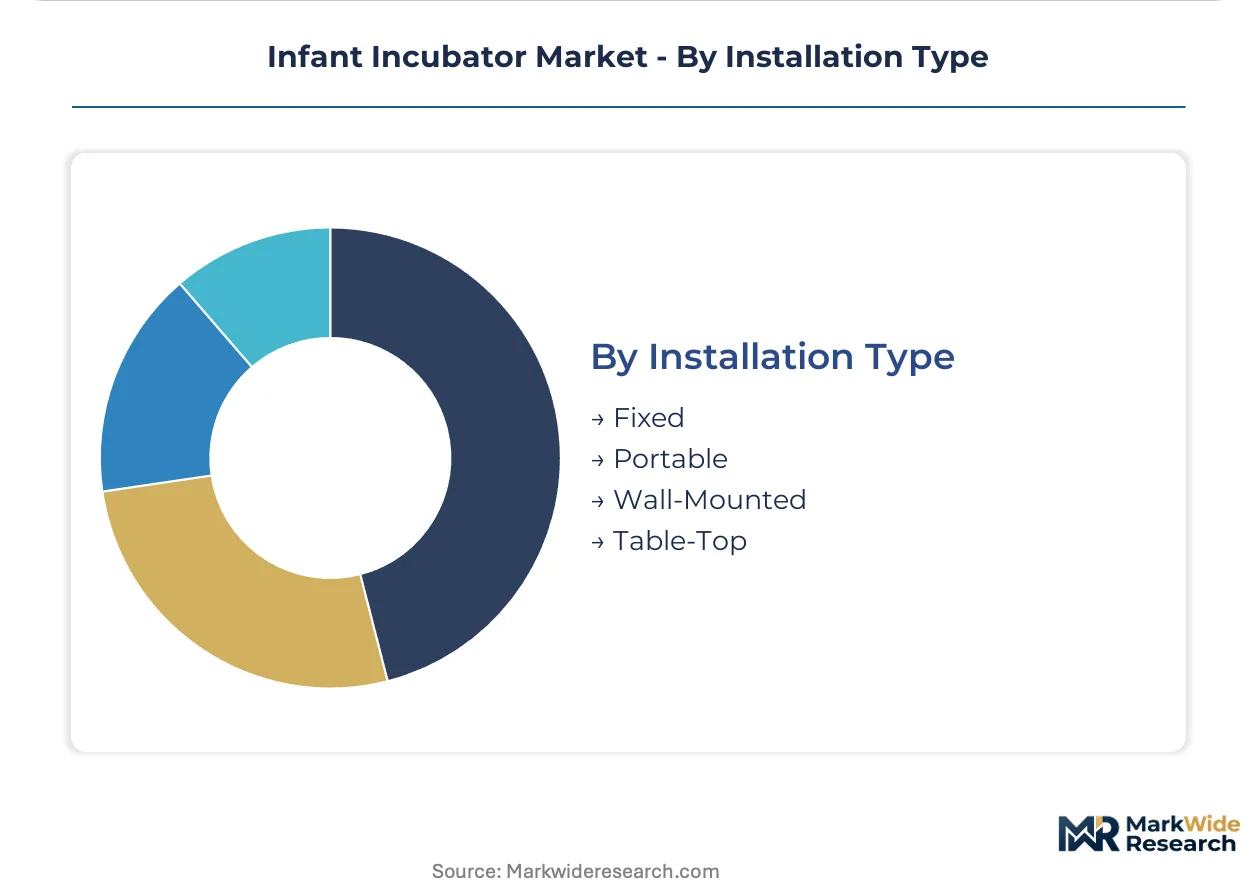
Installation Type:
Physical integration requirements vary by facility infrastructure age, with newer construction accommodating fixed mounting systems while retrofit installations favor portable configurations.
- Fixed:Permanent mounting on dedicated NICU pods enables hardwired telemetry integration and centralized medical gas supply. New hospital construction in China and Germany specifies these for long-term operational stability.
- Portable:Castor-mounted units with quick-release utility connections relocate between patient rooms and procedure areas. Flexible staffing models in United States health systems drive preference for mobility.
- Wall-Mounted:Articulating arm suspensions free floor space in congested clinical environments. These configurations concentrate in urban hospitals with premium real estate costs.
- Table-Top:Compact footprints for limited-space resuscitation areas and transitional care settings. Developing market clinics select these for minimal infrastructure requirements.
Fixed installations represent the dominant configuration; Portable systems are expanding most quickly as workflow flexibility priorities reshape capital planning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government hospital infrastructure programs and NICU expansion initiatives are redirecting procurement flows across major economies. Regulatory harmonization pressures from FDA and CE marking under MDR are compressing manufacturer entry timelines in developed markets while creating replacement demand cycles.
United States
Regional health systems in California and Texas are expanding mobile NICU capabilities, driving transport incubator procurement. FDA premarket notification requirements and EPA energy efficiency guidelines shape design specifications for domestic manufacturers. Academic medical centers in Boston and the Research Triangle anchor demand for integrated NICU workflow systems with bundled device-and-service contracts.
Germany
Notified-body partnerships concentrate in Baden-Württemberg and Bavaria as MDR recertification deadlines compress manufacturer timelines. CE marking under EU Medical Device Regulation forces quality management system upgrades for software components and cybersecurity validation. The country's engineering base sustains dominance in servo-control firmware development and thermal modeling expertise for transport systems.
China
National Health Mission infrastructure programs create first-time equipment demand in tier-2 and tier-3 cities beyond established coastal hubs. NMPA regulatory pathways and GB standards for medical electrical equipment frame product clearance for domestic and imported systems. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta are scaling production of cost-optimized open care warmers for developing market export.
India
Government hospital infrastructure programs under the National Health Mission are expanding NICU capacity in Maharashtra, Gujarat, and Karnataka. CDSCO medical device regulations and BIS standards for electrical safety govern import and domestic manufacturing requirements. Pediatric specialty centers in Delhi-NCR and Chennai are selecting advanced humidity servo-control systems for extremely low birth weight infant care.
Brazil
ANVISA regulatory frameworks and budget constraints in public health systems are formalizing third-party certified pre-owned equipment channels. Regional health networks in São Paulo and Minas Gerais are balancing capital expenditure between new incubator procurement and refurbishment programs. Cost-optimized open care warmers compete for allocation against enclosed systems in secondary care facilities.
Infant Incubator Market Competitive Environment
Player mix skews toward diversified medical device conglomerates with established notified-body relationships and regional specialists competing on cost optimization. Market structure exhibits tiered consolidation with premium-tier incumbents defending position through integrated NICU workflows and mid-tier challengers penetrating price-sensitive segments. Two strategic archetypes dominate: German-engineering specialists leveraging servo-control expertise and diversified health technology conglomerates anchoring North American procurement. Competitive moves concentrate on M&A for regulatory capacity and strategic partnerships for notified-body queue management.
Within the diversified conglomerate tier, Koninklijke Philips N.V. and GE HealthCare exemplify positioning through integrated hospital system relationships, while Drägerwerk AG & Co. KGaA anchors the engineering-specialist archetype with German-origin manufacturing heritage. Among Asia-Pacific fabricators, Bistos Co., Ltd. and Atom Medical Corp. occupy positions within regional supply chains serving cost-optimized segments. Fanem represents the Latin American specialist model competing on refurbishment channel formalization and budget-constrained market penetration. NOVOS and Inspiration Healthcare Group sit within emerging competitive vectors around software-as-medical-device convergence and predictive thermal algorithm development.
| Leading Market Players |
|---|
| Fanem |
| Koninklijke Philips N.V. |
| Atom Medical Corp. |
| Inspiration Healthcare Group |
| International Biomedical |
| Drägerwerk AG & Co. KGaA |
| Bistos Co., Ltd. |
| NOVOS |
| GE HealthCare |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at polycarbonate enclosure fabrication facilities in Germany and China establishes price floors for medical-grade incubator housings, compressing margin headroom for mid-tier assemblers while concentrating pricing power among integrated polymer compounders with captive resin supply.
Pricing Analysis
Certification level (ISO 10993/FDA-grade/CE-MDR tier) creates the primary spread between premium and economy positioning. Three-tier pricing structure across premium, standard, and economy levels reflects documentation burden divergence, with MDR-notified-body validation adding substantial cost layers to European-bound units. Price erosion runs through open care warmer segments as regional manufacturers in China and Brazil scale production of basic radiant platforms. Pediatric specialty centers show lowest price sensitivity, prioritizing humidity servo-precision over acquisition cost, while tier-3 hospital procurement in India and Southeast Asia concentrates volume in budget-tier configurations.
Supply Chain Analysis
Petrochemical feedstock transit through Rotterdam and Singapore anchorage zones exposes medical-grade polycarbonate and silicone suppliers to bunker fuel volatility and container scheduling disruptions. Manufacturing concentration clusters in Germany, China, and the United States feed from specialty polymer compounders in Belgium, Japan, and Saudi Arabia. Single-source vulnerability concentrates in servo-control microprocessor supply, where German and US firmware developers dominate thermal algorithm IP. Distribution runs through hospital group purchasing organizations in North America and regional medical device distributors in Latin America and Southeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment replacement cycles triggered by EU MDR recertification deadlines position the market for cyclical recovery, pulling forward capital expenditure from health systems with expiring legacy certificates.
For Market Incumbents: Consolidate notified-body relationships to secure queue priority for transport incubator recertification, protecting premium positioning against emerging software-as-medical-device entrants. Deepen backward integration into servo-control firmware development to defend margin structure against polymer input volatility. Lock in multi-year service contracts with US academic medical centers before independent service organizations capture additional maintenance share.
For New Entrants and Emerging Players: Anchor in India's tier-2 and tier-3 city NICU expansion under National Health Mission infrastructure programs, where first-time equipment demand outpaces incumbent distribution reach. Target cost-optimized open care warmer segments in Brazil and Southeast Asian refurbishment channels, exploiting price sensitivity that premium-tier manufacturers leave unaddressed. Pursue strategic partnerships with regional medical device distributors rather than direct hospital sales forces.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-as-medical-device platforms with predictive thermal algorithm licensing, offering subscription multiples distinct from hardware transactional models. Long-term viability over the next decade favors manufacturers with established MDR quality management systems and cybersecurity validation capabilities. Monitor FDA software guidance harmonization progress as the critical inflection signal for SaMD revenue model scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR recertification deadlines compress timelines, favoring incumbents with notified-body partnerships in Germany. |
| Hospital System Partnership | Integrated NICU workflow contracts with US academic medical centers lock in multi-year device-and-service revenue streams. |
| Software Companion Development | SaMD-enabled predictive thermal algorithms open recurring licensing revenue separate from hardware procurement cycles. |
| Backward Integration | In-house polymer compounding insulates margin structure from petrochemical feedstock volatility in enclosure manufacturing. |
| Refurbishment Channel Formalization | Third-party certified pre-owned programs address budget constraints in Brazilian and Southeast Asian public health systems. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with NICU directors, hospital procurement committee members, biomedical engineering leads, and medical device distribution channel managers. Secondary validation drew from FDA 510(k) premarket notification databases, CE marking records under EU MDR, hospital GPO contract repositories, and EPA energy efficiency guideline filings. Bottom-up unit demand modeling across installation types and end-user segments was triangulated against top-down macro health expenditure trends.
Across the projection horizon, analytical frameworks segmented volume and value outputs by product configuration, technology tier, end-user facility type, and geographic regulatory cluster. CAGRs were derived from regression analysis of historical replacement cycles and forward projection of MDR-driven equipment refresh demand. Forecast inputs incorporated servo-control technology adoption curves, transport incubator network expansion plans, and software-as-medical-device regulatory pathway maturation.
Material uncertainties — polymer price volatility, notified-body accreditation capacity constraints, and harmonization timing between FDA SaMD guidance and incubator digital platforms — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory deadline adherence and health system capital allocation continuity. Practitioners should keep alternative scenarios live as EU MDR enforcement intensity and US hospital unbundling trends evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
China Diabetes Devices Market
Medical Devices
Polyp Trap Devices Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Rechargeable Medical Battery Market
Medical Devices
Cryoablation Devices Market
Medical Devices
Dry Eye Treatment Devices Market
Medical Devices
Europe Ablation Technologies Market
Medical Devices
Spine Surgery Robots Market
Medical Devices
Ventilator Breathing Circuit Market
Medical Devices
Sonohysterography Catheters Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
Dose Monitoring Devices Market
Medical Devices
Bone Allografts Market
Medical Devices
South Africa Anesthesia Devices Market
Medical Devices
Direct Energy Medical Devices Market