
 Europe Ambulatory Infusion Pumps Market | 2026-2036
Europe Ambulatory Infusion Pumps Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Ambulatory Infusion Pumps Market Foresight
German manufacturing capacity for precision medical devices is shifting toward connected ambulatory platforms. B. Braun Melsungen AG leverages its integrated production network to dominate electromechanical pump assembly across Central Europe. Fresenius Kabi AG sustains strong positioning in infusion therapy through dedicated R&D facilities in Germany. Ypsomed Holding AG specializes in patch pump miniaturization, anchoring Swiss engineering expertise in wearable drug delivery.
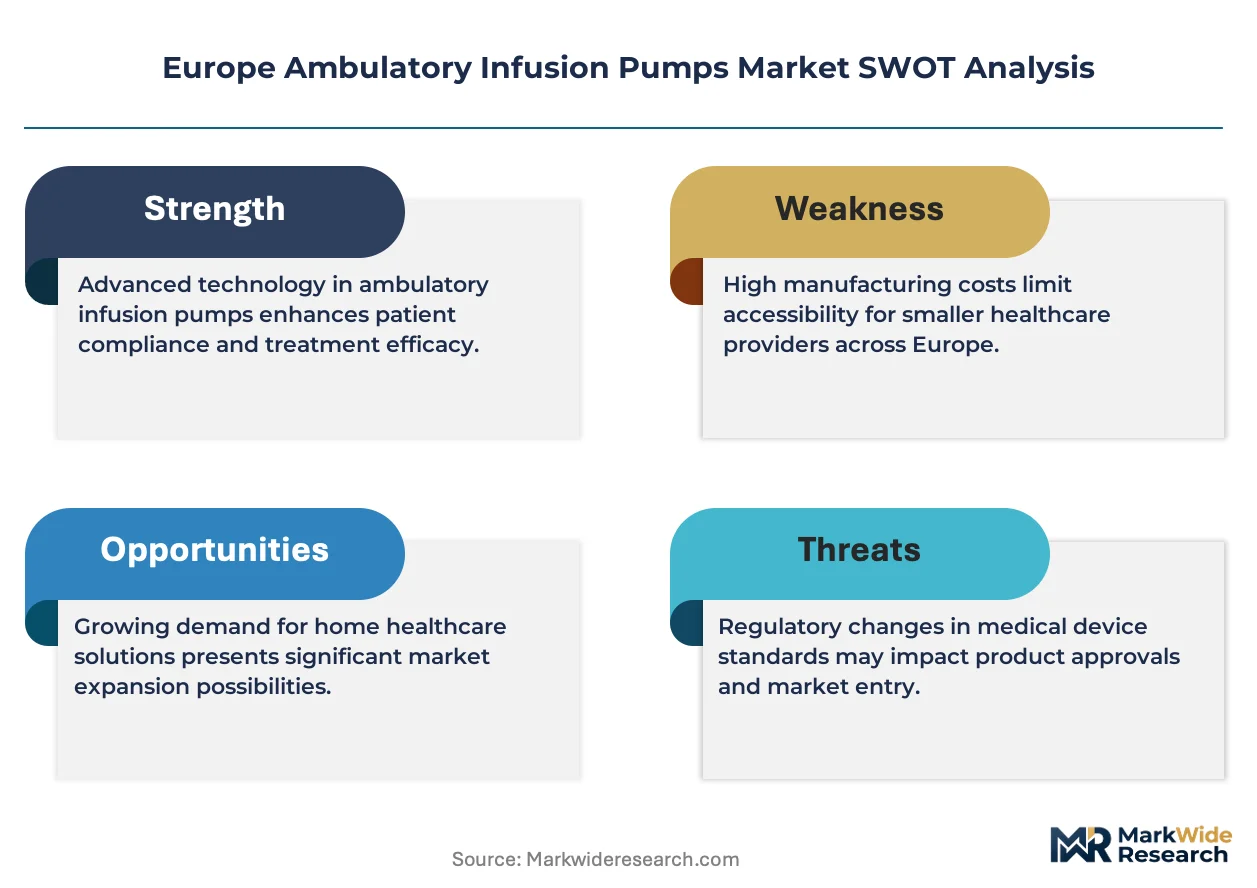
Europe ambulatory infusion pumps are portable electromechanical or elastomeric devices programmed to deliver fluids, medications, or nutrients into a patient's circulatory system at controlled rates, typically operating with flow precision within plus or minus five percent and battery autonomy exceeding eight hours for mobile use. These systems serve primarily to administer chemotherapy, analgesics, insulin, and antibiotics outside acute care settings, reducing hospital occupancy while maintaining therapeutic adherence. Volumetric pumps and smart pumps occupy the premium tier where software integration and safety interlocks command higher margins, while elastomeric pumps compete on disposability and lower total cost of ownership in short-cycle antibiotic therapy. Homecare and oncology application segments are expanding fastest as reimbursement pathways mature and patient preference for outpatient treatment intensifies across Northern and Western Europe.
EMA guidelines on combination products and the EU MDR framework are elevating clinical evidence requirements and post-market surveillance obligations for ambulatory pump manufacturers. CE marking under strengthened notified body oversight now demands extensive biocompatibility and software validation documentation, filtering market access toward established players with regulatory infrastructure. Stakeholders must monitor evolving MDR transition timelines and national reimbursement harmonization to anticipate where product registration investments will yield sustainable commercial traction.
Market Dynamics
The EU Medical Device Regulation is compressing market access timelines while simultaneously elevating clinical evidence thresholds, forcing manufacturers to restructure regulatory affairs functions and accelerate software validation pipelines before CE marking deadlines.
Growth Catalysts
- MDR compliance infrastructure:Strengthened notified body oversight under EU MDR is filtering competition toward established players with biocompatibility documentation capabilities and post-market surveillance systems.
- Oncology outpatient migration:Hospital systems in Germany, France, and the United Kingdom are expanding chemotherapy administration in ambulatory settings to reduce inpatient bed occupancy.
- Patch pump miniaturization:Advances in micromechanical engineering and flexible electronics are enabling wearable insulin delivery platforms with sub-5% flow precision.
Market Restraints
- Notified body capacity bottleneck:CE marking queue delays under MDR transition timelines are extending product launch windows by 12-18 months for non-priority device categories.
- Lithium-ion cell supply concentration:Battery autonomy requirements exceeding eight hours create dependency on East Asian cell manufacturers, exposing procurement to shipping lane volatility.
- Elastomeric pump margin compression:Single-use disposable alternatives compete on total cost of ownership in short-cycle antibiotic therapy, limiting pricing power in high-volume hospital procurement.
Strategic Opportunities
- Nordic homecare reimbursement:Sweden and Denmark are harmonizing outpatient drug delivery reimbursement codes, creating contiguous market entry for connected ambulatory platforms.
- EU AI Act convergence:Machine-learning-enabled dose error reduction systems will face harmonized conformity assessment pathways, rewarding early algorithm validation investments.
- Smart pump software-as-service:Cloud-connected safety interlocks and remote dose monitoring are opening recurring revenue streams beyond hardware sales to hospital networks.
Industry Challenges
- Embedded systems cybersecurity certification:MDR Annex I requirements for software lifecycle processes demand specialized talent scarce in Central European medical device hubs.
- Legacy hospital IT integration:HL7 FHIR connectivity and electronic health record interoperability create deployment friction requiring site-specific customization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Ambulatory Infusion Pumps Market |
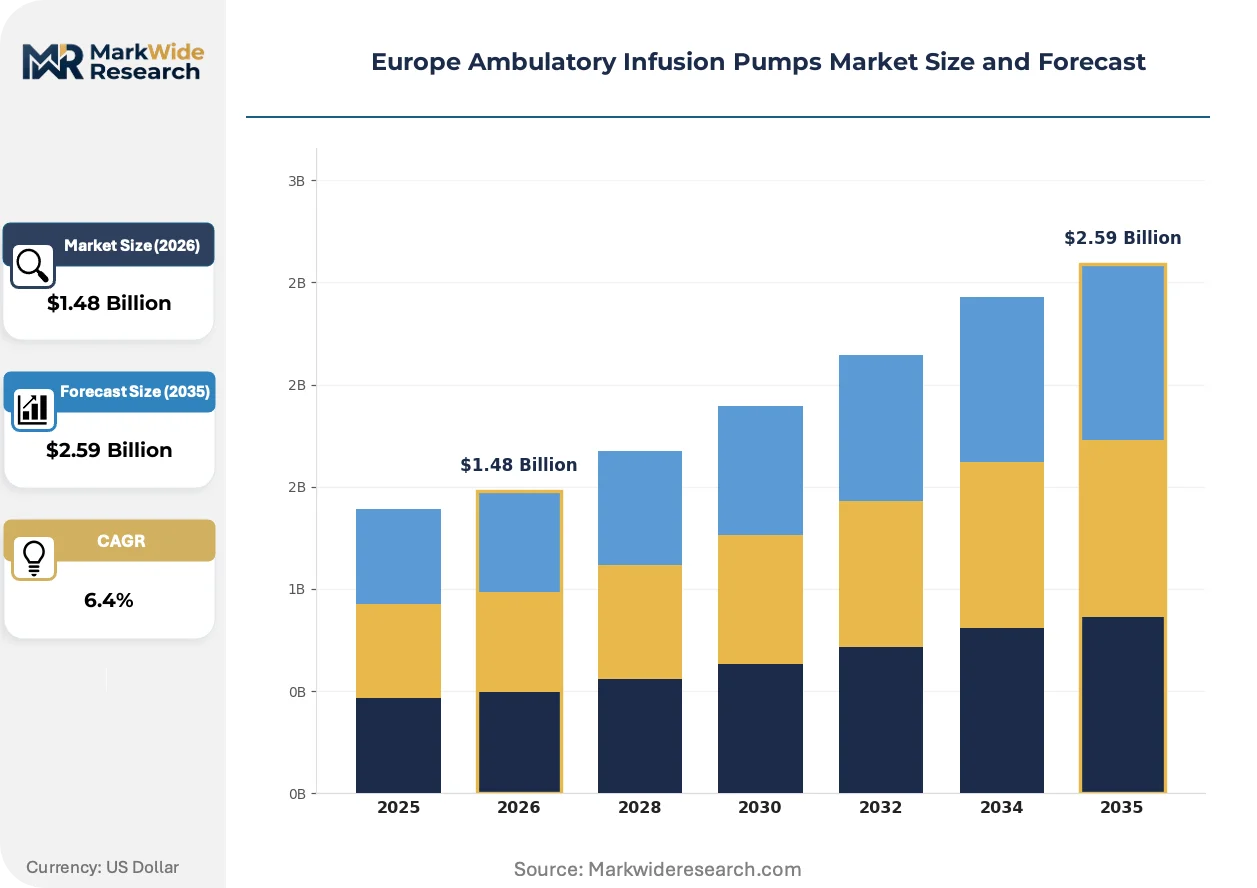
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Volumetric Pumps, Syringe Pumps, Elastomeric Pumps, Ambulatory Devices End User: Hospitals, Homecare, Clinics, Long-term Care Facilities Technology: Smart Pumps, Battery-operated, Mechanical, Manual Application: Oncology, Pain Management, Diabetes, Antibiotic Therapy |
| Companies Covered | B. Braun Melsungen AG, Fresenius Kabi AG, Baxter International Inc., Medtronic, BD, ICU Medical, Inc., Terumo Corporation, Smiths Medical, Ypsomed Holding AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Ambulatory Infusion Pumps Market Shifts & Advancements
Connectivity architectures and closed-loop control systems are redefining competitive differentiation in ambulatory infusion, compressing the gap between hospital-grade safety and homecare convenience.
Closed-loop glucose-insulin integration is unifying continuous monitoring with automated basal rate adjustment in patch pump form factors. Pediatric and Type 1 diabetes patient populations in the Netherlands and Belgium are piloting these systems through reimbursed remote monitoring programs. This convergence is compressing the traditional separation between diagnostic sensing and therapeutic delivery into single-platform chronic disease management.
EU MDR Article 10 post-market surveillance obligations are mandating systematic analysis of serious incidents and trend reporting across distributed device fleets. Manufacturers must now maintain vigilance systems capable of correlating field performance data with design documentation. Oncology ambulatory pumps face the steepest compliance burden due to high-risk classification and narrow therapeutic indices requiring traceable adverse event investigation.
Hospital procurement consortia are consolidating infusion device purchasing across integrated delivery networks in France and Italy. Traditional distributor relationships are yielding to direct manufacturer agreements with centralized technical service contracts. This concentration is most visible in Paris and Milan metropolitan regions where public hospital groups command multi-year framework agreements bundling hardware, disposables, and preventive maintenance.
Europe Ambulatory Infusion Pumps Market Segmentation
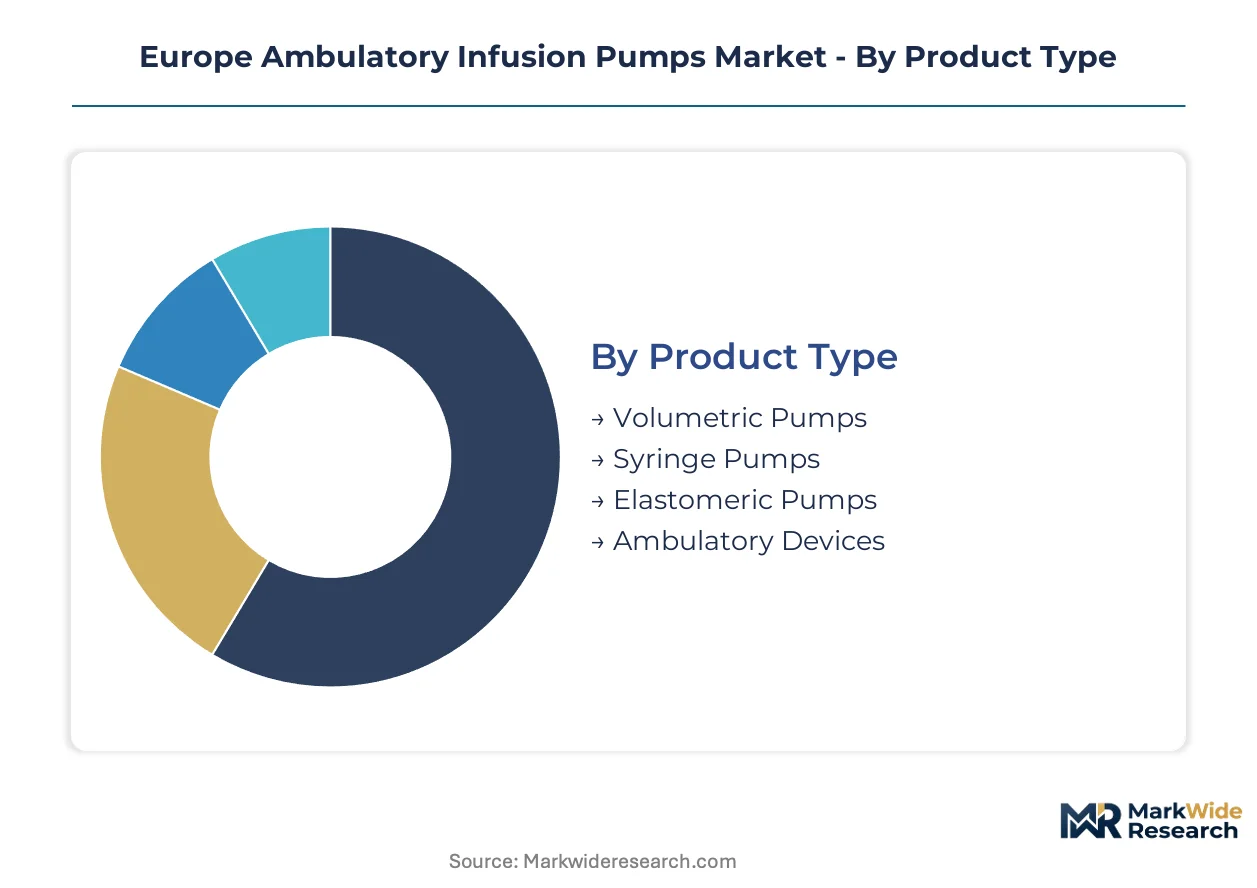
Segmentation in Europe's ambulatory infusion pumps market reveals divergent paths to value capture. Product architecture and care setting economics create distinct competitive arenas where precision engineering, regulatory compliance, and reimbursement alignment determine segment profitability.
Product Type:
Customization intensity spans from configurable electromechanical platforms to standardized disposable formats, with software-enabled differentiation commanding premium positioning.
- Volumetric Pumps:Electromechanical systems deliver precise fluid volumes through peristaltic or cassette mechanisms with programmable flow rates and occlusion detection. Demand concentrates in German and French hospital oncology wards where high-risk chemotherapy protocols require flow accuracy within plus or minus five percent and integrated dose error reduction software.
- Syringe Pumps:Compact motor-driven devices administer medications from prefilled syringes with high-pressure capability for viscous solutions or arterial lines. UK neonatal intensive care units and Swiss pediatric centers drive procurement, prioritizing compact footprint and bolus-dose flexibility for low-volume high-precision applications.
- Elastomeric Pumps:Disposable balloon reservoirs deliver antibiotics or analgesics through passive pressure without electronic components. Italian and Spanish outpatient clinics favor these for short-cycle therapy where total cost of ownership outweighs precision requirements.
- Ambulatory Devices:Wearable patch and pocket-sized pumps enable mobile therapy across homecare and ambulatory settings. Scandinavian reimbursement frameworks for diabetes and pain management are accelerating patient-controlled analulatory delivery adoption.
Most installed capacity flows through Volumetric Pumps. Expansion is steepest in Ambulatory Devices.
End User:
Procurement authority and reimbursement pathways fragment demand across institutional buyers and direct-to-patient channels, with margin structures inversely correlated to purchasing scale.
- Hospitals:Integrated delivery networks in Germany, France, and the United Kingdom negotiate multi-year framework agreements bundling hardware, disposables, and preventive maintenance. Centralized technical service contracts and cybersecurity compliance requirements favor established manufacturers with MDR-certified quality management systems.
- Homecare:Patients or family caregivers operate devices outside institutional supervision, requiring simplified interfaces and remote monitoring connectivity. Dutch and Belgian diabetes reimbursement programs are piloting closed-loop patch pump systems through reimbursed remote monitoring pathways.
- Clinics:Outpatient chemotherapy and antibiotic infusion centers balance throughput efficiency against capital constraints. French cancer centers and German day-clinics prioritize rapid patient turnover with pre-programmed disposable systems.
- Long-term Care Facilities:Nursing homes and rehabilitation centers manage chronic pain and parenteral nutrition for immobile populations. Swiss and Austrian elderly care networks seek durable devices with simplified training protocols for non-specialist staff.
Revenue concentration sits with Hospitals. Homecare is climbing the fastest as outpatient migration accelerates.
Technology:
Software integration intensity separates premium-tier platforms from commodity alternatives, with algorithm-enabled safety systems creating defendable differentiation.
- Smart Pumps:Network-connected devices with drug library databases, dose error reduction algorithms, and electronic health record interoperability. German university hospitals and Paris public hospital groups mandate these for high-alert medication protocols under strengthened EU MDR software lifecycle requirements.
- Battery-operated:Portable electromechanical pumps with lithium-ion power exceeding eight-hour autonomy for mobile therapy. Supply chain concentration in East Asian cell manufacturers exposes procurement to shipping lane volatility and raw material cost fluctuations.
- Mechanical:Spring-powered or elastomeric pressure systems without electronic components, offering disposability and lower unit economics. Short-cycle antibiotic therapy in Italian regional health systems favors these for uncomplicated outpatient protocols.
- Manual:Gravity-fed or hand-operated devices for emergency backup or resource-limited settings. Minimal presence in Western Europe outside humanitarian stockpiles and military medical reserves.
Deployment volume centers on Battery-operated systems. Smart Pumps are gaining share fastest as connectivity mandates tighten.
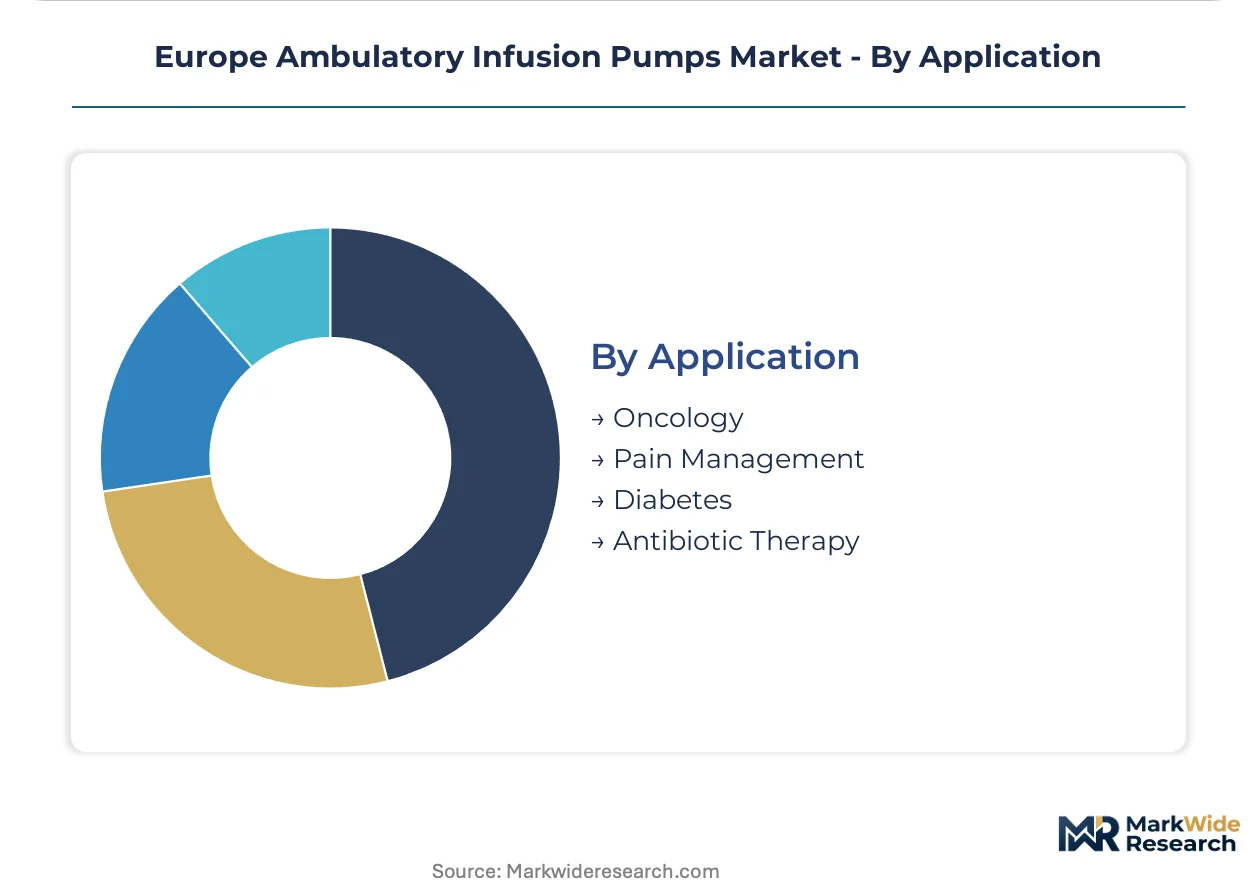
Application:
Therapeutic risk profiles and reimbursement generosity shape segment attractiveness, with narrow-index oncology therapies commanding highest safety investment.
- Oncology:Chemotherapy, immunotherapy, and supportive care medications delivered through continuous or intermittent infusion. German outpatient oncology networks and UK cancer alliances are expanding ambulatory administration to reduce inpatient bed occupancy, driving demand for portable precision pumps with traceable adverse event logging.
- Pain Management:Patient-controlled analgesia and continuous regional anesthesia for post-surgical and chronic pain. Swiss and Austrian chronic pain clinics are adopting wearable elastomeric systems for home-based palliative care.
- Diabetes:Insulin delivery through patch pumps or traditional ambulatory pumps with continuous glucose monitor integration. Netherlands and Belgium Type 1 diabetes populations are piloting closed-loop automated basal rate adjustment through reimbursed remote monitoring programs.
- Antibiotic Therapy:Extended-duration antimicrobial infusion for resistant infections or outpatient parenteral antibiotic therapy. Spanish and Portuguese hospital-at-home programs favor disposable elastomeric pumps for simplified logistics and reduced nursing visit frequency.
Clinical investment intensity peaks in Oncology. Diabetes is expanding most quickly as closed-loop integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as MDR compliance costs diverge across European jurisdictions, prompting precision device producers to consolidate electromechanical assembly in Germany and Switzerland while locating software development in lower-cost Central European tech clusters.
Germany
Hospital procurement consortia in North Rhine-Westphalia and Bavaria are expanding multi-year framework agreements for connected ambulatory platforms. The EU MDR transition timeline is compressing notified body capacity, favoring established manufacturers with existing BfArM rapporteur relationships. Tuttlingen's medical device cluster anchors electromechanical pump assembly, with suppliers deepening specialization in miniature motor systems for portable drug delivery.
United Kingdom
NHS cancer alliances are accelerating outpatient chemotherapy migration to reduce inpatient bed occupancy, driving demand for traceable adverse event logging in ambulatory pumps. MHRA convergence with EU MDR requirements is elevating software lifecycle documentation burdens for market entrants. The Oxford-Cambridge life sciences corridor hosts validation laboratories serving manufacturers seeking dual UK-EU market access.
France
Public hospital groups in Île-de-France are consolidating infusion device purchasing through centralized technical service contracts bundling hardware and preventive maintenance. ANSM post-market surveillance obligations mandate systematic trend reporting across distributed device fleets. The Paris-Saclay medtech ecosystem is attracting algorithm development talent for dose error reduction systems.
Switzerland
Swissmedic's streamlined quality system assessments are drawing EU manufacturers seeking parallel conformity pathways for premium-tier devices. Reimbursement harmonization across cantonal health insurers is standardizing outpatient insulin pump coverage. The Solothurn-Jura watchmaking basin is transferring micromechanical expertise to wearable patch pump miniaturization, with suppliers achieving sub-5% flow precision in flexible electronics integration.
Netherlands
Dutch diabetes reimbursement programs are piloting closed-loop patch pump systems through remote monitoring pathways, creating reference markets for automated basal rate adjustment. The EMA's centralized marketing authorization procedures are streamlining combination product assessments for manufacturers with Amsterdam-based regulatory affairs functions. The Brainport Eindhoven high-tech cluster is developing flexible printed circuit manufacturing for conformable wearable drug delivery platforms.
Europe Ambulatory Infusion Pumps Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue software-enabled differentiation and closed-loop integration. The vendor base stratifies across three maturity levels: diversified healthcare conglomerates with integrated infusion therapy portfolios, mid-cap specialists with concentrated electromechanical expertise, and venture-backed innovators attacking patch pump miniaturization. Consolidation pressure is intensifying as MDR compliance costs filter sub-scale participants, while strategic partnerships between hardware manufacturers and algorithm developers are accelerating closed-loop platform development.
Among German-based diversified manufacturers, B. Braun Melsungen AG and Fresenius Kabi AG exemplify the integrated healthcare conglomerate archetype with captive supply networks spanning precision component fabrication to hospital service contracts. Swiss specialist Ypsomed Holding AG occupies a distinct position within the wearable drug delivery tier, representing engineering-intensive miniaturization capabilities transferable across diabetes, oncology, and pain management applications. These three anchors collectively demonstrate how geographic clustering around regulatory expertise and precision manufacturing heritage creates defendable positioning in an increasingly compliance-driven market.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Fresenius Kabi AG |
| Baxter International Inc. |
| Medtronic |
| BD |
| ICU Medical, Inc. |
| Terumo Corporation |
| Smiths Medical |
| Ypsomed Holding AG |
| Others |
Supply & Pricing Matrix
Hospital procurement consortia in Germany, France, and the United Kingdom negotiate multi-year framework agreements that compress distributor margins while bundling hardware, disposables, and preventive maintenance into single-contract pricing.
Pricing Analysis
Distributor margins in the ambulatory infusion pump channel have compressed from traditional medical device markups toward direct-manufacturer contracting as hospital groups consolidate purchasing authority. Pricing stratifies across premium smart pumps with dose error reduction software, standard battery-operated electromechanical systems, and economy elastomeric disposables. Cost compression in the elastomeric tier is intensifying because Italian and Spanish regional health systems prioritize total cost of ownership over precision specifications. Homecare patients demonstrate highest price sensitivity, while German university hospitals accept premium positioning for MDR-certified connected platforms with cybersecurity validation.
Supply Chain Analysis
Freight costs from East Asian lithium-ion cell manufacturers have exposed European pump assemblers to shipping lane volatility, prompting inventory buffer expansion at German and Swiss final assembly sites. Electromechanical component manufacturing concentrates in Germany, Switzerland, and China, with precision motor systems sourced from Tuttlingen and Solothurn-Jura clusters. Battery autonomy requirements exceeding eight hours tether procurement to South Korean and Japanese cell suppliers, creating single-source vulnerability during maritime disruption. Distribution runs through hospital procurement consortia and specialized medical device distributors serving outpatient clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Europe's ambulatory infusion pump market rests on software-enabled service revenue and MDR compliance infrastructure that filters competition toward scaled players.
For Market Incumbents: To counter notified body capacity bottlenecks extending CE marking timelines, B. Braun and Fresenius Kabi should deepen captive supply of precision motor systems through Tuttlingen cluster partnerships while accelerating software validation pipelines for EU AI Act convergence on algorithm-enabled dose reduction systems. For New Entrants and Emerging Players: Scandinavian homecare reimbursement programs for diabetes patch pumps represent the most penetrable entry point, with Dutch and Belgian remote monitoring pilots offering reference market validation before German hospital procurement engagement. For Investors and Strategic Acquirers: Diversified healthcare conglomerates with integrated infusion therapy portfolios are the most active acquirer in this space, seeking algorithm development capabilities for closed-loop glucose-insulin integration. Watch Nordic reimbursement harmonization as the inflection signal for connected ambulatory platform viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR software lifecycle documentation accelerates market access for established notified body relationships. |
| Hospital System Partnership | Multi-year framework agreements with Paris and Milan public hospital groups lock in recurring maintenance revenue. |
| Software Companion Development | Cloud-connected safety interlocks enable SaaS revenue streams beyond hardware sales to German networks. |
| Reimbursement Strategy | Harmonized outpatient drug delivery codes in Sweden and Denmark create contiguous market entry for patch pumps. |
| Backward Integration | In-house production of miniature motor systems defends margin position against East Asian component volatility. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineers, regulatory affairs leads at notified bodies, and GPO contracts managers grounded this analysis in procurement decision dynamics. Secondary validation drew from EMA combination product guidelines, EU MDR transition timelines, hospital procurement databases, and CMS Medicare reimbursement data. Bottom-up installed base estimates triangulated against top-down therapy volume projections across the analysis window.
Segment-level value outputs reflect modeling across product architecture, care setting economics, therapeutic application risk profiles, and technology integration intensity. CAGRs derived from procedure volume growth, reimbursement pathway maturation, and replacement cycle dynamics in connected platforms. Forecast inputs incorporated MDR compliance cost trajectories and lithium-ion cell supply concentration risk.
Underlying measurement precision varies by segment; smart pump and oncology application forecasts carry tighter precision than mechanical alternatives. Projections reflect assumptions on notified body capacity expansion and national reimbursement harmonization timelines. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Africa Ultrasound Devices Market
Medical Devices
ePTFE Vascular Prosthesis Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Liver-On-Chip Market
Medical Devices
US Thrombectomy Devices Market
Medical Devices
Retinal Surgery Devices Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Therapeutic Contact Lenses Market
Medical Devices
Neurotechnology Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Global PC-Based Audiometer Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Gastric Electrical Stimulators Market
Medical Devices
Europe Spinal Fusion Devices Market