
 Global Drug Eluting Balloon Catheters Market | 2026-2036
Global Drug Eluting Balloon Catheters Market Size, Share, and Industry Trends Forecast 2026-2036
Global Drug Eluting Balloon Catheters Market Foresight
Germany is fragmenting its catheter supply base as domestic manufacturers and Asian exporters compete for contracts with university hospitals in Munich and Berlin. Medtronic leverages its integrated balloon-coating facilities in Ireland to sustain cost advantages across European tenders. Boston Scientific Corporation anchors its position in North American electrophysiology labs through specialized scoring balloon designs.
Drug eluting balloon catheters are semi-compliant angioplasty devices coated with antiproliferative agents such as paclitaxel or sirolimus, designed to deliver localized drug transfer to vessel walls during inflation while minimizing systemic exposure. The coating matrix typically employs a urea-based excipient to control release kinetics over 30 to 60 days post-intervention, primarily inhibiting neointimal hyperplasia in coronary and peripheral revascularization. Drug-coated balloon catheters now command the highest margin pools as hospitals prioritize single-procedure efficacy over bare-metal stent alternatives. Peripheral artery disease applications are expanding fastest among therapy areas as limb-salvage protocols gain traction in diabetic patient populations.
FDA premarket notification requirements and EMA's Medical Device Regulation (MDR) compliance deadlines are reshaping product registration strategies, with manufacturers consolidating technical documentation across notified bodies. Japan's PMDA has tightened pharmacokinetic validation standards for drug-device combinations, extending review timelines for new coating formulations. Stakeholders must monitor how reimbursement recalibrations in Medicare and Japan's Diagnosis Procedure Combination system alter site-of-service economics for outpatient angioplasty.
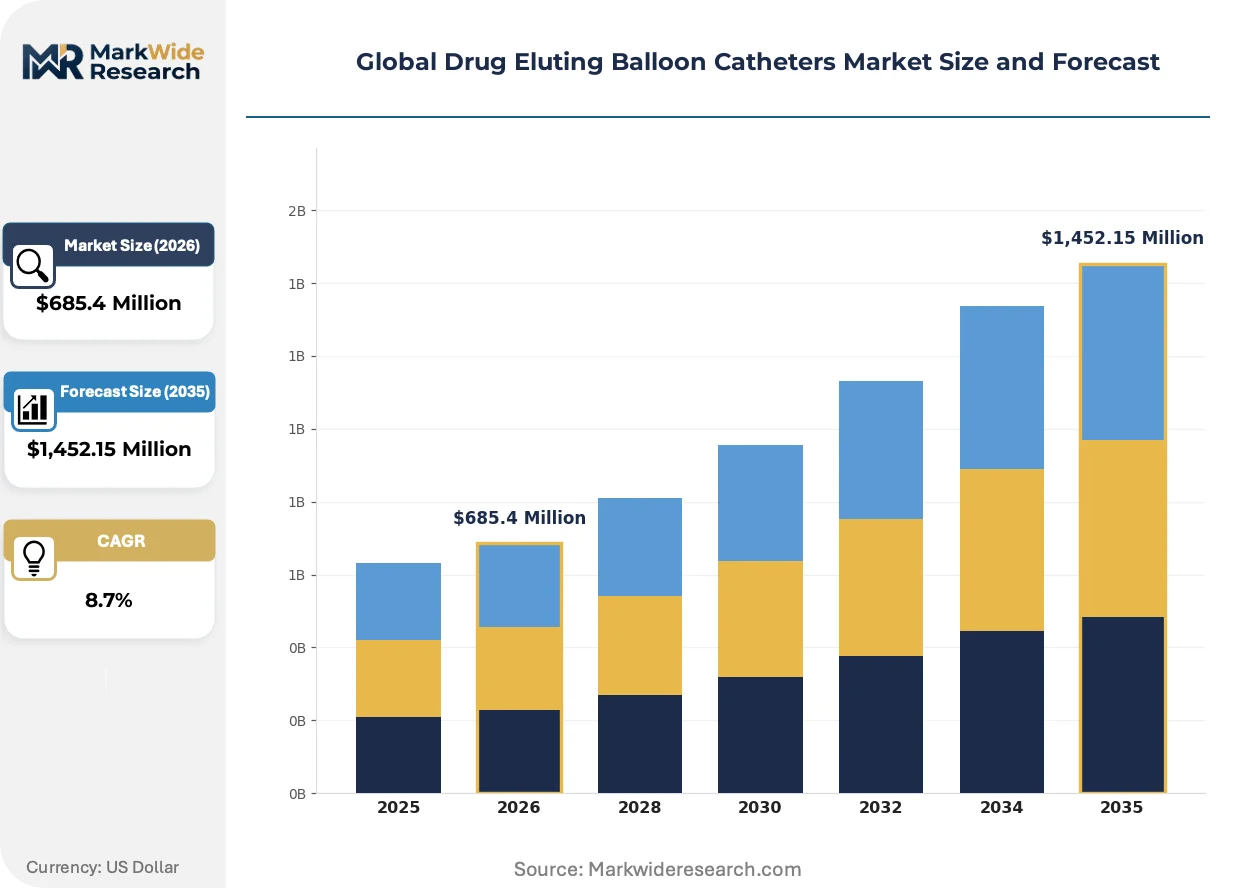
Market Dynamics
The drug eluting balloon catheters market is restructuring around coating formulation differentiation, as manufacturers race to demonstrate superior tissue retention kinetics while navigating divergent pharmacokinetic validation standards across FDA, EMA, and PMDA jurisdictions.
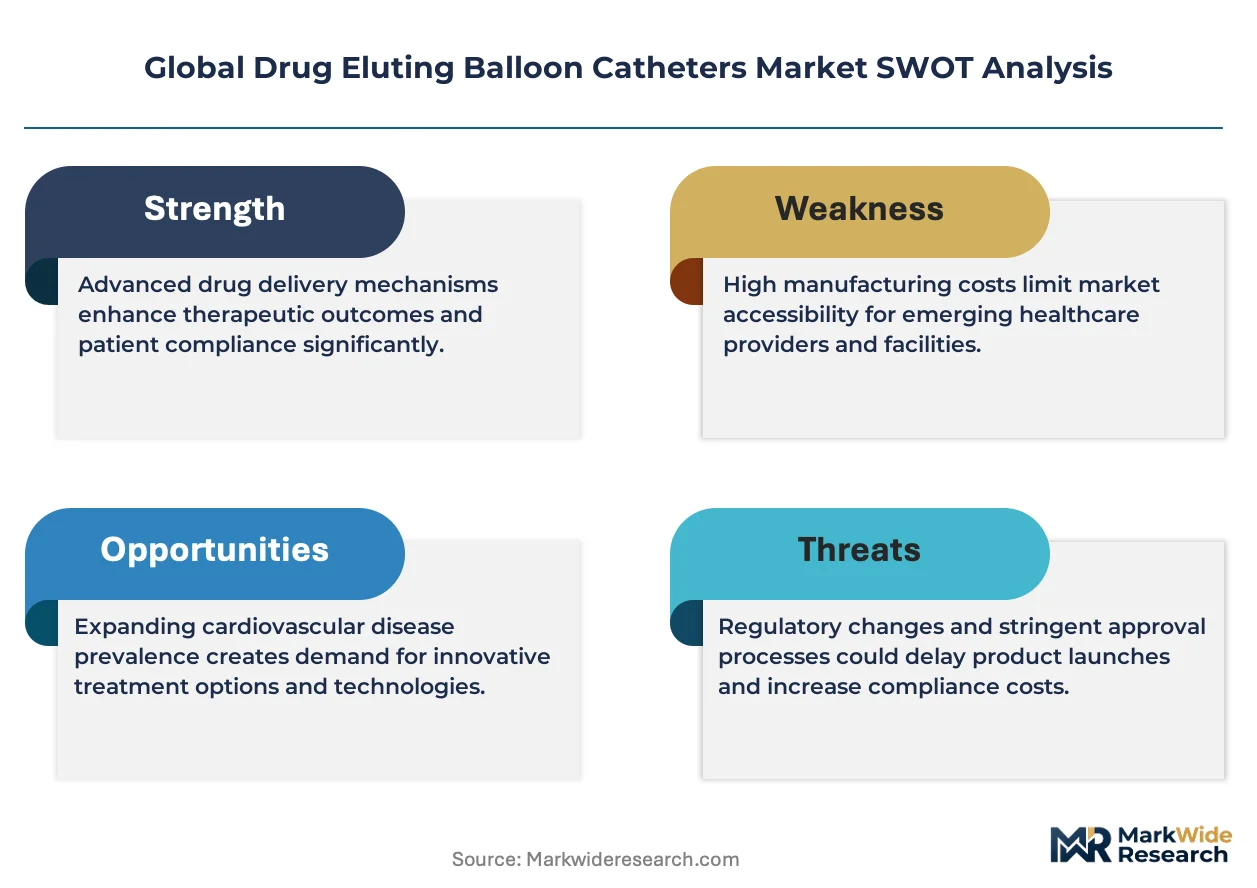
Growth Catalysts
- Japan's Diagnosis Procedure Combination reimbursement expansion:The national health insurance system's coverage alignment for drug-coated balloon angioplasty accelerates hospital procurement cycles in Tokyo and Osaka metropolitan clusters.
- Peripheral artery disease limb-salvage protocols:Diabetic patient populations in Germany and the United States drive procedural volume expansion as amputation-prevention guidelines elevate catheter-based revascularization priority.
- Paclitaxel excipient matrix advances:Urea-based coating technologies with controlled 30-to-60-day release profiles improve neointimal hyperplasia inhibition outcomes, elevating physician preference over bare-metal stent alternatives.
Market Restraints
- Polymer supply concentration in Ireland and Germany:Coating matrix raw material production clusters in specific European manufacturing zones create vulnerability to regional logistics disruptions.
- PMDA pharmacokinetic validation stringency:Japan's tightened drug-device combination review timelines extend new formulation approval cycles, compressing revenue recognition windows for innovative coatings.
- Bare-metal stent residual cost advantage:Price-sensitive healthcare systems in select geographies retain legacy stent purchasing patterns despite inferior restenosis outcomes.
Strategic Opportunities
- India's interventional cardiology infrastructure buildout:Government hospital expansion programs in Mumbai, Delhi, and Bangalore create first-mover positioning for coating technology licensors.
- Coronary in-stent restenosis salvage applications:Second-line therapy positioning for drug eluting balloons in failed stent cases opens procedural categories previously dominated by repeat revascularization surgery.
- FDA streamlined premarket notification pathways:Updated combination device submission frameworks reduce clearance timeline variability, enabling faster geographic rollout sequencing.
Industry Challenges
- Coating uniformity quality control:Sub-micron paclitaxel distribution consistency across balloon surfaces demands specialized metrology capabilities scarce in contract manufacturing organizations.
- EMA MDR technical documentation consolidation:Manufacturers face redundant notified body engagement costs as European regulatory alignment deadlines compress compliance resource allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Drug Eluting Balloon Catheters Market |
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Balloon Catheters, High-Pressure Balloon Catheters, Cutting Balloon Catheters, Drug-Coated Balloon Catheters, Scoring Balloon Catheters Therapy Area: Cardiovascular Disease, Peripheral Artery Disease, Neurovascular Interventions, Urological Treatments, Gynecological Applications End User: Cardiology Centers, Specialty Clinics, Ambulatory Surgical Facilities, Medical Research Institutes, Diagnostic Laboratories Delivery Method: Over-the-Wire, Rapid Exchange, Dual Lumen, Balloon-Only, Hybrid Systems |
| Companies Covered | Medtronic, Boston Scientific Corporation, B. Braun SE, BD, Koninklijke Philips N.V., BIOTRONIK, Terumo Corporation, MedAlliance, Cook Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Drug Eluting Balloon Catheters Market Shifts & Advancements
Coating science convergence with computational modeling is compressing formulation development cycles. Three developments are restructuring competitive positioning.
Excipient-controlled release kinetics is virtualizing traditional empirical coating development. Computational fluid dynamics models now predict paclitaxel tissue penetration depth before physical prototyping. Cardiology research centers in Munich and Rotterdam adopt these in-silico validation protocols, compressing preclinical study timelines by eliminating iterative bench testing iterations.
EMA's Medical Device Regulation recertification mandates are forcing portfolio rationalization across European notified bodies. Manufacturers consolidate technical documentation under single conformity assessment procedures to avoid redundant audit costs. German and French catheter producers accelerate MDR transition spending ahead of 2024-2025 deadline clustering, prioritizing high-margin peripheral artery platforms over legacy coronary devices.
Hospital procurement committees now unbundle device selection from physician preference cards. Integrated delivery networks in the United States and Japan centralize catheter purchasing through value-analysis committees, displacing individual operator brand loyalty with outcome metrics and total procedural cost benchmarking. This concentration compresses supplier count per metropolitan hospital system from six-to-eight vendors to two-to-three preferred contracting relationships.
Global Drug Eluting Balloon Catheters Market Segmentation
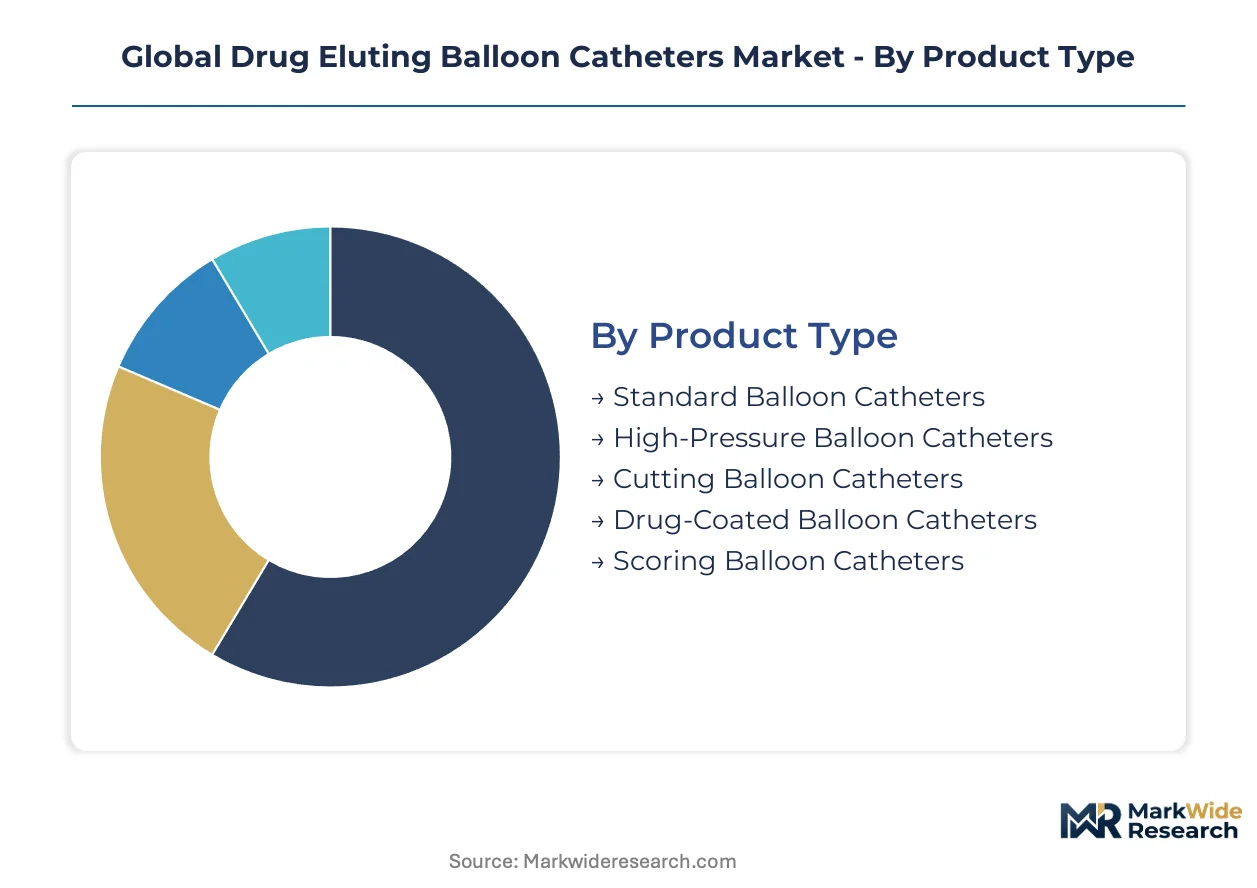
Drug eluting balloon catheter segmentation reveals how coating technology, procedural setting, and anatomical target interact to determine purchasing criteria. Manufacturers align R&D pipelines with the highest-margin intersections of these dimensions.
Product Type:
The use-case spectrum spans from routine angioplasty to lesion modification requiring mechanical scoring or cutting capability.
- Drug-Coated Balloon Catheters:Paclitaxel or sirolimus coatings with urea-based excipient matrices enable controlled 30-to-60-day drug release kinetics. Cardiology centers in Germany and Japan prioritize these platforms for in-stent restenosis salvage cases where stent reimplantation carries elevated thrombosis risk.
- Scoring Balloon Catheters:Longitudinal nitinol wires embedded in the balloon surface create controlled micro-incisions during inflation. Boston Scientific Corporation anchors North American electrophysiology lab demand through specialized designs that optimize lesion preparation before drug-coated balloon delivery.
- Standard Balloon Catheters:Semi-compliant polyethylene terephthalate construction for baseline vessel predilation.
- High-Pressure Balloon Catheters:Non-compliant nylon blends rated for 20+ atmospheres to address calcified lesions.
- Cutting Balloon Catheters:Atherotome-equipped platforms for fibrotic plaque modification in peripheral applications.
Established volume favors drug-coated platforms; emerging adoption favors scoring balloon designs as lesion preparation protocols standardize.
Therapy Area:
Cost tier stratification separates high-reimbursement cardiovascular procedures from emerging peripheral and neurovascular applications.
- Peripheral Artery Disease:Limb-salvage protocols for diabetic populations drive procedural expansion in Germany and the United States. Below-the-knee revascularization now represents the steepest expansion trajectory as amputation-prevention guidelines elevate catheter-based intervention priority over surgical bypass.
- Cardiovascular Disease:Coronary drug-coated balloon angioplasty commands premium pricing in established markets. Tokyo and Osaka metropolitan clusters accelerate procurement through Japan's Diagnosis Procedure Combination reimbursement alignment.
- Neurovascular Interventions:Emerging applications in intracranial atherosclerosis with specialized low-profile delivery systems.
- Urological Treatments:Benign prostatic hyperplasia and urethral stricture dilation with coated balloon platforms.
- Gynecological Applications:Fallopian tube recanalization and endometrial ablation support procedures.
Mature reimbursement stabilizes cardiovascular volumes; procedural innovation expands peripheral artery disease fastest.
End User:
Customer type determines procurement complexity, from centralized hospital value-analysis committees to decentralized clinic purchasing.
- Cardiology Centers:University hospitals in Munich and Berlin fragment supply bases as domestic manufacturers compete with Asian exporters for interventional suite contracts. Integrated delivery networks in the United States consolidate purchasing through outcome metrics and total procedural cost benchmarking.
- Ambulatory Surgical Facilities:Site-of-service economics shift as Medicare reimbursement recalibrations favor outpatient angioplasty. These settings prioritize single-procedure efficacy and rapid patient turnover over device brand loyalty.
- Specialty Clinics:Peripheral vascular-focused practices with concentrated diabetic patient populations.
- Medical Research Institutes:Clinical trial sites driving pharmacokinetic validation for new coating formulations.
- Diagnostic Laboratories:Ancillary catheter deployment for vascular access and imaging support.
Procurement concentration favors cardiology centers; volume growth shifts toward ambulatory surgical facilities.
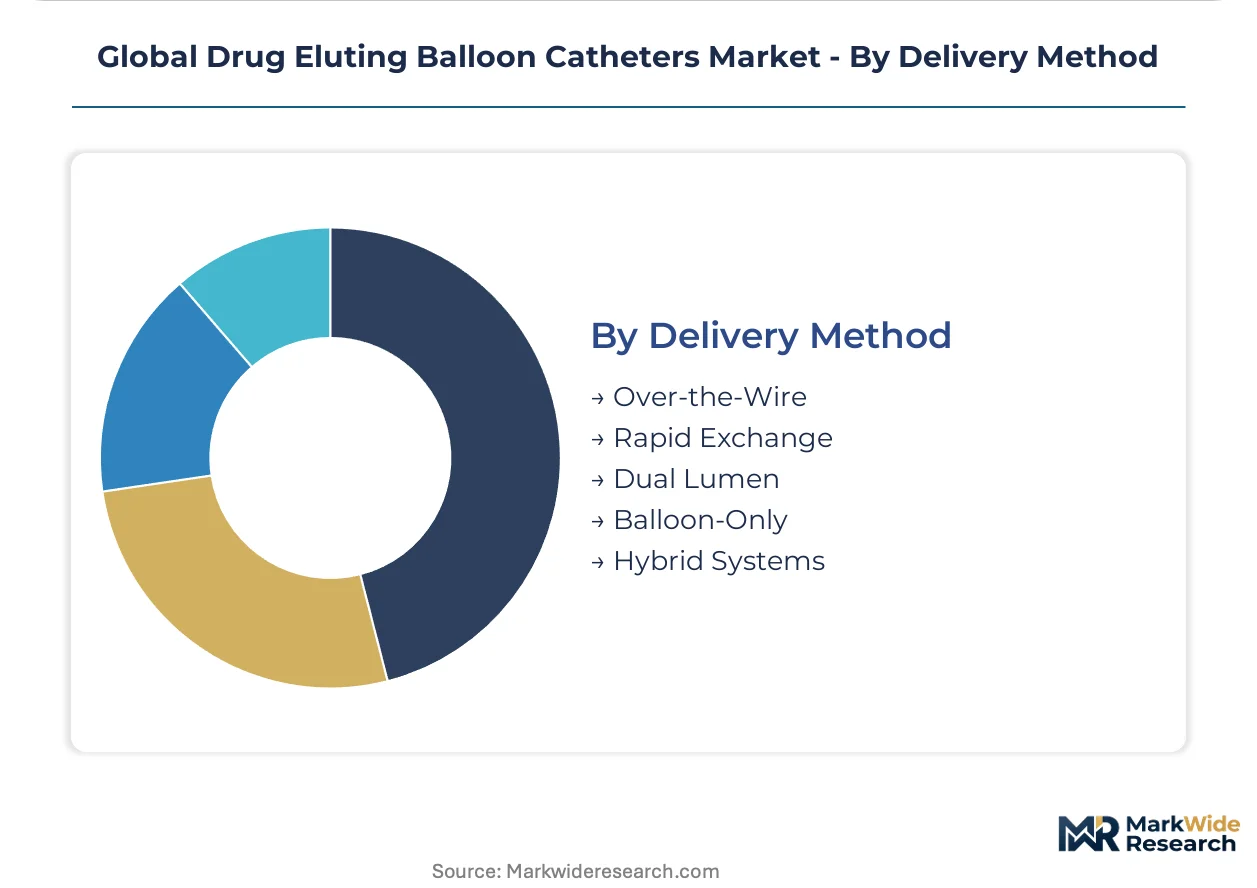
Delivery Method:
Supply concentration in polymer and coating technology clusters shapes manufacturing economics across platform architectures.
- Rapid Exchange:Single-operator design with short guidewire lumen segment enabling rapid catheter exchanges. Munich and Rotterdam cardiology research centers adopt these platforms for complex multivessel interventions requiring sequential lesion treatment.
- Over-the-Wire:Full-length guidewire lumen provides superior trackability in tortuous anatomy. Medtronic leverages integrated balloon-coating facilities in Ireland to sustain cost advantages across European tenders for these longer-procedure platforms.
- Dual Lumen:Simultaneous guidewire and inflation media channels for specialized lesion access.
- Balloon-Only:Bare platforms for coating customization by third-party manufacturers.
- Hybrid Systems:Convertible rapid exchange-over-the-wire configurations for procedural flexibility.
Clinical preference stabilizes rapid exchange dominance; complex case volumes sustain over-the-wire positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer supply for coating matrices clusters in Ireland and Germany, yet procedural demand concentrates in aging metropolitan clusters across Japan, Germany, and the United States where reimbursement alignment accelerates hospital procurement cycles.
United States
Medicare reimbursement recalibrations favor outpatient angioplasty site-of-service economics, shifting volume toward ambulatory surgical facilities. FDA streamlined premarket notification pathways for combination devices reduce clearance timeline variability. Integrated delivery networks in Texas and Florida centralize catheter purchasing through value-analysis committees that benchmark total procedural cost.
Germany
University hospitals in Munich and Berlin fragment supply bases as domestic manufacturers compete with Asian exporters for interventional suite contracts. EMA MDR compliance deadlines compress technical documentation consolidation timelines. Cardiology centers in the Rhine-Ruhr metropolitan cluster expand interventional suites to accommodate complex peripheral artery procedures in diabetic populations.
Japan
Aging demographics in Tokyo and Osaka metropolitan clusters accelerate hospital procurement cycles for drug-coated balloon angioplasty. PMDA tightened pharmacokinetic validation standards extend review timelines for new coating formulations. The Diagnosis Procedure Combination reimbursement expansion aligns national health insurance coverage with procedural innovation.
India
Government hospital expansion programs in Mumbai, Delhi, and Bangalore create first-mover positioning for coating technology licensors. CDSCO regulatory pathways for drug-device combinations mature as domestic clinical trial infrastructure scales. Interventional cardiology infrastructure buildout concentrates in Maharashtra and Karnataka state hospital systems.
China
Domestic manufacturers scale coating capabilities to serve provincial hospital procurement centralization. NMPA review timelines for paclitaxel-coated platforms stabilize as local pharmacokinetic validation standards align with international norms. Manufacturing investment clusters in Jiangsu and Zhejiang provinces support cost-competitive balloon production.
Global Drug Eluting Balloon Catheters Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in coating matrix and excipient supply. The vendor base separates into consolidated multinational device platforms and fragmented regional coating technology providers. Three archetypes dominate: integrated balloon-coating facilities, specialized scoring balloon designers, and third-party coating licensors. Competitive moves concentrate on M&A for regulatory approval bundling and capacity expansion in polymer supply zones.
Among integrated platform providers, Medtronic anchors European tender participation through Ireland-based manufacturing, while Boston Scientific Corporation occupies a position in North American electrophysiology lab supply. B. Braun SE exemplifies the diversified medtech conglomerate archetype with catheter portfolios spanning multiple interventional specialties. These three represent distinct strategic postures: captive coating integration, specialized lesion preparation focus, and broad interventional platform breadth.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific Corporation |
| B. Braun SE |
| BD |
| Koninklijke Philips N.V. |
| BIOTRONIK |
| Terumo Corporation |
| MedAlliance |
| Cook Medical |
| Others |
Supply & Pricing Matrix
Ireland's integrated balloon-coating facilities anchor European supply capacity, with Medtronic's captive production in Galway translating into tender participation advantages that compress competitor pricing power across German university hospital contracts. The concentration of urea-based excipient manufacturing in the Rhine-Ruhr cluster and polymer supply in Irish pharmaceutical zones creates asymmetric cost positions that downstream device makers exploit in procurement negotiations with Tokyo and Osaka metropolitan hospital systems.
Pricing Analysis
EMA's Medical Device Regulation dictates the pricing tier structure across European notified bodies, with CE marking tier separating premium drug-coated platforms from standard semi-compliant alternatives. FDA premarket notification pathways create parallel tiering in North American markets, where integrated delivery networks benchmark total procedural cost to consolidate vendor relationships. Cost compression in standard balloon segments intensifies as Asian exporters penetrate German procurement, while premium drug-coated platforms retain margin resilience through pharmacokinetic validation barriers. Ambulatory surgical facilities exhibit highest price sensitivity, prioritizing single-procedure efficacy metrics over brand premiums; cardiology centers in Japan demonstrate lowest sensitivity, aligning procurement with Diagnosis Procedure Combination reimbursement optimization.
Supply Chain Analysis
Tariff exposure between Ireland and Germany dominates supply chain risk planning for coating matrix raw materials, with urea-based excipient production concentrated in the Rhine-Ruhr metropolitan cluster and polymer synthesis anchored in Irish pharmaceutical manufacturing zones. Paclitaxel active pharmaceutical ingredient supply draws from Indian and Chinese bulk chemical producers, while nitinol wire for scoring platforms sources from specialized German metallurgical suppliers. Single-source vulnerability in sub-micron coating metrology equipment creates procurement bottlenecks for contract manufacturers lacking in-house quality control capabilities. Distribution runs through hospital value-analysis committees in the United States and centralized procurement authorities in Japan's metropolitan clusters, displacing traditional physician-driven purchasing patterns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The drug eluting balloon catheter market exhibits cyclical recovery characteristics tied to reimbursement recalibration cycles, with Medicare site-of-service economics and Japan's Diagnosis Procedure Combination expansion driving procedural volume normalization after regulatory review delays.
For Market Incumbents: Entrench coating formulation differentiation through captive excipient matrix production in Ireland or Germany, insulating margin positions from Asian exporter price competition in standard balloon segments. Accelerate MDR technical documentation consolidation ahead of European deadline clustering to capture notified body capacity before competitor submissions create audit queue bottlenecks. Prioritize pharmacokinetic validation investment for paclitaxel tissue retention kinetics, as PMDA stringency extends review timelines and compresses revenue recognition windows for under-resourced challengers. For New Entrants and Emerging Players: Build out coating technology licensing partnerships with Maharashtra and Karnataka state hospital systems in India, where government infrastructure expansion creates first-mover positioning absent entrenched vendor relationships. Target peripheral artery disease applications in below-the-knee revascularization, the steepest expansion trajectory as limb-salvage protocols elevate catheter-based intervention priority over surgical bypass in diabetic populations. Pursue go-to-market alignment with CDSCO regulatory pathway maturation, leveraging domestic clinical trial infrastructure scaling to accelerate approval timelines relative to multinational incumbent submission sequences. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors coating formulation specialists with validated pharmacokinetic datasets and established notified body relationships, as regulatory stringency consolidates competitive advantage around incumbent capabilities. Long-term viability over the next decade hinges on computational modeling integration for in-silico validation protocols, compressing development cycles and reducing iterative bench testing capital intensity. Acquisition target archetype: regional coating technology providers with PMDA submission experience and existing urea-based excipient production capacity. Signal to watch: FDA premarket notification pathway utilization rates for combination device submissions, indicating geographic rollout sequencing speed and revenue recognition timing.| Strategic Initiative | Industry Significance |
|---|---|
| Coating Formulation Patent Expansion | Urea-based excipient matrix IP in Germany and Ireland protects 30-to-60-day release kinetics advantages. |
| MDR Technical Documentation Consolidation | Single notified body engagement reduces redundant audit costs ahead of European deadline clustering. |
| PMDA Pharmacokinetic Validation Investment | Accelerated tissue retention data generation compresses review timelines for innovative coating submissions. |
| India Hospital System Partnership | Maharashtra and Karnataka state procurement relationships establish first-mover positioning in infrastructure buildout. |
| Computational Modeling Capability Acquisition | In-silico validation protocols in Munich and Rotterdam eliminate iterative bench testing iterations. |
Research Methodology
A spread of perspectives from interventional cardiologists, hospital procurement committee chairs, biomedical engineers, regulatory affairs specialists, and GPO contracts managers converged on the working assumptions underlying demand projections. Primary interview data combined with secondary validation from FDA 510(k) filings, EMA MDR submission databases, PMDA approval records, and hospital procurement contract repositories. Bottom-up procedural volume estimates triangulated against top-down device shipment data from customs records and distributor disclosures across the analysis window.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning coating technology type, procedural setting, anatomical target, and delivery method architecture. CAGRs derived from fitted growth curves applied to normalized baseline volumes, adjusted for reimbursement recalibration timing and regulatory approval pathway completion rates. Industry-specific forecast inputs incorporated pharmacokinetic validation timeline distributions and notified body audit queue depth estimates.
Practitioners should monitor PMDA review timeline extensions, Medicare site-of-service reimbursement recalibrations, and polymer supply logistics disruptions for early signals of forecast deviation. Operating assumptions reflect documented regulatory pathway frameworks and hospital procurement centralization trends. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cardiovascular Devices
Pulmonary Artery Catheter Market
Cardiovascular Devices
Endovascular Stent Market
Cardiovascular Devices
Cerebral Vascular Stent Market
Cardiovascular Devices
Fluid Aspiration System Market
Cardiovascular Devices
Global PTA Balloon Catheter Market
Cardiovascular Devices
Global Cardiac Output Monitoring Devices Market
Cardiovascular Devices
Percutaneous Transluminal Coronary Angioplasty (PTCA) Balloon Catheters Market
Cardiovascular Devices
Global Vascular Patch Market
Cardiovascular Devices
Percutaneous Coronary Intervention Market
Cardiovascular Devices
Branched Stent Grafts Market
Cardiovascular Devices
3D Cardiac Mapping Systems Market
Cardiovascular Devices
Vascular Screening Market
Cardiovascular Devices
Global Resuscitation Devices Market
Cardiovascular Devices
Cardiovascular Diagnostic and Monitoring Devices Market
Cardiovascular Devices
Vascular Access Catheters Market
Cardiovascular Devices
Europe Cardiac Assist Devices Market