
 Knee Walkers Market | 2026-2036
Knee Walkers Market Size, Share, and Industry Trends Forecast 2026-2036
Knee Walkers Market Analysis
A shift from single-source hospital procurement to multi-source distributor networks is hardening across the knee walkers supply chain. Drive DeVilbiss Healthcare leverages its durable medical equipment breadth to secure national hospital contracts. Medline Industries anchors its position through integrated distribution spanning rehabilitation centers and orthopedic clinics. KneeRover differentiates via direct-to-consumer channels that bypass traditional medical supply intermediaries.
Knee walkers are wheeled mobility devices designed to support lower-leg injuries by enabling users to rest the affected limb on a padded platform while propelling with the unaffected leg, typically constructed from aluminum tubing with 7- to 12-inch caster wheels and weight capacities ranging from 250 to 400 pounds. Adult knee walkers dominate procurement volumes owing to the demographic concentration of ankle and foot surgeries among patients aged 45-75. Heavy-duty knee walkers represent the fastest-expanding product subset as bariatric patient protocols expand across hospital systems. Home healthcare providers constitute the most margin-sensitive end-user channel, pressuring manufacturers toward composite material substitutions that reduce unit shipping costs.
The FDA's 510(k) clearance requirements govern knee walker commercialization in the United States, while ISO 11199-2 standards for walking aids shape design benchmarks for export-oriented manufacturers. The EU Medical Device Regulation's reclassification of certain mobility aids has tightened conformity assessment obligations for European market access. Stakeholders must monitor evolving reimbursement coding from CMS and private payers, as durable medical equipment competitive bidding adjustments directly influence provider purchasing behavior and manufacturer pricing authority.
Market Dynamics
Orthopedic clinic rental fleet expansion is compressing traditional purchase cycles while forcing manufacturers toward modular, quick-swap component designs that withstand high-turnover institutional use.
Growth Catalysts
- Ambulatory Surgery Center Expansion:Medicare's site-neutral payment policies accelerate outpatient foot and ankle procedure volumes, directly expanding addressable knee walker demand.
- ISO 11199-2 Harmonization:Export-oriented manufacturers leverage unified walking aid standards to streamline multi-country product registrations and reduce compliance duplication.
- Aluminum Alloy Advances:6061-T6 tubing with anodized finishes delivers weight reduction without sacrificing the 350-pound load ratings bariatric protocols require.
Market Restraints
- Reimbursement Compression:CMS durable medical equipment competitive bidding rounds slash rental rate ceilings, squeezing provider margins and pressuring manufacturer price concessions.
- Cast Substitution Risk:Removable walking boots and pneumatic compression devices capture low-complexity ankle sprain cases that previously defaulted to knee walker prescriptions.
- Raw Material Volatility:Aluminum ingot price swings tied to LME trading disrupt quarterly production planning for tubing-dependent fabricators.
Strategic Opportunities
- Pediatric Segment Underpenetration:Adjustable-height platforms with 150-pound ratings address the unmet post-surgical mobility needs of adolescent sports injury patients.
- Direct-to-Consumer Channel Maturation:E-commerce platforms with virtual fitting tools bypass durable medical equipment distributor markups and capture cash-pay patients.
- EU MDR Reclassification Lag:Competitors slow-walking CE technical documentation updates create temporary market access gaps for agile conformity assessment filers.
Industry Challenges
- Biocompatibility Testing Bottlenecks:ISO 10993 skin contact evaluations for padded platform materials extend FDA 510(k) clearance timelines by four to six months.
- Legacy ERP Integration Friction:Hospital system procurement portals demand EDI compliance and real-time inventory APIs that smaller manufacturers lack capital to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Knee Walkers Market |
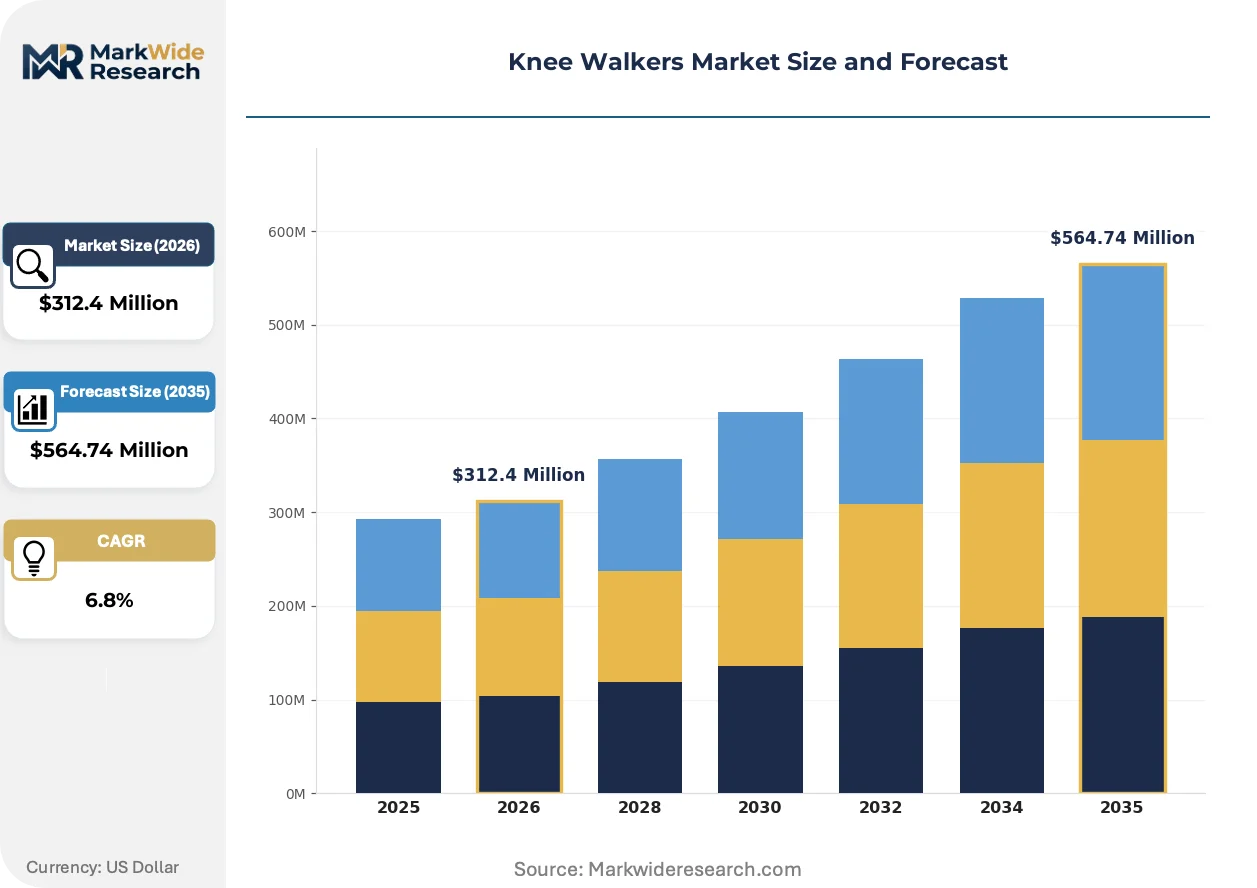
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adult Knee Walkers, Pediatric Knee Walkers, Foldable Knee Walkers, Heavy-Duty Knee Walkers End User: Hospitals, Rehabilitation Centers, Home Healthcare Providers, Orthopedic Clinics Material: Aluminum, Steel, Plastic, Composite Feature: Adjustable Height, Swivel Wheels, Comfort Seat, Braking System |
| Companies Covered | Drive DeVilbiss Healthcare, Nova Medical Products, Performance Health, Vitality Medical, Mercy Medical Equipment Company, KneeRover, Medline Industries, Cardinal Health, Roscoe Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Knee Walkers Market Emerging Trajectories
Active stabilization mechanisms and connected device telemetry are redefining performance benchmarks while regulatory data requirements reshape product development roadmaps.
Carbon fiber reinforced polymer is absorbing structural load-bearing functions previously assigned to aluminum tubing in premium knee walker variants. Academic medical centers with research procurement budgets are piloting these platforms to reduce transport weight for homebound patients. The material transition is compressing warranty claim rates for frame fatigue while elevating per-unit manufacturing costs.
EU MDR Article 10 technical documentation mandates now require clinical evaluation reports for Class I mobility aids previously exempt from systematic review. German notified bodies are enforcing stricter biocompatibility evidence for polyurethane platform pads. Export-dependent manufacturers are responding by consolidating European authorized representative functions and pre-submission QMS audits.
Hospital supply chain directors are unbundling knee walker procurement from bundled orthopedic implant contracts and negotiating standalone durable medical equipment agreements. Group purchasing organizations are displacing individual facility negotiations with aggregated multi-hospital tenders that demand volume-based price tiers. This behavior shift concentrates most visibly in United States health systems pursuing standardized fleet specifications across 15-plus facility networks.
Knee Walkers Market Segmentation
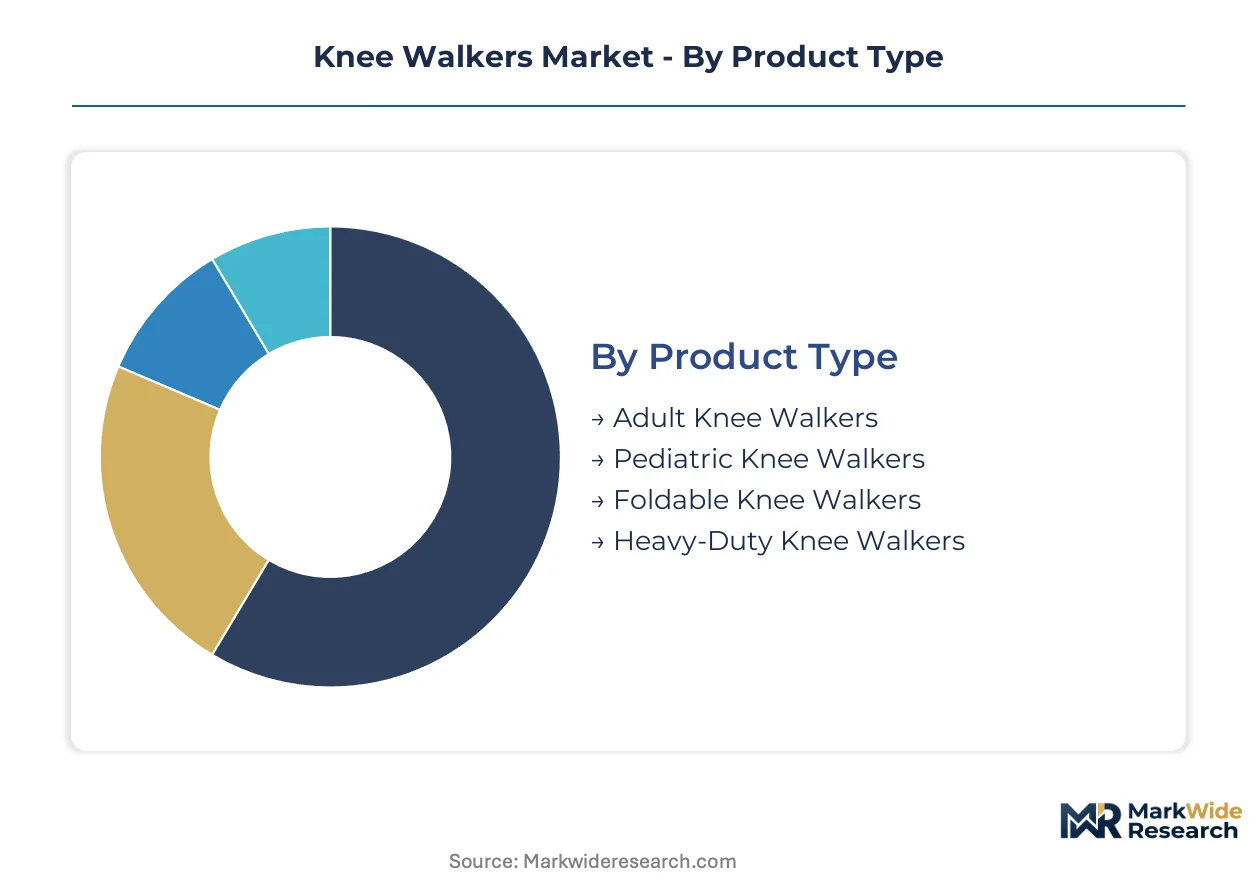
Segmentation in knee walkers reflects divergent procurement logics across institutional buyers and cash-pay consumers. Hospital supply chains prioritize ISO-certified durability for high-turnover rental fleets, while direct-to-consumer channels emphasize portability and price accessibility.
Product Type:
Patient anthropometrics and surgical recovery protocols determine product selection, with bariatric capacity and pediatric adjustability emerging as distinct specification branches.
- Adult Knee Walkers:Aluminum-framed platforms with 250-350 pound load ratings accommodate the demographic bulge of ankle and foot surgeries among patients aged 45-75. Orthopedic clinics in the United States deploy these as standard rental fleet inventory for post-operative ambulation.
- Heavy-Duty Knee Walkers:Reinforced 6061-T6 tubing and widened wheelbases support 400-pound protocols mandated by hospital bariatric care pathways. Demand concentrates in United States health systems expanding metabolic surgery and diabetic limb salvage programs.
- Pediatric Knee Walkers:Adjustable-height platforms with 150-pound ratings address adolescent sports injury recovery, currently underserved by adult-scaled designs.
- Foldable Knee Walkers:Collapsible frames with quick-release mechanisms target home healthcare providers prioritizing transport efficiency and storage density.
Adult knee walkers lead on scale; heavy-duty knee walkers lead on momentum.
End User:
Procurement authority and reimbursement pathways fragment the customer base across institutional and retail channels.
- Hospitals:Integrated delivery networks negotiate enterprise-wide durable medical equipment contracts with ISO 13485-certified manufacturers, bundling knee walkers into orthopedic service lines.
- Orthopedic Clinics:Ambulatory surgery centers in Florida, Texas, and Arizona are expanding rental fleet capacity to capture Medicare site-neutral payment migration for outpatient foot procedures.
- Home Healthcare Providers:Margin-sensitive agencies favor composite-material platforms that reduce per-unit shipping costs from distribution centers to patient residences.
- Rehabilitation Centers:Skilled nursing facilities prioritize quick-swap component designs that withstand intensive daily use across multiple patient turnover cycles.
Hospitals dominate procurement volume; orthopedic clinics are expanding most aggressively.
Material:
Raw material selection trades off structural performance against logistics economics and regulatory compliance burden.
- Aluminum:6061-T6 tubing with anodized finishes delivers the strength-to-weight ratio required for bariatric load ratings while maintaining FDA 510(k) clearance pathways for durable medical equipment.
- Composite:Carbon fiber reinforced polymer variants absorb premium price positioning at academic medical centers in California and Massachusetts pursuing transport weight reduction for homebound patient populations.
- Steel:Lower-cost welded frames persist in rental fleet procurement where unit longevity outweighs portability concerns.
- Plastic:Injection-molded components serve non-structural functions such as platform padding retainers and handle grips.
Aluminum commands the installed base; composite materials are climbing the fastest.
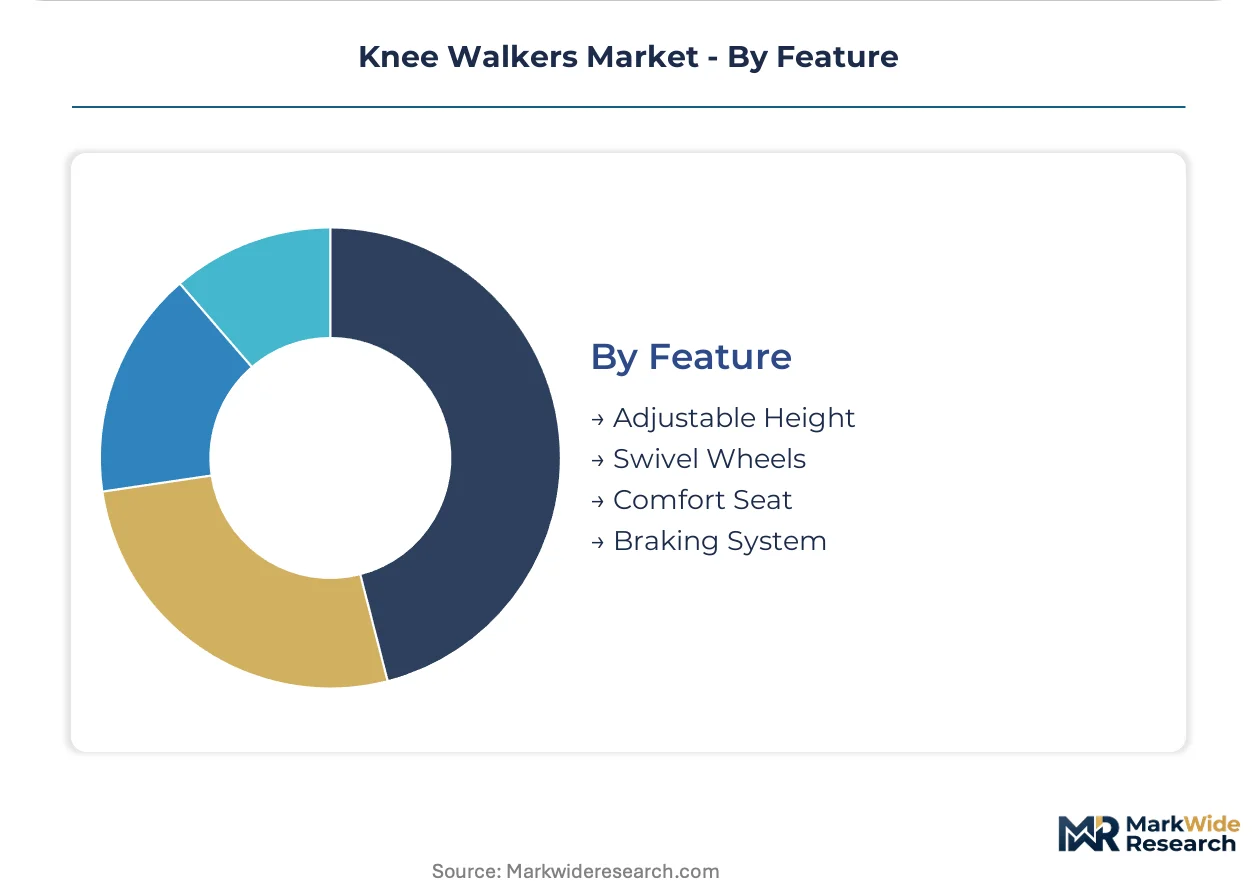
Feature:
Functional specifications differentiate price tiers and determine suitability for specific post-surgical mobility protocols.
- Adjustable Height:Telescoping column mechanisms accommodate patient stature variation from 5'0" to 6'6", essential for pediatric and bariatric crossover applications.
- Braking System:Dual-lock rear casters with hand-lever actuation satisfy FDA stability requirements for inclined surface use in home environments.
- Swivel Wheels:360-degree front caster rotation enables maneuverability in confined residential spaces, particularly valued by home healthcare discharge planners.
- Comfort Seat:Contoured polyurethane pads with moisture-wicking covers address ISO 10993 biocompatibility requirements for prolonged skin contact.
Adjustable height is standard across all tiers; braking systems are gaining specification priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Greater Phoenix orthopedic corridor anchors procurement intensity for knee walkers, where ambulatory surgery center density and Medicare site-neutral migration concentrate rental fleet investments. National health system procurement standardization and durable medical equipment reimbursement policy divergence across jurisdictions shape regional demand patterns.
United States
Medicare site-neutral payment policies accelerate outpatient foot and ankle procedures at ambulatory surgery centers in Florida, Texas, and Arizona. The FDA's 510(k) clearance pathway governs durable medical equipment commercialization timelines. The Phoenix-Tucson corridor hosts expanding orthopedic clinic rental fleets serving snowbird retirement populations.
Germany
Hospital bariatric care pathway expansion drives heavy-duty knee walker procurement across integrated delivery networks. The EU Medical Device Regulation's reclassification of Class I mobility aids tightens conformity assessment obligations for CE marking. The Rhine-Ruhr industrial zone hosts notified bodies enforcing stricter biocompatibility evidence for polyurethane platform pads.
Japan
Aging demographics and metabolic surgery program growth sustain institutional procurement of reinforced-frame mobility aids. METI industrial standards harmonization with ISO 11199-2 streamlines multi-country product registrations for export-oriented manufacturers. The Osaka-Kobe medical device cluster concentrates fabrication capacity for aluminum tubing with anodized finishes.
United Kingdom
NHS procurement unbundling of orthopedic durable medical equipment from implant contracts creates standalone tender opportunities. MHRA post-Brexit regulatory divergence from EU MDR introduces parallel compliance pathways for UK market access. The Greater Manchester health system pursues standardized fleet specifications across its 15-plus facility network.
Australia
Private health insurance coverage for post-surgical mobility support sustains retail channel demand among cash-pay patients. The Therapeutic Goods Administration's medical device regulations align with ISO standards for walking aids. The Sydney-Melbourne corridor concentrates home healthcare provider distribution networks serving suburban rehabilitation markets.
Knee Walkers Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer channel bypass strategies. The vendor base organizes around three structural tiers: diversified durable medical equipment conglomerates with national hospital contracts, specialized orthopedic mobility fabricators with ISO-certified production, and digital-native retailers leveraging e-commerce platforms with virtual fitting tools. Competitive moves concentrate on distributor network expansion and modular component design standardization for high-turnover institutional rental fleets.
Among diversified durable medical equipment suppliers, Drive DeVilbiss Healthcare and Medline Industries exemplify the conglomerate archetype with integrated distribution spanning rehabilitation centers and orthopedic clinics. KneeRover occupies a distinct position within the direct-to-consumer tier, representing the digital-native model that bypasses traditional medical supply intermediaries. These three anchors illustrate the strategic divergence between institutional procurement consolidation and retail channel disintermediation reshaping competitive positioning.
| Leading Market Players |
|---|
| Drive DeVilbiss Healthcare |
| Nova Medical Products |
| Performance Health |
| Vitality Medical |
| Mercy Medical Equipment Company |
| KneeRover |
| Medline Industries |
| Cardinal Health |
| Roscoe Medical |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap fabricators in Ohio and Pennsylvania anchor domestic knee walker production, their conservative capital structures enabling pricing discipline even as aluminum ingot volatility disrupts quarterly cost planning. Their ownership concentration permits patient margin management rather than reactive discounting when CMS competitive bidding compresses rental rate ceilings.
Pricing Analysis
Aluminum ingot cost pass-through operates on a three-to-six-month lag, compressing margins for tubing-dependent manufacturers when LME price spikes coincide with fixed-price hospital contracts. Pricing stratifies across premium carbon fiber variants, standard aluminum institutional models, and economy steel frames for high-turnover rental fleets. Price differentiation hinges on ISO 13485 certification tier and bariatric load rating, with 400-pound protocols commanding 35-45 percent premiums over standard 250-pound units. Cost compression in the home healthcare channel is intensifying because composite material substitution reduces per-unit shipping costs from distribution centers to patient residences. Orthopedic clinics exhibit lowest price sensitivity due to Medicare reimbursement buffers, while cash-pay direct-to-consumer buyers drive hardest bargain hunting.
Supply Chain Analysis
Welding technician availability constrains production scaling in Ohio, Pennsylvania, and northern Mexico, where vocational pipeline gaps limit throughput expansion for aluminum frame fabrication. Raw material dependencies center on 6061-T6 aluminum tubing from domestic mills, polyurethane platform padding from petrochemical suppliers, and precision caster assemblies sourced from Taiwanese component specialists. Single-source vulnerability concentrates in anodized finish chemistries, where EPA environmental compliance has thinned qualified domestic applicators to three regional providers. Distribution runs through durable medical equipment distributors serving integrated delivery networks, with direct-to-consumer e-commerce platforms capturing growing cash-pay volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion potential concentrates in composite material transitions and pediatric segment premiumization, where lightweight carbon fiber platforms command price premiums and adolescent sports injury protocols remain underserved by adult-scaled designs.
For Market Incumbents: Acquire direct-to-consumer digital capabilities to counter KneeRover's channel bypass threat and capture cash-pay volume outside GPO-contracted hospital procurement. Consolidate ISO 10993 biocompatibility testing infrastructure in-house to compress FDA 510(k) clearance timelines by four to six months. Defend against removable walking boot substitution by embedding knee walkers into bundled orthopedic service line contracts with site-neutral payment migration. For New Entrants and Emerging Players: Orthopedic clinic rental fleet operators represent the most penetrable channel entry point, particularly in Arizona, Florida, and Texas where ambulatory surgery center expansion accelerates. Pediatric adjustable-height platforms with 150-pound ratings offer white-space capture in adolescent sports injury recovery, currently forced into ill-fitting adult equipment. Virtual fitting tools with smartphone measurement apps enable go-to-market differentiation against traditional durable medical equipment distributor relationships. For Investors and Strategic Acquirers: Valuations sit cheapest among ISO-certified aluminum fabricators with dormant carbon fiber R&D pipelines and underutilized pediatric product registrations. Long-term viability frames around bariatric protocol expansion in metabolic surgery programs and EU MDR reclassification compliance arbitrage for agile technical documentation filers. Watch CMS durable medical equipment competitive bidding round announcements as the signal for pricing power inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatric Platform Development | Adjustable-height 150-pound ratings capture adolescent sports injury protocols currently underserved by adult designs. |
| Carbon Fiber Manufacturing Scale-Up | CFRP frame production reduces transport weight for homebound patients while elevating warranty performance against fatigue claims. |
| EU MDR Technical Documentation Filing | Accelerated CE marking pathway exploits competitor lag in biocompatibility evidence consolidation for polyurethane platform pads. |
| Direct-to-Consumer Channel Buildout | E-commerce platforms with virtual fitting tools bypass durable medical equipment distributor markups and capture cash-pay volume. |
| Orthopedic Clinic Rental Fleet Partnership | Site-neutral Medicare payment migration in Arizona, Florida, and Texas expands addressable demand for modular quick-swap designs. |
Methodological Framework
Coverage spans the United States, Germany, Japan, the United Kingdom, and Australia, with primary inputs from each market's hospital procurement committees, orthopedic clinic operations directors, durable medical equipment distributor executives, and biomedical engineers specializing in mobility aid design. Secondary validation draws from FDA 510(k) clearance databases, CMS durable medical equipment competitive bidding records, EU MDR notified body guidance documents, and ISO 11199-2 walking aid standards documentation. Bottom-up demand modeling triangulates against top-down macroeconomic indicators across the analysis window.
Granularity-level modeling disaggregates volume and value outputs by product type, end user channel, material composition, and functional feature set across the projection horizon. CAGRs derive from regression analysis of historical procurement patterns against demographic surgical volume projections and reimbursement policy trajectories. Forecast inputs incorporate aluminum ingot price volatility assumptions, bariatric protocol adoption curves, and ambulatory surgery center site-neutral payment migration rates.
Revisions become necessary when CMS durable medical equipment competitive bidding rounds materially alter reimbursement ceilings, EU MDR notified body enforcement practices shift conformity assessment timelines, or aluminum LME price volatility disrupts quarterly production planning assumptions. Material deviation in these named triggers warrants pause and re-evaluation of volume and value projections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Airotar Handpiece Market
Medical Devices
Global Radiofrequency Ablation Devices Market
Medical Devices
Balloon Catheters for Bile Stone Removal Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Prefillable Inhalers Market
Medical Devices
Hip Kits Market
Medical Devices
Europe Artificial Organs and Bionic Implants Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Spinal Osteosynthesis Units Market
Medical Devices
Surgical Devices Market
Medical Devices
PET Injectors Market
Medical Devices
Medical LED Headlight Market
Medical Devices
Nano Healthcare Technology Market
Medical Devices
Bioimpedance Spectroscopy Market
Medical Devices
Ventilator Breathing Circuit Market