
 Arthroscopy Visualization Systems Market | 2026-2036
Arthroscopy Visualization Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Arthroscopy Visualization Systems Market Outlook
Ambulatory surgical centers is consolidating as the fastest-expanding end-use vertical for arthroscopy visualization systems, displacing traditional hospital-only procurement models across North America and Western Europe. Stryker Corporation leverages integrated operating room ecosystems to bundle camera systems with surgical instruments. Arthrex Inc. anchors its position through specialized sports medicine visualization platforms. Smith & Nephew plc competes on R&D intensity in 4K imaging modules for shoulder and knee procedures.
Arthroscopy visualization systems comprise high-resolution camera heads, light sources, image processors, and display monitors engineered to transmit real-time intra-articular imagery through rigid or flexible endoscopes with optical resolutions spanning HD to 4K and beyond. These systems enable minimally invasive diagnostic and therapeutic procedures across orthopedic surgery, sports medicine, and trauma interventions by magnifying joint structures for precise instrument navigation. Camera systems command the largest revenue share within product type segmentation due to recurring upgrade cycles and proprietary connector ecosystems that lock in replacement demand. 4K imaging technology leads technology segmentation in growth velocity as surgical teams prioritize tissue differentiation and depth perception, while 3D visualization occupies a nascent but expanding niche in complex reconstructive procedures where spatial orientation proves critical.
FDA 510(k) clearance requirements and EU MDR conformity assessments shape product development timelines and market access trajectories for arthroscopy visualization systems sold in the United States and European member states. ISO 13485 quality management standards and IEC 60601-1 electrical safety specifications govern manufacturing consistency and international commercialization eligibility across jurisdictions. Stakeholders must monitor reimbursement parity between inpatient and outpatient arthroscopic procedures as payor policies determine site-of-service economics and capital equipment placement decisions.
Market Dynamics
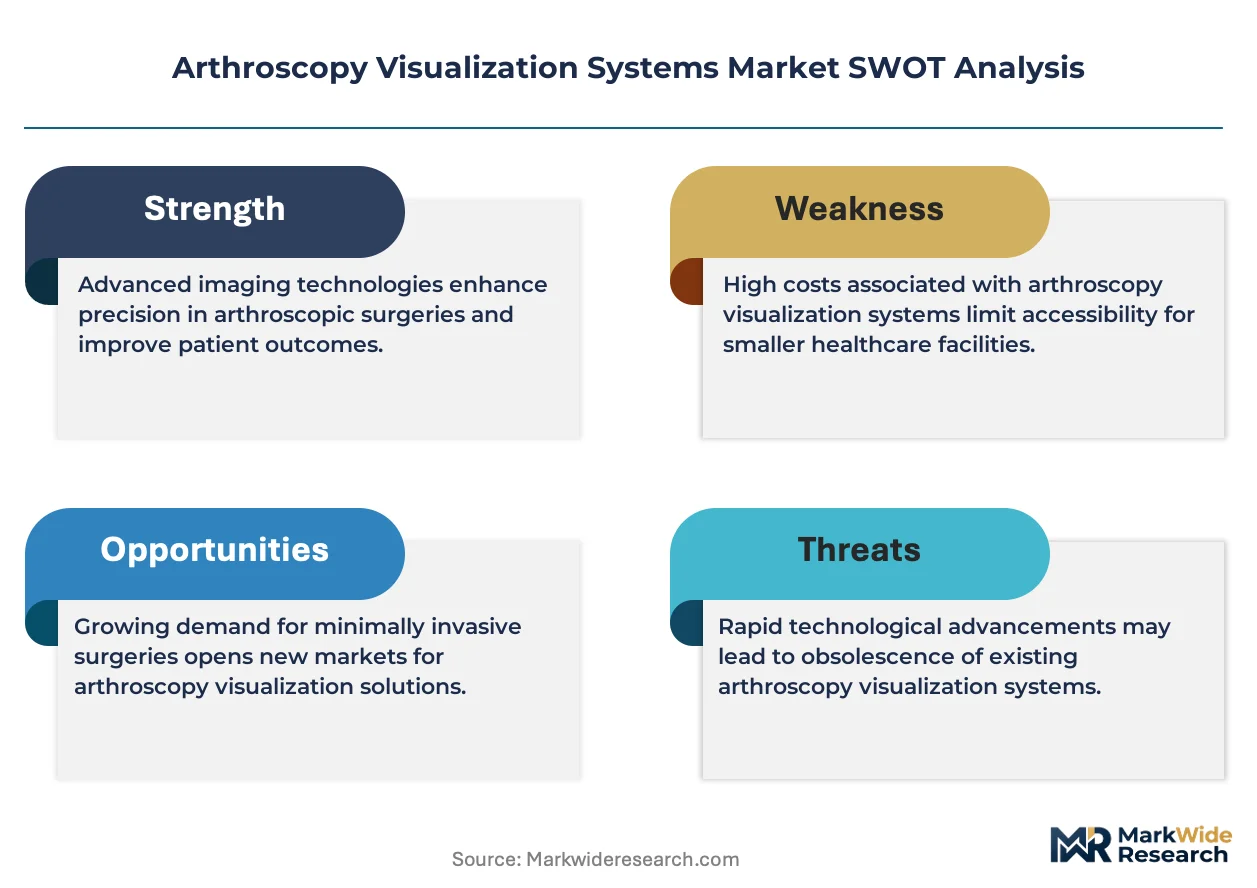
The migration of arthroscopic procedures from inpatient settings to ambulatory surgical centers is compressing capital equipment replacement cycles and forcing manufacturers to rebundle service contracts around utilization-based models rather than traditional ownership structures.
Growth Catalysts
- FDA 510(k) clearance pathways:Expedited review timelines for predicate-device submissions are accelerating commercialization of next-generation camera heads and image processors in the United States.
- Sports medicine demand:Rising volumes of ACL reconstruction and rotator cuff repair procedures are driving capital allocation toward dedicated arthroscopy suites in orthopedic specialty clinics.
- 4K imaging module penetration:Surgeon demand for enhanced tissue differentiation is pulling upgrade cycles forward in high-volume knee and shoulder arthroscopy centers.
Market Restraints
- Optical component supply concentration:Precision lens grinding and CMOS sensor fabrication capacity clusters in Germany and Japan, creating vulnerability to regional production disruptions.
- EU MDR conformity assessment bottlenecks:Extended notified body audit queues are delaying market access for novel visualization system submissions in European member states.
- Capital equipment substitution:Leasing and reconditioned device programs are displacing new system purchases among mid-tier ambulatory surgical centers.
Strategic Opportunities
- India's orthopedic infrastructure buildout:Government hospital modernization programs and private specialty clinic chains are creating first-mover advantages for visualization system vendors establishing local service networks.
- AI-assisted image processing convergence:Integration of real-time anatomical recognition algorithms with 4K camera streams is opening premium pricing tiers for intelligent arthroscopy platforms.
- Outpatient procedure reimbursement parity:CMS site-of-service payment adjustments are incentivizing ambulatory surgical center capital investment in dedicated arthroscopy visualization suites.
Industry Challenges
- Biomedical engineer talent scarcity:Specialized expertise in optical-mechanical integration and IEC 60601-1 electrical safety compliance is concentrating among a limited pool of experienced professionals.
- Legacy system interoperability:Proprietary connector ecosystems from incumbent manufacturers are complicating multi-vendor operating room configurations and driving integration service costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Arthroscopy Visualization Systems Market |
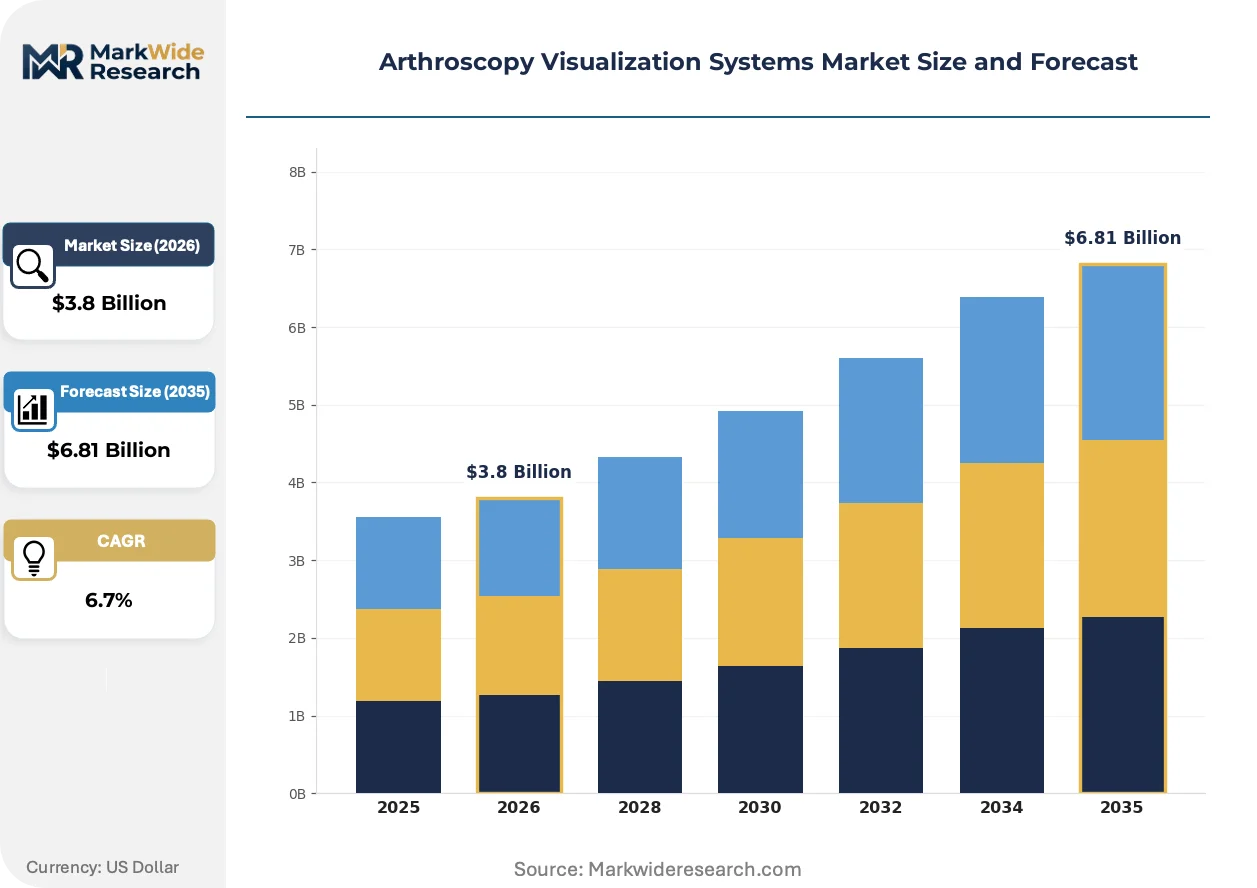
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Endoscopes, Flexible Endoscopes, Camera Systems, Visualization Software Technology: HD Imaging, 4K Imaging, Augmented Reality, 3D Visualization End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Application: Orthopedic Surgery, Sports Medicine, General Surgery, Trauma Surgery |
| Companies Covered | Stryker Corporation, Arthrex Inc., Smith & Nephew plc, Johnson & Johnson Services Inc., KARL STORZ SE & Co. KG, CONMED Corporation, Olympus Corporation, Richard Wolf GmbH, Zimmer Biomet Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Arthroscopy Visualization Systems Market Strategic Shifts
Image fidelity standards, regulatory data requirements, and procurement contracting models are simultaneously evolving, forcing arthroscopy visualization system vendors to coordinate hardware roadmaps with service architecture redesigns.
4K ultra-high-definition camera systems are expanding into standard equipment configurations across high-volume orthopedic centers. Ambulatory surgical centers in Germany and the United States are adopting these platforms within compressed 24-to-36-month replacement windows. The technology is expanding into complex reconstructive procedures previously reserved for open surgical approaches, enabling minimally invasive techniques in hip and ankle arthroscopy.
EU MDR technical documentation requirements are mandating expanded clinical evidence packages for Class IIa and IIb arthroscopy devices. Manufacturers must now submit post-market surveillance data and risk management files that exceed prior Medical Device Directive standards. Camera system and light source categories face the steepest compliance cost increases, with European notified bodies prioritizing audits of reusable surgical instrument integrations.
Hospital procurement departments are consolidating vendor relationships through integrated operating room ecosystem contracts. Single-source agreements bundling visualization hardware, instruments, and maintenance services are displacing discrete capital equipment purchases in North American health systems. This concentration is most pronounced in IDN-affiliated ambulatory surgical centers seeking standardized equipment platforms across multi-site networks.
Arthroscopy Visualization Systems Market Segmentation
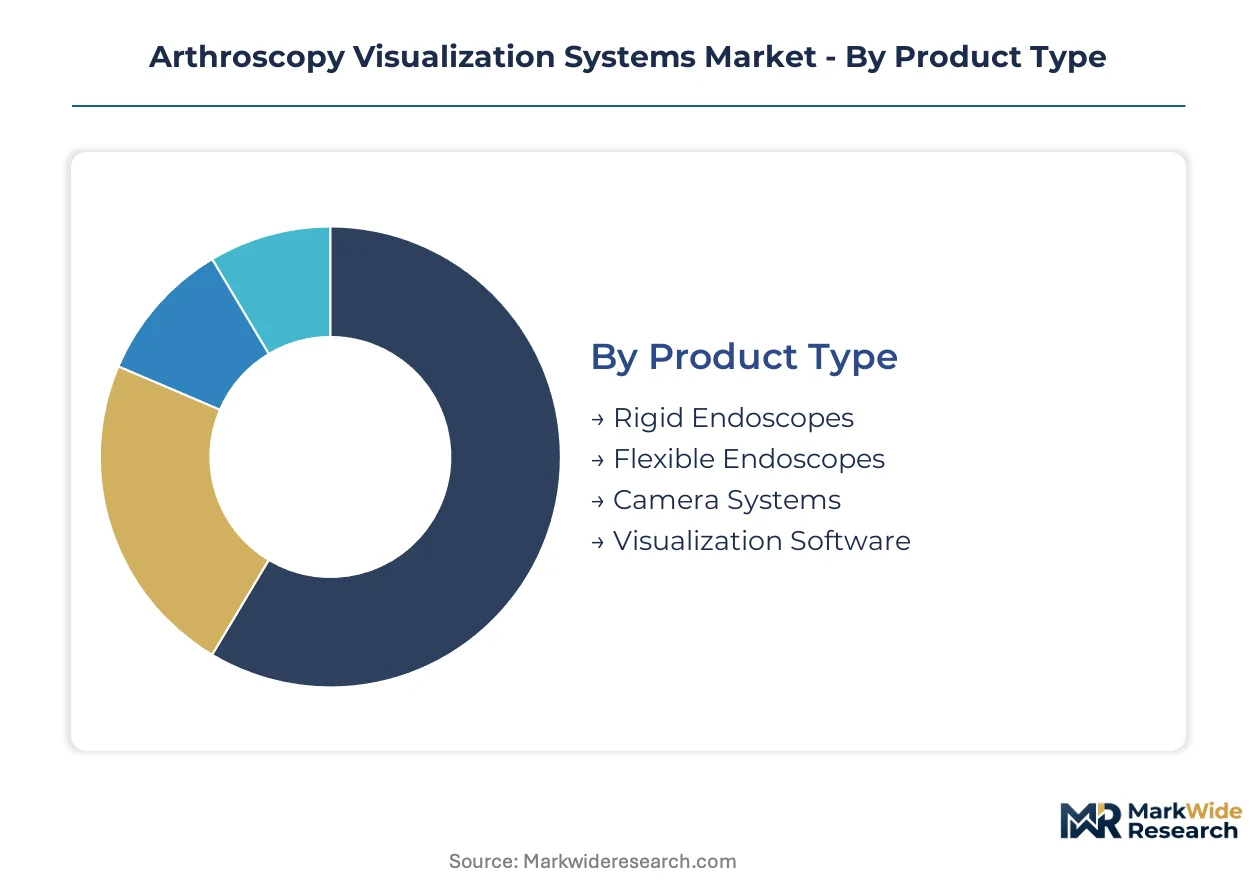
Segmentation in arthroscopy visualization systems reveals distinct procurement patterns across hardware, software, and service layers. Technology tiers and site-of-service economics drive divergent investment priorities among orthopedic providers.
Product Type:
Volume procurement concentrates in camera systems, while premium positioning attaches to integrated visualization software platforms.
- Camera Systems:These units combine CMOS sensors, proprietary connectors, and image processing chipsets into replaceable heads that lock into rigid endoscope couplers. Demand clusters in high-volume knee and shoulder arthroscopy centers across Germany and the United States, where replacement cycles compress to 24-36 months as 4K resolution becomes standard.
- Visualization Software:Platforms integrate real-time image enhancement, anatomical recognition algorithms, and surgical workflow documentation into vendor-locked ecosystems. Premium deployment is accelerating in academic medical centers and IDN-affiliated ambulatory surgical centers seeking AI-assisted operative planning capabilities.
- Rigid Endoscopes:Stainless steel shafts with rod-lens optical chains remain the workhorse for joint access in orthopedic surgery.
- Flexible Endoscopes:Fiberoptic or video-chip designs enable navigation through tortuous anatomical paths in hip and small-joint procedures.
Mature deployment sits with rigid endoscopes. Newer deployment is concentrated in visualization software platforms.
Technology:
Resolution tiers separate standard-care infrastructure from competitive differentiation investments.
- 4K Imaging:Ultra-high-definition sensors deliver 3840x2160 pixel resolution with enhanced chromatic fidelity for tissue plane discrimination. Sports medicine specialists in the United States and Germany are pulling upgrade cycles forward, prioritizing depth perception in complex rotator cuff and ligament reconstructions.
- 3D Visualization:Stereoscopic camera systems generate binocular disparity for spatial orientation during intricate reconstructive procedures. Adoption is climbing the fastest in tertiary orthopedic centers performing revision arthroplasty and multi-ligament knee reconstructions where anatomical complexity demands enhanced depth cues.
- HD Imaging:1080p resolution platforms retain installed-base dominance in cost-constrained ambulatory settings.
- Augmented Reality:Overlay systems project preoperative imaging onto live endoscopic views for instrument guidance.
Established infrastructure relies on HD imaging. Capital allocation is shifting toward 4K and 3D platforms.
End User:
Procurement authority is migrating from hospital capital committees toward ambulatory surgical center operators.
- Ambulatory Surgical Centers:Freestanding facilities perform same-day arthroscopic procedures under CMS site-of-service payment models. These centers in the United States are consolidating vendor relationships through bundled visualization ecosystem contracts that prioritize equipment standardization across multi-site networks.
- Hospitals:Inpatient facilities maintain arthroscopy suites for complex trauma and revision cases requiring overnight observation. Demand concentrates in orthopedic specialty hospitals within Germany's Ruhr industrial corridor and the United States' Midwest manufacturing regions.
- Clinics:Office-based settings deploy compact visualization systems for diagnostic arthroscopy and minor interventions.
- Research Institutions:Academic centers drive early adoption of experimental imaging modalities and AI integration.
Traditional procurement sits with hospitals. Volume expansion is concentrated in ambulatory surgical centers.
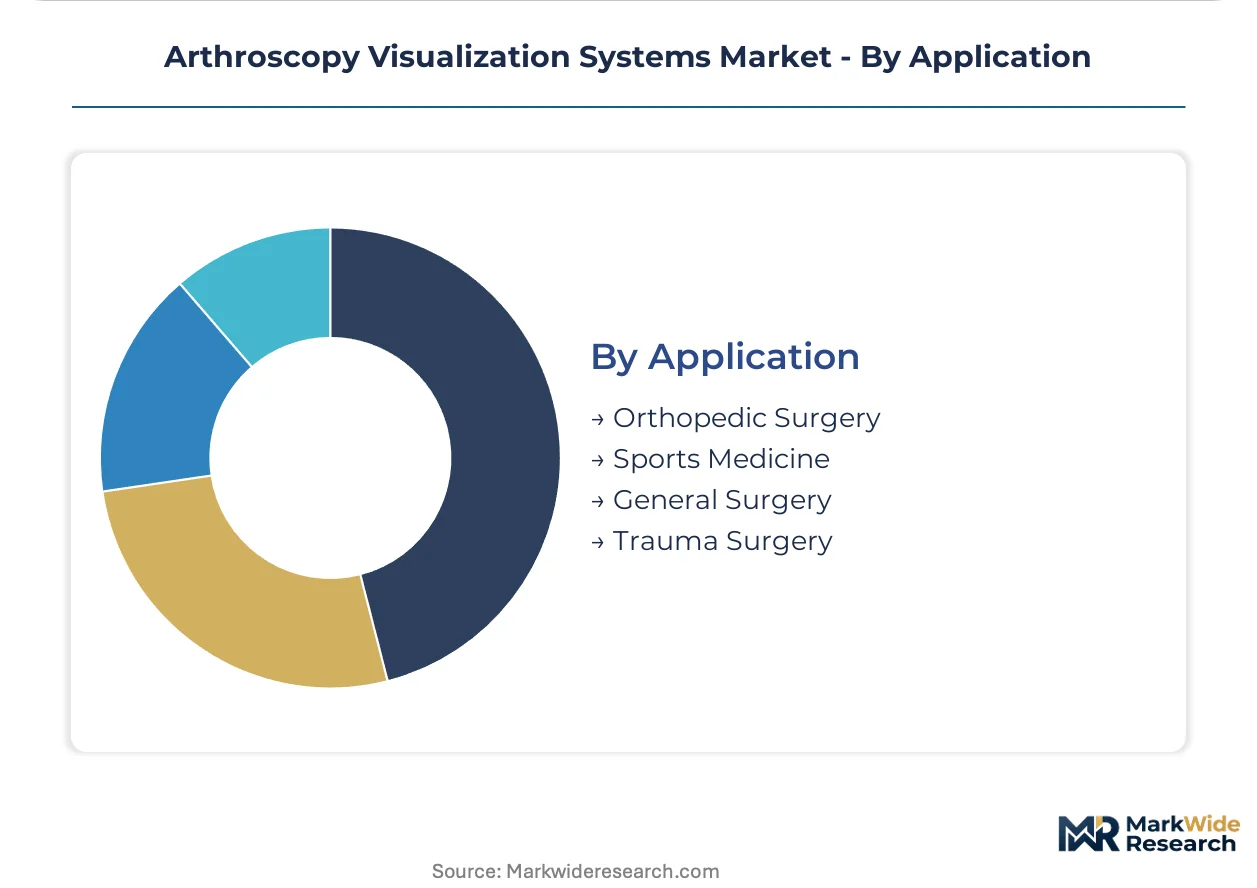
Application:
Procedure complexity determines capital intensity and technology specification requirements.
- Sports Medicine:ACL reconstruction, meniscal repair, and rotator cuff fixation demand high-resolution visualization for anatomical landmark identification. Ambulatory surgical centers in the United States are dedicating capital to dedicated sports medicine suites as athlete demographics and aging active populations expand procedure volumes.
- Orthopedic Surgery:Joint replacement preparation, synovectomy, and cartilage debridement span diagnostic and therapeutic indications. German orthopedic clinics anchor demand for precision-engineered visualization systems integrated with KARL STORZ and Richard Wolf instrument ecosystems.
- Trauma Surgery:Acute joint injury assessment and fracture-related arthroscopy require rapid deployment capabilities.
- General Surgery:Laparoscopic-adapted arthroscopy systems serve niche applications outside dedicated orthopedic settings.
Established utilization sits with orthopedic surgery. Steepest expansion trajectory is concentrated in sports medicine applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Germany's Ruhr industrial corridor concentrate precision endoscope manufacturing capacity. FDA 510(k) clearance pathways and EU MDR conformity assessments compress product development timelines across North American and European markets. India's orthopedic infrastructure buildout creates first-mover positioning for vendors establishing localized service networks.
United States
Ambulatory surgical centers displace hospital-only procurement models through bundled visualization ecosystem contracts. CMS site-of-service payment adjustments incentivize capital investment in dedicated arthroscopy suites. Stryker Corporation anchors integrated operating room ecosystems in the Midwest manufacturing regions.
Germany
KARL STORZ and Richard Wolf anchor manufacturing clusters for precision endoscope production. EU MDR technical documentation requirements mandate expanded clinical evidence packages for Class IIa and IIb devices. Tuttlingen in Baden-Württemberg hosts the densest concentration of arthroscopy visualization system component suppliers.
India
Government hospital modernization programs and private specialty clinic chains expand addressable market infrastructure. CDSCO medical device registration pathways determine market access timelines for imported visualization hardware. Maharashtra and Karnataka anchor demand concentration among corporate hospital chains.
Japan
PMDA regulatory reviews shape product approval timelines for 4K imaging modules and 3D visualization platforms. METI industrial policy supports domestic precision optics manufacturing for medical device applications. Tokyo-Osaka corridor concentrates orthopedic specialty clinics driving capital equipment procurement.
United Kingdom
NHS procurement frameworks consolidate vendor relationships through integrated operating room ecosystem contracts. MHRA post-Brexit regulatory autonomy diverges from EU MDR implementation timelines for visualization system registrations. London and Southeast England concentrate private ambulatory surgical center expansion.
Arthroscopy Visualization Systems Market Competitive Environment
Top-tier vendors anchor integrated operating room ecosystems, while mid-tier specialists compete on modular component pricing and regional service density. The market structure reflects concentrated procurement authority among IDN-affiliated health systems and multi-site ambulatory networks. Three strategic archetypes dominate: diversified orthopedic conglomerates bundling visualization with instruments, pure-play endoscope manufacturers defending proprietary connector ecosystems, and imaging technology specialists licensing sensor modules across OEM channels. Competitive moves concentrate on M&A for AI-assisted image processing capabilities and backward integration into CMOS sensor fabrication.
Among diversified orthopedic conglomerates, Stryker Corporation and Zimmer Biomet Holdings Inc. exemplify the integrated ecosystem archetype through bundled hardware-instrument-service offerings. Arthrex Inc. occupies a position within the sports medicine specialization tier, while KARL STORZ SE & Co. KG represents the precision endoscope manufacturing tradition anchored in German industrial clusters.
| Leading Market Players |
|---|
| Stryker Corporation |
| Arthrex Inc. |
| Smith & Nephew plc |
| Johnson & Johnson Services Inc. |
| KARL STORZ SE & Co. KG |
| CONMED Corporation |
| Olympus Corporation |
| Richard Wolf GmbH |
| Zimmer Biomet Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Ambulatory surgical center procurement consolidation across United States IDN networks is compressing vendor margins and forcing manufacturers to absorb logistics costs previously passed through to buyers. This demand-side concentration is reshaping contract structures toward utilization-based service models that bundle hardware, software, and maintenance into recurring revenue streams rather than discrete capital sales.
Pricing Analysis
Lead-time-sensitive pricing tiers separate emergency replacement orders from scheduled upgrade cycles, with premium multiples attaching to sub-30-day delivery commitments for 4K camera heads. The dominant structure stratifies across premium, standard, and economy tiers differentiated by resolution specification and after-sales service bundling. Cost compression in the economy tier is intensifying because reconditioned device programs from German and Japanese suppliers are displacing new system purchases among mid-tier buyers. Price sensitivity concentrates in independent ambulatory surgical centers, while IDN-affiliated networks prioritize standardization over unit cost minimization.
Supply Chain Analysis
ISO 13485 and IEC 60601-1 certification requirements gate supplier qualification, limiting component sourcing to pre-audited precision optics manufacturers in Germany, Japan, and the United States. CMOS sensor fabrication, rod-lens optical chains, and proprietary connector systems anchor the bill of materials, drawing from captive production facilities in Tuttlingen and Tokyo-Osaka corridor. Single-source vulnerability concentrates in German precision lens grinding capacity, where regional production disruptions would cascade through multiple vendor ecosystems. Distribution runs through authorized service networks that co-locate technical support with major orthopedic clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The arthroscopy visualization systems market sits in a technology-transition phase as 4K imaging modules displace HD platforms across high-volume surgical centers. This displacement is compressing replacement cycles and forcing ecosystem-level competitive responses.
For Market Incumbents: Deploy backward integration into CMOS sensor fabrication to secure supply continuity against German and Japanese optical component concentration. Lock in IDN-affiliated ambulatory surgical centers through integrated operating room ecosystem contracts that bundle visualization hardware with instrument portfolios, defending against modular competitors. Invest in FDA 510(k) clearance capacity to accelerate predicate-device submissions as regulatory timelines compress. For New Entrants and Emerging Players: Capture India's orthopedic infrastructure buildout by establishing localized service networks ahead of CDSCO registration pathways for imported hardware. Target corporate hospital chains in Maharashtra and Karnataka with modular visualization software platforms that integrate with existing camera systems, avoiding proprietary connector lock-in. Pursue AI-assisted image processing licensing agreements with academic medical centers to bypass capital-intensive hardware manufacturing. For Investors and Strategic Acquirers: Re-rating potential sits with pure-play visualization software specialists given convergence of real-time anatomical recognition algorithms with 4K camera streams. Long-term viability over the next decade hinges on regulatory data infrastructure rather than hardware manufacturing scale. Acquisition targets should demonstrate EU MDR technical documentation readiness and post-market surveillance capabilities. The signal to watch is CMS site-of-service payment parity adjustments that accelerate ambulatory surgical center capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Expedited predicate-device submissions accelerate commercialization timelines for next-generation camera heads in the United States. |
| EU MDR Conformity Assessment | Expanded clinical evidence packages for Class IIa and IIb devices determine market access trajectories across European member states. |
| Hospital System Partnership | Integrated operating room ecosystem contracts bundle visualization hardware with surgical instruments across IDN-affiliated networks. |
| Software Companion Development | AI-assisted image processing platforms open premium pricing tiers through real-time anatomical recognition algorithm integration. |
| Reimbursement Strategy | CMS site-of-service payment adjustments incentivize ambulatory surgical center capital investment in dedicated arthroscopy suites. |
Study Parameters
Document review covered FDA 510(k) clearance databases, EU MDR notified body audit records, and hospital procurement contract filings, complemented by interviews with biomedical engineers, orthopedic surgeons, ambulatory surgical center administrators, GPO contracts managers, and regulatory affairs specialists. Secondary validation drew from CMS Medicare reimbursement data, ISO 13485 certification registries, and orthopedic device trade association reports. Bottom-up and top-down triangulation reconciled procedure volume estimates with capital equipment replacement cycle assumptions.
Segment-level outputs across the projection horizon reflect modeled interactions between technology tier adoption curves, site-of-service migration patterns, and regulatory compliance cost structures. Segmentation dimensions included product type, resolution technology, end-user facility category, and application specialty. CAGRs were derived from logistic diffusion curves fitted to 4K imaging module penetration data and ambulatory surgical center infrastructure buildout rates. Industry-specific inputs incorporated EU MDR technical documentation burden estimates and CDSCO registration pathway timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body capacity constraints and optical component supply disruptions. Forecasts reflect assumptions regarding reimbursement parity stability and orthopedic procedure volume trajectories. A model refresh is warranted upon material change in CMS site-of-service payment policy or FDA 510(k) review timeline adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Veno-Venous Extracorporeal Life Support (VV ECLS) Devices Market
Medical Devices
Implantable Port Market
Medical Devices
Next Generation Optical Biometry Devices Market
Medical Devices
Japan Aesthetic Devices Market
Medical Devices
Muscle Stimulation Devices Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Esophagoscopes and Gastroscopes Market
Medical Devices
Europe Insulin Pumps Market
Medical Devices
Drug Delivery Solutions Market
Medical Devices
Microcirculation Microscope Market
Medical Devices
Prefilled Syringe Small Molecule Market
Medical Devices
Spherical IOL Market
Medical Devices
3D Printed Medical Devices Market
Medical Devices
Global Digital Pathology Systems Market
Medical Devices
Italy Artificial Organs and Bionic Implants Market
Medical Devices
Europe Mobility Aids Market