
 Global Endoscopic Stricture Management Device Market | 2026-2036
Global Endoscopic Stricture Management Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endoscopic Stricture Management Device Market Foresight
Consolidation among ambulatory surgical centers and specialty hospital networks is recalibrating procurement patterns for stricture management systems. Boston Scientific Corporation leverages its integrated stent and dilation portfolio to anchor large GPO contracts across North American outpatient settings. Olympus Corporation sustains competitive positioning through proprietary endoscope-dilator compatibility that locks in system-level hospital commitments. Cook Medical Inc. specializes in wire-guided platforms that dominate interventional gastroenterology training programs and academic medical centers.
Endoscopic stricture management devices encompass balloon dilators, self-expanding metallic and plastic stents, and mechanical bougie systems designed to restore luminal patency in obstructed gastrointestinal, biliary, and urinary tracts, typically manufactured from nitinol alloys, silicone, or polyurethane with radial expansion forces calibrated to specific anatomical pressures. These instruments serve the primary purpose of enabling minimally invasive dilation or stenting procedures that replace open surgical revision in benign and malignant stricture cases. Self-expanding stents command the dominant revenue share due to longer indwell times and premium pricing in malignant biliary and esophageal applications, while balloon dilators represent the highest procedural volume segment driven by recurrent benign stricture retreatment cycles. Single-use deployment modes are displacing reusable instruments in ambulatory settings as infection control protocols harden and reprocessing cost economics deteriorate.
FDA premarket notification requirements under 510(k) pathways govern stent biocompatibility and migration resistance testing, while the EU MDR demands enhanced clinical evidence and post-market surveillance for implantable stricture devices with extended body contact duration. Japan's PMDA enforces stringent QMS inspections on foreign manufacturers seeking market access, creating compliance barriers that favor established multinationals with in-country regulatory infrastructure. Stakeholders must monitor evolving reimbursement thresholds for outpatient stricture procedures as payors in the United States, Germany, and Japan recalibrate endoscopic intervention coverage against surgical alternatives.
Market Dynamics
EU MDR clinical evidence requirements are compressing approval timelines for implantable esophageal and biliary stents, forcing manufacturers to front-load post-market surveillance infrastructure before commercial launch.
Growth Catalysts
- Aging Demographics:Japan's super-aged population and Germany's elderly cohort are expanding the addressable patient pool for malignant stricture interventions requiring repeat stenting procedures.
- MDR Compliance Infrastructure:The EU Medical Device Regulation's extended body contact duration classifications are accelerating clinical data generation capabilities among established manufacturers with in-country regulatory teams.
- Minimally Invasive Migration:Ambulatory surgical centers in the United States are consolidating procurement volumes around single-use dilation platforms that eliminate reprocessing liability.
Market Restraints
- Nitinol Alloy Concentration:Supply of shape-memory alloys for self-expanding stents concentrates among a limited set of specialty metallurgical suppliers, creating input cost volatility and qualification bottlenecks.
- PMDA Market Access Barriers:Japan's Pharmaceuticals and Medical Devices Agency enforces stringent QMS inspections on foreign manufacturers, favoring multinationals with established Tokyo regulatory infrastructure.
- Surgical Revision Substitution:Open surgical stricture repair remains the fallback for failed endoscopic interventions in complex benign cases, limiting addressable procedural expansion.
Strategic Opportunities
- India Outpatient Infrastructure:Private gastroenterology clinic chains in Mumbai and Delhi are installing endoscopy suites faster than domestic stent manufacturing capacity can localize.
- Bioresorbable Stent Convergence:Magnesium alloy metallurgy and controlled degradation polymer chemistry are converging to enable temporary stricture management without secondary removal procedures.
- IRAs Hospital-at-Home Incentives:United States Inflation Reduction Act provisions for outpatient procedure reimbursement are creating channel expansion for home-based stricture monitoring adjuncts.
Industry Challenges
- Interventional Gastroenterology Training Pipeline:Academic medical centers face fellowship placement constraints for advanced endoscopy sub-specialization, limiting operator availability for complex stricture cases.
- EU MDR Technical Documentation Burden:The conformity assessment timeline for legacy stent product lines is stretching internal regulatory affairs capacity at mid-tier manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endoscopic Stricture Management Device Market |
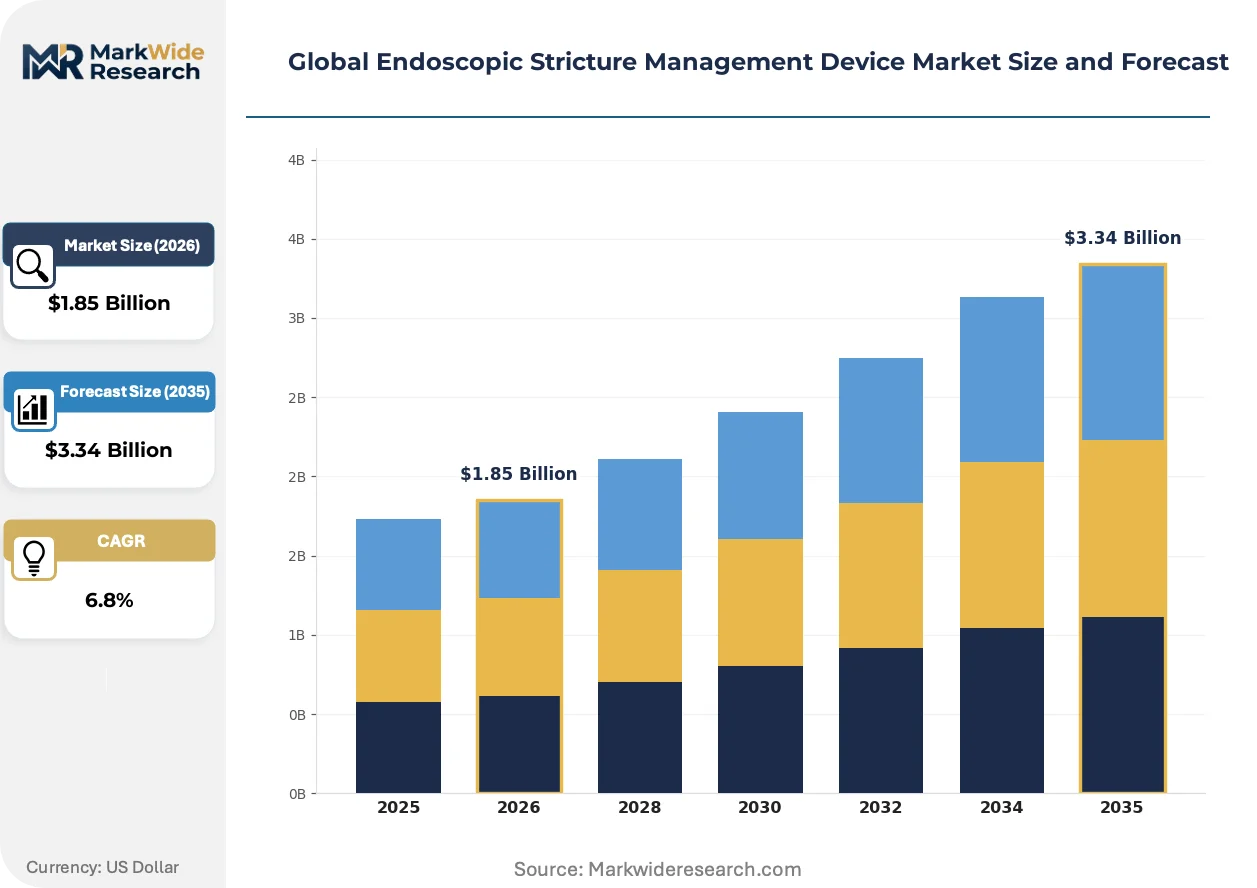
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.34 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Balloon Dilators, Self-Expanding Stents, Wire-guided Dilators, Bougie Dilators, Needle-knife Devices Clinical Indication: Esophageal Strictures, Colorectal Strictures, Biliary Strictures, Urethral Strictures, Gastric Outlet Obstruction End User: Gastroenterology Clinics, Ambulatory Surgical Centers, Specialty Hospitals, Academic Medical Centers, Diagnostic Centers Deployment Mode: Single-use Devices, Reusable Instruments, Semi-disposable Kits, Portable Systems, Operating Room Integration |
| Companies Covered | Boston Scientific Corporation, Olympus Corporation, CONMED Corporation, Cook Medical Inc., Merit Medical Systems, Becton, Dickinson and Company, Medi-Globe GmbH, HOBBS MEDICAL, INC., Micro-Tech (Nanjing) Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endoscopic Stricture Management Device Market Shifts & Advancements
Digital integration and material science advances are redefining stricture management workflows, shifting competitive advantage toward system-level solution providers rather than component vendors.
Bioresorbable esophageal stents fabricated from magnesium alloys and polylactic acid composites are expanding into malignant stricture applications where temporary patency restoration eliminates retrieval morbidity. Tertiary oncology centers in Germany and Japan are piloting these platforms for neoadjuvant therapy bridges. The technology is expanding into reimbursement negotiations as payors weigh device cost against avoided secondary procedures.
REACH substance restrictions and EU MDR post-market surveillance mandates are tightening biocompatibility documentation for silicone and polyurethane stent coatings with extended indwell durations. Manufacturers must now generate clinical evidence on degradation byproduct accumulation across 12-month implantation windows. Biliary stent portfolios face the steepest compliance recalibration given their exposure to enzymatic degradation environments.
Group purchasing organizations in the United States are consolidating ambulatory surgery center networks around sole-source contracts for integrated dilation-stenting systems. Independent gastroenterology practices are losing negotiating leverage as procurement authority concentrates within multi-site specialty platforms. California and Texas outpatient markets exhibit the most advanced buyer consolidation, with three GPOs controlling majority stricture device volumes.
Global Endoscopic Stricture Management Device Market Segmentation
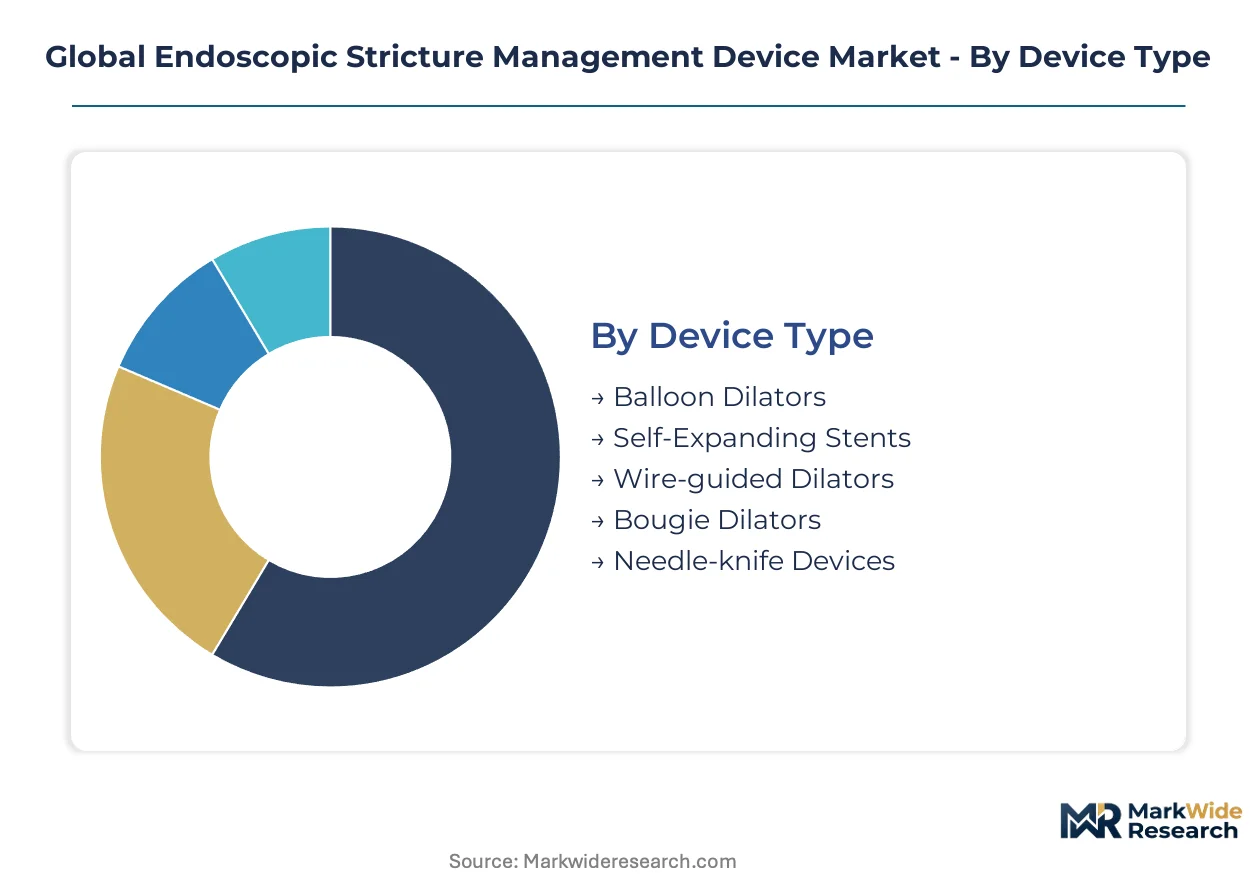
Stricture management devices fragment across intervention type, anatomical target, and care setting. Each segmentation axis reveals distinct procurement patterns, reimbursement thresholds, and technology adoption curves that shape manufacturer positioning.
Device Type:
Volume concentrates in high-turnover dilation platforms, while premium revenue aggregates in implantable stent systems with extended indwell economics.
- Self-Expanding Stents:Nitinol alloy frameworks deliver calibrated radial force for malignant esophageal and biliary strictures. Demand clusters in United States oncology centers and German tertiary hospitals where premium pricing aligns with longer implantation windows and reduced reintervention frequency.
- Balloon Dilators:Elastomeric balloons with radiopaque markers enable graded dilation across benign stricture retreatment cycles. United States ambulatory surgical centers drive procedural volume through single-use procurement models that eliminate reprocessing overhead and infection control liability.
- Wire-guided Dilators:Track over guidewires through tortuous anatomy for precision stricture navigation. Academic medical centers favor these platforms for complex interventional training protocols.
- Bougie Dilators:Rigid tapered instruments provide mechanical dilation for straightforward esophageal strictures. Cost-sensitive outpatient settings in India retain reusable bougie systems despite single-use migration trends.
- Needle-knife Devices:Electrocautery-enabled stricturotomy for refractory fibrotic strictures. Japan's PMDA-cleared platforms dominate advanced endoscopy suites.
Mature deployment sits with bougie dilators in resource-constrained settings. Newer deployment is concentrated in self-expanding stents with drug-eluting coatings.
Clinical Indication:
Anatomical site determines stent material selection, indwell duration tolerance, and secondary procedure risk calculus.
- Biliary Strictures:Polyurethane and silicone stents navigate enzymatic degradation environments with shorter indwell tolerances. German hepatobiliary centers and United States transplant programs generate repeat intervention demand for malignant hilar obstruction.
- Esophageal Strictures:Covered metal stents prevent tumor ingrowth while permitting removal in benign cases. Japan's aging population expands malignant stricture volumes requiring palliative stenting.
- Colorectal Strictures:Large-diameter stents address obstructing neoplasms and post-surgical anastomotic narrowing. United States colorectal surgery networks drive adoption.
- Gastric Outlet Obstruction:Pyloric and duodenal stenting for unresectable malignancy. Tertiary oncology centers in Germany pilot lumen-apposing metal stents.
- Urethral Strictures:Urological crossover applications for bulbar stricture dilation. Specialized urology clinics in Japan maintain distinct procurement channels.
Biliary applications command the steepest expansion trajectory as cholangiocarcinoma incidence rises and interventional hepatology sub-specializes.
End User:
Procurement authority concentrates in multi-site specialty platforms, fragmenting across independent practice settings.
- Ambulatory Surgical Centers:United States outpatient networks consolidate stricture device volumes under sole-source GPO contracts favoring integrated dilation-stenting systems with predictable per-procedure economics.
- Academic Medical Centers:Training program infrastructure and fellowship pipelines anchor wire-guided platform adoption. Complex case referrals sustain premium device tolerance.
- Gastroenterology Clinics:Independent practices in Mumbai and Delhi install endoscopy suites faster than domestic supply localization, creating import-dependent procurement.
- Specialty Hospitals:Oncology-focused institutions in Germany and Japan concentrate malignant stricture case volumes requiring specialized interventional gastroenterology staffing.
- Diagnostic Centers:Screening-dominant facilities with limited therapeutic capability represent minimal stricture device demand.
Procurement leverage aggregates with ambulatory surgical centers. Capability investment concentrates in academic medical centers.
Deployment Mode:
Infection control protocols and reprocessing cost economics drive modality substitution across care settings.
- Single-use Devices:Eliminate sterilization infrastructure and liability exposure. United States ASC networks and German outpatient clinics complete transition from reusable platforms.
- Reusable Instruments:Stainless steel bougie and balloon systems persist in India's private clinic chains where capital constraints outweigh infection control mandates.
- Semi-disposable Kits:Hybrid models with reusable handles and single-use consumables balance cost and compliance. Japan's PMDA-inspected manufacturers favor this architecture.
- Portable Systems:Battery-powered dilation platforms for field deployment and rural outreach. Limited penetration outside humanitarian and military applications.
- Operating Room Integration:Fixed installations with imaging compatibility for hybrid surgical-endoscopic procedures. German and United States tertiary centers deploy for complex benign stricture revision.
Regulatory pressure accelerates single-use migration. Cost containment preserves reusable instrument presence in price-sensitive markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for endoscopic stricture management devices concentrates in healthcare systems with aging demographics and established interventional gastroenterology infrastructure. The United States, Germany, and Japan absorb the majority of premium stent and dilation system volumes. Procurement authority is consolidating within multi-site ambulatory networks across these markets.
United States
Malignant esophageal and biliary stricture cases are expanding as the population ages past 65. FDA 510(k) premarket notification pathways govern stent biocompatibility and migration resistance testing for commercial entry. Group purchasing organizations in California and Texas have consolidated ambulatory surgery center networks around sole-source contracts for integrated dilation-stenting systems.
Germany
Tertiary hepatobiliary centers generate repeat intervention demand for malignant hilar obstruction requiring specialized interventional staffing. EU MDR conformity assessment timelines are compressing for implantable esophageal and biliary stents with extended body contact classifications. Bavarian oncology-focused institutions are piloting lumen-apposing metal stents for gastric outlet obstruction applications.
Japan
Super-aged demographic expansion is driving palliative stenting volumes for malignant esophageal strictures. PMDA enforces stringent QMS inspections on foreign manufacturers, creating compliance barriers that favor established multinationals with Tokyo regulatory infrastructure. Kanto region academic medical centers anchor wire-guided platform adoption for complex interventional training protocols.
India
Private gastroenterology clinic chains in Mumbai and Delhi are installing endoscopy suites faster than domestic stent manufacturing capacity can localize. CDSCO medical device regulations are tightening import dependency for stricture management systems. Maharashtra and Gujarat outpatient markets retain reusable bougie dilators where capital constraints outweigh infection control mandates.
United Kingdom
Post-surgical anastomotic stricture cases are rising within colorectal surgery networks. MHRA alignment with EU MDR post-market surveillance mandates is tightening biocompatibility documentation for silicone and polyurethane stent coatings. London and Southeast England tertiary centers concentrate complex benign stricture revision volumes requiring hybrid surgical-endoscopic procedures.
Global Endoscopic Stricture Management Device Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue bioresorbable material convergence and single-use platform economics. The vendor base stratifies across integrated system providers, specialized wire-guided platform manufacturers, and regional dilation instrument fabricators. Three archetypes dominate: multinational medical device conglomerates with endoscope-stent compatibility ecosystems; mid-tier interventional specialists with academic medical center training program anchoring; and cost-optimized regional suppliers serving price-sensitive outpatient markets. Competitive moves concentrate on GPO contract consolidation for ambulatory surgery center networks and backward integration into nitinol alloy supply qualification.
Within the multinational integrated systems tier, Boston Scientific Corporation and Olympus Corporation exemplify endoscope-dilator ecosystem control that locks in hospital procurement commitments. Cook Medical Inc. occupies a position within the interventional specialist archetype, anchoring wire-guided platform presence across academic training pipelines. CONMED Corporation represents the diversified medical technology tier with cross-specialty stricture management applicability. These three entities collectively illustrate how competitive positioning in this market depends on either system-level compatibility lock-in, training program embedding, or portfolio breadth across anatomical intervention sites.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Olympus Corporation |
| CONMED Corporation |
| Cook Medical Inc. |
| Merit Medical Systems |
| Becton, Dickinson and Company |
| Medi-Globe GmbH |
| HOBBS MEDICAL, INC. |
| Micro-Tech (Nanjing) Co., Ltd |
| Others |
Supply & Pricing Matrix
REACH substance restrictions on silicone and polyurethane coatings gate qualified supply access and premium-tier pricing power for implantable stent manufacturers serving European oncology centers. Nitinol alloy qualification bottlenecks concentrate input sourcing among specialty metallurgical suppliers, compressing margin structures for mid-tier device fabricators while anchoring premium pricing for established players with captive supply relationships.
Pricing Analysis
Volume concentrates in single-use balloon dilators with thin margins, while premium revenue aggregates in self-expanding metallic stents with extended indwell economics. Three-tier pricing structure across premium, standard, and economy levels separates FDA-cleared drug-eluting platforms from CE-marked bare-metal systems and uncoated reusable bougie instruments. Price differentiation hinges on biocompatibility certification tier and radial force calibration precision. Cost compression in the standard tier is intensifying as Indian clinic chains negotiate volume discounts against reprocessing cost advantages. Ambulatory surgical centers in the United States exhibit the least price sensitivity due to GPO-negotiated sole-source contracts, while independent gastroenterology practices in Maharashtra retain reusable instruments where capital constraints dominate procurement calculus.
Supply Chain Analysis
Reverse-logistics flows for explanted biliary and esophageal stents are minimal given implantation duration, though Japan's PMDA-inspected manufacturers operate refurbishment programs for semi-disposable dilation system handles. Nitinol alloy feedstock concentrates in the United States, Germany, and Japan among shape-memory specialty suppliers with medical-grade qualification protocols. Raw material dependencies rest on nickel-titanium master alloys, medical-grade silicone elastomers, and radiopaque marker compounds. Single-source vulnerability in nitinol melt capacity creates qualification bottlenecks for new market entrants. Distribution runs through hospital system procurement committees and GPO contract administrators in consolidated North American outpatient networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nitinol alloy melt capacity constraints prop pricing power for qualified suppliers, positioning this market as supply-constrained with incumbent manufacturers capturing margin expansion from input bottlenecks.
For Market Incumbents: Extend backward integration into nitinol alloy supply qualification to defend against emerging bioresorbable magnesium alloy substitutes threatening metallic stent franchises. Anchor GPO contract renewals through integrated endoscope-dilator compatibility ecosystems that raise switching costs for ambulatory surgical center networks. Prioritize EU MDR technical documentation completion for legacy esophageal stent portfolios before conformity assessment timelines compress further. For New Entrants and Emerging Players: Capture white-space in India's outpatient clinic chains where domestic stent manufacturing localization lags behind endoscopy suite installation rates in Mumbai and Delhi. Target bioresorbable stent pilot programs at German tertiary oncology centers as reimbursement negotiations open for temporary patency platforms. Pursue academic medical center training program partnerships as the primary go-to-market angle for wire-guided platform adoption. For Investors and Strategic Acquirers: PMDA QMS inspection clearance for foreign manufacturers is the leading indicator that regulatory infrastructure investments are yielding market access returns. Mid-tier interventional specialists with anchored academic training pipelines represent the most viable acquisition archetype over a multi-year horizon. Monitor EU MDR post-market surveillance mandate enforcement as the signal for compliance cost escalation favoring scaled manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nitinol Supply | Captive alloy qualification reduces input cost volatility for self-expanding stent manufacturers. |
| Bioresorbable Stent FDA Submission | 510(k) clearance for magnesium alloy platforms opens malignant stricture applications without retrieval morbidity. |
| GPO Sole-Source Contract Consolidation | Integrated dilation-stenting system bundling locks in ambulatory surgery center procurement volumes. |
| EU MDR Technical Documentation Completion | Legacy product line conformity assessment preserves European market access for implantable devices. |
| Academic Medical Center Training Partnership | Fellowship program embedding anchors wire-guided platform adoption across interventional gastroenterology pipelines. |
Research Methodology
Multi-period observation of stent indwell duration trends, reintervention frequency patterns, and ambulatory procedural volume shifts anchored the trend analysis, supplemented by interviews with interventional gastroenterologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers. Secondary validation drew from FDA 510(k) premarket notification databases, EU MDR conformity assessment filings, hospital procurement contract records, and CMS Medicare reimbursement schedules. Bottom-up device shipment modeling triangulated against top-down healthcare expenditure allocation estimates.
Segment-weighting across device type, anatomical indication, and care setting dimensions structured the analytical framework over the projection horizon. Self-expanding stent revenue pools, balloon dilator procedural volumes, and deployment mode substitution rates informed segment-level growth assumptions. CAGRs were derived from installed base expansion, replacement cycle compression, and premium product mix shift trajectories. Reimbursement threshold recalibration and regulatory compliance cost escalation served as industry-specific forecast sensitivity inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to bioresorbable stent reimbursement adoption curves and nitinol alloy supply qualification bottlenecks. Forecasts reflect documented assumptions regarding procedural volume migration to ambulatory settings and EU MDR enforcement intensity. Practitioners should monitor PMDA foreign manufacturer inspection clearance rates and German tertiary center pilot program outcomes for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Endoscopy
Veterinary Endoscopy Devices Market
Endoscopy
Germany Endoscopy Devices Market
Endoscopy
Endoscope Detergents and Disinfectants Market
Endoscopy
Endoscopic Retrograde Cholangiopancreatography/ERCP Market
Endoscopy
Endoscopic Balloon Dilator Market
Endoscopy
Endotherapy Devices Market
Endoscopy
Canada Endoscopy Devices Market
Endoscopy
Sweden Endoscopy Devices Market
Endoscopy
Nasopharyngoscope Market
Endoscopy
Australia Endoscopy Devices Market
Endoscopy
High-Resolution Anoscopy Market
Endoscopy
Video Laryngoscope Market
Endoscopy
Global Veterinary Endoscopes Market
Endoscopy
France Endoscopy Devices Market
Endoscopy
Industrial Endoscope Market
Endoscopy
Global Veterinary Endoscopy Market