
 Ultra High Definition (UHD) Surgical Display Market | 2026-2036
Ultra High Definition (UHD) Surgical Display Market Size, Share, and Industry Trends Forecast 2026-2036
Ultra High Definition (UHD) Surgical Display Market Analytics
Aftermarket service revenue is reconfiguring profit pools across the UHD surgical display value chain. Sony Corporation leverages its broadcast-grade image-processing heritage to dominate premium calibration services. Barco anchors its position through proprietary color-management protocols that lock hospitals into long-term maintenance contracts. EIZO Corporation specializes in grayscale calibration standards for radiology-surgery crossover environments.
Ultra High Definition (UHD) Surgical Displays are medical-grade visualization systems engineered to deliver resolutions of 3840 x 2160 pixels or higher, with luminance outputs exceeding 500 cd/m² and DICOM Part 14 grayscale compliance for tissue differentiation during operative procedures. Their primary purpose is to render anatomical structures with sufficient fidelity that surgical teams can perform minimally invasive procedures without optical degradation. Flat panel displays currently occupy the largest installed base, while OLED displays represent the fastest-expanding margin pool due to their infinite contrast ratios and reduced heat emission in sterile fields. Wall-mounted installations dominate hospital infrastructure, though portable configurations are gaining traction in ambulatory surgical centers seeking flexible room utilization.
FDA 510(k) clearance requirements and the EU Medical Device Regulation (MDR) are elevating barriers for non-compliant manufacturers while mandating traceable color-calibration documentation across product lifecycles. Japan's PMDA has tightened electromagnetic compatibility standards for surgical displays used in electrophysiology labs, redirecting procurement toward certified suppliers. Stakeholders must monitor evolving interoperability mandates between display systems and surgical navigation platforms as hybrid operating rooms integrate multiple imaging modalities.
Market Dynamics
Hybrid operating room installations are compressing procurement cycles for UHD surgical displays as hospitals consolidate multiple imaging modalities onto single visualization platforms. This infrastructure convergence is forcing display manufacturers to prioritize interoperability certifications over standalone hardware specifications.
Growth Catalysts
- EU Medical Device Regulation:MDR compliance mandates for traceable color-calibration documentation are locking hospitals into certified supplier relationships. This regulatory pressure eliminates gray-market competitors.
- OLED thermal profiles:Reduced heat emission in sterile fields is accelerating replacement of legacy flat panel installations in electrophysiology suites. Tertiary hospitals prioritize patient safety margins.
- Japan PMDA electromagnetic standards:Tightened compatibility requirements for surgical displays used in catheterization labs are redirecting procurement toward certified Japanese and German suppliers.
Market Restraints
- Panel supply concentration:Premium OLED substrates depend on concentrated Korean and Taiwanese foundry capacity. Geopolitical friction threatens input security for display assemblers.
- FDA 510(k) pathway costs:Pre-market notification expenses and clinical validation timelines create capital barriers for mid-tier manufacturers seeking US market entry.
- Grayscale calibration labor:DICOM Part 14 compliance requires specialized biomedical engineering expertise that concentrates in Germany and Japan, limiting service scalability.
Strategic Opportunities
- India tertiary hospital buildout:CDSCO medical device registration pathways are streamlining for Class B visualization equipment. Unmet demand exists across 40+ AIIMS-affiliated institutions.
- Ambulatory surgical center portability:Mobile UHD cart configurations address flexible room utilization requirements that wall-mounted systems cannot satisfy.
- ISO 13485 convergence:Unified quality management certification is reducing duplicate audit burdens for manufacturers serving multiple regulatory jurisdictions simultaneously.
Industry Challenges
- Biomedical visualization engineering talent:Cross-disciplinary expertise spanning radiology standards and surgical workflow design concentrates in legacy German and Japanese industrial clusters.
- Legacy PACS integration:Hospital information system heterogeneity forces costly middleware development for each major electronic health record platform.
- Color-calibration drift management:Continuous DICOM compliance requires automated sensor networks that most installed base systems lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultra High Definition (UHD) Surgical Display Market |
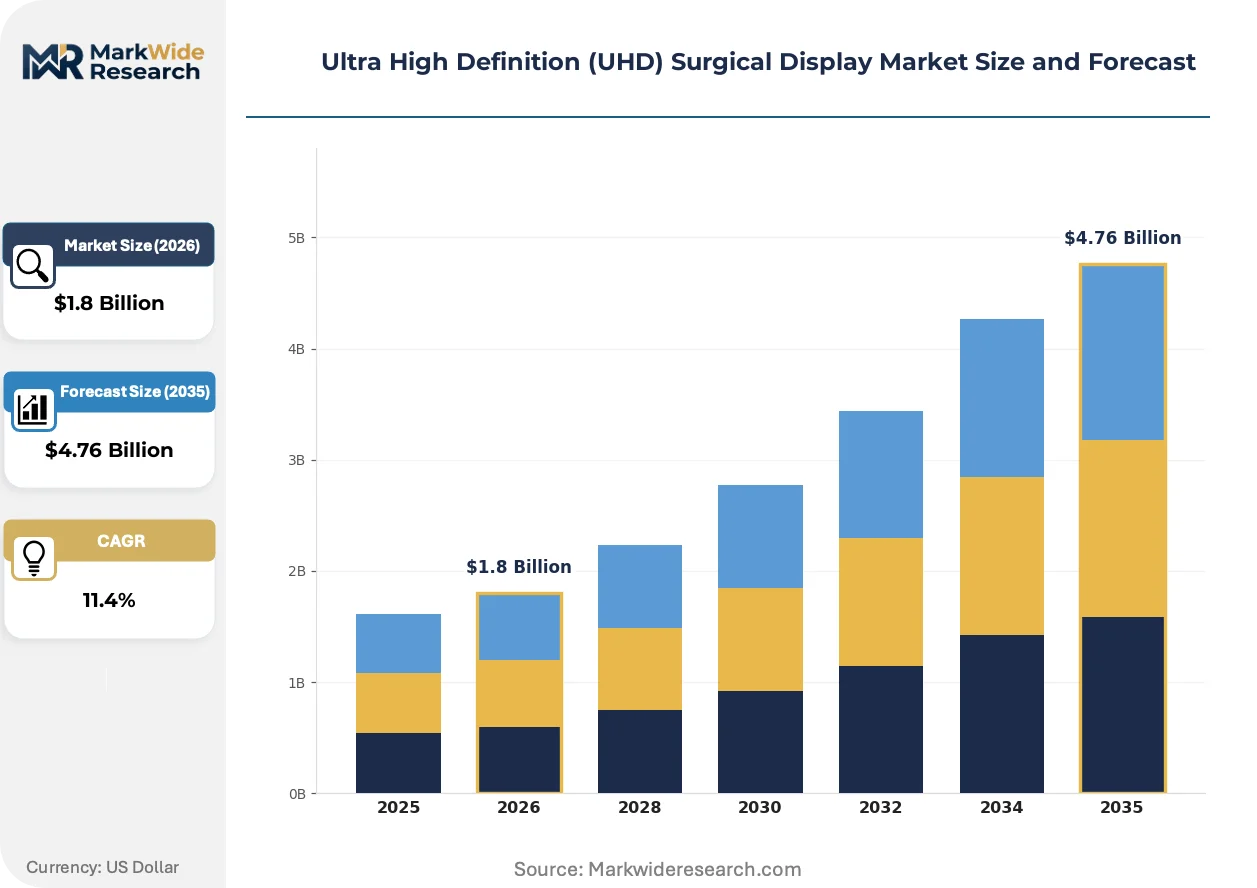
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Panel Display, LED Display, OLED Display, LCD Display End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Laboratories Installation Type: Wall-mounted, Ceiling-mounted, Portable, Integrated Systems Features: High Brightness, Touchscreen, 3D Visualization, Multi-display Capability |
| Companies Covered | Sony Corporation, STERIS, Barco, FSN Medical Technologies, Olympus Corporation, Siemens Healthineers, EIZO Corporation, Advantech, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultra High Definition (UHD) Surgical Display Market Evolving Landscape
Visualization fidelity requirements are diverging between radiology-diagnostic and surgical-interventional use cases, forcing manufacturers to architect modular calibration engines rather than universal display platforms.
OLED micro-display technology is collapsing the luminance gap between emissive panels and backlit LCD alternatives in surgical environments. Academic medical centers in Germany and Japan are piloting 31-inch OLED surgical monitors for neuro-interventional suites. This transition is collapsing the installed base advantage that legacy flat panel technologies held in hybrid operating rooms.
Japan's PMDA revised electromagnetic compatibility standards for devices deployed in electrophysiology laboratories during 2023. The regulation now mandates shielding validation against radiofrequency ablation equipment interference. Surgical display manufacturers serving Japanese tertiary hospitals must recertify existing product lines, compressing time-to-market for competitive refreshes.
Hospital procurement committees are unbundling hardware acquisition from multi-year calibration service contracts. German university hospitals pioneered this separation, forcing manufacturers to price visualization systems and maintenance subscriptions independently. This unbundling is most visible in North Rhine-Westphalia's clustered hospital networks, where shared service organizations negotiate centralized calibration agreements across multiple surgical sites.
Ultra High Definition (UHD) Surgical Display Market Segmentation
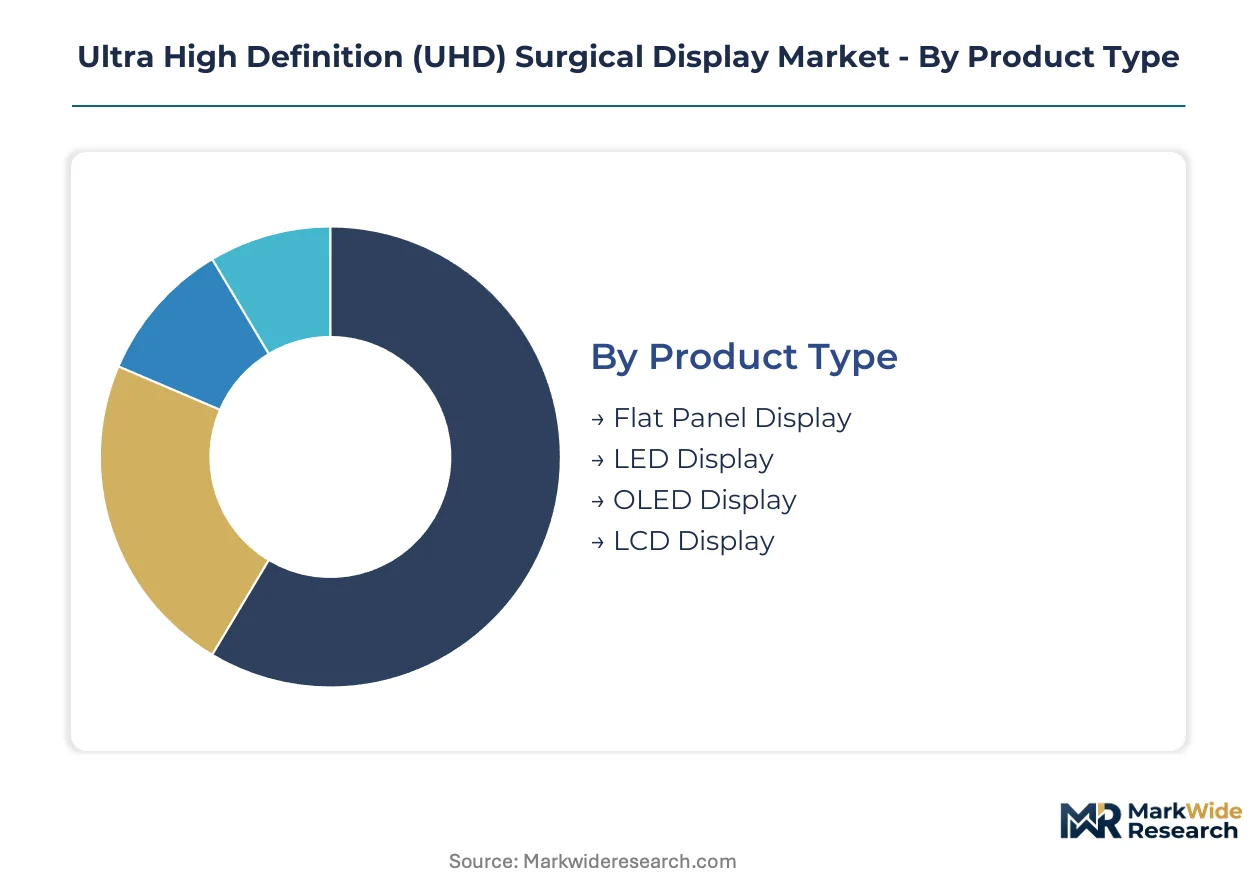
Segmentation in the UHD surgical display market reveals how procurement priorities diverge between capital-intensive hospital infrastructure and flexible outpatient environments. Product specifications, installation constraints, and end-user workflows each create distinct margin pools that manufacturers must navigate simultaneously.
Product Type:
Technology architecture determines thermal performance, contrast fidelity, and service lifecycle economics across surgical visualization platforms.
- Flat Panel Display:Backlit LCD architectures with LED edge-lighting dominate current installed base across hybrid operating rooms in the United States and Germany. Procurement committees prioritize proven supply chains and interchangeable components over emerging specifications.
- OLED Display:Organic emissive layers eliminate backlight bleed and achieve infinite contrast ratios critical for neuro-interventional visualization. Tertiary hospitals in Japan and academic medical centers in Germany are accelerating replacement cycles to capture reduced heat emission benefits in sterile fields.
- LED Display:Direct-backlit configurations with local dimming arrays serve cost-sensitive installations requiring higher peak luminance than edge-lit alternatives.
- LCD Display:Legacy twisted-nematic and in-plane switching panels persist in non-interventional settings where grayscale calibration demands remain modest.
Flat panel configurations hold installed capacity. OLED variants are rotating up the share rankings.
End User:
Customer type shapes procurement authority, budget cycles, and service contract structures across the value chain.
- Hospitals:Tertiary institutions with hybrid operating room buildouts command multi-display procurement volumes and negotiate enterprise calibration agreements. German university hospital networks pioneered unbundled hardware-service pricing that North American systems now replicate.
- Ambulatory Surgical Centers:Freestanding facilities prioritize portable configurations and flexible room utilization over fixed infrastructure. Mobile cart systems address same-day discharge workflows that wall-mounted installations cannot accommodate.
- Clinics:Outpatient diagnostic settings require lower specification tiers focused on PACS integration rather than real-time surgical visualization.
- Research Laboratories:Preclinical and training environments drive demand for multi-display capability and 3D visualization in surgical simulation suites.
Hospitals anchor procurement volume. Ambulatory surgical centers are climbing the fastest as site-of-care migration accelerates.
Installation Type:
Physical mounting configuration determines spatial flexibility, infection control protocols, and capital depreciation schedules.
- Wall-mounted:Fixed bracket installations dominate legacy infrastructure in United States and Japanese tertiary hospitals. These configurations optimize sightline ergonomics but constrain room reconfiguration for multi-specialty use.
- Portable:Motorized cart systems with battery backup address ambulatory surgical center requirements for same-day room turnover. Indian tertiary hospital buildouts are specifying mobile configurations to maximize utilization across constrained square footage.
- Ceiling-mounted:Suspended boom integrations serve neurosurgical and cardiac suites requiring unobstructed floor access for equipment positioning.
- Integrated Systems:Vendor-neutral surgical boom packages bundle display, lighting, and gas delivery for greenfield hybrid operating room construction.
Wall-mounted systems retain legacy dominance. Portable configurations are gaining share fastest as flexible infrastructure investments expand.
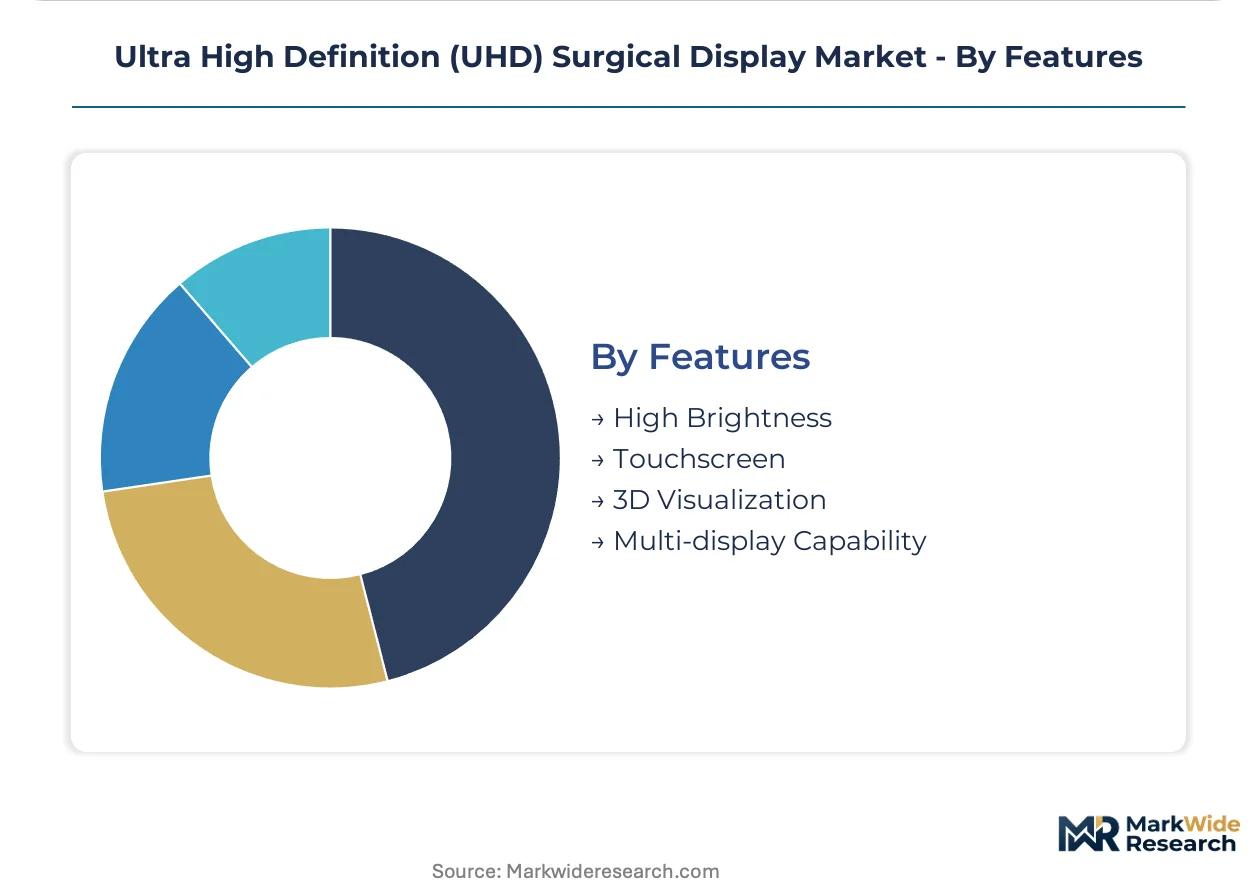
Features:
Functional specifications differentiate premium tiers and determine regulatory validation burdens for manufacturers.
- High Brightness:Luminance outputs exceeding 500 cd/m² enable visualization under direct surgical illumination. FDA 510(k) clearance pathways mandate photometric validation for these specifications.
- 3D Visualization:Stereoscopic rendering with active shutter or polarized glasses supports depth perception in laparoscopic and robotic-assisted procedures. Academic medical centers in Germany pilot these configurations for complex minimally invasive surgery training.
- Touchscreen:Projected capacitive or resistive overlays enable direct manipulation of surgical navigation interfaces without sterile field contamination.
- Multi-display Capability:Synchronized output across 2-4 panels supports picture-in-picture integration of preoperative imaging with real-time endoscopic feeds.
High brightness specifications hold baseline penetration. 3D visualization is rotating up the share rankings as robotic surgery adoption deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply across procurement environments. German university hospitals negotiate unbundled service contracts aggressively. Japanese tertiary institutions absorb premium pricing for electromagnetic compatibility certification. Indian AIIMS-affiliated centers prioritize capital efficiency over calibration sophistication.
United States
Hybrid operating room buildouts at Cleveland Clinic and Mayo Clinic drive multi-display procurement volumes. FDA 510(k) clearance pathways mandate photometric validation for luminance outputs exceeding 500 cd/m². The Texas Medical Center cluster in Houston concentrates demand for integrated surgical boom packages with vendor-neutral display configurations.
Germany
North Rhine-Westphalia's hospital networks pioneered unbundled hardware-service pricing that now spreads across Bavaria and Baden-Württemberg. EU Medical Device Regulation traceability requirements lock facilities into certified supplier relationships. The Munich industrial corridor anchors grayscale calibration expertise for radiology-surgery crossover environments.
Japan
PMDA electromagnetic compatibility standards tightened in 2023 for electrophysiology laboratory deployments. METI procurement guidelines favor domestic suppliers for catheterization lab installations. The Osaka-Kobe medical device cluster concentrates OLED surgical monitor pilot programs for neuro-interventional suites.
India
CDSCO Class B medical device registration streamlines for visualization equipment across 40+ AIIMS-affiliated institutions. Mobile cart configurations dominate procurement to maximize utilization across constrained square footage. The Delhi-NCR corridor concentrates tertiary hospital buildouts with flexible infrastructure specifications.
Ultra High Definition (UHD) Surgical Display Market Competitive Landscape
Capability concentration sits with heritage imaging specialists; scale advantage sits with diversified electronics conglomerates. The vendor base stratifies across three tiers: broadcast-grade calibration heritage, proprietary color-management protocols, and cost-optimized panel assembly. Strategic archetypes include integrated surgical workflow providers, standalone display specialists, and diversified industrial electronics manufacturers. Dominant competitive moves encompass long-term service contract lock-in and interoperability certification racing for hybrid operating room integration.
Within the heritage imaging tier, Sony Corporation and EIZO Corporation exemplify divergent specialization vectors. Sony leverages broadcast-grade image-processing lineage to anchor premium calibration service relationships. EIZO occupies a position focused on grayscale calibration standards for radiology-surgery crossover environments. Among diversified industrial players, Barco anchors proprietary color-management protocols that reinforce maintenance contract duration.
| Leading Market Players |
|---|
| Sony Corporation |
| STERIS |
| Barco |
| FSN Medical Technologies |
| Olympus Corporation |
| Siemens Healthineers |
| EIZO Corporation |
| Advantech |
| LG Electronics |
| Others |
Value Network & Pricing Analysis
Gyeonggi Province's OLED substrate foundries concentrate premium panel capacity, compressing margin negotiation leverage for downstream surgical display assemblers serving tertiary hospitals in Germany and Japan. This geographic concentration of emissive-layer manufacturing feeds directly into tiered pricing power across calibration-intensive product lines.
Pricing Analysis
Aftermarket calibration service contracts generate lifetime value multiples exceeding hardware margins for incumbent suppliers. Three-tier pricing structure across premium, standard, and economy levels segments by DICOM Part 14 certification grade and bundled maintenance duration. Pricing pressure stems from German university hospital networks forcing unbundled hardware-service negotiations. Ambulatory surgical centers exhibit highest price sensitivity; Japanese electrophysiology labs absorb premium pricing for PMDA electromagnetic compatibility validation.
Supply Chain Analysis
Upstream OLED organic compound synthesis and precision TFT backplane fabrication anchor in South Korea, Taiwan, and Japan. Premium surgical displays draw from concentrated Korean substrate foundries, Japanese grayscale calibration sensor components, and German optical-engine subassemblies. Single-source vulnerability in LG Display and Samsung Display OLED panel supply creates procurement risk for tier-two assemblers. Distribution runs through authorized medical device distributors with ISO 13485 certification and direct hospital GPO contracts in the United States and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OLED thermal-profile advantages are disrupting legacy flat-panel installed bases as PMDA electromagnetic standards tighten certification barriers. This regulatory-technological inflection compresses replacement cycles and consolidates supplier relationships around calibration-heritage players.
For Market Incumbents: Build proprietary color-management protocol moats through automated DICOM drift-correction networks that lock hospitals into recurring calibration subscriptions. Deepen backward integration into OLED panel sourcing through strategic offtake agreements with Korean foundries to defend against supply concentration risks. Acquire grayscale calibration engineering talent concentrated in Munich and Osaka industrial corridors to maintain service differentiation. For New Entrants and Emerging Players: India's AIIMS-affiliated tertiary hospital buildout offers the most penetrable geographic entry point with streamlined CDSCO Class B registration pathways. Target mobile cart configurations for ambulatory surgical centers where flexible room utilization requirements outpace incumbent wall-mounted infrastructure. Pursue ISO 13485 convergence certification to reduce duplicate audit burdens across multiple regulatory jurisdictions simultaneously. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among heritage imaging specialists with broadcast-grade calibration service relationships. Long-term viability favors targets with locked hospital maintenance contracts spanning hybrid operating room installations. Monitor PMDA electromagnetic recertification timelines as an inflection signal for competitive refresh windows in Japanese catheterization lab procurement.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Photometric validation for luminance outputs exceeding 500 cd/m² mandates pre-market notification. |
| EU MDR Traceability Compliance | Color-calibration documentation requirements eliminate gray-market competitors from hospital procurement. |
| Hospital System Partnership | Enterprise calibration agreements with German university networks unbundle hardware-service pricing. |
| Software Companion Development | Automated sensor networks for continuous DICOM compliance address installed base calibration drift. |
| Reimbursement Strategy | Hybrid OR capital equipment coding alignment accelerates procurement committee approval cycles. |
Research Methodology
The analysis maps flat-panel, OLED, LED, and LCD surgical display architectures, each validated through hospital procurement committees, biomedical engineering directors, GPO contracts managers, and surgical navigation platform integrators. Primary interviews with these stakeholders combined with FDA 510(k) clearance databases, EU MDR notified body filings, Japanese PMDA approval records, and Indian CDSCO registration portals. Secondary sources include hospital procurement databases, GPO contract repositories, and medical device trade customs data. Bottom-up unit demand estimates triangulate against top-down market value reconstructions.
Assumptions held fixed include regulatory compliance timelines, OLED substrate foundry capacity expansion schedules, and hybrid operating room installation rates at major academic medical centers. Variables include electromagnetic compatibility standard revisions, grayscale calibration labor availability, and ambulatory surgical center portability adoption curves. CAGRs derive from segmented demand modeling across product type, end user, installation configuration, and feature specification dimensions. Industry-specific inputs incorporate DICOM Part 14 compliance adoption rates and PACS integration complexity indices.
Practitioners should monitor PMDA electromagnetic recertification deadlines, Korean foundry capacity utilization reports, and German hospital network procurement unbundling trends for early signals of forecast revision. Cross-checking against hospital capital expenditure surveys and medical device distributor inventory cycles is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Drug Device Combination Products Market
Medical Devices
Lacrimal Devices Market
Medical Devices
Global Pupillometer Market
Medical Devices
Rhinoplasty Implants Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Intravaginal Device Market
Medical Devices
US Medical Sector Contract Electronic Manufacturing Market
Medical Devices
Brazil Cardiac Pacemakers Market
Medical Devices
Global Breast Biopsy Devices Market
Medical Devices
Global Defibrillators Market
Medical Devices
Electrosurgery Accessories Market
Medical Devices
US Medical Bionic Implants & Artificial Organs Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Global Smart Implants Market
Medical Devices
Asthma Spacers Market
Medical Devices
Global Bowel Management System Market