
 GCC Orthopedic Braces and Supports Market | 2026-2036
GCC Orthopedic Braces and Supports Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Orthopedic Braces and Supports Market Insights
Post-surgery patients are gaining share against athletes as the dominant buyer archetype in the GCC orthopedic braces and supports market is bifurcating toward clinical rehabilitation channels. Zimmer Biomet leverages its hospital supply relationships to sustain premium positioning across Gulf surgical networks. Ottobock anchors its regional presence through specialized prosthetic-orthotic service centers in Dubai and Riyadh. Bauerfeind differentiates via German-engineered compression technology that commands loyalty among physiotherapy clinics.
Orthopedic braces and supports are mechanical or semi-rigid devices fabricated from polymers, metals, textiles, or composite laminates, designed to restrict joint motion, offload mechanical stress, or stabilize musculoskeletal structures during healing or activity. Knee braces fabricated with carbon fiber frames and silicone padding dominate hospital procurement budgets due to their durability under Gulf climate conditions. Rigid technology leads institutional sales while 3D printed customization captures the fastest expansion among high-end sports medicine clinics seeking patient-specific anatomical fit. The elderly end-user segment occupies expanding shelf space at pharmacy chains as Gulf populations age and osteoarthritis diagnoses multiply.
Saudi Food and Drug Authority and UAE Ministry of Health and Prevention enforce medical device registration standards that mandate biocompatibility testing and clinical evidence for brace classifications, filtering out uncertified imports. The UAE's mandatory health insurance reforms and Saudi Arabia's privatization of healthcare delivery are reshaping reimbursement pathways and procurement centralization. Stakeholders must monitor regulatory harmonization timelines between Gulf Cooperation Council states to anticipate whether unified device approval will accelerate market entry or consolidate incumbent advantages.
Market Dynamics
The GCC orthopedic braces and supports market is restructuring around post-acute care centralization, as Saudi Arabia's hospital privatization and UAE insurance reforms compress procurement decisions into fewer institutional buyers with stricter technical specifications.
Growth Catalysts
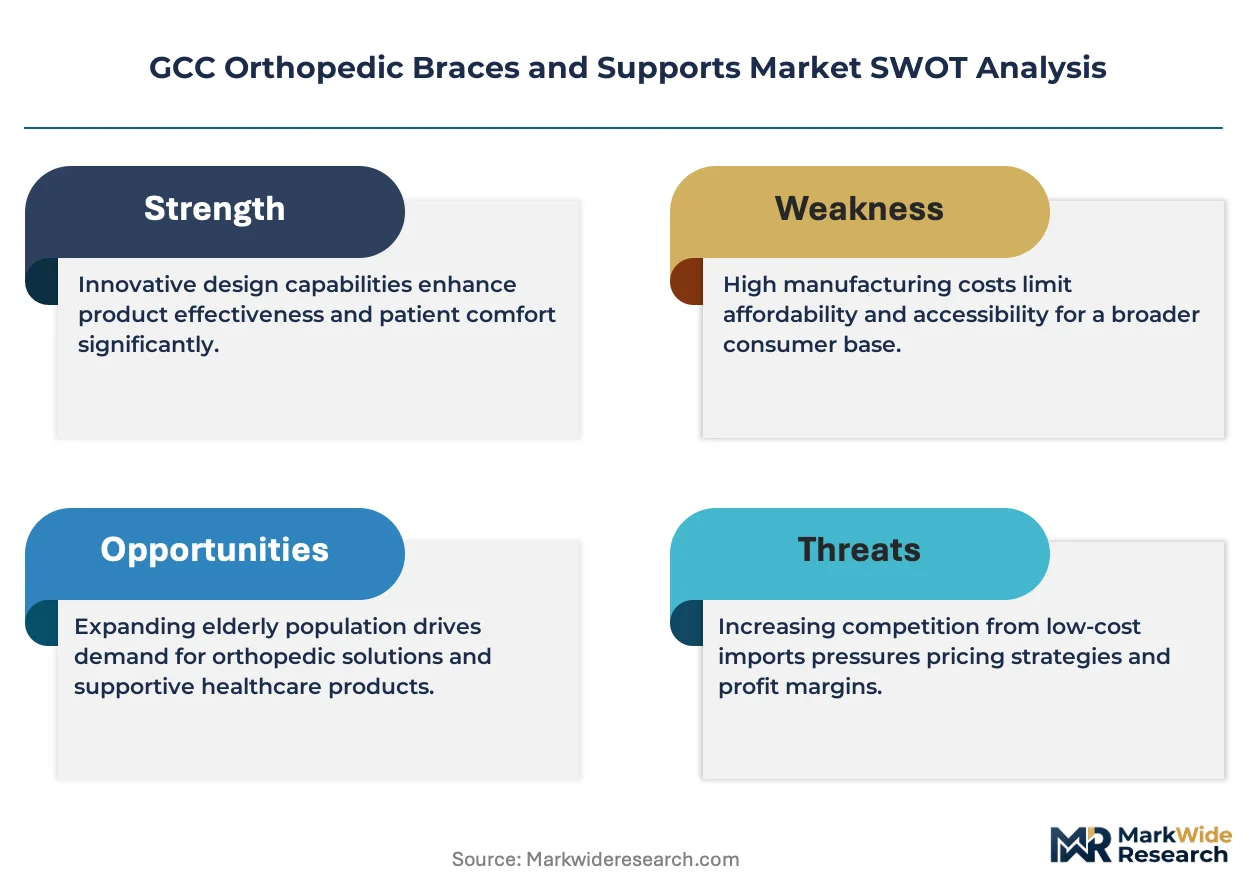
- SFDA Registration Mandates:Saudi Food and Drug Authority enforcement of biocompatibility testing and clinical evidence requirements is filtering uncertified imports, elevating compliant manufacturers into preferred supplier status across Riyadh-Jeddah hospital networks.
- Carbon Fiber Frame Adoption:Knee braces fabricated with carbon fiber frames and silicone padding are capturing institutional procurement budgets due to durability under Gulf climate conditions and extended wear-cycle performance.
- 3D Printed Customization:High-end sports medicine clinics in Dubai are adopting patient-specific anatomical fitting for rigid brace fabrication, compressing turnaround times from weeks to days for complex post-surgical applications.
Market Restraints
- Polymer Input Volatility:Medical-grade polypropylene and thermoplastic elastomer prices fluctuate with petrochemical feedstock costs, squeezing margin structures for manufacturers without backward integration into polymer supply.
- Registration Timeline Friction:UAE Ministry of Health and Prevention device approval processes extend 12-18 months for novel brace classifications, delaying market entry for innovative products against incumbent catalog positions.
- Compression Sleeve Substitution:Basic elastic compression garments from textile manufacturers are capturing mild osteoarthritis cases that previously warranted semi-rigid brace prescriptions, compressing addressable volume in pharmacy retail channels.
Strategic Opportunities
- Kuwait Underpenetration:Kuwait's orthopedic device market lacks specialized prosthetic-orthotic service infrastructure, creating first-mover advantage for service-center models that integrate fitting, adjustment, and rehabilitation protocol design.
- Elderly Pharmacy Channel:Aging Gulf populations and multiplying osteoarthritis diagnoses are expanding shelf-space allocation for off-the-shelf knee and back braces at pharmacy chains serving walk-in geriatric consumers.
- MOHAP Insurance Integration:UAE mandatory health insurance reforms are embedding orthopedic brace coverage into standard benefit packages, reducing out-of-pocket friction and expanding reimbursed addressable demand.
Industry Challenges
- Prosthetist-Orthotist Talent Scarcity:Certified fitting specialists are concentrated in Dubai and Riyadh, creating service delivery bottlenecks for manufacturers attempting geographic expansion into secondary GCC cities.
- Biocompatibility Testing Capex:In-house ISO 10993 testing capability requires substantial laboratory investment, forcing smaller manufacturers to outsource and extend product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Orthopedic Braces and Supports Market |
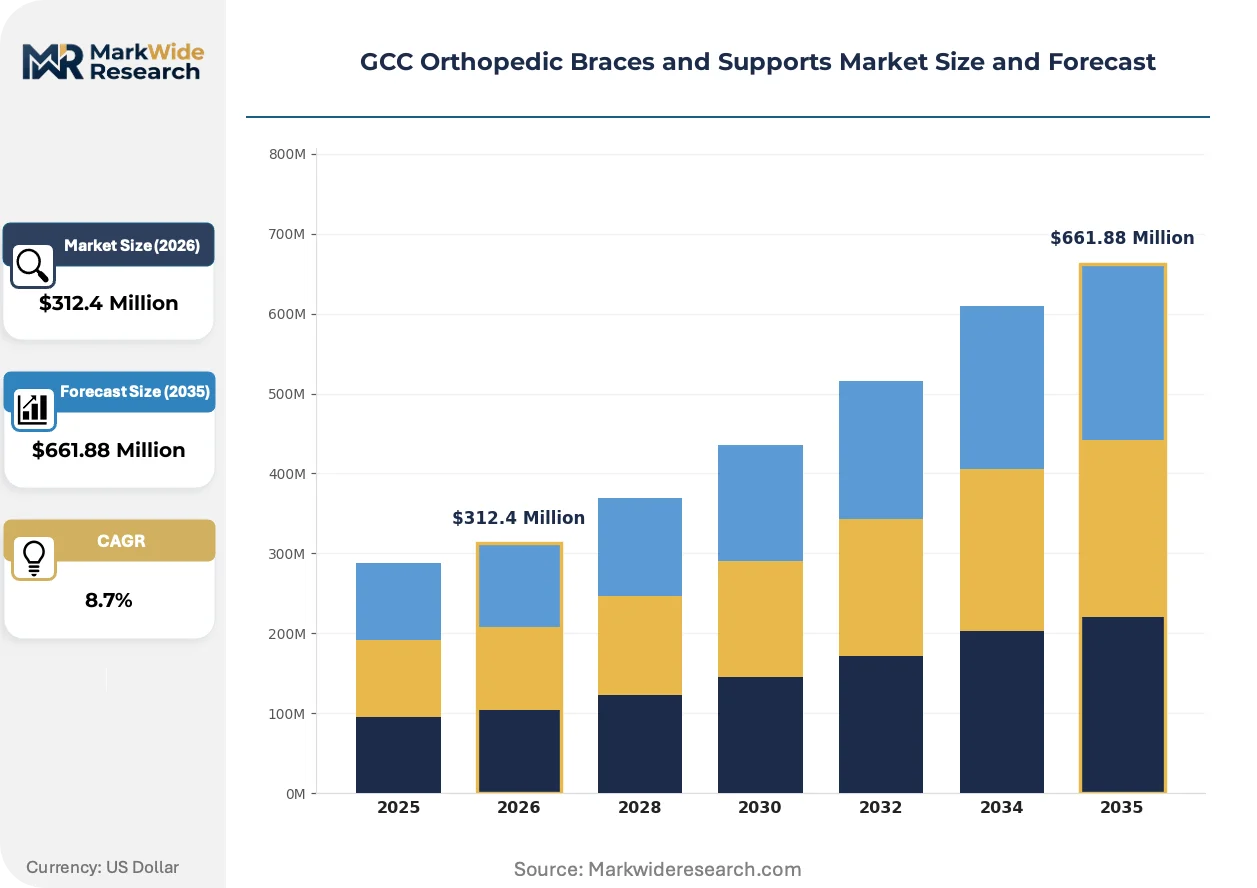
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $661.88 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Knee Braces, Ankle Braces, Back Supports, Wrist Supports Technology: Elastic, Rigid, Magnetic, 3D Printed End User: Athletes, Elderly, Post-Surgery Patients, Active Individuals Distribution Channel: Online Retail, Pharmacies, Hospitals, Specialty Stores |
| Companies Covered | Zimmer Biomet, Ossur, 3M, DJO LLC, Becker Orthopedic, Ottobock, Bauerfeind, DeRoyal Industries, BREG, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Orthopedic Braces and Supports Market Trends and Innovations
Digital manufacturing and regulatory tightening are converging to reshape product development cycles and distribution economics across Gulf orthopedic device markets.
Additive manufacturing of patient-specific brace components is displacing thermoforming for complex anatomical cases in Dubai's sports medicine clinics. Hospital procurement committees are specifying 3D-printed customization for post-surgical rigid braces where standard sizing fails. This technology is displacing inventory-heavy distribution models that relied on size-range speculation, compressing working capital requirements for specialized service centers.
UAE Ministry of Health and Prevention tightened medical device registration requirements are elevating compliance documentation burdens for brace classifications. Manufacturers must now submit clinical evidence packages and biocompatibility testing results that previously applied only to implantable devices. High-end rigid brace segments are responding by consolidating supplier relationships with established registrants rather than onboarding novel entrants.
Hospital procurement centralization is compressing vendor counts as Saudi privatization concentrates purchasing authority within holding company supply chains. Independent orthopedic clinics are losing direct supplier access as procurement decisions migrate to centralized committees. This concentration is most visible in Riyadh-Jeddah corridor specialty clinics now funneled through approved vendor lists managed by hospital group procurement offices.
GCC Orthopedic Braces and Supports Market Segmentation
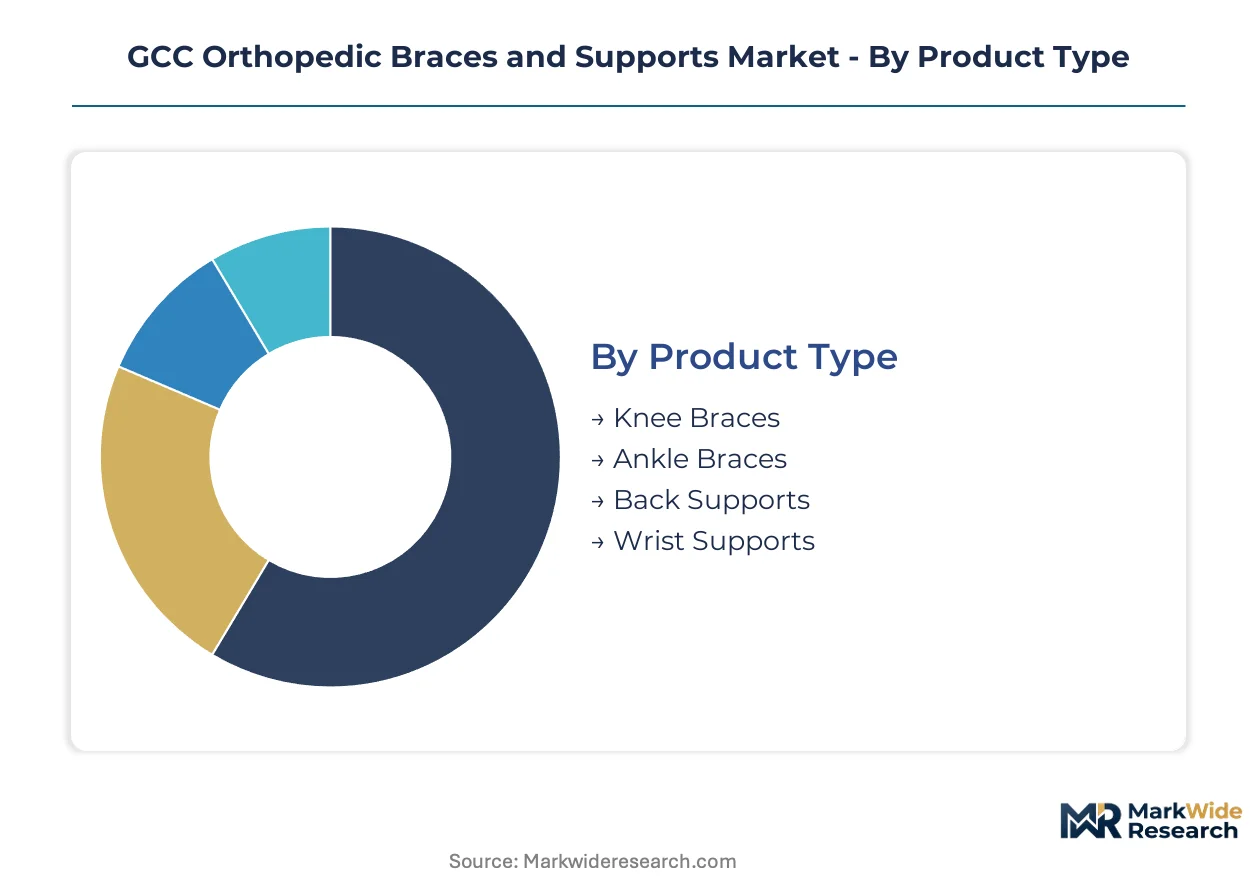
Orthopedic brace manufacturers must navigate divergent substitution pressures across product categories, where basic compression garments threaten entry-level segments while premium rigid devices defend against cheaper alternatives through clinical validation requirements. Segmentation strategy determines whether suppliers pursue volume through pharmacy retail or margin through hospital procurement centralization.
Product Type:
Substitution pressure from unbranded compression sleeves hits ankle and wrist categories hardest, while knee and back segments maintain structural demand through physician prescription requirements and surgical protocol integration.
- Knee Braces:Carbon fiber frames with silicone padding dominate institutional procurement in Saudi Arabia's Riyadh-Jeddah corridor hospitals. Post-surgical rehabilitation programs across privatized Saudi hospital networks are expanding rigid knee brace procurement as standardized discharge protocols.
- Back Supports:Semi-rigid lumbar braces with thermoplastic shells and adjustable compression straps capture expanding pharmacy shelf space. Aging Gulf populations and multiplying osteoarthritis diagnoses are driving walk-in geriatric demand at retail pharmacy chains.
- Ankle Braces:Elastic compression sleeves from textile manufacturers capture mild sprain cases that previously warranted semi-rigid prescriptions.
- Wrist Supports:Basic neoprene wraps face commoditization pressure from unbranded alternatives in online retail channels.
Knee braces retain volume leadership; back supports hold the steepest expansion curve.
Technology:
Cost tier stratification separates premium fabrication methods from commodity production, with 3D printed and rigid technologies commanding hospital procurement budgets while elastic and magnetic variants compete on price in retail channels.
- Rigid:Molded polymer and composite laminate braces with aluminum or carbon fiber structural elements anchor institutional sales. SFDA registration mandates for biocompatibility testing filter uncertified imports, elevating compliant rigid brace manufacturers into preferred supplier status.
- 3D Printed:Patient-specific anatomical fitting fabricated through additive manufacturing compresses turnaround times from weeks to days. Dubai's high-end sports medicine clinics are adopting this technology for complex post-surgical applications where standard sizing fails.
- Elastic:Textile-based compression garments face margin compression from polymer input volatility tied to petrochemical feedstock costs.
- Magnetic:Therapeutic claims require clinical evidence packages under tightened UAE MOHAP registration requirements, delaying market entry.
Rigid technology commands procurement volume; 3D printed fabrication is expanding most quickly among premium service centers.
End User:
Customer type bifurcation is concentrating demand around clinical rehabilitation channels, with post-surgery patients displacing athletes as the dominant buyer archetype across Gulf orthopedic networks.
- Post-Surgery Patients:Rigid brace prescriptions integrated into discharge protocols at Saudi privatized hospitals create predictable demand streams. Procurement centralization within hospital holding companies is compressing vendor counts for this segment.
- Elderly:Walk-in consumers at pharmacy chains seek off-the-shelf knee and back braces for osteoarthritis management. Kuwait's underpenetrated market lacks specialized service infrastructure, creating first-mover opportunity for integrated fitting and rehabilitation protocol design.
- Athletes:Sports medicine clinics in Dubai represent a concentrated but smaller addressable market compared to clinical rehabilitation.
- Active Individuals:Preventive brace usage remains limited by out-of-pocket payment friction outside reimbursed channels.
Post-surgery patients anchor institutional demand; the elderly segment is gaining share fastest through pharmacy retail expansion.
Distribution Channel:
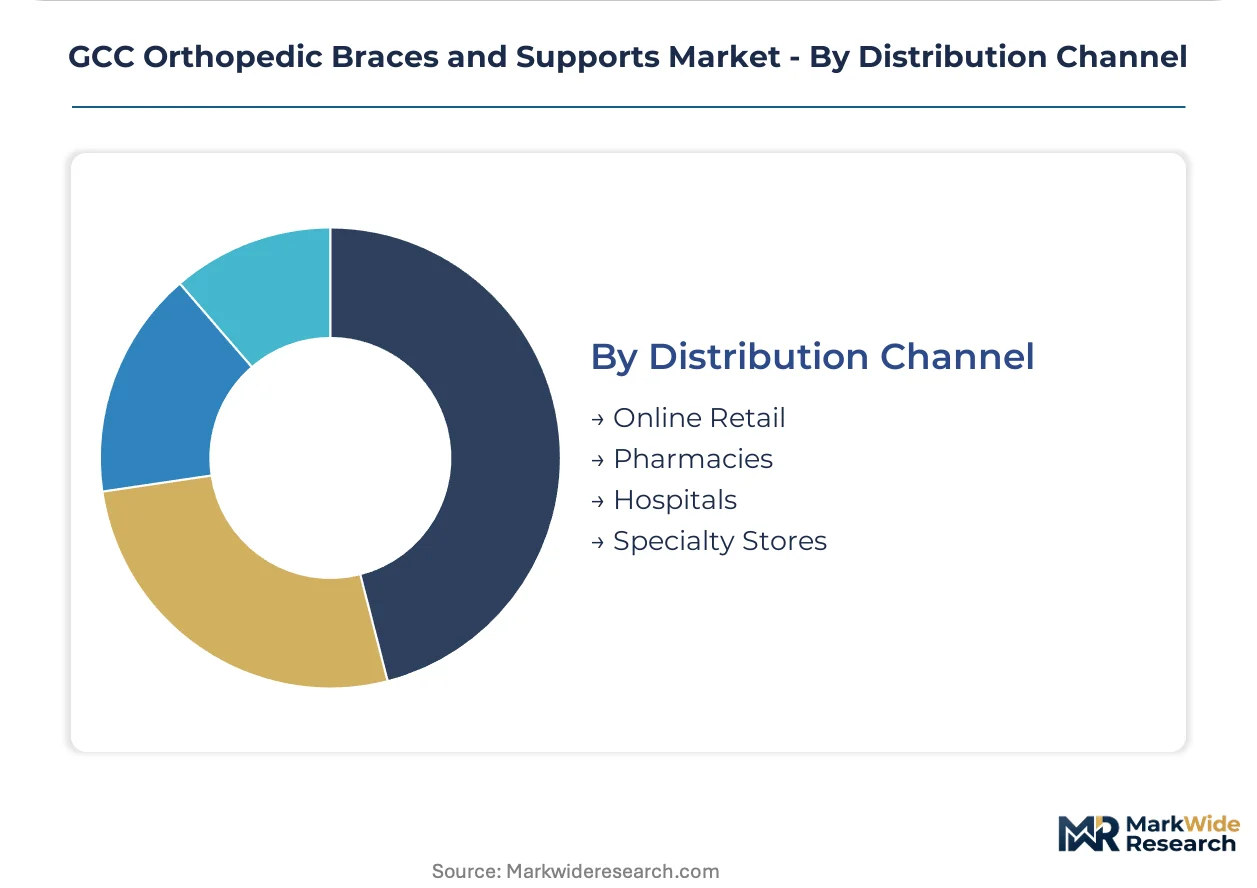
Supply concentration in hospital procurement offices is displacing independent clinic access, while online retail captures price-sensitive substitution demand that bypasses clinical validation requirements.
- Hospitals:Centralized procurement committees at Saudi hospital groups and UAE health systems specify technical requirements and approved vendor lists. Carbon fiber frame durability under Gulf climate conditions is a mandatory specification in institutional tenders.
- Pharmacies:Chain retail networks are expanding shelf-space allocation for geriatric-targeted braces as Gulf populations age. Walk-in consumers drive volume for off-the-shelf compression and semi-rigid products.
- Specialty Stores:Prosthetic-orthotic service centers in Dubai and Riyadh concentrate certified fitting specialist talent, creating geographic bottlenecks for expansion.
- Online Retail:E-commerce channels capture basic elastic compression garment demand that escapes clinical prescription pathways.
Hospitals dominate value capture; pharmacies are climbing the fastest as aging demographics reshape retail allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Fahd Causeway links Saudi Arabia and Bahrain, cementing the Eastern Province as the Gulf's medical device distribution nexus for orthopedic imports transiting through Dammam's industrial ports.
Saudi Arabia
Privatized hospital networks in Riyadh and Jeddah are consolidating procurement authority within holding company supply chains. SFDA registration mandates for biocompatibility testing filter uncertified imports, elevating compliant manufacturers into preferred supplier status. The Riyadh-Jeddah corridor clusters orthopedic specialty clinics now funneled through approved vendor lists.
United Arab Emirates
MOHAP tightened medical device registration requirements, extending approval timelines to 12-18 months for novel brace classifications. Mandatory health insurance reforms embed orthopedic brace coverage into standard benefit packages, expanding reimbursed demand. Dubai's high-end sports medicine clinics concentrate 3D printed customization adoption for complex post-surgical applications.
Kuwait
The orthopedic device market lacks specialized prosthetic-orthotic service infrastructure, creating first-mover advantage for integrated service-center models. Aging demographics drive walk-in geriatric demand at pharmacy chains for off-the-shelf knee and back braces. Kuwait City's medical district shows underpenetration compared to Riyadh or Dubai benchmarks.
Qatar
Hamad Medical Corporation centralizes procurement for public healthcare infrastructure, compressing vendor counts for institutional brace supply. National health insurance schemes reduce out-of-pocket friction for post-surgical rehabilitation devices. Doha's specialty clinics remain dependent on Dubai-based fitting specialists for complex custom fabrication.
Bahrain
The King Fahd Causeway facilitates cross-border supply from Saudi Arabia's Eastern Province, positioning Bahrain as a secondary distribution node. Private hospital groups in Manama source through Saudi-registered suppliers to bypass duplicative regulatory burdens. Local pharmacy chains capture geriatric walk-in demand with limited specialized service infrastructure.
GCC Orthopedic Braces and Supports Market Competitive Landscape
Concentration sits with multinational medical device conglomerates that leverage hospital supply relationships and regulatory compliance scale. The vendor base stratifies across three tiers: premium registrants with full SFDA/MOHAP dossiers, mid-tier regional distributors with limited customization capability, and commodity importers facing registration barriers. Strategic moves center on procurement committee capture through approved vendor list placement and 3D printing capability acquisition for patient-specific fabrication.
Within the premium registrant tier, Zimmer Biomet and Ottobock exemplify archetypes that anchor hospital network positioning through compliant supply relationships. Becker Orthopedic occupies a position among specialized fabricators with prosthetic-orthotic service center integration. These three represent distinct strategic postures: conglomerate scale, integrated service delivery, and specialized fabrication expertise respectively.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Ossur |
| 3M |
| DJO LLC |
| Becker Orthopedic |
| Ottobock |
| Bauerfeind |
| DeRoyal Industries |
| BREG |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber frame manufacturing economies at scale suppliers in Germany and China compress per-unit costs for institutional knee brace procurement, while smaller fabricators face margin erosion from polymer input volatility and extended SFDA registration timelines. This scale asymmetry concentrates pricing power among compliant manufacturers with backward integration into medical-grade polymer supply, forcing mid-tier distributors toward service-based differentiation or exit.
Pricing Analysis
Volume-discount tiering structures separate premium rigid brace manufacturers with full SFDA/MOHAP dossiers from standard-tier regional distributors and economy-grade commodity importers facing registration barriers. Price differentiation rests on certification grade and after-sales fitting service bundling. Pricing pressure stems from polymer input volatility tied to petrochemical feedstock costs. Hospital procurement committees demonstrate lowest price sensitivity due to centralized budgets, while pharmacy retail channels serving elderly walk-in consumers exhibit highest elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate Dubai's high-end sports medicine clinics where 3D printed customization compresses patient-specific brace turnaround from weeks to days, while Saudi hospital networks maintain strategic stockpiles of carbon fiber knee braces to ensure discharge protocol compliance. Geographic supply concentration centers on Germany, China, and the United States for carbon fiber composites and medical-grade polymers. Raw material dependencies include polypropylene, thermoplastic elastomers, and silicone padding. Supply chain risk manifests as single-source vulnerability for certified prosthetist-orthotist talent concentrated in Dubai and Riyadh. Distribution runs through hospital procurement committees, specialty service centers, pharmacy chains, and online retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as Saudi hospital privatization and UAE insurance reforms compress procurement decisions into fewer institutional buyers with stricter technical specifications and approved vendor lists.
For Market Incumbents: Secure placement on approved vendor lists at Saudi hospital holding companies and UAE health systems by accelerating SFDA and MOHAP registration dossiers for expanded brace classifications. Deepen backward integration into medical-grade polymer supply to defend margin structures against petrochemical feedstock volatility. The threat of 3D printed customization adoption by Dubai sports medicine clinics demands capability acquisition or partnership with additive manufacturing specialists. For New Entrants and Emerging Players: Certification fast-track through regulatory consulting partnerships targeting Kuwait's underpenetrated prosthetic-orthotic service infrastructure offers first-mover positioning before incumbent service-center expansion. The elderly pharmacy channel in Kuwait City and secondary Saudi cities represents the most penetrable segment given limited specialized fitting infrastructure. A go-to-market angle integrating remote fitting consultation with off-the-shelf brace distribution bypasses talent scarcity bottlenecks. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among prosthetic-orthotic service centers with integrated fitting, adjustment, and rehabilitation protocol design capabilities. Long-term viability over a five-to-ten year window favors acquisition targets with established SFDA/MOHAP registrations and 3D printing fabrication capacity rather than commodity distribution assets. The signal to watch is regulatory harmonization timelines between GCC states, where unified device approval would accelerate market entry for compliant registrants.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Acceleration | Fast-tracked biocompatibility dossiers secure preferred supplier status at Riyadh-Jeddah hospital networks. |
| 3D Printing Capability Acquisition | Additive manufacturing integration captures Dubai sports medicine clinic demand for patient-specific anatomical fitting. |
| Kuwait Service Center Establishment | First-mover infrastructure in underpenetrated market creates integrated fitting and rehabilitation protocol moats. |
| Backward Polymer Integration | In-house medical-grade polypropylene production insulates margins from petrochemical feedstock volatility. |
| MOHAP Insurance Integration | Reimbursement pathway alignment with UAE mandatory health insurance reforms expands addressable demand pools. |
Research Methodology
The analysis maps rigid brace, semi-rigid support, and compression garment sub-sectors, each validated through hospital procurement managers, prosthetist-orthotist specialists, biomedical engineers, and pharmacy category buyers. Primary interviews with these stakeholders combined with secondary validation against SFDA registration databases, MOHAP medical device filings, hospital procurement records, and GCC customs trade data. Bottom-up demand modeling across patient discharge protocols and top-down supply validation through manufacturer capacity assessments enabled triangulation.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions including product rigidity tier, fabrication technology, end-user rehabilitation stage, and distribution channel concentration. CAGRs derived from patient population growth, surgical procedure volumes, and insurance coverage expansion trajectories. Industry-specific forecast inputs incorporated SFDA registration timeline friction and 3D printing adoption curves at Dubai sports medicine clinics.
Decision-makers should treat outputs as directional under assumptions of sustained hospital privatization momentum and stable polymer feedstock pricing; material deviation would warrant model refresh. Forecasts reflect these base assumptions alongside projected aging demographic trajectories and insurance reimbursement pathway stability. Revision becomes warranted when regulatory harmonization timelines between GCC states accelerate or decelerate beyond current policy signaling thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Orthopedic Devices
Vertebroplasty and Kyphoplasty Devices Market
Orthopedic Devices
Hip Replacement Market
Orthopedic Devices
Asia-Pacific Kyphoplasty Market
Orthopedic Devices
Orthopedic Contract Manufacturing Market
Orthopedic Devices
Prosthetics and Orthotics Market
Orthopedic Devices
Antibacterial Orthopedic Implant Market
Orthopedic Devices
Global Veterinary Orthopedics Market
Orthopedic Devices
North America Spinal Surgery Market
Orthopedic Devices
Closed Heel Nursing Shoes Market
Orthopedic Devices
Global Total Knee Replacement Market
Orthopedic Devices
Dental Orthotic Devices Market
Orthopedic Devices
Spine Surgery Devices Market
Orthopedic Devices
Hip Orthosis Market
Orthopedic Devices
Europe Orthopedic Navigation Systems Market
Orthopedic Devices
Global Orthopedic Navigation Systems Market
Orthopedic Devices
Orthotic Devices Orthotic Splints and Orthopedic Braces and Support Market