
 Global Gynecology Devices Market | 2026-2036
Global Gynecology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Global Gynecology Devices Market Foresight
EU MDR is broadening the cost-of-entry calculus for gynecology device manufacturers seeking CE marking in Europe. Boston Scientific Corporation leverages its regulatory infrastructure to sustain multi-market registrations across high-stringency jurisdictions. Hologic, Inc. anchors its competitive position through specialized diagnostic imaging platforms for cervical cancer screening workflows. Medtronic plc competes on manufacturing scale, extending its supply network to serve high-volume hospital purchasing consortia.
Gynecology devices encompass instrument systems, energy platforms, and visualization tools engineered for diagnostic and therapeutic procedures within the female reproductive tract, typically manufactured from medical-grade stainless steel, polymer composites, or ceramic substrates with precision tolerances of 0.1 mm or finer for minimally invasive access. Their primary commercial purpose centers on enabling accurate tissue manipulation, bleeding control, and anatomical visualization during hysteroscopy, laparoscopy, and fertility interventions. Ultrasound systems and hysteroscopes command the largest installed base, reflecting their indispensability in initial diagnostic workups across fertility clinics and academic medical centers. Electrosurgical devices represent the fastest-expanding product category as outpatient facilities convert open procedures to loop excision and endometrial ablation techniques. Catheters and cryotherapy systems occupy narrower margin pools, constrained by commodity pricing pressures in bulk procurement contracts.
FDA premarket notification pathways and EU MDR conformity assessments shape product development timelines and clinical evidence requirements for manufacturers distributing in North America and Europe. China's NMPA implements distinct GB standards for electrosurgical safety and biocompatibility testing, creating parallel compliance obligations for multinational portfolios. ISO 13485 quality management certification functions as a baseline qualifier for contract manufacturing relationships across all target markets. Stakeholders must monitor how divergent sterilization validation protocols between FDA and EMA jurisdictions affect reusable device economics and single-use conversion rates.
Market Dynamics
Outpatient surgical migration is compressing hospital purchasing cycles and forcing device manufacturers to recalibrate their service architectures around ambulatory surgical center workflows rather than traditional inpatient procurement models.
Growth Catalysts
- EU MDR recertification mandates:Reusable hysteroscopic systems face upgraded clinical evidence requirements, accelerating replacement demand among European hospitals seeking compliant inventory.
- Ambulatory surgical center expansion:United States outpatient facilities are converting open hysterectomies to loop excision procedures, expanding the addressable base for electrosurgical platforms.
- China's fertility clinic infrastructure:Provincial governments in Guangdong and Jiangsu are subsidizing assisted reproductive technology centers, driving diagnostic ultrasound and hysteroscope procurement.
Market Restraints
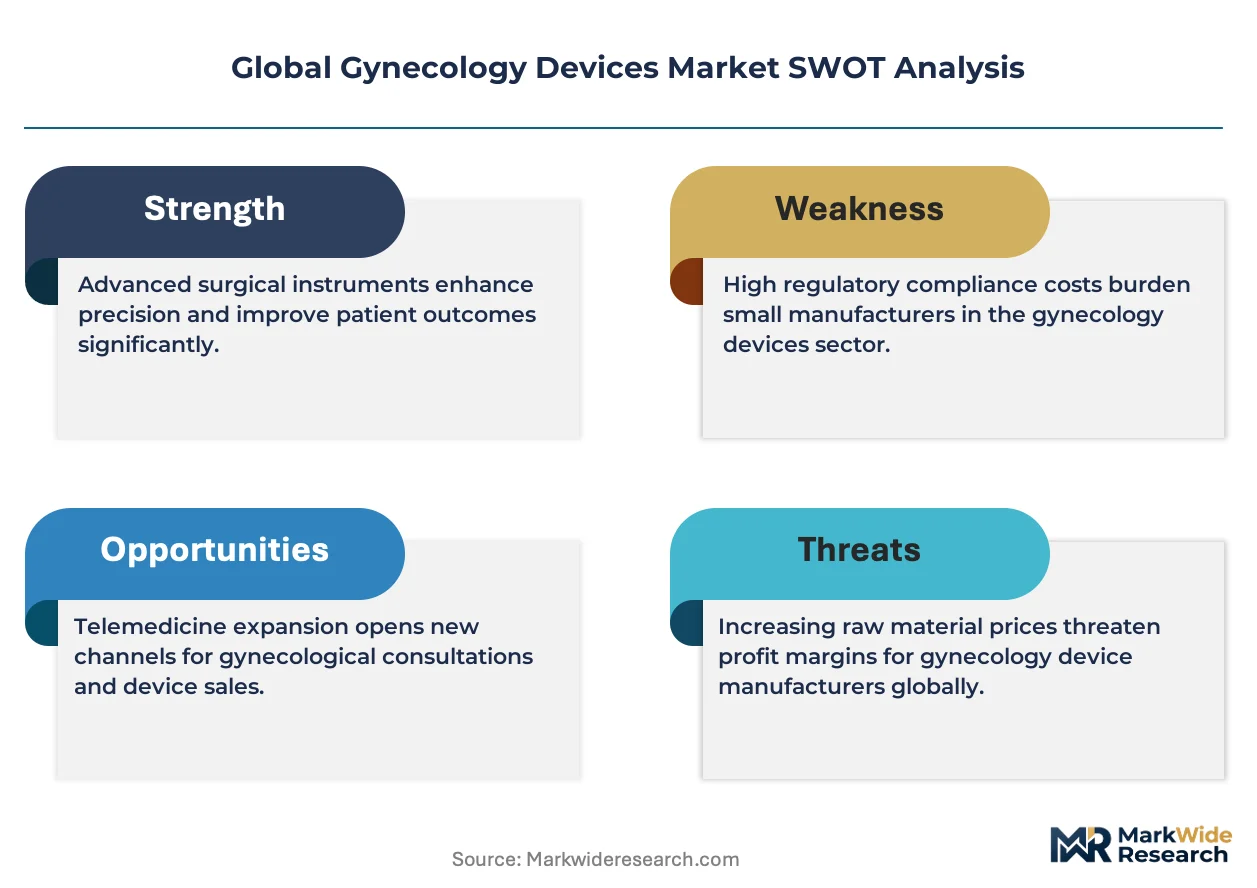
- Medical-grade polymer supply concentration:Precision polymer composites for instrument shafts depend on German and Japanese specialty chemical suppliers, exposing manufacturers to input cost volatility.
- EU MDR conformity assessment bottlenecks:Notified body capacity constraints extend CE marking timelines for Class IIa reusable devices, delaying European market entry.
- Single-use conversion economics:Sterilization validation costs for reusable systems under FDA 510(k) pathways are narrowing the cost gap with disposable alternatives.
Strategic Opportunities
- India's tier-two city penetration:Gynecological screening programs in Maharashtra and Tamil Nadu remain underpenetrated for colposcopy and cryotherapy systems relative to metropolitan benchmarks.
- AI-assisted hysteroscopic navigation:Machine vision algorithms are converging with conventional optical systems to reduce operative time and training burdens for complex polypectomy.
- Brazil's ANVISA fast-track pathway:Streamlined registration for devices with prior FDA or CE approval reduces time-to-market for manufacturers with established regulatory dossiers.
Industry Challenges
- Hysteroscopic skill acquisition timelines:Academic medical centers report extended learning curves for advanced operative hysteroscopy, constraining procedure throughput and device utilization rates.
- Cross-jurisdictional sterilization validation:Divergent FDA and EMA protocols for reusable device reprocessing force manufacturers to maintain parallel quality systems, elevating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Gynecology Devices Market |
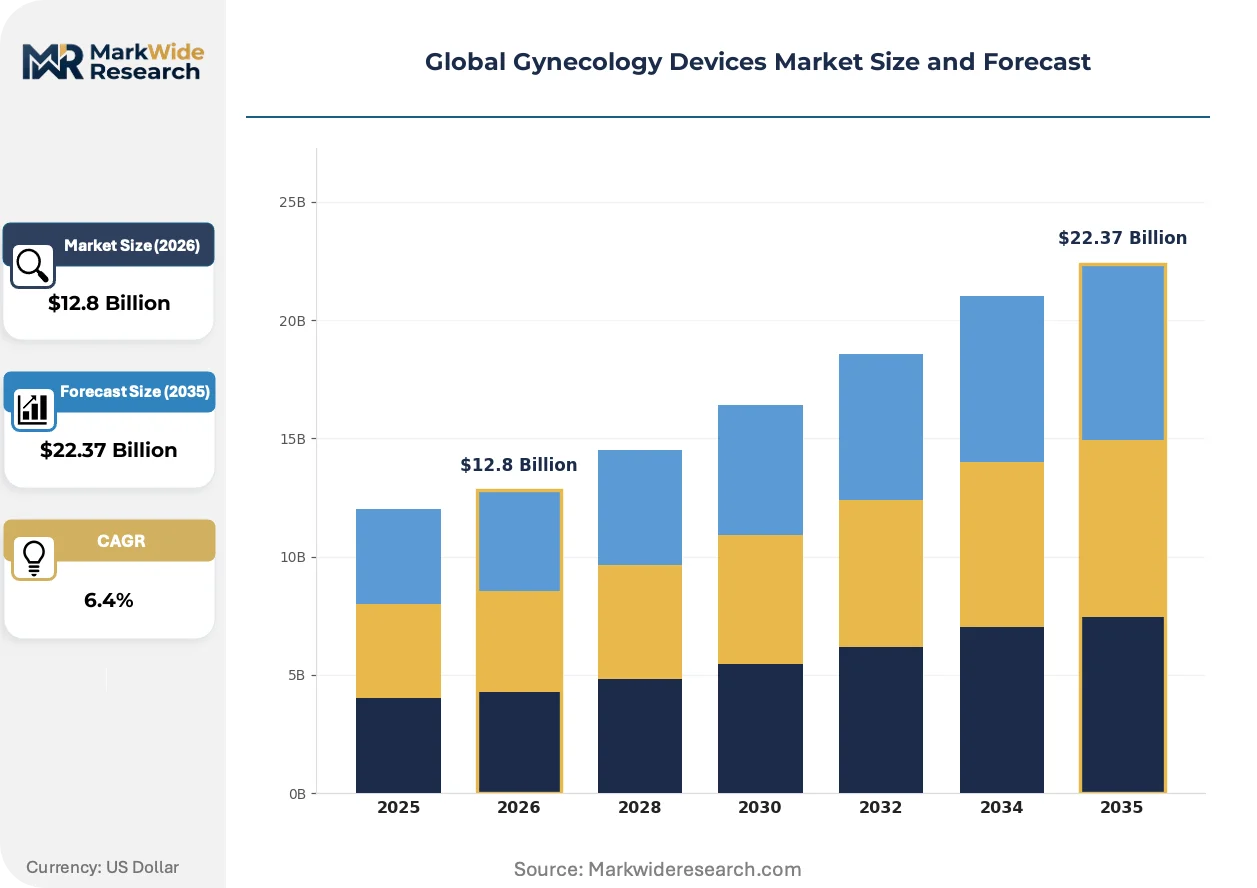
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.37 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasound Systems, Hysteroscopes, Electrosurgical Devices, Catheters, Cryotherapy Systems, Laparoscopes Application: Fertility Treatment, Pelvic Organ Prolapse, Menstrual Disorders, Endometriosis, Cervical Cancer Screening, Uterine Fibroids End User: Specialty Clinics, Diagnostic Centers, Ambulatory Surgical Centers, Fertility Clinics, Private Practices, Academic Medical Centers Deployment: Inpatient Facilities, Outpatient Facilities, Mobile Health Units, Telemedicine Platforms |
| Companies Covered | Boston Scientific Corporation, Hologic, Inc., Medtronic plc, CooperSurgical Inc., Karl Storz SE & Co. KG, Stryker Corporation, Johnson & Johnson, Olympus Corporation, Richard Wolf GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Gynecology Devices Market Shifts & Advancements
Digital integration and energy platform miniaturization are redefining the technical specifications that determine competitive viability across diagnostic and therapeutic gynecology workflows.
Single-use hysteroscopes with integrated 4K imaging chips are converging with cloud-based procedure documentation systems, enabling fertility clinics to eliminate capital equipment depreciation while capturing reimbursable diagnostic data. Academic medical centers in Germany and the Netherlands are piloting these platforms for office-based polypectomy. The shift is compressing the traditional sales cycle from capital budget approval to disposable contract negotiation.
EU MDR Article 10 clinical evaluation requirements are forcing manufacturers to generate post-market surveillance data for legacy reusable devices, not merely new submissions. This recalibrates R&D resource allocation toward clinical affairs functions. Hysteroscopic morcellation systems face particular scrutiny, with notified bodies demanding extended follow-up studies on tissue dispersion rates.
Hospital purchasing consortia in the United States are consolidating gynecology device procurement under single-source agreements that bundle capital equipment, disposables, and service contracts. Independent ambulatory surgical centers respond by joining group purchasing organizations to recover negotiating leverage. The behavioral shift is most pronounced in Texas and Florida, where freestanding women's health facilities have proliferated fastest.
Global Gynecology Devices Market Segmentation
Device specialization in gynecology tracks the procedural shift from open surgery to minimally invasive and office-based interventions. Segmentation reveals how purchasing power migrates across facility types and how regulatory stringency reshapes product form factors.
Product Type:
Customization intensity varies sharply across this category, from capital-intensive imaging platforms to commodified single-use consumables.
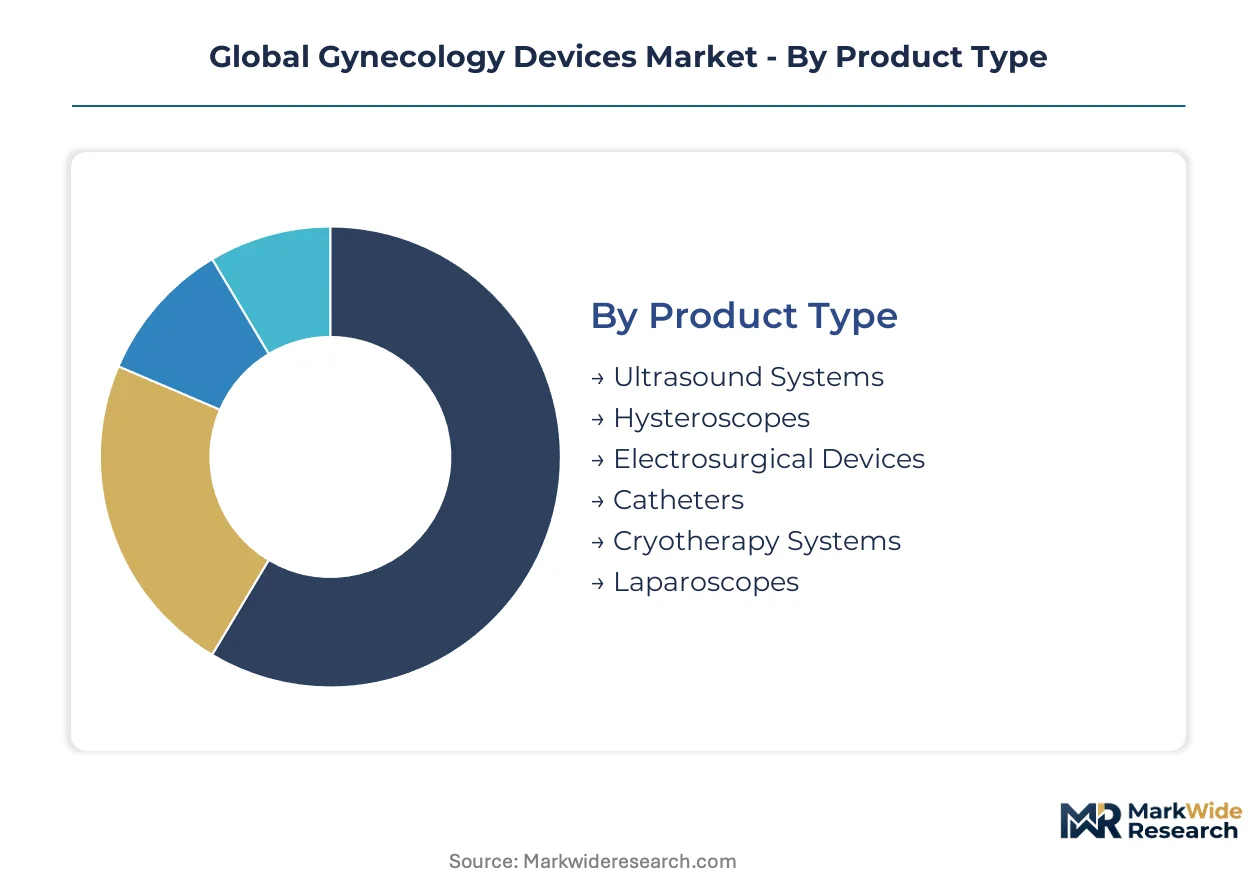
- Ultrasound Systems:Cart-based and handheld transvaginal probes with Doppler capability dominate initial diagnostic workups. Demand concentrates in fertility clinics across the United States and China as assisted reproductive technology volumes climb.
- Hysteroscopes:Rigid and flexible optical systems with 2.9mm to 4mm outer diameters enable diagnostic and operative uterine access. European hospitals are accelerating replacement cycles to meet EU MDR recertification deadlines for reusable systems.
- Electrosurgical Devices:Loop electrodes and ablation generators for endometrial resection. Fastest-expanding category as outpatient facilities convert open procedures to minimally invasive techniques.
- Catheters:Balloon and suction catheters for uterine manipulation and fluid management.
- Cryotherapy Systems:Nitrous oxide and carbon dioxide-based cervical ablation platforms for dysplasia treatment.
- Laparoscopes:Rod-lens and video laparoscopes for peritoneal cavity visualization during adnexal surgery.
Most installed capacity flows through Ultrasound Systems. Expansion is steepest in Electrosurgical Devices.
Application:
Procedure reimbursement rates and clinical evidence requirements create divergent margin profiles across therapeutic indications.
- Fertility Treatment:Ovarian stimulation monitoring, oocyte retrieval, and embryo transfer procedures drive specialized device demand. Concentrated in academic medical centers and dedicated fertility clinics in Germany and China where public and private insurance coverage for assisted reproductive technology is expanding.
- Cervical Cancer Screening:Colposcopy, biopsy, and excisional procedures for precancerous lesion management. United States outpatient migration and India's national screening programs are accelerating colposcope and cryotherapy procurement.
- Uterine Fibroids:Hysteroscopic and laparoscopic myomectomy instrumentation.
- Endometriosis:Diagnostic and excisional laparoscopy for peritoneal and deep infiltrating disease.
- Menstrual Disorders:Endometrial ablation and polypectomy systems for heavy menstrual bleeding.
- Pelvic Organ Prolapse:Mesh and native tissue repair instrumentation for apical and anterior compartment defects.
Procedure volume concentrates in Fertility Treatment. Fastest share gains are occurring in Cervical Cancer Screening.
End User:
Facility scale determines capital equipment depreciation schedules and disposable contract negotiation leverage.
- Ambulatory Surgical Centers:Freestanding facilities performing hysteroscopy, laparoscopy, and endometrial ablation without overnight admission. Texas and Florida regulatory environments have enabled rapid facility proliferation, compressing device procurement cycles toward single-use preference.
- Fertility Clinics:Specialized reproductive endocrinology practices with embedded embryology laboratories. China's provincial subsidy programs in Guangdong and Jiangsu are driving ultrasound and hysteroscope procurement.
- Academic Medical Centers:Teaching hospitals with residency training programs and research protocols.
- Specialty Clinics:Gynecology-focused practices without surgical suites.
- Diagnostic Centers:Imaging-only facilities for screening and triage.
- Private Practices:Solo and group gynecology offices with limited procedure capability.
Capital deployment concentrates in Ambulatory Surgical Centers. Steepest patient volume growth is occurring in Fertility Clinics.
Deployment:
Physical infrastructure requirements versus virtual care integration create distinct equipment specifications and reimbursement pathways.
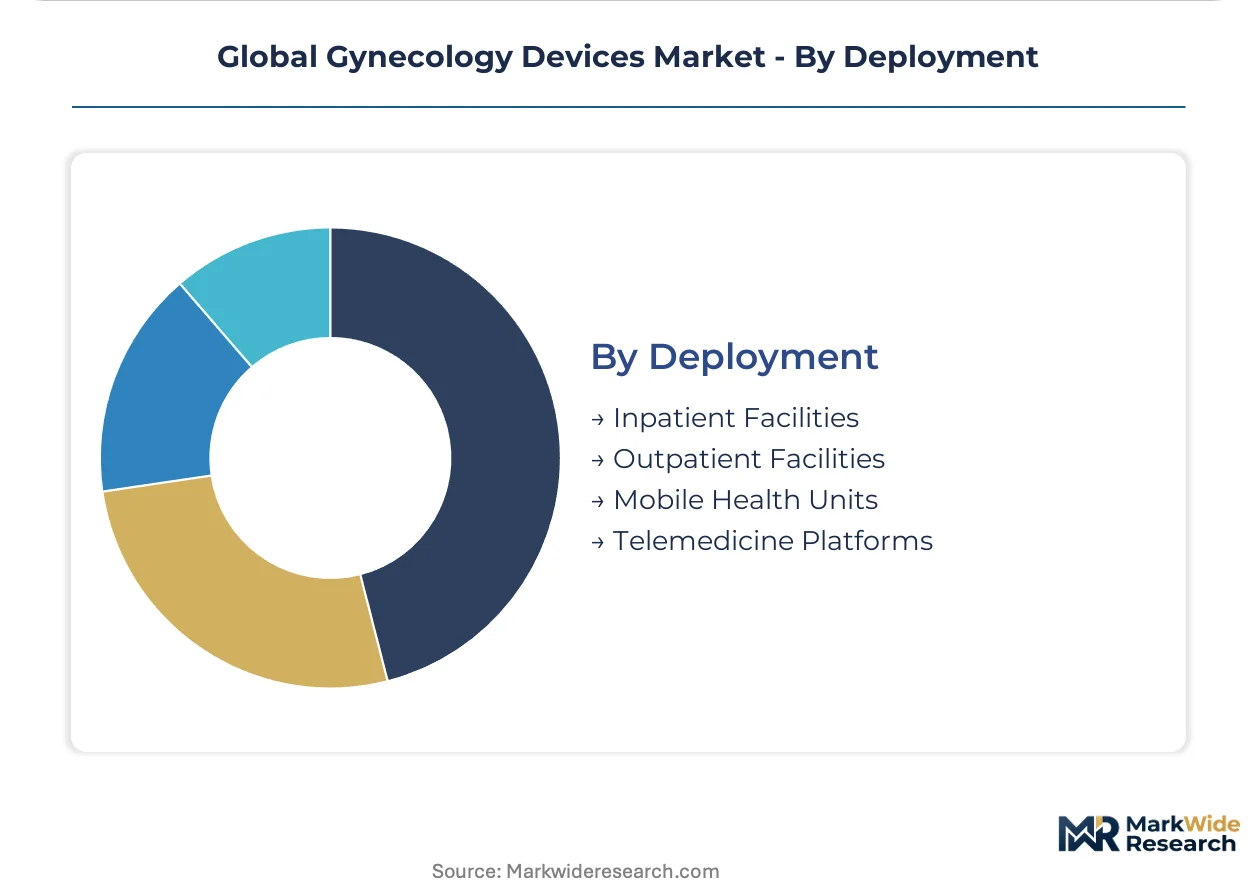
- Outpatient Facilities:Office-based hysteroscopy suites and procedure rooms with local anesthesia capability. United States migration from hospital outpatient departments to freestanding centers is reshaping service contract architectures and disposable pricing negotiations.
- Inpatient Facilities:Hospital operating rooms for complex laparotomy and advanced laparoscopy.
- Mobile Health Units:Screening vehicles for cervical cancer prevention programs in rural India and sub-Saharan Africa.
- Telemedicine Platforms:Remote consultation infrastructure with asynchronous image review for ultrasound interpretation.
Device utilization concentrates in Outpatient Facilities. Fastest infrastructure buildout is occurring in Mobile Health Units.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized reproductive endocrinologists and minimally invasive surgeons concentrate in the United States, Germany, and China, anchoring procedural volume and device procurement intensity across three distinct regulatory environments.
United States
Freestanding ambulatory surgical centers in Texas and Florida are converting hysterectomy volumes to outpatient loop excision and endometrial ablation procedures. FDA 510(k) premarket notification pathways govern electrosurgical platform clearances, with sterilization validation protocols narrowing the cost gap between reusable and single-use systems. Dallas and Houston facility clusters are driving disposable contract negotiations that bundle capital equipment with service agreements.
Germany
Academic medical centers in Baden-Württemberg and Bavaria are piloting AI-assisted hysteroscopic navigation for complex polypectomy workflows. EU MDR Article 10 recertification mandates are accelerating replacement demand for reusable hysteroscopic systems as notified bodies demand extended clinical evidence. Stuttgart and Munich teaching hospitals are consolidating procurement under single-source agreements that span imaging platforms and energy devices.
China
Provincial subsidy programs in Guangdong and Jiangsu are expanding assisted reproductive technology center infrastructure. NMPA implements distinct GB standards for electrosurgical safety and biocompatibility testing, creating parallel compliance obligations for multinational portfolios. Shanghai and Shenzhen fertility clinic clusters are driving diagnostic ultrasound and hysteroscope procurement at volumes exceeding metropolitan benchmarks.
India
Gynecological screening programs in Maharashtra and Tamil Nadu remain underpenetrated for colposcopy and cryotherapy systems relative to metropolitan benchmarks. CDSCO medical device regulations are converging toward international standards for Class B and C device registrations. Mumbai and Chennai diagnostic networks are expanding mobile health unit deployments for cervical cancer prevention in tier-two cities.
Brazil
ANVISA fast-track registration pathways for devices with prior FDA or CE approval are reducing time-to-market for established regulatory dossiers. São Paulo and Rio de Janeiro facility networks are deepening investment in outpatient hysteroscopy suites with local anesthesia capability. Southeastern state purchasing consortia are negotiating disposable contracts that displace traditional capital equipment depreciation models.
Global Gynecology Devices Market Competitive Landscape
The competitive structure tilts toward diversified medical technology conglomerates with regulatory infrastructure spanning multiple high-stringency jurisdictions. Three to five multinational corporations anchor procurement relationships with hospital purchasing consortia through bundled equipment-service-disposable agreements. Strategic archetypes include regulatory-scale specialists, diagnostic imaging platform anchors, and manufacturing-scale supply network extenders. Dominant competitive moves center on M&A for sterilization validation capabilities and strategic partnerships with ambulatory surgical center group purchasing organizations.
Among US-based diversified health technology corporations, Boston Scientific Corporation and Stryker Corporation exemplify the regulatory-scale specialist archetype, leveraging multi-market registration infrastructure to sustain CE marking and FDA clearance portfolios. Hologic, Inc. occupies a diagnostic imaging platform position, while Medtronic plc and Johnson & Johnson anchor the manufacturing-scale tier with supply network extensions serving high-volume hospital purchasing consortia. Karl Storz SE & Co. KG and Richard Wolf GmbH represent German precision instrumentation specialists, with CooperSurgical Inc. and Olympus Corporation sitting within the fertility and visualization platform segments respectively.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Hologic, Inc. |
| Medtronic plc |
| CooperSurgical Inc. |
| Karl Storz SE & Co. KG |
| Stryker Corporation |
| Johnson & Johnson |
| Olympus Corporation |
| Richard Wolf GmbH |
| Others |
Supply & Pricing Matrix
Hospital purchasing consortia in the United States anchor procurement volume for gynecology devices, compressing vendor margins through bundled equipment-service-disposable contracts that disaggregate traditional capital depreciation models.
Pricing Analysis
Bundled service agreements dominate pricing architecture for reusable hysteroscopic systems, while single-use alternatives command per-procedure transactional pricing. Price differentiation rests on CE marking tier under EU MDR and sterilization validation depth for FDA 510(k) pathways. Cost compression in standard-grade electrosurgical platforms is intensifying because German and Japanese polymer suppliers are passing through specialty chemical input volatility. Ambulatory surgical centers in Texas and Florida exhibit highest price sensitivity, whereas academic medical centers in Germany prioritize certification grade over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the United States, and China orchestrate hub-and-spoke patterns for precision instrumentation, with Stuttgart and Dallas hubs serving European and North American demand clusters respectively. Medical-grade stainless steel and polymer composites for instrument shafts draw from German and Japanese specialty chemical suppliers, creating single-source vulnerability for 4mm hysteroscope outer diameter specifications. Tariff exposure on Chinese-manufactured electrosurgical generators is elevating landed costs for United States distributors. Distribution runs through GPO-affiliated logistics networks for independent ambulatory surgical centers seeking negotiating leverage against hospital consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR recertification deadlines function as a regulatory compounder, accelerating replacement demand for legacy reusable hysteroscopic systems as notified bodies demand extended clinical evidence portfolios.
For Market Incumbents: Anticipate sterilization validation cost escalation for reusable systems under FDA 510(k) pathways, narrowing the cost gap with single-use alternatives and threatening installed base retention. Defend position through backward integration into polymer composite manufacturing to dampen input cost volatility from German and Japanese suppliers. Prioritize CE marking infrastructure investment to capture European hospital replacement cycles ahead of notified body capacity constraints. For New Entrants and Emerging Players: Launch via AI-assisted hysteroscopic navigation partnerships with academic medical centers in Baden-Württemberg and Bavaria, where operative training burdens constrain procedure throughput. Target India's tier-two city colposcopy and cryotherapy penetration gaps in Maharashtra and Tamil Nadu, where national screening programs remain underdeployed relative to metropolitan benchmarks. Pursue ANVISA fast-track registration in Brazil for devices with prior FDA or CE approval to compress time-to-market. For Investors and Strategic Acquirers: Diversified medical technology conglomerates with multi-jurisdiction regulatory infrastructure are the most active acquirers in this space, seeking sterilization validation capabilities and ambulatory surgical center GPO relationships. Long-term viability over a five-to-ten year window rests on exposure to outpatient surgical migration and disposable conversion economics. Acquisition target archetypes include precision instrumentation specialists with EU MDR technical documentation depth. Monitor notified body capacity expansion timelines as an inflection indicator for European market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR Article 10 compliance unlocks European hospital replacement demand ahead of recertification deadlines. |
| Hospital System Partnership | Single-source agreements with Texas and Florida ambulatory surgical center networks secure disposable contract volumes. |
| Software Companion Development | Machine vision algorithms for hysteroscopic navigation reduce operative time and training burdens in German teaching hospitals. |
| Reimbursement Strategy | Alignment with CMS outpatient procedure codes in the United States accelerates loop excision and endometrial ablation adoption. |
| FDA Submission | Premarket notification pathways for electrosurgical platforms govern clearance timelines and sterilization validation requirements. |
Research Methodology
Coverage spans the United States, Germany, China, India, and Brazil, with primary inputs from each market cluster combining interviews with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and fertility clinic operations directors with secondary validation. Regulatory filing databases including FDA 510(k) clearances, EMA MDR technical documentation, and NMPA GB standard submissions anchor secondary source triangulation. Bottom-up procedure volume estimates and top-down manufacturer revenue analysis converge through cross-referencing.
Rate-of-change decomposition separates volume expansion from price mix effects across the projection horizon, with segmentation modeling across product type, application, end user, and deployment dimensions. CAGRs derive from fitted growth curves applied to hysteroscope and electrosurgical device procurement trajectories, incorporating provincial subsidy program announcements in Guangdong and Jiangsu and United States ambulatory surgical center facility licensing data as industry-specific inputs.
Several conditions sit outside the modeled scope, including unforeseen EU MDR notified body capacity expansion, abrupt polymer composite supply disruptions, and regulatory reciprocity agreements that could harmonize sterilization validation protocols. Forecasts reflect assumptions about outpatient surgical migration velocity and disposable conversion economics that may shift with reimbursement policy changes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Ear Tube Devices Market
Medical Devices
Australia Artificial Organs and Bionic Implants Market
Medical Devices
Europe Clear Aligners Market
Medical Devices
Global Sacral Nerve Stimulation Market
Medical Devices
Benign Prostatic Hyperplasia (BPH) Treatment Devices Market
Medical Devices
High Viscosity Bone Cement Market
Medical Devices
UAE Artificial Organs and Bionic Implants Market
Medical Devices
Global Total Wrist Replacement Market
Medical Devices
Russia Massage Equipment Market
Medical Devices
Medical Devices Reimbursement Market
Medical Devices
Brazil Ultrasound Devices Market
Medical Devices
Occlusion Microcatheter Market
Medical Devices
Transplant Monitoring Kits Market
Medical Devices
Global Medical Exoskeleton Market
Medical Devices
Neonatal Hearing Screening Devices Market
Medical Devices
Cerebral Thrombectomy Devices Market