
 Marble Market | 2026-2036
Marble Market Size, Share, and Industry Trends Forecast 2026-2036
Marble Market Intelligence
The proliferation of digital templating and CNC cutting technology is fragmenting traditional stone fabrication workflows, enabling smaller shops to execute complex designs. This shift pressures large, vertically integrated producers to differentiate their offerings beyond raw material supply. Antolini Luigi & C Spa positions itself in the ultra-luxury segment with exclusive quarry rights for rare stones. In contrast, Polycor Inc. operates a portfolio of quarries across North America and Europe, focusing on scale and consistent supply for large architectural projects.
Marble is a metamorphic rock formed from limestone subjected to heat and pressure, composed primarily of recrystallized calcite. Its characteristic veining and swirls are caused by mineral impurities, making each slab unique. Within applications, countertops and flooring represent the largest volume segments, driven by both residential and commercial construction. While polished finishes remain the standard, demand for honed and leathered finishes is increasing in high-end interior design projects for their unique textural qualities.
Worker safety regulations, such as those from the US OSHA concerning silica dust exposure, govern fabrication processes. In Europe, CE marking for construction products mandates declaration of performance for marble used in building applications, while ISO standards define testing protocols. Quarry operators and processors must now balance resource sustainability with investments in advanced processing technologies to meet evolving aesthetic and performance demands.
Market Dynamics
The convergence of digital fabrication technologies with demands for material traceability is the central force shaping the marble market. This dynamic pressures quarry operators and processors to provide not only unique aesthetics but also verifiable data on origin and sustainability.
Growth Catalysts
- Infrastructure Investment:Major construction and hospitality projects in Gulf Cooperation Council countries, particularly the UAE and Saudi Arabia, create concentrated demand for high-grade marble for luxury hotels, airports, and public buildings.
- Digital Fabrication Adoption:The proliferation of CNC milling and waterjet cutting technology enables architects and designers to specify intricate patterns and custom shapes, expanding marble's use from simple slabs to complex decorative features.
- Luxury Residential Demand:A persistent preference for natural stone in high-end residential kitchens, bathrooms, and flooring applications, especially in North America and Europe, sustains a high-volume base for the market.
Market Restraints
- Substitution from Engineered Materials:Engineered quartz, porcelain slabs, and sintered stone offer superior performance in terms of stain and scratch resistance at competitive price points, eroding marble's share in high-traffic applications.
- Logistical Complexity:The significant weight and fragility of marble slabs result in high transportation, handling, and installation costs, which can be prohibitive for projects with tight budgets or remote locations.
- Quarrying Impact:Environmental regulations and public scrutiny over the ecological impact of quarrying, including habitat disruption and water usage, create operational hurdles and reputational risks for producers.
Strategic Opportunities
- Sustainable Certification:Developing and marketing marble collections with third-party sustainability certifications, such as those for responsible sourcing and low-impact quarrying, can attract environmentally conscious architects and clients.
- Waste Upcycling:Processors can create new revenue streams by converting quarry and fabrication waste into high-value products like terrazzo, composite panels, aggregates, or calcium carbonate powders for industrial use.
- Textural Innovation:Moving beyond polished finishes to develop and promote a wider array of textures like honed, leathered, and brushed surfaces allows producers to cater to evolving interior design aesthetics seeking subtlety and tactile quality.
Industry Challenges
- Skilled Labor Scarcity:The industry faces a shortage of skilled artisans, including stone fabricators, CNC machine programmers, and installers, who are essential for executing complex and high-quality marble installations.
- Regulatory Compliance Costs:Adhering to increasingly stringent worker safety regulations, such as OSHA standards for silica dust exposure in the US and equivalent European directives, requires significant capital investment in dust mitigation and monitoring equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Marble Market |
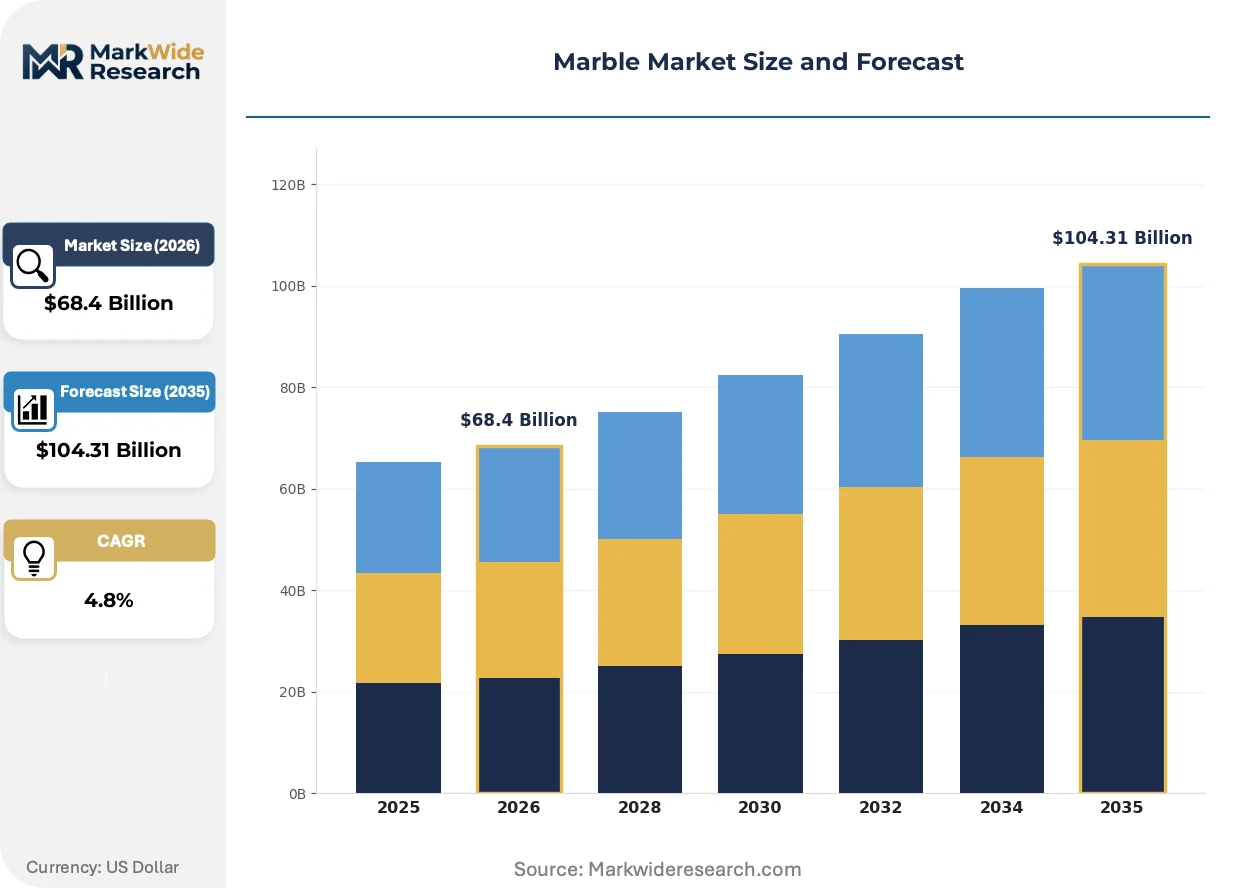
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $104.31 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Calacatta, Carrara, Crema Marfil, Breccia, Emperador, Botticino Application: Flooring, Wall Cladding, Countertops, Sculptures, Fireplace Surrounds, Staircases Finish: Polished, Honed, Tumbled, Brushed, Sandblasted, Leathered End User: Architects, Interior Designers, Construction Firms, Renovation Specialists, Fabricators, Real Estate Developers |
| Companies Covered | Dimpomar, Temmer Mermer, Levantina y Asociados de Minerales S.A., Kangli Stone Group, TOPALIDIS S.A., Polycor Inc., M S International, Inc., Fox Marble, Inc, Antolini Luigi & C Spa, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Marble Market Strategic Shifts & Innovations
Technological advancements in processing are intersecting with a growing emphasis on material authenticity and sustainability. This forces a re-evaluation of traditional workflows and product offerings, pushing the industry toward greater customization and transparency from quarry to installation.
Advanced 3D scanning and digital templating systems provide fabricators with precise, non-contact measurement capabilities. Small and mid-sized shops are rapidly adopting this technology to capture complex countertop layouts and architectural features. This evolution is rendering obsolete the manual creation of physical wood or cardboard templates, dramatically reducing material waste and shortening project lead times.
A global convergence of safety and building material standards is reshaping fabrication environments. Regulations like the US OSHA silica dust permissible exposure limit and Europe's CE marking, which requires declaration of performance for construction products, create a dual pressure. This is forcing fabricators worldwide to invest in advanced wet cutting technologies and comprehensive dust extraction systems to ensure both worker safety and market access.
Shifting aesthetic preferences among interior designers and homeowners are altering demand patterns for finishes. A distinct move away from the traditional high-gloss polish toward more subtle, low-sheen surfaces is disrupting inventory management for distributors. This trend is most visible in high-end residential projects in North America and Europe, where honed, leathered, and brushed finishes are specified for their textural depth and reduced glare.
Marble Market Segmentation
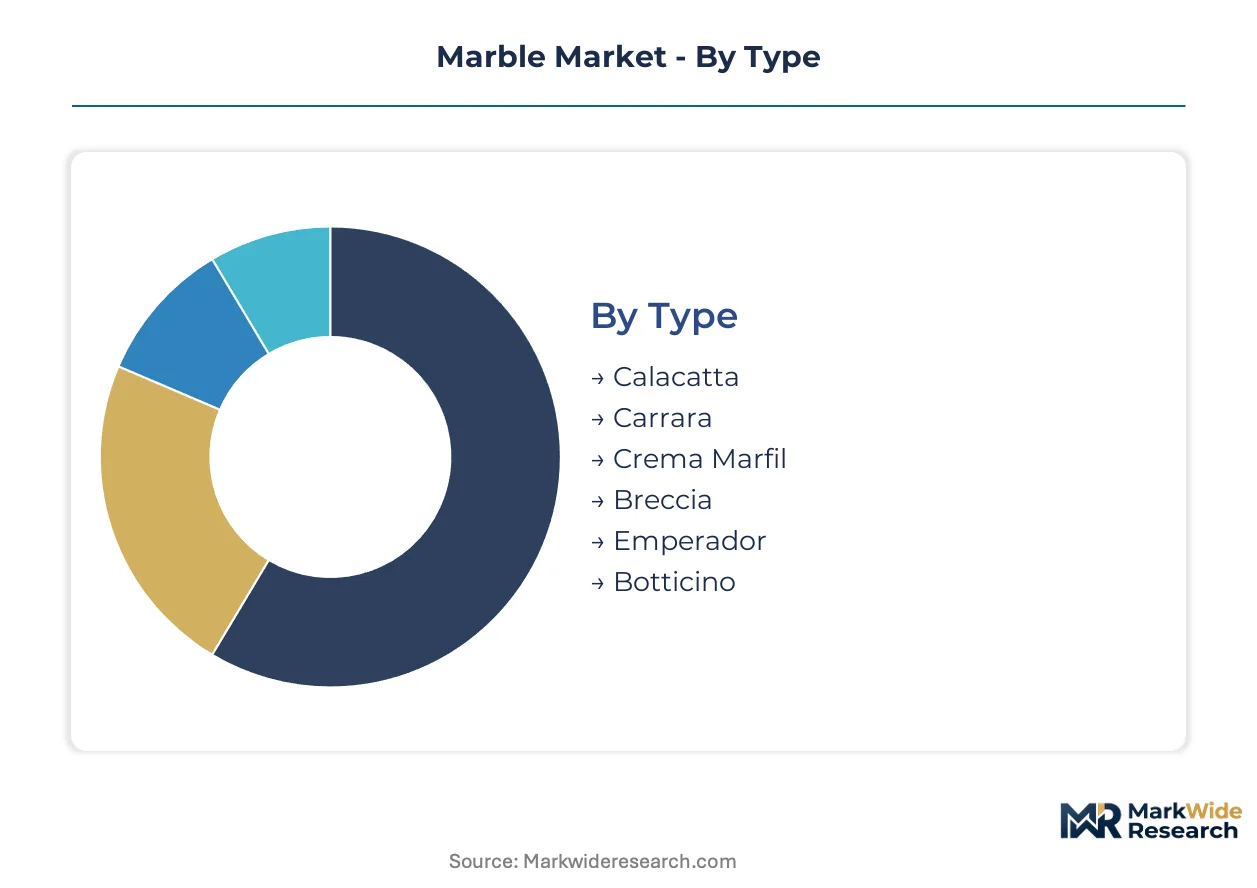
The marble market categorizes its offerings to address diverse aesthetic preferences, functional requirements, and professional stakeholder needs. Understanding these distinctions allows producers and distributors to tailor product lines and service models effectively across various construction and design projects.
Type:
The material composition of marble types dictates their aesthetic and performance characteristics, influencing their application across different project segments.
- Calacatta:This Italian marble features a brilliant white base with dramatic, thick veining in gold or gray. It commands the ultra-luxury segment for statement pieces in North American and Middle Eastern interiors.
- Carrara:Characterized by a white to gray background with soft, feathery veining, Carrara marble offers a classic aesthetic. Its consistent appeal drives demand in high-end residential and commercial projects across Europe.
- Crema Marfil:This creamy beige Spanish limestone offers a warm, neutral palette for large-scale flooring installations.
- Breccia:Known for its fragmented appearance with angular pieces of stone cemented by a finer matrix, Breccia provides a distinctive, rustic texture.
- Emperador:A dark brown marble with fine golden veins, Emperador is sourced primarily from Spain and used for opulent accents.
- Botticino:This Italian marble presents a uniform beige color with subtle light veins, offering a refined look for traditional designs.
Carrara marble holds installed capacity. Calacatta is rotating up the share rankings.
Application:
The functional utility of marble across various applications defines its volume consumption and specific market niches within the construction and design industries.
- Flooring:Marble flooring provides a durable and aesthetically rich surface for both residential and commercial spaces. High foot traffic areas in luxury hotels and public buildings in the UAE frequently specify this application.
- Countertops:Utilized extensively in kitchens and bathrooms, marble countertops offer a natural, elegant surface. High-end residential projects in North America consistently choose marble for its unique veining and classic appeal.
- Wall Cladding:Marble panels are used for interior and exterior wall finishes, particularly in architectural projects seeking a grand aesthetic.
- Sculptures:Artisans carve marble into decorative and artistic forms, leveraging its workability and inherent beauty.
- Fireplace Surrounds:Marble provides a heat-resistant and decorative frame for fireplaces, enhancing interior focal points.
- Staircases:Marble staircases offer a luxurious and durable solution for grand entrances in both private residences and public institutions.
Flooring applications drive significant volume. Countertops are gaining share fastest among high-value residential projects.
Finish:
Aesthetic preferences dictate the surface treatment of marble, influencing its visual impact and tactile qualities in diverse interior and exterior designs.
- Polished:This finish creates a high-gloss, reflective surface that enhances the stone's color and veining. Polished marble remains a standard for traditional luxury applications in Europe.
- Honed:A matte, non-reflective finish that provides a softer, more subtle appearance and is less prone to showing etching. Demand for honed surfaces is increasing in contemporary interior design projects in North America.
- Tumbled:This process creates a worn, aged look with rounded edges, popular for rustic or antique-style installations.
- Brushed:A brushed finish results in a textured, slightly rough surface, highlighting the natural grain of the stone.
- Sandblasted:Sandblasting creates a coarse, textured finish, often used for exterior applications or non-slip surfaces.
- Leathered:A leathered finish offers a soft sheen with a textured, tactile feel, gaining traction in high-end kitchen designs.
Polished finishes represent the traditional standard. Honed surfaces are experiencing a strong expansion trajectory.
End User:
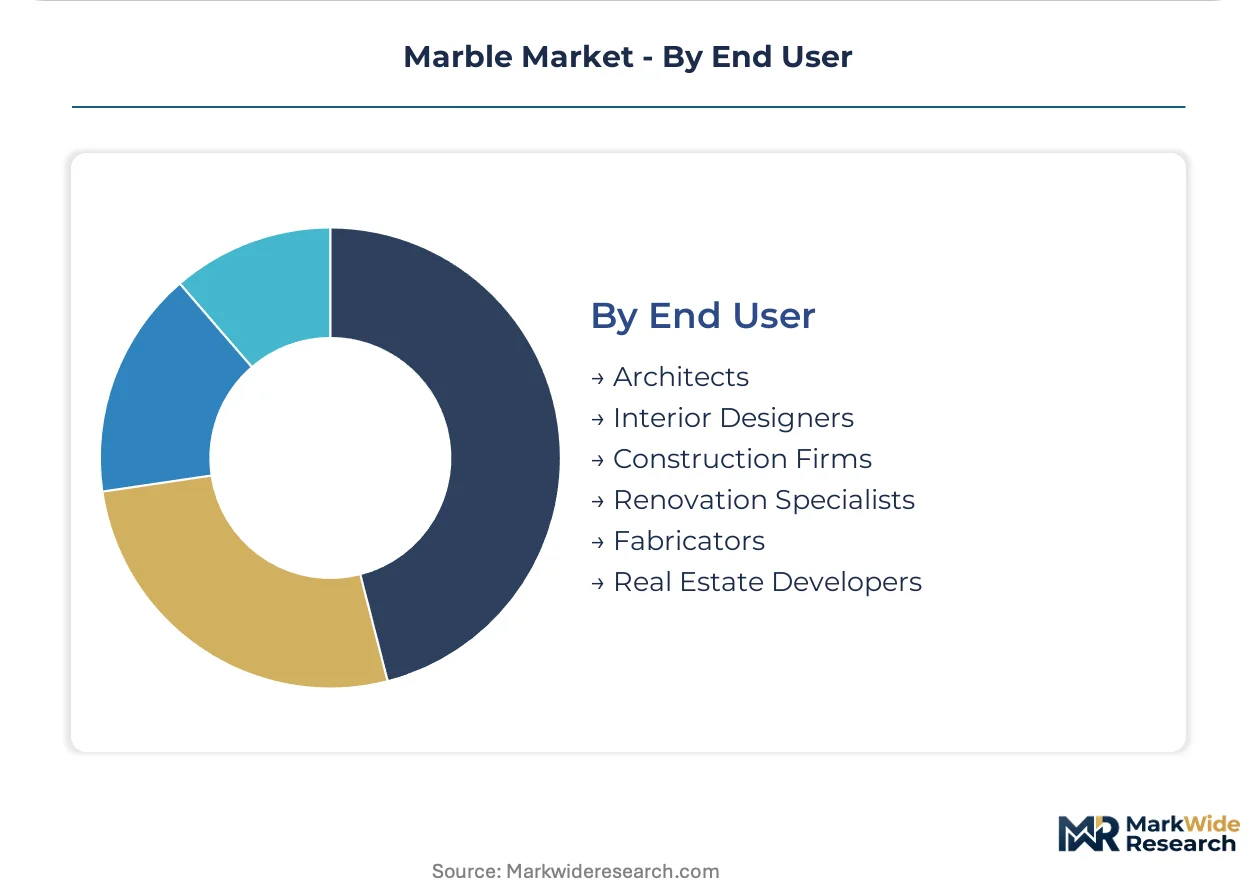
The professional stakeholders driving marble specification and procurement shape demand patterns and influence material selection criteria across the value chain.
- Construction Firms:These entities procure marble in bulk for large-scale residential, commercial, and infrastructure projects. Major construction initiatives in Saudi Arabia drive significant demand for their material sourcing and installation capabilities.
- Architects:Architects specify marble types and finishes during the design phase of luxury residential and commercial developments. Their influence shapes material selection based on aesthetic, performance, and sustainability criteria.
- Interior Designers:These professionals select marble for specific aesthetic outcomes within high-end residential and hospitality interiors.
- Renovation Specialists:Focused on upgrading existing properties, renovation specialists integrate marble into kitchens, bathrooms, and living spaces.
- Fabricators:Fabricators cut, shape, and finish marble slabs into custom products like countertops and wall panels for various clients.
- Real Estate Developers:Developers integrate marble into their property designs to enhance perceived value and attract premium buyers.
Construction firms dictate bulk procurement. Architects are increasingly influential in specifying premium and sustainable marble solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-end residential and luxury hospitality buyers concentrate demand for premium marble across specific global hubs. These discerning consumers drive significant volume in construction and interior design projects. Material traceability and sustainable sourcing are becoming increasingly important for these markets.
United Arab Emirates
Major construction projects in Dubai and Abu Dhabi create concentrated demand for high-grade marble. The Ministry of Energy and Infrastructure supports sustainable building practices across the Emirates. Luxury hotels and public buildings in Dubai drive substantial procurement for grand aesthetic applications.
Italy
Italian marble maintains a strong position in the global luxury market due to its renowned quality. CE marking regulations ensure performance declarations for construction products, including Italian marble. The Carrara region remains a primary source, supplying distinctive white marble to global markets.
United States
Luxury residential demand for natural stone sustains a high-volume base in North America. OSHA regulations govern worker safety, particularly concerning silica dust exposure in fabrication facilities. High-end residential projects in major metropolitan areas like New York and Los Angeles consistently specify unique marble designs.
Saudi Arabia
Infrastructure investment for Vision 2030 projects generates significant demand for premium marble. The Saudi Standards, Metrology and Quality Organization (SASO) sets quality standards for imported building materials. NEOM and Riyadh are major development hubs, driving large-scale marble procurement for new cities and hospitality venues.
Germany
Commercial and high-end residential construction projects in Germany utilize diverse marble types. European directives like the Construction Products Regulation (CPR) mandate performance declarations for marble. Major cities such as Berlin and Munich feature numerous architectural projects incorporating natural stone finishes.
Marble Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in the marble industry. The market structure exhibits fragmentation, with numerous small and medium-sized enterprises alongside a few larger, integrated producers. Strategic archetypes include quarry-owning material suppliers, specialized fabricators, and global distributors. Companies often pursue geographic expansion into high-growth regions and portfolio diversification into value-added finishes to enhance their market reach.
On the premium-tier vector, Antolini Luigi & C Spa exemplifies a focus on exclusive quarry rights and rare stone offerings, targeting the ultra-luxury segment. Polycor Inc. represents a scale-driven approach, operating a portfolio of quarries across North America and Europe to ensure consistent supply for large architectural projects. Levantina y Asociados de Minerales S.A., a Spanish company, occupies a position emphasizing diverse material sourcing and global distribution capabilities, catering to various project types. These entities collectively shape the competitive dynamics through their distinct operational models, influencing material availability and aesthetic trends.
| Leading Market Players |
|---|
| Dimpomar |
| Temmer Mermer |
| Levantina y Asociados de Minerales S.A. |
| Kangli Stone Group |
| TOPALIDIS S.A. |
| Polycor Inc. |
| M S International, Inc. |
| Fox Marble, Inc |
| Antolini Luigi & C Spa |
| Others |
Cost & Logistics Intelligence
Marble quarry undercapacity in Italy and Spain drives supplier behavior, influencing material availability and pricing posture for premium segments. This dynamic creates a competitive environment where access to resources directly impacts market position and profitability across the value chain.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material extraction and processing costs, define pricing within the marble market. Project-based procurement for large architectural installations frequently utilizes long-term offtake agreements. Price differentiation stems from the quality grade, with Calacatta commanding premiums over Carrara, and the level of customization achieved through advanced CNC milling. Pricing softness stems from substitution pressure from engineered materials, particularly in high-traffic applications. Construction firms, managing large project budgets, exhibit the most price sensitivity, while ultra-luxury residential clients prioritize unique aesthetics over cost.
Supply Chain Analysis
Export-control regimes for certain rare earth minerals or advanced processing technologies do not directly impact marble, but logistical challenges limit material flows. Geographic supply concentrates in Italy, Spain, and Turkey, which are primary sources for high-grade marble blocks. The supply chain draws from quarry blocks as raw material and requires specialized processing chemicals for finishes. A significant structural risk is logistics chokepoints due to the considerable weight and fragility of marble slabs, leading to high transportation and handling costs. Downstream distribution runs through a network of global distributors and specialized fabricators serving diverse end-user segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The marble market presents a defensive moat story, primarily due to the high switching costs associated with established architectural specifications and the inherent uniqueness of natural stone. This structural advantage protects incumbent positions.
For Market Incumbents:Insulate core business by securing exclusive quarry rights for rare and distinctive stone varieties, mirroring Antolini Luigi & C Spa's strategy. Invest in advanced processing technologies like multi-axis CNC milling to offer intricate designs and differentiate from substitution from engineered materials. Pursue third-party sustainability certifications for responsible sourcing, strengthening brand reputation and meeting evolving client demands. Focus on developing a portfolio of unique textural finishes beyond traditional polish.
For New Entrants and Emerging Players:Pursue niche opportunities in high-end residential projects in North America and Europe by specializing in unique finishes like honed or leathered marble. Target waste upcycling ventures, converting quarry and fabrication byproducts into high-value items such as terrazzo or calcium carbonate powders. A viable go-to-market angle involves partnering with architecture and interior design firms that prioritize custom digital fabrication, leveraging smaller-scale, agile operations. Emphasize sustainable sourcing and transparency in material origin.
For Investors and Strategic Acquirers:Capital-intensity ratios are inflecting in an upward direction across the processing and fabrication segments due to technology and regulatory investments. The market exhibits long-term viability, anchored by persistent demand for natural stone aesthetics in luxury sectors. Acquisition targets should include specialized fabricators with advanced digital capabilities or quarry operators possessing sustainability certifications. The signal to watch is the increasing stringency of regulatory compliance costs, such as OSHA standards for silica dust, which could drive consolidation among smaller, undercapitalized players.
| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Quarry Rights Acquisition | Secures unique material access for ultra-luxury segments, differentiating offerings from mass-market producers. |
| Digital Fabrication Technology Integration | Enhances customization capabilities for architects, reducing waste and accelerating project timelines. |
| Sustainable Sourcing Certification Program | Attracts environmentally conscious clients and meets evolving regulatory demands from the EU. |
| Waste-to-Product Upcycling Ventures | Creates new revenue streams from quarry byproducts, mitigating environmental impact and material costs. |
| Skilled Artisan Training Initiatives | Addresses labor scarcity in fabrication, ensuring high-quality execution for intricate marble installations. |
Research Approach
Desk research of industry association reports, construction project databases, and regulatory body publications preceded structured interviews with architects, interior designers, construction firm procurement leads, and stone fabricators. This primary and secondary research approach ensured a comprehensive understanding of market dynamics. The data was then subjected to bottom-up and top-down triangulation to validate findings and refine market sizing estimates.
The forecast framework incorporated a set of assumptions regarding global economic growth and construction investment, held fixed across the analysis window. Segmentation dimensions modeled included marble type, application, finish, end user, and regional demand hubs like the UAE. Compound annual growth rates were derived from historical trends and projected market dynamics, factoring in the adoption rates of digital fabrication technologies and infrastructure investment levels.
Sensitivities concentrate around global economic downturns, unforeseen regulatory changes, and shifts in material preference among designers. Forecasts reflect these assumptions, acknowledging potential deviations from baseline projections. Material shifts in geopolitical instability affecting key quarrying regions would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
India Manufacturing Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
Global Shotcrete/Sprayed Concrete Market
Building & Construction Materials
Poland Ceramic Tiles Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
APAC Commercial Glazing System Market
Building & Construction Materials
Geofoam Market
Building & Construction Materials
Runway Pavement Grade Asphalt Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
USA and Canada Pre-Painted Steel Roofing and Cladding Market
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
India UPVC Doors and Windows Market
Building & Construction Materials
Building Downpipe Market
Building & Construction Materials
Global Fire-Rated Medium Density Fiberboard Market
Building & Construction Materials
Vegetal Concrete Market