
 Vegetal Concrete Market | 2026-2036
Vegetal Concrete Market Size, Share, and Industry Trends Forecast 2026-2036
Vegetal Concrete Market Analytics
Skilled horticultural-concrete applicators is bifurcating the competitive landscape between premium project specialists and commodity suppliers. CEMEX leverages its ready-mix distribution network to pre-qualify vegetal concrete crews across North American markets. HeidelbergCement anchors European supply through captive biogenic aggregate sourcing from its limestone operations. ECOncrete differentiates via marine-grade vegetal formulations that tolerate salt-laden coastal environments.
Vegetal concrete refers to cementitious or geopolymer matrices impregnated with plant seeds, nutrients, and hydro-retentive fibers that germinate post-installation to form living structural surfaces, typically achieving compressive strengths of 15-35 MPa while supporting root penetration. The material serves dual functions as load-bearing infrastructure and active ecological habitat, reducing urban heat island effects while sequestering atmospheric carbon through photosynthesis. Pre-fabricated panels dominate current volume due to factory-controlled curing conditions that stabilize germination rates, though in-situ concrete commands premium pricing for bespoke architectural geometries. Green roof systems represent the fastest-expanding application segment as municipalities rewrite stormwater codes to mandate permeable coverage ratios.
The EU Green Deal and F-Gas Regulation indirectly propel vegetal concrete adoption by penalizing high-embodied-carbon alternatives, while EPA stormwater rules in the United States create compliance-driven demand for permeable vegetal surfaces. ISO 14040 life-cycle assessment frameworks increasingly govern procurement tenders, forcing manufacturers to document cradle-to-gate carbon footprints. Stakeholders must weigh biogenic substrate standardization against project-specific botanical performance guarantees when specifying systems for long-term maintenance contracts.
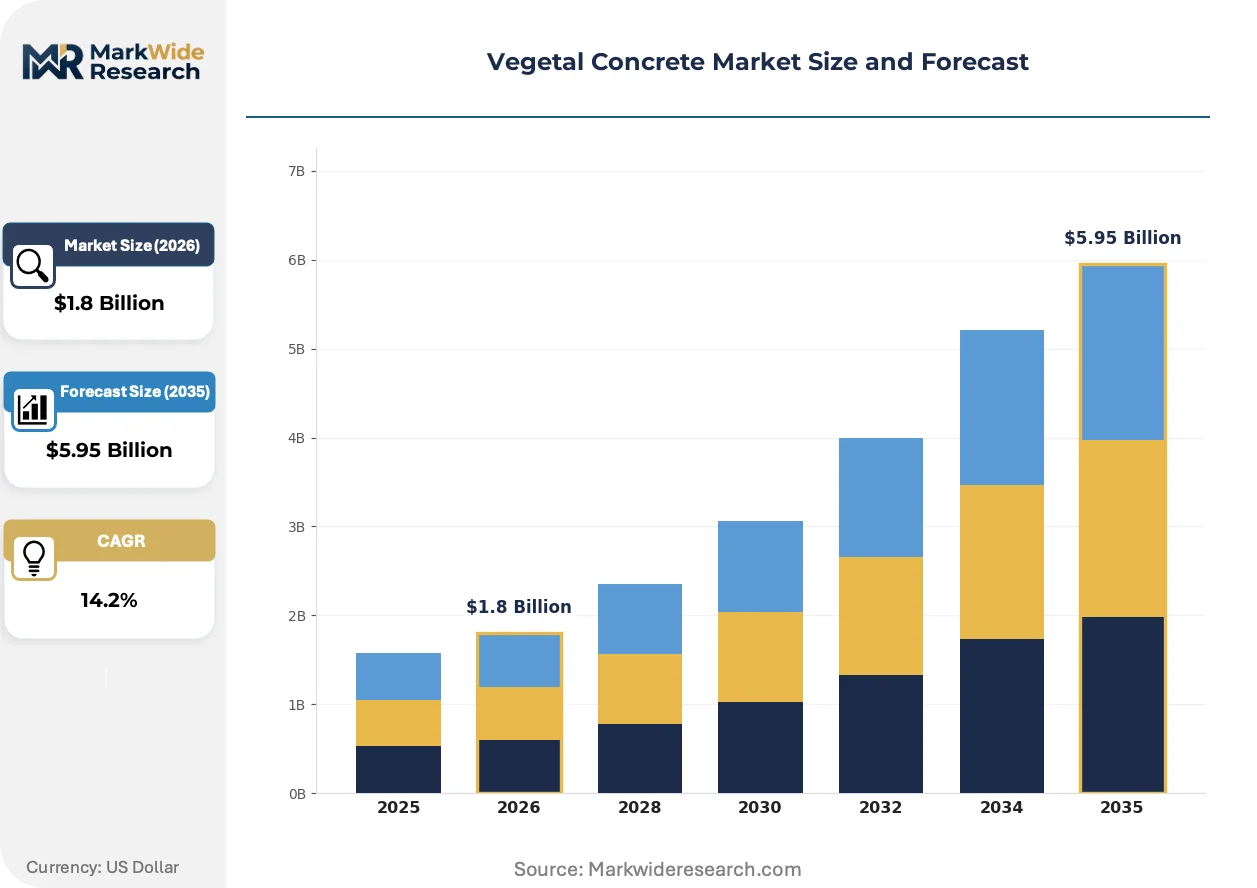
Market Dynamics
EU Green Deal embodied carbon thresholds are forcing construction procurement toward biogenic cementitious systems, compressing specification timelines as municipal green infrastructure mandates harden across member states.
Growth Catalysts
- EU Green Deal thresholds:Penalties on high-embodied-carbon alternatives redirect public building specifications toward vegetal concrete facades and living walls.
- German municipal mandates:Stormwater code rewrites now require permeable coverage ratios on new public buildings, accelerating green roof system procurement.
- ISO 14040 LCA frameworks:Cradle-to-gate carbon documentation requirements increasingly govern tender evaluations, advantaging manufacturers with verified biogenic substrate data.
Market Restraints
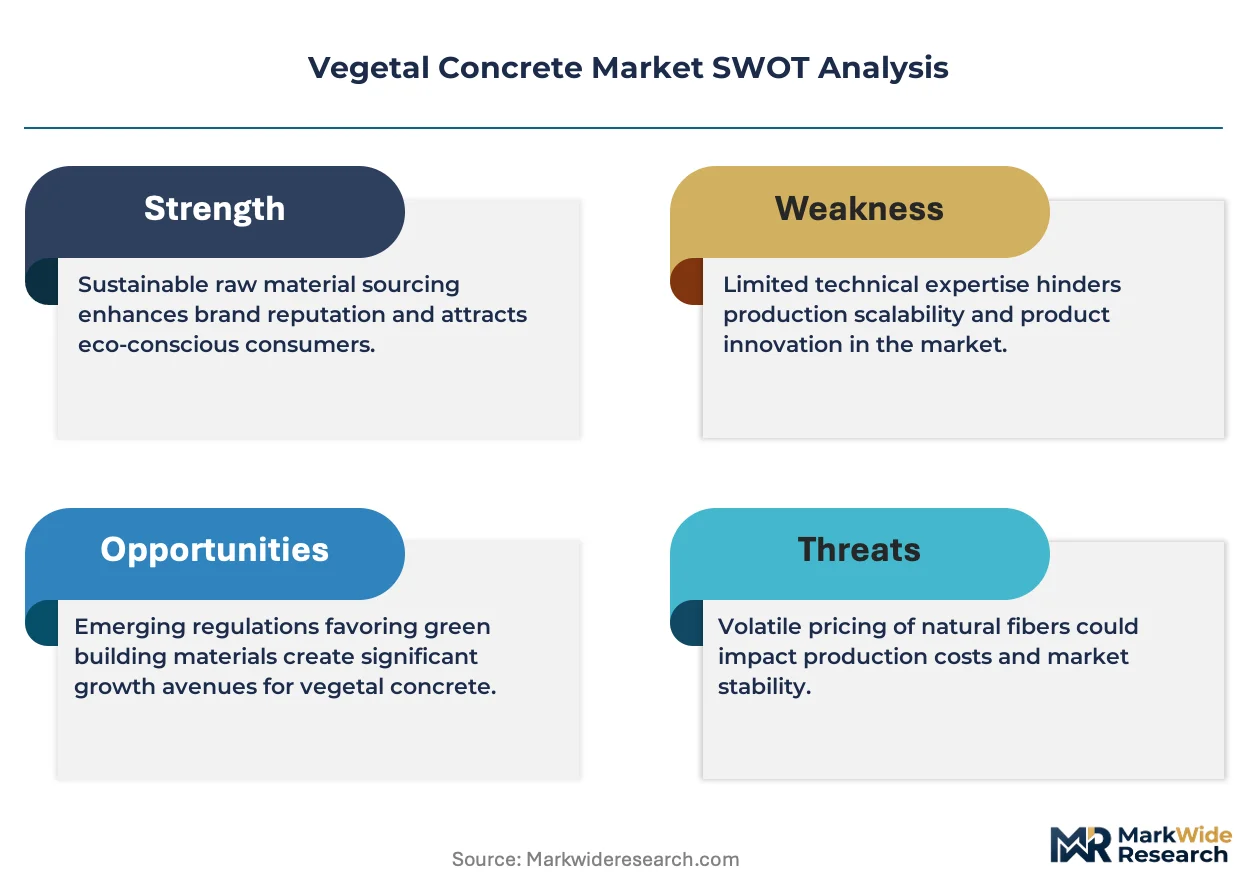
- Biogenic aggregate supply concentration:Limestone-dependent captive sourcing in Central Europe creates vulnerability to quarry permitting delays and transport cost spikes.
- Hydro-retentive fiber cost volatility:Cellulose and bio-polymer feedstock prices fluctuate with agricultural commodity cycles, compressing margin predictability for panel fabricators.
- Technical limitation in freeze-thaw zones:Root penetration pathways compromise matrix integrity below minus 15 degrees Celsius, excluding Nordic and Alpine applications without thermal barrier retrofits.
Strategic Opportunities
- Underpenetrated coastal markets:Salt-tolerant marine-grade formulations open specification in Mediterranean and Atlantic port cities where conventional vegetal systems fail.
- Convergence with digital twin platforms:Real-time moisture and germination monitoring via embedded sensors enables predictive maintenance contracts and performance guarantees.
- US EPA stormwater rule expansion:Federal compliance-driven demand for permeable surfaces creates entry path for pre-fabricated panel suppliers in Great Lakes and Chesapeake watersheds.
Industry Challenges
- Horticultural-concrete applicator scarcity:Skilled crews capable of balancing structural placement with botanical establishment protocols remain concentrated in France and Germany, constraining project scaling.
- Biogenic substrate standardization delays:Absence of unified seed germination rate and nutrient load specifications forces project-by-project performance negotiation, extending pre-construction timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vegetal Concrete Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-fabricated Panels, In-situ Concrete, Modular Blocks, Green Roof Systems Application: Building Facades, Urban Landscaping, Noise Barriers, Retaining Walls End User: Architects, Construction Companies, Municipalities, Landscaping Firms Distribution Channel: Direct Sales, Online Retail, Distributors, Contractors |
| Companies Covered | Taiheiyo Cement Corporation, China National Building Material, CEMEX, Solidia Technologies, Taiwan Cement Corporation, HeidelbergCement, Votorantim Cimentos, ECOncrete, LafargeHolcim, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vegetal Concrete Market Evolving Landscape
Specification workflows are compressing as digital tools merge with living material performance tracking, while regulatory carbon accounting hardens material selection criteria across procurement tiers.
Self-healing geopolymer matrices impregnated with dormant bacterial cultures and mineral precursors are decomposing traditional maintenance cycles for cracked vegetal concrete surfaces. Infrastructure asset managers in Dutch and Belgian canal zones are piloting these systems for revetment walls subject to cyclic wet-dry stress. The technology is decomposing the conventional separation between structural repair contracts and horticultural maintenance agreements, forcing integrated service bundling.
EU F-Gas Regulation phase-down schedules are indirectly accelerating vegetal concrete specification by penalizing synthetic refrigerant-dependent alternatives in building envelope systems. Industrial consequence flows through MEP contractor material substitution decisions on mixed-use developments. French and Spanish commercial developers most affected are pre-qualifying vegetal facade suppliers ahead of 2027 compliance checkpoints.
Performance-based maintenance contracting is displacing fixed-scope horticultural service agreements for large-format living wall installations. Facility management providers in London and Milan are absorbing botanical risk through guaranteed biomass coverage clauses tied to remote monitoring data. This shift concentrates vendor selection on suppliers with captive substrate laboratories and climate-controlled germination facilities rather than installation-only crews.
Vegetal Concrete Market Segmentation
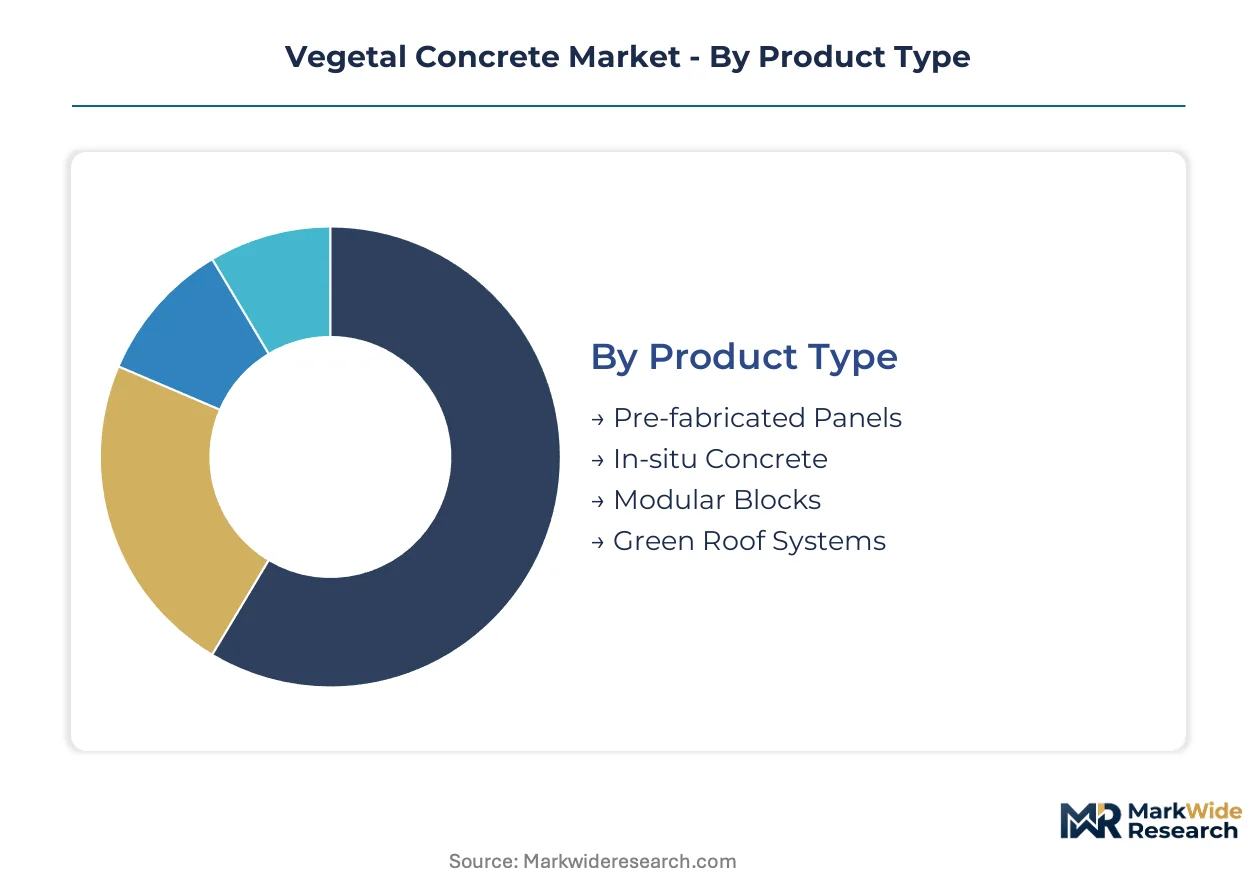
Segmentation in vegetal concrete markets reveals divergent margin structures between standardized pre-fabricated systems and high-touch in-situ applications. Understanding where value pools concentrate helps suppliers align R&D investment with procurement workflows that dominate specification decisions.
Product Type:
Margin pools concentrate in factory-controlled curing environments where germination rate guarantees command pricing premiums over field-poured alternatives.
- Pre-fabricated Panels:Cementitious matrices cured under climate-controlled conditions achieve stabilized seed germination rates of 85-95%. Demand clusters in German municipal green infrastructure projects where EU Green Deal embodied carbon documentation requirements favor factory-verified LCA data.
- In-situ Concrete:Bespoke architectural geometries poured on-site accommodate complex curved facades and integrated water management features. French commercial developers leverage this format for flagship projects where living wall aesthetics drive leasing premiums in Paris and Lyon office markets.
- Modular Blocks:Interlocking units enable rapid assembly of freestanding vegetal structures without specialized horticultural-concrete crews.
- Green Roof Systems:Pre-assembled drainage and substrate layers reduce installation complexity for stormwater compliance mandates.
The dominant share belongs to pre-fabricated panels, while in-situ concrete is closing the gap fastest through premium positioning in signature architectural commissions.
Application:
Volume concentration tracks regulatory enforcement intensity, with building envelope applications capturing disproportionate specification activity under tightening carbon accounting rules.
- Building Facades:Load-bearing vegetal surfaces integrate thermal mass with active photosynthetic carbon sequestration. French construction companies are accelerating procurement as the EU Green Deal tightens embodied carbon thresholds for public building tenders.
- Urban Landscaping:Street furniture and plaza installations deploy vegetal concrete for permeable surfacing that reduces urban heat island effects. Demand concentrates in German cities where municipal mandates require living wall integration on new public buildings.
- Noise Barriers:Highway and rail corridor installations combine acoustic dampening with ecological habitat creation.
- Retaining Walls:Slope stabilization structures leverage root penetration for soil reinforcement in civil engineering applications.
Building facades command the largest application share, though urban landscaping is expanding most quickly as stormwater code rewrites proliferate across EU member states.
End User:
Procurement authority fragmentation creates tiered service requirements, with municipalities demanding extended performance guarantees that strain smaller installation crews.
- Architects:Specification gatekeepers prioritize aesthetic integration and long-term biomass coverage warranties. London and Milan facility management providers now absorb botanical risk through guaranteed performance clauses tied to remote monitoring data.
- Construction Companies:Volume purchasers negotiate pre-qualified vegetal concrete crew networks to compress project timelines. CEMEX leverages its ready-mix distribution infrastructure to certify installation capacity across North American markets.
- Municipalities:Public procurement entities mandate ISO 14040-compliant cradle-to-gate carbon documentation.
- Landscaping Firms:Maintenance-focused operators seek standardized substrate specifications to reduce project-by-project negotiation overhead.
Construction companies hold the dominant procurement volume, while municipalities are climbing the fastest as green infrastructure mandates harden across member states.
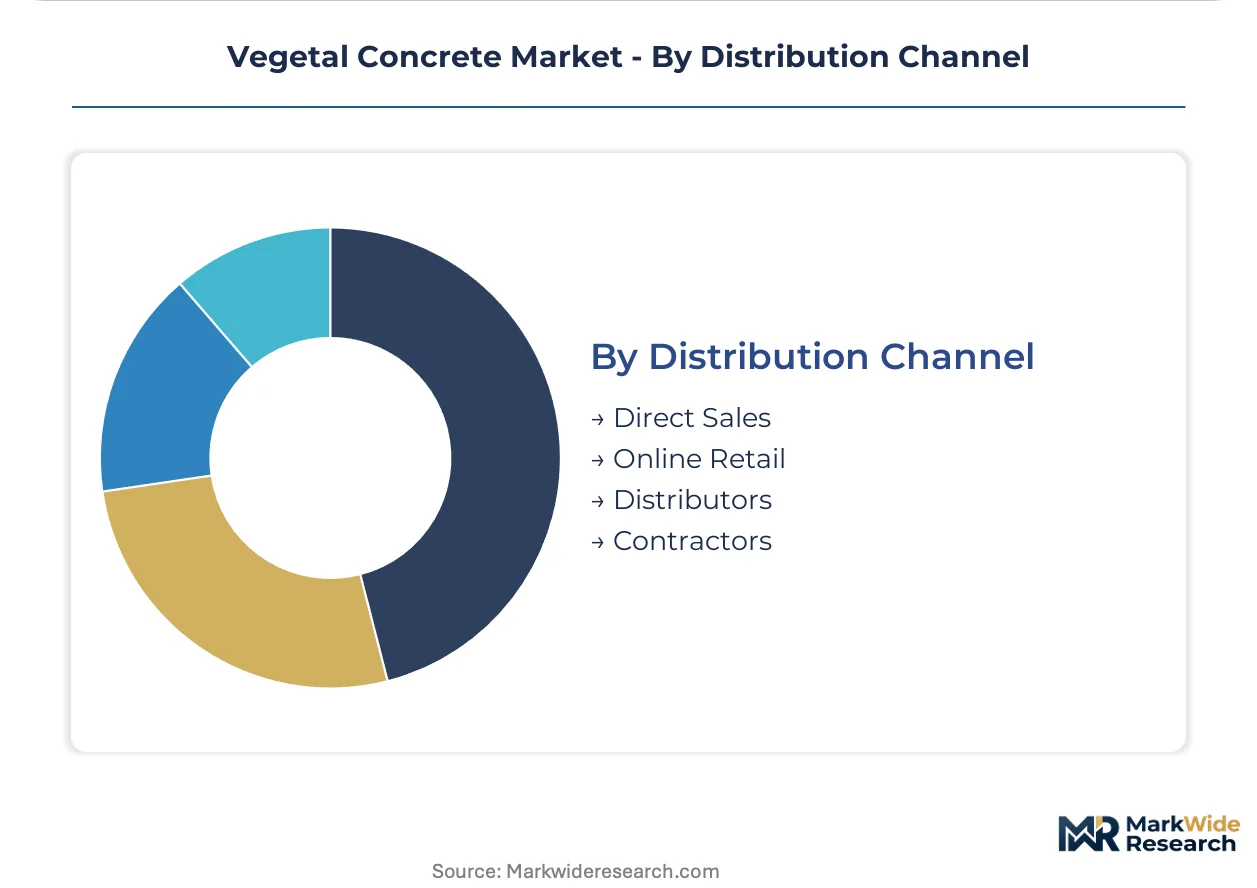
Distribution Channel:
Channel selection reflects project scale and technical complexity, with direct relationships capturing high-value contracts requiring integrated design support.
- Direct Sales:Manufacturer-to-contractor relationships enable custom substrate formulation and germination protocol alignment. ECOncrete deploys this channel for marine-grade vegetal formulations requiring salt-tolerance verification.
- Contractors:Turnkey installation providers bundle material supply with horticultural establishment services. HeidelbergCement anchors European supply through captive biogenic aggregate sourcing from its limestone operations.
- Distributors:Regional inventory stocking reduces lead times for standardized panel formats.
- Online Retail:Digital platforms serve small-format residential and commercial landscaping projects with limited technical support.
Direct sales maintains the dominant channel position, while contractor-led bundling is gaining share fastest as performance-based maintenance contracts displace fixed-scope service agreements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal anchors European demand through embodied carbon thresholds that redirect public procurement toward biogenic cementitious systems. Municipal mandates in Germany and France are compressing specification timelines as green infrastructure requirements harden.
Germany
Municipal stormwater codes now mandate permeable coverage ratios on new public buildings, accelerating green roof system procurement. The country's national building regulator enforces strict LCA documentation under EU Green Deal frameworks. Berlin and Hamburg construction clusters concentrate specification activity for living wall integration on municipal projects.
France
Commercial developers in Paris and Lyon leverage vegetal facades for leasing premiums on flagship office projects. The EU F-Gas Regulation phase-down penalizes synthetic refrigerant-dependent alternatives, redirecting envelope specifications. Construction companies accelerate procurement as embodied carbon thresholds tighten for public building tenders.
United States
EPA stormwater rules create compliance-driven demand for permeable vegetal surfaces in Great Lakes and Chesapeake watersheds. The federal environmental regulator mandates runoff reduction targets that favor living infrastructure. Chicago and Milwaukee municipal clusters pilot green roof mandates on commercial developments.
Netherlands
Canal zone infrastructure managers pilot self-healing geopolymer matrices for revetment walls under cyclic wet-dry stress. The country's national environmental agency supports biogenic material substitution in hydraulic engineering. Rotterdam and Amsterdam port authorities specify marine-grade formulations for salt-laden coastal applications.
United Kingdom
London facility management providers absorb botanical risk through guaranteed biomass coverage clauses tied to remote monitoring data. The national building standards body references ISO 14040 frameworks for cradle-to-gate carbon documentation. Manchester and Birmingham commercial districts concentrate performance-based maintenance contracting for large-format living walls.
Vegetal Concrete Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the vegetal concrete value chain. The market structure consolidates around cement majors with captive biogenic aggregate sourcing and specialized innovators with substrate formulation expertise. Three archetypes dominate: multinational cement groups leveraging ready-mix distribution networks, regional specialists with climate-controlled germination facilities, and marine-grade formulators targeting salt-tolerant coastal applications. Competitive moves concentrate on backward integration into limestone quarry operations and pre-qualification of horticultural-concrete installation crews.
Among Asia-Pacific cement groups, Taiheiyo Cement Corporation and China National Building Material occupy positions within the scale-driven tier, representing archetypes that anchor supply through integrated raw material control. ECOncrete exemplifies the specialization vector, sitting within the marine-grade formulation segment where salt-tolerance verification commands specification premiums in port city developments.
| Leading Market Players |
|---|
| Taiheiyo Cement Corporation |
| China National Building Material |
| CEMEX |
| Solidia Technologies |
| Taiwan Cement Corporation |
| HeidelbergCement |
| Votorantim Cimentos |
| ECOncrete |
| LafargeHolcim |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between municipal procurement entities and pre-fabricated panel fabricators lock in biogenic aggregate supply access while stabilizing germination-rate-guaranteed pricing visibility across EU Green Deal compliance windows. These contracts concentrate pricing power with manufacturers operating climate-controlled curing facilities in Germany and France, compressing margin flexibility for field-poured competitors facing hydro-retentive fiber cost volatility.
Pricing Analysis
Price spreads between German factory-cured panels and French in-situ applications reflect divergent cost structures tied to germination protocol standardization. Three-tier pricing structure across premium, standard, and economy levels segments by ISO 14040 LCA documentation completeness and thermal barrier retrofit inclusion. Pricing pressure stems from cellulose fiber feedstock volatility linked to agricultural commodity cycles. Municipalities demonstrate highest price sensitivity due to extended performance guarantee requirements, while flagship commercial developers in Paris absorb premiums for bespoke architectural geometries.
Supply Chain Analysis
Port congestion along Rotterdam-Antwerp container corridors elevates inbound logistics costs for hydro-retentive fiber imports originating from Nordic pulp operations. Supply concentrates in Germany, France, and the Netherlands, where limestone-dependent captive sourcing anchors biogenic aggregate availability. Raw material dependencies center on cellulose fibers, mineral nutrient blends, and dormant seed matrices. Single-source vulnerability characterizes Central European quarry networks subject to permitting delays. Distribution runs through direct manufacturer-to-contractor relationships for complex facade specifications, with regional distributors stocking standardized panel formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vegetal concrete market is emerging from a cyclical trough as EU Green Deal embodied carbon enforcement accelerates municipal procurement timelines, compressing the traditional lag between regulatory announcement and specification conversion.
For Market Incumbents: Consolidate horticultural-concrete applicator networks through certified training partnerships, preempting crew scarcity bottlenecks that constrain project scaling. Deepen backward integration into limestone quarry operations to insulate biogenic aggregate supply from permitting volatility. CEMEX and HeidelbergCement archetypes should prioritize captive substrate laboratory investments to defend margin position against specialized marine-grade formulators. For New Entrants and Emerging Players: Predictive maintenance service bundling represents an under-served layer where incumbent cement majors lack embedded sensor integration capabilities. Mediterranean and Atlantic port cities offer the most penetrable geography given salt-tolerance verification gaps in conventional formulations. A go-to-market angle targeting facility management providers with guaranteed biomass coverage clauses bypasses direct competition with established installation crews. For Investors and Strategic Acquirers: Capital is best deployed toward regional specialists with climate-controlled germination facilities and verified ISO 14040 LCA datasets, positioning for long-term viability as procurement tender documentation requirements harden. Acquisition targets should demonstrate captive substrate formulation expertise rather than installation-only capabilities. The signal to watch is municipal stormwater code adoption velocity across secondary EU cities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Quarries | Captive biogenic aggregate sourcing insulates HeidelbergCement archetypes from transport cost spikes and permitting delays. |
| Marine-Grade Formulation Development | Salt-tolerance verification opens specification in Rotterdam and Barcelona port zones where conventional systems degrade. |
| Embedded Sensor Platform Integration | Real-time moisture monitoring enables predictive maintenance contracts that absorb botanical risk for London facility managers. |
| Horticultural-Concrete Crew Certification | Pre-qualified installation networks compress project timelines for CEMEX distribution partners across North American markets. |
| ISO 14040 LCA Dataset Investment | Verified cradle-to-gate carbon documentation governs tender evaluations under EU Green Deal procurement frameworks. |
Research Methodology
The analysis maps pre-fabricated panels, in-situ concrete, modular blocks, and green roof systems, each validated through primary interviews with concrete plant managers, municipal procurement officers, horticultural-concrete applicators, and facility management providers. Secondary validation draws from EU Green Deal regulatory filings, ISO 14040 framework documentation, EPA stormwater rule dockets, and national building regulator guidance. Bottom-up volume estimates triangulate against top-down construction spend allocation models across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs across product type, application, end user, and distribution channel segmentation dimensions. CAGRs were derived from regression analysis of historical procurement patterns and regulatory enforcement intensity curves. Industry-specific forecast inputs include municipal green infrastructure mandate adoption trajectories and hydro-retentive fiber feedstock price elasticity assumptions.
Material uncertainties — quarry permitting delays, agricultural commodity cycle swings, and freeze-thaw zone technical limitations — sit outside the modeled envelope. Forecasts reflect assumptions about EU Green Deal implementation velocity and EPA stormwater rule expansion timing. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
Global Formwork Market
Building & Construction Materials
Roofing Underlay Market
Building & Construction Materials
External Wall Insulation Board Market
Building & Construction Materials
Global Drywall Textures Market
Building & Construction Materials
Granite Flooring Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
Moisture Resistant Plaster Boards Market
Building & Construction Materials
Waterproofing Systems Market
Building & Construction Materials
North America Ceiling Tiles Market
Building & Construction Materials
Acoustic Insulation Market
Building & Construction Materials
Ultra High Performance Concrete (UHPC) Market
Building & Construction Materials
Gypsum Concrete Market
Building & Construction Materials
Indonesia Ceramic Tiles Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
Roofing Materials Market