
 China Marble Market | 2026-2036
China Marble Market Size, Share, and Industry Trends Forecast 2026-2036
China Marble Market Analysis
Modular slab-to-tile bundling is realigning how developers procure finished stone, compressing supplier lists and raising minimum order thresholds. Xiamen Yuanda Stone leverages its Fujian fabrication base to anchor large-format slab contracts for commercial towers. JSC Group sustains quarry-to-project direct sales that bypass wholesale layers in premium residential segments. Kangli Stone specializes in processed marble cut-to-size for hotel interiors, competing on installation-ready precision rather than raw block volume.
China marble encompasses metamorphic calcium carbonate rock with Mohs hardness of 3–4, quarried in blocks and processed through gang saw cutting, resin treatment, and surface polishing for architectural cladding and interior finishes. Slab marble dominates value capture due to higher fabrication margins and specification in luxury commercial facades, while processed marble grows fastest as developers demand pre-cut, pre-finished components to accelerate construction timelines. The flooring application retains the largest volume position across residential and infrastructure end users, though wall cladding commands premium pricing in high-rise commercial towers.
MEE enforces emission caps on quarry operations under dual carbon implementation, while GB standards govern radioactivity limits and structural safety for interior stone applications. SAMR market access rules require testing certification that filters smaller, uncertified fabricators from commercial project supply chains. Stakeholders must monitor enforcement intensity in Fujian and Guangdong provinces where quarry consolidation and certification compliance will determine supplier viability ahead of the next planning cycle.
Market Dynamics
Dual carbon mandates from MEE are forcing quarry electrification and water recycling retrofits, compressing margins for energy-intensive block extraction while advantaging fabricators with captive renewable power and closed-loop processing systems in Fujian and Guangdong.
Growth Catalysts
- Greater Bay Area construction pipeline:Infrastructure and luxury residential projects in Guangdong Province are absorbing large-format slab marble at accelerating volumes, pulling processed stone through Xiamen and Yunfu fabrication clusters.
- GB standards compliance:Radioactivity testing and structural safety certification under national building codes is filtering uncertified suppliers from commercial project supply chains, consolidating procurement around SAMR-certified fabricators.
- Modular slab-to-tile bundling:Developers are compressing supplier lists and raising minimum order thresholds, rewarding integrated quarry-to-finish players with capacity to deliver pre-cut, pre-finished components.
Market Restraints
- Energy cost volatility:Quarry electrification under dual carbon goals requires diesel-to-electric machinery conversion, straining capital reserves of mid-tier extraction operators in Fujian.
- Supply concentration risk:Premium white marble block supply concentrates in select Guangxi and Sichuan quarries, exposing fabricators to volume rationing during peak construction seasons.
- Substitution threat:Sintered stone and large-format ceramic tile are displacing marble in standard-grade flooring specifications, compressing addressable market for economy-tier processed stone.
Strategic Opportunities
- Hotel interior retrofit wave:Cut-to-size precision marble for five-star renovation cycles in Shanghai and Shenzhen is creating demand for installation-ready components with pre-applied resin and edge finishing.
- Water recycling technology convergence:Gang saw slurry treatment systems combined with closed-loop polishing water recovery are enabling MEE-compliant expansion in water-stressed western quarry regions.
- Direct quarry-to-project channels:Bypassing wholesale layers through project-specific block reservation contracts is capturing margin in premium residential segments in Beijing and Hangzhou.
Industry Challenges
- Gang saw operator skill scarcity:Precision block cutting and resin treatment expertise is concentrating at aging master technicians, constraining quality throughput at expanding fabrication lines.
- Certification timeline compression:SAMR market access testing and GB standard compliance documentation is extending project qualification cycles, delaying supplier approval for urgent commercial tenders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Marble Market |
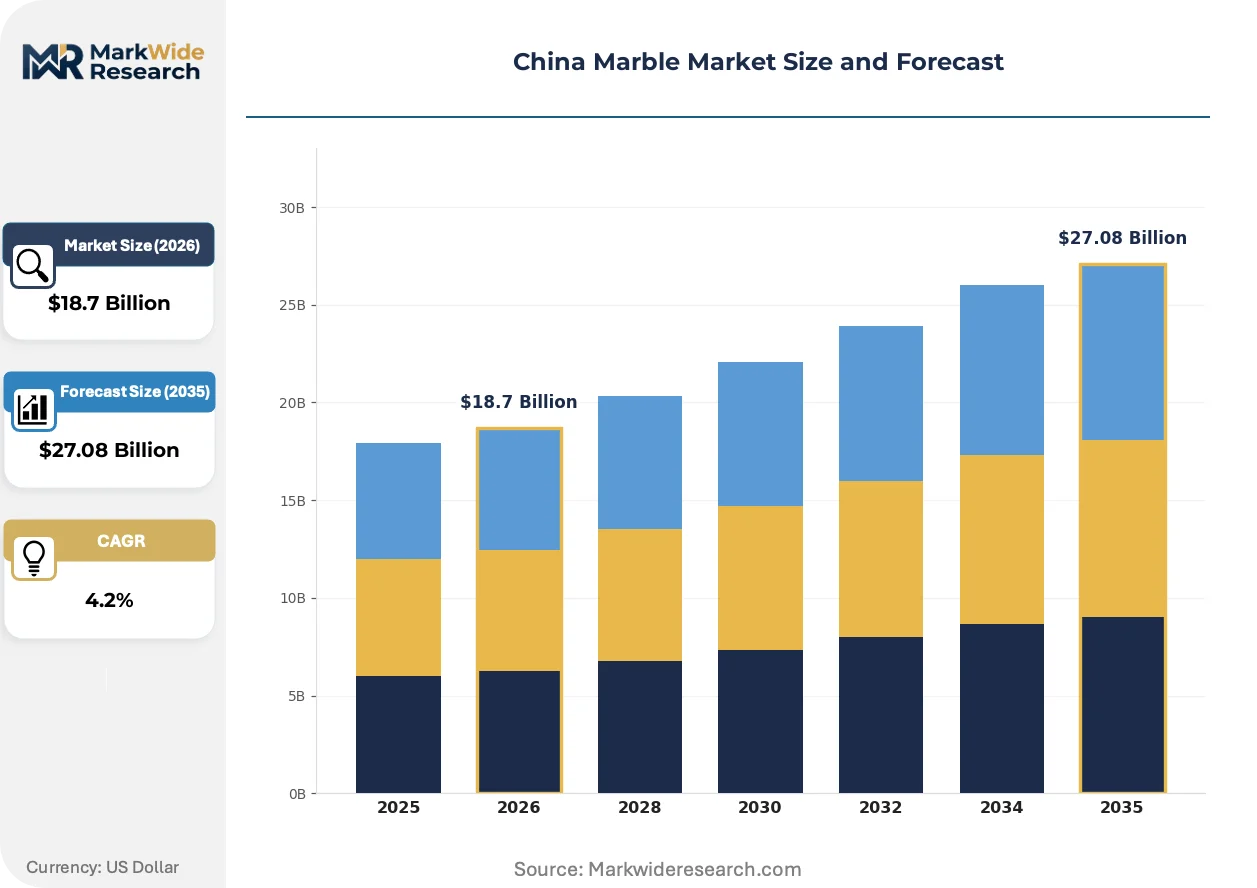
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $27.08 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Block Marble, Slab Marble, Processed Marble, Marble Tiles End User: Residential, Commercial, Infrastructure, Interiors Distribution Channel: Direct Sales, Wholesalers, Online, Retail Application: Flooring, Wall Cladding, Countertops, Decorative |
| Companies Covered | XIAMEN YUANDA STONE CO., LTD, JSC Group, China Kingstone Mining Holdings Limited, Fulei Stone, Xiamen Hongzhanxing Stone Co. Ltd, XISHI Group Ltd, Kangli Stone Group, Xiamen Quality Stone Co. Ltd, Universal Marble Granite Group Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Marble Market Emerging Trajectories
Digital templating and automated polishing lines are compressing fabrication lead times while MEE emission audits are reshaping quarry equipment procurement priorities. These shifts are unifying previously fragmented production stages.
Resin-injection treatment systems for crack-stabilized slab marble are unifying gang saw cutting with surface hardening in single-pass processing lines. Luxury commercial facade developers in Shanghai are specifying pre-treated slabs to reduce on-site installation risk. This unifying technology is compressing the traditional separation between raw block suppliers and finish-ready fabricators, concentrating value capture at integrated operators.
MEE emission caps on quarry diesel machinery are mandating electric excavator and wire saw adoption under dual carbon implementation timelines. Fujian and Guangdong extraction sites face accelerated equipment replacement cycles. Premium block producers are responding with photovoltaic-powered quarry operations to secure compliance headroom ahead of enforcement intensification.
Pre-cut, pre-finished marble component procurement is displacing traditional slab-and-fabricate contracting for hotel and commercial tower interiors. General contractors in the Greater Bay Area are consolidating stone purchasing around single-source suppliers capable of dimensional precision and installation-ready packaging. This pattern is most visible in Shenzhen luxury residential developments where construction timeline compression rewards suppliers with in-house CNC cutting and waterjet profiling capacity.
China Marble Market Segmentation
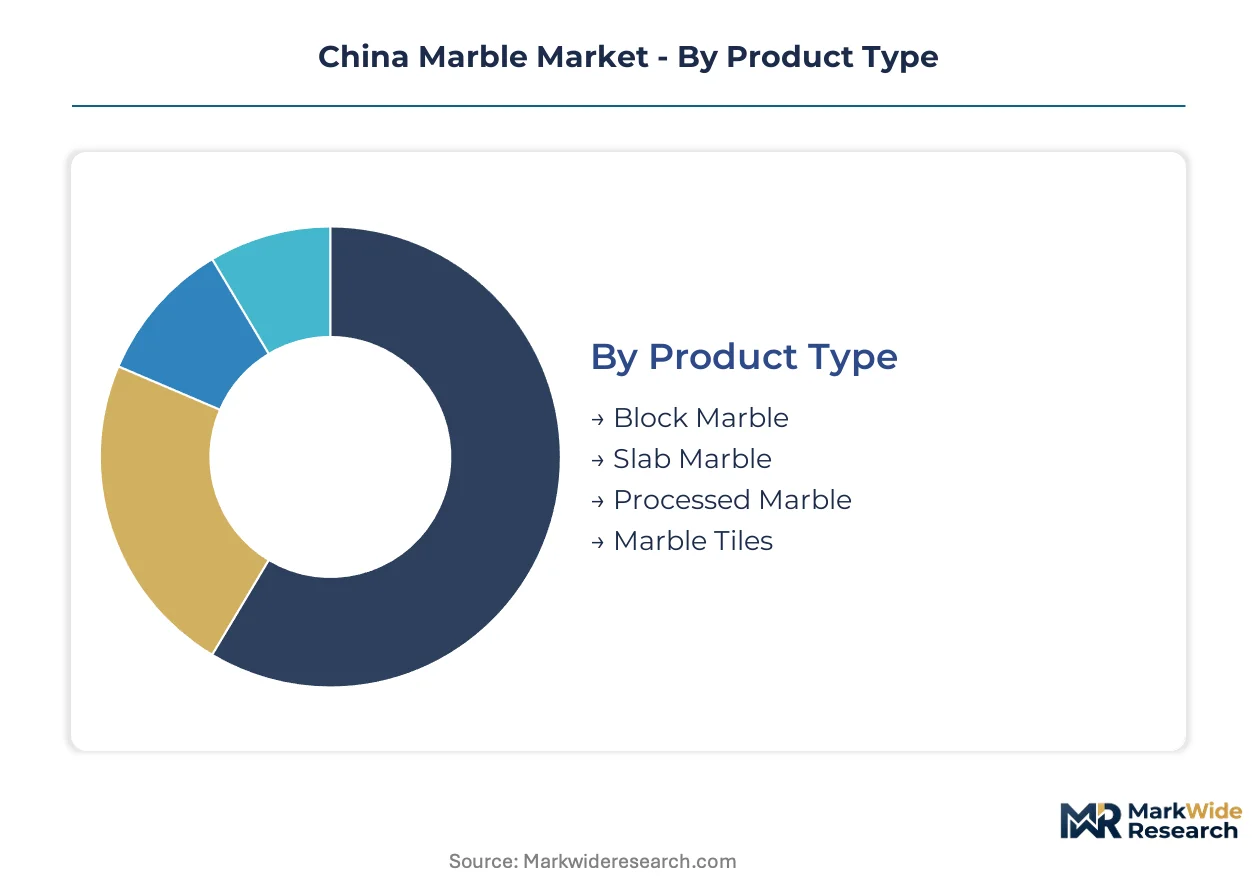
Marble segmentation in China reflects capital deployment patterns across quarry extraction, fabrication infrastructure, and finished goods distribution. Understanding where investment concentrates reveals which segments command pricing power and which face margin compression from regulatory compliance costs.
Product Type:
Capital intensity escalates sharply from raw block extraction through precision finishing, with gang saw lines and resin treatment systems requiring the heaviest upfront outlays.
- Block Marble:Raw calcium carbonate rock extracted through wire saw and controlled blasting operations in Guangxi and Sichuan quarries. Quarry electrification under MEE dual carbon mandates is forcing diesel-to-electric machinery conversions that strain mid-tier operators' balance sheets.
- Slab Marble:Gang-sawn sheets with resin-stabilized surfaces and polished finishes, commanding premium margins in luxury commercial facades. Shanghai and Shenzhen developers are absorbing larger format slabs, pulling volume through Xiamen and Yunfu fabrication clusters with captive renewable power.
- Processed Marble:Pre-cut, pre-finished components with CNC edge profiling and waterjet dimensional precision. Hotel interior retrofits in Beijing and Hangzhou are accelerating demand for installation-ready pieces that compress on-site fabrication timelines.
- Marble Tiles:Standardized dimensional units for residential flooring and wall coverage. Guangdong Province fabrication clusters dominate output, though substitution pressure from sintered stone is compressing addressable market for economy-grade specifications.
Slab marble absorbs the bulk of installed fabrication capacity; processed marble is expanding most quickly as developers prioritize construction timeline compression.
End User:
Customer concentration patterns split between volume-driven residential flooring and margin-rich commercial specification work.
- Residential:Luxury developments in Shanghai, Shenzhen, and Hangzhou specifying large-format slab marble for lobbies and common areas. Direct quarry-to-project channels are bypassing wholesale layers to capture margin in premium segments.
- Commercial:High-rise towers and mixed-use developments where wall cladding commands premium pricing over flooring applications. GB standards compliance and SAMR certification requirements filter uncertified suppliers from project supply chains.
- Infrastructure:Public buildings and transportation hubs with standardized material specifications. Procurement concentrates around state-backed contractors with established supplier qualification frameworks.
- Interiors:Hotel renovation cycles and retail fit-outs demanding cut-to-size precision with pre-applied resin and edge finishing. Five-star properties in Shanghai and Shenzhen are driving specification toward installation-ready components.
Commercial end users absorb the bulk of high-margin slab volume; interiors segment is climbing the fastest on hotel retrofit demand and precision component procurement.
Distribution Channel:
Channel economics favor integrated players capable of bypassing intermediary markups in premium segments.
- Direct Sales:Quarry-to-project contracts reserving specific block lots for named developments. JSC Group and similar operators sustain this channel in Beijing and Hangzhou premium residential markets.
- Wholesalers:Traditional aggregation layer for standard-grade material, facing compression as developers consolidate supplier lists and raise minimum order thresholds.
- Online:Digital templating and specification tools emerging for standardized tile and processed component procurement. Limited penetration in slab marble due to inspection requirements.
- Retail:Showroom-based selection for residential renovation and small-scale commercial fit-out, concentrated in Guangdong and Fujian fabrication hub cities.
Direct sales channel captures the bulk of premium segment value; online is gaining share fastest on digital templating adoption for standardized specifications.
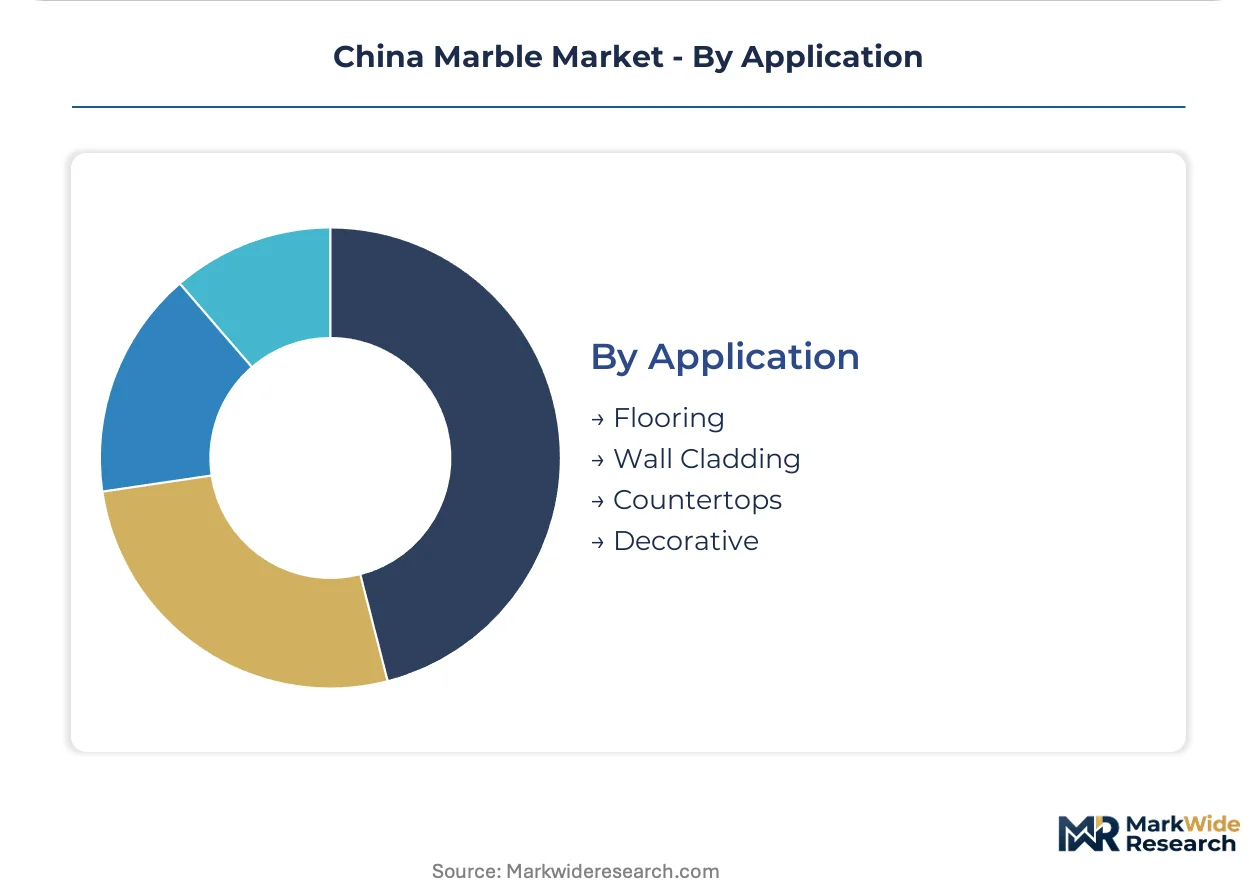
Application:
Application mix determines fabrication equipment configuration and margin structure across polishing lines.
- Flooring:Largest volume position across residential and infrastructure end users, though facing displacement threat from large-format ceramic tile and sintered stone in standard-grade specifications.
- Wall Cladding:Premium pricing in high-rise commercial towers where pre-treated resin-stabilized slabs reduce on-site installation risk. Shanghai facade developers are specifying single-source supply with dimensional precision guarantees.
- Countertops:Kitchen and bathroom surfaces requiring cut-to-size precision and edge finishing. Hotel interior retrofits are pulling processed marble through this application with installation-ready packaging requirements.
- Decorative:Sculptural and accent applications with specialized carving and waterjet profiling demands. Lower volume but highest per-unit margin due to craft skill concentration.
Flooring retains the bulk of total market volume; wall cladding is expanding most quickly on commercial tower pipeline acceleration in the Greater Bay Area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's marble production concentrates in Fujian and Guangdong provinces while consumption gravitates toward coastal megacities. Quarry electrification under MEE mandates is widening the cost gap between extraction zones and fabrication hubs.
Guangdong Province
Luxury residential towers in Shenzhen and Guangzhou absorb large-format slab marble at accelerating volumes. SAMR certification requirements filter uncertified fabricators from commercial project supply chains. Yunfu fabrication clusters process material for Greater Bay Area construction pipelines with captive renewable power installations.
Fujian Province
Xiamen-based fabricators anchor gang saw and resin treatment capacity for premium commercial facades. MEE dual carbon enforcement is mandating diesel-to-electric machinery conversion at coastal quarries. Water recycling retrofits at Zhangzhou processing lines are securing compliance headroom ahead of emission audit intensification.
Shanghai Municipality
Five-star hotel renovation cycles are driving specification toward cut-to-size precision marble with pre-applied edge finishing. GB standards govern radioactivity limits for interior stone applications in high-rise mixed-use developments. Pudong and Hongqiao districts concentrate procurement offices for direct quarry-to-project contracting.
Zhejiang Province
Hangzhou luxury residential developers are bypassing wholesale layers through block reservation contracts with Guangxi quarries. Provincial environmental bureaus align enforcement timelines with MEE national emission caps. Ningbo port infrastructure facilitates import block handling for domestic fabrication redistribution.
Sichuan Province
Premium white marble block extraction concentrates in Hanwang and Baoxing county quarries with limited seasonal operating windows. Provincial water resource regulations constrain gang saw slurry discharge in upper Yangtze watershed zones. Chengdu-based traders coordinate rail freight consolidation to eastern fabrication hubs during peak construction seasons.
China Marble Market Vendor Landscape
The competitive structure tilts toward integrated quarry-to-finish operators with captive renewable power and SAMR certification. Mid-tier extraction players face margin compression from MEE-mandated electrification costs while fabrication specialists capture premium positioning through precision cutting capacity. Two archetypes dominate: scale-driven integrated producers controlling block supply and installation-ready finishers, alongside regional specialists with deep vertical relationships in single metropolitan markets. Competitive moves concentrate on direct project channel development and water recycling technology licensing to secure compliance expansion rights.
Within the integrated tier, Xiamen Yuanda Stone Co., Ltd. and JSC Group exemplify quarry-to-project operators with direct sales channels in premium residential segments. Kangli Stone Group occupies a specialist position in processed marble for hotel interiors, competing on dimensional precision rather than raw block volume. XISHI Group Ltd. anchors the Fujian fabrication base with capacity to deliver pre-finished components for accelerated construction timelines.
| Leading Market Players |
|---|
| XIAMEN YUANDA STONE CO., LTD |
| JSC Group |
| China Kingstone Mining Holdings Limited |
| Fulei Stone |
| Xiamen Hongzhanxing Stone Co. Ltd |
| XISHI Group Ltd |
| Kangli Stone Group |
| Xiamen Quality Stone Co. Ltd |
| Universal Marble Granite Group Ltd |
| Others |
Supply Flow & Price Mechanics
Quarry electrification capex under MEE dual carbon mandates cascades through block extraction costs into downstream pricing tiers, compressing margins at mid-tier operators while integrated fabricators with captive renewable power capture premium positioning in slab and processed marble segments.
Pricing Analysis
Margin tightening in economy-tier processed marble reflects substitution pressure from sintered stone and large-format ceramic tile in standard flooring specifications. Three-tier pricing structure across premium, standard, and economy levels separates SAMR-certified fabricators from uncertified competitors on compliance grade and volume scale. Cost-down pressure on block marble accelerates because diesel-to-electric machinery conversion strains capital reserves of mid-tier extraction operators in Fujian. Commercial end users demonstrate lowest price sensitivity due to specification-driven procurement, while residential flooring buyers face highest sensitivity to ceramic tile alternatives.
Supply Chain Analysis
Direct-to-project channels handle hyperscale developer demand in Shanghai and Shenzhen, bypassing wholesale markups through block reservation contracts. Raw material supply concentrates in Guangxi, Sichuan, and Fujian provinces where premium white marble block extraction faces seasonal operating constraints. Gang saw slurry discharge regulations and wire saw equipment dependencies create processing bottlenecks at eastern fabrication hubs. Single-source vulnerability concentrates in select Guangxi quarries for premium white block, exposing fabricators to volume rationing. Distribution runs through Xiamen and Yunfu fabrication clusters with captive renewable power serving Greater Bay Area construction pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as MEE emission caps and SAMR certification requirements filter uncertified fabricators from commercial project supply chains, forcing weaker extraction and processing operators toward exit or acquisition.
For Market Incumbents: Cement market position through backward integration into Guangxi block supply and SAMR certification investment ahead of enforcement intensification. Defend against sintered stone substitution by expanding CNC cutting and waterjet profiling capacity for installation-ready component delivery. Prioritize direct quarry-to-project channel control in Beijing and Hangzhou premium residential segments. For New Entrants and Emerging Players: Launch via digital templating platforms for standardized processed marble procurement in hotel interior retrofit cycles. Target cut-to-size precision segments where aging gang saw operator scarcity constrains incumbent quality throughput. Penetrate through water recycling technology licensing to western quarry operators facing MEE compliance pressure. For Investors and Strategic Acquirers: SAMR certification timeline compression is the leading indicator that integrated quarry-to-finish operators with captive renewable power will command persistent premium positioning. Over the medium-term horizon, acquisition focus should center on Fujian and Guangdong fabricators with closed-loop processing systems and direct project channel relationships. Watch for enforcement intensity signals in provincial environmental bureau audit schedules as inflection triggers.| Strategic Initiative | Industry Significance |
|---|---|
| Quarry Electrification Investment | MEE dual carbon compliance secures operating license continuity in Fujian and Guangdong extraction zones. |
| Water Recycling Technology Deployment | Gang saw slurry treatment enables expansion in water-stressed western quarry regions under tightening discharge rules. |
| Direct Project Channel Development | Block reservation contracts with Shanghai and Shenzhen developers capture margin bypassing wholesale layers. |
| SAMR Certification Acceleration | Testing documentation completion filters uncertified competitors from commercial tower supply chains. |
| Precision Fabrication Capacity Addition | CNC cutting and waterjet profiling installation-ready components compress on-site timelines for hotel retrofits. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with quarry operations managers, fabrication plant engineers, commercial project procurement officers, and hotel interior design consultants. Quarry production databases, MEE emission audit disclosures, SAMR certification registries, and Greater Bay Area construction permit filings provided volume and value triangulation points. Bottom-up block extraction and fabrication capacity estimates were cross-validated against top-down construction material demand forecasts.
Granularity-level modeling operated at product type, end user, application, and distribution channel dimensions, with additional disaggregation by provincial regulatory enforcement cluster and renewable power availability. CAGRs were derived from trend extrapolation of historical volume flows through the projection horizon, adjusted for MEE electrification timeline impacts on quarry operating cost structures and SAMR certification penetration curves affecting supplier qualification rates.
The model assumes a particular technology adoption path for electric quarry machinery and closed-loop water systems; alternative pathways for diesel-to-electric conversion timing or water recycling technology cost curves would alter the outlook. Forecasts reflect base-case assumptions regarding dual carbon enforcement intensity and substitution elasticity from sintered stone competitors. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Concrete Sealer Market
Building & Construction Materials
Aerated Autoclaved Concrete (AAC) Market
Building & Construction Materials
China UPVC Doors and Windows Market
Building & Construction Materials
Geogrid Market
Building & Construction Materials
North America Ready-Mix Concrete Market
Building & Construction Materials
Plasterboard Market
Building & Construction Materials
US Glass Curtain Wall Market
Building & Construction Materials
Tar Paper Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Plumbing Components Market
Building & Construction Materials
Plastic Fencing Market
Building & Construction Materials
Fire Hydrant System Market
Building & Construction Materials
Japan Concrete Conditioner Market
Building & Construction Materials
Acoustic Plasterboard Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market