
 Sliding Bearing Market | 2026-2036
Sliding Bearing Market Size, Share, and Industry Trends Forecast 2026-2036
Sliding Bearing Market Analysis
Multi-source procurement is restructuring supply relationships across the sliding bearing value chain. SKF Group leverages its captive polymer compounding capabilities to secure margin pools in composite bearing grades. Schaeffler Group anchors European automotive programs through backward integration into sintered bronze strip production. Daido Metal Co., Ltd. dominates Asian marine and construction equipment channels with oil-impregnated bearing technologies refined over decades.
A sliding bearing is a tribological component that supports radial or axial loads through direct surface contact between a stationary housing and a rotating or sliding shaft, typically incorporating lubricant grooves, PTFE-impregnated liners, or babbitt overlays to manage friction and wear. These bearings serve critical damping and alignment functions in power transmission, heavy rotating equipment, and precision motion systems where rolling-element alternatives fail under shock loads or contaminated environments. Plain bearings occupy the mature volume base across industrial machinery rebuild cycles, while composite bearings capture the fastest expansion as PTFE-and-fabric liners displace traditional metal architectures in electrified automotive and aerospace weight-reduction programs. Ceramic bearings remain a narrow premium tier concentrated in semiconductor fabrication and medical imaging equipment where magnetic interference and chemical inertness command price premiums.
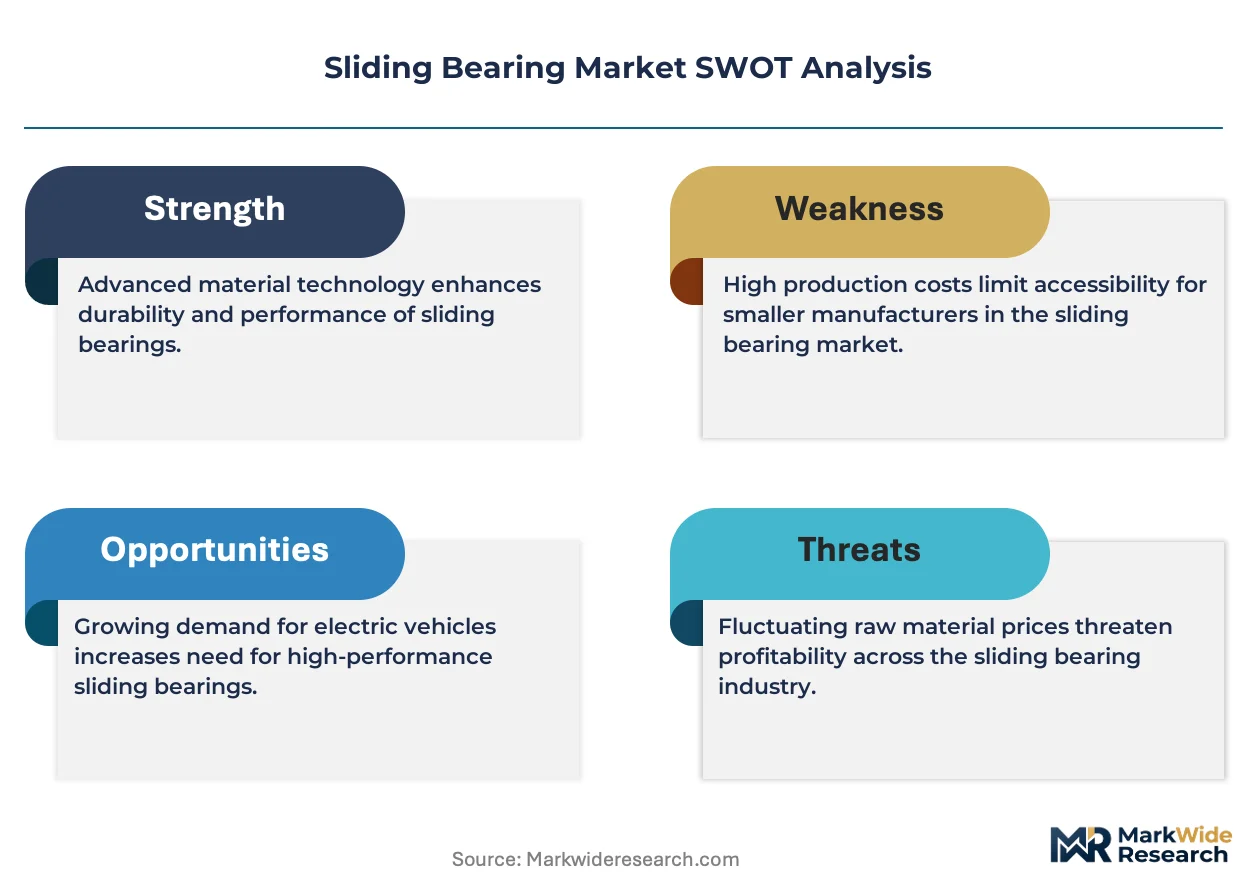
FDA scrutiny of bearing materials in medical device applications, combined with EPA restrictions on perfluorinated lubricant chemistries and REACH substance-of-very-high-concern listings for lead and cadmium bearing alloys, is compressing the approved material palette and extending qualification timelines for new formulations. ISO 4384 and DIN 1494 standards govern dimensional interchangeability and tribological testing protocols, creating compliance barriers for non-European suppliers seeking OEM qualification. Stakeholders must monitor regulatory convergence between EU chemical policy and emerging U.S. state-level restrictions on heavy metals in manufactured goods, as divergence would fragment material platforms and multiply certification burdens.
Market Dynamics
Electrified powertrain architectures are fundamentally reconfiguring tribological requirements across automotive OEM supply chains, forcing bearing suppliers to abandon legacy babbitt formulations in favor of self-lubricating polymer composites that tolerate intermittent lubrication and thermal cycling.
Growth Catalysts
- REACH substance restrictions:European ECHA listings for lead and cadmium in bearing alloys are accelerating material substitution programs toward PTFE-impregnated liners and sintered bronze composites across Tier-1 supplier networks.
- Marine equipment refurbishment cycles:Oil-impregnated bearing technologies are capturing expanded demand from Asian shipyards executing fleet modernization programs under tightened IMO emissions enforcement.
- Precision manufacturing clustering:Germany's Baden-Württemberg and Bavaria industrial corridors concentrate R&D investment in integrated bearing-transmission modules that reduce assembly steps for electrified axle systems.
Market Restraints
- Copper and tin price volatility:Sintered bronze strip production faces margin compression from London Metal Exchange commodity swings that propagate through multi-tier supply contracts.
- Polymer compounding concentration:Captive PTFE formulation capabilities cluster within a narrow set of integrated manufacturers, limiting second-source qualification options for composite bearing buyers.
- Ceramic bearing substitution in semiconductor fabrication:Silicon nitride and zirconia architectures displace metal-matrix plain bearings in wafer handling equipment where magnetic neutrality commands specification premiums.
Strategic Opportunities
- Indian automotive localization:PLI scheme incentives for advanced automotive components are drawing sintered metal bearing investments toward Pune and Chennai manufacturing corridors to serve domestic EV production.
- Additive manufacturing convergence:Laser powder bed fusion of copper-nickel-tin alloys enables topology-optimized bearing housings with embedded lubricant channels that conventional casting cannot replicate.
- Digital aftermarket channels:Industrial MRO platforms are disintermediating traditional distributor networks for plain bearing replacement, compressing lead times from weeks to days for maintenance-critical operations.
Industry Challenges
- Tribology simulation expertise scarcity:Finite element modeling of mixed lubrication regimes requires specialized computational fluid dynamics talent that competes with aerospace and energy sector hiring pools.
- ISO 4384 certification timelines:New material formulations face 18-24 month qualification protocols for dimensional interchangeability that delay OEM program entry.
- Legacy equipment integration friction:Composite bearing retrofits into existing pillow block housings demand geometric tolerance reconciliation that complicates field installation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sliding Bearing Market |
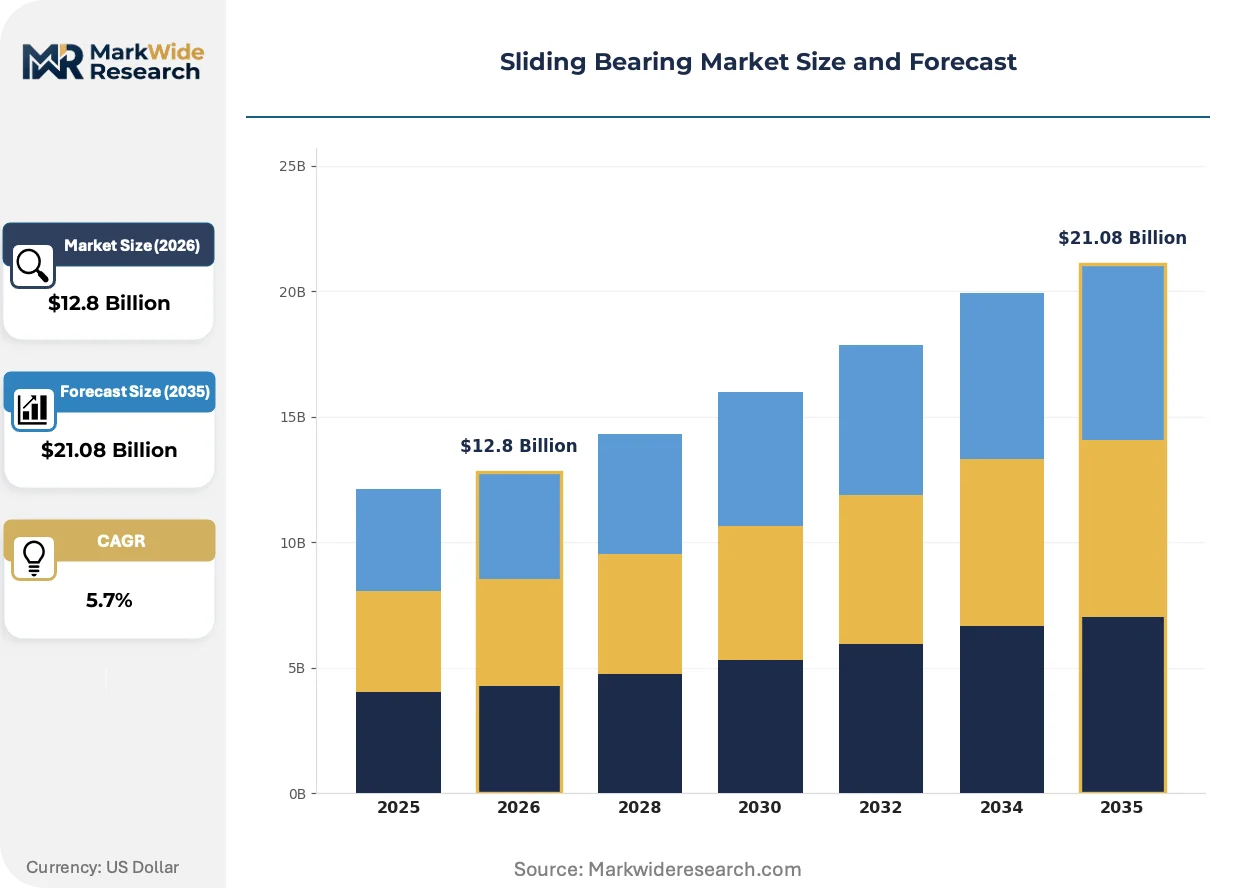
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plain Bearings, Rolling Bearings, Composite Bearings, Magnetic Bearings Application: Aerospace, Automotive, Industrial Machinery, Marine Material: Steel, Bronze, Plastic, Ceramic End User: Manufacturers, OEMs, Aftermarket, Repair Services |
| Companies Covered | NSK Ltd., JTEKT Corporation, SKF Group, RBC Bearings Incorporated, GGB Bearing Technology, Schaeffler Group, NTN Corporation, Daido Metal Co., Ltd., Timken Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sliding Bearing Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are converging to compress the approved formulation palette while opening architectural possibilities that metal-to-metal contact bearings cannot achieve.
PTFE-fabric composite liners are decentralizing traditional bearing supply relationships by enabling module suppliers to specify performance parameters without sourcing finished bearings from established metalworking houses. Automotive axle integrators in Stuttgart and Detroit are embedding these specifications directly into transmission housing RFQs. The structural consequence is margin compression for conventional babbitt casting operations that lack polymer compounding capabilities.
EPA restrictions on perfluorinated lubricant chemistries are forcing reformulation of PTFE-based bearing liners toward bio-derived or silicone alternatives that maintain coefficient of friction performance under boundary lubrication. Industrial consequence spans medical imaging equipment where FDA material scrutiny intersects with environmental compliance, compressing qualified supplier lists. Semiconductor fabrication equipment manufacturers in Hsinchu and Dresden are responding with accelerated qualification of ceramic bearing alternatives that eliminate polymer chemistry entirely.
Direct technical collaboration between bearing suppliers and OEM engineering teams is displacing arm's-length specification purchasing that historically flowed through tiered distributor networks. Power transmission OEMs in Japan and Germany are embedding tribologists within joint development programs for electrified powertrains. This pattern concentrates most visibly in automotive programs where thermal management requirements for e-axles demand bearing architectures designed concurrently with housing castings and cooling circuits.
Sliding Bearing Market Segmentation
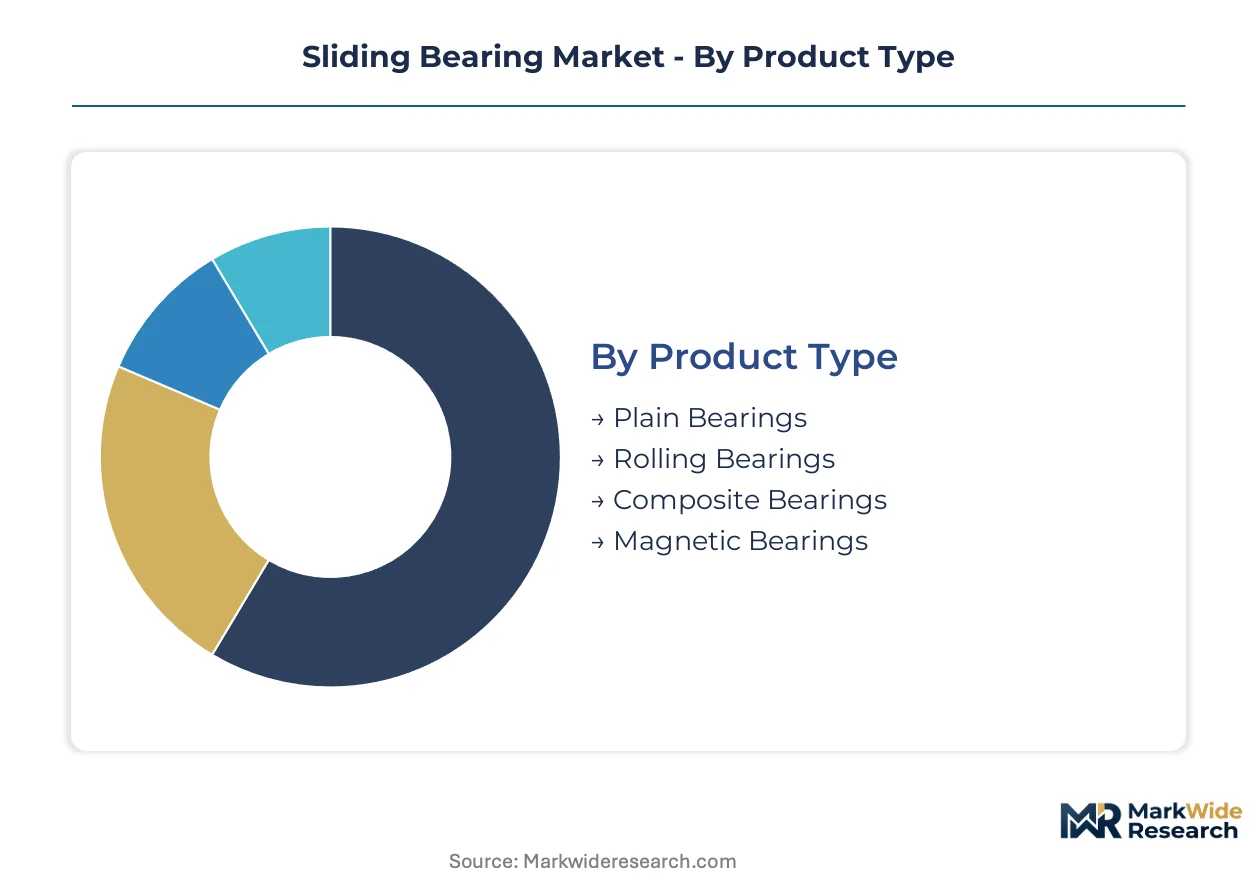
Sliding bearing procurement patterns diverge sharply between specification-driven OEM programs and price-sensitive aftermarket channels. Material selection and product architecture decisions cascade through qualification timelines, manufacturing footprints, and margin structures that suppliers cannot easily reverse.
Product Type:
Customization intensity spans from commodity plain bearings to engineered magnetic levitation systems, with composite architectures occupying the contested middle ground where polymer compounding capabilities determine supplier viability.
- Plain Bearings:Babbitt-lined steel shells and sintered bronze sleeves constitute the installed base across industrial machinery rebuild cycles. Demand concentrates in German precision manufacturing clusters where DIN 1494 interchangeability standards govern procurement specifications for axle and transmission modules.
- Composite Bearings:PTFE-impregnated fabric liners bonded to steel backings tolerate intermittent lubrication regimes that electrified automotive powertrains impose. Stuttgart-based automotive integrators embed these specifications directly into housing RFQs, compressing margins for conventional metalworking houses lacking captive polymer formulation.
- Rolling Bearings:Ball and roller configurations serve high-speed rotating equipment where rolling contact fatigue life governs replacement intervals.
- Magnetic Bearings:Active magnetic levitation systems eliminate mechanical contact in semiconductor wafer handling and medical imaging equipment where magnetic neutrality commands specification premiums.
Most installed capacity flows through Plain Bearings. Expansion is steepest in Composite Bearings.
Application:
End-use requirements fracture along duty cycle severity, with continuous heavy-load industrial applications demanding fundamentally different tribological architectures than intermittent-duty automotive systems.
- Automotive:Electrified powertrain architectures impose thermal cycling tolerance and boundary lubrication performance that legacy babbitt formulations cannot satisfy. E-axle integrators in Detroit and Stuttgart specify self-lubricating polymer composites concurrently with housing castings and cooling circuits.
- Industrial Machinery:Continuous-duty pumps, compressors, and gearboxes drive replacement demand through predictable wear cycles. Maintenance departments specify ISO 4384 dimensioned bearings through industrial MRO platforms that compress lead times from weeks to days.
- Aerospace:Weight-reduction programs and FAA material qualification requirements favor PTFE-fabric liners in flight control actuation and landing gear systems.
- Marine:Oil-impregnated bronze bearings serve stern tube and deck machinery applications where seawater contamination tolerance outweighs dry-running capability requirements.
Volume concentrates in Industrial Machinery. Steepest expansion trajectory belongs to Automotive.
Material:
REACH substance restrictions and EPA perfluorinated chemistry limitations are compressing the approved material palette while opening architectural possibilities that metal-to-metal contact bearings cannot achieve.
- Steel:Hardened steel backing strips provide structural support for babbitt overlays and polymer liners alike. Cost volatility in alloy feedstocks propagates through multi-tier supply contracts from European strip mills.
- Bronze:Sintered copper-tin matrices impregnated with lubricating oils serve marine and construction equipment channels. London Metal Exchange commodity swings compress margins for independent bearing houses lacking backward integration into strip production.
- Plastic:PTFE, PEEK, and ultra-high molecular weight polyethylene formulations enable dry-running capability in food processing and medical device applications where FDA material scrutiny intersects with environmental compliance.
- Ceramic:Silicon nitride and zirconia architectures displace metal-matrix bearings in semiconductor fabrication equipment where magnetic interference elimination and chemical inertness command price premiums.
Installed base tilts toward Bronze. Ceramic is gaining share fastest in precision equipment segments.
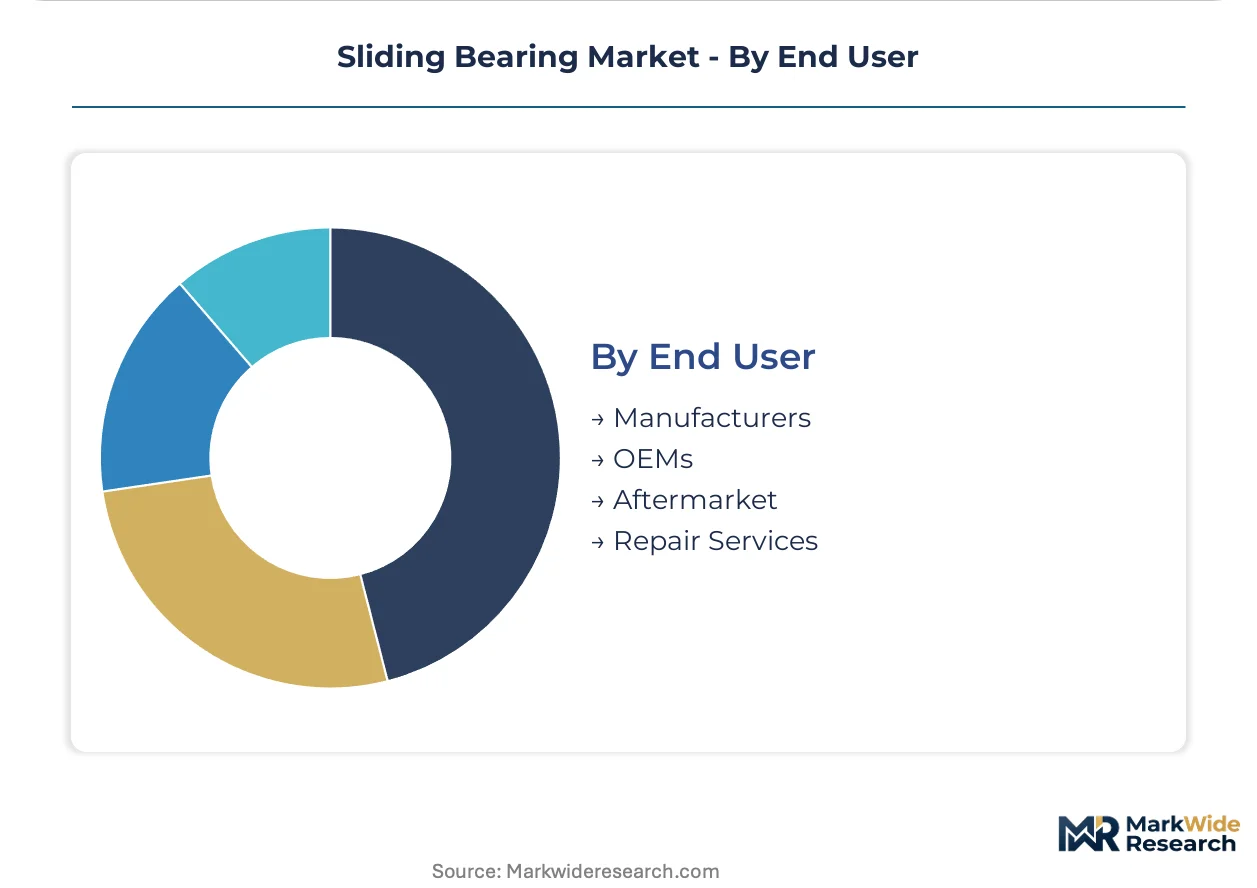
End User:
Channel structure determines pricing power and qualification burden, with OEM direct relationships demanding concurrent engineering investment that aftermarket distributors cannot justify.
- OEMs:Automotive and aerospace original equipment manufacturers embed tribologists within joint development programs for electrified powertrains. Direct technical collaboration displaces arm's-length specification purchasing that historically flowed through tiered distributor networks.
- Aftermarket:Industrial maintenance departments procure replacement bearings through digital MRO platforms that disintermediate traditional distributor networks. Compressed lead times shift volume toward standardized ISO-dimensioned products.
- Manufacturers:Tier-1 suppliers integrate bearing modules directly into axle and transmission assemblies, consolidating specification authority within Baden-Württemberg and Bavaria industrial corridors.
- Repair Services:Field service organizations execute emergency replacements where geometric tolerance reconciliation between composite liners and legacy pillow block housings complicates installation protocols.
Revenue concentration sits with OEMs. Digital channel expansion is accelerating most quickly in Aftermarket.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's precision manufacturing cluster anchors sliding bearing demand through integrated automotive transmission programs. Regulatory chemistry restrictions and electrified powertrain architectures are redrawing procurement geographies across supplier networks.
Germany
Automotive axle integrators in Stuttgart specify self-lubricating composite bearings concurrently with housing castings. REACH substance-of-very-high-concern listings for lead and cadmium alloys accelerate material substitution toward PTFE-impregnated liners. Bavaria's industrial corridor concentrates R&D investment in bearing-transmission modules that reduce assembly steps for electrified systems.
United States
Detroit-based e-axle engineering teams embed tribologists within joint development programs for thermal management architectures. EPA restrictions on perfluorinated lubricant chemistries compress the approved formulation palette for PTFE-based liners. Midwest industrial maintenance departments procure ISO 4384 dimensioned replacements through digital MRO platforms.
Japan
Power transmission OEMs in Nagoya and Tokyo execute direct technical collaboration with bearing suppliers for electrified powertrain qualification. METI industrial standards govern dimensional interchangeability protocols that create compliance barriers for non-domestic suppliers. Kanto region semiconductor fabrication equipment manufacturers accelerate ceramic bearing qualification to eliminate polymer chemistry entirely.
China
Marine equipment refurbishment cycles at Asian shipyards drive demand for oil-impregnated bearing technologies under tightened emissions enforcement. MIIT standards for advanced automotive components intersect with GB tribological testing protocols. Yangtze River Delta manufacturing bases serve domestic EV production with localized sintered metal bearing investments.
India
PLI scheme incentives for advanced automotive components draw sintered metal bearing investments toward Pune and Chennai corridors. BIS certification requirements extend qualification timelines for new material formulations serving domestic OEM programs. Maharashtra and Tamil Nadu manufacturing clusters integrate bearing modules directly into axle assemblies for emerging EV platforms.
Sliding Bearing Market Vendor Landscape
Global majors compete with regional champions across polymer compounding capabilities and backward integration into sintered bronze strip production. Market structure tilts toward consolidated specification authority within integrated Tier-1 supplier networks, with captive formulation capabilities determining supplier viability. Two strategic archetypes dominate: integrated polymer compounders capturing margin pools in composite grades, and metalworking houses defending installed base through bronze casting expertise. Competitive moves concentrate on capacity expansion in Asian automotive corridors and technology licensing for additive manufacturing convergence.
Among European-integrated manufacturers, SKF Group and Schaeffler Group exemplify the polymer-compounding archetype through captive formulation capabilities that secure specification authority in automotive RFQs. Daido Metal Co., Ltd. occupies a position representing the oil-impregnated specialization vector refined over decades in marine and construction equipment channels. These three anchors illustrate how geographic origin and structural integration determine competitive positioning across electrified powertrain and industrial refurbishment demand segments.
| Leading Market Players |
|---|
| NSK Ltd. |
| JTEKT Corporation |
| SKF Group |
| RBC Bearings Incorporated |
| GGB Bearing Technology |
| Schaeffler Group |
| NTN Corporation |
| Daido Metal Co., Ltd. |
| Timken Company |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap metalworking houses across Central Europe anchor bronze casting capacity and enforce pricing discipline through captive sintered strip production that independent bearing houses cannot replicate. Their ownership structure insulates margin pools from quarterly earnings pressure while concentrating supply relationships with Stuttgart automotive integrators.
Pricing Analysis
Input-cost pass-through from London Metal Exchange copper and tin volatility propagates unevenly across contract tiers. Three-tier pricing structure across premium, standard, and economy levels separates ISO 4384-certified OEM grades from DIN 1494 industrial interchangeability and unbranded aftermarket replacements. Cost compression in standard-grade sintered bronze is intensifying because commodity swings outpace annual contract renegotiation cycles. Aftermarket maintenance departments exhibit highest price sensitivity; aerospace qualification programs demonstrate lowest.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese polymer compounding capabilities that automotive RFQs specify without second-source alternatives. Raw material flows draw from Chilean copper concentrate, Indonesian tin smelters, and Chinese PTFE resin production. Tariff exposure on sintered bronze strip imports from European mills threatens margin structures for North American bearing houses. Distribution runs through Tier-1 transmission integrators that embed bearing specifications directly into housing RFQs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where electrified powertrain thermal management demands are shifting procurement toward premium self-lubricating composites with extended qualification timelines.
For Market Incumbents: Deploy captive polymer formulation capabilities to secure specification authority in Stuttgart and Detroit e-axle programs. Ceramic bearing substitution in semiconductor fabrication threatens oil-impregnated legacy revenue; accelerate PTFE-fabric liner capacity in Baden-Württemberg to defend position. Backward integration into sintered bronze strip production insulates margin pools from London Metal Exchange volatility. For New Entrants and Emerging Players: REACH substance-of-very-high-concern listings in Europe open a window for bio-derived lubricant formulations that bypass perfluorinated chemistry restrictions. Indian PLI scheme incentives represent the most penetrable geography; target Pune and Chennai manufacturing corridors with localized sintered metal investments. Qualification as ISO 4384-certified second source for composite bearing grades offers fastest OEM program entry. For Investors and Strategic Acquirers: Automotive Tier-1 suppliers are the most active acquirer in this space, consolidating bearing module suppliers into integrated transmission assembly operations. Long-term viability centers on formulation chemistry capabilities rather than metalworking assets. Watch for ceramic bearing qualification acceleration in Hsinchu and Dresden semiconductor clusters as inflection indicator for polymer composite displacement risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Compounding | SKF and Schaeffler capture margin pools in PTFE-fabric liners that metalworking houses forfeit. |
| Localized Sintered Metal Capacity | Pune and Chennai investments under India's PLI scheme serve domestic EV platform procurement. |
| Ceramic Bearing Qualification Acceleration | Silicon nitride architectures eliminate polymer chemistry for METI-governed semiconductor equipment. |
| Digital MRO Channel Expansion | Industrial maintenance platforms disintermediate distributor networks and compress replacement lead times. |
| Additive Manufacturing Convergence | Laser powder bed fusion enables topology-optimized copper-nickel-tin housings with embedded lubricant channels. |
Methodological Framework
Direct dialogue with tribology directors at power transmission OEMs, procurement leads at Tier-1 automotive suppliers, maintenance directors at industrial machinery operators, and polymer formulation chemists at integrated bearing manufacturers grounded qualitative assessment. Secondary validation drew from ECHA REACH substance listings, EPA perfluorinated chemistry guidance, ISO 4384 and DIN 1494 standard documentation, London Metal Exchange commodity data, and SEC filings from publicly traded bearing houses. Bottom-up demand modeling across electrified powertrain programs and industrial refurbishment cycles triangulated against top-down market sizing.
Segment-level outputs across the analysis window reflect product type disaggregation into plain, composite, rolling, and magnetic bearing architectures; material stratification across steel, bronze, plastic, and ceramic matrices; and end-user channel splits between OEM direct specification and aftermarket digital procurement. CAGRs were derived from regression analysis of historical qualification timelines, electrified vehicle production ramp assumptions, and replacement cycle intensity in marine refurbishment programs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated ceramic substitution in semiconductor fabrication or divergence between EU REACH and U.S. state-level heavy metal restrictions. Forecasts reflect documented assumptions regarding electrified powertrain thermal management requirements and polymer formulation qualification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America Decks Market
Building & Construction Materials
Nordic Solar Shades Market
Building & Construction Materials
Residential and Commercial Smart Glass Market
Building & Construction Materials
South Africa Wall Putty Market
Building & Construction Materials
Roofing Shingles Market
Building & Construction Materials
Electrochromic Glass for Construction Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
United States Gutter Guards Market
Building & Construction Materials
Steel Bolts and Nuts Market
Building & Construction Materials
North America Siding and Decking Market
Building & Construction Materials
Precast Concrete Manufacturing Market
Building & Construction Materials
India Faucet Market
Building & Construction Materials
Steel Wire Rope Products Market
Building & Construction Materials
Europe Oriented Strand Board Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Building Downpipe Market