
 Plasterboard Market | 2026-2036
Plasterboard Market Size, Share, and Industry Trends Forecast 2026-2036
Plasterboard Market Intelligence
The distinction between standard and specialty fire-resistant boards is collapsing as building codes tighten globally. Compagnie de Saint-Gobain S.A. leverages its extensive research in gypsum technology to meet these new performance standards. Knauf Gips KG dominates European markets with its scaled manufacturing of advanced plasterboard solutions. USG Corporation sustains a strong position in North America through its established brand and wide distribution network for building materials.
Plasterboard consists of a gypsum core pressed between two thick sheets of paper or fiberglass matting. Its primary function is creating smooth, durable interior walls and ceilings in residential and commercial construction. Fire-resistant and moisture-resistant boards command higher margins than standard plasterboard due to their specialized additives. Demand from construction contractors for wall partitioning and ceiling panel applications represents the largest volume segment, driven by new builds and renovations.
Building material standards, including the CE marking in Europe and ASTM specifications in the United States, dictate product performance and safety requirements. Environmental regulations such as the EU Green Deal and China's dual carbon goals influence raw material sourcing and manufacturing energy consumption. Suppliers must now decide whether to invest in recycling technologies for gypsum waste or focus on developing lower-carbon binder alternatives to maintain a competitive edge.
Market Dynamics
The convergence of stringent building safety codes and corporate sustainability mandates represents the central force shaping the plasterboard market. This pressure compels manufacturers to innovate beyond standard products, focusing on specialized formulations that meet dual requirements for fire resistance and lower environmental footprints across global construction projects.
Growth Catalysts
- Infrastructure Initiatives:Large-scale urban development and housing programs, particularly across India and Southeast Asian nations, are creating sustained volume demand for wall and ceiling partitioning materials.
- Building Code Harmonization:The tightening of performance standards, such as Europe's CE marking requirements for fire safety and acoustics, is forcing an upgrade cycle from standard to specialty boards.
- Lightweight Formulations:The development of boards with reduced weight simplifies logistics and installation, lowering labor costs for construction contractors and accelerating project timelines for commercial and residential builds.
Market Restraints
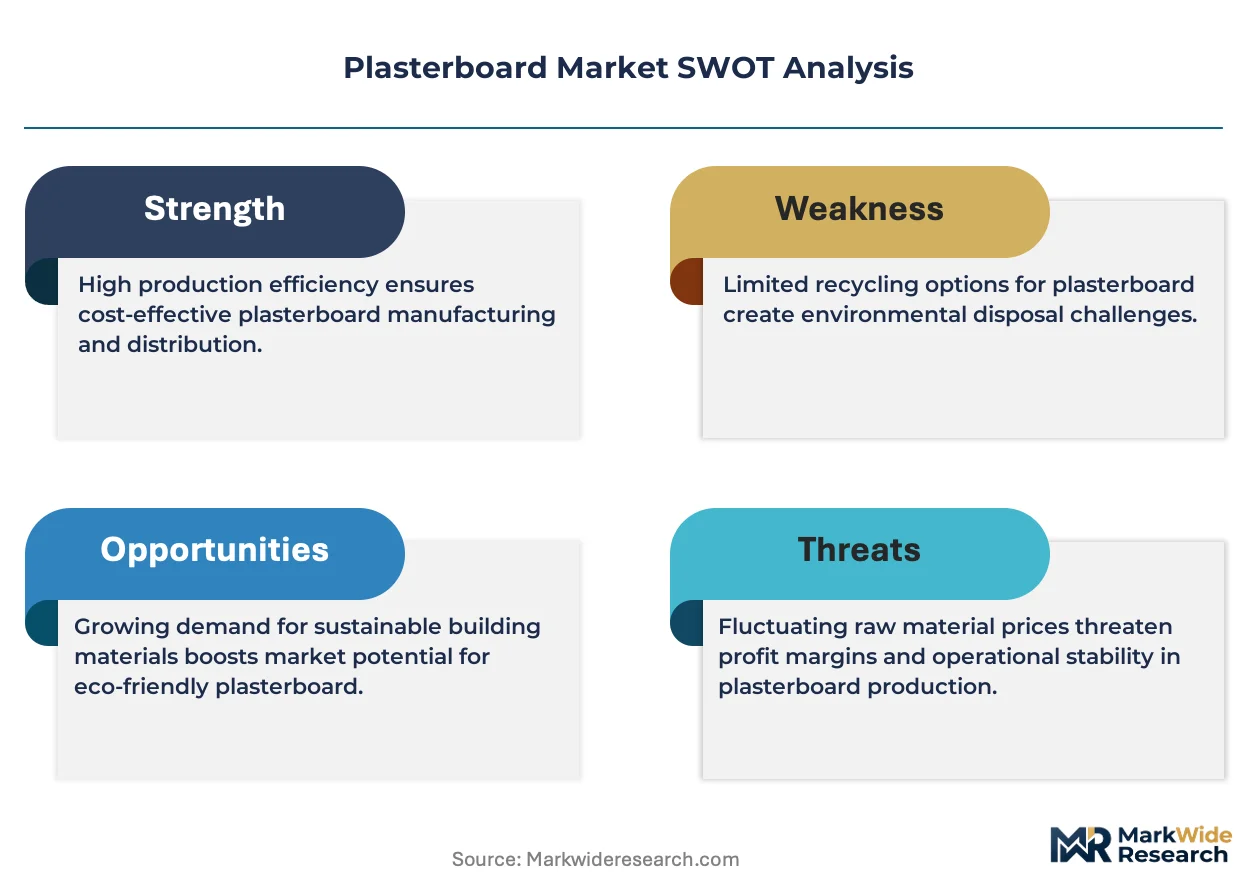
- Raw Material Volatility:The price and availability of high-quality natural gypsum and the energy required for its calcination process are subject to market fluctuations, impacting production costs.
- Logistical Costs:The bulk and weight of plasterboard panels make long-distance transportation expensive, constraining inter-regional trade and favoring local or regional manufacturing footprints. *Substitution from Alternatives: In certain low-cost construction segments, alternative walling materials like plywood, fiber cement boards, or traditional wet plaster applications present a viable substitute.
Strategic Opportunities
- Circular Economy Models:Investing in closed-loop recycling technologies to process gypsum waste from construction and demolition sites offers a path to secure raw material supply and meet sustainability goals.
- Bio-based Binders:Developing plasterboard using lower-carbon, bio-based binder alternatives to traditional materials can create a new premium product category for green building projects.
- Modular Construction Integration:Designing plasterboard solutions specifically for off-site and modular construction methods can open a high-growth channel focused on efficiency and reduced on-site labor.
Industry Challenges
- Capital-Intensive Manufacturing:Establishing or upgrading a plasterboard production line requires significant capital investment in heavy machinery, including kilns and forming equipment, creating high barriers to entry.
- Gypsum Waste Management:The operational complexity and cost of collecting, separating, and reprocessing gypsum waste from demolition sites remain a significant hurdle to achieving circularity at scale.
- Skilled Labor for Installation:The proper installation of specialized systems, such as high-performance acoustic or fire-rated assemblies, requires trained labor which can be scarce in some markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Plasterboard Market |
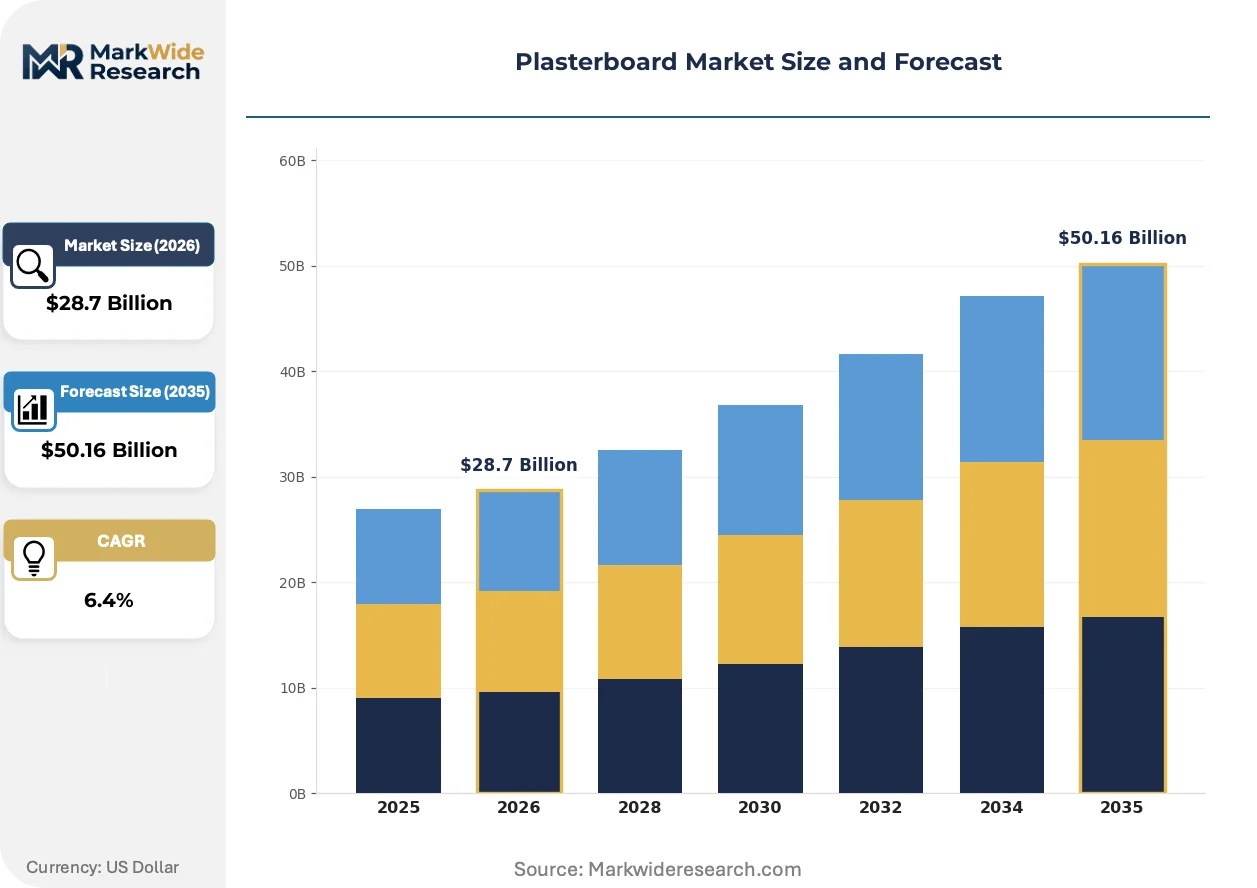
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Plasterboard, Moisture-Resistant Board, Fire-Resistant Board, Soundproof Board, Impact-Resistant Board Application: Wall Partitioning, Ceiling Panels, Interior Decoration, Exterior Cladding, Sound Insulation End User: Construction Contractors, Building Developers, Interior Designers, Renovation Companies, Property Managers Distribution Channel: Direct Sales, Wholesale Distributors, Specialty Retailers, Online Marketplaces, Building Material Suppliers |
| Companies Covered | USG Corporation, National Gypsum Company, Knauf Gips KG, CSR Limited, Holcim Group, Compagnie de Saint-Gobain S.A., Etex Group, American Gypsum Company LLC, Georgia-Pacific LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Plasterboard Market Strategic Shifts & Innovations
The plasterboard industry's innovation trajectory is defined by the dual pursuit of enhanced material performance and improved environmental credentials. This evolution is driven by material science advancements in gypsum and binder chemistry, responding directly to new regulatory frameworks and shifting architectural demands for sustainable building components.
Technology and Product Evolution
Advanced formulations incorporating synthetic gypsum and novel, low-carbon binders are gaining traction. These materials offer comparable or superior performance in fire resistance and acoustics while reducing the embodied carbon of the final product. Architectural specifiers and contractors on projects seeking green certifications are the primary adopters. This new generation of eco-conscious board **is supplanting** traditional, energy-intensive plasterboard in high-value commercial and institutional building segments.
Regulatory and Policy Shifts
Environmental regulations like the EU Green Deal are fundamentally altering manufacturing priorities. The policy framework imposes stricter limits on industrial energy consumption and promotes circular economy principles, directly impacting gypsum processing and sourcing. European producers are most affected, responding with investments in energy-efficient kilns and developing infrastructure for post-consumer gypsum recycling to comply with evolving standards and maintain market access.
Demand-Side and Behavioral Shifts
A notable change in buying behavior is the move from commodity-based purchasing to specification-driven procurement for specialized boards. This trend sees manufacturers engaging earlier in the design process with architects and engineers, bypassing traditional distributor channels for high-performance acoustic and fire-resistant systems. This direct engagement model is most prominent in large-scale commercial projects within North American and European metropolitan centers.
Plasterboard Market Segmentation
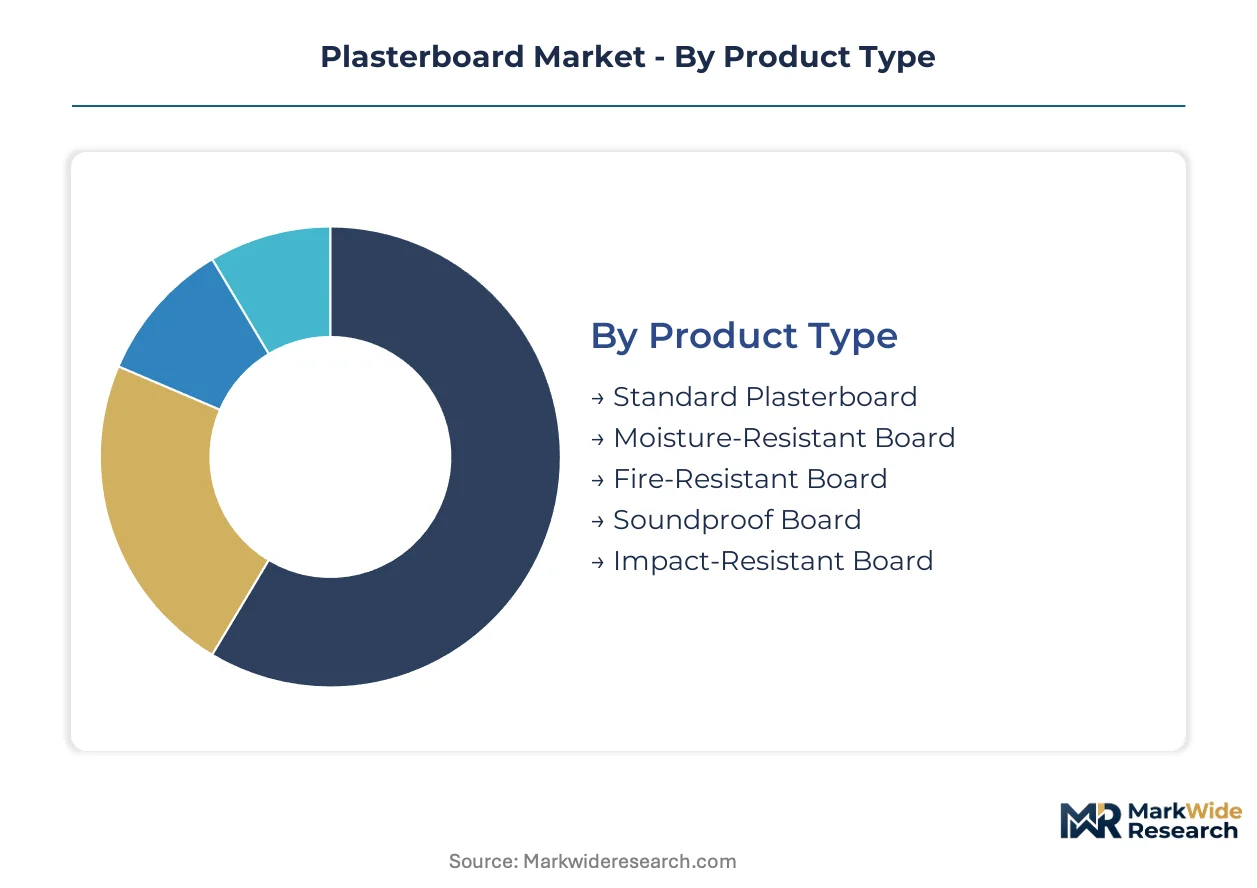
The plasterboard market's segmentation reflects the evolving demands for specialized building materials and the diverse channels through which these products reach construction sites. Understanding these distinct categories provides clarity on product innovation priorities and strategic distribution pathways.
Product Type:
Regulatory differentiation increasingly shapes the product type landscape, driving demand for boards that meet specific performance criteria beyond basic functionality.
- Moisture-Resistant Board:This product incorporates additives reducing water absorption and inhibiting mold growth, suitable for high-humidity environments like bathrooms and kitchens. Demand is high in Southeast Asian nations, driven by health and durability requirements.
- Fire-Resistant Board:Formulated with non-combustible glass fibers and other fire-retardant materials, this board provides enhanced protection against fire spread and structural collapse. Global building code harmonization, including Europe's CE marking, compels its specification in commercial and multi-story residential projects, particularly in urban development hubs.
- Standard Plasterboard:Composed of a gypsum core between paper facers, this is the foundational product for interior wall and ceiling applications.
- Soundproof Board:Features higher density or viscoelastic layers to absorb sound waves, reducing noise transmission between rooms.
- Impact-Resistant Board:Designed with fiberglass mesh or other reinforcing agents to withstand physical impacts in high-traffic areas.
Established volume favors Standard Plasterboard; emerging adoption favors Fire-Resistant Board.
Application:
Volume considerations significantly influence application segment dynamics, with core construction activities driving the largest demand for plasterboard products.
- Wall Partitioning:This application involves creating internal walls and separating spaces within buildings, utilizing large quantities of plasterboard for both new builds and renovations. Demand is particularly strong across India and Southeast Asian nations due to rapid urbanization and housing initiatives.
- Ceiling Panels:Plasterboard forms the primary material for suspended and fixed ceilings, contributing to aesthetics and structural integrity. Commercial and residential projects, especially in North American and European metropolitan centers, specify advanced ceiling systems for acoustic and fire performance.
- Interior Decoration:Plasterboard serves as a versatile substrate for various finishes, including paint, wallpaper, and textured coatings.
- Sound Insulation:Specialized plasterboard systems are installed to minimize noise transfer, crucial in multi-unit residential buildings and commercial offices.
- Exterior Cladding:Though less common, specific weather-resistant plasterboard variants can be used as a substrate for exterior finishes in certain construction types.
The largest share remains with Wall Partitioning, while Sound Insulation exhibits the steepest expansion trajectory.
End User:
Customer type segmentation highlights distinct procurement behaviors and project scales, influencing product specifications and service requirements.
- Construction Contractors:These professionals purchase plasterboard for large-scale commercial, residential, and infrastructure projects, valuing bulk pricing, reliable supply, and technical support. Their demand is particularly high in developing urban centers across India for new builds.
- Building Developers:These entities oversee entire construction projects, often specifying particular plasterboard types for performance, sustainability, and aesthetic reasons. They drive demand for specialized boards in major housing initiatives and commercial complexes in Europe.
- Renovation Companies:These firms focus on upgrading existing structures, requiring various plasterboard types for repairs, remodels, and aesthetic improvements.
- Interior Designers:These professionals specify plasterboard based on aesthetic and functional requirements for high-end residential and commercial fit-outs.
- Property Managers:They procure plasterboard for maintenance, repairs, and minor renovations within their managed residential or commercial portfolios.
Procurement patterns indicate a strong preference from Construction Contractors for standard products, with Building Developers increasingly opting for high-performance solutions.
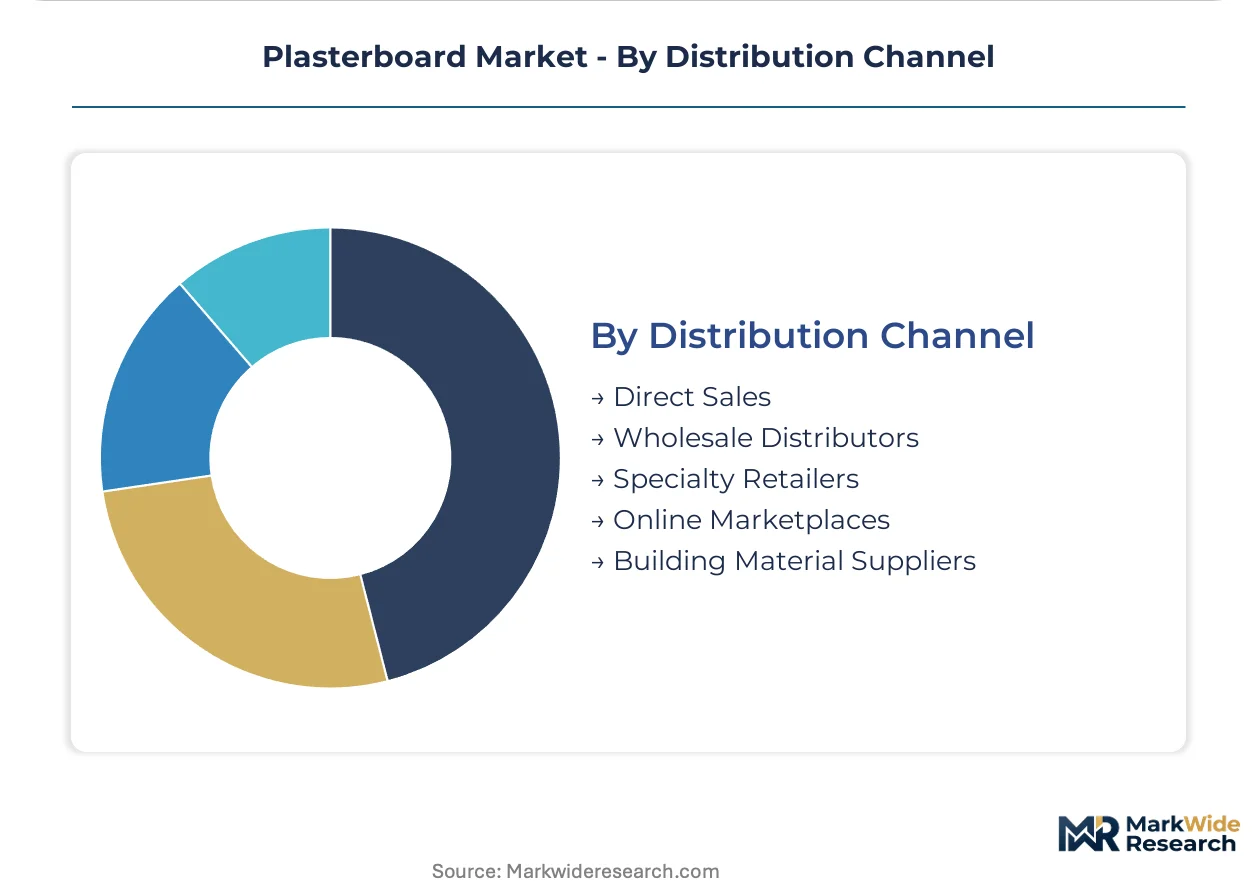
Distribution Channel:
Supply concentration within distribution channels determines product accessibility and logistical efficiency for various buyer segments.
- Wholesale Distributors:These large-scale operators purchase plasterboard in bulk directly from manufacturers and supply it to smaller retailers, contractors, and building material suppliers. This channel dominates in markets like Europe, where established networks facilitate efficient large-volume delivery.
- Building Material Suppliers:These outlets provide a range of construction products, including plasterboard, to local contractors, small builders, and individual consumers. Their extensive reach makes them crucial for project supply in North America.
- Direct Sales:Manufacturers sell directly to very large construction projects or key accounts, often for specialized or high-volume orders.
- Specialty Retailers:These stores focus on specific building materials or niche products, offering a curated selection of plasterboard types, often with expert advice.
- Online Marketplaces:E-commerce platforms facilitate the purchase of plasterboard, particularly for smaller orders or individual consumers, offering convenience and broader product comparison.
Traditional channels like Wholesale Distributors continue to manage the majority of plasterboard volume, while Online Marketplaces are gaining traction for niche products and smaller-scale procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Supply concentration in the plasterboard market is influenced by regional manufacturing capabilities and proximity to major construction hubs. Localized production minimizes logistical costs, which are substantial given the bulk and weight of plasterboard panels. This geographic alignment ensures efficient delivery to large-scale projects.
United States
United States demand for plasterboard stems from robust commercial and residential construction activity, particularly for interior walls and ceilings. ASTM specifications dictate stringent product performance and safety requirements for building materials across the nation. Major metropolitan centers, such as New York and Los Angeles, drive procurement patterns for specialized high-performance acoustic and fire-resistant systems.
Germany
German construction projects increasingly specify advanced plasterboard solutions, responding to stringent energy efficiency and safety standards. The EU Green Deal significantly influences raw material sourcing and manufacturing energy consumption for European producers. Industrial regions like North Rhine-Westphalia focus on scaled manufacturing of advanced plasterboard solutions to meet these evolving performance benchmarks.
India
India experiences substantial plasterboard demand from large-scale urban development and housing programs, driving volume for wall and ceiling partitioning materials. The Bureau of Indian Standards (BIS) sets national requirements for building material quality and safety. Major urban centers such as Bangalore and Chennai exhibit high construction contractor demand for new builds and renovation projects.
China
Chinese infrastructure and housing initiatives generate significant plasterboard demand for both new construction and renovation activities. China's dual carbon goals influence manufacturing energy consumption and promote lower-carbon binder alternatives in the construction sector. Major economic zones, including the Yangtze River Delta, are adopting eco-conscious board formulations for green building projects.
Plasterboard Market Key Industry Players
Concentration sits with large multinational manufacturers possessing extensive research and development capabilities in gypsum technology. The plasterboard market exhibits a tiered structure, with established global players alongside regional specialists and niche innovators. Key strategic archetypes include integrated building material suppliers, advanced gypsum product innovators, and regional volume producers. Dominant competitive moves involve continuous innovation in specialized fire-resistant and moisture-resistant formulations and strategic investments in recycling technologies for gypsum waste.
Among established multinational players, Compagnie de Saint-Gobain S.A. represents a diversified building materials group leveraging extensive research in gypsum technology. Knauf Gips KG, a German-based entity, exemplifies a European market leader known for its scaled manufacturing of advanced plasterboard solutions. USG Corporation, an American Gypsum Company LLC, maintains a strong position in North America, anchoring its presence through an established brand and wide distribution network for building materials. These companies occupy positions across various product types, from standard to specialized fire-resistant and moisture-resistant boards.
| Leading Market Players |
|---|
| USG Corporation |
| National Gypsum Company |
| Knauf Gips KG |
| CSR Limited |
| Holcim Group |
| Compagnie de Saint-Gobain S.A. |
| Etex Group |
| American Gypsum Company LLC |
| Georgia-Pacific LLC |
| Others |
Cost & Logistics Intelligence
Project-based long-term contracts lock in both supply access and price visibility for large-scale plasterboard procurement. This structure mitigates raw material volatility and logistical cost pressures for major construction projects.
Pricing Analysis
Europe's CE marking dictates the pricing tier structure for specialized plasterboard solutions. Pricing stratifies across performance tiers for fire-resistant and acoustic boards, with standard products priced transactionally. Price differentiation stems from certification levels and volume scale for large orders. Pricing pressure affects standard plasterboard due to commodity competition. Construction contractors purchasing standard products are highly price-sensitive, while building developers specifying high-performance solutions exhibit lower sensitivity.
Supply Chain Analysis
Port congestion and container availability impact the inbound logistics of raw gypsum and additives for plasterboard manufacturing. Supply concentration for high-quality natural gypsum draws from specific regions in Europe, North America, and Asia. Raw material dependencies include natural gypsum, energy for calcination, and specialized additives. Commodity price volatility for energy and gypsum represents a structural risk. Distribution runs through wholesale distributors for bulk volumes to construction sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The plasterboard market is experiencing high-growth disruption, driven by the technological inflection of advanced, eco-conscious board formulations. This shift responds to tightening global building codes and corporate sustainability mandates.
For Market Incumbents:Compound existing research and development capabilities in gypsum technology to create next-generation fire-resistant and bio-based binder formulations. Invest in recycling technologies for gypsum waste to secure raw material supply and address environmental regulations like the EU Green Deal. This mitigates the threat of substitution from alternative materials and reduces reliance on volatile natural gypsum. Strengthen regional manufacturing footprints to minimize logistical costs and ensure reliable supply.
For New Entrants and Emerging Players:Anchor in specialized niches such as modular construction integration and high-performance acoustic systems. Target green building projects in urban development hubs across India and Southeast Asian nations, where demand for eco-conscious materials is expanding. Focus on developing lower-carbon binder alternatives to traditional materials, offering a clear sustainability value proposition. A direct engagement model with architectural specifiers provides a strong go-to-market angle.
For Investors and Strategic Acquirers:Innovators in bio-based materials and regional specialists with established recycling infrastructure represent attractive acquisition targets for long-term viability. The market benefits from sustained urban development and tightening building codes over the next five to ten years. A key signal to watch is the increasing regulatory mandates for embodied carbon in construction materials, indicating future growth in premium, sustainable products.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Gypsum Recycling Technologies | Secures raw material supply and meets circular economy sustainability goals for manufacturers. |
| Develop Bio-based Binder Formulations | Creates a new premium product category for green building projects and eco-conscious specifiers. |
| Expand Specialized Board Manufacturing | Addresses increasing demand for high-performance fire-resistant and acoustic solutions. |
| Integrate Modular Construction Solutions | Captures efficiency gains and reduced on-site labor demand in a high-growth construction segment. |
| Strengthen Architect/Engineer Engagement | Fosters early design specification for advanced systems, bypassing traditional distributor channels. |
Research Approach
Initial hypotheses were tested against primary input from construction contractors, building developers, material scientists, and regulatory compliance officers and refined through iterative feedback. This approach combined insights from over 15 in-depth interviews with extensive secondary validation. Secondary sources included building code databases, environmental policy documents, company financial reports, and construction industry statistics. Bottom-up market sizing was cross-referenced with top-down industry revenue figures for triangulation.
Variance decomposition isolated the impact of key drivers like infrastructure spending and regulatory shifts across the analysis window. The quantitative model integrated segmentation dimensions including product type, application, end user, distribution channel, and material composition. Compound annual growth rates were derived from historical trends and projected market dynamics. Urban development project pipelines and building code updates served as critical forecast inputs.
Underlying assumptions cover stable raw material supply and consistent regulatory enforcement, with deviation risk concentrated in geopolitical instability affecting trade routes. Unforeseen technological breakthroughs or abrupt shifts in construction financing could also impact projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Cement Sacks Market
Building & Construction Materials
Traffic Road Marking Coatings Market
Building & Construction Materials
Concrete Densifier Market
Building & Construction Materials
India Roofing Market
Building & Construction Materials
South America Industrial Flooring Market
Building & Construction Materials
Australia and New Zealand Industrial Flooring Market
Building & Construction Materials
PVC Window Market
Building & Construction Materials
Roofing Underlay Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
Geosynthetics Market
Building & Construction Materials
Honeycomb Sandwich Panels Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
Ready-Mix Concrete Market
Building & Construction Materials
Tower Bolt Market