
 North America Mobile Light Tower Market | 2026-2036
North America Mobile Light Tower Market Size, Share, and Industry Trends Forecast 2026-2036
North America Mobile Light Tower Market Insights
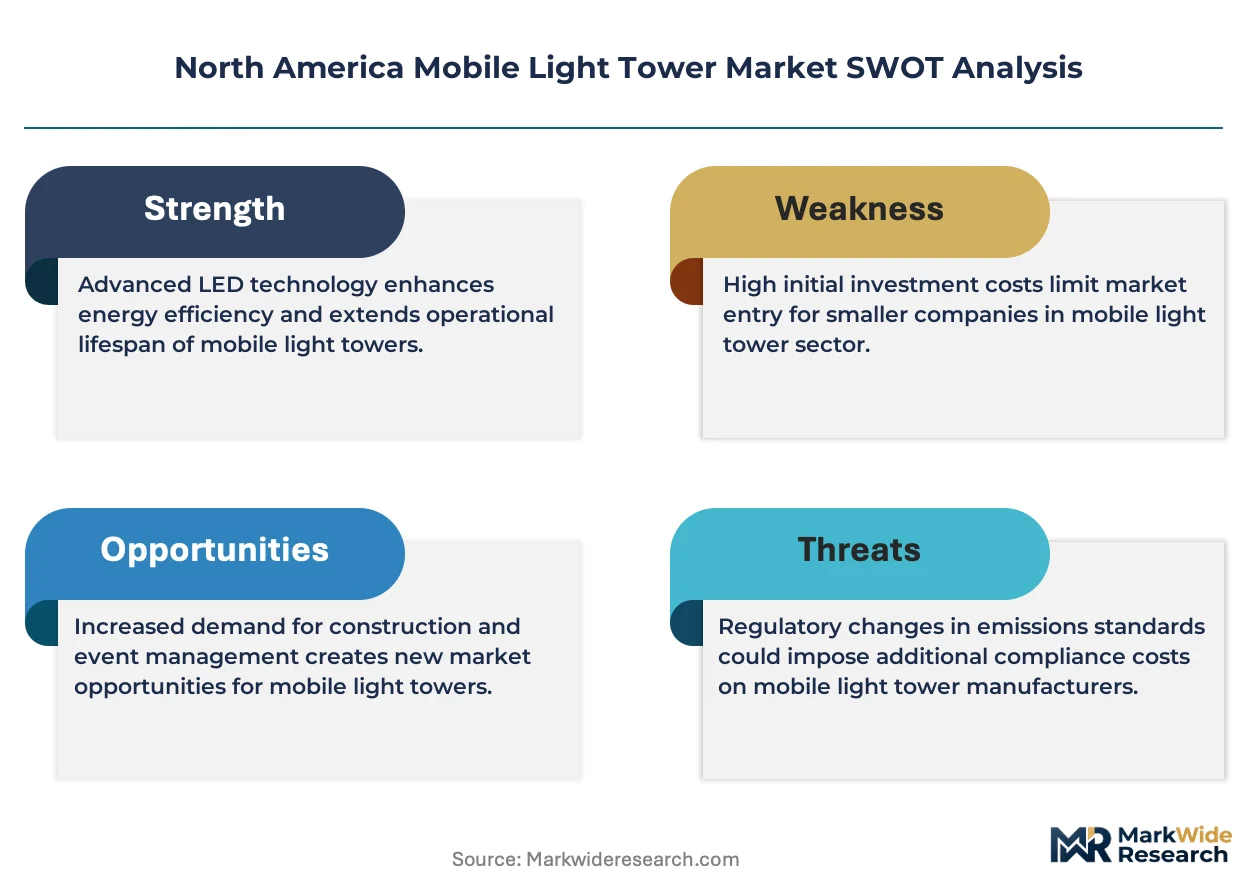
EPA Tier 4 Final emissions standards for non-road diesel engines is consolidating demand toward hybrid and solar-powered mobile light towers across North American job sites. Generac Power Systems leverages its vertically integrated generator manufacturing to anchor supply of dual-fuel light tower platforms. Doosan Portable Power competes through its extensive rental dealer network covering Canadian oil patch and US Gulf Coast markets. Atlas Copco specializes in LED-integrated towers with automated dimming controls that reduce fuel burn during low-activity periods.
A mobile light tower is a self-contained, trailer-mounted illumination system typically comprising a telescoping mast extending 30 feet, high-intensity discharge or LED lamp arrays, and an onboard power source such as a diesel generator, battery bank, or solar array; the unit deploys to construction zones, mining pits, and emergency scenes where grid electricity remains unavailable. Diesel-powered units still dominate rental fleet composition due to lower capital outlay and established service infrastructure, though hybrid configurations are capturing the fastest expansion as fuel cost volatility and emissions compliance costs reshape total cost of ownership calculations. LED technology has matured into the standard lamp specification across premium and mid-tier product tiers, displacing metal halide on lumen-per-watt efficiency and lamp longevity metrics.
EPA enforcement of Tier 4 Final standards, OSHA workplace illumination requirements for construction and mining operations, and Canadian Environmental Protection Act regulations on off-road engine emissions collectively shape product design priorities and market access conditions across the continent. NHTSA trailer safety standards additionally govern transportable light tower configurations, affecting mast retraction mechanisms and highway towing specifications. Stakeholders must monitor state-level zero-emission equipment mandates in California and New York, as these jurisdictions signal broader regulatory trajectories that will determine technology investment timelines and fleet replacement cycles.
Market Dynamics
EPA Tier 4 Final compliance deadlines are compressing replacement cycles across rental fleets, forcing capital redeployment toward dual-fuel and solar-hybrid architectures before 2027 enforcement windows close.
Growth Catalysts
- Alberta oil sands corridor expansion:Remote extraction sites require 24-hour illumination without grid access, pulling diesel-hybrid units into active deployment.
- OSHA workplace illumination mandates:Construction and mining operators must maintain minimum lux levels during night shifts, creating baseline demand for portable tower rentals.
- LED lumen-per-watt efficiency gains:Lamp technology now delivers equivalent brightness at 60% lower generator load, extending runtime between refueling.
Market Restraints
- Diesel price volatility:Fuel constitutes 35-45% of total operating cost for conventional units, eroding rental margins when crude benchmarks spike.
- Battery supply concentration:Lithium-ion cell production clusters in East Asia, exposing North American assemblers to shipping disruptions and tariff exposure.
- Solar intermittency in northern latitudes:Canadian winter daylight hours collapse below four daily, limiting pure solar unit viability without oversized battery buffers.
Strategic Opportunities
- Texas Permian Basin electrification:Flared gas-to-power infrastructure creates anchor demand for grid-tied light towers at multi-well pads.
- California zero-emission equipment mandates:State-level requirements for off-road machinery create first-mover advantage for battery-dominant platform suppliers.
- Telematics-enabled predictive maintenance:Sensor-integrated towers allow rental houses to shift from scheduled service to condition-based intervention, improving asset turns.
Industry Challenges
- Certification lag for hybrid architectures:EPA and CARB approval timelines for novel powertrain configurations extend 18-24 months, delaying product launches.
- Technician skill bifurcation:Field service teams must now diagnose both combustion engine faults and high-voltage electrical systems without standardized training curricula.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Mobile Light Tower Market |
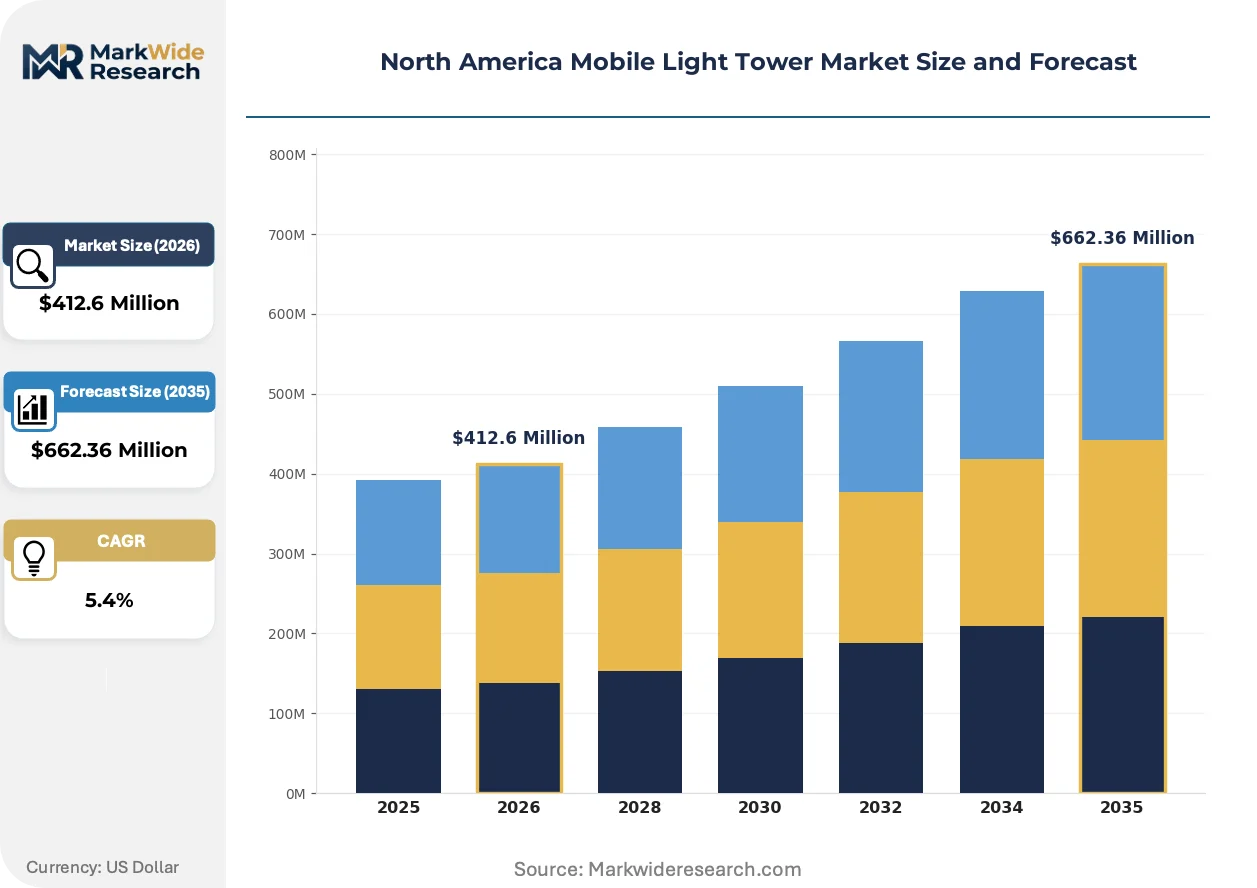
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $662.36 Million |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solar, LED, Diesel, Hybrid End User: Construction, Mining, Events, Emergency Services Application: Outdoor Lighting, Emergency Response, Road Construction, Industrial Use Technology: Portable, Fixed, Automated, Wireless |
| Companies Covered | Generac Power Systems, Inc., Doosan Portable Power, Atlas Copco AB, LARSON Electronics, Caterpillar, United Rentals, Inc., Allmand Bros Inc., Wacker Neuson SE, Terex Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Mobile Light Tower Market Trends and Innovations
Technology trajectories in mobile illumination center on powertrain diversification, regulatory alignment with emissions frameworks, and rental fleet digitization. These forces are reconfiguring supplier R&D priorities and customer procurement criteria simultaneously.
Solar-hybrid powertrains are electrifying the mid-tier product segment. These configurations combine photovoltaic arrays with downsized diesel generators and lithium buffering to deliver silent runtime during low-load periods. California infrastructure contractors and Texas oilfield services firms are specifying these units for noise-restricted sites. The technology is compressing addressable market share for pure diesel alternatives in premium rental tiers.
EPA enforcement of Tier 4 Final standards for non-road diesel engines is mandating exhaust aftertreatment systems across remaining conventional units. Manufacturers must integrate diesel particulate filters and selective catalytic reduction hardware without compromising tower transportability or mast stability. The regulatory pressure is concentrating engineering resources at Generac, Doosan, and Atlas Copco toward compliance-ready platforms ahead of 2027 deadlines.
Rental houses are unbundling lighting services from fuel provision in their commercial structures. Large construction contractors now negotiate all-inclusive rates covering equipment, delivery, maintenance, and energy rather than accepting dry rentals with separate fuel charges. This model shift is most visible in Arizona and Nevada solar farm construction, where EPC firms demand guaranteed uptime with zero operational burden. Suppliers responding with telemetry-equipped fleets gain preference in multi-year master service agreements.
North America Mobile Light Tower Market Segmentation
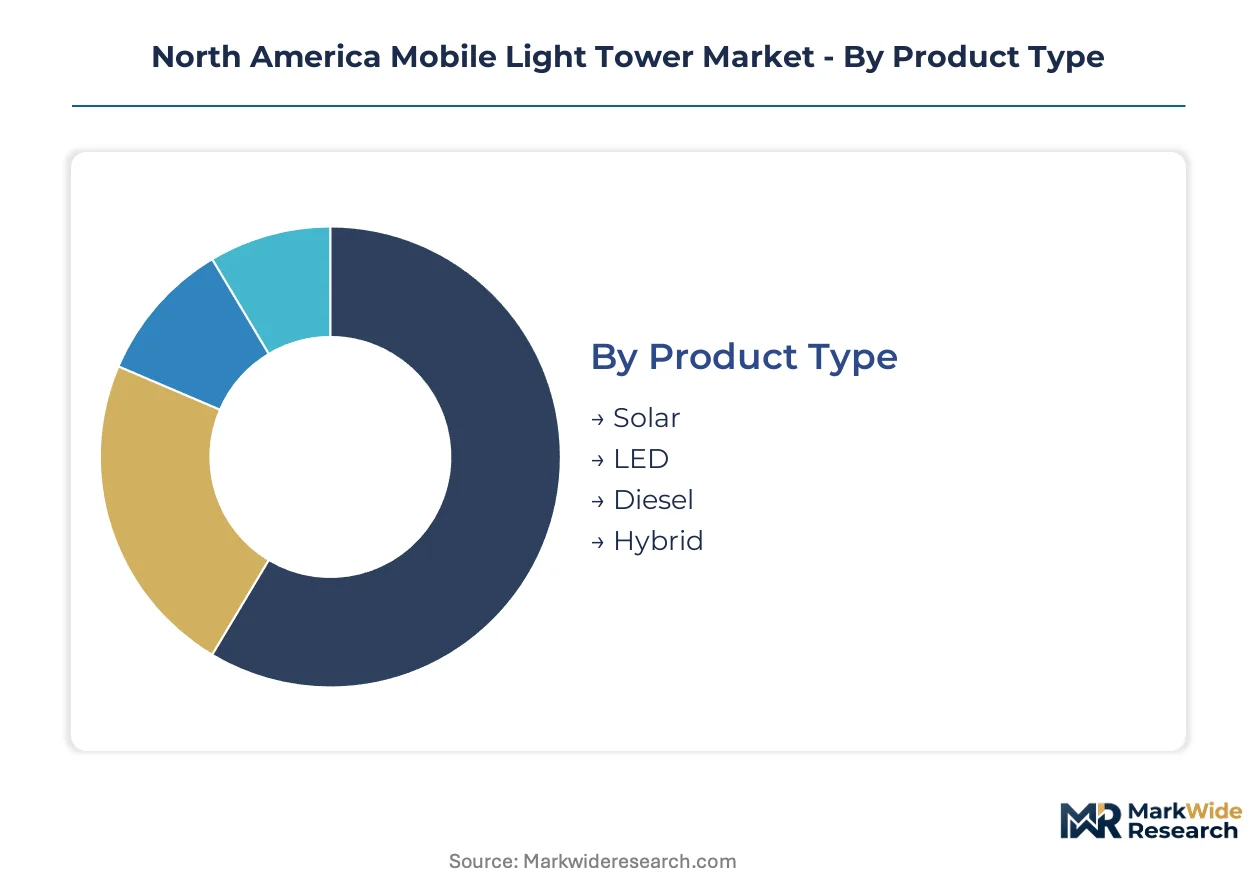
Equipment replacement cycles across North American rental fleets differ sharply by segment, with EPA Tier 4 Final deadlines compressing diesel-to-hybrid transitions while LED lamp retrofits proceed on separate timelines. Procurement patterns reveal distinct customer priorities: construction firms optimize for total cost of ownership, mining operators prioritize runtime reliability, and event producers demand silent operation.
Product Type:
Upgrade trajectories vary by incumbent fleet composition, with diesel-heavy rental houses facing the steepest capital redeployment requirements.
- Hybrid:Combines downsized diesel generators with lithium battery buffering and optional solar arrays, enabling silent runtime during low-load periods. Demand concentrates in California infrastructure corridors and Texas Permian Basin multi-well pads where noise restrictions and emissions mandates overlap.
- LED:Solid-state lamp arrays delivering 60% lower generator load versus metal halide predecessors, extending refueling intervals and reducing maintenance truck rolls. Alberta oil sands operators and Nevada solar farm EPCs specify these units for 24-hour illumination with minimal downtime.
- Solar:Photovoltaic-dominant powertrains with oversized battery banks for overnight operation, viable primarily in southern-tier states with consistent insolation.
- Diesel:Conventional generator-powered units with Tier 4 Final aftertreatment systems, retaining cost advantage in price-sensitive rural construction markets.
Volume placements concentrate in LED-equipped diesel units; the faster expansion belongs to hybrid architectures.
End User:
Customer procurement scale determines service model preferences, with large fleet operators driving telemetry integration and smaller contractors accepting dry rentals.
- Construction:General contractors and specialty trades rent towers for roadway, commercial, and residential projects, with OSHA workplace illumination mandates establishing baseline demand across all project scales.
- Mining:Surface and underground extraction operations require explosion-rated fixtures and extended mast heights, with Canadian oil sands corridors pulling specialized high-lumen configurations.
- Events:Festival promoters and sports venue operators prioritize silent operation and rapid deployment, specifying solar-hybrid units for noise-restricted sites.
- Emergency Services:Municipal fire departments and disaster response agencies stock portable towers for grid-down scenarios, favoring simple mechanical systems over complex hybrid powertrains.
Construction generates the heaviest unit volumes; emergency services adoption is climbing the fastest as climate-related disaster frequency rises.
Application:
Use-case lighting requirements dictate mast height, lamp array density, and runtime specifications with limited cross-application standardization.
- Outdoor Lighting:Temporary illumination for work zones, parking facilities, and material yards, typically requiring 30-foot mast extension and 360-degree coverage.
- Road Construction:Highway and arterial roadway projects demand high-visibility beacon configurations compliant with Manual on Uniform Traffic Control Devices standards.
- Industrial Use:Manufacturing facility maintenance turnarounds and refinery shutdowns require explosion-proof fixtures and hot-work permitting compatibility.
- Emergency Response:Search-and-rescue operations and temporary shelter illumination prioritize rapid deployment and battery-independent operation.
Outdoor lighting anchors current fleet utilization; road construction applications are gaining share fastest under federal infrastructure spending.
Technology:
Control system sophistication separates premium rental tiers from commodity offerings, with telemetry penetration varying by fleet scale.
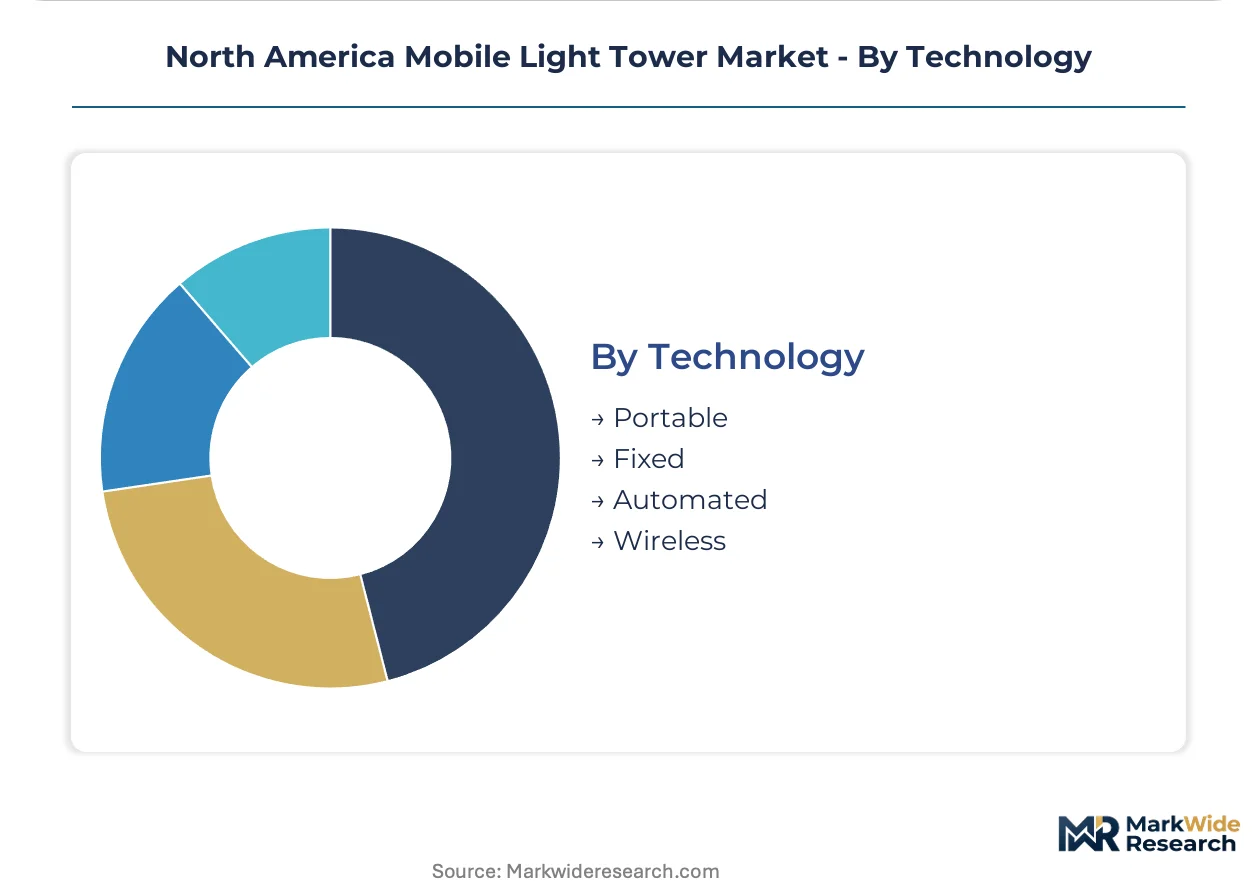
- Portable:Trailer-mounted units with manual mast deployment and basic on/off switching, dominating short-term rental markets.
- Automated:Sensor-integrated towers with daylight harvesting, motion-activated dimming, and remote telemetry for predictive maintenance.
- Fixed:Semi-permanent installations with hardwired power connections, common in multi-year mining and oilfield contracts.
- Wireless:Mesh-networked units enabling centralized fleet monitoring and automated dispatch, preferred by national rental houses with dense depot networks.
Portable technology holds the largest installed base; automated systems are expanding most quickly as rental houses unbundle lighting from fuel provision.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in the United States and Canada, while Mexico serves as an emerging assembly hub for components destined northward. Demand patterns diverge sharply across sub-regions, driven by energy extraction cycles, infrastructure spending waves, and state-level emissions mandates.
United States
Texas Permian Basin shale operators and California infrastructure contractors drive hybrid unit procurement. EPA Tier 4 Final enforcement compresses diesel fleet replacement timelines through 2027. Houston and Bakersfield anchor rental fleet deployment corridors where noise restrictions overlap with emissions compliance.
Canada
Alberta oil sands extraction and Saskatchewan mining operations require 24-hour remote illumination without grid access. Canadian Environmental Protection Act regulations on off-road engine emissions parallel EPA standards. Fort McMurray and Saskatoon form the core demand clusters for high-lumen diesel-hybrid configurations.
Mexico
Northern border states and Baja California construction activity pull portable lighting for maquiladora facility expansion. Mexican environmental regulations under SEMARNAT tighten gradually, creating preparation demand for cleaner powertrains. Monterrey and Tijuana industrial zones concentrate equipment rental activity near manufacturing corridors.
North America Mobile Light Tower Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with captive generator manufacturing and established rental dealer networks. Equipment manufacturers compete across three tiers: vertically integrated power systems specialists, construction machinery diversifiers, and pure-play rental service operators. Consolidation pressure intensifies as emissions compliance costs favor scale economies in R&D and certification. Strategic moves center on dual-fuel platform development and telemetry-enabled fleet management capabilities.
Among North American power systems specialists, Generac Power Systems, Inc. and Doosan Portable Power exemplify the integrated manufacturing archetype, while Atlas Copco AB occupies a position within the premium-tier industrial equipment segment. These anchors represent divergent approaches to regulatory compliance—some leveraging captive engine production, others emphasizing modular powertrain architectures adaptable across emission zones.
| Leading Market Players |
|---|
| Generac Power Systems, Inc. |
| Doosan Portable Power |
| Atlas Copco AB |
| LARSON Electronics |
| Caterpillar |
| United Rentals, Inc. |
| Allmand Bros Inc. |
| Wacker Neuson SE |
| Terex Corporation |
| Others |
Pricing and Supply Chain Analysis
Steel price volatility cascades through mobile light tower manufacturing into tiered equipment pricing, with diesel generator block costs and lithium battery pack values compressing margin structures differently across hybrid and conventional product lines.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for rental fleet operators, shifting procurement economics from capital expenditure to operational expenditure models. Three-tier pricing structure across premium telemetry-integrated, standard LED-equipped, and economy metal-halide tiers separates buyers by compliance requirements and runtime reliability needs. Pricing pressure stems from EPA Tier 4 Final aftertreatment cost absorption in diesel units. Small municipal contractors exhibit highest price sensitivity; large oilfield services firms prioritize total cost of ownership over unit rates.
Supply Chain Analysis
Diesel engine supply rests on captive manufacturing at Generac and Doosan facilities in Wisconsin and North Carolina, while lithium-ion cell production draws from South Korean and Chinese chemical conglomerates. Mast fabrication feeds from domestic steel service centers; LED arrays source from Taiwanese semiconductor foundries. Tariff exposure on Chinese battery components creates margin vulnerability for hybrid platform assemblers. Distribution runs through national rental house networks with regional depot stocking.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America mobile light tower market sits in a technology-transition phase as solar-hybrid powertrains displace legacy diesel-only architectures under emissions compliance deadlines.
For Market Incumbents: Extend telemetry-enabled fleet management capabilities to capture multi-year master service agreements from California infrastructure contractors. Deepen backward integration into generator manufacturing to defend margin position against Tier 4 Final aftertreatment cost inflation. Prioritize CARB certification investment ahead of New York zero-emission mandate expansion. For New Entrants and Emerging Players: The mid-tier price gap between premium solar-hybrid units and economy diesel rentals opens white-space targeting for battery-dominant platforms with simplified powertrain architectures. Focus penetration on Texas Permian Basin electrification corridors where flared-gas-to-power infrastructure enables grid-tied light tower deployment. Pursue direct EPC contractor relationships bypassing established rental house intermediaries. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional rental operators with dense depot networks in Alberta oil sands and US Gulf Coast corridors. Long-term viability hinges on hybrid fleet transition completion within the current replacement cycle window. Monitor California Air Resources Board rulemaking velocity as the inflection signal for accelerated zero-emipment mandate adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Fuel Platform Development | Enables EPA Tier 4 Final compliance without sacrificing runtime reliability in Canadian winter conditions. |
| Telematics Fleet Integration | Shifts rental houses from scheduled maintenance to condition-based intervention, improving asset utilization. |
| Solar-Hybrid Powertrain Scale-Up | Captures California zero-emission equipment mandate demand ahead of broader state adoption. |
| Rental Dealer Network Expansion | Secures preferred supplier status with United Rentals and regional independents in Texas shale corridors. |
| LED Array Technology Licensing | Reduces generator load requirements and extends refueling intervals for remote mining operations. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with rental fleet managers, construction procurement officers, oilfield services coordinators, and aftermarket service technicians. EPA certification databases, CARB executive orders, and provincial environmental registry documents provided regulatory trajectory validation. Equipment utilization metrics from national rental house disclosures and EPC contractor capex breakdowns informed demand-side calibration. Bottom-up unit shipment tallies triangulated against top-down market value estimates.
Data-stream reconciliation across the projection horizon applied segment-specific growth assumptions for hybrid, LED, solar, and diesel product categories, with end-user splits across construction, mining, events, and emergency services. Powertrain technology adoption curves, state-level mandate implementation schedules, and commodity price scenarios fed the analytical framework. CAGRs derived from logistic diffusion modeling of regulatory compliance deadlines and fleet replacement cycle clustering.
Underlying measurement precision varies by segment; diesel unit forecasts carry tighter precision given established fleet composition data, while solar-hybrid projections reflect wider uncertainty bands around battery cost trajectories. Forecasts reflect assumptions on EPA enforcement consistency and lithium supply chain stability. A small set of named triggers—CARB rulemaking acceleration, Texas grid interconnection delays, Canadian oil sands production cuts—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Bucket Teeth and Tips Market
Construction Equipment
Middle-East and Africa Anchors and Grouts Market
Construction Equipment
Hexagonal Wire Netting Machine Market
Construction Equipment
Metal Machinery Market
Construction Equipment
Concrete Placing Booms Market
Construction Equipment
United States Crane Market
Construction Equipment
Pressure Vessel Market
Construction Equipment
Utility Locator Market
Construction Equipment
Europe Air Compressor Market
Construction Equipment
Plasma Welding Machine Market
Construction Equipment
Earthmoving Equipment Undercarriage Market
Construction Equipment
Self-Drilling Screws Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
Shot Peening Machine Market
Construction Equipment
Soil Compaction Equipment Market
Construction Equipment
Global Pile Driving Equipment Market