
 United Kingdom Architectural Coatings Market | 2026-2036
United Kingdom Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Architectural Coatings Market Analytics
Waterborne polymer technology is reshaping formulation priorities across the United Kingdom architectural coatings sector. AkzoNobel N.V. leverages its decorative paints heritage to dominate premium interior segments through controlled distribution networks. PPG Industries, Inc. competes on specification-grade exterior systems for commercial facades. Hempel A/S specializes in high-performance protective coatings that extend building envelope lifecycles in marine-exposed coastal regions.
Architectural coatings comprise pigmented liquid or powder films applied to building substrates for decoration, protection, and functional performance, typically formulated with binders such as acrylic or alkyd resins at solids contents ranging from thirty to sixty percent depending on application method. Water-based formulations lead volume across residential application due to tightened volatile organic compound limits, while solvent-based alkyd systems retain share in industrial and institutional maintenance where durability requirements exceed aqueous performance thresholds. Acrylic formulations command margin pools in new-build commercial projects specified by architects seeking color stability and weathering resistance.
The Health and Safety Executive enforces UK REACH substance restrictions inherited from EU frameworks, while the Building Safety Regulator imposes fire-performance labeling under the Building Safety Act. These frameworks compel reformulation investment and third-party certification expenditure that smaller blenders struggle to absorb. Stakeholders must monitor divergence between UK and EU chemical regimes as retained law amendments proceed through parliamentary consultation.
Market Dynamics
Waterborne polymer systems are compressing solvent-based alkyd capacity across United Kingdom manufacturing plants as REACH substance restrictions tighten volatile organic compound thresholds. Property developers in Greater London and the South East corridor now specify low-emission formulations as standard, forcing reformulation investment through the supply base.
Growth Catalysts
- Building Safety Act enforcement:Fire-performance labeling mandates under the Building Safety Regulator are accelerating specification of certified intumescent coatings in high-rise residential schemes.
- Commercial facade refurbishment:Aging building stock in Manchester and Birmingham city centers is driving protective recoating cycles for weathered concrete and metal substrates.
- Marine-exposed coastal demand:Hempel A/S and specialist protective manufacturers are capturing specification-grade projects in Plymouth, Southampton, and Hull port zones.
Market Restraints
- Titanium dioxide feedstock volatility:Pigment cost swings from Chinese and Ukrainian suppliers are compressing margin pools for mid-tier blenders without captive supply.
- UK REACH divergence risk:Parliamentary amendments to retained EU chemical law are creating dual-registration burdens for formulators serving both British and continental markets.
- Solvent-based performance ceiling:Aqueous acrylic systems still fail durability thresholds for industrial maintenance in heavy manufacturing environments.
Strategic Opportunities
- Scottish housing expansion:Edinburgh and Glasgow affordable housing schemes remain underpenetrated by premium decorative brands relative to English markets.
- Carbon-accounting specification:Embodied carbon disclosure requirements under UK Building Regulations are creating first-mover advantage for Environmental Product Declaration holders.
- Digital color matching:Spectrophotometer-linked tinting systems in trade distribution are reducing waste and accelerating project turnaround for contractor segments.
Industry Challenges
- Formulation chemist scarcity:Polymer science expertise capable of balancing VOC compliance with durability performance commands premium compensation and long recruitment cycles.
- Third-party certification backlog:British Standards Institution and other notified bodies face extended lead times for fire-resistance testing, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Architectural Coatings Market |
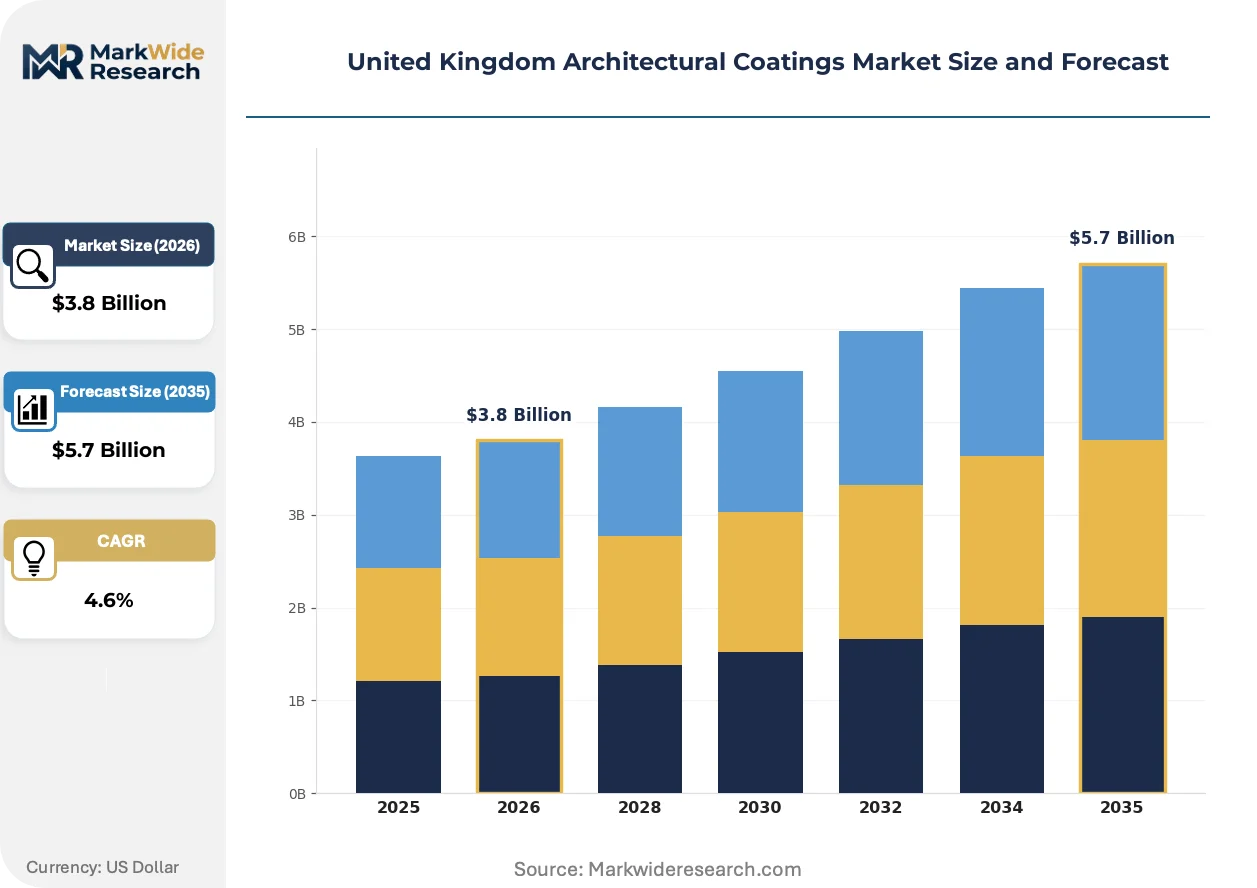
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water-Based, Solvent-Based, Powder Coatings, Specialty Coatings Application: Residential, Commercial, Industrial, Institutional Formulation: Acrylic, Alkyd, Epoxy, Polyurethane End User: Architects, Contractors, Homeowners, Property Developers |
| Companies Covered | AkzoNobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Jotun A/S, RPM International Inc., BASF SE, Hempel A/S, DAW SE, Beckers Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Architectural Coatings Market Evolving Landscape
United Kingdom architectural coatings are pivoting toward performance-verified, low-carbon systems as procurement teams embed lifecycle assessment into specification criteria. Three developments are compressing legacy formulation and distribution models.
Photocatalytic titanium dioxide additives are enabling self-cleaning facade coatings that degrade airborne pollutants through UV-activated oxidation. Commercial developers in Canary Wharf and Manchester Spinningfields are specifying these systems for premium office assets. The technology is migrating from demonstration projects to standard specification in BREEAM Outstanding-rated developments, compressing conventional acrylic maintenance coating volumes.
UK REACH substance restrictions inherited from ECHA frameworks are tightening authorization requirements for chromium-based corrosion inhibitors and certain isocyanate hardeners. The Health and Safety Executive is accelerating substance evaluation timelines that exceed EU counterparts. Industrial maintenance contractors in Teesside chemical processing clusters are stockpiling legacy formulations while qualifying zinc-rich epoxy alternatives.
Direct-to-contractor digital platforms are disintermediating traditional merchant distribution for standard decorative products. National housebuilders are consolidating procurement through centralized specification portals that bypass regional distributor networks. This pattern concentrates in volume residential schemes across the South East and Midlands where standardized color palettes dominate.
United Kingdom Architectural Coatings Market Segmentation
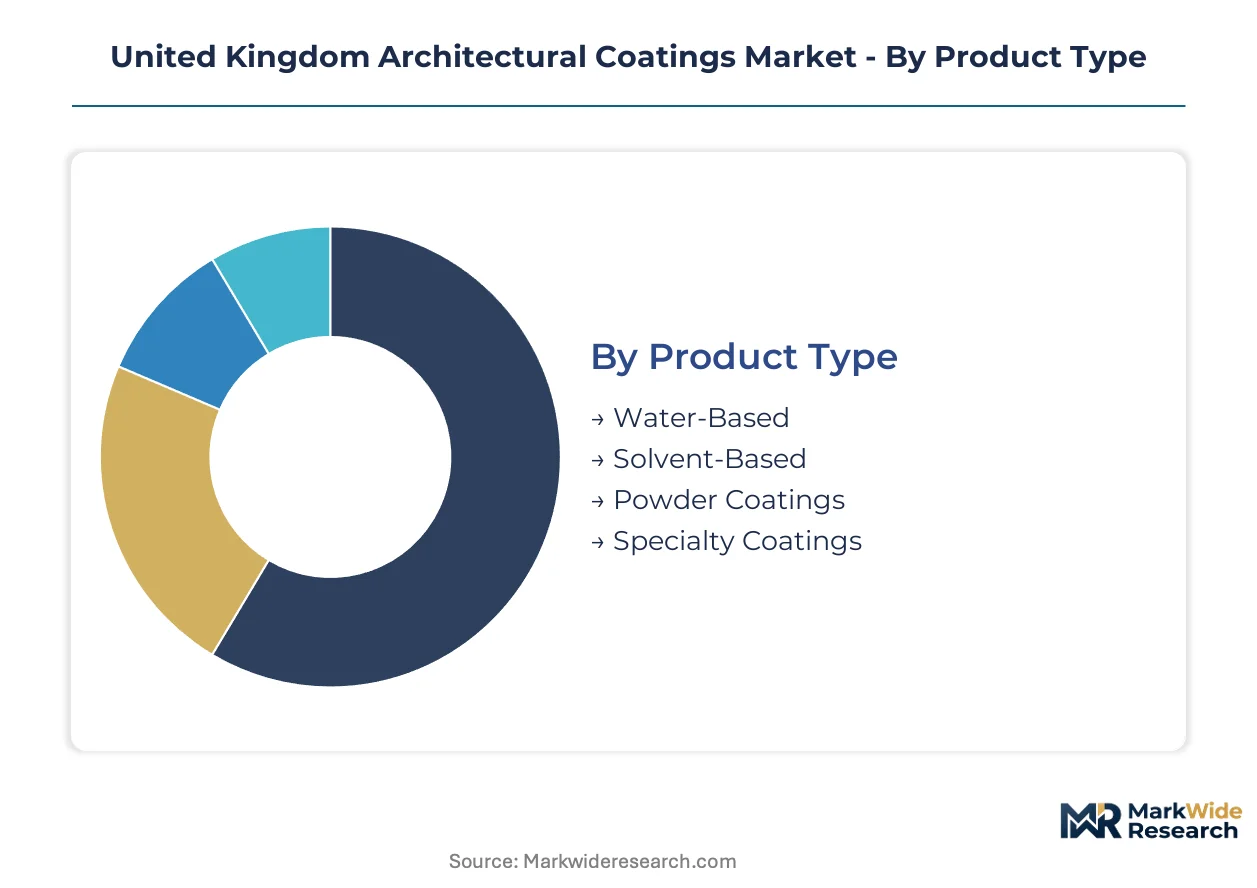
Architectural coatings segmentation in the United Kingdom reflects divergent technical requirements across building lifecycle stages. Specification authority varies sharply by end-user type, dictating margin capture and reformulation investment priorities.
Product Type:
After-sales service intensity runs highest in specialty systems requiring applicator certification and warranty support, lowest in commodity decorative products.
- Water-Based:Acrylic and vinyl acetate emulsions dominate interior residential specification under Health and Safety Executive VOC thresholds. Greater London housing schemes now mandate these formulations as baseline, compressing solvent-based volumes through the supply base.
- Solvent-Based:Alkyd and urethane systems retain industrial maintenance share where aqueous durability falls short. Teesside chemical processing clusters and heavy manufacturing facilities in the Midlands specify these for corrosion resistance exceeding waterborne performance ceilings.
- Powder Coatings:Thermoset polyester and epoxy powders serve metal cladding and window frame fabrication with zero VOC profiles.
- Specialty Coatings:Intumescent fire-protection and photocatalytic self-cleaning systems command specification-grade pricing in high-rise residential and BREEAM Outstanding commercial assets.
Water-Based holds the largest share; momentum sits with Specialty Coatings.
Application:
Cost tier stratification separates premium specification-grade systems from maintenance recoating commodities.
- Residential:New-build and refurbishment demand concentrates in the South East corridor where housing starts outpace northern regions. Homeowner DIY segments favor water-based decorative paints through trade merchant channels.
- Commercial:Facade refurbishment cycles in Manchester and Birmingham city centers drive protective recoating specification. Canary Wharf and Manchester Spinningfields developers are embedding lifecycle assessment criteria into procurement.
- Industrial:Heavy manufacturing environments in the Midlands and Teesside require solvent-based alkyd and epoxy systems for substrate protection.
- Institutional:Healthcare and education facilities specify low-emission formulations under Building Safety Regulator fire-performance mandates.
Residential captures the greatest volume; commercial refurbishment is climbing the fastest.
Formulation:
Application method dictates solids content and rheology requirements across roller, spray, and brush deposition.
- Acrylic:Thermoplastic emulsions command margin pools in architect-specified new-build commercial projects seeking color stability and UV resistance. South East commercial schemes specify these for weathering performance.
- Alkyd:Oil-modified polyester resins retain industrial maintenance share where hardness and gloss retention exceed aqueous capabilities.
- Epoxy:Two-component amine-cured systems serve high-performance protective applications in coastal and chemical-exposed environments.
- Polyurethane:Aliphatic and aromatic isocyanate systems provide abrasion resistance for flooring and exterior metal substrates.
Acrylic leads specification value; epoxy is gaining share fastest in marine-exposed zones.
End User:
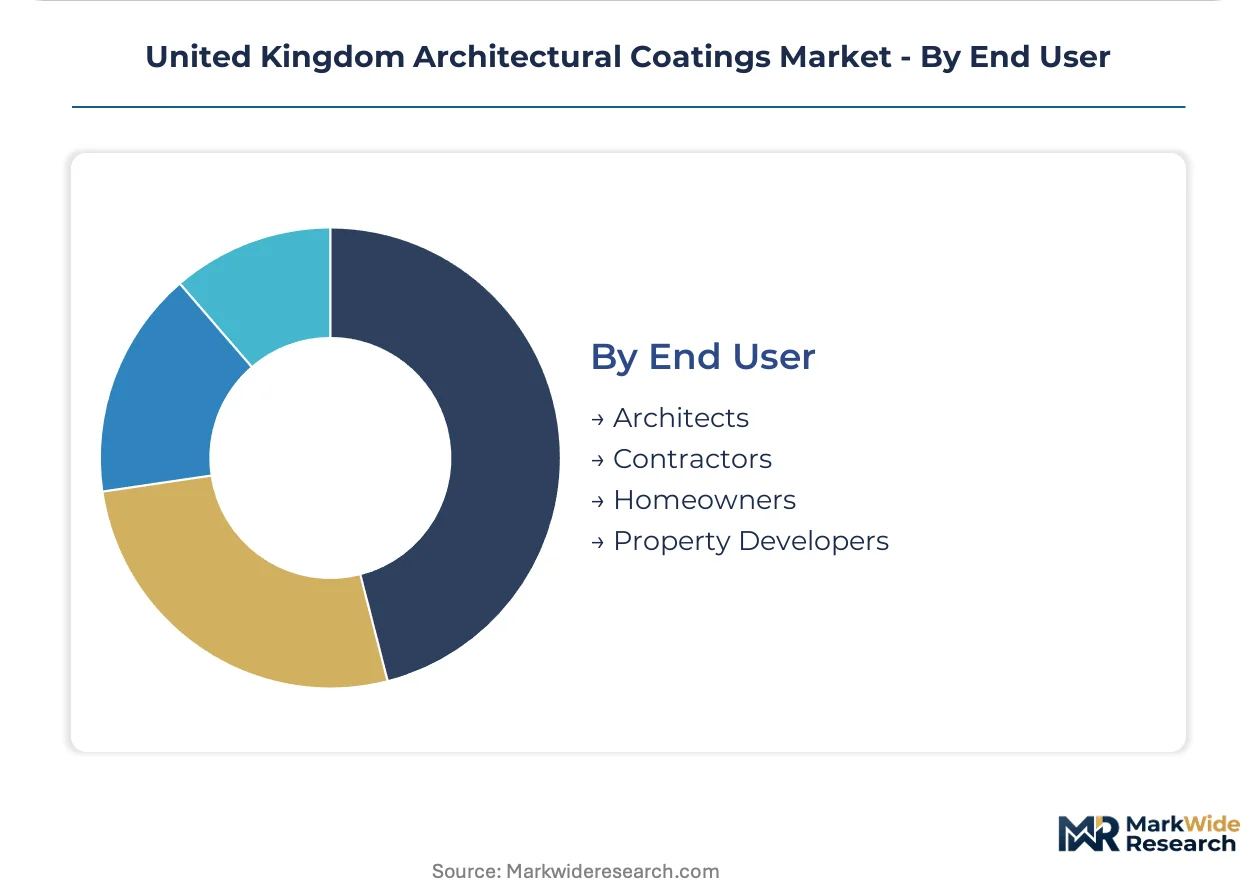
Customer type determines specification authority and price elasticity across the procurement chain.
- Architects:Design-phase specification of premium systems for commercial and high-rise residential schemes concentrates in London practices serving BREEAM-rated developments.
- Contractors:Trade applicators purchase through merchant distribution for residential refurbishment and maintenance cycles.
- Homeowners:DIY segments drive volume in standard decorative products through retail and digital channels.
- Property Developers:National housebuilders consolidate procurement through centralized specification portals, disintermediating regional distributors in volume South East schemes.
Contractors represent the largest procurement volume; property developers are driving the steepest channel consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch and German coating manufacturers export waterborne systems through the Port of Rotterdam into British distribution networks serving Greater London housing schemes.
Greater London and South East
Canary Wharf commercial developers specify photocatalytic self-cleaning facades for BREEAM Outstanding assets. The Building Safety Regulator enforces fire-performance labeling mandates under the Building Safety Act. Manchester Spinningfields clusters drive protective recoating demand for weathered concrete substrates.
Midlands
Birmingham city center refurbishment cycles consume specification-grade exterior systems for aging commercial stock. UK REACH substance restrictions inherited from ECHA frameworks tighten chromium-based corrosion inhibitor authorizations. Teesside chemical processing clusters stockpile legacy solvent-based formulations while qualifying zinc-rich epoxy alternatives.
North England
Manchester housing starts outpace Liverpool and Leeds in new-build residential volume. The Health and Safety Executive enforces VOC thresholds that compress alkyd capacity across regional manufacturing plants. Sheffield and Leeds industrial zones specify solvent-based urethane systems where aqueous durability falls short.
Scotland
Edinburgh and Glasgow affordable housing schemes remain underpenetrated by premium decorative brands relative to English markets. Scottish Building Standards embed fire-safety requirements that diverge from English frameworks. Aberdeen coastal exposure drives specification of Hempel A/S protective systems for marine-degraded substrates.
Wales and Northern Ireland
Cardiff commercial refurbishment lags London and Manchester in specification-grade coating adoption. Welsh Government procurement guidelines prioritize low-emission formulations for public sector construction. Belfast housing associations consolidate decorative purchasing through centralized portals bypassing regional merchant networks.
United Kingdom Architectural Coatings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement structures. The vendor base separates into consolidated multinational formulators and mid-cap regional blenders. Three archetypes dominate: heritage decorative brands with distribution lock-in, specification-grade protective specialists, and merchant-dependent commodity suppliers. Competitive moves concentrate on digital platform consolidation and third-party certification acquisition.
Within the heritage decorative tier, AkzoNobel N.V. and DAW SE occupy positions anchored by controlled distribution networks. Among specification-grade protective manufacturers, Hempel A/S exemplifies the marine-exposed coastal specialist archetype. PPG Industries, Inc. sits within the commercial facade systems segment serving architect-specified new-build projects.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Jotun A/S |
| RPM International Inc. |
| BASF SE |
| Hempel A/S |
| DAW SE |
| Beckers Group |
| Others |
Value Network & Pricing Analysis
Teesside chemical processing clusters anchor titanium dioxide and alkyd resin supply for United Kingdom formulators, concentrating upstream pricing power among pigment manufacturers while downstream blenders absorb volatility through contract structures. This geographic concentration of feedstock processing translates directly into margin pressure for mid-tier decorative coating suppliers serving Greater London housing schemes.
Pricing Analysis
Waterborne acrylic emulsions command a 15-25% premium over solvent-based alkyd equivalents in architect-specified commercial projects, while commodity decorative tiers compete on volume scale through centralized procurement portals. Price differentiation hinges on Environmental Product Declaration certification and third-party fire-performance testing under Building Safety Regulator mandates. Cost compression in mid-tier decorative segments is intensifying because national housebuilders are consolidating specification authority through direct-to-contractor digital platforms. DIY homeowners exhibit highest price sensitivity, whereas BREEAM-rated commercial developers prioritize lifecycle performance over unit cost.
Supply Chain Analysis
Upstream titanium dioxide feedstock draws from Chinese and Ukrainian suppliers, with acrylic monomer and alkyd resin intermediates sourced from Dutch and German petrochemical complexes through Rotterdam port distribution. Raw material dependencies center on ilmenite ore processing, naphtha derivatives, and corrosion-inhibiting zinc pigments. Single-source vulnerability concentrates in chromium-based additives facing UK REACH authorization restrictions. Distribution runs through merchant trade networks for residential decorative products, while specification-grade protective coatings deploy direct technical sales to project developers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated national housebuilders and centralized procurement portals, fragmenting traditional distributor influence across volume residential segments in the South East corridor.
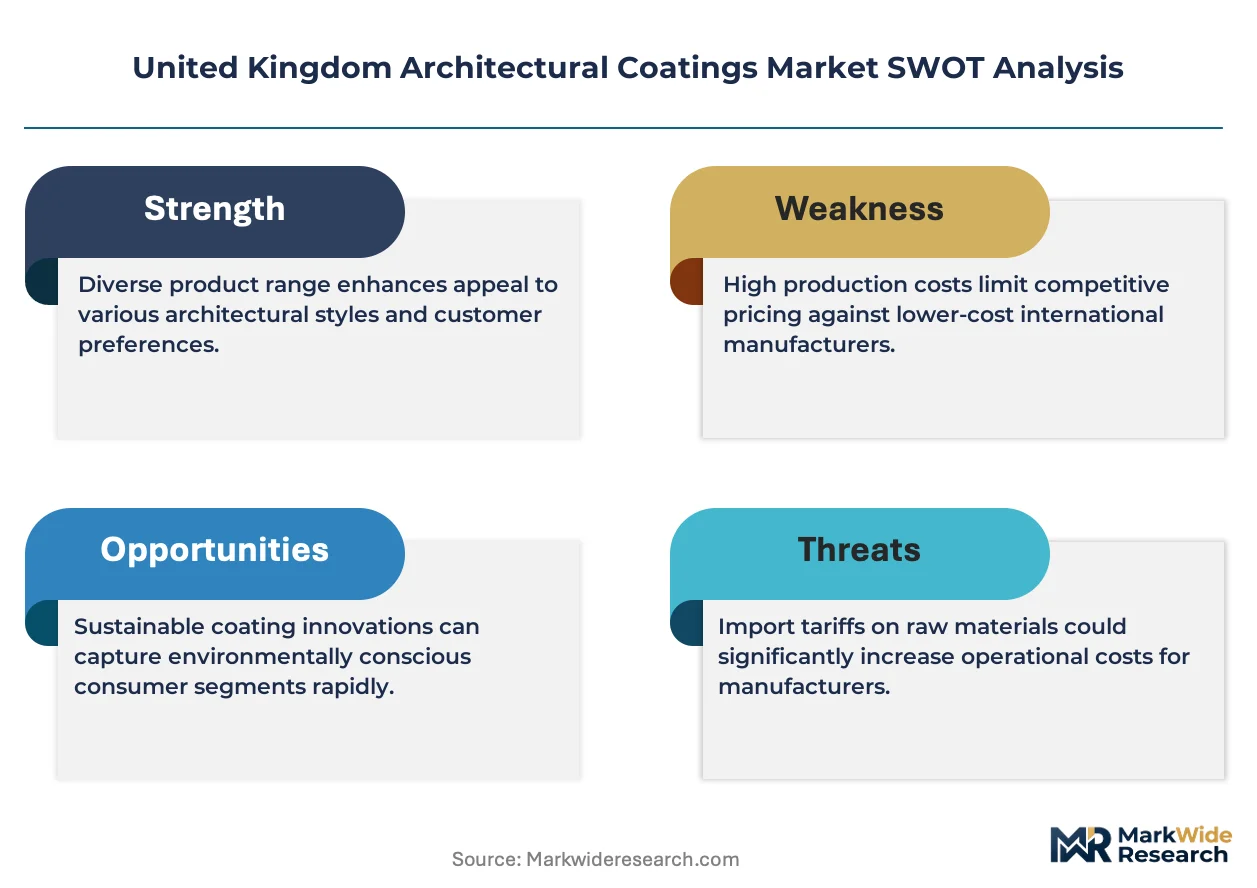
For Market Incumbents: Harden specification-grade positioning through captive supply of titanium dioxide feedstock and accelerated Environmental Product Declaration certification for BREEAM-rated commercial projects. Threat substitution from photocatalytic self-cleaning facade systems demands R&D investment in UV-activated coating technologies. Channel control through spectrophotometer-linked tinting systems in trade distribution preserves contractor loyalty against digital platform disintermediation. For New Entrants and Emerging Players: Establish a beachhead in Scottish affordable housing schemes where premium decorative brands remain underpenetrated relative to English markets. White-space targets include Edinburgh and Glasgow new-build residential volume and marine-exposed coastal protective coatings for Aberdeen port infrastructure. A go-to-market angle anchored in carbon-accounting specification under UK Building Regulations creates first-mover advantage against heritage decorative incumbents. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because mid-tier blenders without captive titanium dioxide supply face unsustainable margin compression from feedstock volatility and dual-registration burdens under UK REACH divergence. Acquisition targets include regional protective coating specialists with zinc-rich epoxy qualifications and established Health and Safety Executive compliance infrastructure. The signal to watch is parliamentary amendment timelines for retained EU chemical law, which will determine registration cost barriers for cross-channel formulators.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Titanium Dioxide Feedstock | Captive pigment supply insulates margin pools from Chinese and Ukrainian price volatility for mid-tier blenders. |
| Environmental Product Declaration Certification | Certification holders capture specification premium in BREEAM Outstanding commercial developments across Canary Wharf and Manchester Spinningfields. |
| Digital Color Matching Platform Deployment | Spectrophotometer-linked tinting systems reduce waste and accelerate project turnaround for South East contractor segments. |
| Zinc-Rich Epoxy Formulation Qualification | Teesside chemical processing clusters stockpile legacy chromium-based systems while qualifying REACH-compliant alternatives. |
| Scottish Market Distribution Expansion | Edinburgh and Glasgow affordable housing schemes remain underpenetrated by premium decorative brands relative to English markets. |
Research Methodology
The analysis maps water-based decorative, solvent-based industrial, powder coating, and specialty intumescent segments, each validated through formulation chemists, procurement leads at national housebuilders, merchant distribution partners, and technical R&D directors at protective coating manufacturers. Primary interviews combined with secondary validation from UK REACH substance registration databases, Health and Safety Executive enforcement notices, Building Safety Regulator guidance documents, and British Standards Institution certification records. Bottom-up project pipeline assessment and top-down construction output triangulation anchored volume estimates.
Assumptions held fixed include UK REACH regulatory divergence trajectory and Building Safety Act enforcement intensity, while housing start volatility and titanium dioxide feedstock price swings were modeled as scenario variables. Segmentation dimensions span product type, application method, formulation chemistry, and end-user specification authority. CAGRs were derived from construction output forecasts cross-referenced with coating intensity per square meter across residential, commercial, and industrial building stock. Industry-specific inputs incorporated VOC threshold compliance timelines and third-party fire-resistance testing backlog durations.
Sensitivities concentrate around parliamentary amendment schedules for retained EU chemical law and Health and Safety Executive substance evaluation acceleration. Forecasts reflect these assumptions with acknowledged revision risk from feedstock supply disruption or regulatory divergence exceeding modeled scenarios. Quarterly review of UK REACH authorization timelines and national housing start data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
West Africa Cement Market
Building Materials
Door Frame Metal Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Germany Aluminum Door and Window Market
Building Materials
India Concealed Cistern Market
Building Materials
Composite Rebar Market
Building Materials
India Cement Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Dutch Brick Market
Building Materials
Cladding Market
Building Materials
Lightweight Precast Wall Panel Market
Building Materials
Europe Exterior Sheathing Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market
Building Materials
Concrete Blocks and Bricks Market