
 Saudi Arabia Sanitaryware Market | 2026-2036
Saudi Arabia Sanitaryware Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Sanitaryware Market Analytics
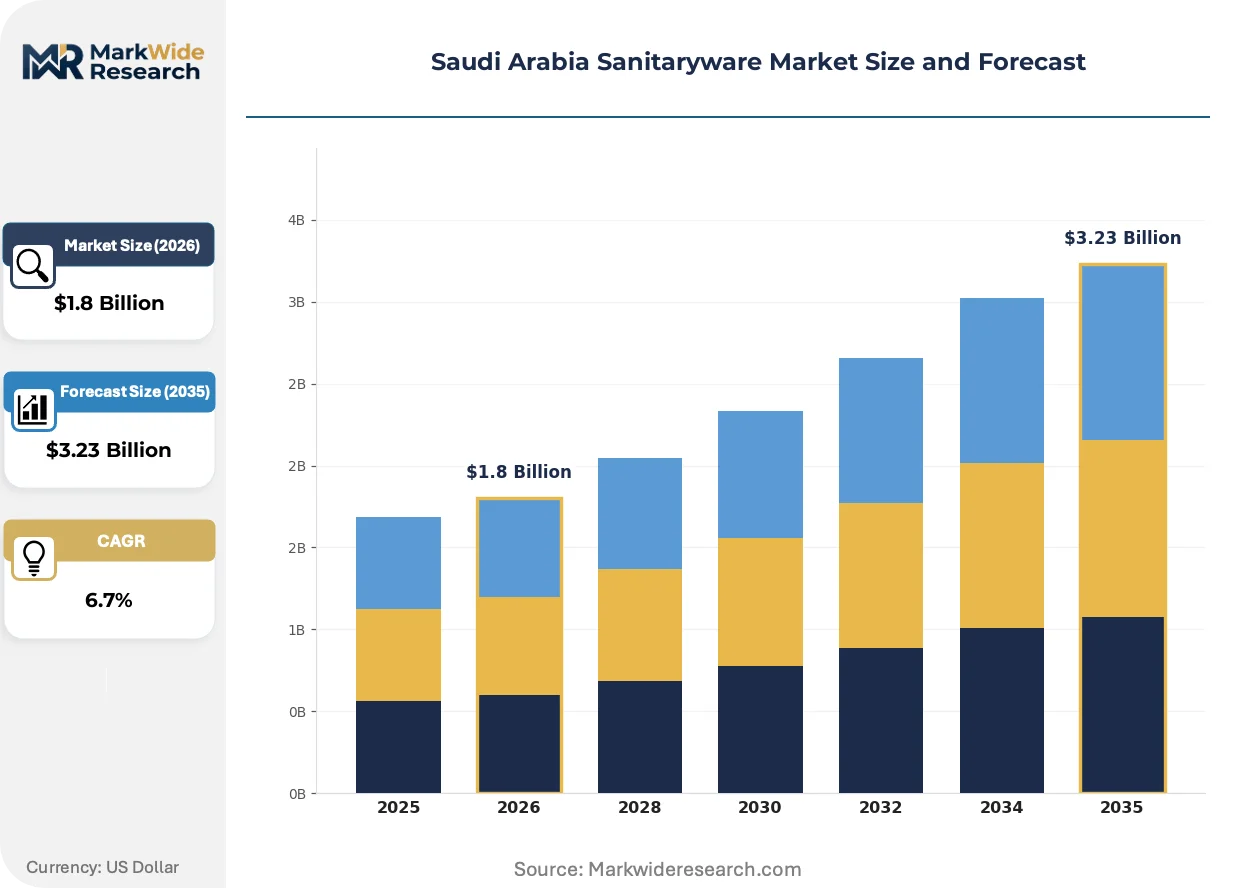
SFDA technical regulations for construction material safety is restructuring the cost-of-entry calculus for sanitaryware imports and local manufacturing alike. Saudi Ceramics leverages captive production of vitreous china to sustain price competitiveness against regional rivals. RAK Ceramics anchors its Gulf position through specialized distribution networks spanning Saudi Arabia's major urban corridors. Forsan Ceramics differentiates via integrated clay-to-firing operations that control input cost volatility.
Sanitaryware encompasses vitreous ceramic fixtures—primarily toilets, sinks, bathtubs, and showers—manufactured through slip casting or pressure casting of kaolin-based bodies, followed by glazing and kiln firing at temperatures exceeding 1,200°C to achieve non-porous, hygienic surfaces essential for water-efficient waste disposal and personal hygiene. Ceramic and porcelain materials dominate value capture due to durability premiums and SASO compliance alignment, while acrylic gains traction in hospitality renovations seeking lighter-weight installation logistics. The residential end-user segment occupies the volume base, though hospitality procurement commands disproportionate margin pools tied to custom design specifications and bulk contract structures.
SASO enforcement of water-efficiency labeling and the Saudi Building Code's fixture performance standards are tightening product eligibility for market access, compelling manufacturers to recalibrate glaze formulations and flush mechanisms. The Ministry of Municipal and Rural Affairs mandates govern public infrastructure procurement, channeling demand toward certified suppliers with established local testing documentation. Stakeholders must monitor evolving green building criteria under the Saudi Green Building Forum as these frameworks increasingly embed into NEOM and Red Sea Project developer specifications.
Market Dynamics
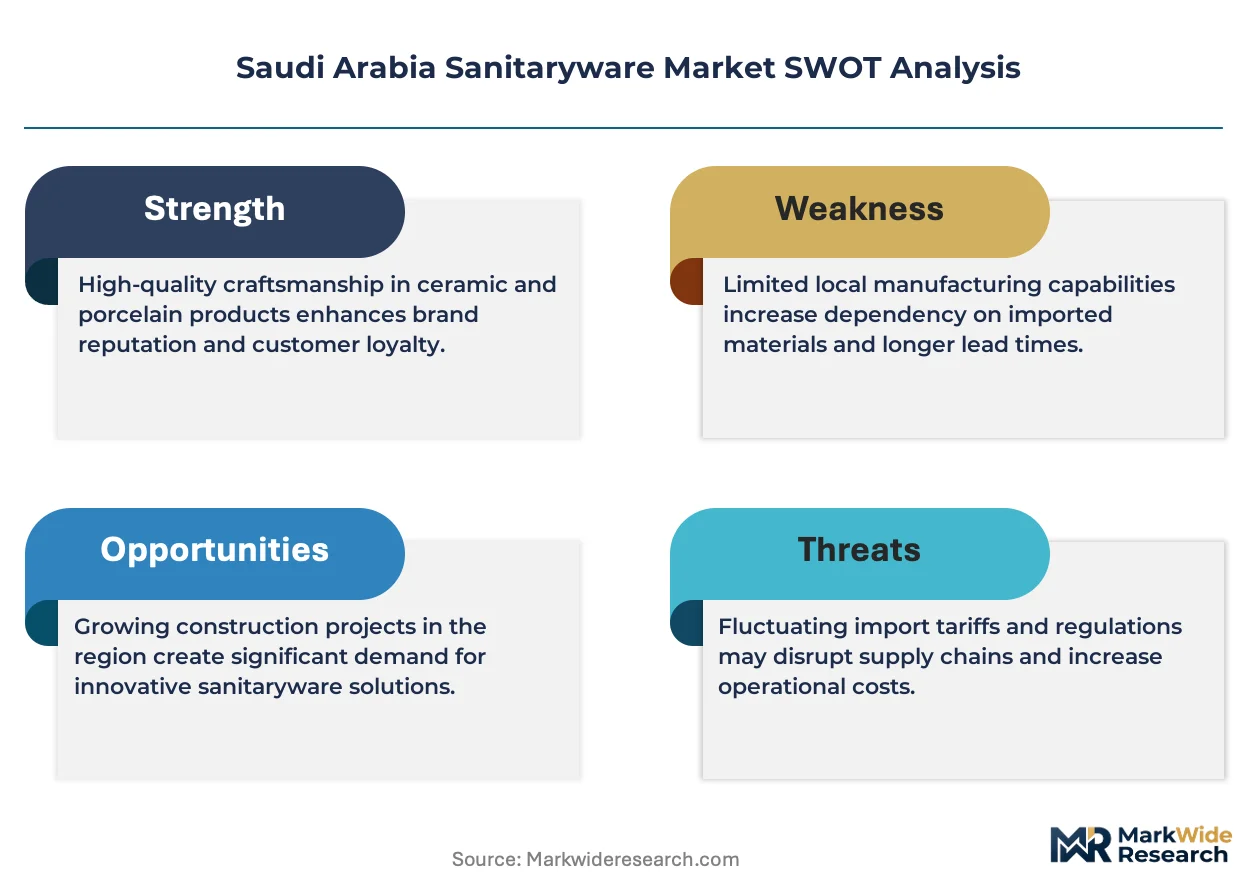
SFDA technical regulations for construction material safety is restructuring the cost-of-entry calculus for sanitaryware imports and local manufacturing alike, compressing margins for non-compliant suppliers while rewarding certified domestic producers with preferential access to public procurement channels.
Growth Catalysts
- NEOM and Red Sea Project pipelines:Megaproject developers are specifying water-efficient fixtures at scale, creating concentrated demand for certified suppliers with local testing documentation.
- SASO water-efficiency labeling mandates:The Saudi Standards, Metrology and Quality Organization is tightening product eligibility thresholds, channeling procurement toward compliant manufacturers.
- Vitreous china durability premiums:Kaolin-based ceramic formulations firing above 1,200°C are capturing specification preference in hospitality and high-end residential segments.
Market Restraints
- Raw material input volatility:Kaolin and feldspar price swings from Southeast Asian suppliers are compressing margin predictability for slip-casting operations.
- Distribution network concentration:Specialized sanitaryware distribution in Riyadh and Jeddah corridors is controlled by a limited pool of established channel partners.
- Acrylic substitution in hospitality renovations:Lighter-weight installation logistics are displacing ceramic specifications in select hotel refurbishment contracts.
Strategic Opportunities
- Central Region sub-regional penetration:Secondary urban centers beyond Riyadh's core present underdeveloped specification channels for water-efficient fixture suppliers.
- Saudi Green Building Forum integration:Evolving green building criteria are embedding into developer specifications, creating certification-driven preference advantages.
- Pressure casting automation convergence:Digital mold control systems combined with robotic glazing lines are enabling quality consistency at reduced labor intensity.
Industry Challenges
- Glaze formulation recalibration timelines:SFDA compliance requirements are forcing extended R&D cycles for flush mechanism and surface chemistry adjustments.
- Skilled kiln technician scarcity:High-temperature firing expertise for vitreous china production is concentrated among aging workforce cohorts with limited apprenticeship pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Sanitaryware Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Toilets, Sinks, Bathtubs, Showers Material: Ceramic, Porcelain, Acrylic, Glass End User: Residential, Commercial, Industrial, Hospitality Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | Arabian Company for Ceramics, Casa Via, Saudi Ceramics, Kohler, Porsalina Ceramics, Forsan Ceramics, Geberit International, Roca Sanitario, RAK Ceramics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Sanitaryware Market Evolving Landscape
Digital manufacturing controls and regulatory tightening are converging to reshape competitive positioning in Saudi sanitaryware, with specification power shifting toward suppliers capable of demonstrating compliance documentation and water-efficiency performance at the point of procurement.
Pressure casting automation is rewriting production economics for complex fixture geometries. Hospitality developers in Jeddah are specifying digitally-controlled molds for custom basin designs at accelerating pace. This technology is compressing lead times for bespoke orders while reducing defect rates in high-value contract manufacturing.
SASO enforcement of water-efficiency labeling is tightening product eligibility for market access. Manufacturers are recalibrating glaze formulations and flush mechanisms to maintain compliance. The residential segment is responding fastest, with volume builders integrating certified fixtures as standard specification to preempt procurement disqualification.
Buyer concentration among megaproject developers is consolidating specification authority. Traditional distributor networks are facing disintermediation pressure as direct manufacturer relationships with NEOM and Red Sea Project procurement teams proliferate. This pattern is most visible in Riyadh's commercial construction corridor, where developer-led tendering now dominates high-value sanitaryware procurement.
Saudi Arabia Sanitaryware Market Segmentation
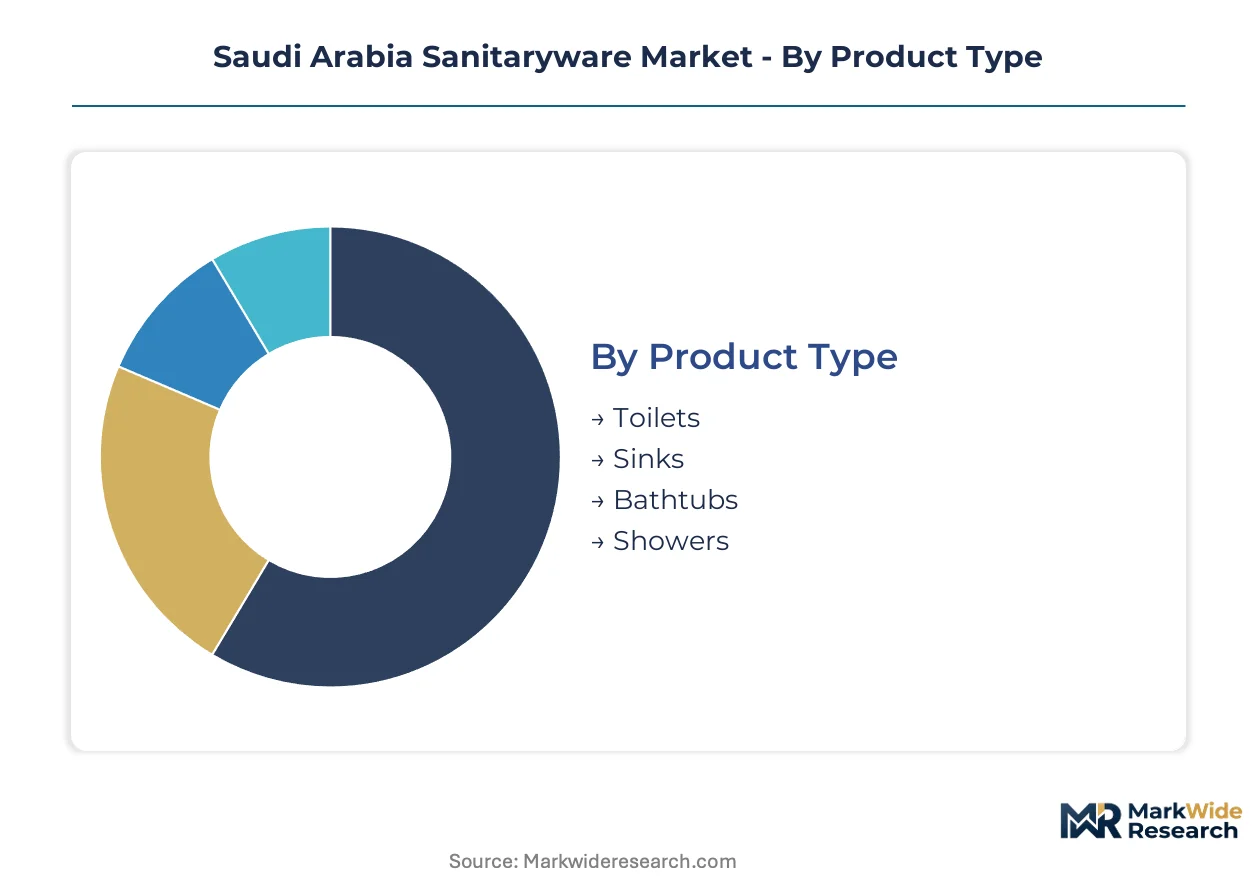
Sanitaryware procurement in Saudi Arabia fragments across specification hierarchies that separate volume residential builders from premium hospitality developers. Material certification thresholds and water-efficiency mandates are reshaping how each segment captures margin pools.
Product Type:
Toilets dominate unit volumes while bathtubs command premium pricing tiers in hospitality specifications.
- Toilets:Water closets and bidets manufactured through pressure casting of vitreous china bodies, achieving non-porous surfaces above 1,200°C firing temperatures. NEOM and Red Sea Project developers are specifying dual-flush mechanisms at scale, channeling procurement toward SASO-certified suppliers with local testing documentation.
- Bathtubs:Freestanding and built-in soaking fixtures requiring complex mold geometries and extended kiln cycles. Jeddah's luxury hotel pipeline favors custom vitreous china designs over acrylic alternatives, sustaining margin premiums for specialized manufacturers.
- Sinks:Washbasins and pedestal designs spanning compact residential formats to expansive hospitality vanities.
- Showers:Enclosures, trays, and fixture systems integrating drainage and thermostatic controls.
Today's leader: Toilets. Tomorrow's challenger: Bathtubs.
Material:
Ceramic formulations anchor compliance-aligned procurement while acrylic gains selective traction in renovation logistics.
- Ceramic:Kaolin-based vitreous china fired above 1,200°C delivers non-porous durability essential for SASO water-efficiency certification. Riyadh's megaproject pipeline specifies ceramic exclusively for new construction, cementing its position in high-volume procurement channels.
- Porcelain:Higher-density ceramic variants with refined clay bodies and superior glaze adhesion. Central Region hospitality developers specify porcelain for premium fixture lines, capturing specification preference through enhanced stain resistance and surface hardness.
- Acrylic:Thermoformed polymer alternatives offering lighter-weight installation and faster renovation turnaround.
- Glass:Tempered vessel sinks and accent pieces serving niche contemporary design specifications.
Ceramic holds the volume base. Acrylic is climbing fastest in refurbishment segments.
End User:
Residential builders drive unit economics while hospitality procurement concentrates margin extraction.
- Residential:Volume housing construction across Riyadh's northern expansion and Jeddah's suburban corridors. SFDA compliance requirements are pushing volume builders toward pre-certified fixture packages to preempt procurement disqualification.
- Hospitality:Hotel and resort developments specifying custom designs with bulk contract structures. Red Sea Project developers are consolidating specification authority through direct manufacturer relationships, bypassing traditional distributor networks.
- Commercial:Office and retail installations governed by Ministry of Municipal and Rural Affairs procurement mandates.
- Industrial:Worker accommodation and facility sanitation with standardized durability requirements.
Residential commands the unit count. Hospitality commands the margin pool.
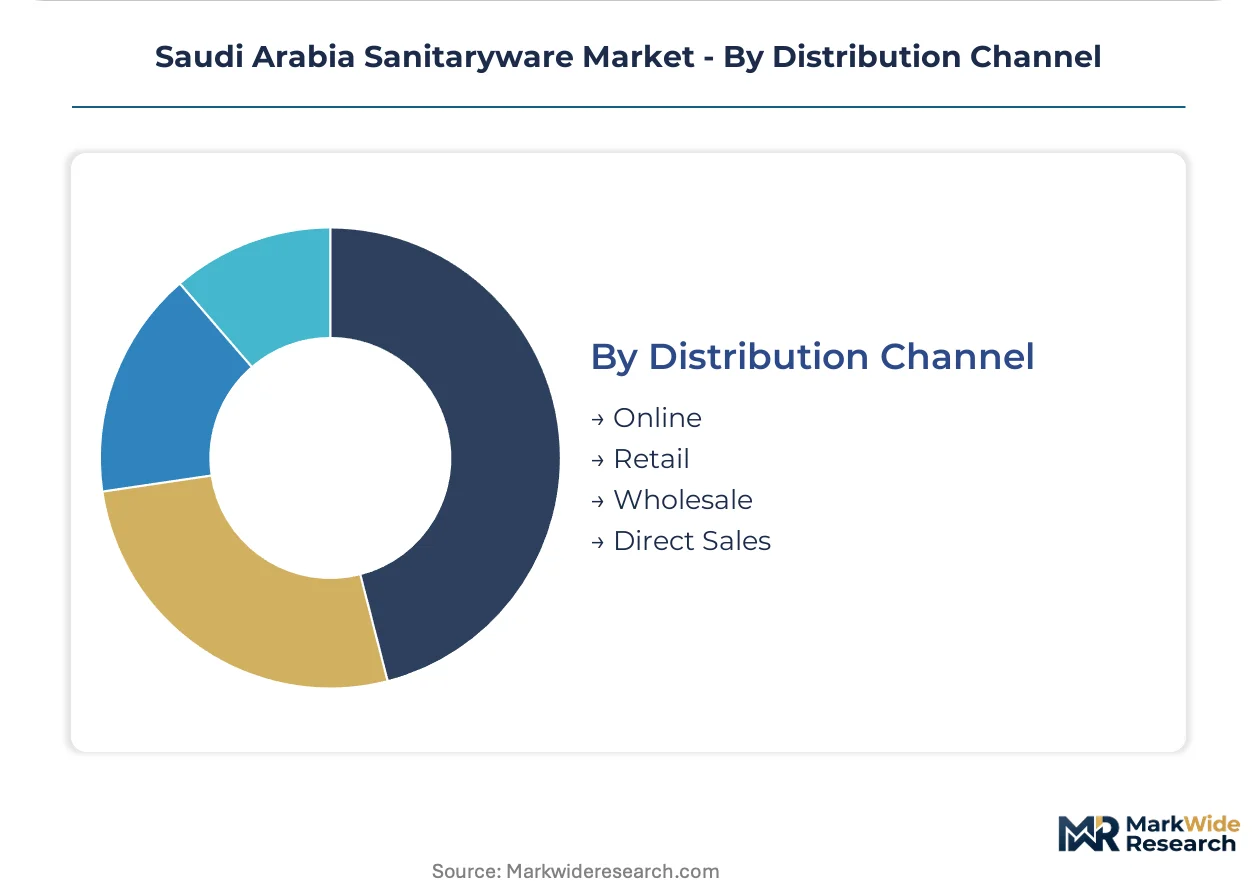
Distribution Channel:
Wholesale networks retain construction-phase dominance while direct sales erode distributor margins in megaproject corridors.
- Wholesale:Specialized sanitaryware distributors controlling Riyadh and Jeddah supply corridors. These established channel partners maintain specification influence with mid-tier contractors and regional builders.
- Direct Sales:Manufacturer relationships with NEOM and Red Sea Project procurement teams. This channel is expanding fastest as developer-led tendering consolidates high-value contract authority.
- Retail:Showroom-based specification for residential renovation and replacement demand.
- Online:Digital procurement platforms serving smaller contractors and accessory replacement markets.
Wholesale anchors current volume. Direct sales is gaining share fastest in premium segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's sanitaryware industry traces its manufacturing roots to the Central Region's clay deposits and Riyadh's emergence as a construction materials hub during the 1970s oil boom, with production scaling through state-backed industrial city programs.
Riyadh
Riyadh's northern expansion and Diriyah Gate developments are absorbing bulk sanitaryware volumes for residential and hospitality fit-outs. SASO water-efficiency labeling mandates channel procurement toward certified suppliers with local testing facilities. Second Industrial City hosts concentrated slip-casting and pressure-casting operations serving megaproject corridors.
Eastern Province
Dhahran and Dammam industrial zones supply worker accommodation and facility sanitation for Aramco-linked developments and petrochemical complexes. Ministry of Municipal and Rural Affairs procurement governs public infrastructure specifications. Jubail Industrial City maintains ceramic raw material processing clusters feeding vitreous china production.
Western Region
Jeddah's luxury hotel pipeline and Makkah pilgrimage infrastructure sustain premium fixture demand with custom design specifications. Red Sea Project developers are consolidating direct manufacturer relationships, bypassing traditional distributor networks. King Abdullah Economic City anchors specialized logistics for hospitality-grade imports.
NEOM Northwest
The LINE and Oxagon developments are specifying water-efficient fixtures at unprecedented scale for sustainable city prototypes. Saudi Green Building Forum criteria embed into developer specifications, creating certification-driven procurement filters. Trojena and Sindalah island resorts concentrate high-value contract opportunities for compliant suppliers.
Saudi Arabia Sanitaryware Market Competitive Landscape
The competitive structure tilts toward integrated domestic manufacturers with captive raw material access and established SASO certification documentation. Market concentration reflects high regulatory barriers to entry and preferential public procurement access for local producers. Two strategic archetypes dominate: vertically integrated clay-to-firing specialists and regional distributors with specialized hospitality specification relationships. Capacity expansion and direct developer engagement represent the dominant competitive moves as megaproject procurement consolidates authority.
Among Saudi-based integrated manufacturers, Saudi Ceramics and Forsan Ceramics occupy positions reflecting captive production advantages and control over input cost volatility. RAK Ceramics, a UAE-headquartered entity, anchors Gulf market presence through specialized distribution networks spanning Saudi Arabia's major urban corridors. These three exemplify the archetype tension between domestic manufacturing scale and regional distribution specialization that defines competitive positioning in compliance-intensive procurement environments.
| Leading Market Players |
|---|
| Arabian Company for Ceramics |
| Casa Via |
| Saudi Ceramics |
| Kohler |
| Porsalina Ceramics |
| Forsan Ceramics |
| Geberit International |
| Roca Sanitario |
| RAK Ceramics |
| Others |
Value Network & Pricing Analysis
Sovereign-backed producers and family-owned ceramics specialists anchor supply-side discipline in Saudi Arabia's sanitaryware sector, compressing margin volatility through captive clay reserves and long-term offtake agreements with Riyadh megaproject developers. This ownership concentration tightens pricing coordination across vitreous china grades while insulating domestic manufacturers from Southeast Asian kaolin price swings that erode importer competitiveness.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments procurement by certification grade and volume scale. SASO water-efficiency labeling tiers separate hospitality-specified porcelain from residential-grade ceramic, with price differentiation driven by glaze formulation complexity and local testing documentation. Cost compression in economy tiers intensifies as Indian and Chinese imports compete on freight-optimized delivery. Hospitality developers exhibit lowest price sensitivity, prioritizing custom basin geometries and extended warranty terms over unit cost.
Supply Chain Analysis
SFDA construction material safety certification gates market access, forcing upstream recalibration of clay sourcing and firing protocols. Saudi supply chains draw from domestic Central Region kaolin deposits, supplemented by feldspar shipments from Turkey and India. Single-source vulnerability concentrates in high-purity kaolin grades essential for vitreous china above 1,200°C firing. Distribution runs through specialized sanitaryware wholesalers in Riyadh and Jeddah corridors, though direct manufacturer relationships with NEOM procurement teams are eroding traditional channel control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's sanitaryware market functions as a geographic-arbitrage play where domestic manufacturers exploit regulatory compliance cost differentials against importers facing extended SFDA certification timelines and local testing facility requirements.
For Market Incumbents: Deepen backward integration into captive kaolin beneficiation to neutralize Southeast Asian raw material volatility. Expand pressure-casting automation in Second Industrial City to defend margin position against acrylic substitution in hospitality renovations. Prioritize SASO certification documentation investments to maintain preferential access to Ministry of Municipal and Rural Affairs procurement channels. For New Entrants and Emerging Players: Enter via secondary urban centers in the Central Region beyond Riyadh's core, where specification channels for water-efficient fixtures remain underdeveloped. Target residential volume builders seeking pre-certified fixture packages to preempt procurement disqualification under tightening SFDA mandates. Deploy direct sales teams to bypass established wholesale networks concentrated in Jeddah corridors. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale ceramics specialists with unexploited clay reserves and dormant kiln capacity. Long-term viability hinges on positioning for NEOM and Red Sea Project fixture specifications across the analysis window. Monitor Saudi Green Building Forum criteria adoption as the inflection signal for certification-driven procurement preference shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Pressure Casting Automation | Digital mold control reduces defect rates for custom hospitality basin orders in Jeddah. |
| Backward Integration into Kaolin | Captive clay reserves insulate margins from Turkish and Indian feldspar price volatility. |
| SASO Certification Investment | Local testing documentation unlocks preferential Ministry of Municipal and Rural Affairs procurement. |
| Direct Developer Engagement | Bypassing Riyadh wholesale networks captures NEOM and Red Sea Project contract authority. |
| Green Building Forum Alignment | Saudi Green Building criteria embedding secures specification advantage in sustainable city prototypes. |
Research Methodology
Multiple input streams — procurement director interviews at Riyadh megaproject developers, distributor margin structure analysis, and regulatory filing review — were reconciled to construct demand estimates. Primary discussions with ceramics plant managers, hospitality specification consultants, and Ministry of Municipal and Rural Affairs procurement officers were validated against secondary sources including SASO technical regulation databases, Saudi Industrial Development Fund project disclosures, and customs trade flow records. Bottom-up fixture demand modeling and top-down construction spend allocation were cross-referenced for triangulation.
Historical shipment volumes were benchmarked against panel input from ceramics manufacturers and wholesale distributors across the projection horizon. Segmentation dimensions modeled include product type, material grade tier, end-user category, and distribution channel structure. CAGRs were derived from fitted growth curves incorporating construction pipeline visibility, regulatory enforcement intensity, and substitution elasticity between ceramic and acrylic formulations.
Inputs from megaproject procurement teams and SASO certification registries were available through the study window; gaps in secondary urban center distributor data introduce uncertainty bands around Central Region penetration forecasts. Forecasts reflect documented assumptions regarding SFDA enforcement timelines and NEOM construction pacing. A model refresh is warranted upon material change in Saudi Green Building Forum criteria adoption or Red Sea Project developer specification shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
China Oriented Strand Board Market
Building & Construction Materials
PU Roof Window Market
Building & Construction Materials
Outside Door Handle Market
Building & Construction Materials
Timber Floor Joist Market
Building & Construction Materials
US Terracotta Cladding Market
Building & Construction Materials
Global Rainscreen Cladding Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Asia-Pacific Flanges Market
Building & Construction Materials
France Oriented Strand Board Market
Building & Construction Materials
Saudi Arabia Concealed Cistern Market
Building & Construction Materials
Building Vibration Isolation Market
Building & Construction Materials
Concrete Resurfacer Market
Building & Construction Materials
Brick Market
Building & Construction Materials
Point Fixing Glass Curtain Wall Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Ready-Mix Concrete Market