
 Welded Steel Tanks Market | 2026-2036
Welded Steel Tanks Market Size, Share, and Industry Trends Forecast 2026-2036
Welded Steel Tanks Market Insights
Direct procurement from engineering-procurement-construction firms is reconfiguring how welded steel tanks reach end users, with fabricators building dedicated project teams for lump-sum contracts. CST Industries, Inc. leverages its bolted-and-welded hybrid capabilities to anchor utility-scale water projects across the central United States. Highland Tank & Manufacturing Company, Inc. specializes in petroleum and chemical containment systems, sustaining long-term relationships with downstream refiners. Tank Connection, LLC competes through field-erection expertise, controlling installation timelines that determine total project cost for large-diameter storage.
Welded steel tanks are pressure-rated or atmospheric vessels fabricated from carbon, stainless, or alloy steel plates, joined by arc welding per API 650 and AWWA D100 standards, with shell courses typically ranging from 6 to 40 millimeters in thickness depending on hydrostatic load and seismic zone. Their primary purpose spans bulk liquid containment for petroleum, chemicals, and municipal water, where structural integrity under cyclic loading and environmental exposure is non-negotiable. Storage tanks dominate volume shipments due to standardized designs for crude oil and fire water reserves, while pressure vessels command premium margins from custom engineering for chemical processing. Stainless steel grades are gaining specification share in water treatment and food-adjacent applications where chloride resistance extends service life beyond carbon steel alternatives.
API 650 and AWWA D100 govern design, welding procedure, and hydrostatic testing in the United States, with OSHA 1910.146 confined-space provisions adding compliance cost to field maintenance cycles. EPA spill prevention rules under 40 CFR 112 mandate secondary containment and integrity testing for aboveground petroleum storage, directly shaping tank configuration and inspection frequency. Buyers must monitor evolving state-level renewable diesel mandates and hydrogen hub developments, as these fuel transitions will redirect fabrication capacity toward new pressure containment specifications and modified alloy requirements.
Market Dynamics
The welded steel tanks market faces structural pressure from tightening material specifications under EPA lead-and-copper rules and AWWA D100 standards, which are forcing fabricators to upgrade welding procedures and shell-course thickness calculations for potable water containment.
Growth Catalysts
- EPA Infrastructure Mandates:Federal drinking water infrastructure replacement programs are accelerating orders for AWWA D100-compliant welded vessels across municipal utilities.
- Permian Basin Produced Water:Oilfield brine storage requirements in Texas and New Mexico generate repeat procurement of corrosion-resistant carbon and stainless steel tanks.
- Stainless Specification Share:Chloride-resistant grades are displacing carbon steel in water treatment and food-adjacent applications where service life extension justifies material cost premiums.
Market Restraints
- Steel Plate Volatility:Carbon and alloy steel input costs fluctuate with commodity markets, compressing fabrication margins on fixed-price lump-sum contracts.
- Skilled Welder Scarcity:Certified API 650 and ASME welders concentrate in Gulf Coast fabrication clusters, creating geographic supply bottlenecks for field-erection projects.
- Concrete Tank Substitution:Prestressed concrete reservoirs compete on unit cost for large-volume water storage above 5 million gallons.
Strategic Opportunities
- Hydrogen Hub Development:Department of Energy hydrogen infrastructure funding is creating demand for high-pressure welded vessels with modified alloy specifications.
- Renewable Diesel Retrofit:State-level renewable diesel mandates are redirecting existing petroleum tank capacity toward new containment requirements.
- Direct EPC Channel:Engineering-procurement-construction firms are consolidating procurement authority, creating dedicated project team relationships with certified fabricators.
Industry Challenges
- OSHA Confined-Space Compliance:1910.146 provisions add labor cost and timeline risk to field maintenance and inspection cycles.
- Seismic Zone Engineering:Shell course thickness calculations for high-load zones require specialized structural analysis capabilities that fragment fabricator competence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Welded Steel Tanks Market |
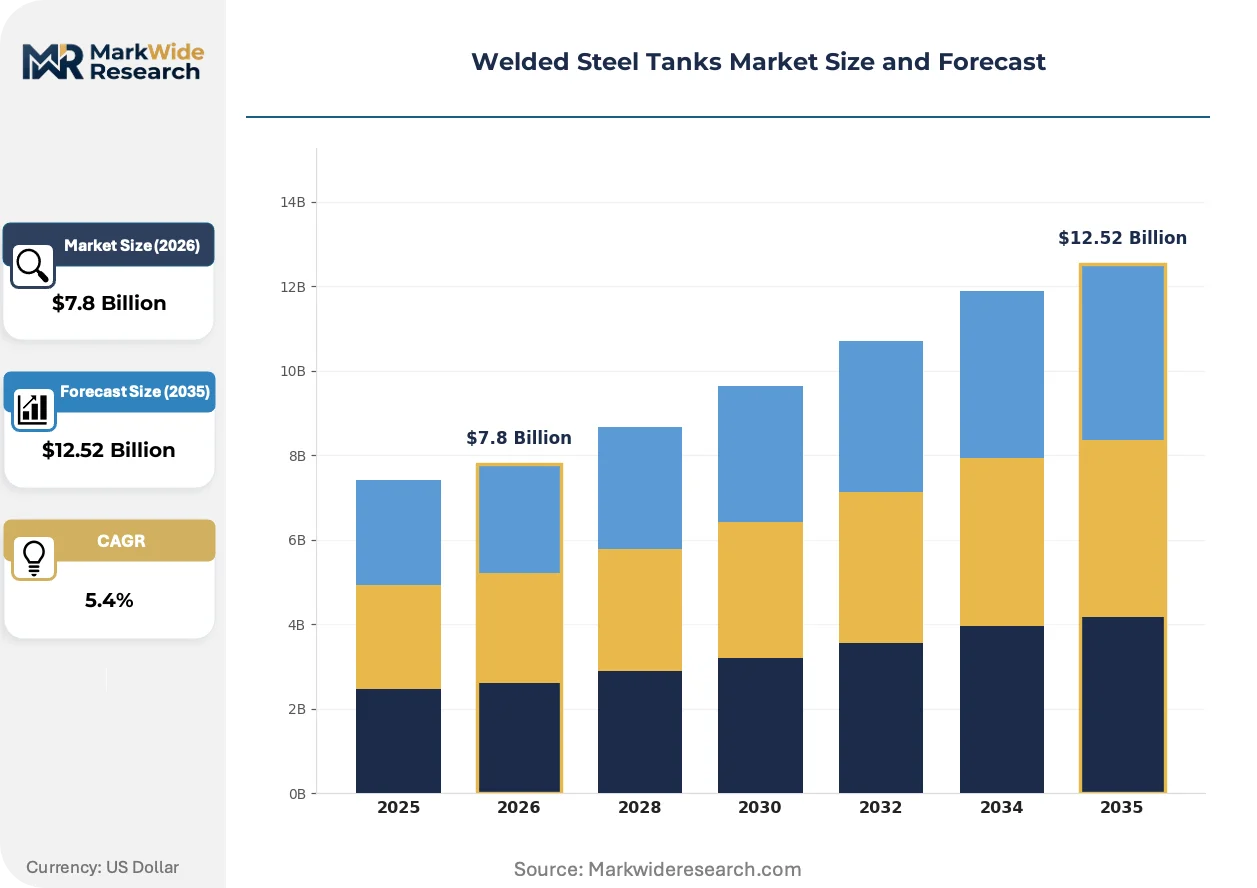
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Storage Tanks, Pressure Vessels, Oil Tanks, Water Tanks Material Grade: Carbon Steel, Stainless Steel, Alloy Steel, Galvanized Steel End User: Industrial, Oil & Gas, Water Treatment, Agriculture Application: Petroleum Storage, Chemical Processing, Water Storage, Wastewater Treatment |
| Companies Covered | CST Industries, Inc., Highland Tank & Manufacturing Company, Inc., Superior Tank Co., Inc., Caldwell Tanks, Inc., PermianLide, Tank Connection, LLC, Tarsco, a TF Warren Company, Kennedy Tank & Manufacturing Co., Inc., Fisher Tank Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Welded Steel Tanks Market Trends and Innovations
Automation in welding and inspection is compressing fabrication timelines while digital twin modeling is reshaping how engineers validate structural integrity before field erection begins.
Automated submerged arc welding systems with real-time radiographic inspection are rendering obsolete manual multi-pass procedures that dominated API 650 tank construction. Large-diameter storage projects in the central United States are adopting these systems to compress shell-course installation schedules. The technology is rendering obsolete traditional weld-repair cycles that previously extended project timelines by 15-20 percent.
EPA spill prevention rules under 40 CFR 112 are mandating secondary containment configurations and accelerated integrity testing frequencies for aboveground petroleum storage. Tank buyers must now specify double-wall designs or external containment berms that add 12-18 percent to installed cost. Downstream refiners and bulk terminals are responding by consolidating procurement with fabricators holding API 653 repair certifications.
Performance-based procurement contracts are displacing traditional specification-driven tendering for municipal water storage projects. Engineering-procurement-construction firms now require guaranteed leakage rates and seismic performance bonds rather than prescriptive material thicknesses. This shift is most visible across Texas and California utilities where lump-sum risk transfer has become standard contracting practice.
Welded Steel Tanks Market Segmentation
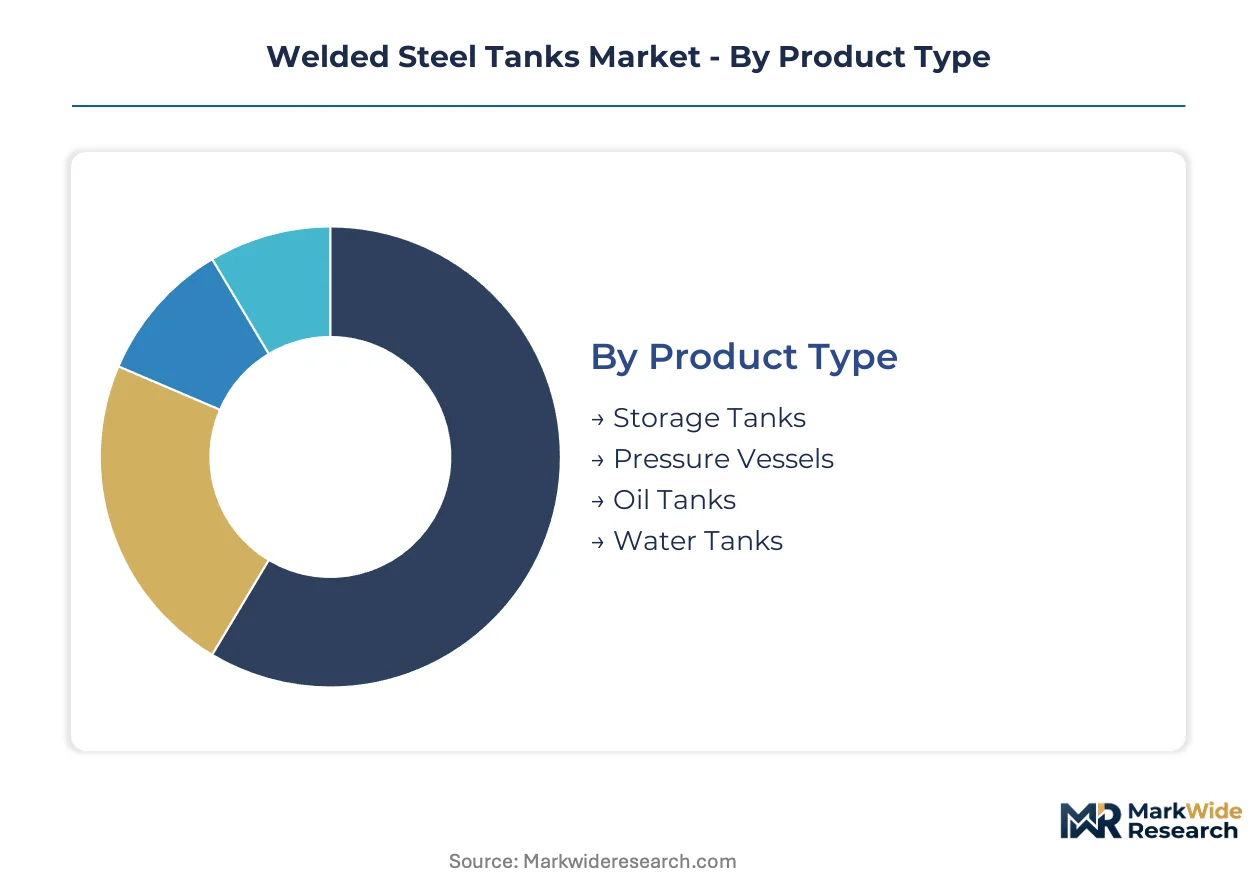
Welded steel tank procurement patterns diverge sharply across product configurations, with atmospheric storage vessels cycling through replacement schedules faster than pressure-rated alternatives. Material specification choices directly determine fabrication lead times and field-erection complexity, creating distinct supply chain rhythms for each segment cluster.
Product Type:
Cycle times range from 8-12 weeks for standardized storage tanks to 20-28 weeks for engineered pressure vessels, with oilfield applications demanding the most rapid turnaround.
- Storage Tanks:Atmospheric vessels built to API 650 dominate shipment volumes through standardized shell-course designs for crude oil and fire water reserves. Municipal utilities across Texas and the Permian Basin drive repeat orders for 500,000 to 5 million gallon configurations where seismic zone engineering adds 15-20 percent to fabrication timelines.
- Pressure Vessels:Custom-engineered containers rated for internal pressure per ASME Section VIII command extended procurement cycles due to specialized weld procedure qualifications and hydrostatic testing protocols. Chemical processors in the Gulf Coast corridor specify these for reactor feed storage and catalytic process containment where failure tolerance approaches zero.
- Oil Tanks:Aboveground petroleum containment systems face EPA 40 CFR 112 secondary containment mandates that extend design-to-delivery intervals.
- Water Tanks:AWWA D100-compliant vessels for potable and non-potable service encounter lengthening lead times from tightened lead-and-copper rule compliance.
Storage tanks anchor the volume base while pressure vessels gain share at the steepest rate.
Material Grade:
Cost tiers separate commodity carbon specifications from corrosion-resistant alternatives, with alloy premiums running 40-60 percent above baseline grades.
- Carbon Steel:ASTM A285 and A516 grades constitute the procurement baseline for non-corrosive petroleum and water service where unit cost minimization overrides service life extension. Fabricators in Oklahoma and Louisiana maintain dedicated production lines for these specifications to serve downstream refinery maintenance cycles.
- Stainless Steel:304L and 316L grades are displacing carbon alternatives in water treatment and food-adjacent applications where chloride resistance justifies 2.5-3x material cost premiums. Desalination plants in California and Florida now specify these grades exclusively for brackish water containment.
- Alloy Steel:Chrome-molybdenum specifications serve high-temperature hydrogen service in emerging hub developments.
- Galvanized Steel:Zinc-coated carbon grades occupy the economy tier for agricultural and remote-site applications with moderate corrosion exposure.
Carbon steel commands the installed base volume while stainless specifications expand most quickly in coastal and chemical-processing deployments.
End User:
Customer type determines specification authority, with industrial direct buyers driving custom engineering and municipal utilities enforcing standardized tendering.
- Industrial:Manufacturing facilities and power generators procure tanks as captive infrastructure, prioritizing seismic performance bonds and guaranteed leakage rates over prescriptive material thicknesses. Performance-based contracting now dominates across Texas and California industrial parks.
- Oil & Gas:Upstream operators in the Permian Basin generate repeat orders for produced water and brine containment where corrosion-resistant specifications reduce replacement frequency. Midstream terminals consolidate procurement with API 653-certified fabricators to satisfy EPA spill prevention inspection cycles.
- Water Treatment:Municipal utilities accelerate replacement schedules under federal infrastructure replacement programs.
- Agriculture:Irrigation districts and feedlot operators prioritize unit cost over extended service life for non-critical containment.
Oil and gas procurement anchors current fabrication capacity while water treatment demand climbs the fastest under regulatory replacement mandates.
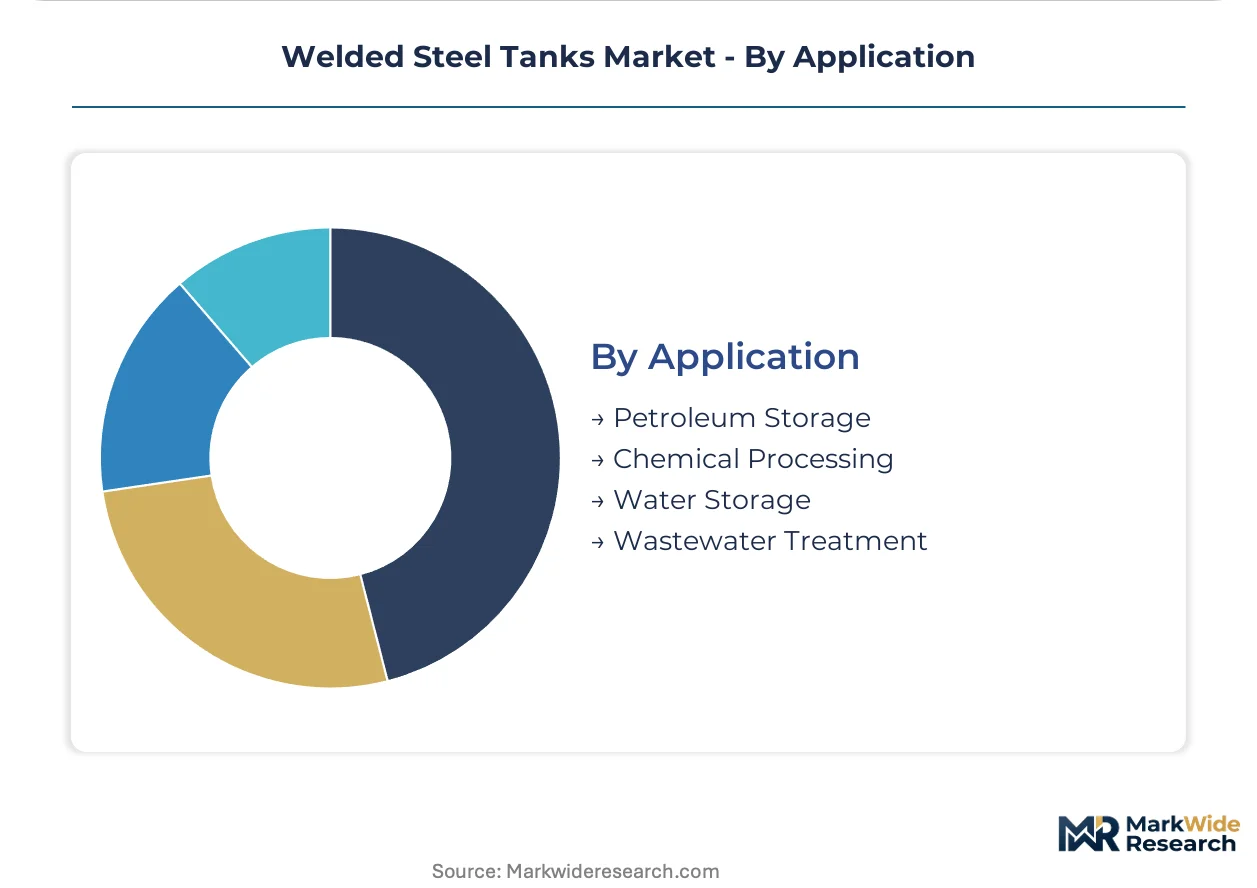
Application:
Application-specific engineering requirements fragment fabricator competence, with petroleum storage rewarding scale economies and chemical processing demanding specialized qualifications.
- Petroleum Storage:Crude oil and refined product containment systems leverage standardized API 650 designs that compress engineering costs across high-volume production runs. Bulk terminals along the Gulf Coast and Midwest pipeline corridors favor these configurations for 10,000 to 100,000 barrel working capacity.
- Chemical Processing:Aggressive fluid containment requires alloy selection and weld procedure optimization beyond carbon steel baselines. Texas and Louisiana chemical corridor operators specify these for acid, caustic, and solvent storage where material compatibility testing precedes fabrication release.
- Water Storage:Potable and fire suppression systems face tightening AWWA D100 material specifications.
- Wastewater Treatment:Anaerobic digester and clarifier applications encounter odor control and corrosion challenges.
Petroleum storage anchors the revenue base while chemical processing applications show the steepest specification upgrade trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Strategic Petroleum Reserve storage complex along the Gulf Coast anchors United States demand for large-diameter welded vessels. Permian Basin pipeline terminals and Texas export facilities drive procurement cycles for corrosion-resistant storage.
United States
EPA infrastructure replacement programs and AWWA D100 standard revisions are accelerating municipal utility orders across Texas and California. OSHA 1910.146 confined-space compliance adds field maintenance costs to tank lifecycle economics. Houston-Gulf Coast fabrication clusters concentrate API 650-certified welders serving downstream refinery maintenance cycles.
Canada
Alberta oil sands bitumen storage and Saskatchewan potash mining operations sustain demand for atmospheric vessels. The country's national environmental regulator enforces spill prevention protocols that mandate secondary containment configurations. Calgary-Edmonton industrial corridor fabricators specialize in cold-weather steel specifications for arctic service conditions.
Germany
Chemical processing complexes along the Rhine-Ruhr corridor require ASME-compliant pressure vessels for catalytic process containment. REACH chemical safety regulations govern material compatibility testing for aggressive fluid storage. Bavarian engineering firms integrate automated welding systems to compress fabrication timelines for export contracts.
Saudi Arabia
Crude oil strategic storage and desalination plant expansion drive stainless steel tank procurement for brackish water containment. The national oil company mandates API 653 repair certifications for aboveground petroleum storage contractors. Eastern Province industrial cities host fabrication yards serving Red Sea and Gulf export terminals.
India
Municipal water infrastructure programs and petrochemical complex expansion generate orders for AWWA D100 and API 650 vessels. The Bureau of Indian Standards enforces material specifications for potable water containment systems. Gujarat and Maharashtra industrial zones concentrate field-erection teams serving refinery and chemical processing installations.
Welded Steel Tanks Market Competitive Landscape
On the supply side, the industry is structured around regional fabrication clusters with distinct certification specializations. API 650 atmospheric storage and ASME pressure vessel qualifications fragment competence across geographic markets. Three archetypes dominate: integrated tank-and-field-service providers, specialty corrosion-resistant fabricators, and EPC-aligned project delivery specialists. Capacity expansion and strategic certification acquisitions represent the dominant competitive moves as fabricators position for hydrogen hub and renewable diesel retrofit opportunities.
Within the integrated service tier, CST Industries, Inc. and Highland Tank & Manufacturing Company, Inc. exemplify fabricators combining bolted and welded capabilities with dedicated project team structures. Tank Connection, LLC occupies a position among field-erection specialists where installation timeline control determines total project economics. These three companies represent distinct competitive positioning vectors—hybrid product breadth, petroleum-chemical specialization, and erection-centric delivery—that anchor the market's strategic segmentation.
| Leading Market Players |
|---|
| CST Industries, Inc. |
| Highland Tank & Manufacturing Company, Inc. |
| Superior Tank Co., Inc. |
| Caldwell Tanks, Inc. |
| PermianLide |
| Tank Connection, LLC |
| Tarsco, a TF Warren Company |
| Kennedy Tank & Manufacturing Co., Inc. |
| Fisher Tank Company |
| Others |
Pricing and Supply Chain Analysis
Steel plate commodity volatility determines both fabrication margin compression and the geographic clustering of certified welders around Gulf Coast supply nodes. This input cost uncertainty widens pricing spreads between lump-sum fixed contracts and cost-plus arrangements while concentrating procurement relationships with fabricators holding captive steel inventories.
Pricing Analysis
Volume-discount tiering separates municipal utility scale orders from single-vessel industrial procurement, with 500,000-gallon-plus configurations commanding 8-12 percent unit cost reductions against baseline quotes. Price differentiation hinges on certification grade—API 653 repair certification adds 15-20 percent premiums—and geographic delivery cost from Oklahoma-Louisiana fabrication clusters. Cost compression in carbon steel storage runs through fixed-price EPC contracts where steel input timing mismatches erode fabricator margins. Municipal water treatment utilities exhibit highest price sensitivity due to bond-financed capital constraints, while Permian Basin oilfield operators prioritize corrosion-resistant specifications over unit cost minimization.
Supply Chain Analysis
Export-control regime limitations on submerged arc welding automation systems restrict technology transfer to Indian and Saudi fabrication yards, preserving Gulf Coast competence advantages. Geographic supply concentrates in the United States, India, and Saudi Arabia, with raw material dependencies on ASTM A285/A516 carbon plate, 304L/316L stainless coil, and chrome-molybdenum alloy feedstock. Single-source vulnerability sits with specialized API 650-certified welder labor pools concentrated in Texas and Louisiana. Distribution runs through direct EPC channel relationships and field-erection subcontractor networks serving terminal and refinery installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The welded steel tanks market is exiting a cyclical trough as federal infrastructure replacement programs and Permian Basin produced water demand create synchronized order flow acceleration.
For Market Incumbents: Build certification moats through API 653 repair qualification expansion and ASME pressure vessel capacity additions in hydrogen hub corridors. Defensive consolidation should target field-erection specialists in Texas and California where seismic zone engineering competence fragments competitor capability. Threat substitution from prestressed concrete reservoirs demands response through performance-based contracting guarantees that concrete cannot match. For New Entrants and Emerging Players: Pursue white-space capture in stainless steel water treatment specifications displacing carbon alternatives across California and Florida desalination markets. Target agricultural irrigation districts in the Midwest where unit-cost prioritization and limited corrosion exposure create penetrable entry points. Go-to-market positioning should emphasize rapid turnaround cycle commitments against incumbent backlog constraints. For Investors and Strategic Acquirers: EPA lead-and-copper rule enforcement reshapes the acquisition landscape toward AWWA D100-certified fabricators with demonstrated potable water compliance track records. Long-term viability centers on hydrogen infrastructure and renewable diesel retrofit exposure across the analysis window. Acquisition target archetype: mid-cap fabricators with hybrid bolted-welded capabilities and established EPC relationships. Signal to watch: Department of Energy hydrogen hub funding disbursement velocity as capacity utilization inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| API 653 Certification Investment | Unlocks EPA-mandated repair revenue streams from downstream refinery inspection cycles. |
| Automated Welding System Deployment | Compresses shell-course installation timelines for large-diameter storage projects in Texas. |
| Stainless Steel Specification Expansion | Captures chloride-resistant demand from California and Florida desalination plant operators. |
| Hydrogen Hub Correspondence | Positions fabrication capacity for high-pressure vessel orders under DOE infrastructure funding. |
| EPC Channel Integration | Secures lump-sum contract access through dedicated project team relationships. |
Research Methodology
Initial hypotheses were tested against primary input from fabrication plant managers, EPC procurement leads, municipal utility engineering directors, and API certification auditors and refined through secondary validation. Primary fieldwork encompassed structured discussions with downstream refinery maintenance planners and field-erection subcontractors across the Gulf Coast and Permian Basin corridors. Secondary sources included EPA 40 CFR 112 enforcement data, AWWA D100 standard revision documentation, Department of Energy hydrogen hub funding announcements, and customs records tracking steel plate import flows. Bottom-up tank shipment tallies by diameter class and material grade were triangulated against top-down demand estimates derived from infrastructure replacement program allocations and oilfield water production forecasts.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeling across product type, material grade, end-user category, and application-specific engineering requirements. CAGRs were derived from regression analysis of historical shipment patterns against regulatory enforcement timelines and commodity price cycle positioning. Industry-specific forecast inputs incorporated API 650 and ASME Section VIII certification velocity trends and Permian Basin produced water volume projections.
Sensitivities concentrate around steel plate commodity price swings, EPA enforcement intensity variations, and hydrogen hub funding disbursement timing. Forecasts reflect documented assumptions regarding regulatory compliance cost pass-through rates and fabricator capacity expansion response lags. Material shifts in federal infrastructure program authorization levels or state-level renewable diesel mandate acceleration would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Global Intelligent Sanitary Ware Market
Building & Construction Materials
Aluminum Board Raised Access Floor Market
Building & Construction Materials
Industrial Flooring Market
Building & Construction Materials
Saudi Arabia Sanitaryware Market
Building & Construction Materials
Global Prefab Wood Building Market
Building & Construction Materials
Australia Steel Rebar Market
Building & Construction Materials
Laminated Veneer Lumber (LVL) Market
Building & Construction Materials
Japan Oriented Strand Board Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Steel Sandwich Panels Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market
Building & Construction Materials
Saddle Plate Market
Building & Construction Materials
Australia Industrial Insulation Market
Building & Construction Materials
Cladding Systems Market
Building & Construction Materials
Sanitary Ware Market
Building & Construction Materials
Global Aggregates Market