
 Europe Industrial Flooring Market | 2026-2036
Europe Industrial Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Industrial Flooring Market Foresight
The capital-intensity divergence between integrated resin manufacturers and regional installers is redrawing competitive boundaries in the Europe industrial flooring sector. Sika AG leverages its captive epoxy formulation capacity to command specification influence among German automotive OEMs. Flowcrete Group Ltd anchors its position through specialized polyurethane systems designed for food-grade environments. MBCC Group competes via broad concrete admixture portfolios that extend into polished flooring finishes.
Europe industrial flooring encompasses load-bearing surface systems engineered from resin-based binders, cementitious matrices, or thermoplastic compounds, typically applied at thicknesses of two to ten millimeters to withstand mechanical abrasion, chemical exposure, and thermal cycling in commercial and industrial environments. Epoxy formulations dominate specification sheets for heavy manufacturing floors requiring chemical resistance, while polyurethane systems capture premium positioning in food processing and cold-storage applications where thermal shock tolerance matters. Self-leveling technology leads installation throughput metrics across warehousing and aerospace hangar projects, whereas raised access flooring occupies a specialized niche in data center and cleanroom infrastructure where underfloor service distribution is critical.
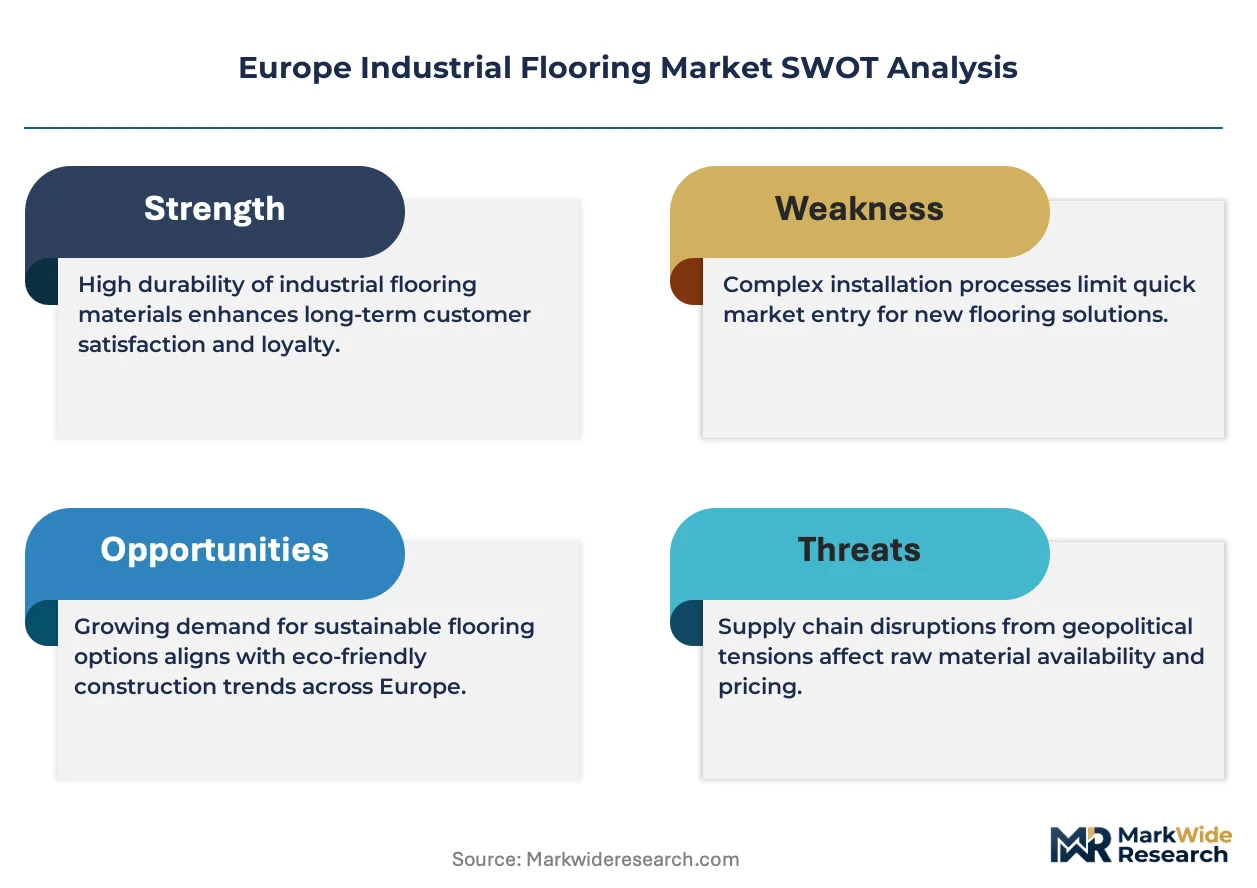
REACH registration requirements govern monomer and hardener chemistries deployed across EU member states, compelling reformulation of legacy solvent-based systems toward low-VOC alternatives. CE marking under the Construction Products Regulation mandates declared performance characteristics for structural bonding and surface durability. ECHA substance evaluations on isocyanates are tightening handler certification protocols, directly influencing contractor qualification thresholds and product liability exposure. Stakeholders must monitor the interplay between embodied carbon reporting under CSRD and emerging bio-based binder certifications, as these frameworks will increasingly determine specification eligibility for public infrastructure and corporate sustainability mandates.
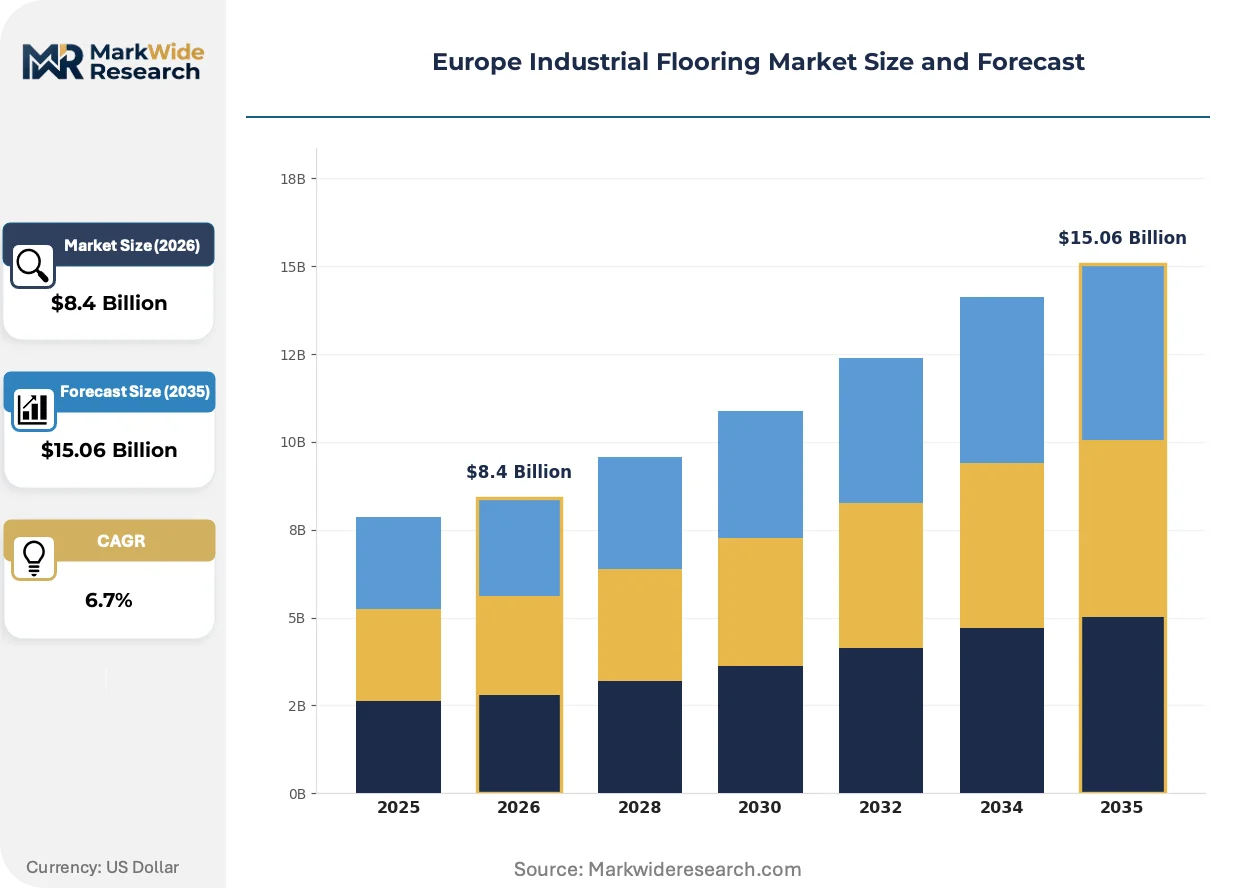
Market Dynamics
REACH compliance deadlines and the EU Green Deal's embodied carbon mandates are forcing simultaneous reformulation of legacy chemistries and disclosure of supply-chain emissions across the Europe industrial flooring sector.
Growth Catalysts
- Food-grade polyurethane systems:Cold-storage facilities and meat processing plants in Germany and France specify thermal-shock-resistant flooring that withstands repeated steam cleaning cycles without delamination.
- CSRD reporting mandates:Corporate sustainability reporting requirements are elevating specification priority for low-embodied-carbon flooring systems in publicly listed manufacturing facilities.
- Automotive manufacturing corridor concentration:Battery gigafactory construction across Baden-Württemberg and Bavaria generates concentrated demand for chemical-resistant epoxy systems in electrolyte handling areas.
Market Restraints
- Isocyanate handler certification:ECHA substance evaluations tighten contractor qualification thresholds, extending project timelines and limiting qualified installer pools in member states.
- Bisphenol A regulatory pressure:ECHA's proposed restrictions on epoxy resin precursors threaten supply continuity for conventional high-performance formulations.
- Cementitious screed price volatility:Energy-intensive production of Portland cement binders exposes project budgets to natural gas and electricity cost swings across Central Europe.
Strategic Opportunities
- Polish warehousing boom:E-commerce fulfillment center construction near Łódź and Wrocław creates underpenetrated demand for rapid-install self-leveling systems in distribution environments.
- Bio-based binder certification:Emerging CEN standards for renewable-content flooring enable premium positioning for manufacturers achieving third-party verification ahead of competitors.
- Raised access flooring-data center convergence:Hyperscale cloud infrastructure expansion in Frankfurt and Amsterdam clusters drives specification of modular underfloor systems for cable management and liquid cooling distribution.
Industry Challenges
- Skilled applicator shortage:Specialized certification requirements for polyurethane and methyl methacrylate installation constrain project throughput during peak construction seasons.
- Multi-layer system integration:Compatibility failures between moisture barriers, primers, and topcoats from different suppliers generate warranty disputes and remediation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Industrial Flooring Market |
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Vinyl, Concrete Application: Manufacturing, Warehousing, Aerospace, Food Processing Technology: Self-Leveling, Coating, Polished, Raised Access Installation: On-site, Pre-fabricated, Modular, Renovation |
| Companies Covered | Flowcrete Group Ltd, Sika AG, Gerflor, Altro Ltd, Akzo Nobel N.V., Forbo Group, Tarkett, Polyflor Ltd, MBCC Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Industrial Flooring Market Shifts & Advancements
Material science advances and tightening environmental protocols are simultaneously expanding performance boundaries and compressing acceptable formulation chemistries in European industrial flooring.
Polyaspartic coating technology is fragmenting the fast-cure application segment. Automotive assembly plants and airport hangar operators adopt these systems for return-to-service times under four hours. The technology is fragmenting installer specialization between rapid-cure polyaspartic crews and traditional epoxy applicators, creating distinct competency silos within contractor networks.
REACH authorization procedures for diisocyanates are accelerating low-monomer polyurethane development. Flooring manufacturers reformulate two-component systems to below 0.1% residual isocyanate content to exempt handler certification requirements. German automotive OEMs and French dairy processors lead specification of these next-generation systems to preempt regulatory disruption.
Facility operators increasingly bundle flooring specification with extended performance warranties. Industrial asset owners in the Netherlands and Belgium negotiate ten-year guarantees covering abrasion loss and chemical resistance rather than accepting standard material-only coverage. This compresses contractor risk profiles and elevates demand for predictive maintenance monitoring integrated into flooring system design.
Europe Industrial Flooring Market Segmentation
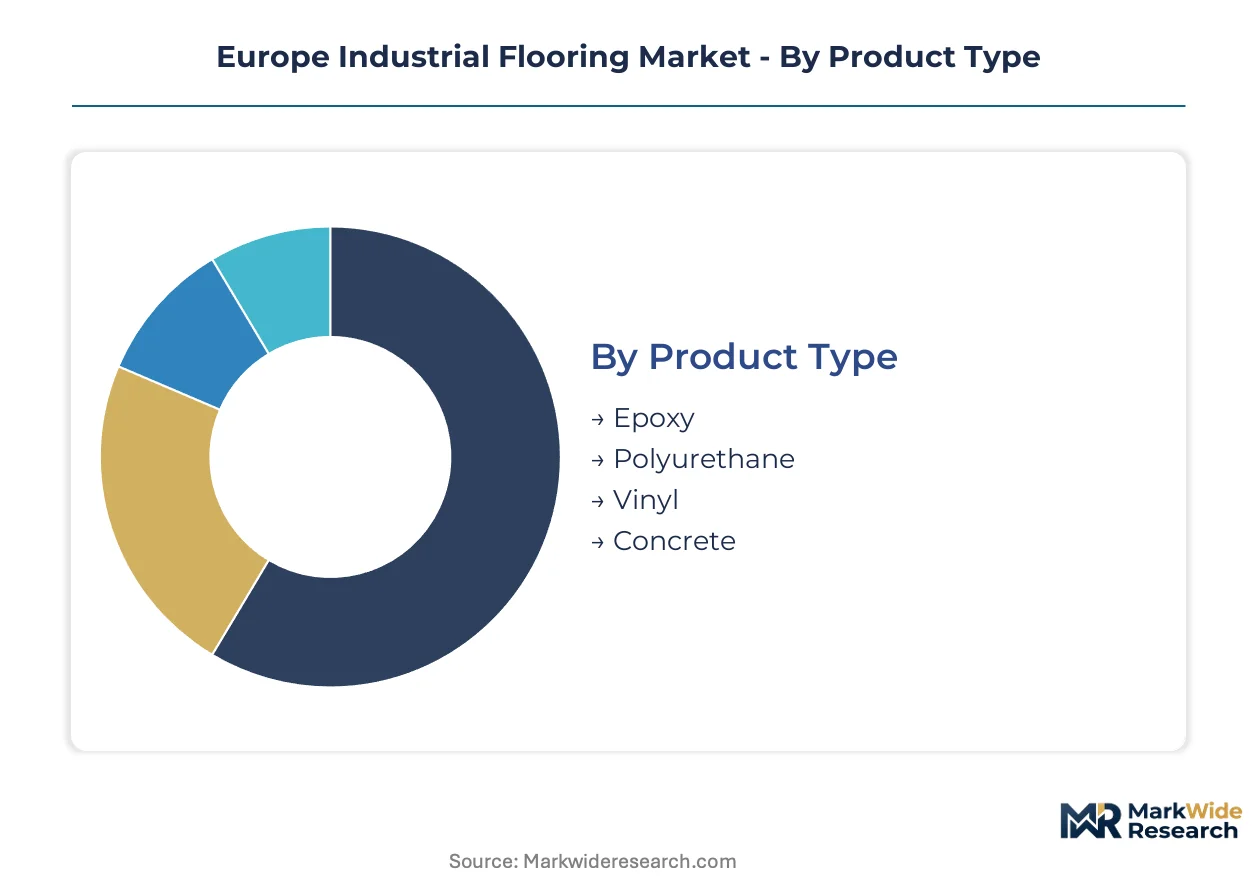
Material selection and installation method determine lifecycle cost and regulatory compliance trajectories across European industrial flooring. Specification patterns diver sharply between automotive OEMs prioritizing chemical resistance and food processors demanding thermal shock tolerance.
Product Type:
Margin pools concentrate in specialized resin formulations where technical certification barriers limit commoditization.
- Epoxy:Thermoset polymer systems formed from bisphenol-A or bisphenol-F resins with amine hardeners deliver superior chemical resistance and compressive strength. German automotive OEMs in Baden-Württemberg specify these for battery electrolyte handling areas where spill containment is critical. REACH restrictions on bisphenol-A precursors are forcing reformulation toward alternative chemistries.
- Polyurethane:Elastomeric systems based on polyol-isocyanate reactions absorb thermal cycling and mechanical impact without cracking. Cold-storage facilities across France and Germany adopt these for repeated steam-cleaning protocols in meat and dairy processing environments.
- Vinyl:Thermoplastic sheets and tiles offer rapid installation and antimicrobial surface properties for healthcare and light industrial settings.
- Concrete:Cementitious systems with densifiers and sealers provide economical load-bearing surfaces for warehousing and logistics infrastructure.
Epoxy holds installed capacity. Polyurethane is rotating up the share rankings.
Application:
End-use concentration follows manufacturing investment cycles and hygiene regulatory intensity.
- Manufacturing:Heavy industrial environments including automotive assembly, metal fabrication, and electronics production require abrasion-resistant surfaces with electrostatic discharge control. Battery gigafactory construction across Bavaria generates concentrated specification demand for chemical-resistant systems.
- Warehousing:High-bay distribution centers and automated storage facilities prioritize flatness tolerances and point-load capacity for forklift and AGV traffic. E-commerce fulfillment construction near Łódź and Wrocław drives rapid-install self-leveling adoption.
- Aerospace:Hangar and MRO facilities specify fuel-resistant coatings with rapid return-to-service characteristics to minimize aircraft downtime.
- Food Processing:Dairy, meat, and beverage facilities mandate seamless, sloped surfaces with thermal shock resistance for hot washdown cycles and microbial control.
Manufacturing commands current specification volume. Food Processing is climbing the fastest as hygiene regulations tighten.
Technology:
Installation throughput and performance warranty terms vary substantially across application methods.
- Self-Leveling:Fluid-applied resin systems that achieve flatness through gravity flow eliminate manual screeding labor. Warehousing and aerospace projects across the Netherlands and Belgium specify these for rapid coverage of large areas with defined flatness tolerances.
- Coating:Thin-film roller or spray-applied systems provide chemical protection and aesthetic finish over existing substrates. Automotive plants apply these for color-coding production zones and chemical containment.
- Polished:Mechanical grinding and densification of concrete surfaces creates reflective, dust-free finishes without topical coatings. Retail and light manufacturing environments favor these for low-maintenance lifecycle costs.
- Raised Access:Modular pedestal-supported panels enable underfloor cable management and liquid cooling distribution. Hyperscale data centers in Frankfurt and Amsterdam clusters specify these for infrastructure flexibility.
Self-Leveling holds installed capacity. Raised Access is rotating up the share rankings.
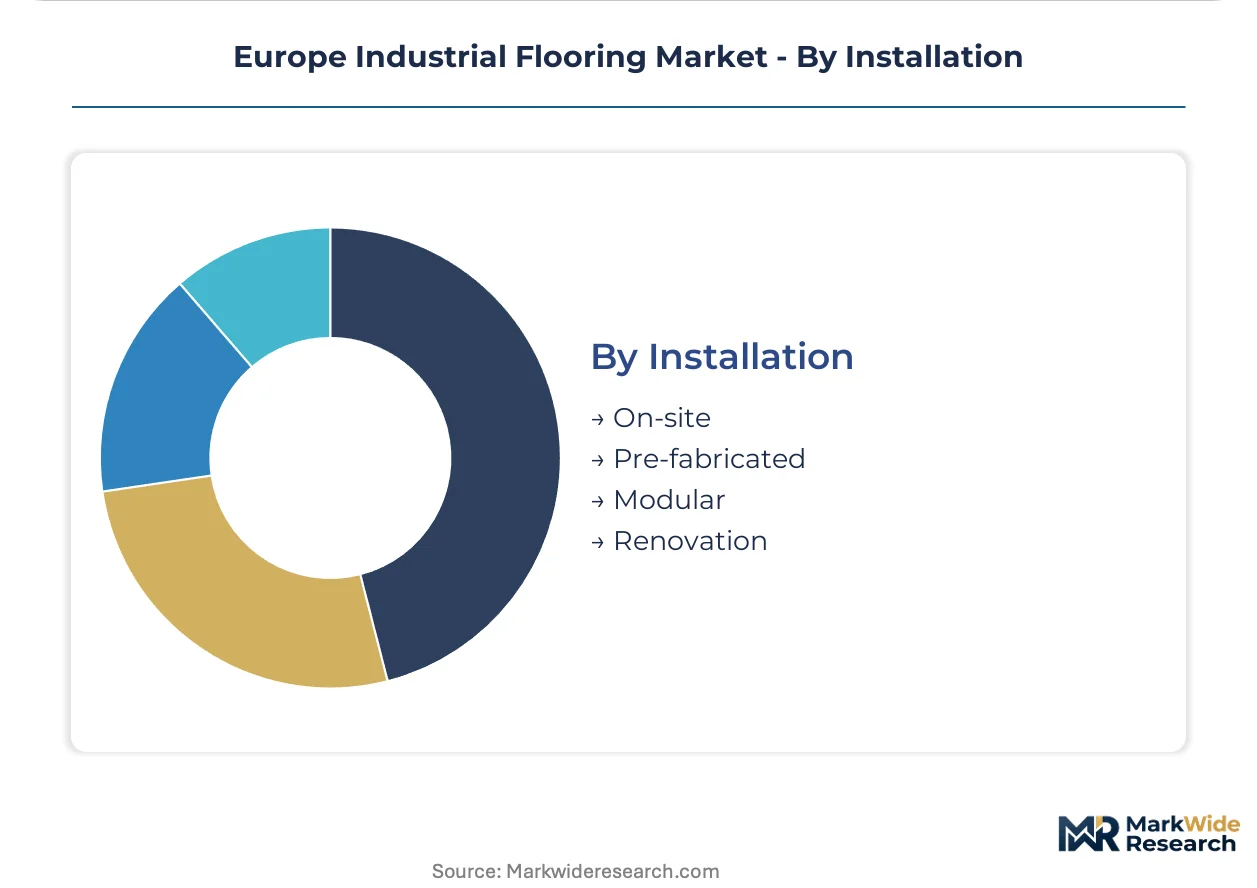
Installation:
Project timeline constraints and substrate condition dictate method selection across renovation and new-build contexts.
- On-site:Wet-applied resin and cementitious systems mixed and placed at the project location allow customization for complex geometries. German contractors dominate this segment through specialized applicator certification networks.
- Pre-fabricated:Factory-cured panels or tiles delivered for adhesive bonding accelerate installation in schedule-critical environments.
- Modular:Interlocking or pedestal-mounted systems enable rapid deployment and future reconfiguration. Data center operators specify these for cable management adaptability.
- Renovation:Overlay and refurbishment systems extend service life of existing floors without full removal. Industrial asset owners in Belgium negotiate extended performance warranties for these applications.
On-site holds installed capacity. Renovation is gaining share fastest as existing industrial stock ages.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's industrial flooring sector runs a modest trade surplus in formulated resin systems, with Germany and Switzerland exporting specialty epoxies to Central European installers while importing bulk cementitious substrates from Poland and the Czech Republic. Cross-border specification standards under CE marking harmonize demand across the single market.
Germany
Battery gigafactory construction across Bavaria and Baden-Württemberg consumes chemical-resistant epoxy systems for electrolyte containment zones. REACH authorization timelines for diisocyanates are compressing reformulation cycles among Stuttgart-based formulators. The automotive manufacturing corridor from Munich to Wolfsburg anchors specification volume for heavy-load polyurethane systems.
France
Dairy and meat processing facilities in Brittany and the Grand Est region specify thermal-shock-resistant polyurethane for steam-cleaning protocols. ANSM hygiene mandates for food-contact surfaces are elevating seamless flooring requirements above tiled alternatives. Lyon and Lille clusters concentrate demand for rapid-install methyl methacrylate systems in pharmaceutical cleanrooms.
Poland
E-commerce fulfillment center construction near Łódź and Wrocław is absorbing self-leveling epoxy at volumes exceeding domestic formulation capacity. EU cohesion fund infrastructure allocations are upgrading regional logistics hubs with abrasion-resistant warehousing surfaces. Silesian manufacturing zones are retrofitting legacy steel plants with polished concrete finishes to attract light industrial tenants.
Netherlands
Hyperscale data center expansion in Amsterdam and Eindhoven is specifying raised access flooring for liquid cooling distribution and cable management. CSRD reporting mandates among Rotterdam-listed industrials are prioritizing low-embodied-carbon screed specifications. Port of Rotterdam chemical handling terminals require solvent-resistant coating systems meeting strict VOC limits.
Belgium
Pharmaceutical manufacturing in Flanders demands electrostatic discharge-controlled flooring for API production suites. Extended performance warranties negotiated by Antwerp industrial asset owners are compressing contractor risk profiles. Brussels regulatory proximity ensures early adoption of ECHA substance restrictions into national building codes.
Europe Industrial Flooring Market Competitive Landscape
Concentration sits with integrated resin manufacturers possessing captive formulation capacity and specification relationships with German automotive OEMs. Mid-tier regional installers compete on project execution speed and applicator certification density. Two archetypes dominate: multinational chemical conglomerates with construction chemicals divisions, and specialized flooring system houses with food-grade technical credentials. Competitive moves center on backward integration into bio-based binder feedstocks and strategic partnerships with battery gigafactory developers for early specification lock-in.
Among Switzerland-based chemical conglomerates, Sika AG exemplifies the integrated manufacturer archetype through its captive epoxy formulation capabilities. Flowcrete Group Ltd represents the specialized system house model with concentrated expertise in hygienic polyurethane applications. MBCC Group anchors the broad construction chemicals portfolio approach, extending concrete admixture capabilities into polished flooring finishes.
| Leading Market Players |
|---|
| Flowcrete Group Ltd |
| Sika AG |
| Gerflor |
| Altro Ltd |
| Akzo Nobel N.V. |
| Forbo Group |
| Tarkett |
| Polyflor Ltd |
| MBCC Group |
| Others |
Supply & Pricing Matrix
CE marking under the Construction Products Regulation gates both supplier qualification and price differentiation simultaneously. German automotive OEMs and French food processors pay configured-to-order premiums for certified systems, while standard epoxy formulations compete on volume pricing in Polish warehousing projects.
Pricing Analysis
The customization-premium spread spans three-tier pricing structure across premium, standard, and economy levels. Project-based pricing dominates, with differentiation driven by REACH certification tier and after-sales warranty bundling. Cost compression in economy-grade epoxy is intensifying because of cementitious screed price volatility. Polish logistics developers exhibit highest price sensitivity, while German battery gigafactory operators prioritize performance over unit cost.
Supply Chain Analysis
BASF Ludwigshafen and Covestro Leverkusen facilities anchor raw material supply for isocyanate and epoxy resin feedstocks. Formulated systems draw from Germany, Switzerland, and the Netherlands, with cementitious substrates sourced from Poland and the Czech Republic. Single-source vulnerability concentrates in specialty amine hardeners. Distribution runs through certified applicator networks rather than merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe industrial flooring market is accelerating through a regulatory inflection as REACH diisocyanate restrictions force simultaneous reformulation and certification investment across the supply base.
For Market Incumbents: Shield specification relationships with German automotive OEMs through captive bio-based binder R&D and early CSRD-compliant carbon disclosure. Secure backward integration into renewable polyol feedstocks before CEN certification standards harden. Lock in ten-year performance warranty capacity to match Dutch and Belgian asset owner demands. For New Entrants and Emerging Players: Anchor in Polish e-commerce fulfillment construction near Łódź and Wrocław, where rapid-install self-leveling demand outstrips domestic formulation capacity. Target food-grade polyurethane segments in France where thermal-shock certification creates technical barriers. Partner with regional installers to bypass Sika AG's specification control in automotive corridors. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across bio-based binder development as CEN standards approach. Prioritize acquisition targets with REACH-registered low-monomer polyurethane portfolios and existing handler certification networks. Watch ECHA substance evaluation timelines as the signal for regulatory disruption windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-based Feedstocks | CEN certification standards will gate premium positioning for renewable-content flooring systems. |
| REACH-Compliant Low-Monomer Reformulation | Exemption from ECHA handler certification requirements opens contractor network expansion. |
| Extended Performance Warranty Programs | Dutch and Belgian asset owners now negotiate ten-year coverage compressing contractor risk profiles. |
| Polish Installer Network Acquisition | E-commerce fulfillment construction near Łódź absorbs self-leveling epoxy beyond domestic capacity. |
| Raised Access Flooring Data Center Partnerships | Hyperscale expansion in Frankfurt and Amsterdam clusters drives modular underfloor specification. |
Research Methodology
The analysis maps resin formulation sub-sectors, each validated through plant managers at German automotive OEMs, procurement leads at French food processors, distribution channel partners, and technical R&D directors at integrated manufacturers. Primary interview findings triangulate against customs trade data, Cefic chemical industry reports, SEC 10-K filings, and ECHA substance registration databases. Bottom-up project pipeline analysis and top-down sector sizing converge through independent verification.
Consistency checks validated volume and value outputs against EIA energy cost indices and construction sector input price series across the projection horizon. Segmentation dimensions include material chemistry tier, end-use industry vertical, installation technology, and regional regulatory cluster. CAGRs derive from elasticity-adjusted demand modeling incorporating battery gigafactory construction schedules and food processing hygiene mandate timelines.
Underlying assumptions cover REACH authorization timelines and EU Green Deal carbon reporting rollout, with deviation risk concentrated in ECHA bisphenol-A restriction decisions and natural gas price volatility affecting cementitious binder costs. Practitioners should keep alternative scenarios live as CSRD disclosure requirements and bio-based certification standards evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
Prefabricated Bathroom Modules Market
Building & Construction Materials
Remodeling Market
Building & Construction Materials
Prestressed Concrete (PC) Wire and Strand Market
Building & Construction Materials
Germany Foam Insulation Market
Building & Construction Materials
North America Freestanding Canopy Market
Building & Construction Materials
Artificial Bowling Surface Market
Building & Construction Materials
Japan Prefab Wood Building Market
Building & Construction Materials
US Steel Rebar Market
Building & Construction Materials
Architectural Window Films Market
Building & Construction Materials
North America Decks Market
Building & Construction Materials
Concrete Densifier Market
Building & Construction Materials
Spray Foam Insulation Market
Building & Construction Materials
Sound Barriers Market
Building & Construction Materials
Storefront Glass Market
Building & Construction Materials
US Retractable Roofing System Market