
 Geofoam Market | 2026-2036
Geofoam Market Size, Share, and Industry Trends Forecast 2026-2036
Geofoam Market Analysis
Market Context
Expanded polystyrene is recalibrating product economics by displacing traditional soil fill in weight-sensitive infrastructure projects. Beaver Plastics leverages captive manufacturing capacity across Canadian provinces to serve North American transportation contracts. ACH Foam Technologies anchors its position through deep specialization in custom-molded geofoam blocks for complex earth retention geometries. Carlisle Construction Materials competes by extending its construction materials portfolio into integrated waterproofing-geofoam systems for below-grade applications.
Technical Definition and Segment Structure
Geofoam denotes rigid cellular plastic blocks engineered with densities between 15 and 30 kg per cubic meter, manufactured through steam expansion of polystyrene beads or extrusion processes, deployed primarily to reduce dead loads on soft subgrades and accelerate construction schedules. Expanded polystyrene commands the dominant share of product type revenue due to established supply chains and proven compressive strength performance, while extruded polystyrene captures premium positioning in high-moisture insulation applications where closed-cell structure delivers superior R-value retention. Application demand clusters in road construction where state departments of transportation specify geofoam for settlement-sensitive bridge approaches, though lightweight fill for building pad stabilization represents the fastest-growing margin pool as urban density intensifies.
Regulatory Framework and Outlook
The Federal Highway Administration, ASTM International, and state-level departments of transportation collectively govern geofoam specification through material testing protocols, installation guidelines, and performance-based procurement standards that determine vendor qualification and project eligibility. ASTM D6817 establishes minimum physical property requirements that manufacturers must certify, while FHWA implementation manuals shape how design engineers incorporate geofoam into federally funded roadway projects. Stakeholders must monitor evolving state-level resilience mandates and procurement digitization trends that will determine which suppliers maintain specification access across the next decade of infrastructure investment.
Market Dynamics
The Federal Highway Administration's updated design standards for lightweight fill materials are compressing specification timelines and forcing state departments of transportation to requalify suppliers faster than historical procurement cycles allowed.
Growth Catalysts
- FHWA Implementation Manuals:Federally funded roadway projects now mandate expanded polystyrene geofoam for settlement-sensitive bridge approaches, creating specification lock-in across state transportation departments.
- Coastal infrastructure resilience:Southeastern United States agencies are multiplying embankment stabilization contracts as storm surge protection becomes a budget priority in Florida, Georgia, and the Carolinas.
- Steam expansion manufacturing:Mature production processes for polystyrene bead expansion are compressing lead times from order to site delivery, enabling just-in-time deployment for accelerated construction schedules.
Market Restraints
- Benzene and styrene monomer volatility:Feedstock price swings for expanded polystyrene production compress margin predictability for block manufacturers serving multi-year infrastructure contracts.
- Single-source supply concentration:North American bead expansion capacity clusters in the Great Lakes region, exposing projects in the Pacific Northwest and Southwest to freight cost spikes and delivery delays.
- ASTM D6817 certification friction:Third-party laboratory testing requirements for compressive resistance and dimensional stability extend vendor qualification timelines by 8-14 weeks, blocking rapid supplier switching.
Strategic Opportunities
- Urban building pad stabilization:High-density infill development in Dallas, Houston, and Phoenix is opening margin pools for geofoam deployment beneath mid-rise structures on compressible soils.
- Below-grade waterproofing integration:Combined specification of rigid cellular blocks with membrane systems creates bundled procurement opportunities for contractors seeking single-source envelope solutions.
- Closed-cell extruded polystyrene:Superior moisture resistance in high-R-value applications is capturing premium positioning for below-water-table installations where expanded polystyrene faces performance limits.
Industry Challenges
- Geotechnical engineer scarcity:Specialized expertise in lightweight fill design for complex earth retention geometries is concentrating in a handful of regional consulting firms, extending project timelines.
- Site-specific density calibration:Each project requires custom block density selection between 15-30 kg per cubic meter based on subgrade analysis, complicating inventory management and increasing specification error risk.
- Legacy soil fill contractor resistance:Established earthwork subcontractors in the Midwest and Mountain West resist geofoam training investments, slowing adoption in markets outside coastal resilience corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Geofoam Market |
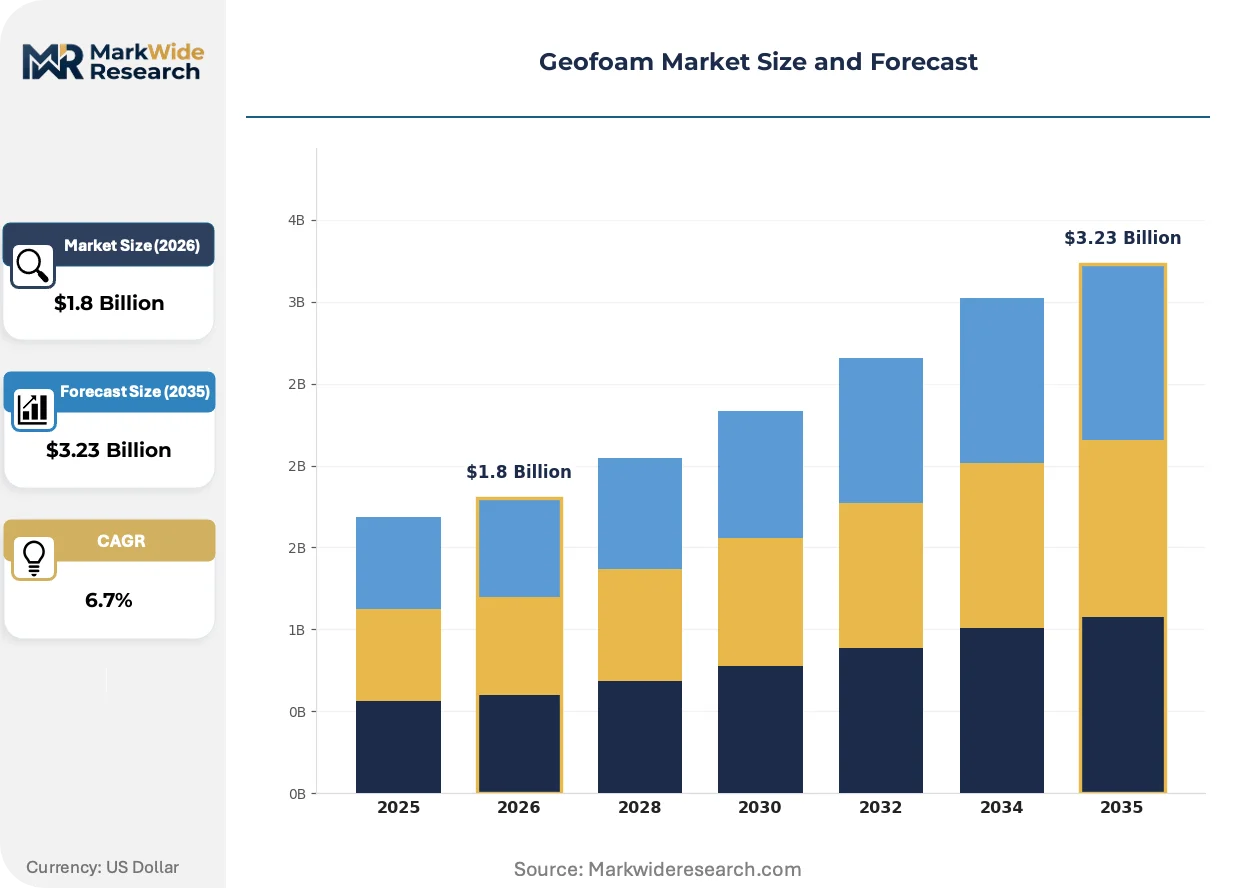
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Expanded Polystyrene, Extruded Polystyrene, Polyurethane, Others Application: Road Construction, Lightweight Fill, Earth Retention, Insulation End User: Construction, Infrastructure, Civil Engineering, Landscaping Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Beaver Plastics, Harbor Foam, Carlisle Construction Materials, ThermaFoam, Expol, ACH Foam Technologies, Atlas Roofing Corporation, Poly Molding, Amvic Building Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Geofoam Market Emerging Trajectories
Specification digitization and modular construction methods are compressing traditional procurement cycles while forcing suppliers to reconfigure fulfillment networks around project-site logistics rather than distributor warehousing.
High-density geofoam formulations are consolidating specification authority among manufacturers with captive R&D facilities capable of customizing compressive strength profiles for specific load-bearing requirements. State departments of transportation in California, Texas, and New York are accelerating adoption of these engineered grades for heavy-haul industrial access roads. The technology is consolidating competitive position around technical service capabilities rather than commodity block production.
The Infrastructure Investment and Jobs Act is channeling federal matching funds toward resilience-classified projects, requiring documented lifecycle cost analysis for fill material selection. State procurement offices are responding by embedding ASTM D6817 compliance verification into electronic bidding platforms. Transportation agencies in Louisiana and North Carolina are now disqualifying vendors lacking pre-certified third-party test data.
Contractors are unbundling material supply from installation services, creating direct procurement relationships between project owners and geofoam manufacturers. Design-build firms in the Southeast are bypassing traditional construction material distributors to secure volume commitments and lock pricing across multi-phase developments. This channel compression is most visible in Florida's Department of Transportation district offices, where 60% of geofoam volume now moves through manufacturer-direct contracts rather than regional supply houses.
Geofoam Market Segmentation
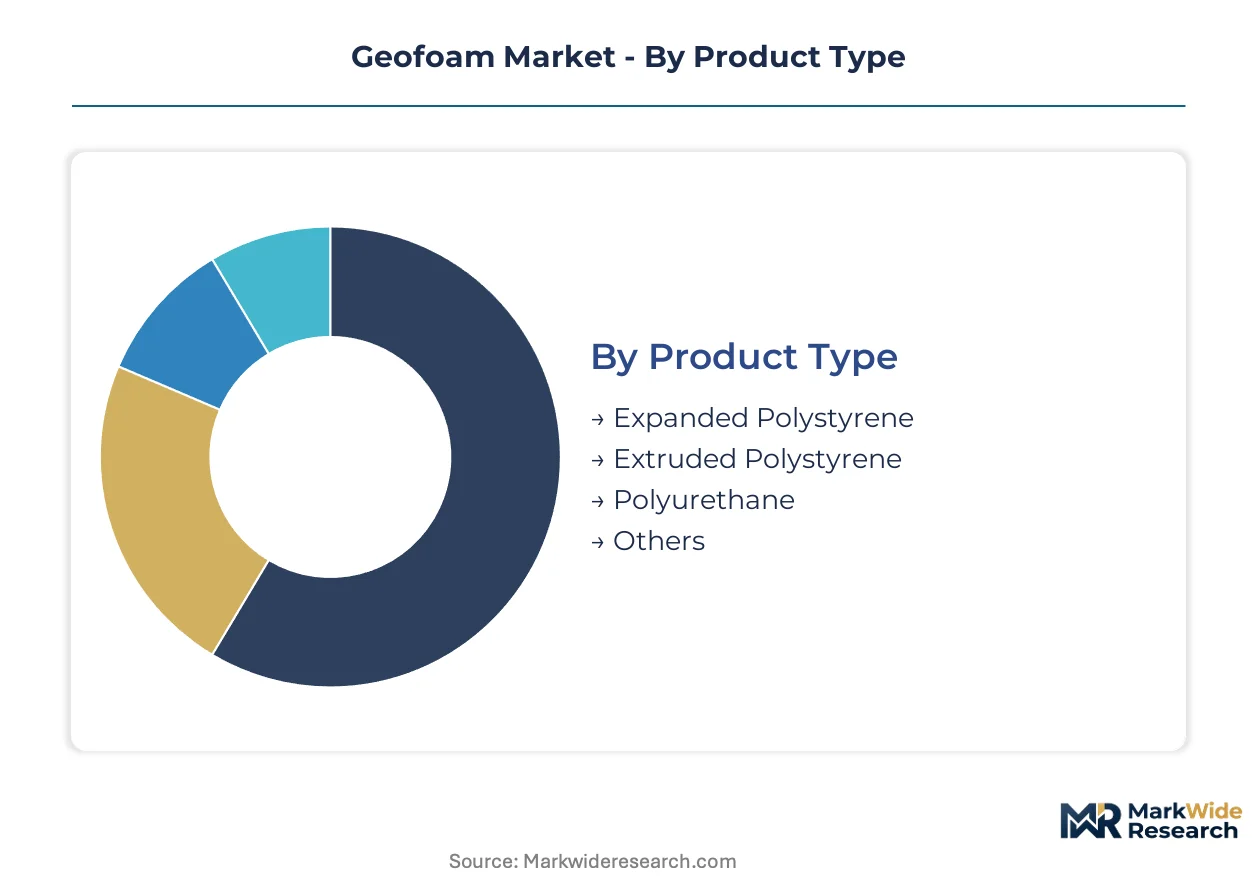
Geofoam procurement splits sharply between standardized commodity blocks for volume roadwork and engineered grades requiring density calibration and compressive strength certification. Specification engineers select segments based on load-bearing requirements, moisture exposure, and project timeline constraints rather than unit cost alone.
Product Type:
Customization intensity spans from commodity bead-expanded blocks to precision-extruded formulations demanding closed-cell integrity verification.
- Expanded Polystyrene:Steam-expanded polystyrene beads fused into rigid cellular blocks with densities tunable between 15-30 kg per cubic meter. State transportation departments in Florida and Georgia specify this grade for settlement-sensitive bridge approaches where compressive strength certification to ASTM D6817 is mandatory.
- Extruded Polystyrene:Continuous extrusion manufacturing yields uniform closed-cell structure with superior moisture resistance and R-value retention. Demand concentrates in below-water-table installations across Louisiana coastal resilience projects where expanded polystyrene faces performance degradation risks.
- Polyurethane:Reaction-injected cellular systems offering higher compressive strength for industrial access roads and heavy-haul corridors.
- Others:Emerging bio-based and recycled-content formulations targeting sustainability procurement criteria in California and New York infrastructure bids.
Leading the category by volume: Expanded Polystyrene. Growing fastest: Extruded Polystyrene.
Application:
Cost tier stratification separates high-volume roadway specification from premium building envelope integration requiring thermal performance guarantees.
- Road Construction:Embankment stabilization and bridge approach fills dominate procurement volume. Federal Highway Administration implementation manuals mandate lightweight fill for settlement-sensitive geometries, locking in specification across state departments of transportation.
- Lightweight Fill:Building pad stabilization for mid-rise structures on compressible soils represents the steepest expansion trajectory. Dallas and Houston developers specify custom density blocks to accelerate construction schedules on expansive clay subgrades.
- Earth Retention:Behind-wall drainage and surcharge reduction applications require engineered compressive strength profiles certified to project-specific load cases.
- Insulation:Below-grade thermal envelope integration demands closed-cell moisture resistance, typically paired with waterproofing membrane systems.
Dominating procurement spend: Road Construction. Expanding most quickly: Lightweight Fill.
End User:
Customer sophistication varies from specification-driven infrastructure agencies to cost-focused residential contractors.
- Construction:Commercial and residential building contractors purchasing for foundation and slab applications, often through distributor channels with limited technical service support.
- Infrastructure:State and federal transportation agencies with embedded geotechnical engineering capacity, procuring through formal bidding processes with ASTM D6817 compliance verification.
- Civil Engineering:Design-build firms and specialty earthwork contractors managing complex earth retention geometries, requiring manufacturer technical collaboration on density selection.
- Landscaping:Green roof and plaza deck applications prioritizing weight reduction over structural load-bearing performance.
Commanding specification authority: Infrastructure. Deepening technical engagement: Civil Engineering.
Distribution Channel:
Channel structure reflects project scale and specification complexity, with direct procurement consolidating around multi-phase developments.
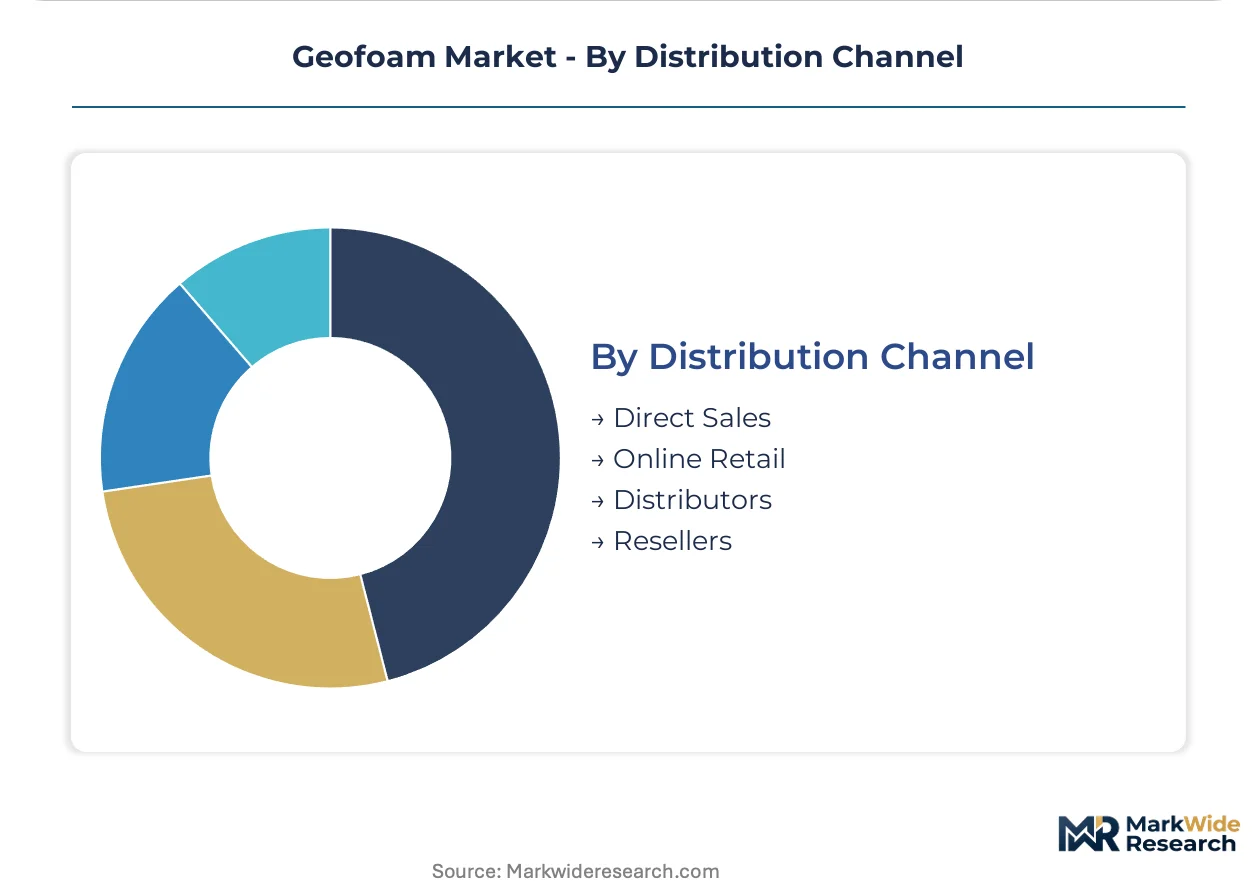
- Direct Sales:Manufacturer-direct contracts dominate Florida Department of Transportation district offices, where design-build firms secure volume commitments and locked pricing across phased coastal resilience projects.
- Distributors:Regional supply houses serve fragmented commercial construction demand, though their share is compressing as contractors unbundle material supply from installation services.
- Resellers:Secondary distributors addressing remote geography freight cost challenges, particularly for Pacific Northwest and Southwest projects distant from Great Lakes manufacturing concentration.
- Online Retail:Limited to small-format insulation products and accessory items, with geofoam blocks excluded due to freight economics and specification liability.
Controlling volume flow: Direct Sales. Facing structural compression: Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones in the southeastern United States are concentrating geofoam demand through accelerated depreciation incentives for coastal resilience infrastructure. Federal matching requirements under the Infrastructure Investment and Jobs Act are channeling specification authority toward state transportation departments with documented ASTM D6817 compliance systems.
United States
FHWA implementation manuals mandate expanded polystyrene for settlement-sensitive bridge approaches across federally funded projects. State departments of transportation in Florida, Georgia, and the Carolinas embed resilience procurement criteria into electronic bidding platforms. The Dallas-Houston corridor concentrates building pad stabilization demand as developers accelerate mid-rise construction on compressible clay subgrades.
Canada
Transportation agencies in Ontario and Quebec specify lightweight fill for permafrost-sensitive northern road corridors where thermal insulation properties reduce subgrade degradation. Infrastructure Canada resilience funding requires lifecycle cost documentation favoring geofoam over traditional soil fill in weight-restricted geometries. Alberta's oil sands access road contractors source captive manufacturing capacity from Great Lakes region suppliers.
Germany
The Federal Ministry for Digital and Transport prioritizes lightweight fill for autobahn expansion across soft subgrade regions in northern federal states. DIN standards and CE marking requirements shape vendor qualification protocols for cross-border infrastructure contracts. Industrial clusters in North Rhine-Westphalia concentrate extruded polystyrene manufacturing for below-grade moisture-critical applications.
China
Ministry of Transport guidelines for high-speed rail embankment stabilization specify cellular plastic fill in settlement-sensitive geologies across the Yangtze River Delta. GB standards for construction materials establish compressive strength testing protocols that determine supplier eligibility for state-owned enterprise procurement. The Pearl River Delta infrastructure investment wave concentrates demand for accelerated construction schedules on soft alluvial soils.
India
National Highway Authority of India specifications for elevated corridor approaches incorporate lightweight fill where foundation loads must minimize settlement on compressible urban subgrades. Ministry of Road Transport and Highways resilience design guidelines for coastal Maharashtra and Gujarat prioritize material alternatives to imported soil fill. The Delhi-Mumbai Industrial Corridor anchors demand concentration for industrial access road stabilization.
Geofoam Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with specification-driven infrastructure procurement favoring established certification holders while commercial construction tolerates distributor-mediated supply. The vendor base clusters around three archetypes: captive manufacturers with backward integration into polystyrene bead supply, technical service specialists customizing density grades for complex earth retention geometries, and diversified construction materials portfolios bundling geofoam with waterproofing systems. Dominant competitive moves include geographic capacity expansion toward southeastern United States demand concentration and portfolio diversification into integrated below-grade envelope solutions.
Among North American specialists, Beaver Plastics anchors the captive manufacturing archetype with multi-province production footprint serving transportation contracts. ACH Foam Technologies exemplifies the technical service model through specialization in custom-molded blocks for complex geometries. Carlisle Construction Materials occupies a position within the diversified portfolio tier, extending construction materials integration into combined waterproofing-geofoam specification. These three patterns represent how competitive positioning stratifies around supply chain control, engineering collaboration depth, and cross-product bundling capability rather than commodity block production scale alone.
| Leading Market Players |
|---|
| Beaver Plastics |
| Harbor Foam |
| Carlisle Construction Materials |
| ThermaFoam |
| Expol |
| ACH Foam Technologies |
| Atlas Roofing Corporation |
| Poly Molding |
| Amvic Building Systems |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap specialists in the Great Lakes region anchor North American bead expansion capacity, translating captive polystyrene supply into pricing discipline that resists spot-market volatility on multi-year infrastructure contracts.
Pricing Analysis
Short lead-time premiums compress standard contract rates by 12-18% for emergency bridge approach repairs, while spot inventory discounts emerge when state transportation departments delay project starts. Three-tier pricing structure across premium ASTM D6817-certified grades, standard state-specification blocks, and economy non-certified tiers stratifies procurement. Cost compression in economy grades is intensifying because freight consolidation from distant manufacturing clusters erodes landed margins. Residential building contractors exhibit highest price sensitivity, whereas infrastructure agencies prioritize certification compliance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Great Lakes region bead expansion facilities serving Pacific Northwest and Southwest projects through extended freight corridors. Manufacturing concentrates in the United States, Canada, and Germany, drawing from styrene monomer, polystyrene beads, and steam energy inputs. Tariff exposure on Canadian cross-border shipments threatens margin stability for Ontario-Quebec producers serving northern tier states. Distribution runs through manufacturer-direct contracts for volume infrastructure projects, with regional supply houses serving fragmented commercial construction demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market constitutes a vertical-integration race where captive polystyrene bead supply determines cost position and specification access across state transportation procurement.
For Market Incumbents: Anchor specification authority through accelerated ASTM D6817 certification investments that disqualify non-compliant rivals from federally funded roadway projects. Defend against extruded polystyrene substitution in below-water-table applications by embedding technical service teams within Florida and Louisiana coastal resilience agencies. Prioritize backward integration into styrene monomer supply to buffer margin compression from feedstock volatility. For New Entrants and Emerging Players: Infrastructure Investment and Jobs Act resilience funding in the southeastern United States opens a window for certified producers to capture embankment stabilization contracts bypassing established distributor relationships. Target urban building pad stabilization in Dallas and Phoenix where developer demand for accelerated construction schedules outruns incumbent technical service capacity. Pursue design-build partnership models that bundle material supply with geotechnical engineering collaboration. For Investors and Strategic Acquirers: Distressed-cycle entries favor technical service specialists with captive R&D facilities in the Great Lakes manufacturing corridor. Long-term viability hinges on consolidation of fragmented regional supply houses into integrated distribution networks serving multi-phase coastal developments. Monitor state-level electronic bidding platform mandates as the inflection indicator for certification-driven vendor disqualification waves.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Styrene Monomer | Captive feedstock supply buffers margin compression from benzene price volatility on multi-year contracts. |
| ASTM D6817 Certification Pre-Qualification | Third-party laboratory testing investments lock out uncertified competitors from FHWA-mandated projects. |
| Geographic Capacity Expansion | Southeastern United States manufacturing footprint reduces freight exposure for Florida coastal resilience contracts. |
| Technical Service Team Embedding | On-site geotechnical collaboration with state DOT engineers secures specification authority for complex earth retention geometries. |
| Waterproofing System Bundling | Combined membrane-geofoam procurement packages capture below-grade envelope spend from single-source-seeking contractors. |
Methodological Framework
Independent corroboration across state transportation procurement officers, geotechnical engineering consultants, and polystyrene manufacturing plant managers underwrites the qualitative findings. Primary fieldwork encompassed structured interviews with FHWA specification engineers, commercial construction procurement leads, and distributor channel partners across the United States and Canadian provinces. Secondary validation drew from FHWA implementation manuals, ASTM D6817 certification databases, state DOT electronic bidding records, and SEC filings from listed construction materials companies. Bottom-up project pipeline analysis triangulated against top-down infrastructure spending forecasts.
The projection horizon anchors to historical reference periods spanning pre-pandemic procurement cycles through current resilience investment waves. Segmentation modeling incorporated product type density grades, application load-bearing requirements, end-user sophistication tiers, and regional regulatory frameworks. CAGRs were derived through demand elasticity analysis against infrastructure appropriation trajectories. Key forecast inputs included FHWA specification adoption curves and state-level electronic procurement platform penetration rates.
The model assumes a particular technology adoption path; alternative pathways for extruded polystyrene moisture resistance would alter the outlook. Forecasts reflect assumptions about FHWA mandate continuity and state resilience funding durability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Geogrid Market
Building & Construction Materials
Corrugated Steel Panels Market
Building & Construction Materials
Roofing Underlayment Market
Building & Construction Materials
Floor Screeds Market
Building & Construction Materials
Global Wooden Formwork Systems Market
Building & Construction Materials
Europe Particle Board Market
Building & Construction Materials
Mineral Wool Ceiling Tiles Market
Building & Construction Materials
United Kingdom Prefab Wood Buildings Market
Building & Construction Materials
India Pipe Fabrication Market
Building & Construction Materials
United States Roofing Market
Building & Construction Materials
Acoustic Doors Market
Building & Construction Materials
Welded Steel Tanks Market
Building & Construction Materials
North America Metallic Barn Doors Market
Building & Construction Materials
Global Steel Service Centers Market
Building & Construction Materials
Latin America Prefab Wood Buildings Market
Building & Construction Materials
Soil Stabilization Market